
 Retinal Vasculitis Treatment Market | 2026-2036
Retinal Vasculitis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Retinal Vasculitis Treatment Market Analytics
Biologics are displacing conventional corticosteroids as first-line therapy in severe cases, which is recalibrating cost structures across the value chain. Bristol-Myers Squibb leverages its immunology portfolio to anchor positions in TNF-alpha inhibitor segments. Novartis dominates intravitreal delivery with manufacturing scale that sustains supply security for retinal specialists. Regeneron Pharmaceuticals differentiates through VEGF-targeted mechanisms that compete directly with legacy immunosuppressant protocols.
Retinal vasculitis treatment encompasses pharmacological interventions targeting inflammatory damage to retinal blood vessels, typically administered via intravitreal injection to achieve therapeutic concentrations exceeding systemic delivery thresholds. The primary purpose centers on preserving visual acuity by suppressing vascular leakage, neovascularization, and ischemic retinal injury. Biologics command premium positioning due to targeted cytokine blockade and favorable safety profiles relative to broad immunosuppression. Intravitreal injection leads delivery mode preference among ophthalmologists seeking localized drug action with minimized systemic exposure. Combination therapy represents the fastest-growing regimen category as clinicians sequence biologic induction with corticosteroid maintenance.
The FDA's orphan drug designation framework and EMA's centralized marketing authorization for advanced therapy medicinal products shape clinical trial investment and market access timelines for novel retinal therapeutics. REACH compliance requirements in Europe govern excipient purity standards and container closure system biocompatibility for intraocular drug products. Stakeholders must monitor how payer consolidation affects reimbursement thresholds for high-cost biologic regimens versus generic corticosteroid alternatives.
Market Dynamics
The FDA's accelerated approval pathways for rare disease indications are compressing commercialization timelines and attracting venture capital into retinal biologics pipelines, while ophthalmology clinics scramble to build intravitreal injection capacity ahead of anticipated therapy launches.
Growth Catalysts
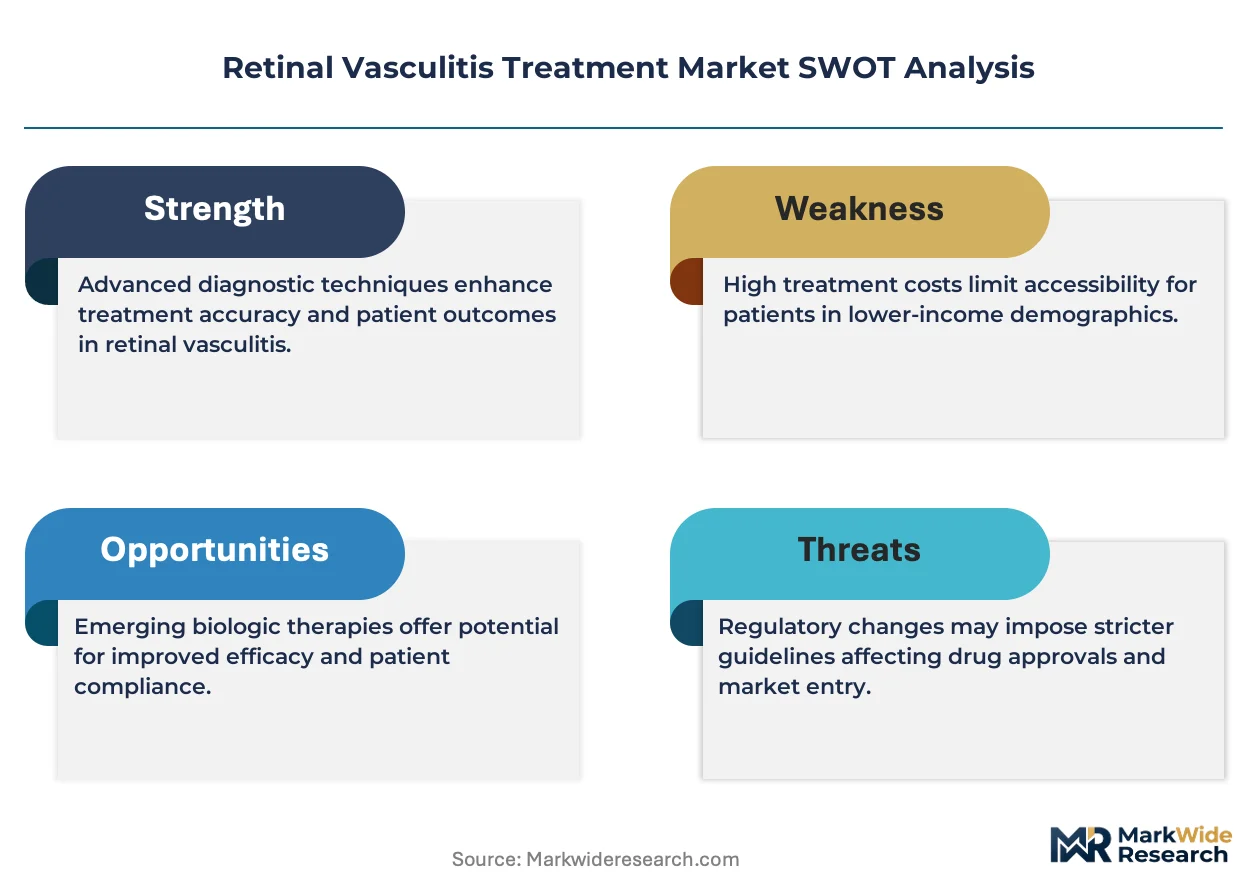
- Orphan Drug Incentives:The FDA's orphan drug designation framework grants seven-year market exclusivity and tax credits for clinical trial costs, incentivizing developers to pursue retinal vasculitis indications despite small patient populations.
- Intravitreal Injection Infrastructure:Tertiary eye care centers in the United States are expanding dedicated retinal suites to accommodate rising volumes of biologic administration procedures requiring sterile compounding capabilities.
- Biologic Manufacturing Scale:Multi-product bioreactor facilities in Switzerland and Ireland are achieving production yields that reduce per-dose costs for monoclonal antibodies targeting ocular inflammation pathways.
Market Restraints
- Reimbursement Compression:Payer consolidation among United States commercial insurers is tightening prior authorization requirements for high-cost biologic regimens versus generic corticosteroid alternatives.
- Excipient Supply Concentration:REACH compliance requirements in Europe have reduced the supplier base for pharmaceutical-grade polysorbates used in intravitreal formulations to three qualified manufacturers.
- Technical Limitation of Delivery:The blood-retinal barrier prevents systemic administration from achieving therapeutic concentrations, mandating invasive injection protocols that limit patient compliance and expand treatment intervals.
Strategic Opportunities
- Sustained-Release Formulations:Polymeric depot technologies converging with anti-VEGF biologics promise to extend dosing intervals from monthly to quarterly, reducing injection burden for retinal specialists and patients.
- EMA Centralized Pathways:The European Medicines Agency's advanced therapy medicinal products designation streamlines marketing authorization across 27 member states, creating regulatory tailwinds for first-movers in retinal inflammation.
- Teleophthalmology Screening:Remote diagnostic platforms are penetrating rural United States markets where retinal specialist density falls below one per 100,000 population, expanding addressable patient identification.
Industry Challenges
- Vitreoretinal Surgeon Training:The specialized skill required for safe intravitreal injection technique creates bottlenecks as community ophthalmology practices attempt to expand biologic administration without fellowship-trained personnel.
- Cold Chain Integrity:Temperature excursions during distribution of protein-based therapeutics from manufacturing sites in Switzerland to infusion centers in the southern United States threaten product stability and reimbursement eligibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Retinal Vasculitis Treatment Market |
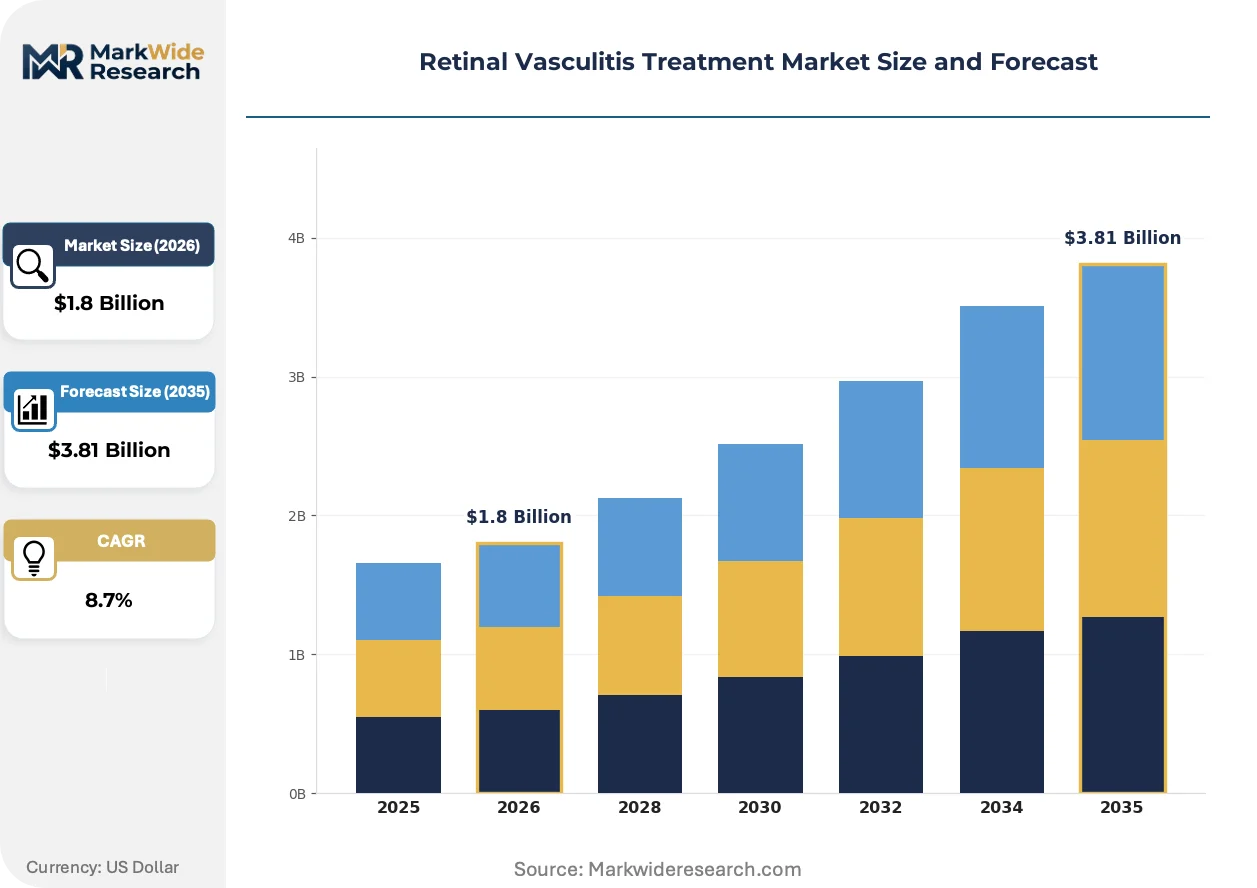
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corticosteroids, Immunosuppressants, Biologics, Antioxidants Delivery Mode: Intravitreal Injection, Oral Administration, Subcutaneous Injection, Topical End User: Hospitals, Ophthalmology Clinics, Ambulatory Surgical Centers, Research Institutes Treatment Regimen: Induction Therapy, Maintenance Therapy, Combination Therapy, Adjuvant Therapy |
| Companies Covered | Bristol-Myers Squibb Company, Pfizer, Inc., Novartis AG, Merck & Co., Inc., Bayer AG, F. Hoffmann-La Roche Ltd., Regeneron Pharmaceuticals, Inc., Eli Lilly and Company, GlaxoSmithKline plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Retinal Vasculitis Treatment Market Evolving Landscape
Biologic delivery mechanisms and diagnostic protocols are undergoing rapid transformation as developers race to match the efficacy of intravitreal injections with less invasive alternatives and earlier intervention windows.
Gene therapy vectors engineered for sustained cytokine suppression are electrifying preclinical pipelines, with adeno-associated viral platforms demonstrating multi-year expression of anti-inflammatory proteins in non-human primate models. Academic medical centers in the United States are establishing dedicated gene therapy infusion suites to prepare for anticipated regulatory submissions. This modality is electrifying competitive positioning by threatening to collapse the recurring revenue model of monthly biologic injections into single-administration interventions.
The European Union's Medical Device Regulation (MDR) is reclassifying intraocular injection devices from Class IIa to Class IIb, triggering substantial notified body involvement and clinical evidence requirements for container closure systems. Manufacturers of prefilled syringes and autoinjectors are accelerating biocompatibility testing programs to maintain CE marking eligibility. Retinal specialists in Germany and France are experiencing delayed access to next-generation delivery devices as certification timelines extend beyond original commercialization schedules.
Retinal imaging analytics are reshaping how ophthalmologists sequence therapy decisions, with artificial intelligence platforms analyzing optical coherence tomography scans to predict treatment response before initiating biologic induction. Academic medical centers are integrating these tools into electronic health record workflows, displacing empirical trial-and-error protocols. This behavioral shift is most visible in the United States, where integrated delivery networks negotiate value-based contracts tying reimbursement to visual acuity outcomes rather than injection volume.
Retinal Vasculitis Treatment Market Segmentation
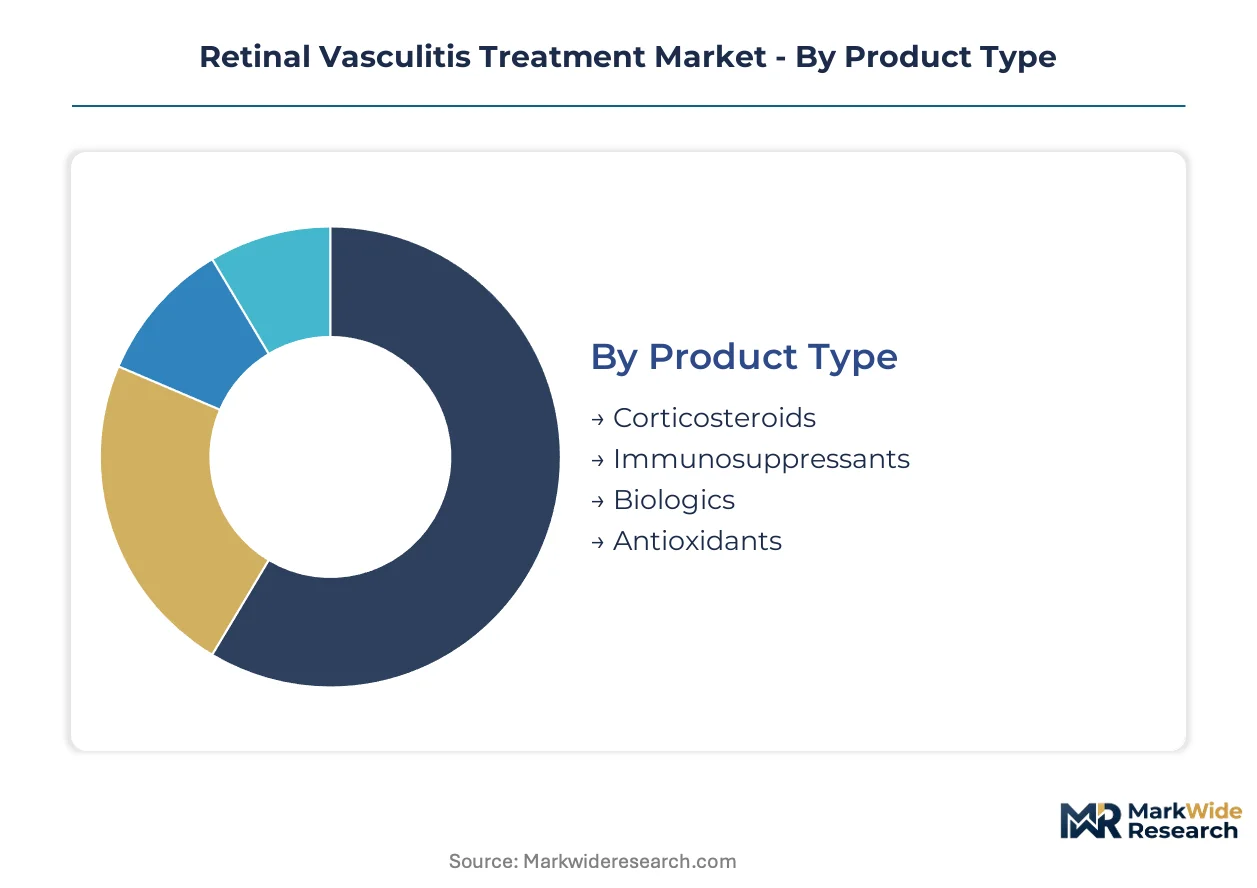
Retinal vasculitis treatment segmentation reveals how clinical severity, delivery logistics, and reimbursement pathways fragment purchasing behavior across the patient journey. Understanding these divides enables targeted positioning for high-cost biologics against legacy corticosteroid alternatives.
Product Type:
Cost tier separates acute intervention buyers from chronic management purchasers in this category.
- Biologics:Monoclonal antibodies and fusion proteins engineered for selective cytokine blockade deliver superior safety margins in severe uveitic presentations. Tertiary eye centers in the United States concentrate procurement of TNF-alpha and VEGF inhibitors, driven by FDA orphan drug exclusivity windows and value-based reimbursement contracts tied to visual acuity preservation.
- Corticosteroids:Synthetic glucocorticoids remain the cost-optimized backbone for initial inflammatory suppression and maintenance tapering. Community ophthalmology practices in Germany and France favor intravitreal triamcinolone where EMA centralized pricing controls limit biologic access.
- Immunosuppressants:Calcineurin inhibitors and antimetabolites serve steroid-sparing roles in bilateral or refractory cases.
- Antioxidants:Nutraceutical adjuncts targeting oxidative retinal stress occupy niche prophylactic positioning.
Volume sits with Corticosteroids; growth tilts toward Biologics.
Delivery Mode:
Application setting dictates sterile infrastructure requirements and procedure reimbursement codes.
- Intravitreal Injection:Direct vitreous cavity administration achieves therapeutic concentrations exceeding systemic thresholds by orders of magnitude. United States retinal specialists perform these procedures in dedicated sterile suites, with Medicare facility fees covering nursing and compounding overhead.
- Subcutaneous Injection:Self-administered biologics bypass ocular barriers through systemic circulation, requiring higher dosing. Patient compliance in rural United States markets improves when injection training programs accompany therapy initiation.
- Oral Administration:Systemic corticosteroids and immunomodulators suit bilateral disease or patients refusing ocular procedures.
- Topical:Periocular and intraocular drops address anterior segment inflammation with limited posterior segment penetration.
Procedure economics favor Intravitreal Injection for severe disease; Subcutaneous Injection gains share in maintenance populations.
End User:
Customer type determines capital intensity, staffing models, and payer contracting leverage.
- Ophthalmology Clinics:Dedicated retinal practices aggregate sufficient injection volume to justify in-house sterile compounding and biologic cold chain infrastructure. United States metropolitan markets see these clinics consolidating through private equity platforms to negotiate manufacturer rebates.
- Hospitals:Academic medical centers manage complex vasculitis with systemic comorbidities requiring multidisciplinary coordination. Centers in Switzerland and Ireland leverage proximity to biologic manufacturing clusters for supply security.
- Ambulatory Surgical Centers:Lower overhead settings capture high-volume injection cases with streamlined prior authorization workflows.
- Research Institutes:Early-phase clinical trial sites drive off-label protocol development and biomarker validation.
Revenue concentrates in Ophthalmology Clinics; expansion tilts toward Ambulatory Surgical Centers.
Treatment Regimen:
Maturity of disease presentation shapes sequencing protocols and therapy duration economics.
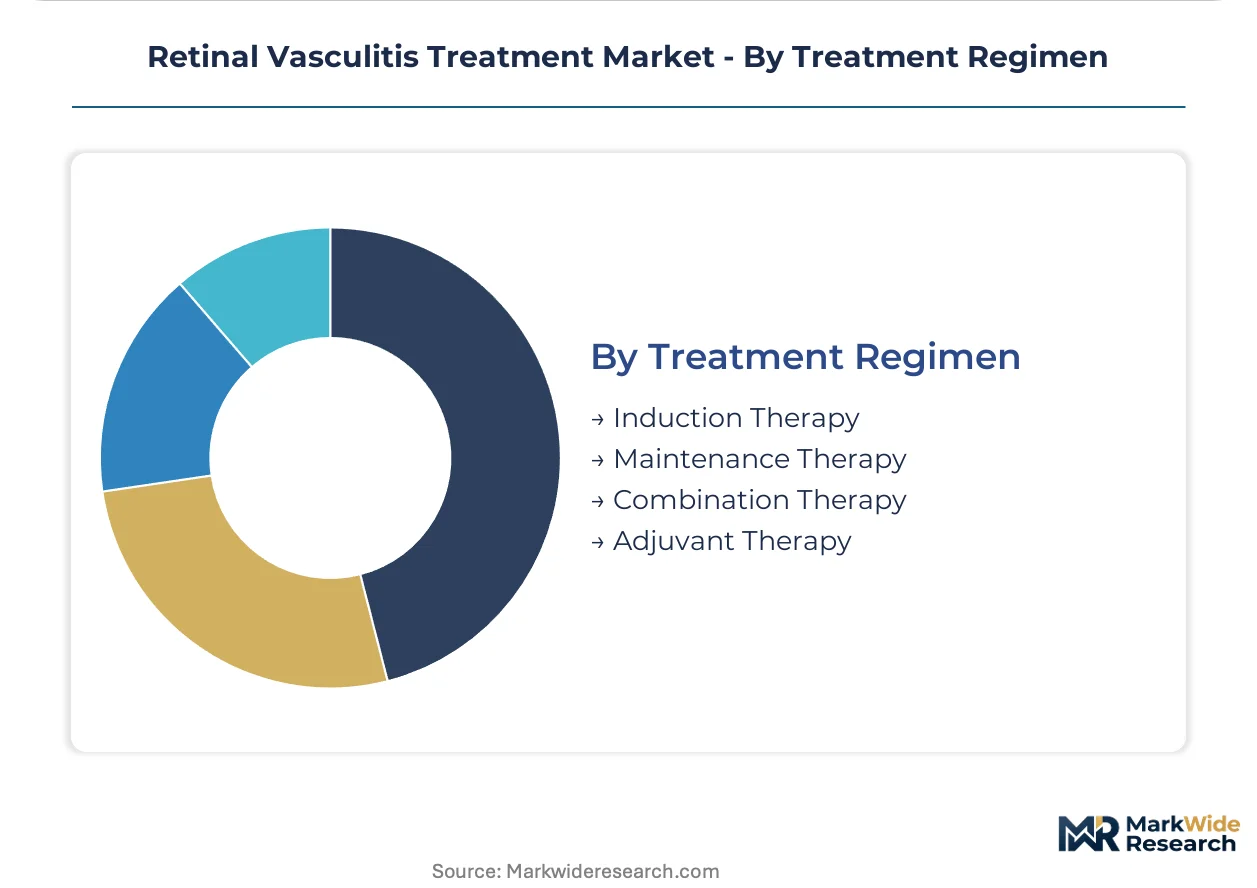
- Combination Therapy:Biologic induction paired with corticosteroid tapering optimizes visual outcomes while minimizing chronic immunosuppression exposure. United States integrated delivery networks favor this approach where bundled payments reward rapid disease control.
- Induction Therapy:Intensive initial dosing protocols aim for rapid inflammatory quiescence in sight-threatening presentations. High-dose intravitreal corticosteroids dominate this phase where biologic access awaits prior authorization.
- Maintenance Therapy:Long-term suppression prevents relapse in chronic recurrent vasculitis.
- Adjuvant Therapy:Supplementary interventions address complications including macular edema and neovascularization.
Clinical investment centers on Combination Therapy; Adjuvant Therapy expands with complication management protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States tertiary eye centers concentrate intravitreal injection volume, while Switzerland and Ireland anchor biologic manufacturing clusters. Regulatory pathways in Germany and Japan shape commercialization timelines for novel retinal therapeutics.
United States
Medicare facility fees and integrated delivery network contracts drive biologic adoption in metropolitan retinal clinics. The FDA's orphan drug designation grants seven-year exclusivity for rare disease indications. Boston and San Francisco academic medical centers establish gene therapy infusion suites ahead of anticipated regulatory submissions.
Germany
EMA centralized marketing authorization streamlines access across member states for advanced therapy medicinal products. The EU Medical Device Regulation reclassifies intraocular injection devices, triggering extended notified body involvement. Heidelberg and Munich ophthalmology clusters experience delayed next-generation delivery device access as certification timelines extend.
Switzerland
Multi-product bioreactor facilities achieve production yields that reduce per-dose monoclonal antibody costs. Swissmedic maintains alignment with EMA standards while offering streamlined national procedures. Basel and Zurich manufacturing sites supply protein-based therapeutics under strict cold chain protocols to southern European and North American markets.
Japan
PMDA accelerated review pathways for serious ophthalmic conditions compress development timelines for domestic and foreign sponsors. METI industrial policy supports precision medicine infrastructure in academic medical centers. Tokyo and Osaka retinal specialist networks integrate artificial intelligence imaging analytics into electronic health record workflows.
United Kingdom
NICE technology appraisals determine National Health Service reimbursement for high-cost biologic regimens versus corticosteroid alternatives. MHRA post-Brexit regulatory autonomy enables tailored approval pathways for ocular gene therapies. London and Cambridge research institutes drive biomarker validation for treatment response prediction algorithms.
Retinal Vasculitis Treatment Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with consolidated positions in biologics contrasting fragmented corticosteroid supply. Large-cap pharmaceutical companies anchor the premium tier through immunology portfolio breadth, while mid-size developers concentrate on targeted cytokine mechanisms. Competitive moves center on manufacturing scale investments and strategic partnerships for sustained-release formulation capabilities.
Within the large-cap immunology tier, Bristol-Myers Squibb Company and Novartis AG represent archetypal positions—one leveraging TNF-alpha inhibitor breadth, the other dominating intravitreal delivery manufacturing scale. Regeneron Pharmaceuticals, Inc. occupies a distinct vector through VEGF-targeted mechanism specialization that competes with legacy immunosuppressant protocols.
| Leading Market Players |
|---|
| Bristol-Myers Squibb Company |
| Pfizer, Inc. |
| Novartis AG |
| Merck & Co., Inc. |
| Bayer AG |
| F. Hoffmann-La Roche Ltd. |
| Regeneron Pharmaceuticals, Inc. |
| Eli Lilly and Company |
| GlaxoSmithKline plc |
| Others |
Value Network & Pricing Analysis
Payer consolidation among United States commercial insurers is compressing reimbursement thresholds for high-cost biologic regimens, forcing manufacturers to absorb margin erosion or redirect volume toward ophthalmology clinics with value-based contracting leverage. This demand-side compression cascades into supply chain restructuring as biologic producers prioritize multi-product bioreactor facilities in Switzerland and Ireland to achieve per-dose cost reductions that preserve profitability.
Pricing Analysis
Volume concentrates with corticosteroids while margins accrue to biologics, creating a bifurcated pricing structure across premium, standard, and economy tiers. Price differentiation hinges on FDA orphan drug exclusivity windows and EMA centralized pricing controls, with tertiary eye centers in the United States commanding manufacturer rebates through consolidated procurement. Pricing pressure stems from generic corticosteroid alternatives in European markets where centralized pricing limits biologic access. Community ophthalmology practices in Germany and France exhibit highest price sensitivity, while United States integrated delivery networks with bundled payment contracts demonstrate lowest sensitivity.
Supply Chain Analysis
REACH compliance requirements and EMA Medical Device Regulation reclassifications have tightened qualification standards for excipient suppliers and container closure systems, reducing the qualified supplier base for pharmaceutical-grade polysorbates to three manufacturers. Manufacturing concentrates in Switzerland, Ireland, and the United States, with multi-product bioreactor facilities in Basel and Zurich achieving production yields that lower per-dose monoclonal antibody costs. Raw material dependencies include pharmaceutical-grade polysorbates, borosilicate glass vials, and silicone-free syringe components. Single-source vulnerability in excipient supply creates exposure to batch contamination events. Distribution runs through cold chain logistics networks from manufacturing sites to tertiary eye centers, with temperature excursions threatening product stability and reimbursement eligibility.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The retinal vasculitis treatment market is becoming a vertical-integration race as players pursue captive control over bioreactor capacity and sterile compounding infrastructure to defend margins against reimbursement compression.
For Market Incumbents: Cement manufacturing scale advantages through backward integration into multi-product bioreactor facilities in Switzerland or Ireland, insulating against excipient supply concentration risks. Lock in long-term contracts with tertiary eye care networks before payer consolidation accelerates prior authorization restrictions on high-cost biologics. For New Entrants and Emerging Players: Rural United States ophthalmology practices represent an underserved buyer archetype with retinal specialist density below one per 100,000 population and limited access to intravitreal injection infrastructure. Target teleophthalmology screening partnerships to identify treatment-naive patients ahead of referral to metropolitan centers, using subcutaneous delivery formulations to bypass sterile suite requirements. For Investors and Strategic Acquirers: The window for entry favors sustained-release formulation specialists with polymeric depot technologies that extend dosing intervals from monthly to quarterly. Watch FDA accelerated approval pathway utilization rates for rare disease indications as the inflection signal for pipeline valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Multi-product bioreactor facilities in Switzerland reduce per-dose monoclonal antibody production costs for retinal biologics. |
| Regulatory Approval Pathway | FDA orphan drug designation grants seven-year exclusivity and tax credits for retinal vasculitis indications despite small patient populations. |
| Strategic Partnership | Teleophthalmology platform alliances expand patient identification in rural United States markets with specialist shortages. |
| Pipeline Diversification | Gene therapy vectors for sustained cytokine suppression threaten to collapse recurring revenue models into single-administration interventions. |
| Reimbursement Strategy | Value-based contracts with integrated delivery networks tie payment to visual acuity outcomes rather than injection volume. |
Research Methodology
Independent corroboration across retinal specialist interviews, payer formulary analyses, and biologic manufacturing site assessments underwrites the qualitative findings in this study. Primary fieldwork encompassed drug development executives at large-cap immunology portfolios, regulatory affairs leads navigating FDA and EMA pathways, formulary directors at consolidated United States commercial insurers, and hospital procurement managers at academic medical centers establishing gene therapy infusion suites. Secondary validation drew from FDA orphan drug designation filings, EMA centralized marketing authorization submissions, ClinicalTrials.gov protocol registrations, and Medicare facility fee schedules. Bottom-up patient volume estimates and top-down market sizing triangulate to bound forecast uncertainty.
Comparable-period anchoring to historical intravitreal injection volume trajectories and biologic adoption curves informed the projection horizon across the analysis window. Segmentation dimensions modeled include product type (biologics, corticosteroids, immunosuppressants), delivery mode (intravitreal injection, subcutaneous, oral), and end user (ophthalmology clinics, hospitals, ambulatory surgical centers). CAGRs derive from patient population growth, therapy penetration assumptions, and pricing trajectory modeling. Forecast inputs incorporate REACH compliance cost pass-through effects and EMA Medical Device Regulation certification timeline delays.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to gene therapy regulatory approvals, payer consolidation velocity, and sustained-release formulation clinical validation. Forecasts reflect documented assumptions regarding therapy sequencing protocols and reimbursement pathway stability. A model refresh is warranted upon material change in FDA accelerated approval pathway utilization or EMA advanced therapy medicinal products designation granting patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Global Anterior Uveitis Treatment Market
Ophthalmology
Japan Ophthalmic Devices and Drugs Market
Ophthalmology
Latin America Dry Eye Syndrome Market
Ophthalmology
North America Vision Care Market
Ophthalmology
India Ophthalmology Devices Market
Ophthalmology
Conjunctivitis Treatment Market
Ophthalmology
Global Artificial Tear Market
Ophthalmology
Ocular Pain Market
Ophthalmology
Excimer and Femtosecond Ophthalmic Lasers Market
Ophthalmology
Neovascular Age-Related Macular Degeneration Treatment Market
Ophthalmology
Ocular Hypertension Treatment Market
Ophthalmology
Conjunctivitis Market
Ophthalmology
Allergy Relieving Eye Drops Market
Ophthalmology
Global Posterior Segment Eye Disorders Market
Ophthalmology
Epidemic Keratoconjunctivitis Treatment Market
Ophthalmology
Diabetic Retinopathy Treatment Market