
 Tunisia Pharmaceutical Market | 2026-2036
Tunisia Pharmaceutical Market Size, Share, and Industry Trends Forecast 2026-2036
Tunisia Pharmaceutical Market Intelligence
The substitution of traditional chemical APIs with advanced biologic active ingredients is realigning production economics across the Tunisian pharmaceutical sector. Domestic manufacturer Adwya leverages its established distribution network to compete on generic drug volumes. Les Laboratoires UNIMED specializes in sterile solutions and ophthalmic products, occupying a key niche. Meanwhile, Sanofi-Aventis Tunisia sustains its market position through its portfolio of branded drugs and extensive clinical trial infrastructure in the country.
The Tunisian pharmaceutical sector encompasses the development, production, and distribution of medicinal products for human use. These products range from chemically synthesized small molecules to complex biologics, all formulated into various dosage forms like tablets, injectables, and oral solutions. Generic drugs command the largest volume share, driven by government cost-containment policies. Hospital procurement channels dominate high-value branded drug and biosimilar sales, while retail pharmacies are the primary channel for over-the-counter products.
Tunisia's Direction de la Pharmacie et du Médicament (DPM) governs drug registration, pricing, and quality control. The Pharmacie Centrale de Tunisie (PCT) acts as the central purchasing body for the public sector, influencing procurement volumes and pricing for hospitals. Navigating the dual-track system of public tenders via the PCT and private market distribution will be a critical decision point for market participants.
Market Dynamics
The Tunisian pharmaceutical market is shaped by the central government's strategic imperative to foster local production, creating a structural tension between import substitution policies and the sector's reliance on foreign-sourced active pharmaceutical ingredients for advanced therapies.
Growth Catalysts
- National Production Strategy:Tunisia's national policy prioritizing domestic manufacturing over imports provides a direct incentive for local firms to expand production capacity, particularly for generic drugs and essential medicines.
- Oncology Investment:Rising public and private investment in specialized oncology treatment centers is creating concentrated demand for high-value biologic and chemotherapy drugs, stimulating growth in this therapeutic category.
- Tunis Regional Hub:The concentration of manufacturing facilities, research laboratories, and skilled labor in the greater Tunis area creates a robust ecosystem that accelerates development and lowers logistical costs for producers.
Market Restraints
- API Import Dependence:The sector's heavy reliance on imported active pharmaceutical ingredients, especially advanced biologics from Europe and Asia, exposes local manufacturers to global price volatility and supply chain disruptions.
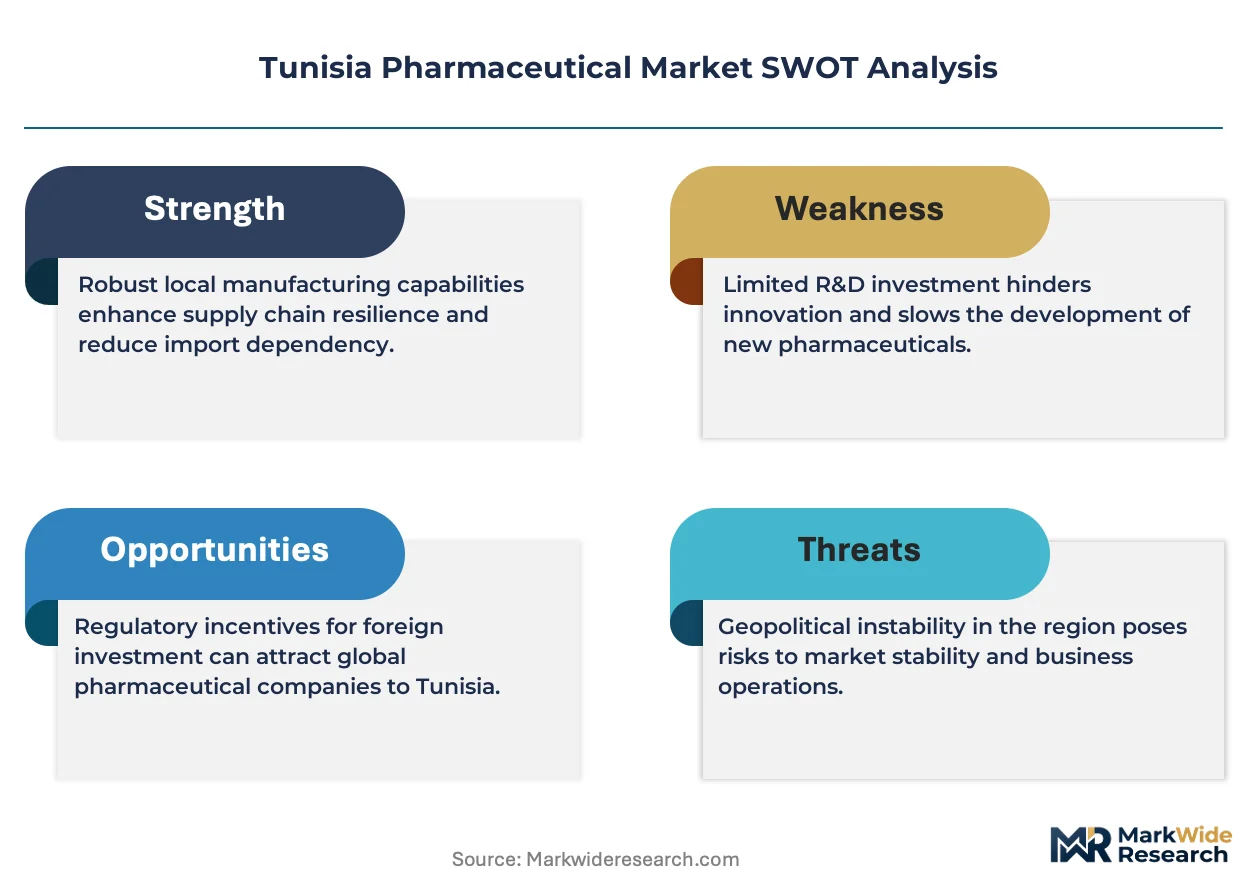
- DPM Price Controls:The Direction de la Pharmacie et du Médicament (DPM) imposes strict price ceilings on many pharmaceutical products, which can compress margins and limit funds available for research and development.
- Public Procurement Power:As the central purchasing body for public hospitals, the Pharmacie Centrale de Tunisie (PCT) wields significant negotiating power, often forcing manufacturers to compete aggressively on price for large-volume tenders.
Strategic Opportunities
- Biosimilar Development:Establishing local production capabilities for biosimilars offers a significant opportunity to substitute high-cost imported biologic drugs as they come off patent, aligning with national cost-containment goals.
- Export to African Markets:Leveraging Tunisia's established pharmaceutical manufacturing base and quality certifications to export generic and specialized medicines to underserved markets across Sub-Saharan Africa presents a major growth vector.
- Digital Health Integration:Developing digital platforms for post-market surveillance and pharmacovigilance can create new service-based revenue streams and strengthen relationships with both regulators and healthcare providers.
Industry Challenges
- Specialized Talent Gaps:A shortage of personnel with expertise in bioprocessing, regulatory science for biologics, and advanced sterile manufacturing techniques constrains the sector's ability to move up the value chain.
- Intellectual Property Navigation:Managing the complex landscape of drug patents and licensing agreements is a significant operational hurdle for local firms seeking to produce generic or biosimilar versions of originator drugs.
- Cold Chain Logistics:Ensuring the integrity of temperature-sensitive biologics and vaccines across the distribution network requires significant capital investment in modernizing cold chain infrastructure, a challenge outside major urban centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tunisia Pharmaceutical Market |
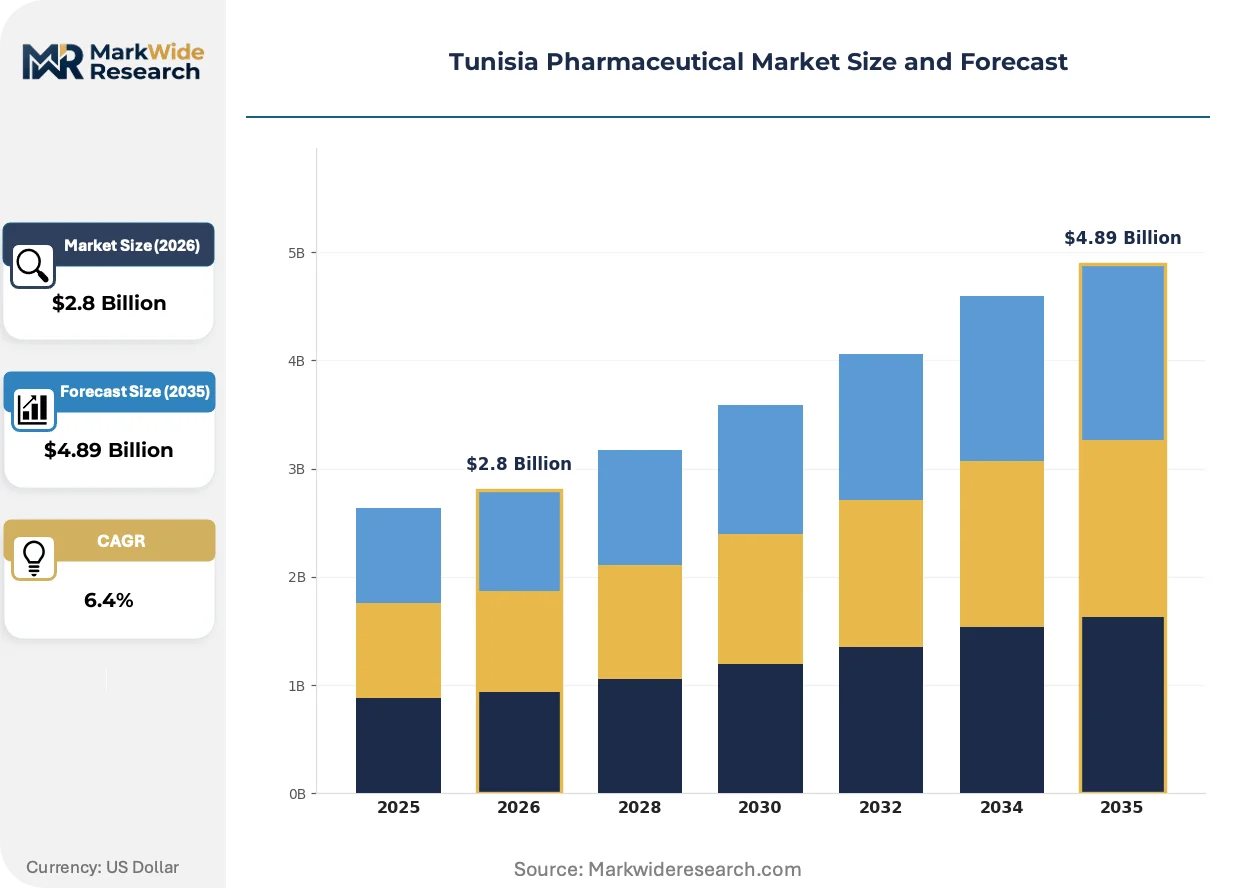
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Generic Drugs, Branded Drugs, Biosimilars, Over-the-Counter, Herbal Supplements, Diagnostics Therapy Area: Cardiovascular, Oncology, Central Nervous System, Respiratory Disorders, Gastrointestinal, Endocrinology End User: Hospitals, Clinics, Pharmacies, Research Laboratories, Specialty Care Centers, Rehabilitation Facilities Distribution Channel: Direct Sales, Distributors, Retail Pharmacies, Online Pharmacies, Wholesalers, Institutional Procurement |
| Companies Covered | Sanofi-Aventis Tunisia, Pfizer, Adwya, Les Laboratoires UNIMED, Teriak, Opalia Pharma, Medis, Taha Pharma, Cytopharma, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tunisia Pharmaceutical Market Strategic Shifts & Innovations
The transition from chemically synthesized molecules to complex biologics is fundamentally altering production economics and regulatory pathways in Tunisia. This shift demands new manufacturing technologies and creates opportunities for firms capable of navigating the higher technical and compliance barriers.
Single-use bioreactor technology provides a flexible platform for biopharmaceutical manufacturing. Local producers are adopting these systems for clinical trial material and small-scale commercial production of monoclonal antibodies. This technology is modularizing biomanufacturing, enabling companies to scale production capacity in response to demand without the massive upfront capital expenditure of traditional stainless-steel facilities.
Tunisia’s policy framework encouraging self-sufficiency in essential medicines directly influences investment decisions. This government-led initiative results in preferential treatment for local producers in public tenders managed by the Pharmacie Centrale de Tunisie (PCT). The policy most impacts importers of finished generic drugs, who face increasing competition from domestic manufacturers expanding their portfolios to meet national demand.
A notable behavioral shift is occurring within hospital purchasing departments, which are moving beyond simple unit-price comparisons. These groups increasingly evaluate the total cost of treatment, factoring in drug efficacy, patient outcomes, and reduced hospitalization times. This trend is most visible in Tunis-based specialty hospitals procuring high-value oncology and immunology therapies.
Tunisia Pharmaceutical Market Segmentation
Understanding the distinct segments within the Tunisia pharmaceutical market is crucial for identifying targeted growth avenues and optimizing strategic investments. Each product type, therapy area, end-user group, and distribution channel presents unique commercial dynamics and regulatory considerations. Market participants leverage this granular view to tailor product development and market entry strategies effectively.
Product Type:
The market's product type segmentation illustrates a shift from traditional chemical compounds to more advanced biologic formulations, impacting manufacturing processes and regulatory compliance. This transition requires significant investment in new production capabilities and quality control systems for local manufacturers.
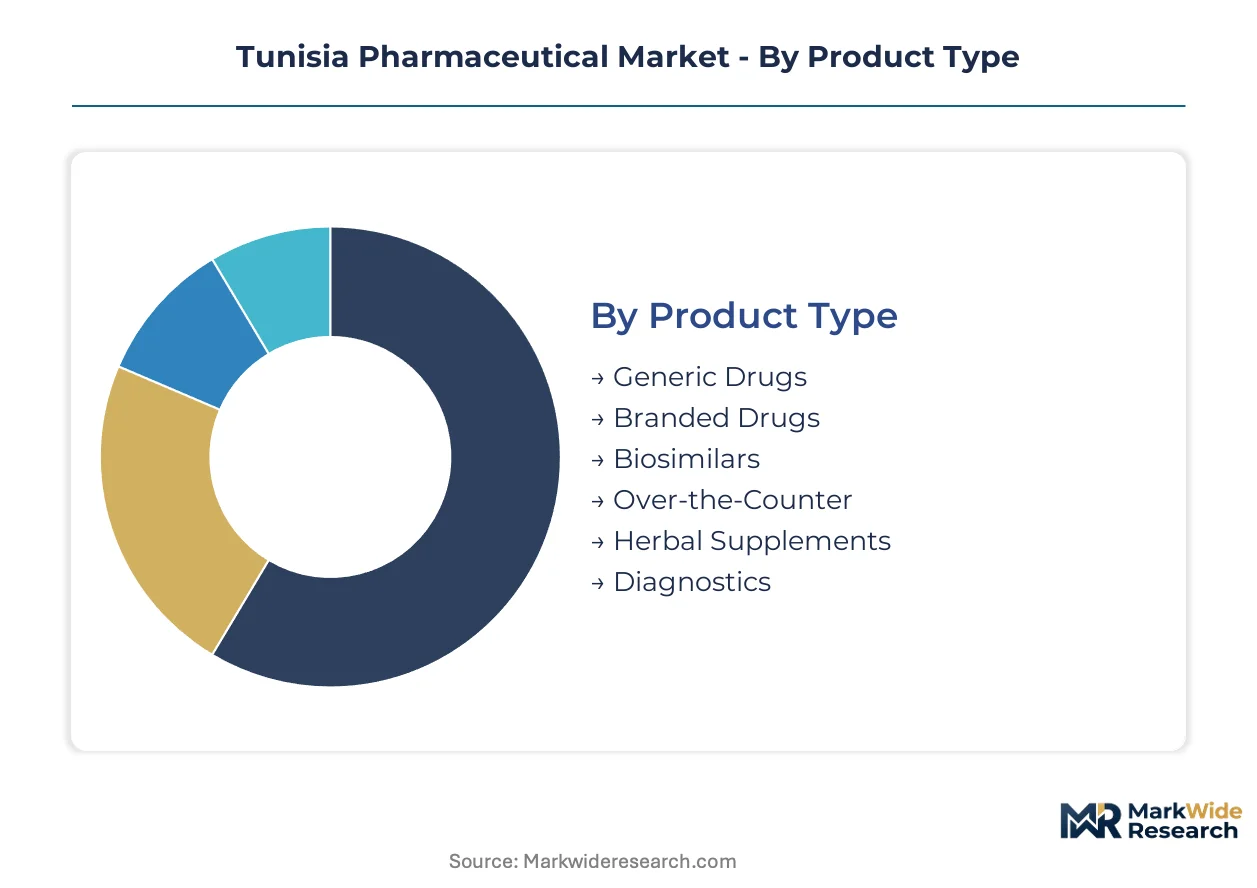
- Generic Drugs:These are pharmaceutical products chemically identical to branded drugs, produced after patent expiry, and command the largest volume share due to government cost-containment policies. Demand for affordable generic drugs is concentrated in public health institutions and retail pharmacies across Tunisia.
- Biosimilars:These are biologic products highly similar to an already approved original biologic medicine, offering a cost-effective alternative to high-priced innovator biologics. Establishing local production capabilities for biosimilars represents a significant strategic opportunity for Tunisian firms to substitute expensive imports.
- Branded Drugs:These are innovator pharmaceutical products sold under a patented brand name, often commanding premium pricing due to their unique formulations and clinical efficacy. Sanofi-Aventis Tunisia maintains a strong position with its portfolio of branded drugs.
- Over-the-Counter:These medicines are available without a prescription, addressing common ailments and sold primarily through retail pharmacies.
- Herbal Supplements: Derived from plant sources, these products are used for health promotion and disease prevention, often perceived as natural alternatives.
- Diagnostics:These products and services are essential for identifying diseases, monitoring patient conditions, and guiding treatment decisions in healthcare settings.
Generic Drugs sits at the top of the volume ranking, with Biosimilars climbing the fastest.
Therapy Area:
The application of pharmaceutical products across various disease categories reveals where healthcare spending and research efforts are increasingly focused within Tunisia. Specific therapeutic needs dictate the types of drugs in demand and the specialized facilities required for treatment.
- Oncology:This segment includes drugs for cancer treatment, encompassing chemotherapy, targeted therapies, and immunotherapies, driven by rising investment in specialized oncology treatment centers. Concentrated demand for high-value biologic and chemotherapy drugs exists in Tunis-based specialty hospitals.
- Cardiovascular:This category covers medications for heart and circulatory system conditions, such as hypertension, heart failure, and dyslipidemia, representing a significant burden of disease in the population. These drugs are widely prescribed across hospitals and general clinics.
- Central Nervous System:This area includes treatments for neurological and psychiatric disorders like depression, epilepsy, and Alzheimer's disease.
- Respiratory Disorders:Medications for conditions affecting the respiratory system, such as asthma, COPD, and allergic rhinitis, fall into this segment.
- Gastrointestinal:This segment comprises drugs for digestive system ailments, including acid reflux, irritable bowel syndrome, and inflammatory bowel disease.
- Endocrinology:This category focuses on treatments for hormonal imbalances and metabolic disorders like diabetes and thyroid dysfunction.
Oncology drugs demonstrate the most significant expansion trajectory, while Cardiovascular therapies maintain substantial market presence.
End User:
The customer type for pharmaceutical products influences procurement patterns, volume requirements, and the specific formulations or services demanded. Different end-user environments have distinct needs for drug storage, administration, and patient monitoring.
- Hospitals:These institutions are major purchasers of high-value branded drugs and biosimilars, often through public procurement channels managed by the Pharmacie Centrale de Tunisie (PCT). Hospital purchasing departments increasingly evaluate the total cost of treatment, considering patient outcomes.
- Specialty Care Centers:These facilities focus on specific disease areas like oncology, requiring specialized and often expensive biologic and advanced therapy products. Investment in these centers creates concentrated demand for targeted treatments.
- Clinics:Outpatient medical facilities providing primary and specialized care, typically procuring a range of generic and branded drugs for immediate patient needs.
- Pharmacies:Retail establishments that dispense prescription medications and sell over-the-counter products directly to the public.
- Research Laboratories:These entities utilize pharmaceutical products for scientific investigation, drug discovery, and clinical trials, requiring specialized reagents and compounds.
- Rehabilitation Facilities:Institutions focused on patient recovery and physical therapy, often requiring pain management and supportive care medications.
Hospitals represent the largest purchasing block, with Specialty Care Centers exhibiting accelerated demand growth.
Distribution Channel:
The pathways through which pharmaceutical products reach end-users dictate logistical infrastructure, pricing strategies, and market access. Each channel has unique operational requirements and regulatory oversight.
- Institutional Procurement:This channel involves the central purchasing body, Pharmacie Centrale de Tunisie (PCT), acquiring pharmaceuticals for public hospitals and health programs. The PCT's negotiating power significantly impacts pricing and volumes for manufacturers.
- Retail Pharmacies:These are the primary outlets for over-the-counter products and prescription medications for individual consumers. Their extensive network ensures broad public access to medicines.
- Direct Sales:Manufacturers sell products directly to large institutional clients or government bodies, often for specialized or high-volume orders.
- Distributors:Wholesalers and logistics providers that manage the storage and transportation of pharmaceutical products from manufacturers to various healthcare providers.
- Online Pharmacies:Digital platforms offering pharmaceutical products for purchase and delivery, a channel gaining traction for convenience and accessibility.
- Wholesalers:Companies that buy products in bulk from manufacturers and sell them to pharmacies, hospitals, and other healthcare facilities.
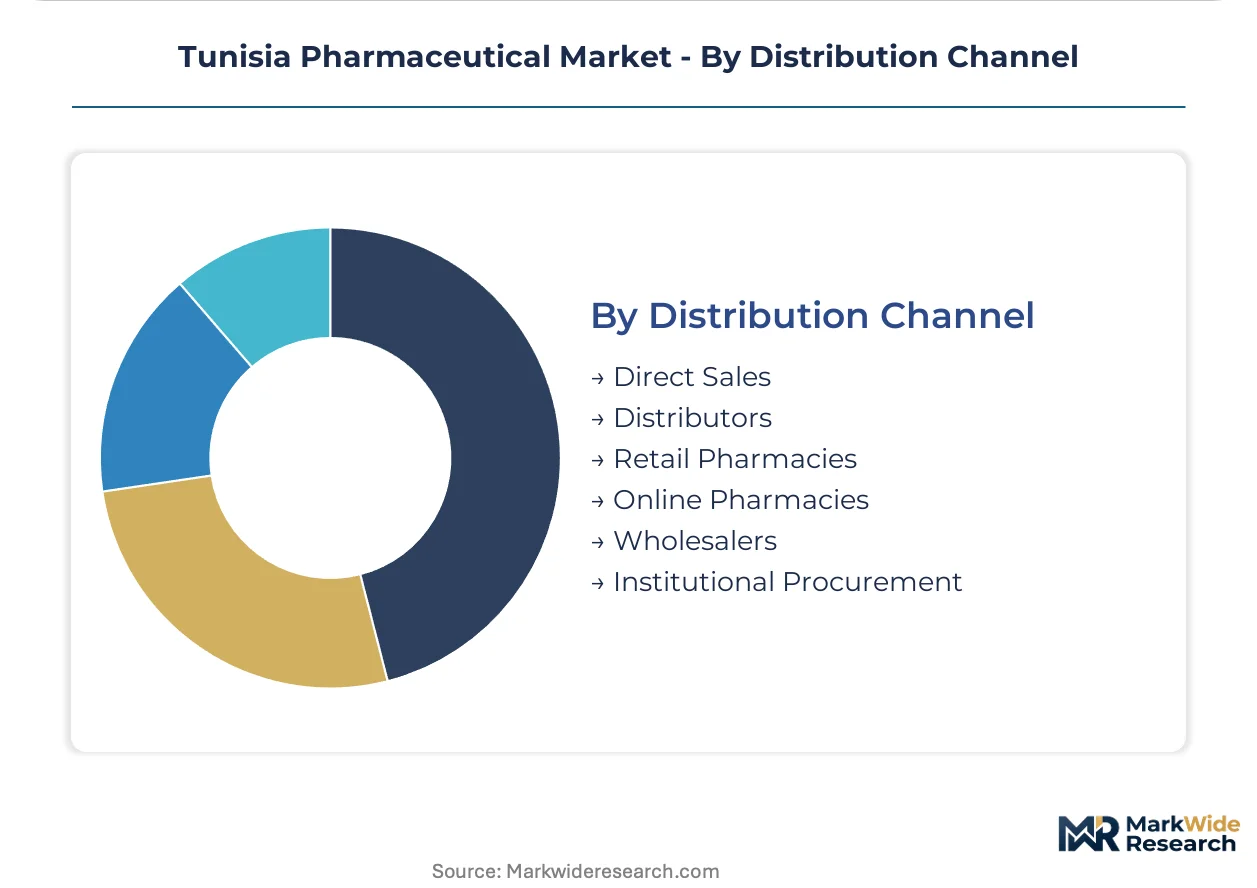
Institutional Procurement drives the largest volumes, while Online Pharmacies are expanding their reach fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The capital region of Tunis anchors pharmaceutical production and demand within Tunisia, serving as the primary hub for advanced medical treatments. This area drives significant investment in oncology treatments and high-value therapies. The region uniquely benefits from a high concentration of manufacturing facilities and research laboratories, forming a robust ecosystem.
Tunis
Demand in Tunis focuses heavily on high-value biologic and chemotherapy drugs, particularly for specialized oncology therapies. The Direction de la Pharmacie et du Médicament (DPM) strictly governs drug registration and pricing across the capital. Tunis hosts numerous state-of-the-art manufacturing facilities, advanced research laboratories, and specialty care centers, fostering localized production.
Sfax
Sfax experiences substantial demand for generic drugs and essential medicines, primarily serving public health institutions and retail pharmacies. The Pharmacie Centrale de Tunisie (PCT) significantly influences procurement volumes and pricing for public sector needs in the region. Sfax functions as a crucial distribution hub for the southern regions, ensuring broader access to pharmaceutical products and supporting regional healthcare.
Sousse
Sousse sees sustained demand for over-the-counter products and specialized pharmaceuticals like sterile solutions and ophthalmic preparations. Tunisia's national production strategy actively prioritizes domestic manufacturing, encouraging local investment in Sousse. The city's developing industrial zones attract pharmaceutical companies focused on expanding local production capabilities and strengthening regional distribution networks.
Gabes
Gabes drives demand for essential medicines and certain basic pharmaceutical ingredients, crucial for local formulation processes. Government policies actively encourage local sourcing to reduce the country's reliance on imported active pharmaceutical ingredients. The Gabes industrial complex supports the manufacturing of chemical inputs, indirectly benefiting the broader pharmaceutical sector through supply chain integration.
Tunisia Pharmaceutical Market Key Industry Players
Global majors compete with regional champions across product portfolios and distribution networks within the Tunisian pharmaceutical market. This market exhibits a tiered competitive structure, accommodating various operational models. Innovator drug companies, generic volume manufacturers, and specialized niche players form distinct archetypes, each carving out specific segments. Companies consistently pursue capacity expansion and strategic partnerships to strengthen their market presence and adapt to evolving demand patterns.
Within the Tunisian market, diverse company archetypes contribute to the competitive dynamics. Sanofi-Aventis Tunisia, a global pharmaceutical entity, exemplifies branded drug leadership through its established portfolio and extensive clinical trial infrastructure. Domestic manufacturer Adwya occupies a significant position among generic drug volume providers, leveraging its extensive distribution network to maintain market share. Les Laboratoires UNIMED represents specialized producers, focusing on niche segments like sterile solutions and ophthalmic products, thereby securing a unique market position.
| Leading Market Players |
|---|
| Sanofi-Aventis Tunisia |
| Pfizer |
| Adwya |
| Les Laboratoires UNIMED |
| Teriak |
| Opalia Pharma |
| Medis |
| Taha Pharma |
| Cytopharma |
| Others |
Cost & Logistics Intelligence
Tunisia's national production strategy, promoting domestic manufacturing, gates access to public tenders for local firms and influences pricing for essential medicines. This policy impacts both qualified supply chains and premium-tier market access.
Pricing Analysis
Input cost pass-through for pharmaceutical manufacturers in Tunisia faces significant constraints from DPM regulatory price ceilings. The market employs a hybrid pricing model, blending contract-based long-term tenders via the PCT with per-unit transactional sales in retail pharmacies. Price differentiation stems from DPM quality grade certification and brand premium for innovator drugs, with volume scale influencing public procurement. Pricing softness runs through generic drugs due to DPM price controls and the PCT's negotiating power, making public hospitals highly price-sensitive compared to specialty care centers for high-value oncology therapies.
Supply Chain Analysis
Active pharmaceutical ingredient supply for Tunisian manufacturers heavily relies on European and Asian specialty chemical producers. The sector sources critical inputs like advanced biologics from these regions, creating significant import dependence. Global price volatility and supply chain disruptions present a structural risk, particularly for temperature-sensitive biologics requiring robust cold chain logistics. Downstream distribution runs through the Pharmacie Centrale de Tunisie for public sector needs and retail pharmacies for over-the-counter products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Tunisia pharmaceutical market operates as a stable compounder, driven by consistent government investment in healthcare infrastructure and local production. This sustained commitment provides a predictable growth trajectory across the analysis window.
For Market Incumbents: Cement market leadership by expanding local production capacity for essential generic drugs and biosimilars. This counters margin pressure from DPM price controls and reduces reliance on foreign-sourced APIs. Strategic investment in specialized talent development for bioprocessing and advanced sterile manufacturing techniques is crucial. Strengthening existing distribution networks further secures market share against emerging competition.
For New Entrants and Emerging Players: The price-point gap between high-cost imported biologics and local generic offerings creates significant white space for biosimilar development. Target underserved Sub-Saharan African export markets with quality-certified generic and specialized medicines. A go-to-market angle focusing on cost-effective biosimilars aligns with national cost-containment goals. Additionally, developing digital platforms for post-market surveillance provides a service-based revenue stream.
For Investors and Strategic Acquirers: Roll-up economics work for domestic generic and specialty manufacturers because of the government's strong national production strategy. The long-term viability of the sector is underpinned by increasing healthcare demand and sustained public sector procurement. Target acquisition archetypes include specialized niche players like Les Laboratoires UNIMED or established generic volume providers like Adwya. Increased government incentives for biosimilar research and development serves as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Capacity Expansion | Increases domestic supply of essential medicines, aligning with Tunisia's self-sufficiency goals and reducing import reliance. |
| Biosimilar Licensing Agreements | Accelerates local production of high-value biologics, offering cost-effective alternatives to expensive imported innovator drugs. |
| Specialized Talent Development | Addresses critical skill gaps in bioprocessing and regulatory science, enabling the sector to move up the pharmaceutical value chain. |
| Sub-Saharan African Export Market Entry | Leverages Tunisia's established manufacturing base to access new revenue streams and diversify geographical sales beyond domestic demand. |
| Digital Health Platform Integration | Enhances pharmacovigilance and post-market surveillance capabilities, strengthening regulatory compliance and patient safety. |
Research Approach
Coverage spans Tunisia's key pharmaceutical regions, with primary inputs from each sub-market. This analysis combines extensive primary interviews with regulatory affairs leads, hospital procurement managers, and drug development executives. Secondary validation leveraged DPM drug registration data, PCT tender documents, and company annual reports. A bottom-up and top-down triangulation approach ensured robust market sizing and forecasting.
The forecast framework modeled market dynamics at a granular level across product type, therapy area, end-user, and distribution channel, alongside regional demand patterns. Compound annual growth rates were derived from historical data trends and projected future growth drivers over the projection horizon. Key industry-specific forecast inputs included new drug approvals and government healthcare spending allocations.
Caveats apply where regulatory policy changes or global API supply disruptions could materially shift the outlook. Forecasts reflect assumptions documented at the time of publication. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Xerostomia Therapeutics Market
Pharmaceuticals
Cytomegalovirus Treatment Market
Pharmaceuticals
Global Hepatitis B Vaccines Market
Pharmaceuticals
Propafenone Hcl Extended Release Capsules Market
Pharmaceuticals
Hospital Pharmaceuticals Market
Pharmaceuticals
Hypertriglyceridemia Therapeutics Market
Pharmaceuticals
Quinolones Market
Pharmaceuticals
Global Vasopressin Market
Pharmaceuticals
Secondary Myelofibrosis Therapeutics Market
Pharmaceuticals
Pembrolizumab Market
Pharmaceuticals
Cough Suppressant Drugs Market
Pharmaceuticals
Hypertensive Emergency Medications Market
Pharmaceuticals
Anti-Viral Therapeutics Market
Pharmaceuticals
Nefopam Hydrochloride Injection Market
Pharmaceuticals
Homocystinuria Therapeutics Market
Pharmaceuticals
Decongestants Market