
 Asia-Pacific Contraceptive Drugs and Devices Market | 2026-2036
Asia-Pacific Contraceptive Drugs and Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Contraceptive Drugs and Devices Market Outlook
Hormonal polymer formulations are consolidating as the preferred substrate for implantable contraceptive delivery systems across the Asia-Pacific region, displacing older silicone-only architectures with tunable release kinetics. Bayer AG leverages its integrated hormone synthesis capabilities to sustain cost advantages in implant manufacturing. HLL Lifecare Limited anchors public-sector procurement across South Asia through its dominant position in institutional tender channels.
Asia-Pacific contraceptive drugs and devices encompass pharmaceutical formulations and mechanical apparatus designed to prevent pregnancy through hormonal suppression, barrier interruption, or intrauterine interference with implantation; copper-bearing intrauterine devices typically contain 380 mm² of wire surface area to generate a spermicidal ionic environment, while levonorgestrel-releasing systems modulate endometrial receptivity through localized progestin delivery. Intrauterine devices command the deepest margin pools among product types due to their multi-year replacement cycles and limited generic competition. Emergency contraception applications face structural pressure from expanding long-term use segments as health systems prioritize continuity-of-care models over reactive dispensing.
India's CDSCO and China's NMPA govern pre-market authorization for hormonal implants and intrauterine systems, while Australia's TGA enforces post-market surveillance standards that shape regional quality benchmarks. The EU MDR's extraterritorial influence on export-oriented manufacturers creates compliance cascades that filter into Asia-Pacific supply chains. Stakeholders must monitor divergence between national pharmacovigilance requirements and harmonized ASEAN technical standards to anticipate registration bottlenecks.
Market Dynamics
India's CDSCO and China's NMPA have compressed implant registration timelines from 24 months to 14 months, accelerating hormonal polymer formulation availability across Southeast Asian clinic networks. This regulatory synchronization is concentrating procurement power in institutional tender channels.
Growth Catalysts
- Streamlined CDSCO Pathways:India's drug regulator has created dedicated fast-track queues for long-acting reversible contraceptives, reducing approval bottlenecks for hormonal implant manufacturers seeking public-sector contracts.
- Urban Health Network Expansion:Municipal hospital systems in Chinese tier-2 cities are establishing dedicated family planning departments, creating pull-through demand for intrauterine devices with multi-year replacement cycles.
- Polymer-Hormone Convergence:Tunable release kinetics in biodegradable substrates are displacing silicone-only architectures, enabling customized dosing profiles that match regional body-mass index distributions.
Market Restraints
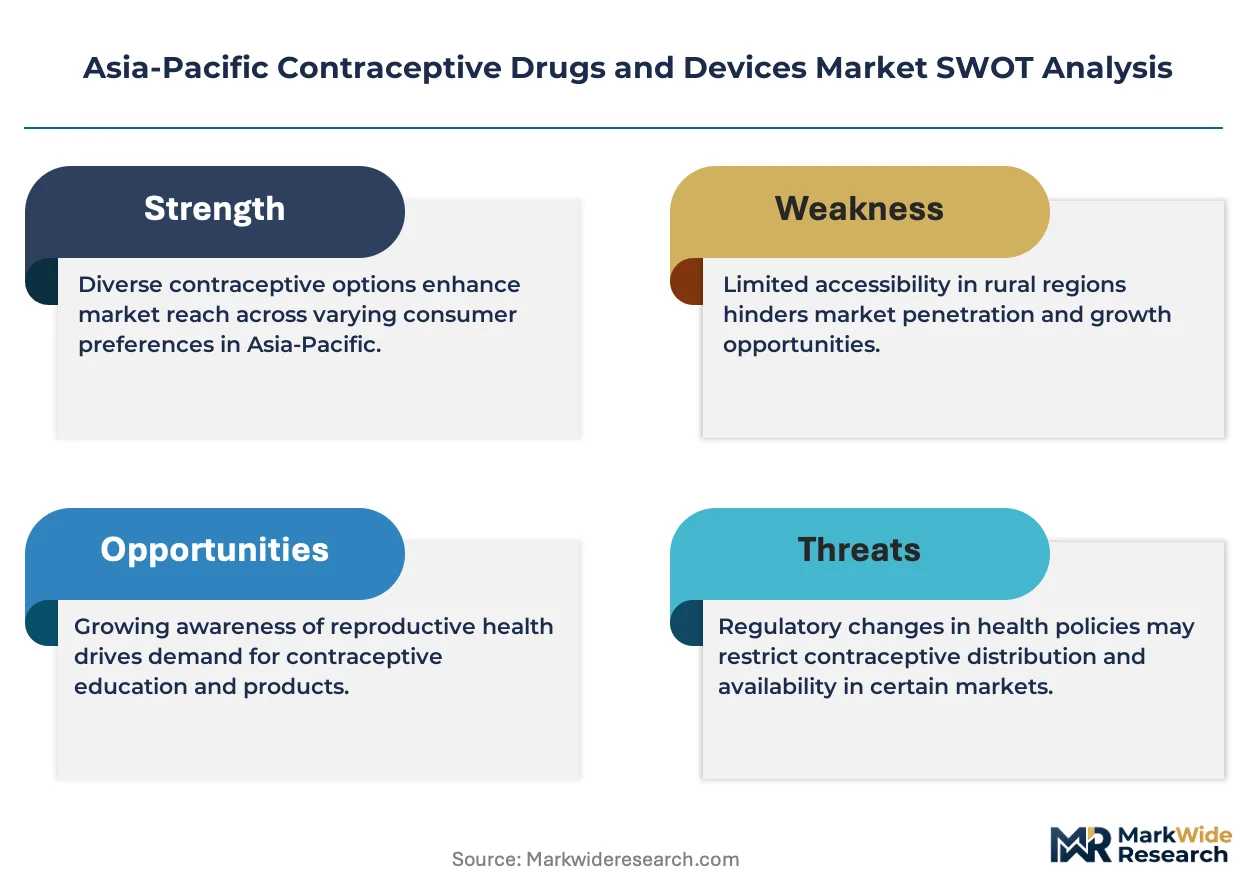
- API Supply Concentration:Levonorgestrel active pharmaceutical ingredient production clusters in three Indian states, exposing downstream implant manufacturers to localized logistics disruptions and input cost volatility.
- Copper Price Exposure:Copper-bearing intrauterine device margins compress when London Metal Exchange prices spike, forcing manufacturers to absorb raw material swings or risk tender disqualification.
- ASEAN Standards Divergence:National pharmacovigilance requirements across Vietnam, Indonesia, and the Philippines lack mutual recognition, fragmenting compliance costs for regional product launches.
Strategic Opportunities
- Rural Indonesia Penetration:Midwife-led distribution networks in Eastern Java and Sulawesi remain underpenetrated for implantable systems, offering first-mover positioning before government tender consolidation.
- Telemedicine Integration:Virtual consultation platforms in Australian metropolitan areas are creating direct-to-patient channels for emergency contraception prescriptions, bypassing traditional pharmacy intermediaries.
- PLI Scheme Alignment:India's production-linked incentive scheme for medical devices subsidizes domestic manufacturing of hormonal delivery systems, reducing landed cost disadvantages against imports.
Industry Challenges
- Biocompatibility Certification Delays:ISO 10993 testing backlog at accredited Southeast Asian laboratories stretches pre-market timelines, forcing manufacturers to queue at European or Australian facilities.
- Legacy Distribution Integration:Public-sector procurement platforms in South Asia require API-to-device traceability systems that conflict with existing ERP configurations, demanding middleware investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Contraceptive Drugs and Devices Market |
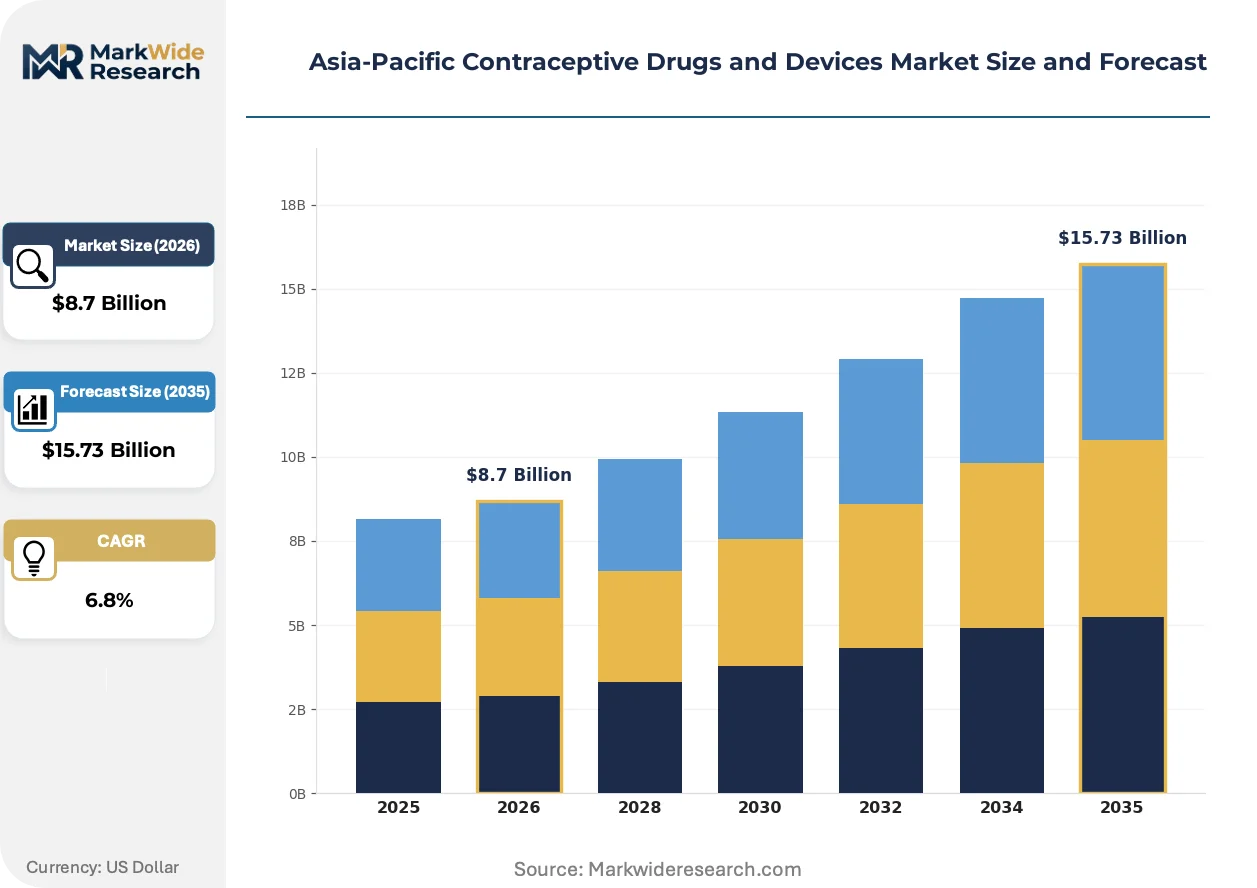
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
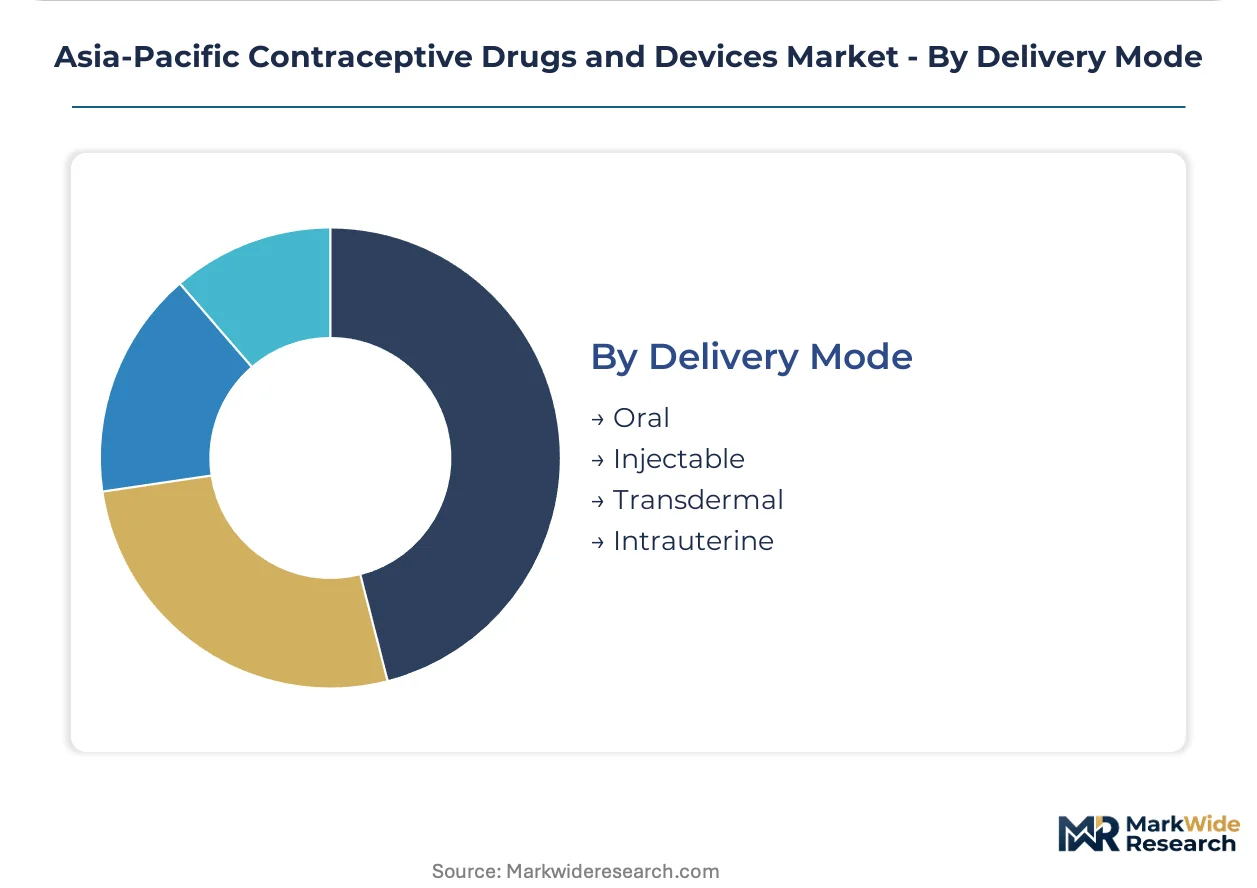
| Segmentation | Product Type: Pills, Intrauterine Devices, Implants, Condoms Application: Emergency Contraception, Long-term Use, Short-term Use, Reproductive Health End User: Hospitals, Clinics, Pharmacies, Home Use Delivery Mode: Oral, Injectable, Transdermal, Intrauterine |
| Companies Covered | CooperSurgical, Inc., China Resources, Bayer AG, Ansell, HLL Lifecare Limited, Pfizer Inc., Allergan PLC, Church & Dwight Co., Inc., Merck & Co., Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Contraceptive Drugs and Devices Market Strategic Shifts
Biodegradable polymer matrices are actively displacing permanent implant architectures across the Asia-Pacific contraceptive landscape. Manufacturers are racing to match release kinetics with regional metabolic profiles while regulators accelerate stability testing protocols.
Hormonal polymer formulations are absorbing the functional requirements previously served by mechanical retrieval systems in implantable devices. Thai and Vietnamese municipal hospitals are piloting single-rod configurations that eliminate explantation procedures. This absorption of retrieval functionality into the substrate itself is compressing total cost-of-ownership calculations in tender evaluations.
China's NMPA has implemented real-world evidence requirements for extended-cycle hormonal products, mandating post-market surveillance data from domestic patient registries. Domestic manufacturers with established hospital data partnerships gain accelerated label expansion pathways. Multinational sponsors without such infrastructure face extended observational study commitments before competitive positioning.
Institutional procurement in India is consolidating from state-level tenders to centralized national frameworks administered through the Government e-Marketplace portal. Tamil Nadu and Karnataka hospital networks have migrated to this platform, compressing supplier qualification cycles from 18 months to 9 months. Bangladesh's Directorate General of Family Planning is observing this migration with adaptation intent.
Asia-Pacific Contraceptive Drugs and Devices Market Segmentation
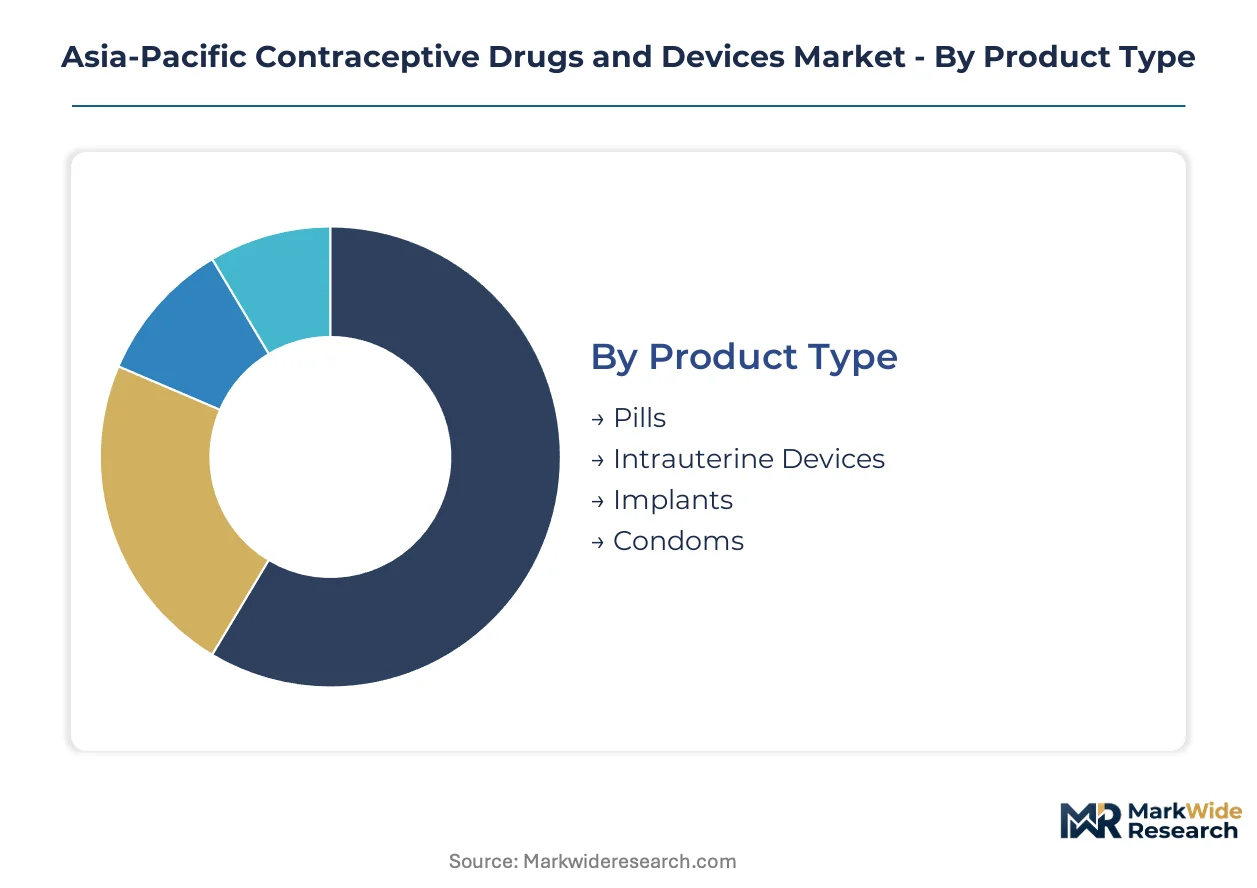
Contraceptive markets fragment along physiological intervention points and care delivery settings. Product architecture determines reimbursement pathways, while end-user channel selection shapes procurement concentration and margin capture.
Product Type:
Material science capabilities differentiate competitive positioning across implantable and pharmaceutical formats.
- Intrauterine Devices:Copper-bearing and hormonal systems generate multi-year revenue cycles through replacement protocols. Chinese municipal hospitals and Indian state procurement frameworks drive volume concentration for levonorgestrel-releasing configurations.
- Implants:Subdermal polymer rods deliver progestin through tunable release kinetics. Southeast Asian clinic networks are absorbing capacity as CDSCO and NMPA registration timelines compress from 24 months to 14 months.
- Pills:Daily oral formulations dominate pharmacy distribution in urban India and Chinese tier-1 cities, with generic competition compressing unit economics.
- Condoms:Barrier methods anchor retail pharmacy and home-use channels across Indonesia and the Philippines, with public-sector tender participation limited by price-point constraints.
Mature deployment sits with pills. Newer deployment is concentrated in implants.
Application:
Clinical intent separates reactive dispensing from continuity-of-care models with divergent margin structures.
- Long-term Use:Intrauterine and implantable systems align with government family planning objectives. India's Government e-Marketplace portal is consolidating state-level tenders into national frameworks, compressing supplier qualification cycles.
- Emergency Contraception:Post-coital hormonal intervention faces structural pressure from expanding long-acting reversible segments. Australian telemedicine platforms are creating direct-to-patient prescription channels that bypass pharmacy intermediaries.
- Short-term Use:Cyclical oral regimens serve transitional reproductive planning needs, with demand clustering in urban Chinese and Indian pharmacy networks.
- Reproductive Health:Comprehensive screening and counseling services bundle contraceptive provision with cervical cancer detection, anchoring hospital-based revenue in Thai and Vietnamese metropolitan systems.
Institutional procurement favors long-term use. Emergency contraception is climbing the fastest as telemedicine infrastructure matures.
End User:
Channel selection determines traceability requirements and pricing authority.
- Clinics:Southeast Asian government health centers represent the steepest expansion trajectory for implantable systems as midwife-led distribution networks penetrate Eastern Java and Sulawesi.
- Hospitals:Chinese tier-2 municipal systems are establishing dedicated family planning departments, creating pull-through demand for intrauterine devices with explantation service integration.
- Pharmacies:Retail networks dominate condom and oral contraceptive distribution, with India's PLI scheme for medical devices subsidizing domestic manufacturing to reduce import dependency.
- Home Use:Direct-to-consumer channels remain underdeveloped outside Australian metropolitan telemedicine pilots, constrained by prescription requirements and cold-chain limitations for hormonal products.
Volume concentration sits with hospitals. Margin expansion is concentrated in clinics.
Delivery Mode:
Administration route dictates manufacturing complexity and regulatory testing burden.
- Intrauterine:Device insertion requires clinical training infrastructure, limiting deployment to hospital and clinic settings with established gynecological services.
- Injectable:Depot formulations serve quarterly dosing schedules, with demand clustering in Indian public-sector programs and Indonesian community health posts.
- Oral:Tablet manufacturing scales efficiently, with API supply concentration in three Indian states exposing downstream formulators to logistics disruptions.
- Transdermal:Patch delivery systems remain niche in Asia-Pacific markets, constrained by skin irritation profiles and higher unit costs relative to oral alternatives.
Established deployment sits with oral delivery. Intrauterine systems are gaining share fastest as biodegradable polymer matrices displace permanent architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in India and China, where urban health networks drive uptake of long-acting reversible contraceptives. Southeast Asian clinic networks represent the steepest expansion trajectory as governments expand family planning access. Regulatory synchronization between India's CDSCO and China's NMPA is compressing implant registration timelines.
India
Municipal hospital systems in tier-2 cities drive intrauterine device uptake through dedicated family planning departments. CDSCO fast-track queues for long-acting reversible contraceptives reduce approval bottlenecks for hormonal implant manufacturers. Tamil Nadu and Karnataka hospital networks have migrated to the Government e-Marketplace portal, compressing supplier qualification cycles.
China
Urban health networks in tier-2 cities establish dedicated family planning departments, creating pull-through demand for multi-year replacement cycle devices. NMPA has implemented real-world evidence requirements for extended-cycle hormonal products, mandating post-market surveillance data from domestic patient registries. Yangtze River Delta municipal hospitals pilot single-rod implant configurations that eliminate explantation procedures.
Indonesia
Midwife-led distribution networks in Eastern Java and Sulawesi remain underpenetrated for implantable systems, offering first-mover positioning. National pharmacovigilance requirements lack mutual recognition with ASEAN neighbors, fragmenting compliance costs for regional product launches. Community health posts in rural corridors absorb depot formulation demand through quarterly dosing schedules.
Australia
Metropolitan telemedicine platforms create direct-to-patient channels for emergency contraception prescriptions, bypassing traditional pharmacy intermediaries. TGA enforces post-market surveillance standards that shape regional quality benchmarks for Asia-Pacific supply chains. Sydney and Melbourne hospital networks anchor comprehensive screening services that bundle contraceptive provision with cervical cancer detection.
Vietnam
Municipal hospitals in Thai Nguyen and Hai Phong pilot biodegradable polymer matrices that displace permanent implant architectures. National standards divergence from ASEAN technical benchmarks creates registration bottlenecks for multinational sponsors. Northern provincial health centers expand implantable system capacity as government tender consolidation proceeds.
Asia-Pacific Contraceptive Drugs and Devices Market Competitive Environment
Capacity expansion dominates the current landscape as manufacturers race to match biodegradable polymer release kinetics with regional metabolic profiles. The vendor base clusters around three strategic archetypes: integrated hormone synthesis specialists, public-sector procurement anchors, and polymer formulation innovators. M&A activity concentrates on polymer-hormone convergence capabilities. Geographic expansion through midwife-led distribution networks in underpenetrated rural corridors represents a parallel competitive vector.
Within the integrated manufacturing tier, Bayer AG leverages captive hormone synthesis capabilities to sustain cost advantages in implant production. HLL Lifecare Limited anchors public-sector procurement across South Asia through dominant positioning in institutional tender channels. Among diversified pharmaceutical conglomerates, Pfizer Inc. and Merck & Co., Inc. occupy positions shaped by oral formulation scale and established pharmacy distribution networks. CooperSurgical, Inc. represents the device-specialist archetype with concentrated exposure to intrauterine system architectures. These four entities exemplify distinct competitive positioning vectors without overlapping core capabilities.
| Leading Market Players |
|---|
| CooperSurgical, Inc. |
| China Resources |
| Bayer AG |
| Ansell |
| HLL Lifecare Limited |
| Pfizer Inc. |
| Allergan PLC |
| Church & Dwight Co., Inc. |
| Merck & Co., Inc. |
| Others |
Value Chain & Pricing Dynamics
Captive hormone synthesis capabilities anchor pricing power for implant manufacturers while exposing copper-dependent IUD producers to London Metal Exchange volatility. Public-sector tender consolidation across South Asia compresses supplier margins through volume aggregation, rewarding players with backward integration into active pharmaceutical ingredient production.
Pricing Analysis
Volume concentrates in oral contraceptives while margin pools deepen in intrauterine devices with multi-year replacement cycles. Pricing stratifies across premium hormone-releasing systems, standard copper-bearing devices, and economy-tier barrier methods, with differentiation driven by certification tier and after-sales service bundling. Cost compression in the copper-IUD segment intensifies because raw material spikes force manufacturers to absorb swings or risk tender disqualification. Public-sector procurement managers exhibit highest price sensitivity, while private hospital networks in Chinese tier-2 cities prioritize clinical performance over unit cost.
Supply Chain Analysis
Freight cost differentials between Indian API hubs and Southeast Asian clinic networks shape regional competitiveness for implant manufacturers. Levonorgestrel active pharmaceutical ingredient production clusters in Maharashtra, Gujarat, and Andhra Pradesh, while polymer substrate fabrication centers on Chinese Yangtze River Delta facilities and Thai industrial estates. Supply chain risk hinges on single-source vulnerability for biodegradable polymer matrices, where ISO 10993 testing backlogs at Southeast Asian laboratories force queuing at Australian or European facilities. Distribution runs through government e-Marketplace portals in India and midwife-led networks in Eastern Java and Sulawesi.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a vertical-integration race into hormone synthesis and polymer formulation capabilities, with CDSCO and NMPA registration timeline compression rewarding players who control upstream substrate development.
For Market Incumbents: Hedge against copper price exposure through long-term offtake agreements with London Metal Exchange clearinghouses, and secure biocompatibility certification capacity at European or Australian laboratories before ISO 10993 testing backlogs worsen. Consolidate position by acquiring polymer-hormone convergence specialists in the Yangtze River Delta to match biodegradable release kinetics with regional metabolic profiles.
For New Entrants and Emerging Players: Launch via midwife-led distribution networks in Eastern Java and Sulawesi, where government tender consolidation has not yet penetrated. Target rural Indonesian community health posts with single-rod implant configurations that eliminate explantation procedures, and pursue fast-track CDSCO queues for long-acting reversible contraceptives before national procurement frameworks fully consolidate.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated pharmaceutical conglomerates seeking hormone synthesis capabilities, with IPO windows requiring demonstrated real-world evidence partnerships with Chinese municipal hospital registries. Target acquisition archetypes are polymer formulation innovators with tunable release kinetics patents and established NMPA registration track records. Watch for inflection when Bangladesh's Directorate General of Family Planning completes its Government e-Marketplace migration.
| Strategic Initiative | Industry Significance |
|---|---|
| Polymer-Hormone Convergence R&D | Tunable release kinetics matching regional BMI distributions displace silicone-only architectures across NMPA-registered products. |
| CDSCO Fast-Track Registration | Dedicated queues for long-acting reversible contraceptives compress approval timelines from 24 months to 14 months. |
| Government e-Marketplace Migration | Tamil Nadu and Karnataka hospital networks reduce supplier qualification cycles from 18 months to 9 months. |
| Real-World Evidence Partnerships | Domestic manufacturers with Chinese municipal hospital data access gain accelerated label expansion pathways. |
| Midwife-Led Distribution Expansion | Eastern Java and Sulawesi networks offer first-mover positioning before Indonesian tender consolidation completes. |
Study Parameters
CDSCO registration filings, NMPA approval databases, and ASEAN harmonization protocols formed the secondary backbone, supplemented by customs records tracking API shipments from Indian manufacturing clusters. Primary interviews with regulatory affairs leads at implant manufacturers, biomedical engineers at Thai and Vietnamese municipal hospitals, and procurement managers at India's Government e-Marketplace portal validated demand assumptions. Bottom-up and top-down triangulation reconciled clinic-level deployment data with national family planning budget allocations.
Bottom-up modeling aggregated patient registry flows and tender award volumes across the projection horizon, while top-down analysis calibrated against healthcare expenditure trajectories in Chinese tier-2 cities and Indian state budgets. Segmentation dimensions included delivery mode, product architecture, end-user channel, and regional regulatory cluster. CAGRs derived from logistic diffusion curves fitted to long-acting reversible contraceptive adoption patterns, with inputs from polymer degradation kinetics studies and hospital capacity expansion pipelines.
Copper price volatility, ASEAN standards divergence, and biocompatibility certification delays are the dominant revision risks that could compress manufacturer margins or extend registration timelines. Stakeholders should weight assumptions against their own operating context and API supply security.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Targeted Liposomes Drug Delivery Market
Pharmaceuticals
Medicinal Fungi Market
Pharmaceuticals
Live Vaccines Market
Pharmaceuticals
RAS-Acting Agents Market
Pharmaceuticals
Pharmaceutical Solid Dosage Contract Manufacturing Market
Pharmaceuticals
Japanese Encephalitis Vaccine Market
Pharmaceuticals
TNF Inhibitors Market
Pharmaceuticals
Asia-Pacific Small Molecule Sterile Injectable Drugs Market
Pharmaceuticals
Complex Injectable Market
Pharmaceuticals
Global Intravenous Solutions Market
Pharmaceuticals
Angiogenesis Inhibitors and Stimulators Market
Pharmaceuticals
Global Antipyretic Drugs for Children Market
Pharmaceuticals
Computer-Aided Drug Discovery Market
Pharmaceuticals
North America Alpha-Glucosidase Inhibitors Market
Pharmaceuticals
Pharmacy Market
Pharmaceuticals
Esomeprazole Market