
 Steroid Injections Market | 2026-2036
Steroid Injections Market Size, Share, and Industry Trends Forecast 2026-2036
Steroid Injections Market Analytics
Sports medicine is shifting toward outpatient steroid injection protocols for tendon and ligament injuries. Pfizer Inc. leverages its broad sterile manufacturing infrastructure to supply hospital systems with preservative-free formulations. Bristol-Myers Squibb Company anchors its position through long-acting corticosteroid R&D programs. Bayer AG competes in the intra-articular segment with established depot formulations for osteoarthritis management.
Steroid injections are sterile pharmaceutical suspensions or solutions containing corticosteroid compounds, typically formulated at concentrations between 10 mg/mL and 40 mg/mL for local anti-inflammatory action. These products function by suppressing immune cell migration and cytokine release at injection sites, providing targeted relief for inflammatory joint conditions, dermatological lesions, and soft-tissue disorders. Glucocorticoids dominate therapeutic volumes due to their potent immunosuppressive and anti-inflammatory profiles across orthopedics and rheumatology. Intramuscular administration routes retain structural importance for systemic conditions, though intra-articular delivery commands premium positioning in sports medicine and hospital outpatient settings. Orthopedics and rheumatology therapy areas concentrate the largest margin pools, driven by repeat procedural volumes in aging patient populations.
The FDA enforces current Good Manufacturing Practice standards for sterile injectable facilities, while the EMA's MDR framework tightens clinical evidence requirements for Class III implantable and injectable devices. ISO 13485 quality management standards govern device-drug combination products in major markets, creating compliance barriers for new entrants. The EPA monitors pharmaceutical manufacturing waste streams containing steroid active pharmaceutical ingredients. Stakeholders must monitor evolving pharmacovigilance requirements for localized steroid side-effect reporting and adapt formulation strategies to address regulatory scrutiny on particulate matter and endotoxin limits.
Market Dynamics
FDA's tightened sterile injectable manufacturing standards are compressing production capacity and forcing facility upgrades across the corticosteroid supply base, reshaping competitive economics for hospital and clinic suppliers.
Growth Catalysts
- Aging Demographics:Expanding Medicare-eligible populations in the United States drive repeat procedural volumes for osteoarthritis and degenerative joint disease management in orthopedic practices.
- EMA MDR Framework:The Medical Device Regulation's clinical evidence requirements for Class III injectables are accelerating consolidation toward manufacturers with robust quality management systems and existing ISO 13485 certification.
- Outpatient Migration:Ambulatory surgical centers are capturing hospital bypass cases for intra-articular procedures, expanding addressable procedure volumes beyond traditional inpatient settings.
Market Restraints
- API Supply Concentration:Corticosteroid active pharmaceutical ingredient production concentrates in Indian and Chinese chemical manufacturing clusters, exposing formulators to geopolitical friction and export control volatility.
- Particulate Compliance Costs:FDA's tightened endotoxin and visible particulate limits for sterile injectables require costly cleanroom upgrades and enhanced quality testing protocols.
- Biologic Substitution:Monoclonal antibody therapies for rheumatoid arthritis and inflammatory conditions are displacing systemic corticosteroid regimens in managed care formularies.
Strategic Opportunities
- Depot Formulation Innovation:Extended-release corticosteroid microsphere technologies enable longer dosing intervals and are capturing premium positioning in sports medicine and pain management clinics.
- Japan's Aging Market:METI's healthcare infrastructure investments and PMDA's streamlined review pathways for locally manufactured sterile injectables create favorable entry conditions for depot formulations.
- Device-Drug Convergence:Combination products integrating pre-filled syringes with needle safety systems are commanding price premiums in hospital outpatient departments seeking reduced liability exposure.
Industry Challenges
- Sterile Manufacturing Talent Scarcity:Aseptic processing operators and quality assurance specialists with current Good Manufacturing Practice experience command wage premiums and extend hiring timelines.
- Legacy System Integration:Electronic batch record systems and automated visual inspection equipment require costly retrofitting in facilities running validated but antiquated production lines.
- Pharmacovigilance Reporting Burden:Localized steroid side-effect surveillance mandates from multiple national regulators strain post-market surveillance infrastructure and adverse event processing capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Steroid Injections Market |
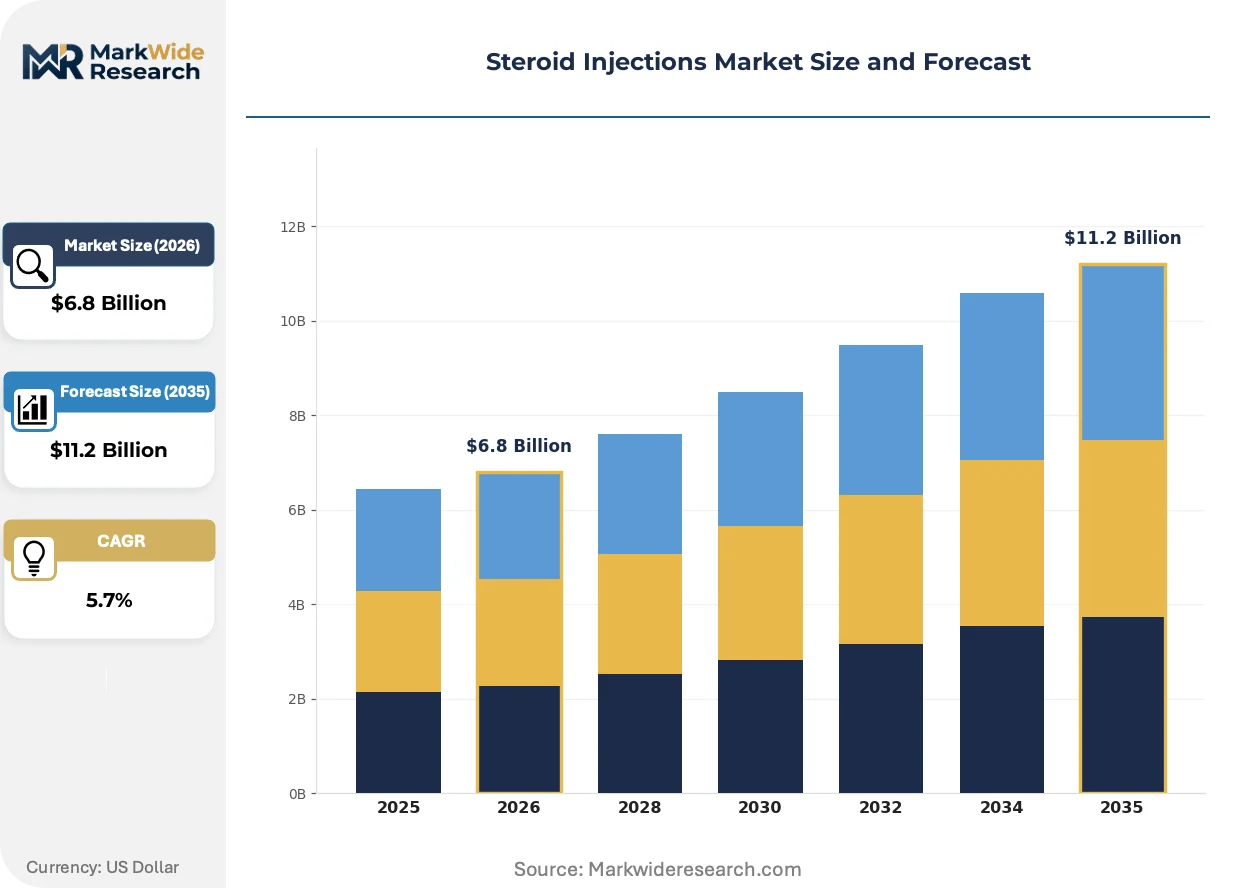
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glucocorticoids, Anabolic Steroids, Mineralocorticoids, Others Therapy Area: Orthopedics, Dermatology, Rheumatology, Sports Medicine Administration Route: Intradermal, Intravenous, Intramuscular, Subcutaneous End User: Hospitals, Clinics, Home Healthcare, Rehabilitation Centers |
| Companies Covered | Pfizer Inc., Bristol-Myers Squibb Company, Merck & Co., Inc., Bayer AG, Mylan N.V., Advanz Pharma, Flexion Therapeutics Inc., Scintilla Pharmaceuticals, Inc., Intrapharm Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Steroid Injections Market Evolving Landscape
Formulation science and delivery mechanism engineering are converging to extend therapeutic duration and reduce injection frequency, compressing the competitive advantage of conventional immediate-release suspensions.
Liposomal corticosteroid encapsulation is electrifying the extended-release segment by enabling sustained drug release over 4-6 week intervals. Sports medicine clinics and orthopedic group practices are adopting these formulations for tendon sheath and bursal injections. The technology is electrifying premium pricing tiers and compressing reimbursement parity with standard depot preparations.
REACH's expanded substance of very high concern candidate list is forcing reformulation of certain corticosteroid esters and solvent systems used in European-manufactured injectables. Chemical suppliers are accelerating substitution programs for phthalate-based plasticizers in primary container components. The regulatory pressure is reshaping raw material sourcing strategies for companies supplying EMA-regulated markets.
Hospital outpatient departments are unbundling procedure reimbursement from drug acquisition costs, creating transparent price competition among corticosteroid suppliers. Group purchasing organizations are consolidating steroid injection contracts and mandating standardized formularies across member health systems. The purchasing transformation is most visible in United States integrated delivery networks seeking to reduce per-procedure supply expenses.
Steroid Injections Market Segmentation
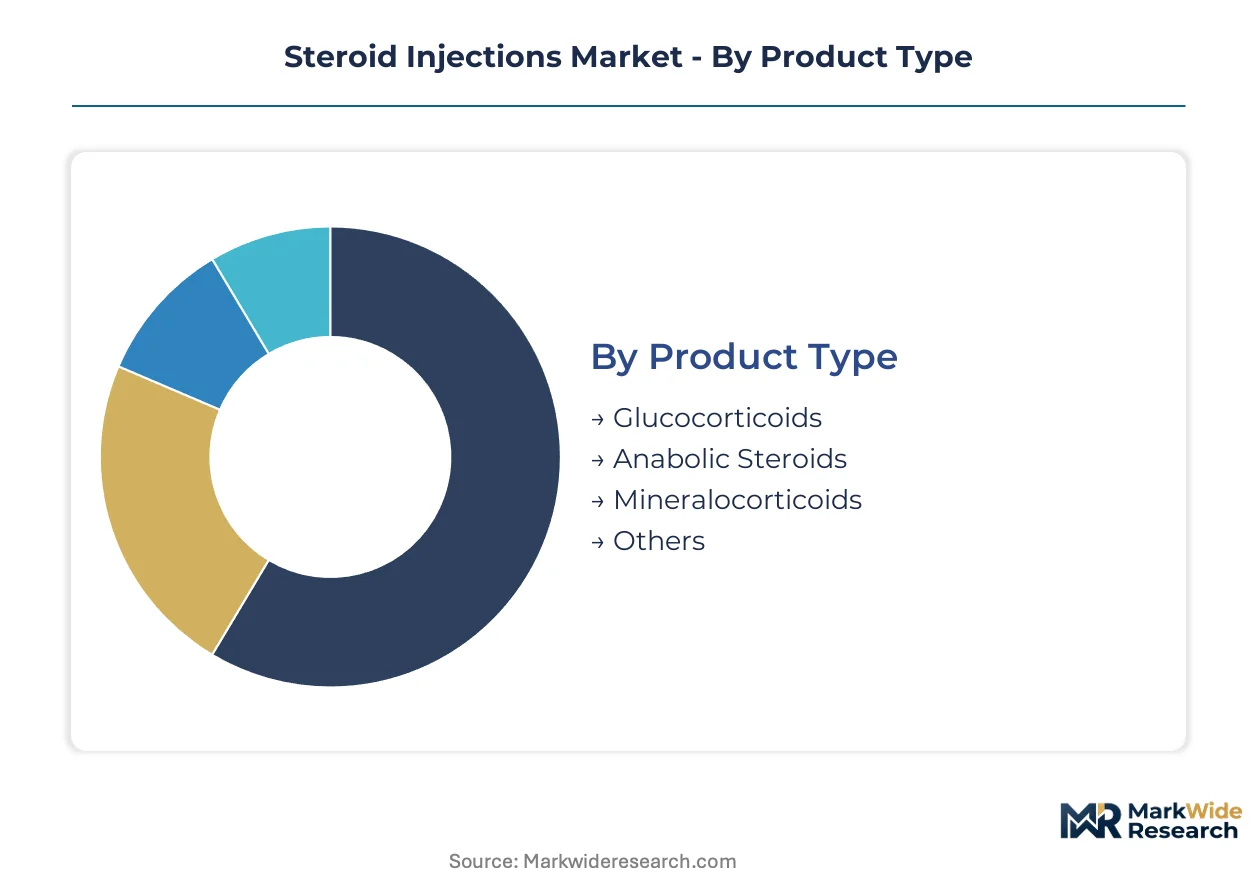
Steroid injection markets fragment across therapeutic mechanism, delivery site, and care setting. Each segmentation axis reveals distinct margin structures, regulatory pathways, and procurement dynamics that shape competitive positioning for formulators and device suppliers.
Product Type:
Volume concentrates in anti-inflammatory glucocorticoids, while premium pricing attaches to specialized anabolic and mineralocorticoid formulations for niche indications.
- Glucocorticoids:Synthetic corticosteroid compounds including methylprednisolone, triamcinolone, and betamethasone dominate procedural volumes in orthopedic and rheumatology practices. Demand concentrates in United States ambulatory surgical centers performing intra-articular injections for osteoarthritis, driven by Medicare reimbursement for outpatient joint procedures.
- Anabolic Steroids:Testosterone esters and nandrolone formulations target muscle wasting conditions and hormone replacement protocols. Sports medicine clinics in Germany and Australia are expanding off-label use for tendon repair adjuvant therapy, though regulatory scrutiny limits formulary penetration.
- Mineralocorticoids:Fludrocortisone acetate injections address adrenal insufficiency and orthostatic hypotension in hospital emergency departments.
- Others:Combination corticosteroid-anesthetic preparations and novel ester variants serve specialized pain management protocols.
Today's leader: Glucocorticoids. Tomorrow's challenger: Anabolic Steroids.
Therapy Area:
Application-driven demand splits between high-frequency joint procedures and lower-volume specialty indications with superior reimbursement rates.
- Orthopedics:Intra-articular and peri-tendinous injections for degenerative joint disease, bursitis, and entrapment neuropathies generate repeat procedural volumes. Aging patient populations in Japan and Italy are expanding addressable cases for knee and shoulder interventions.
- Sports Medicine:Athlete injury management protocols favor ultrasound-guided corticosteroid delivery for precise anatomical targeting. FIFA-accredited medical centers in Spain and Brazil are standardizing depot formulations for ligament and tendon sheath applications.
- Dermatology:Intralesional triamcinolone addresses keloid scarring, alopecia areata, and inflammatory skin conditions in dermatology group practices.
- Rheumatology:Systemic and intra-articular regimens for rheumatoid arthritis, gout flares, and polymyalgia rheumatica compete with biologic disease-modifying therapies in managed care formularies.
Orthopedics commands current volume leadership, while Sports Medicine exhibits the steepest expansion trajectory as outpatient athlete care protocols proliferate.
Administration Route:
Delivery mechanism selection hinges on pharmacokinetic requirements, anatomical target accessibility, and facility reimbursement structures.
- Intramuscular:Deep gluteal or deltoid depot injections enable sustained systemic corticosteroid release for inflammatory conditions. Primary care networks in the United Kingdom and Canada rely on this route for acute exacerbation management where hospital access is constrained.
- Intravenous:High-dose methylprednisolone pulse therapy for acute spinal cord injury, multiple sclerosis flares, and severe allergic reactions concentrates in tertiary hospital emergency departments and neurocritical care units.
- Intradermal:Superficial corticosteroid delivery targets localized dermatological and aesthetic applications.
- Subcutaneous:Self-administered anabolic steroid protocols in home healthcare settings require patient training and sharps disposal infrastructure.
Intramuscular administration retains structural importance for systemic therapy, while intravenous delivery captures premium positioning in acute care reimbursement tiers.
End User:
Procurement authority and volume scale diverge sharply between consolidated hospital systems and fragmented outpatient settings.
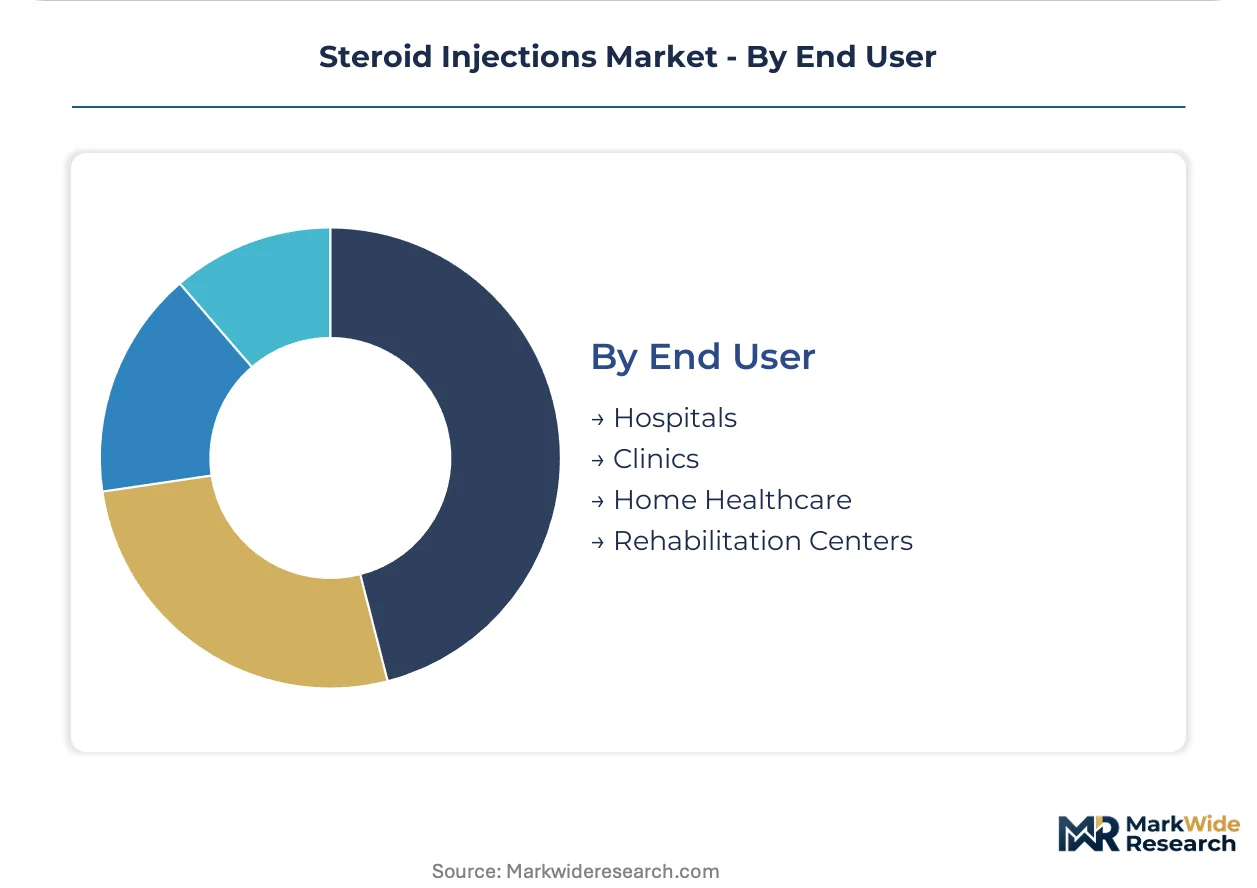
- Hospitals:Integrated delivery networks and academic medical centers leverage group purchasing organization contracts to standardize corticosteroid formularies across emergency, orthopedic, and rheumatology service lines. FDA-mandated sterile injectable compliance costs disproportionately burden smaller community hospitals.
- Clinics:Independent orthopedic, sports medicine, and pain management practices drive intra-articular procedure volumes through direct-to-physician distribution channels. United States ambulatory surgery center joint ventures with hospital systems are consolidating purchasing for high-frequency injection protocols.
- Home Healthcare:Self-injection training programs and remote monitoring infrastructure support subcutaneous anabolic steroid regimens for chronic conditions.
- Rehabilitation Centers:Post-acute facilities coordinate with referring physicians for interval joint injections during functional recovery protocols.
Hospitals anchor current purchasing volume, though Clinics are gaining procurement influence as outpatient migration accelerates procedural site-of-care shifts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting sterile injectable production toward jurisdictions with streamlined compliance pathways and lower facility certification costs. Manufacturers are relocating finishing operations to exploit gaps in FDA, EMA, and PMDA enforcement intensity while maintaining API sourcing from established chemical clusters.
United States
Medicare reimbursement for outpatient intra-articular procedures drives volume concentration in ambulatory surgical centers and orthopedic group practices. FDA's tightened endotoxin and particulate limits for sterile injectables are forcing domestic facility upgrades and compressing production capacity. New Jersey and North Carolina pharmaceutical manufacturing corridors host the majority of corticosteroid formulation sites serving hospital integrated delivery networks.
Germany
EMA MDR framework implementation is accelerating consolidation toward manufacturers with pre-existing ISO 13485 certification and robust quality management systems. REACH substance of very high concern regulations are forcing reformulation of certain corticosteroid esters and solvent systems in European-manufactured injectables. Bavaria's chemical-pharmaceutical cluster around Ludwigshafen and Leverkusen anchors continental production for depot formulations.
Japan
METI healthcare infrastructure investments and PMDA streamlined review pathways for locally manufactured sterile injectables create favorable entry conditions for extended-release formulations. Aging demographics expand addressable cases for knee and shoulder interventions in orthopedic practices. Kanto region pharmaceutical manufacturing around Tokyo and Kanagawa Prefecture concentrates domestic corticosteroid finishing operations.
India
Corticosteroid active pharmaceutical ingredient production concentrates in Gujarat and Maharashtra chemical manufacturing clusters, exposing formulators to export control volatility and geopolitical friction. CDSCO manufacturing standards for sterile injectables are tightening compliance requirements for domestic and export-oriented facilities. Hyderabad and Mumbai pharmaceutical corridors supply global formulators with methylprednisolone and triamcinolone intermediates.
Brazil
ANVISA pharmacovigilance requirements for localized steroid side-effect reporting are straining post-market surveillance infrastructure among domestic distributors. Sports medicine clinics in São Paulo and Rio de Janeiro are expanding ultrasound-guided corticosteroid delivery for athlete injury management. Southeast regional manufacturing around São Paulo state anchors Latin American formulation capacity for intra-articular products.
Steroid Injections Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with formulation innovators commanding premium positioning in sports medicine while generic suppliers compete on acquisition cost in hospital formularies. Market structure tilts toward consolidated supply among top-tier sterile injectable houses with validated aseptic processing infrastructure. Three archetypes dominate: Big Pharma integrated units with broad hospital contracts, mid-cap depot formulation specialists, and API-forward Indian manufacturers with backward integration into corticosteroid chemistry. Competitive moves concentrate on M&A for sterile manufacturing capacity and strategic partnerships for liposomal delivery technology licensing.
Among US-based pharmaceutical conglomerates, Pfizer Inc. and Bristol-Myers Squibb Company occupy positions exemplifying the Big Pharma integrated archetype with established hospital system relationships. Bayer AG represents the European depot formulation specialist model with historical intra-articular product portfolios. These three companies anchor competitive dynamics across distinct geographic and therapeutic positioning vectors.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Bristol-Myers Squibb Company |
| Merck & Co., Inc. |
| Bayer AG |
| Mylan N.V. |
| Advanz Pharma |
| Flexion Therapeutics Inc. |
| Scintilla Pharmaceuticals, Inc. |
| Intrapharm Laboratories |
| Others |
Value Network & Pricing Analysis
Hospital integrated delivery networks and ambulatory surgical center joint ventures concentrate procurement authority for steroid injections, locking in contract-based long-term offtake pricing with tiered discounts tied to volume commitments and formulary exclusivity clauses.
Pricing Analysis
Distributor margins for corticosteroid injectables compress at the wholesale tier while direct-to-clinic channels capture premium positioning for liposomal depot formulations. Three-tier pricing structure across premium, standard, and economy levels separates extended-release microsphere technologies from conventional immediate-release suspensions and commodity generic vials. Pricing pressure stems from group purchasing organization consolidation mandating standardized formularies across member health systems. Ambulatory surgical centers exhibit highest price sensitivity due to unbundled reimbursement structures, while academic medical centers prioritize supply security over acquisition cost.
Supply Chain Analysis
Direct-to-clinic distribution channels handle high-frequency intra-articular procedure demand, while hospital system contracts route through specialized pharmaceutical distributors with cold-chain capabilities. Active pharmaceutical ingredient production draws from India and China chemical manufacturing clusters, with finishing operations concentrated in United States, Germany, and Japan pharmaceutical corridors. Methylprednisolone and triamcinolone intermediates, sterile vial components, and liposomal encapsulation excipients anchor raw material dependencies. Single-source vulnerability in Indian API supply exposes formulators to export control volatility and geopolitical friction.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Steroid injection markets offer margin expansion through depot formulation premiumization and manufacturing automation cost-down programs, with liposomal delivery technologies commanding sustained price premiums over conventional suspensions.
For Market Incumbents: Hedge API supply disruption through backward integration into corticosteroid chemistry or captive supply agreements with Indian and Chinese manufacturers. Accelerate sterile manufacturing automation to offset wage premiums for aseptic processing operators. Defend against biologic substitution in rheumatology by expanding sports medicine and orthopedic clinic partnerships for intra-articular protocols. For New Entrants and Emerging Players: Independent pain management clinics in United States metropolitan markets represent the most penetrable buyer archetype, underserved by legacy hospital-contracted suppliers. Target ultrasound-guided injection protocols with pre-filled syringe and needle safety combination products. Pursue PMDA streamlined review pathways for Japan's aging knee and shoulder intervention market as a geographic beachhead. For Investors and Strategic Acquirers: Big Pharma integrated units with hospital system relationships are the most active acquirer in this space, seeking sterile injectable capacity and liposomal delivery technology licensing. Mid-cap depot formulation specialists with ISO 13485 certification and existing EMA MDR technical documentation represent prime acquisition targets. Monitor FDA sterile injectable facility inspection citation rates as an inflection indicator for supply-constrained pricing power shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Liposomal Encapsulation Licensing | Flexion Therapeutics and depot specialists capture premium positioning in sports medicine clinics. |
| Sterile Manufacturing Scale-Up | Facilities in New Jersey and North Carolina corridors serve hospital integrated delivery networks. |
| EMA MDR Technical Documentation | ISO 13485-certified manufacturers accelerate consolidation in European corticosteroid markets. |
| Device-Drug Combination Development | Pre-filled syringes with needle safety systems command price premiums in outpatient departments. |
| API Backward Integration | Gujarat and Maharashtra chemical clusters provide captive supply security against export volatility. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with regulatory affairs leads at sterile injectable manufacturers, hospital procurement managers at integrated delivery networks, and formulary directors at group purchasing organizations with secondary validation against FDA filings, EMA MDR technical documentation, ClinicalTrials.gov entries, and CMS Medicare outpatient procedure databases. Bottom-up procedure volume estimates triangulated against top-down pharmaceutical shipment data.
Segment-weighting approaches distributed value across glucocorticoid, anabolic, and mineralocorticoid product types; orthopedics, sports medicine, dermatology, and rheumatology therapy areas; and intramuscular, intravenous, and intra-articular administration routes. CAGRs derived from procedure volume growth trajectories, pricing trend analysis, and reimbursement rate evolution across the projection horizon. Forecast inputs incorporated aging demographic projections, sterile manufacturing capacity constraints, and biologic substitution elasticities in managed care formularies.
Underlying measurement precision varies by segment; hospital outpatient procedure volumes carry tighter precision than home healthcare self-injection estimates due to claims data availability. Forecasts reflect assumptions regarding FDA enforcement intensity, EMA MDR implementation timelines, and API export policy stability in India and China. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Asia-Pacific Vaccines Market
Pharmaceuticals
Sodium Aescinate Market
Pharmaceuticals
Spain Opioids Market
Pharmaceuticals
Opioids Market
Pharmaceuticals
G Protein Coupled Receptors (Gpcrs) Market
Pharmaceuticals
Atopic Dermatitis Drugs Market
Pharmaceuticals
Rabeprazole Sodium Market
Pharmaceuticals
Male Hypogonadism Market
Pharmaceuticals
Testosterone Nasal Gels Market
Pharmaceuticals
US Transdermal Drug Delivery System Market
Pharmaceuticals
Global Anti-Retroviral Drugs Market
Pharmaceuticals
Europe Anesthesia Drugs Market
Pharmaceuticals
Global Compounding Pharmacy Market
Pharmaceuticals
Hydroxycarbamide Market
Pharmaceuticals
Nephrology Drugs Market
Pharmaceuticals
Global Antipyretic Drugs for Children Market