
 Oral Anti-Diabetic Drugs Market | 2026-2036
Oral Anti-Diabetic Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Oral Anti-Diabetic Drugs Market Analytics
Extended-release formulation tiers is bifurcating the competitive landscape between premium bioequivalent brands and high-volume generics. Novo Nordisk leverages its insulin-to-oral pipeline integration to sustain patient continuity across therapy stages. Eli Lilly and Company anchors its position through differentiated cardiovascular outcome claims for SGLT2 inhibitor portfolios. Sanofi competes on manufacturing scale, occupying cost leadership in metformin supply across European hospital networks.
Oral anti-diabetic drugs comprise small-molecule pharmaceutical agents administered per os to lower blood glucose through mechanisms including hepatic glucose suppression, insulin sensitization, or renal glucose excretion, with bioavailability parameters and dissolution profiles governing therapeutic efficacy. These agents serve as foundational therapy for type 2 diabetes mellitus, reducing HbA1c levels to delay microvascular complications and defer insulin dependency. SGLT2 inhibitors command the fastest expansion trajectory among product types, driven by heart failure risk reduction indications that extend prescriber preference beyond glycemic control alone. Homecare delivery mode segments are capturing disproportionate growth as remote patient monitoring platforms enable titration without clinic visits. Combination therapies concentrate margin pools where single-pill regimens improve adherence metrics and command pricing premiums over component monotherapies.
FDA bioequivalence standards and EMA's MDR compliance requirements shape formulation development costs and generic substitution rules across the United States and European Union. The EPA oversees active pharmaceutical ingredient manufacturing discharge permits, constraining production location decisions for metformin and sulfonylurea intermediates. China's NMPA alignment with ICH Q3D elemental impurity guidelines is forcing reformulation of legacy products for export eligibility. Stakeholders must monitor evolving pharmacovigilance obligations for sodium-glucose cotransporter inhibitors as renal impairment labeling requirements tighten across major regulatory jurisdictions.
Market Dynamics
Fixed-dose combination therapies are compressing the oral anti-diabetic landscape into single-pill dominance, forcing manufacturers to abandon standalone metformin portfolios and reallocate R&D toward dual-mechanism formulations that hospital formularies now prioritize.
Growth Catalysts
- IRA Medicare price negotiation:The US Inflation Reduction Act caps out-of-pocket insulin costs and extends oral agent coverage, expanding patient access to SGLT2 inhibitors and DPP-4 combinations through Medicare Part D expansion.
- Cardiovascular outcome labeling:FDA-approved heart failure risk reduction claims for empagliflozin and dapagliflozin classes are pulling prescribing behavior beyond endocrinology into cardiology practices.
- Hospital pharmacy centralization:Integrated delivery networks in the United States are consolidating procurement through 340B program participation, driving volume commitments for extended-release metformin and combination tablets.
Market Restraints
- API supply concentration:Metformin hydrochloride active pharmaceutical ingredient production clusters in Zhejiang and Shandong provinces, exposing formulators to single-source disruption risks from China's environmental compliance shutdowns.
- Renal impairment labeling restrictions:FDA and EMA tightening of eGFR thresholds for SGLT2 inhibitor initiation is shrinking the addressable patient population for manufacturers dependent on broad-spectrum prescribing.
- Biosimilar insulin substitution:Improved bioequivalence of basal insulin analogs is pulling late-stage type 2 patients toward injectable therapy earlier, compressing the oral-to-insulin transition window.
Strategic Opportunities
- Homecare titration platforms:Remote patient monitoring integration with continuous glucose monitors enables dose adjustment without clinic visits, opening pharmacy-direct dispensing channels bypassing traditional physician intermediation.
- Fixed-dose triple combinations:Unmet demand exists for metformin-SGLT2 inhibitor-DPP-4 antagonist single pills, with only one approved formulation currently capturing this adherence-improving white space.
- EMA MDR compliance services:European manufacturers face legacy product recertification deadlines, creating consultancy and contract manufacturing demand for pharmacovigilance documentation and clinical evidence packages.
Industry Challenges
- Bioequivalence study bottlenecks:FDA's tightened statistical criteria for generic extended-release formulations are extending ANDA approval timelines and inflating clinical pharmacology program costs for mid-tier manufacturers.
- Legacy system integration:Hospital pharmacy enterprise resource planning platforms require EHR interoperability upgrades to support real-time formulary management of combination therapies across multiple sites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oral Anti-Diabetic Drugs Market |
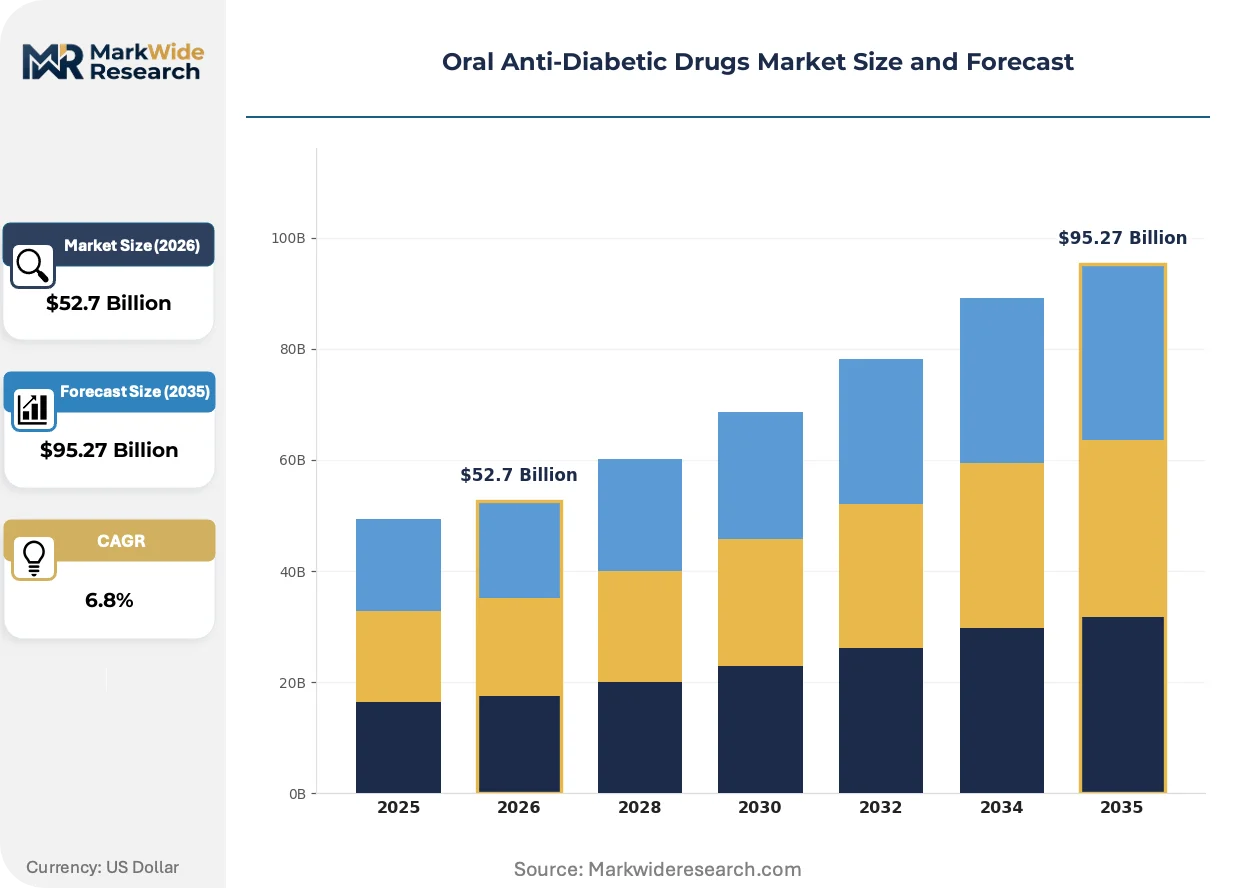
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $95.27 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metformin, Sulfonylureas, DPP-4 Inhibitors, SGLT2 Inhibitors End User: Hospitals, Clinics, Pharmacies, Homecare Delivery Mode: Oral Tablets, Oral Solutions, Extended-Release Tablets, Combination Therapies Therapy Area: Type 2 Diabetes, Prediabetes, Metabolic Syndrome, Insulin Resistance |
| Companies Covered | Sanofi, Novo Nordisk, Eli Lilly and Company, AstraZeneca, Merck & Co., Boehringer Ingelheim, Takeda Pharmaceutical Company, Johnson & Johnson, Pfizer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oral Anti-Diabetic Drugs Market Evolving Landscape
Oral anti-diabetic development is pivoting from glycemic-centric molecules to cardiorenal-protective platforms, with formulation science and digital therapeutics converging to redefine adherence and outcome measurement.
Extended-release polymer matrix technology is bifurcating the competitive landscape between premium bioequivalent brands and high-volume generics. Hospital systems in the United States are accelerating procurement of once-daily metformin formulations that reduce pill burden for elderly populations. This technology is bifurcating manufacturing investment, with specialized contract development organizations capturing value from complex dissolution profile engineering while commodity producers face margin compression.
EMA's Medical Device Regulation recertification deadlines are forcing reformulation of legacy combination products containing dose-counting mechanisms. Manufacturers must resubmit technical documentation for fixed-dose pens and blister packs previously grandfathered under the MDD framework. European hospital networks are responding by consolidating supplier lists to vendors with established notified body relationships, privileging larger pharmaceutical groups over regional players.
Homecare delivery models are displacing clinic-based titration protocols as the standard of care initiation pathway. Pharmacy benefit managers are unbundling dispensing from physician reimbursement, enabling direct-to-patient shipment of 90-day supplies with remote monitoring integration. This shift concentrates in Medicare Advantage plans operating in Florida and Arizona, where elderly population density supports centralized distribution hub economics.
Oral Anti-Diabetic Drugs Market Segmentation
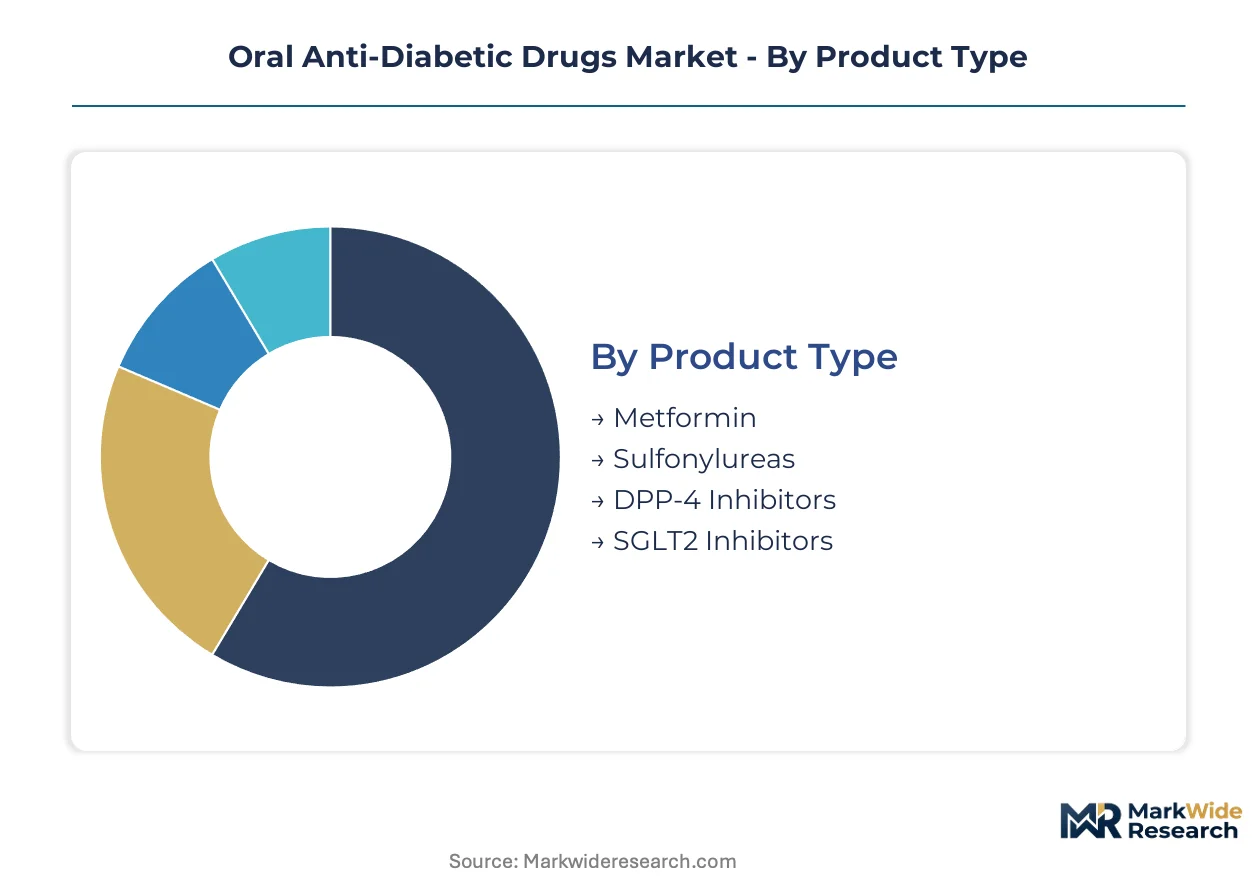
Oral anti-diabetic drug procurement channels diverge sharply across patient acuity levels and reimbursement structures. Hospital formularies prioritize extended-release formulations for newly diagnosed populations, while retail pharmacies capture maintenance therapy refills through Medicare Part D networks.
Product Type:
Channel mix varies by mechanism of action, with SGLT2 inhibitors flowing predominantly through specialty pharmacy tiers and metformin dominating 340B hospital procurement.
- SGLT2 Inhibitors:Sodium-glucose cotransporter-2 blockers reduce renal glucose reabsorption with demonstrated cardiovascular outcome benefits. Demand concentrates in United States Medicare Advantage plans where cardiology co-prescribing protocols have expanded beyond endocrinology departments.
- DPP-4 Inhibitors:Dipeptidyl peptidase-4 antagonists enhance incretin hormone activity with weight-neutral profiles. United States hospital systems favor these agents for elderly populations where hypoglycemia avoidance drives formulary placement.
- Metformin:Biguanide compounds suppress hepatic gluconeogenesis as first-line monotherapy. Generic substitution rates exceed 95% in United States retail channels.
- Sulfonylureas:Pancreatic beta-cell secretagogues with established hypoglycemia risk profiles. Prescribing concentrates in Medicaid populations where acquisition cost governs selection.
Metformin dominates installed base. SGLT2 inhibitors are where expansion concentrates.
End User:
Cost tier stratification separates acute intervention sites from chronic disease management venues, with reimbursement differentials driving site-of-care migration.
- Hospitals:Inpatient and emergency department settings manage acute hyperglycemic crises and initiate oral therapy prior to discharge. United States integrated delivery networks consolidate purchasing through centralized 340B pharmacies.
- Homecare:Remote patient monitoring platforms enable dose titration without clinic visits. Medicare Advantage penetration in Florida and Arizona supports pharmacy-direct dispensing economics.
- Clinics:Outpatient endocrinology and primary care practices manage dose escalation and combination therapy transitions. Fee-for-service reimbursement pressures constrain prescribing flexibility.
- Pharmacies:Community and specialty pharmacies capture 90-day maintenance supplies through pharmacy benefit manager networks. Prior authorization requirements delay SGLT2 inhibitor dispensing.
Hospitals anchor volume procurement. Homecare delivery is climbing the fastest.
Delivery Mode:
Application requirements dictate formulation selection, with polypharmacy populations driving adherence-focused engineering.
- Extended-Release Tablets:Polymer matrix formulations enable once-daily metformin dosing with reduced gastrointestinal adverse events. United States geriatric populations in Medicare Part D plans generate disproportionate demand for pill burden reduction.
- Combination Therapies:Fixed-dose dual and triple mechanism tablets improve adherence metrics. Hospital formularies in United States systems prioritize single-pill regimens for formulary compliance monitoring.
- Oral Tablets:Immediate-release formulations remain standard for sulfonylurea and DPP-4 inhibitor classes. Generic substitution protocols apply across Medicaid programs.
- Oral Solutions:Liquid formulations serve pediatric populations and patients with swallowing disorders. Compounding pharmacies manufacture these preparations under United States FDA 503B regulations.
Oral tablets dominate installed base. Combination therapies are gaining share fastest.
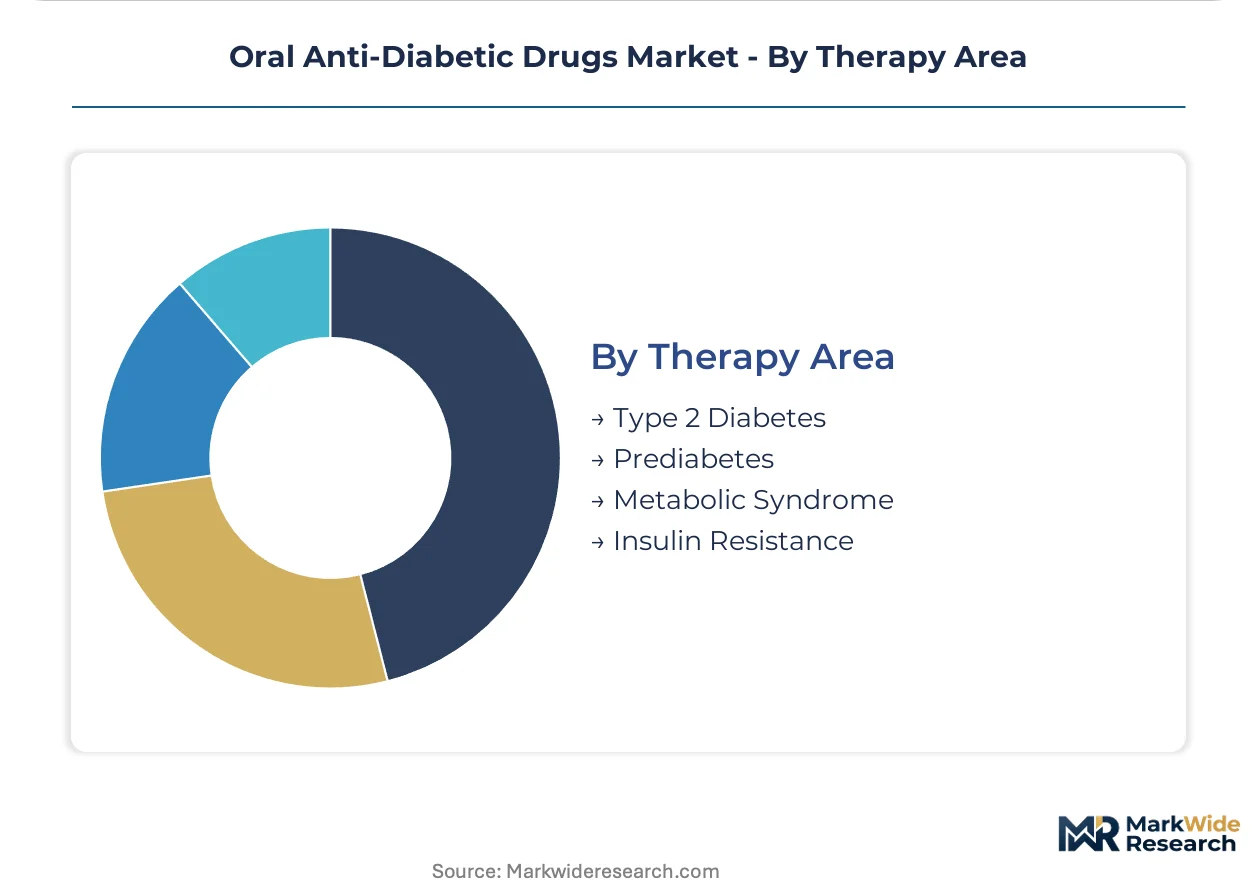
Therapy Area:
Patient population maturity separates established disease management from emerging preventive prescribing, with label expansion driving addressable market redefinition.
- Type 2 Diabetes:Established disease state with HbA1c targets driving therapeutic intensity escalation. United States clinical practice guidelines prioritize oral agents prior to insulin initiation.
- Prediabetes:Impaired glucose tolerance populations with emerging pharmacologic intervention indications. United States Preventive Services Task Force screening expansion broadens identification.
- Metabolic Syndrome:Cluster of cardiovascular risk factors including dysglycemia. Off-label utilization concentrates in cardiology practices seeking multi-risk factor modification.
- Insulin Resistance:Pathophysiologic state preceding beta-cell failure. Polycystic ovary syndrome populations generate niche demand for insulin sensitizers.
Type 2 diabetes dominates installed base. Prediabetes represents the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Active pharmaceutical ingredient manufacturing clusters in eastern China dominate metformin hydrochloride supply, exposing formulators to environmental compliance shutdown risks. Formulation development and commercialization concentrate in the United States and Western Europe, where regulatory pathways for fixed-dose combinations are accelerating product launches.
United States
Medicare Part D expansion and IRA price negotiation caps are driving SGLT2 inhibitor volume through cardiology co-prescribing protocols. FDA accelerated approval pathways for dual-mechanism tablets are compressing development timelines. Hospital procurement centralization through 340B program participation concentrates purchasing in integrated delivery networks across Florida and Arizona.
Germany
EMA MDR recertification deadlines are forcing legacy product reformulation for dose-counting blister packs. Hospital networks in Bavaria and North Rhine-Westphalia are consolidating supplier lists to vendors with established notified body relationships. Domestic manufacturing of extended-release metformin serves as the distribution hub for European hospital pharmacy networks.
China
NMPA alignment with ICH Q3D elemental impurity guidelines is forcing reformulation of legacy sulfonylurea products for export eligibility. Zhejiang and Shandong provinces host concentrated metformin API production clusters subject to MEE environmental discharge permit enforcement. Domestic demand for SGLT2 inhibitors is accelerating through national reimbursement list inclusion.
Japan
PMDA pharmacovigilance requirements for renal impairment labeling are tightening prescriber protocols for sodium-glucose cotransporter inhibitors. Elderly population demographics in the Kanto region are driving demand for once-daily extended-release formulations that reduce pill burden. Domestic manufacturers are prioritizing combination therapy development for hospital formulary placement.
India
CDSCO streamlined approval pathways for fixed-dose combinations are attracting contract manufacturing investment from multinational sponsors. Gujarat and Maharashtra pharmaceutical clusters are expanding metformin formulation capacity for export to African and Southeast Asian markets. Domestic prescribing concentrates on cost-optimized sulfonylurea generics for Medicaid-equivalent populations.
Oral Anti-Diabetic Drugs Market Competitive Landscape
Concentration sits with integrated pharmaceutical conglomerates that command vertical control from API supply through hospital formulary contracting. Three strategic archetypes dominate: insulin-to-oral pipeline integrators sustaining patient continuity across therapy stages, cardiovascular outcome differentiators leveraging FDA-approved heart failure claims, and manufacturing scale leaders occupying cost leadership in high-volume generic categories. Competitive moves center on fixed-dose combination portfolio expansion and 340B program volume commitments.
Within the pipeline integration archetype, Novo Nordisk and Eli Lilly and Company exemplify strategies that bridge injectable and oral therapy stages. Sanofi occupies a position representing manufacturing scale leadership in legacy biguanide supply. AstraZeneca and Boehringer Ingelheim sit within the cardiovascular outcome differentiation tier, with empagliflozin-class portfolios anchored by FDA-approved heart failure risk reduction labeling that extends prescriber reach beyond endocrinology into cardiology practices. Merck & Co. represents the DPP-4 inhibitor specialization archetype with weight-neutral positioning for elderly populations.
| Leading Market Players |
|---|
| Sanofi |
| Novo Nordisk |
| Eli Lilly and Company |
| AstraZeneca |
| Merck & Co. |
| Boehringer Ingelheim |
| Takeda Pharmaceutical Company |
| Johnson & Johnson |
| Pfizer |
| Others |
Value Network & Pricing Analysis
API manufacturing scale economies in Zhejiang province anchor cost floors for metformin hydrochloride, concentrating bargaining power among bulk purchasers while fragmenting margin pools for formulation-only competitors. This scale concentration simultaneously depresses spot-market pricing for commodity generics and inflates premiums for extended-release polymer matrix technologies that hospital formularies now mandate.
Pricing Analysis
IRA Medicare price negotiation dictates the pricing tier structure across oral anti-diabetic portfolios, compressing SGLT2 inhibitor net prices while preserving margin pools for fixed-dose combination therapies exempt from early negotiation rounds. Three-tier pricing structure across premium cardiovascular-outcome brands, standard DPP-4 inhibitors, and economy sulfonylurea generics governs hospital procurement. Cost compression in the metformin tier is intensifying because 340B program participation concentrates volume with integrated delivery networks demanding 90-day supply commitments. Medicaid populations exhibit highest price sensitivity, while Medicare Advantage plans with cardiology co-prescribing protocols demonstrate lowest sensitivity to SGLT2 inhibitor premiums.
Supply Chain Analysis
Container availability constraints on Shanghai-to-Long Beach trade lanes are extending lead times for metformin hydrochloride API shipments, forcing European formulators to maintain elevated safety stock levels. Active pharmaceutical ingredient production clusters in Zhejiang, Shandong, and Gujarat provinces feed global formulation capacity, with metformin hydrochloride, empagliflozin intermediates, and DPP-4 inhibitor precursors drawing from these hubs. Single-source vulnerability from China's MEE environmental compliance shutdowns represents the dominant structural risk. Distribution runs through hospital 340B pharmacies in the United States, specialty pharmacy tiers for SGLT2 inhibitors, and retail chains for maintenance metformin refills.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fixed-dose combination therapy disruption is accelerating market consolidation, with FDA accelerated approval pathways compressing development timelines and privileging incumbents with established bioequivalence capabilities.
For Market Incumbents: Compound defensive positioning through backward integration into metformin API supply and captive polymer matrix formulation capacity. Secure 340B program volume commitments with integrated delivery networks in Florida and Arizona before formulary consolidation completes. Prioritize cardiovascular outcome label expansion for SGLT2 inhibitor portfolios to sustain pricing power against biosimilar insulin substitution threats.
For New Entrants and Emerging Players: Anchor in homecare titration platform development, where pharmacy-direct dispensing channels bypass established physician intermediation. Target fixed-dose triple combination white space—metformin-SGLT2 inhibitor-DPP-4 antagonist formulations—where only one approved product currently captures adherence-improving demand. Deploy remote patient monitoring integration as the primary go-to-market angle for Medicare Advantage penetration.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among contract development organizations with established FDA bioequivalence track records and notified body relationships for EMA MDR compliance services. Five-to-ten year viability favors acquisition targets possessing vertical control from API supply through hospital formulary contracting, not formulation-only players exposed to Zhejiang sourcing concentration. Monitor IRA Medicare price negotiation expansion timelines as the critical inflection signal for SGLT2 inhibitor portfolio valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Fixed-Dose Triple Combination Development | Captures unmet adherence demand where single-pill regimens command formulary preference from hospital pharmacy committees. |
| EMA MDR Compliance Service Expansion | Addresses legacy product recertification deadlines forcing European manufacturers to resubmit technical documentation for dose-counting mechanisms. |
| 340B Program Volume Commitment | Locks in procurement relationships with integrated delivery networks consolidating purchasing across Florida and Arizona hospital systems. |
| Homecare Titration Platform Integration | Enables pharmacy-direct dispensing bypassing traditional physician intermediation through continuous glucose monitor connectivity. |
| Cardiovascular Outcome Label Expansion | Extends prescriber reach from endocrinology into cardiology practices through FDA-approved heart failure risk reduction claims. |
Research Methodology
Operator-level perspectives from drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists anchored the qualitative base for this analysis. Primary interview insights triangulated against FDA filings, EMA submission databases, ClinicalTrials.gov records, and CMS Medicare Part D claims data. Bottom-up patient population modeling and top-down pharmaceutical revenue reconciliation validated segmentation assumptions across mechanism of action, delivery mode, and therapy area dimensions.
Sensitivity analysis around IRA price negotiation implementation timelines and API supply disruption scenarios framed the forecast envelope. The analytical framework disaggregated volume and value across the projection horizon by product type, end user channel, delivery mode formulation, and regional regulatory cluster. CAGRs derived from treatment intensity escalation curves and oral-to-insulin transition window compression. Forecast inputs incorporated hospital formulary placement probability models and 340B program participation rates by integrated delivery network.
Material uncertainties—regulatory labeling revisions for renal impairment thresholds, environmental compliance enforcement intensity in Zhejiang province, and biosimilar insulin bioequivalence advancement—sit outside the modeled envelope. Forecasts reflect documented assumptions about Medicare reimbursement stability and fixed-dose combination approval velocity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Dermatitis Drugs Market
Pharmaceuticals
Metformin Hydrochloride Market
Pharmaceuticals
Global Acetazolamide Market
Pharmaceuticals
Global Erectile Dysfunction Drugs Market
Pharmaceuticals
Global Anesthesia Drugs Market
Pharmaceuticals
Pharmaceutical Grade Lactose Market
Pharmaceuticals
Global Viral Vaccines Market
Pharmaceuticals
Oxaliplatin Market
Pharmaceuticals
Pharmacy and Drug Store Franchises Market
Pharmaceuticals
Alkylating Agents Market
Pharmaceuticals
Global Pharmaceutical Warehousing Market
Pharmaceuticals
Etoricoxib Market
Pharmaceuticals
Levothyroxine Sodium Market
Pharmaceuticals
Drug-Loaded Oral Thin Films Market
Pharmaceuticals
Long-Acting Beta-Agonists Market
Pharmaceuticals
Pregabalin Market