
 Human Growth Hormone Treatment and Drugs Market | 2026-2036
Human Growth Hormone Treatment and Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Human Growth Hormone Treatment and Drugs Market Foresight
The EU Green Deal's pharmaceutical sustainability benchmarks are rebalancing procurement criteria across European hospital networks. Novo Nordisk A/S leverages its recombinant protein manufacturing scale to supply long-acting somatropin formulations. Pfizer Inc. anchors its position through established distribution partnerships with pediatric endocrinology centers. Eli Lilly and Company differentiates via sustained-release injection technologies that reduce dosing frequency.
Human growth hormone treatment and drugs encompass recombinant DNA-derived polypeptide hormones, synthetic analogues, and biosimilar formulations administered to stimulate linear growth, metabolic regulation, and cellular repair. Recombinant HGH dominates commercial value due to established purity profiles and batch consistency, while biosimilar HGH captures expanding share as regulatory reference pathways mature across developed markets. Subcutaneous injection remains the primary administration route, though oral delivery platforms represent the fastest-growing segment as peptide permeation technologies advance toward clinical validation.
The FDA, EMA, and WHO set divergent standards for immunogenicity testing and bioequivalence thresholds that determine market access timelines for new entrants. FDA's biosimilar guidance requires extensive analytical and clinical bridging studies, while EMA's scientific advice procedures offer earlier developer engagement. Stakeholders must monitor evolving interchangeability designations and their cascading effects on payer substitution policies.
Market Dynamics
The convergence of long-acting somatropin formulations with peptide permeation research is compressing dosing frequency expectations while expanding addressable patient populations beyond traditional growth hormone deficiency diagnoses.
Growth Catalysts
- FDA Biosimilar Pathways:The Biologics Price Competition and Innovation Act streamlines reference product bridging requirements, accelerating competitive entry and expanding treatment accessibility across pediatric endocrinology networks.
- Peptide Delivery Platforms:Oral permeation technologies employing tight-junction modulators are advancing through Phase II validation, promising to displace injection burden in adolescent patient populations.
- Metabolic Indication Expansion:Adult growth hormone deficiency protocols in Germany and Japan now encompass sarcopenia and body composition management, broadening reimbursement-eligible cohorts.
Market Restraints
- Recombinant Protein Manufacturing Concentration:Bulk active pharmaceutical ingredient production clusters in Danish and Swiss biologics corridors, creating single-source vulnerability for long-acting formulation supply.
- EMA Immunogenicity Thresholds:Stringent anti-drug antibody monitoring requirements extend biosimilar development timelines and elevate clinical trial costs relative to FDA benchmarks.
- Small Molecule IGF-1 Agonists:Non-peptide growth factor mimetics in early clinical development threaten to capture convenience-sensitive segments if oral bioavailability targets are achieved.
Strategic Opportunities
- Idiopathic Short Stature Protocols:United States pediatric endocrinology centers are expanding off-label recombinant HGH utilization, creating volume expansion outside formal deficiency diagnoses.
- EU Green Deal Procurement:Pharmaceutical sustainability benchmarks in European hospital networks favor suppliers with validated carbon footprint reduction across cold-chain distribution.
- Home Administration Training:Digital therapeutics platforms combining injection technique coaching with adherence monitoring are penetrating Japanese reimbursement channels.
Industry Challenges
- Peptide Formulation Expertise Scarcity:Sustained-release depot engineering requires rare combinations of polymer science and bioconjugation experience, constraining development pipeline velocity.
- Interchangeability Designation Complexity:Payer substitution policies hinge on FDA interchangeability rulings that remain unsettled for biosimilar HGH products, creating commercial forecasting uncertainty.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Human Growth Hormone Treatment and Drugs Market |
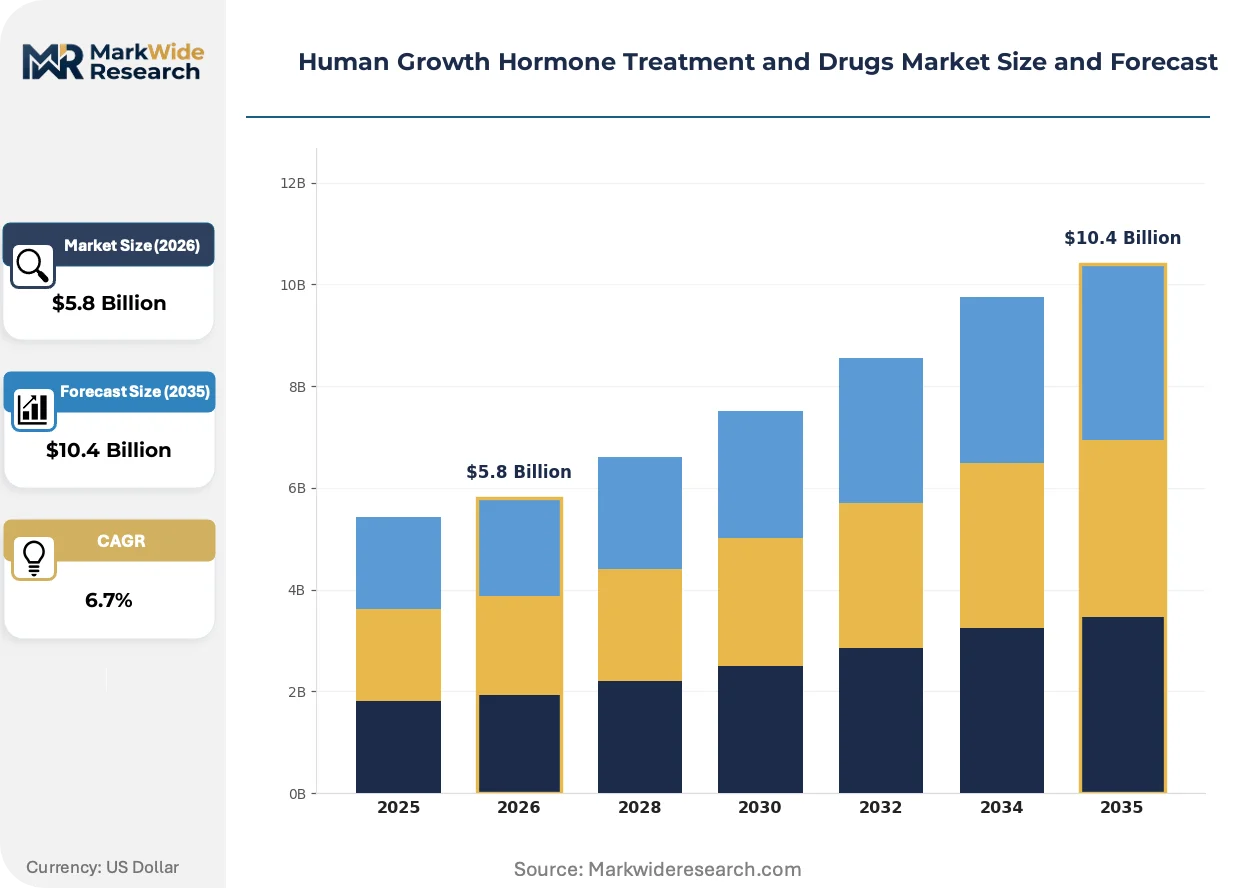
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $10.4 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Recombinant HGH, Synthetic HGH, Biosimilar HGH, Combination Therapy End User: Pediatric Patients, Adult Patients, Athletes, Clinics Administration Route: Subcutaneous Injection, Intramuscular Injection, Oral Delivery, IV Infusion Therapy Area: Growth Disorders, Aging, Short Stature, Hypopituitarism |
| Companies Covered | Novo Nordisk A/S, Pfizer Inc., Merck KGaA, Eli Lilly and Company, Ferring Pharmaceuticals, Ascendis Pharma A/S, Genentech, Sandoz International GmbH, Ipsen S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Human Growth Hormone Treatment and Drugs Market Shifts & Advancements
Long-acting depot technologies and peptide engineering advances are compressing competitive differentiation cycles while elevating patient adherence metrics as primary value demonstration criteria.
Transdermal microneedle arrays delivering somatropin through stratum corneum disruption are electrifying administration route innovation. Adolescent patient advocacy groups in Germany and Japan are driving formulary access negotiations based on needle anxiety reduction. This technology is compressing the perceived efficacy gap between daily injections and weekly depot formulations in physician preference studies.
EMA's evolving scientific advice procedures for biosimilar immunogenicity assessment are accelerating developer engagement timelines relative to FDA's post-submission feedback model. European reference product sponsors now face earlier disclosure of analytical comparability thresholds. Pediatric endocrinology clinics in France and Italy are adapting procurement specifications to accommodate accelerated biosimilar substitution schedules.
Hospital network consolidation across the United States is concentrating purchasing authority within integrated delivery systems. Traditional distributor relationships with standalone pediatric endocrinology practices are yielding to centralized pharmacy benefit management contracts. This concentration is most visible in the Northeast and Midwest, where three health systems now control majority recombinant HGH procurement volume.
Human Growth Hormone Treatment and Drugs Market Segmentation
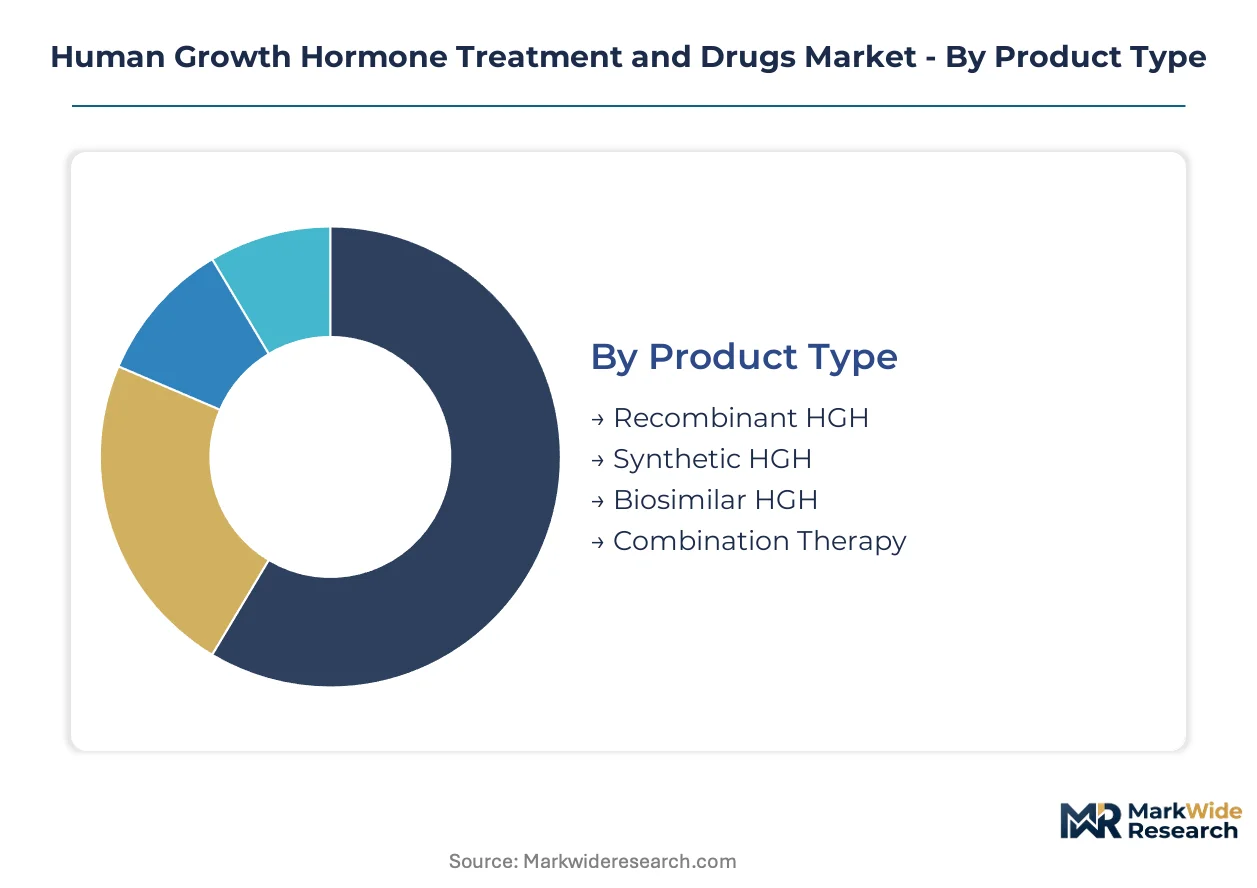
Segmentation in the HGH treatment market reveals how therapeutic applications, delivery technologies, and patient demographics create distinct commercial battlegrounds. Each dimension carries divergent margin profiles, regulatory burdens, and competitive intensity that shape portfolio prioritization.
Product Type:
Volume concentrates in mature recombinant formulations while premium capture shifts toward next-generation delivery platforms and biosimilar substitution economics.
- Recombinant HGH:DNA-derived somatropin produced in E. coli or mammalian cell culture delivers established purity profiles and batch-to-batch consistency. Demand clusters in United States pediatric endocrinology networks where FDA-validated manufacturing documentation supports reimbursement continuity.
- Biosimilar HGH:Reference product mimetics exploit maturing FDA and EMA approval pathways to compress price points while expanding access. German hospital procurement frameworks now mandate biosimilar evaluation in tender processes, accelerating volume migration from originator products.
- Synthetic HGH:Chemically synthesized analogues with modified amino acid sequences for extended half-life.
- Combination Therapy:Co-formulated growth hormone with IGF-1 or metabolic modulators for synergistic effect.
Today's leader: Recombinant HGH. Tomorrow's challenger: Biosimilar HGH.
End User:
Pediatric deficiency protocols anchor prescription volume while adult metabolic indications and performance optimization segments command price premiums.
- Pediatric Patients:Children with growth hormone deficiency, Turner syndrome, or chronic kidney disease constitute the reimbursement-validated core. Japanese universal health coverage maintains generous somatropin access for height velocity targets below population norms.
- Adult Patients:GHD protocols for body composition, bone density, and quality-of-life metrics expand addressable cohorts beyond linear growth. German endocrinology practices now incorporate sarcopenia assessments into adult HGH evaluation criteria.
- Athletes:Off-label and illicit use for performance enhancement with stringent anti-doping surveillance.
- Clinics:Specialized endocrinology centers and hospital outpatient departments administering supervised therapy.
Pediatric Patients currently dominate prescription volumes. Adult Patients are climbing the fastest as metabolic indication protocols mature.
Administration Route:
Injection burden tolerance varies sharply across age cohorts, driving divergent R&D investment toward needle-free alternatives.
- Subcutaneous Injection:Daily or near-daily abdominal or thigh administration using pen devices dominates current practice. Swiss and Danish biologics manufacturers optimize formulation viscosity for reduced injection pain in adolescent populations.
- Oral Delivery:Peptide permeation technologies employing tight-junction modulators promise to displace injection burden. Phase II trials in United States adolescent cohorts are validating bioavailability thresholds for somatropin absorption.
- Intramuscular Injection:Less frequent depot administration requiring clinical supervision.
- IV Infusion:Hospital-based delivery for acute metabolic crises or diagnostic stimulation testing.
Subcutaneous Injection retains volume leadership. Oral Delivery represents the steepest expansion trajectory pending clinical validation.
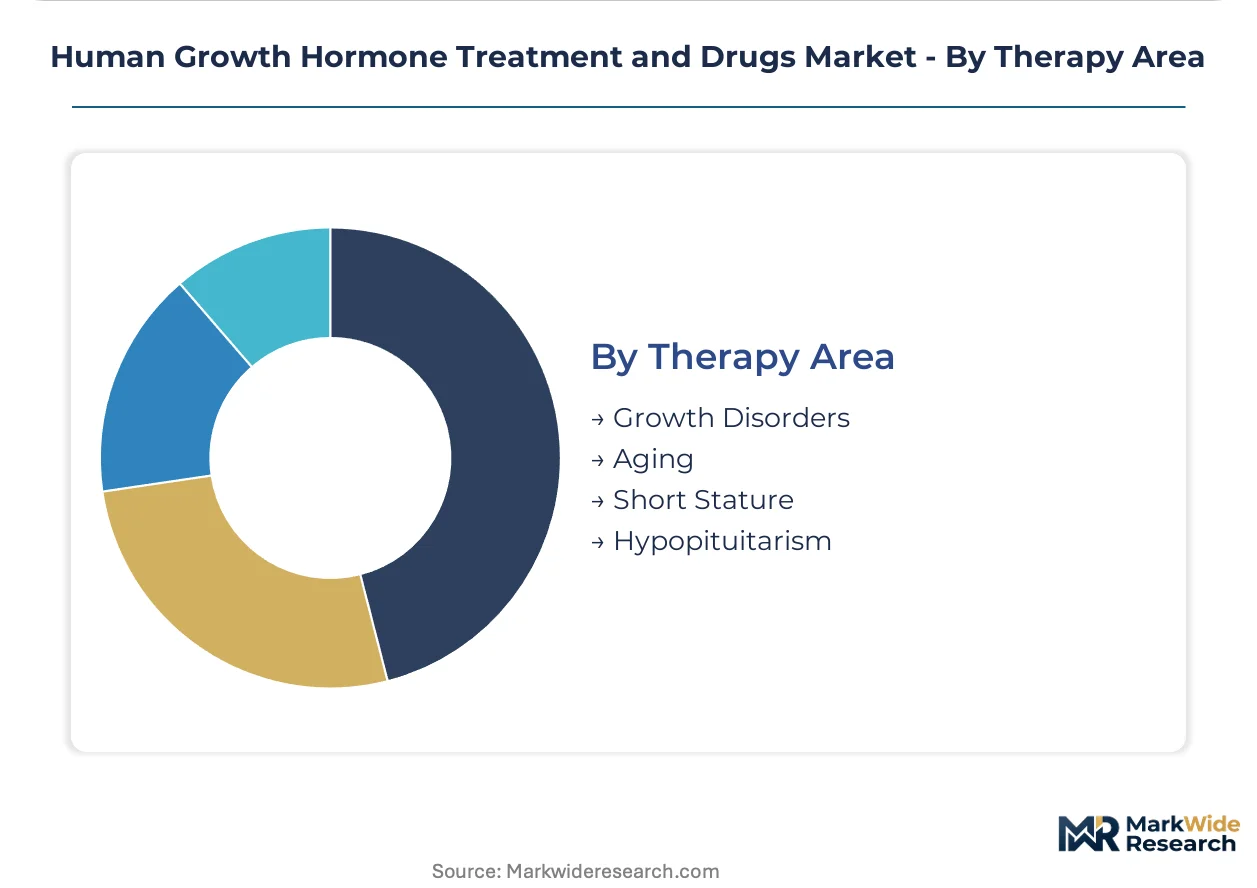
Therapy Area:
Formal deficiency diagnoses secure reimbursement while borderline indications and wellness applications operate in cash-pay or contested coverage zones.
- Growth Disorders:FDA and EMA-approved indications for GHD, Turner syndrome, Prader-Willi syndrome, and SGA constitute the reimbursable foundation. United States Medicaid programs require documented height velocity deficits and failed growth hormone stimulation tests.
- Short Stature:Idiopathic short stature protocols expand utilization beyond biochemical deficiency markers. Pediatric endocrinology centers in the Northeast and Midwest are adapting diagnostic thresholds to accommodate parental demand for intervention.
- Aging:Anti-aging and longevity applications with limited regulatory recognition.
- Hypopituitarism:Multi-hormone replacement contexts where HGH complements cortisol, thyroid, and sex steroid therapy.
Growth Disorders command established reimbursement. Short Stature is gaining share fastest through diagnostic boundary expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Recombinant human growth hormone manufacturing originated in Danish and Swiss biotechnology corridors during the 1980s, establishing production expertise that continues to concentrate bulk active pharmaceutical ingredient supply in Northern Europe. Today, demand validation and reimbursement frameworks determine market access across distinct national healthcare systems.
United States
Pediatric endocrinology networks in the Northeast and Midwest anchor prescription volume through integrated delivery system contracts. FDA's biosimilar approval pathways under the Biologics Price Competition and Innovation Act compress reference product bridging timelines. Boston and Philadelphia hospital systems now control majority procurement through centralized pharmacy benefit management agreements.
Germany
Adult growth hormone deficiency protocols now encompass sarcopenia and body composition management, expanding reimbursement-eligible cohorts beyond pediatric indications. EMA immunogenicity thresholds extend biosimilar development timelines while hospital procurement frameworks mandate biosimilar evaluation in tender processes. The Rhine-Ruhr metropolitan region concentrates endocrinology practice density and reference laboratory capacity.
Japan
Universal health coverage maintains generous somatropin access for height velocity targets below population norms, sustaining pediatric prescription volumes. PMDA guidance on long-acting formulation approval creates regulatory clarity for sustained-release depot submissions. Tokyo and Osaka medical centers pioneer digital therapeutics platforms combining injection technique coaching with adherence monitoring.
Switzerland
Swissmedic oversight of recombinant protein manufacturing maintains stringent batch consistency standards that shape export quality benchmarks. Basel and Zurich biologics corridors host concentrated formulation expertise for sustained-release depot engineering. The country's pharmaceutical sustainability frameworks anticipate EU Green Deal procurement criteria for carbon footprint reduction across cold-chain distribution.
United Kingdom
NHS England specialized commissioning frameworks restrict growth hormone prescribing to designated pediatric endocrinology centers, concentrating demand validation authority. MHRA post-Brexit regulatory autonomy enables accelerated scientific advice engagement for biosimilar developers. London teaching hospitals and Manchester referral networks coordinate multi-site clinical trial access for oral permeation technologies.
Human Growth Hormone Treatment and Drugs Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation complexity and delivery technology differentiation. The market structure consolidates around recombinant protein manufacturing scale at the top tier, with mid-tier biosimilar specialists capturing volume through price compression and emerging entrants advancing oral delivery platforms. Three archetypes dominate: originator biologics manufacturers with established distribution partnerships, biosimilar developers exploiting regulatory reference pathways, and peptide engineering specialists pursuing needle-free administration. Competitive moves concentrate on long-acting depot formulation advancement and digital therapeutics integration for home administration support.
Among Danish and American pharmaceutical conglomerates, Novo Nordisk A/S and Pfizer Inc. occupy positions reflecting recombinant protein manufacturing heritage and pediatric endocrinology network penetration. Eli Lilly and Company exemplifies the sustained-release technology tier through sustained-release injection engineering. These three entities anchor distinct competitive vectors: manufacturing scale, distribution infrastructure, and delivery innovation.
| Leading Market Players |
|---|
| Novo Nordisk A/S |
| Pfizer Inc. |
| Merck KGaA |
| Eli Lilly and Company |
| Ferring Pharmaceuticals |
| Ascendis Pharma A/S |
| Genentech |
| Sandoz International GmbH |
| Ipsen S.A. |
| Others |
Supply & Pricing Matrix
Integrated delivery systems in the United States Northeast and Midwest anchor procurement volume through centralized pharmacy benefit management contracts, compressing price negotiation leverage for originator manufacturers while amplifying biosimilar substitution economics. This buyer concentration forces three-tier pricing stratification across premium long-acting formulations, standard daily recombinant products, and economy-positioned biosimilars.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by formulation complexity and dosing convenience. Premium capture rests on sustained-release depot technologies that reduce injection frequency, while standard recombinant products compete on manufacturing documentation and reimbursement continuity. Price erosion runs through the economy tier as German hospital procurement frameworks mandate biosimilar evaluation, intensifying cost compression. Pediatric endocrinology networks exhibit lowest price sensitivity due to parental demand for height optimization, whereas adult metabolic indication protocols face stricter payer scrutiny.
Supply Chain Analysis
Reverse logistics for temperature-sensitive biologics encompasses cold-chain remediation, batch recall coordination, and patient returns of unused pen devices. Bulk active pharmaceutical ingredient production clusters in Denmark and Switzerland, drawing from specialized recombinant protein manufacturing corridors established during the 1980s biotechnology wave. Formulation inputs hinge on E. coli and mammalian cell culture media, high-purity chromatography resins, and medical-grade polymer components for pen injectors. Single-source vulnerability concentrates in Danish biologics corridors for long-acting formulation supply. Distribution runs through specialized pharmaceutical wholesalers with validated cold-chain capabilities, bypassing generalist distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on biosimilar manufacturing scale economies compressing cost structures while long-acting formulation premiums sustain pricing power in convenience-sensitive segments.
For Market Incumbents: To counter biosimilar price erosion in standard recombinant segments, anchor position through exclusive distribution partnerships with consolidated United States pediatric endocrinology networks and accelerate sustained-release depot engineering to differentiate beyond daily injection protocols. Backward integration into recombinant protein manufacturing capacity in Swiss and Danish corridors secures supply continuity for premium-tier formulations. For New Entrants and Emerging Players: Launch via direct-to-patient digital therapeutics platforms combining home administration training with adherence monitoring, penetrating Japanese reimbursement channels where such services receive favorable coverage. Target oral peptide permeation technologies in adolescent populations as the most penetrable white space, exploiting needle anxiety reduction as the primary value proposition against established injection protocols. For Investors and Strategic Acquirers: Mid-cap biologics manufacturers with validated biosimilar immunogenicity testing capabilities are the most active acquirer in this space, consolidating reference product analytical comparability expertise. Acquisition targets should demonstrate Phase II oral delivery platform validation or established pediatric endocrinology distribution relationships. Watch FDA interchangeability designations for biosimilar HGH products as the signal for payer substitution policy acceleration and volume migration timing.| Strategic Initiative | Industry Significance |
|---|---|
| Long-Acting Formulation Development | Sustained-release depot engineering reduces dosing burden and commands premium positioning in adolescent segments. |
| Biosimilar Interchangeability Pursuit | FDA interchangeability designation unlocks automatic substitution at pharmacy level, accelerating volume capture from originators. |
| Digital Therapeutics Integration | Home administration coaching platforms penetrate Japanese reimbursement channels and improve adherence metrics for payers. |
| Peptide Permeation Investment | Oral delivery technologies employing tight-junction modulators promise to displace injection burden in convenience-sensitive populations. |
| EU Green Deal Compliance | Carbon footprint reduction across cold-chain distribution aligns procurement criteria for European hospital network tenders. |
Research Methodology
Bottom-up pediatric and adult patient population modeling reconciled against top-down recombinant protein manufacturing capacity tracking forms the analytical core. Primary interviews with drug development executives, regulatory affairs leads at EMA and FDA, formulary directors in United States integrated delivery systems, and hospital procurement managers in German and Japanese networks combined with secondary validation from FDA filings, EMA scientific advice procedures, ClinicalTrials.gov entries, and hospital procurement databases. This triangulation ensures demand-side prescription volume estimates align with supply-side production constraints.
Historical trendline analysis of recombinant HGH prescription patterns, pricing trajectories across originator and biosimilar segments, and reimbursement policy evolution informed the projection framework. Segmentation dimensions encompassed product type, administration route, therapy area, and patient demographics across the analysis window. CAGRs were derived from weighted scenario modeling incorporating regulatory approval timelines, biosimilar substitution elasticity, and oral delivery platform clinical validation progress. Forecast inputs included PMDA guidance on long-acting formulations and evolving FDA interchangeability standards.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated biosimilar approval pathways or breakthrough oral bioavailability achievements. Practitioners should monitor FDA interchangeability rulings, EMA immunogenicity threshold adjustments, and Phase II oral permeation readouts for early signals of competitive inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Europe Alpha-Glucosidase Inhibitors Market
Pharmaceuticals
Global Atosiban Market
Pharmaceuticals
US Sex Reassignment Hormone Therapy Market
Pharmaceuticals
Antispasmodics Drugs Market
Pharmaceuticals
Plasma-Derived Protein Therapies Market
Pharmaceuticals
Fibromyalgia Antidepressant Market
Pharmaceuticals
Chemotherapy-Induced Nausea and Vomiting (CINV) Treatment Market
Pharmaceuticals
US Transdermal Drug Delivery System Market
Pharmaceuticals
Intravenous Pegloticase Market
Pharmaceuticals
Cerumenolytic Agents Market
Pharmaceuticals
Enbrel Market
Pharmaceuticals
PAP and Paracetamol Market
Pharmaceuticals
Long-Acting Monoclonal Antibodies Market
Pharmaceuticals
G Protein Coupled Receptors (Gpcrs) Market
Pharmaceuticals
Depression Drugs Market
Pharmaceuticals
Nephrology Drugs Market