
 Pharmaceutical Water Market | 2026-2036
Pharmaceutical Water Market Size, Share, and Industry Trends Forecast 2026-2036
Pharmaceutical Water Market Outlook
Membrane-based purification is repositioning traditional distillation economics in pharmaceutical water production. Thermo Fisher Scientific leverages its analytical instrumentation portfolio to anchor integrated water quality monitoring systems. Merck KGaA sustains dominance in high-purity reagent-grade water through backward integration into resin manufacturing. Danaher Corporation competes across filtration and chromatography platforms that precondition feedwater for final purification stages.
Pharmaceutical water comprises highly purified water meeting strict chemical, microbial, and endotoxin specifications for drug manufacturing, parenteral preparation, and analytical testing; systems typically achieve resistivity of 18.2 MΩ·cm and endotoxin levels below 0.25 EU/mL through multi-stage treatment trains. Water for Injection commands premium positioning due to pyrogen-free requirements for biologics and vaccine production, while Reverse Osmosis Water expands fastest as pretreatment technology improves membrane longevity. Purified Water remains the volume anchor across oral solid dosage and topical formulation facilities where endotoxin limits are less stringent.
The FDA enforces current Good Manufacturing Practice water system validation under 21 CFR 211, while the EMA's GMP Annex 1 revision mandates continuous viable monitoring for Grade A/B environments. India's CDSCO aligns with WHO TRS 970 water quality specifications for export-oriented formulation facilities. Stakeholders must weigh capital deployment between centralized bulk generation and point-of-use polishing as therapy modalities fragment manufacturing footprints.
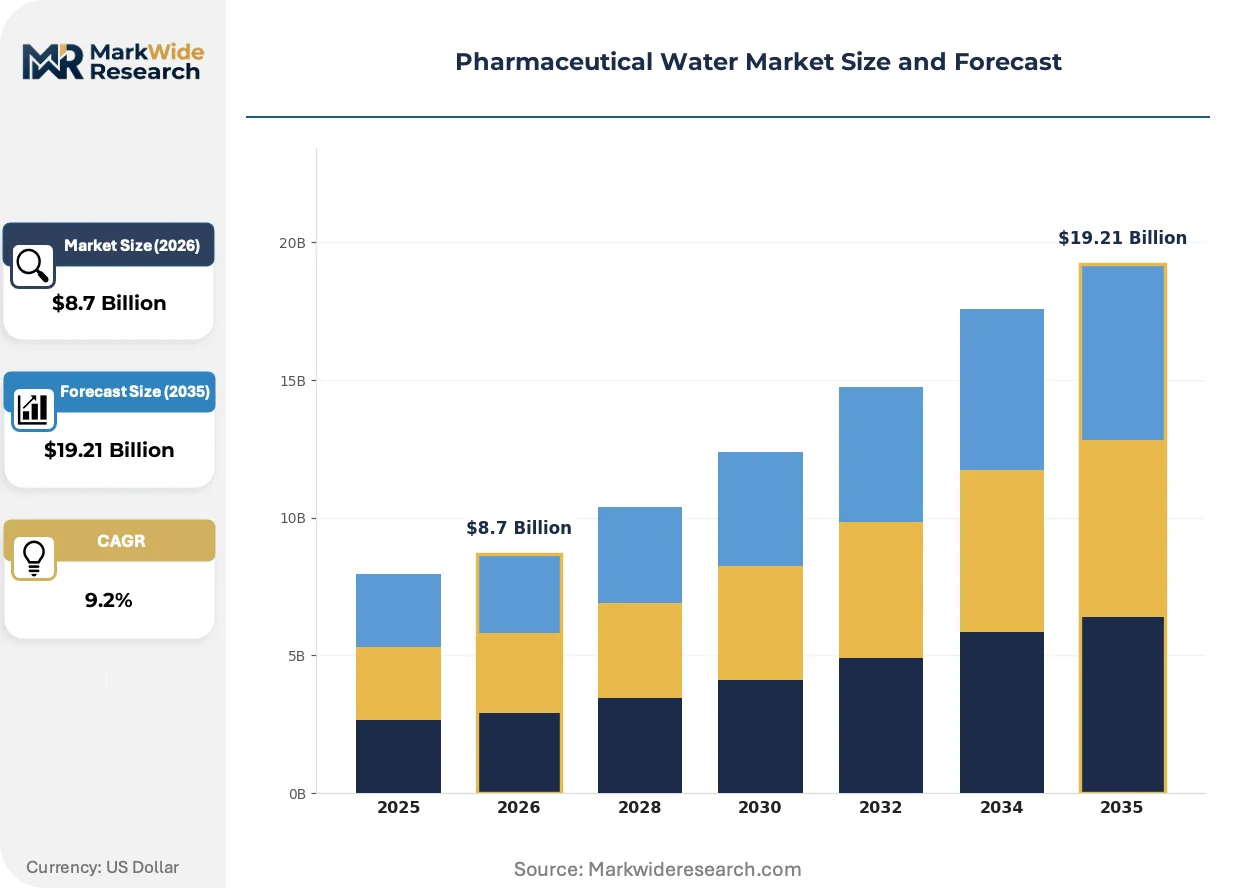
Market Dynamics
Membrane-based purification systems are compressing capital recovery timelines for pharmaceutical water infrastructure while FDA's tightened endotoxin thresholds force simultaneous upgrades across multi-site manufacturing networks.
Growth Catalysts
- Cell therapy manufacturing expansion:CAR-T production facilities in Boston and San Diego require Water for Injection systems capable of supporting closed-process bioreactors under 21 CFR 211 validation protocols.
- EMA GMP Annex 1 revision:Continuous viable monitoring mandates for Grade A/B cleanroom environments are accelerating replacement cycles for legacy bulk water generation systems across European formulation sites.
- Reverse osmosis membrane advances:Improved polyamide chemistry and fouling-resistant coatings are extending membrane lifespans in pretreatment trains, reducing total cost of ownership for high-volume oral solid dosage manufacturers.
Market Restraints
- High-purity resin supply concentration:Ion exchange resin manufacturing concentrates among German and Japanese chemical suppliers, creating vulnerability for water system OEMs dependent on just-in-time regenerant delivery.
- Stainless steel input cost volatility:Electropolished 316L vessel fabrication accounts for substantial system capex, with nickel price swings directly compressing margin structures for skid-mounted purification equipment.
- Distillation energy intensity:Multi-effect stills for WFI production face carbon accounting pressure under EU Green Deal industrial emissions frameworks, particularly at legacy European facilities with constrained utility infrastructure.
Strategic Opportunities
- India CDSCO export alignment:WHO TRS 970 water quality certification requirements for export-oriented formulation facilities create retrofit demand across Ahmedabad and Hyderabad manufacturing clusters.
- Point-of-use polishing decentralization:Modular loop systems with integrated UV and ultrafiltration enable flexible manufacturing footprints for personalized medicine batch sizes, displacing centralized bulk generation in multi-product facilities.
- Continuous manufacturing integration:Real-time release testing requirements for oral solid dosage lines create specification for online TOC and conductivity analyzers with automated diversion protocols.
Industry Challenges
- Validation engineer scarcity:IQ/OQ/PQ documentation for water system commissioning requires specialized expertise in FDA 21 CFR Part 11 electronic records compliance, with talent pools concentrated among contract service providers.
- Legacy system interoperability:Retrofitting PAT-enabled sensors onto 1990s-era distribution loops demands custom mechanical adapters and software bridges, extending project timelines and qualification risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharmaceutical Water Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.21 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Water Type: Purified Water, Water for Injection, Distilled Water, Reverse Osmosis Water End User: Pharmaceutical Manufacturers, Biotechnology Companies, Research Laboratories, Contract Manufacturing Organizations Treatment Technology: Filtration, Ion Exchange, UV Treatment, Ozonation Distribution Channel: Direct Sales, Distributors, Online Sales, Others |
| Companies Covered | Thermo Fisher Scientific, Merck KGaA, Danaher Corporation, Veolia Water Solutions and Technologies, Evoqua Water Technologies, B. Braun Melsungen AG, Fresenius Kabi AG, Baxter International, SUEZ Water Technologies & Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharmaceutical Water Market Strategic Shifts
Pharmaceutical water infrastructure is pivoting from static compliance to dynamic quality assurance, with sensor networks and predictive analytics compressing deviation response times while enabling continuous process verification.
Electrodeionization technology is converging with advanced oxidation processes to eliminate final polishing resin beds in high-purity water systems. Biologics manufacturers in Singapore and Switzerland are piloting these hybrid trains for monoclonal antibody production. This convergence is compressing footprint requirements while reducing chemical regenerant handling and disposal costs.
EMA's 2022 GMP Annex 1 revision mandates continuous viable particle monitoring for Grade A/B environments, forcing water system designers to integrate rapid microbial detection methods into distribution loops. Parenteral drug facilities are responding by specifying laser-induced fluorescence sensors with automated alert thresholds. This regulatory pressure is accelerating obsolescence of grab-sample testing protocols.
Contract development and manufacturing organizations are consolidating water system procurement under master service agreements with integrated validation packages. Large molecule drug sponsors are shifting from capital purchase to performance-based service contracts covering generation, distribution, and ongoing compliance monitoring. This restructuring is most advanced among Boston and San Diego biotech clusters where facility flexibility outweighs asset ownership.
Pharmaceutical Water Market Segmentation
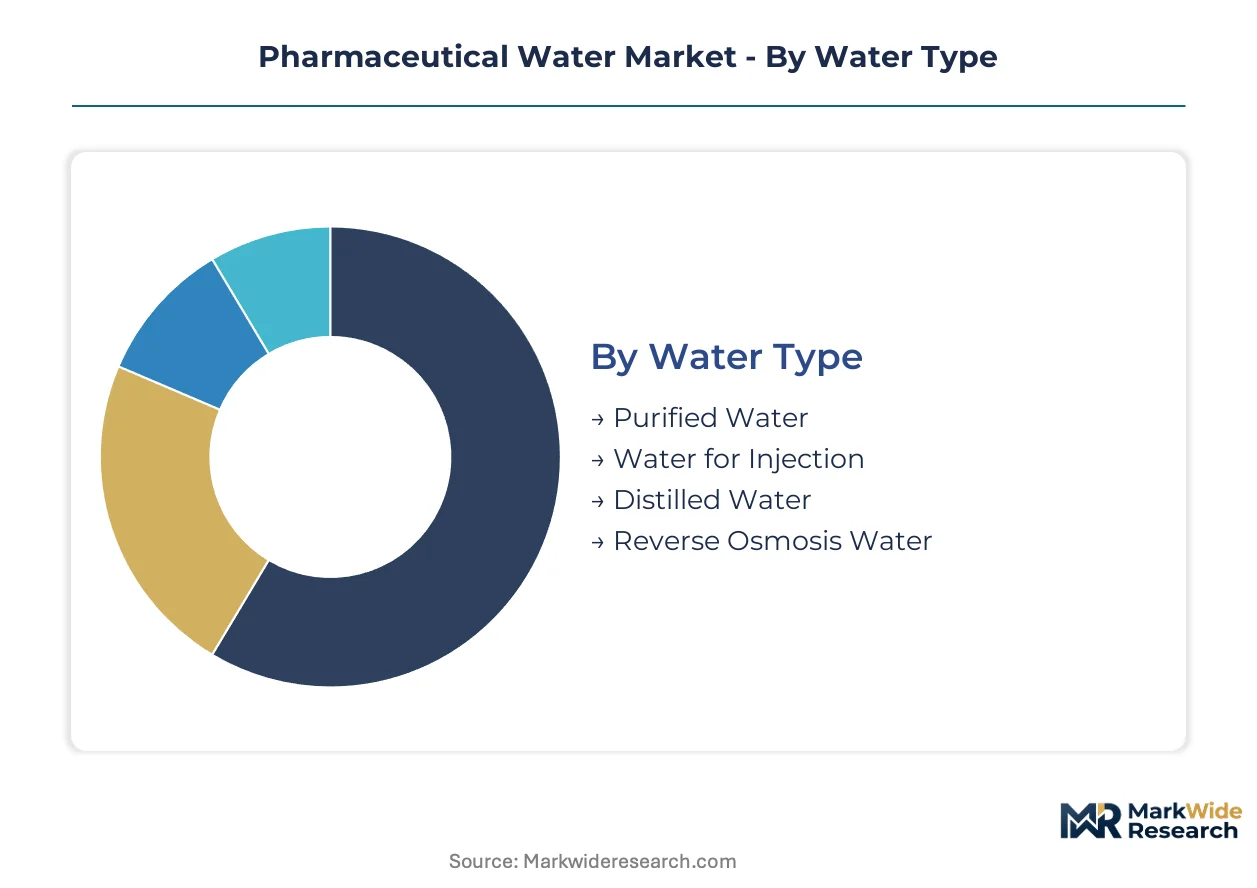
Pharmaceutical water specifications cascade through manufacturing hierarchies, with each tier demanding distinct purity thresholds, validation protocols, and distribution architectures. Segmentation clarity enables capital allocation across multi-product facilities where a single water loop must simultaneously serve oral solid dosage, parenteral biologics, and analytical testing operations.
Water Type:
Technology and specification axes define competitive positioning across water grade portfolios.
- Water for Injection:Pyrogen-free water meeting endotoxin limits below 0.25 EU/mL through distillation or reverse osmosis with ultrafiltration. Demand concentrates in Boston and San Diego cell therapy clusters where CAR-T manufacturing under FDA 21 CFR 211 validation requires closed-process bioreactor compatibility.
- Purified Water:High-purity water achieving 18.2 MΩ·cm resistivity through multi-stage membrane and ion exchange trains. Oral solid dosage facilities in Ahmedabad and Hyderabad leverage this grade for tablet granulation and coating operations where endotoxin specifications remain less stringent than parenteral applications.
- Distilled Water:Thermal purification via multi-effect stills producing condensate for legacy parenteral facilities. European sites face carbon accounting pressure under EU Green Deal emissions frameworks.
- Reverse Osmosis Water:Membrane-based permeate serving as pretreatment feed or final polishing input. Singapore biologics manufacturers pilot hybrid trains combining RO with electrodeionization.
Mature deployment sits with Purified Water across high-volume oral solid dosage networks. Newer deployment is concentrated in Reverse Osmosis Water as membrane chemistry advances compress pretreatment footprints.
End User:
Customer scale and regulatory exposure shape procurement patterns and service contract structures.
- Pharmaceutical Manufacturers:Integrated bulk generation systems serving multi-product facilities with centralized distribution loops and continuous monitoring under FDA cGMP protocols. Large molecule sites in Switzerland specify redundant generation trains with automated failover.
- Biotechnology Companies:Modular point-of-use polishing for personalized medicine batch sizes. Boston and San Diego clusters favor performance-based service contracts over capital ownership.
- Research Laboratories:Bench-scale purification with analytical-grade specifications. Academic medical centers require flexible loop configurations supporting diverse therapeutic modalities.
- Contract Manufacturing Organizations:Master service agreements consolidating water system procurement with integrated IQ/OQ/PQ validation packages. CDMOs serving EU markets align with EMA GMP Annex 1 continuous monitoring mandates.
Volume concentration remains with Pharmaceutical Manufacturers. Margin expansion is climbing the fastest among Contract Manufacturing Organizations consolidating multi-site compliance under single vendor relationships.
Treatment Technology:
Capital intensity and operating chemistry differentiate technology selection across facility life cycles.
- Filtration:Membrane-based particle and microbial removal spanning microfiltration through ultrafiltration. Singapore monoclonal antibody facilities deploy fouling-resistant polyamide coatings extending membrane longevity.
- Ion Exchange:Resin-based cation and anion removal for resistivity polishing. German and Japanese chemical suppliers concentrate regenerant manufacturing, creating supply vulnerability for just-in-time delivery models.
- UV Treatment:254 nm germicidal irradiation for microbial control in distribution loops. EMA Grade A/B environments mandate continuous viable monitoring accelerating laser-induced fluorescence sensor integration.
- Ozonation:Advanced oxidation for biofilm prevention and endotoxin reduction. Swiss biologics sites pilot ozone-electrodeionization hybrids eliminating final polishing resin beds.
Established infrastructure favors Ion Exchange for high-volume resistivity polishing. Technology transition is gaining share fastest in UV Treatment as real-time microbial detection displaces grab-sample protocols.
Distribution Channel:
Transaction scale and technical support requirements segment channel economics.
- Direct Sales:OEM-engineered skid systems with integrated commissioning and validation services. Large molecule manufacturers in San Diego specify direct relationships for complex multi-train installations.
- Distributors:Regional inventory and service networks for consumables and replacement components. Hyderabad formulation facilities leverage distributor proximity for resin regenerant logistics.
- Online Sales:E-procurement for standardized consumables, sensors, and documentation templates. Research laboratories favor digital channels for analytical-grade water verification.
- Others:Rental and lease structures for temporary manufacturing capacity. CDMOs expanding into personalized medicine utilize short-term equipment deployment.
Revenue concentration persists with Direct Sales for capital equipment. Channel expansion is expanding most quickly in Online Sales as procurement digitization penetrates consumables and compliance documentation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cell therapy manufacturing clusters in Boston and San Diego concentrate pharmaceutical water demand, while biologics production in Switzerland and Singapore drives ultrapure infrastructure investment. Regulatory divergence between FDA, EMA, and CDSCO compliance frameworks shapes capital deployment across multi-site networks.
United States
CAR-T manufacturing facilities in Boston and San Diego require Water for Injection systems validated under FDA 21 CFR 211 protocols for closed-process bioreactors. The FDA's tightened endotoxin thresholds force simultaneous upgrades across multi-site manufacturing networks. Thermo Fisher Scientific leverages its analytical instrumentation portfolio to anchor integrated water quality monitoring systems serving these clusters.
Germany
High-purity resin manufacturing concentrates among German chemical suppliers, creating supply vulnerability for water system OEMs dependent on just-in-time regenerant delivery. The EU Green Deal industrial emissions frameworks pressure multi-effect stills for WFI production at legacy European facilities. Merck KGaA sustains dominance in high-purity reagent-grade water through backward integration into resin manufacturing.
Switzerland
Large molecule manufacturers specify redundant generation trains with automated failover for monoclonal antibody production. Swissmedic alignment with EMA GMP Annex 1 continuous monitoring mandates accelerates laser-induced fluorescence sensor integration. Biologics manufacturers pilot electrodeionization-ozone hybrid trains eliminating final polishing resin beds.
India
Export-oriented formulation facilities in Ahmedabad and Hyderabad require WHO TRS 970 water quality certification for CDSCO compliance. The country's national pharmaceutical regulator aligns with international specifications for global market access. Danaher Corporation competes across filtration and chromatography platforms that precondition feedwater for final purification stages in these manufacturing clusters.
Singapore
Biologics manufacturers deploy fouling-resistant polyamide coatings extending membrane longevity in pretreatment trains. The national environmental agency enforces stringent discharge standards that favor closed-loop water recycling architectures. Hybrid trains combining reverse osmosis with electrodeionization compress footprint requirements while reducing chemical regenerant handling costs.
Pharmaceutical Water Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated analytical-instrumentation providers commanding premium positioning in quality monitoring subsystems while pure-play water treatment OEMs compete on capital equipment efficiency. The vendor base organizes around three strategic archetypes: diversified life science conglomerates with water as a vertical extension, specialized purification technology developers, and service-integrated contract operators. Competitive moves concentrate on backward integration into consumables manufacturing and performance-based service contract structures displacing traditional capital sales.
Among diversified life science conglomerates, Thermo Fisher Scientific, Merck KGaA, and Danaher Corporation exemplify contrasting strategic positions. Thermo Fisher Scientific occupies a position anchored in analytical instrumentation that extends into integrated monitoring systems. Merck KGaA represents the backward-integrated archetype with captive resin manufacturing capabilities. Danaher Corporation sits within the filtration and chromatography platform tier that preconditions feedwater for downstream purification stages.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Merck KGaA |
| Danaher Corporation |
| Veolia Water Solutions and Technologies |
| Evoqua Water Technologies |
| B. Braun Melsungen AG |
| Fresenius Kabi AG |
| Baxter International |
| SUEZ Water Technologies & Solutions |
| Others |
Value Chain & Pricing Dynamics
Biopharmaceutical manufacturers consolidating procurement under master service agreements command pricing leverage that compresses margins for skid-mounted equipment suppliers while favoring performance-based service contracts over capital sales.
Pricing Analysis
High-volume oral solid dosage manufacturers anchor the economy tier through standardized purified water systems with minimal customization, while cell therapy facilities in Boston and San Diego absorb premium pricing for Water for Injection systems with integrated validation packages. Price differentiation hinges on FDA 21 CFR 211 compliance tier and endotoxin specification stringency. Cost compression in the mid-market intensifies as membrane-based reverse osmosis systems displace traditional distillation economics. Contract manufacturing organizations exhibit highest price sensitivity due to sponsor pass-through constraints, whereas large molecule biologics manufacturers prioritize reliability over unit cost.
Supply Chain Analysis
India's PLI scheme for pharmaceutical manufacturing and local-content preferences in government tenders are reshaping sourcing patterns for water system components across export-oriented formulation facilities. Ion exchange resin manufacturing concentrates in Germany and Japan, with electropolished 316L stainless steel vessel fabrication anchored in Chinese and European metalworking centers. Single-source vulnerability in high-purity regenerant chemicals creates exposure for just-in-time delivery models. Distribution runs through OEM direct sales for capital equipment and regional distributor networks for consumables and replacement membranes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
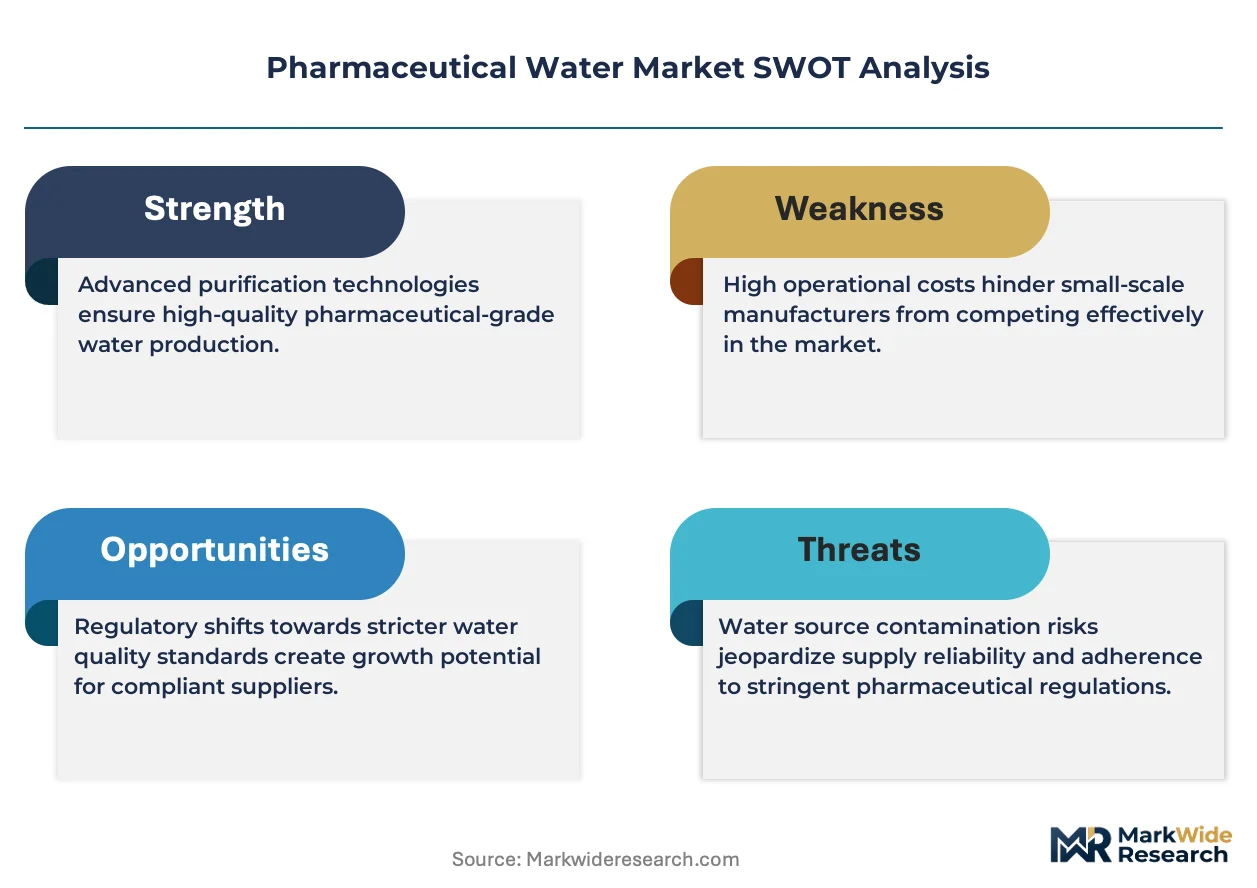
The pharmaceutical water market functions as a cost-of-compliance arena where FDA's tightened endotoxin thresholds and EMA GMP Annex 1 continuous monitoring mandates erect regulatory moats favoring incumbents with established validation documentation and quality management systems.
For Market Incumbents: Deploy backward integration into ion exchange resin manufacturing to neutralize supply concentration risk from German and Japanese chemical suppliers. Consolidate validation engineering talent pools through acquisition of specialized IQ/OQ/PQ service providers as contract manufacturers shift procurement toward integrated compliance packages. Counter membrane-based purification substitutes by embedding analytical instrumentation into monitoring subsystems that lock in recurring revenue streams. For New Entrants and Emerging Players: Contract manufacturing organizations represent the most penetrable customer segment as they consolidate multi-site water system procurement under single vendor relationships. Target India's CDSCO-aligned export facilities in Ahmedabad and Hyderabad where WHO TRS 970 certification requirements create retrofit demand without incumbent entrenchment. Pursue point-of-use polishing modular systems for personalized medicine batch sizes as biotechnology clusters shift from asset ownership to performance-based service contracts. For Investors and Strategic Acquirers: The window for entry favors specialized validation service providers and membrane technology developers with fouling-resistant coating intellectual property over commodity equipment fabricators. Mid-cap water treatment OEMs with captive resin regeneration capabilities offer defensive positioning against supply chain concentration. Monitor FDA guidance publication timelines on water-for-injection quality specifications as the inflection signal for replacement cycle acceleration across multi-site manufacturing networks.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Manufacturing | Merck KGaA's captive supply of ion exchange regenerants insulates margin structures from German and Japanese chemical supplier concentration. |
| Performance-Based Service Contract Expansion | Thermo Fisher Scientific's integrated monitoring systems lock in recurring revenue from Boston and San Diego cell therapy clusters shifting from capital purchase. |
| Fouling-Resistant Membrane Coating Development | Singapore biologics manufacturers piloting polyamide chemistry advances extend pretreatment train longevity and reduce total cost of ownership. |
| Point-of-Use Polishing Modular Deployment | Decentralized loop systems with integrated UV and ultrafiltration enable flexible manufacturing footprints for personalized medicine batch sizes. |
| Continuous Viable Monitoring Sensor Integration | Laser-induced fluorescence sensors with automated alert thresholds satisfy EMA GMP Annex 1 mandates while accelerating obsolescence of grab-sample protocols. |
Study Parameters
Independent corroboration across primary interviews with water system validation engineers, pharmaceutical manufacturing facility directors, and contract manufacturing organization procurement leads, combined with secondary validation through FDA 21 CFR guidance documents, EMA GMP Annex 1 revision texts, and WHO TRS 970 technical specifications, underwrites the qualitative findings. Bottom-up triangulation across equipment shipment data and top-down reconciliation against biopharmaceutical capital expenditure disclosures ensure dimensional consistency across the analysis window.
Comparable historical reference periods spanning pre- and post-EMA 2022 GMP Annex 1 implementation anchor the forecast window, with growth trajectories modeled across water type, treatment technology, end user vertical, and regional regulatory cluster dimensions. CAGRs derive from segmented adoption curves for membrane-based versus thermal purification systems, incorporating capacity expansion announcements from monoclonal antibody and cell therapy manufacturing facilities.
Several conditions sit outside the modeled scope, including abrupt nickel price volatility affecting stainless steel vessel fabrication costs, unilateral regulatory harmonization failures between FDA and EMA frameworks, and breakthrough electrodeionization-ozone hybrid technology obsolescence of established resin polishing trains. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Empty Capsules Market
Pharmaceuticals
US Sex Reassignment Hormone Therapy Market
Pharmaceuticals
Middle-East and Africa Diabetes Drugs Market
Pharmaceuticals
Global Esketamine Market
Pharmaceuticals
Sarcoidosis Drugs Market
Pharmaceuticals
Tuberculosis Therapeutics Market
Pharmaceuticals
Testosterone Nasal Gels Market
Pharmaceuticals
API Contract Manufacturing Market
Pharmaceuticals
North America Adenomyosis Drugs Market
Pharmaceuticals
Oral Solid Dosage Pharmaceutical Formulation Market
Pharmaceuticals
Omega 3 Prescription Drugs Market
Pharmaceuticals
Netupitant-Palonosetron FDC Market
Pharmaceuticals
Global Narcolepsy Drugs Market
Pharmaceuticals
Herbal Drugs Market
Pharmaceuticals
MRSA Antibiotic Preparations Market
Pharmaceuticals
Europe Contraceptives Market