
 Long-Acting Beta-Agonists Market | 2026-2036
Long-Acting Beta-Agonists Market Size, Share, and Industry Trends Forecast 2026-2036
Long-Acting Beta-Agonists Market Foresight
Active pharmaceutical ingredient production for bronchodilator compounds is consolidating in Western European contract manufacturing networks. GlaxoSmithKline leverages its respiratory heritage to sustain dominance in fixed-dose combination portfolios. AstraZeneca anchors its position through biologics-adjacent LABA development programs in Sweden and the United Kingdom.
Long-acting beta-agonists comprise a class of bronchodilator compounds with extended receptor occupancy exceeding twelve hours, formulated as salmeterol, formoterol, indacaterol, or vilanterol salts for sustained smooth muscle relaxation in obstructive airway disease. These agents serve primarily as maintenance therapy to prevent exacerbations in chronic respiratory conditions requiring scheduled rather than rescue administration. The therapy area dimension shows Chronic Obstructive Pulmonary Disease commanding the largest patient volume base, while Asthma applications occupy higher-margin positioning due to biologic-adjacent prescribing patterns. Dry Powder Inhalers compete aggressively with Metered-Dose Inhalers on carbon footprint metrics, with the former gaining formulary preference in European hospital tenders.
FDA oversight of new molecular entity approvals and EMA's MDR framework for device-drug combination products jointly elevate clinical evidence requirements for market entry. The EPA's phase-down of hydrofluoroalkane propellants under the AIM Act is forcing reformulation investments across pressurized inhaler portfolios. Stakeholders must monitor evolving propellant transition timelines and device revalidation costs to preserve competitive positioning.
Market Dynamics
Device interoperability mandates from ISO are forcing simultaneous reformulation of propellant chemistry and inhaler electronics, compressing development timelines for combination bronchodilator products.
Growth Catalysts
- EPA AIM Act phase-down:Hydrofluoroalkane propellant restrictions are accelerating investment in dry powder inhaler platforms and next-generation propellant systems.
- Medicare home nebulization reimbursement:Expanded coverage pathways in the United States are extending maintenance bronchodilator access to rural and mobility-limited patient populations.
- EMA MDR framework:Device-drug combination product standards are elevating clinical evidence requirements that favor established manufacturers with integrated development capabilities.
Market Restraints
- API supply concentration:Western European contract manufacturing networks dominate active pharmaceutical ingredient production for salmeterol and formoterol salts, creating geographic single-source vulnerability.
- Reformulation capex burden:Propellant transition timelines compress returns on legacy pressurized metered-dose inhaler portfolios before patent expiry.
- Biologic substitution pressure:Anti-IL5 and anti-IgE monoclonal antibodies are capturing severe asthma maintenance share from LABA/ICS combination therapies in tertiary care settings.
Strategic Opportunities
- Carbon footprint differentiation:Dry powder inhaler platforms with reduced lifecycle emissions are gaining formulary preference in European hospital purchasing consortia tender evaluations.
- COPD exacerbation prevention protocols:Hospital-based disease management programs in Germany are expanding scheduled LABA/ICS maintenance under EMA-approved combination therapy protocols.
- Smart inhaler convergence:Bluetooth-enabled adherence monitoring is integrating with electronic health record systems to demonstrate outcomes-based value to United States payers.
Industry Challenges
- Device revalidation complexity:ISO inhaler interoperability standards require simultaneous hardware and software recertification, extending regulatory submission timelines.
- Inhaler technique training gaps:Pulmonary rehabilitation programs face staffing constraints in delivering standardized patient education for multi-step device activation sequences.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Long-Acting Beta-Agonists Market |
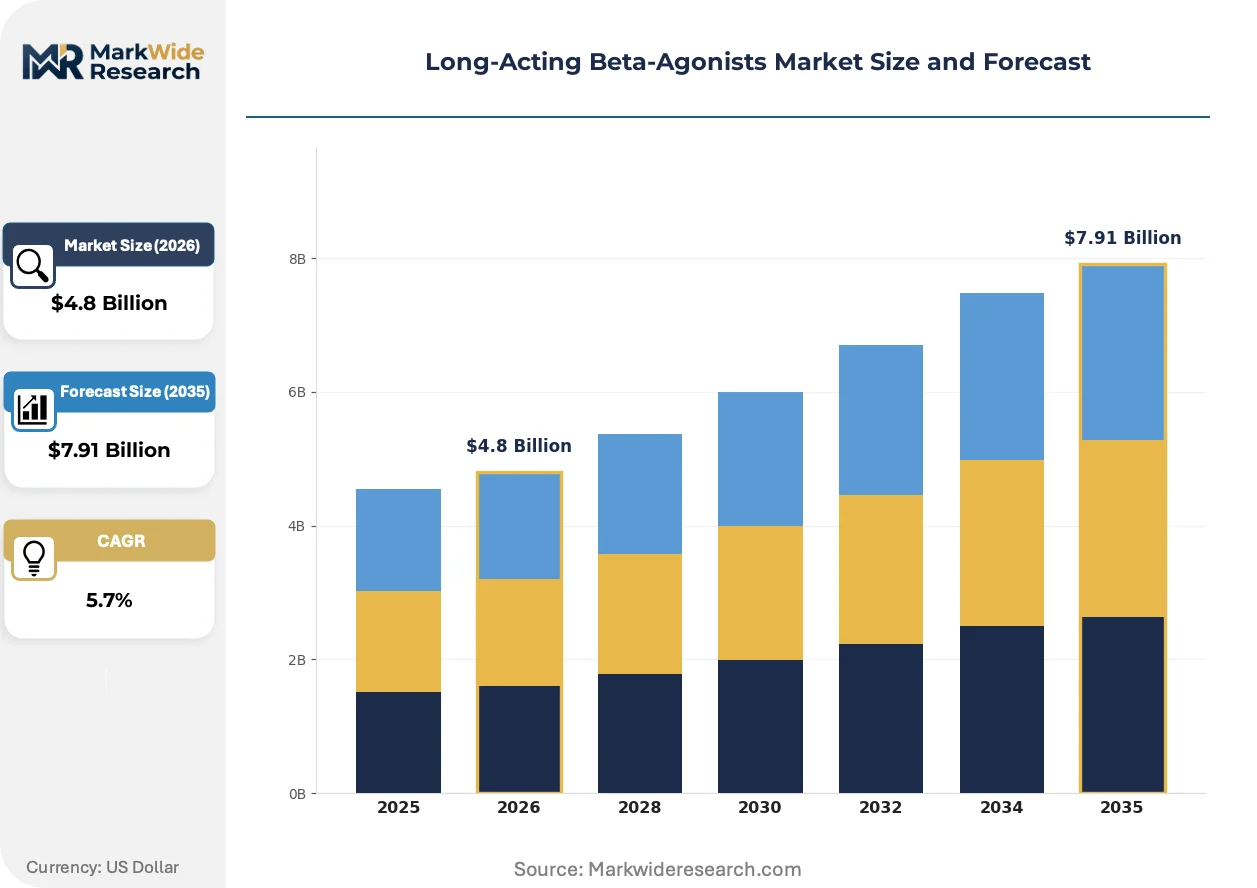
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Salmeterol, Formoterol, Indacaterol, Vilanterol Therapy Area: Chronic Obstructive Pulmonary Disease, Asthma, Cystic Fibrosis, Allergic Rhinitis End User: Hospitals, Clinics, Home Care, Rehabilitation Centers Delivery Mode: Inhalers, Nebulizers, Metered-Dose Inhalers, Dry Powder Inhalers |
| Companies Covered | GlaxoSmithKline, AstraZeneca, Boehringer Ingelheim, Novartis, Teva Pharmaceutical Industries, Merck & Co., Chiesi Farmaceutici, Viatris, Cipla, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Long-Acting Beta-Agonists Market Shifts & Advancements
Receptor pharmacology advances and environmental compliance pressures are converging to reshape formulation science and delivery platform selection across maintenance bronchodilator portfolios.
Triple-combination therapies incorporating LABA, long-acting muscarinic antagonist, and inhaled corticosteroid are integrating into single-inhaler devices to reduce polypharmacy burden and improve adherence metrics in severe COPD populations. United States pulmonology practices are adopting these platforms faster than European counterparts due to consolidated reimbursement pathways. The structural consequence is compressing market space for dual-combination legacy products while expanding the addressable patient pool previously managed on separate devices.
EMA's Medical Device Regulation framework for drug-device combinations is elevating human factors engineering requirements and post-market surveillance obligations across European member states. Manufacturers must now submit usability validation studies and real-world evidence protocols that were previously voluntary. Fixed-dose combination portfolios face the steepest compliance burden, particularly those with electronic dose counters or connected features.
Hospital procurement consortia are consolidating purchasing volume and demanding carbon footprint disclosures alongside clinical efficacy data in tender evaluations. Dry powder inhaler platforms with quantified lifecycle assessments are displacing pressurized alternatives in Nordic and German hospital formularies. This pattern is most visible in tertiary respiratory centers where sustainability committees hold veto authority over device selection.
Long-Acting Beta-Agonists Market Segmentation
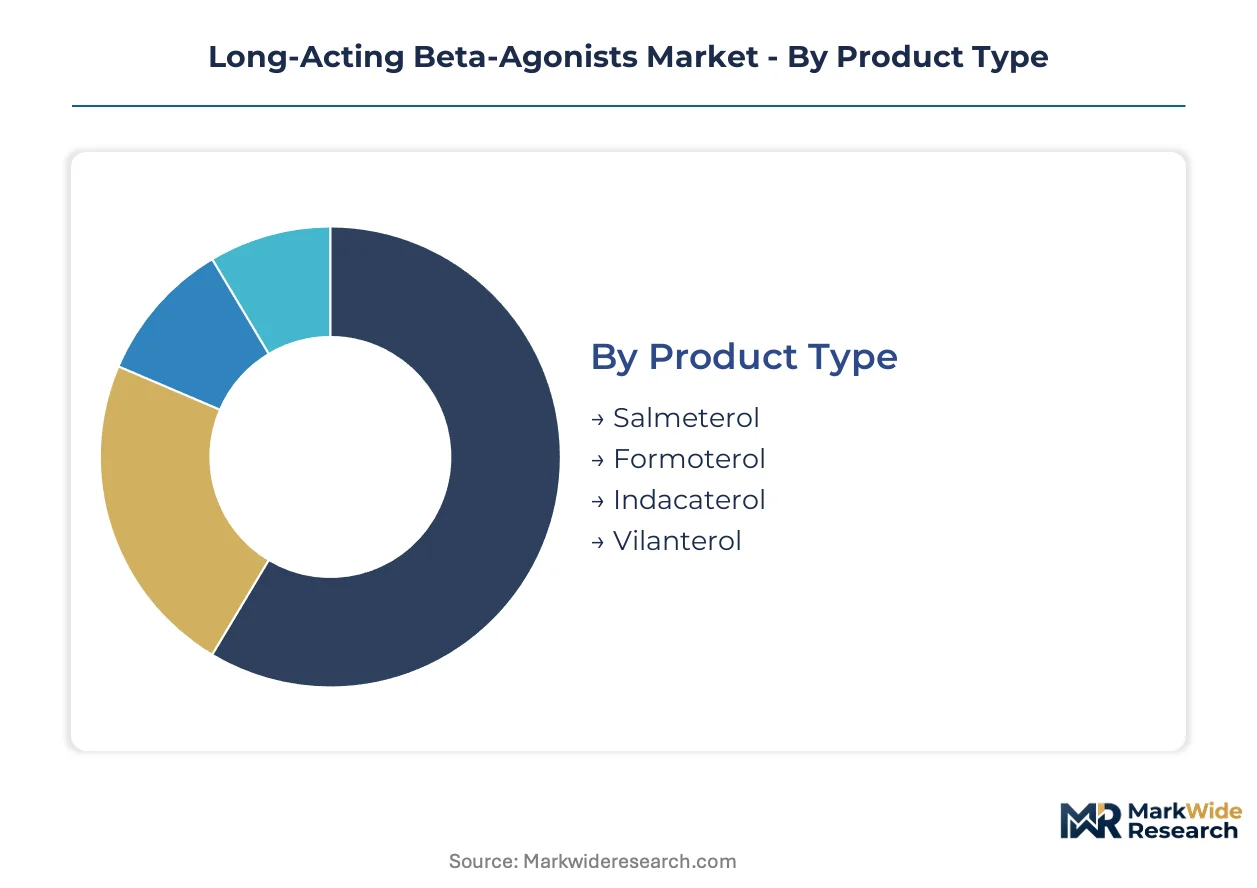
Segmentation in the Long-Acting Beta-Agonists Market reveals how formulation chemistry, disease severity, and care setting interact to determine prescribing patterns. Manufacturers must align R&D investments with the technical requirements of each delivery platform and the reimbursement constraints of distinct end-use environments.
Product Type:
Receptor pharmacology and duration of action define the competitive positioning of each molecular entity.
- Salmeterol:The lipophilic 12-hour beta-2 agonist with slow receptor association kinetics requires concurrent corticosteroid use for asthma safety protocols. Demand concentrates in United States maintenance regimens where FDA labeling mandates combination therapy.
- Formoterol:This hydrophilic compound delivers rapid onset with 12-hour coverage, enabling both maintenance and acute symptom relief in approved indications. German hospital protocols favor formoterol-based combinations for COPD exacerbation prevention programs.
- Indacaterol:The ultra-LABA with 24-hour receptor occupancy supports once-daily dosing adherence in elderly COPD populations.
- Vilanterol:Engineered for sustained bronchodilation in single-inhaler triple-therapy combinations, this GSK-proprietary molecule anchors next-generation portfolio expansion.
Salmeterol leads on scale; vilanterol leads on momentum.
Therapy Area:
Disease prevalence and treatment intensity create divergent margin profiles across respiratory indications.
- Chronic Obstructive Pulmonary Disease:Progressive airflow limitation in this smoking-related population drives the highest absolute prescription volumes globally. Medicare reimbursement for home nebulization services in the United States expands maintenance bronchodilator access to rural patient cohorts.
- Asthma:Biologic-adjacent prescribing patterns in severe allergic asthma elevate pricing power for LABA/ICS combinations. United States pulmonology practices adopt triple-therapy platforms faster than European counterparts due to consolidated payer pathways.
- Cystic Fibrosis:Bronchodilator therapy serves as adjunctive care in this orphan disease population with specialized center-based management.
- Allergic Rhinitis:Off-label or combination use of LABA compounds remains limited in this upper airway indication dominated by intranasal corticosteroids.
COPD commands volume leadership; asthma captures premium positioning.
End User:
Care setting determines device complexity tolerance and reimbursement pathway structure.
- Hospitals:Acute care units manage exacerbations with nebulized bronchodilators while respiratory wards initiate maintenance therapy. German hospital purchasing consortia now require carbon footprint disclosures alongside clinical efficacy in tender evaluations.
- Clinics:Outpatient pulmonology practices in the United States drive triple-combination adoption through electronic health record-integrated prescribing.
- Home Care:Medicare-expanded reimbursement for home nebulization services extends maintenance regimen access to mobility-limited patients.
- Rehabilitation Centers:Pulmonary rehabilitation programs face staffing constraints in delivering standardized inhaler technique training for multi-step device activation.
Hospitals lead on procurement scale; home care leads on access expansion.
Delivery Mode:
Device engineering and environmental compliance reshape platform selection across maintenance portfolios.
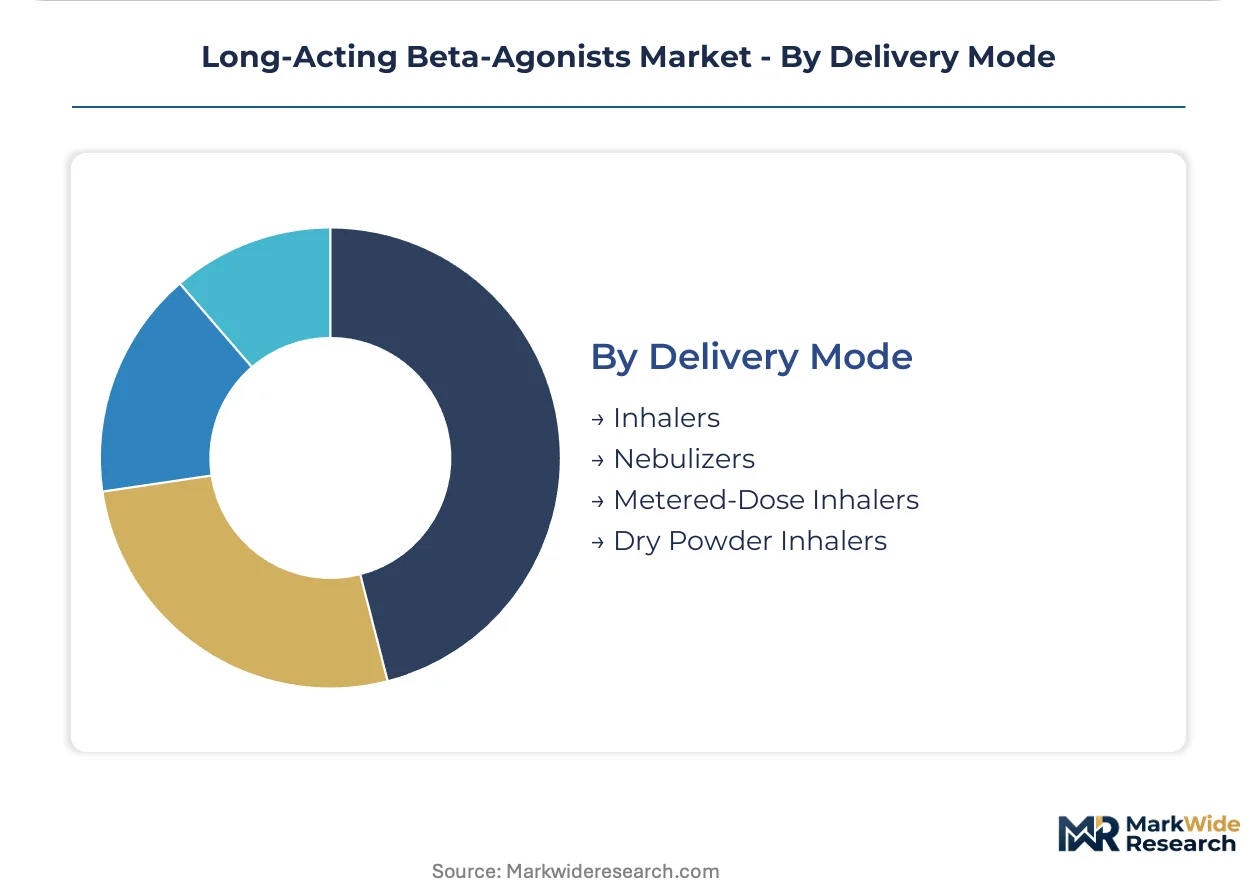
- Inhalers:This broad category encompasses multiple mechanical designs for bronchodilator aerosolization. EPA AIM Act hydrofluoroalkane restrictions force simultaneous reformulation of propellant chemistry and device electronics.
- Nebulizers:Jet and mesh nebulization systems serve acute care and home maintenance segments with high-dose delivery capability.
- Metered-Dose Inhalers:Pressurized devices with hydrofluoroalkane propellants face compressed returns on legacy portfolios before patent expiry.
- Dry Powder Inhalers:Breath-actuated platforms with quantified lifecycle assessments displace pressurized alternatives in Nordic and German hospital formularies.
Metered-dose inhalers retain installed base dominance; dry powder inhalers gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost-of-compliance gaps between the United States and European Union are redirecting active pharmaceutical ingredient manufacturing toward contract networks in India and Eastern Europe. Manufacturers now site production where EMA MDR and FDA oversight create differential burdens.
United States
Medicare reimbursement expansion for home nebulization services is extending maintenance bronchodilator access to rural and mobility-limited patient populations across the Southeast and Midwest. FDA labeling mandates for LABA/ICS combination therapy in asthma safety protocols shape prescribing patterns in pulmonology practices. The Research Triangle Park cluster in North Carolina anchors respiratory clinical trial infrastructure.
Germany
Hospital-based COPD management programs in Bavaria and North Rhine-Westphalia are expanding scheduled LABA/ICS maintenance under EMA-approved combination therapy protocols. EMA's Medical Device Regulation framework elevates human factors engineering requirements for device-drug combinations. The Rhine-Main pharmaceutical manufacturing corridor concentrates active pharmaceutical ingredient synthesis for salmeterol and formoterol salts.
United Kingdom
Biologics-adjacent LABA development programs in Cambridge and London sustain AstraZeneca's respiratory portfolio positioning. NHS England procurement frameworks now incorporate carbon footprint metrics alongside clinical efficacy in inhaler tender evaluations. The Golden Triangle biotech cluster drives next-generation receptor pharmacology research.
India
Contract manufacturing organizations in Hyderabad and Ahmedabad are capturing formulation and active pharmaceutical ingredient production for generic LABA compounds. CDSCO alignment with ICH quality guidelines accelerates regulatory submission pathways for export markets. The Gujarat pharmaceutical zone specializes in bronchodilator salt chemistry and dry powder inhaler component fabrication.
Switzerland
Swissmedic oversight of combination product approvals maintains Basel's position as a regulatory gateway for European market entry. Precision device engineering capabilities in the Lake Geneva region support connected inhaler platform development. The country's contract research organizations manage multi-site clinical trials for triple-combination therapies.
Long-Acting Beta-Agonists Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue connected-device differentiation and carbon-neutral formulation platforms. The market consolidates around integrated respiratory portfolios where fixed-dose combinations dominate maintenance therapy positioning. Three archetypes prevail: Big Pharma incumbents with heritage respiratory franchises, mid-cap specialists in generic bronchodilator salts, and device-engineering firms converging on smart inhaler electronics. Competitive moves center on triple-therapy portfolio expansion and dry powder inhaler platform migration to escape hydrofluoroalkane propellant constraints.
Within the heritage pharmaceutical tier, GlaxoSmithKline and AstraZeneca exemplify integrated development capabilities spanning molecular design through device engineering. Boehringer Ingelheim occupies a position emphasizing respiratory specialization within a privately held structure. These three anchors represent distinct geographic concentrations—UK-based, Swedish-anchored, and German-rooted respectively—each aligning with regional regulatory pathways and procurement consortia preferences.
| Leading Market Players |
|---|
| GlaxoSmithKline |
| AstraZeneca |
| Boehringer Ingelheim |
| Novartis |
| Teva Pharmaceutical Industries |
| Merck & Co. |
| Chiesi Farmaceutici |
| Viatris |
| Cipla |
| Others |
Supply & Pricing Matrix
Hydrofluoroalkane propellant phase-downs under the EPA AIM Act are simultaneously inflating reformulation costs and redistributing manufacturing capacity toward dry powder inhaler platforms, compressing margins on legacy pressurized devices while elevating pricing power for suppliers with certified low-carbon alternatives.
Pricing Analysis
Distributor margins on LABA combination therapies vary sharply by device certification tier, with EMA MDR-compliant connected inhalers commanding premium positioning against commodity generic bronchodilators. Price differentiation rests on carbon footprint disclosure grades and ISO interoperability certification levels, with Nordic hospital procurement consortia penalizing uncertified alternatives. Cost compression in pressurized metered-dose inhalers is intensifying because propellant transition timelines outpace patent protection windows. Home care segments show highest price sensitivity due to Medicare reimbursement caps, while tertiary respiratory centers prioritize clinical outcomes over unit cost.
Supply Chain Analysis
EMA MDR and FDA combination product qualification requirements are gating active pharmaceutical ingredient sourcing to certified Western European and Indian contract manufacturing networks. Salmeterol and formoterol salt production draws from specialized facilities in Germany's Rhine-Main corridor and Hyderabad's pharmaceutical zone, with device electronics sourcing from Swiss precision engineering clusters. Single-source vulnerability concentrates in German API synthesis for legacy bronchodilator compounds. Distribution runs through hospital purchasing consortia in Europe and integrated pharmacy benefit managers in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EPA propellant restrictions and EMA device frameworks are accelerating replacement demand for reformulated maintenance bronchodilator portfolios.
For Market Incumbents: Deepen backward integration into dry powder inhaler component fabrication to escape hydrofluoroalkane supply constraints. Secure EMA MDR certification for connected device platforms before tender eligibility windows close. Anchor manufacturing capacity in India's Gujarat pharmaceutical zone to offset Western European cost inflation. For New Entrants and Emerging Players: Capture carbon-neutral formulation white space in Nordic hospital procurement channels where sustainability committees hold veto authority. Target home nebulization service segments in United States rural markets where Medicare reimbursement expansion is outpacing incumbent coverage. Lead with Bluetooth-enabled adherence monitoring as differentiated value demonstration to United States payers. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap generic bronchodilator specialists with untapped connected device pipelines. Long-term viability hinges on regulatory navigation capabilities across FDA and EMA parallel submission pathways. Watch for inflection when triple-combination therapy adoption rates in United States pulmonology practices cross threshold into mainstream maintenance protocols.| Strategic Initiative | Industry Significance |
|---|---|
| EMA MDR Certification Pathway | Secures tender eligibility in German and Nordic hospital purchasing consortia. |
| Dry Powder Inhaler Platform Migration | Escapes EPA AIM Act propellant restrictions while capturing carbon footprint premiums. |
| Connected Device Development | Enables Bluetooth adherence monitoring integration with United States electronic health records. |
| Triple-Combination Portfolio Expansion | Captures severe COPD patients previously managed on separate LAMA and ICS devices. |
| API Manufacturing Scale-Up in India | Reduces cost exposure to Western European contract manufacturing concentration. |
Research Methodology
Coverage spans North America, Western Europe, and South Asia, with primary inputs from each region triangulated against secondary validation. Interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists informed prescribing pattern and reimbursement dynamics. Secondary sources include FDA filings, EMA submissions, ClinicalTrials.gov records, and CMS Medicare reimbursement databases. Bottom-up patient volume modeling and top-down pharmaceutical revenue triangulation anchored market sizing.
Granularity-level modeling operated at molecule-device combination, therapy area severity tier, and regional regulatory cluster dimensions. CAGRs were derived from patient population epidemiology, treatment penetration curves, and pricing trajectory assumptions across the analysis window. Forecast inputs incorporated EPA propellant phase-down timelines, EMA MDR implementation schedules, and Medicare home nebulization reimbursement expansion pathways.
Underlying measurement precision varies by segment; triple-combination therapy forecasts carry tighter precision than legacy dual-combination projections due to concentrated United States adoption data. Forecasts reflect documented assumptions on regulatory compliance timelines and reimbursement policy continuity. A model refresh is warranted upon material change in EPA propellant transition deadlines or EMA device recertification requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
China Opioids Market
Pharmaceuticals
Dipeptide Peptidase 4 Inhibitors Market
Pharmaceuticals
Global Varicella Vaccine Market
Pharmaceuticals
Global Divalproex Sodium Market
Pharmaceuticals
Antidepressants Market
Pharmaceuticals
Peptide Therapeutics Market
Pharmaceuticals
Australia Schizophrenia Drugs Market
Pharmaceuticals
Brain Tumor Drugs Market
Pharmaceuticals
Global Basal Insulin Market
Pharmaceuticals
Cough Oral Solution Market
Pharmaceuticals
Global Paracetamol Market
Pharmaceuticals
North America Sodium-Dependent Glucose Co-Transporter 2 (Sglt2) Market
Pharmaceuticals
Global Doxorubicin Market
Pharmaceuticals
Global Human Rabies Vaccine Market
Pharmaceuticals
Pharmaceutical Contract Development and Manufacturing Organization (CDMO) Market
Pharmaceuticals
Netupitant-Palonosetron FDC Market