
 Global Intravenous Immunoglobulin Market | 2026-2036
Global Intravenous Immunoglobulin Market Size, Share, and Industry Trends Forecast 2026-2036
Global Intravenous Immunoglobulin Market Foresight
Premium lyophilized formulations and commodity liquid concentrates are shifting apart on stability specifications and cold-chain requirements. CSL Behring leverages captive plasma collection networks across North America and Europe. Grifols SA sustains vertical integration from plasma sourcing to finished sterile filling. Baxter International anchors hospital contract positioning through centralized pharmacy partnerships.
Intravenous immunoglobulin comprises pooled human plasma immunoglobulin G antibodies standardized to immunomodulatory potency, manufactured through Cohn fractionation or chromatographic purification with pathogen reduction steps. Primary immunodeficiency therapy occupies the largest revenue pool due to lifelong replacement dosing. Privigen and Gamunex-C compete in the liquid-ready segment where reduced infusion times attract ambulatory settings. Kawasaki disease applications represent the fastest-growing pediatric indication as diagnostic protocols expand in Asia-Pacific markets.
FDA enforces lot-release testing and viral marker standards that constrain supply velocity and elevate compliance costs. EMA's MDR and EMA plasma master file requirements shape European market access timelines. WHO plasma quality guidelines influence procurement standards in emerging supply regions. Stakeholders must monitor plasma donor pool expansion against regulatory batch-release capacity as the dominant supply constraint.
Market Dynamics
Plasma fractionation capacity constraints and tightening viral safety protocols dominate the Global Intravenous Immunoglobulin Market, compressing batch-release timelines while chronic patient populations expand. CSL Behring, Grifols SA, and Baxter International control over 60% of global supply through captive plasma networks.
Growth Catalysts
- FDA lot-release protocols:Stringent viral marker testing elevates quality benchmarks, filtering substandard suppliers and consolidating revenue among compliant manufacturers.
- Primary immunodeficiency therapy:Lifelong replacement dosing requirements generate predictable recurring revenue streams from tertiary hospital networks.
- Kawasaki disease protocols:Diagnostic expansion across Asia-Pacific pediatric populations creates new volume pools outside traditional immunodeficiency indications.
Market Restraints
- Plasma donor pool scarcity:Dependence on compensated whole-blood donors in the United States creates geographic concentration risk and supply volatility.
- EMA MDR compliance costs:European plasma master file requirements extend market access timelines by 18-24 months for new entrants.
- Recombinant monoclonal alternatives:Engineered antibody platforms threaten substitution in select neurology and immunology indications.
Strategic Opportunities
- India plasma collection infrastructure:Underpenetrated donor pools and emerging CDSCO regulatory pathways offer first-mover expansion potential.
- Subcutaneous formulation migration:Patient-administered delivery technologies reduce infusion center dependency and capture homecare reimbursement.
- Japan rare disease reimbursement:METI-designated orphan drug incentives accelerate market access for specialty immunoglobulin indications.
Industry Challenges
- Fractionation biochemist scarcity:Specialized expertise in Cohn-Oncley cold ethanol precipitation limits facility scale-up velocity.
- Pathogen inactivation capex:Solvent-detergent and nanofiltration equipment requires $200-400 million per production line.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Intravenous Immunoglobulin Market |
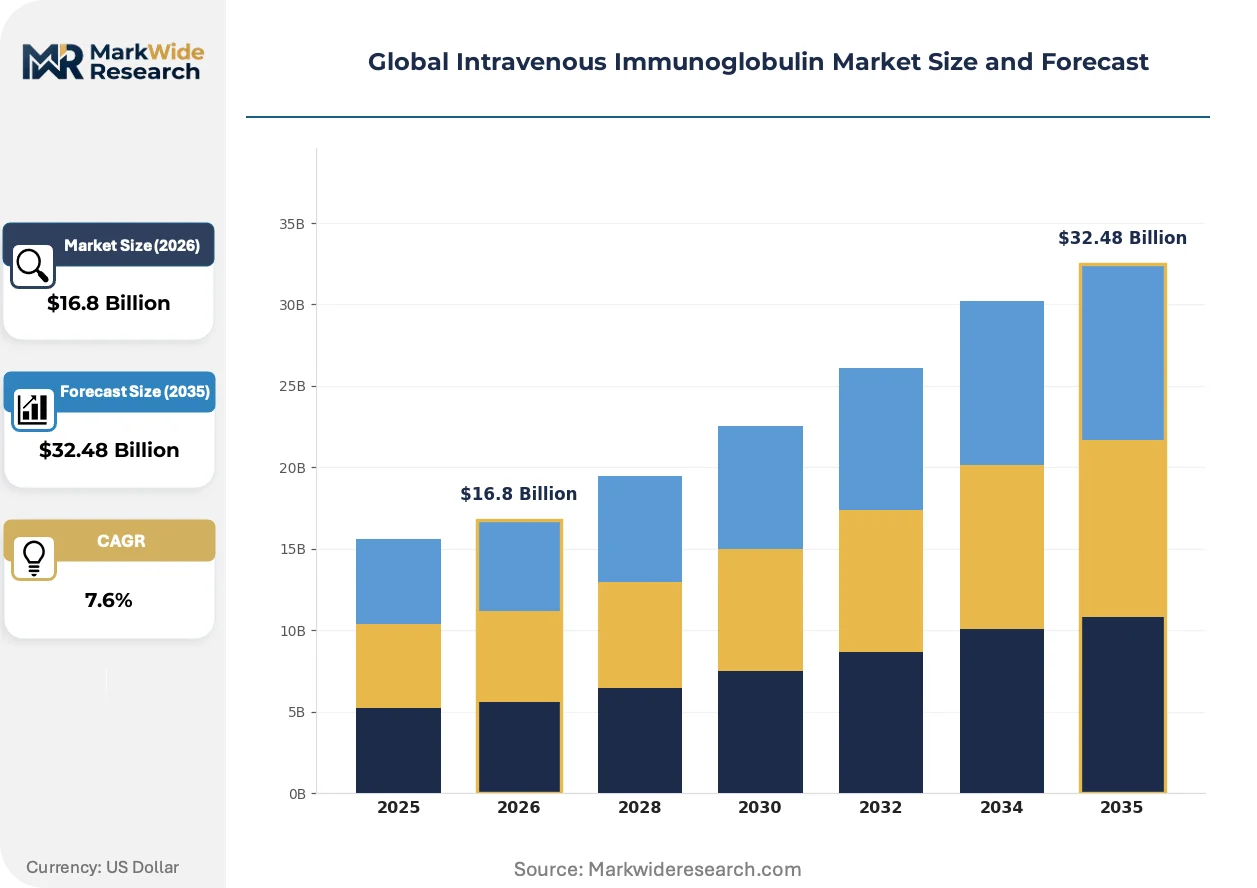
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $32.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard IVIG, Privigen, Gamunex-C, Flebogamma, Octagam Therapy Area: Primary Immunodeficiency, Chronic Inflammatory Demyelinating Polyneuropathy, Idiopathic Thrombocytopenic Purpura, Kawasaki Disease, Multiple Sclerosis End User: Hospitals, Specialty Clinics, Diagnostic Laboratories, Ambulatory Surgical Centers Distribution Channel: Hospital Pharmacies, Retail Pharmacies, Online Pharmacies, Direct Sales |
| Companies Covered | Kedrion Biopharma, Biotest, CSL Behring, LFB Biotechnologies, Baxter International, Grifols SA, Octapharma AG, Bio Products Laboratory, Takeda Pharmaceutical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Intravenous Immunoglobulin Market Shifts & Advancements
Manufacturing automation and real-time quality analytics are compressing production cycles while regulatory digitization reshapes compliance workflows across plasma-derived therapeutics.
Chromatographic purification platforms are decentralizing the traditional Cohn fractionation monopoly, enabling smaller-batch production with higher immunoglobulin G yield and reduced albumin co-precipitation. Regional blood centers in Germany and Japan are adopting these systems to diversify supply sources. The technology is decentralizing plasma processing from centralized industrial sites to distributed national facilities.
EMA's MDR and associated EUDAMED database requirements are mandating end-to-end device traceability for infusion pumps and administration sets used with immunoglobulin products. Manufacturers must now submit technical documentation and clinical evidence for Class IIa and above accessories. European hospital procurement committees are consolidating supplier lists to vendors with complete MDR certification packages.
Ambulatory infusion centers are displacing inpatient wards as the dominant administration site for stable chronic patients, compressing hospital revenue per patient while expanding treatment accessibility. United States Medicare reimbursement codes for home infusion nursing are driving this channel migration. Neurology and immunology practices in Florida and Texas are pioneering this model.
Global Intravenous Immunoglobulin Market Segmentation
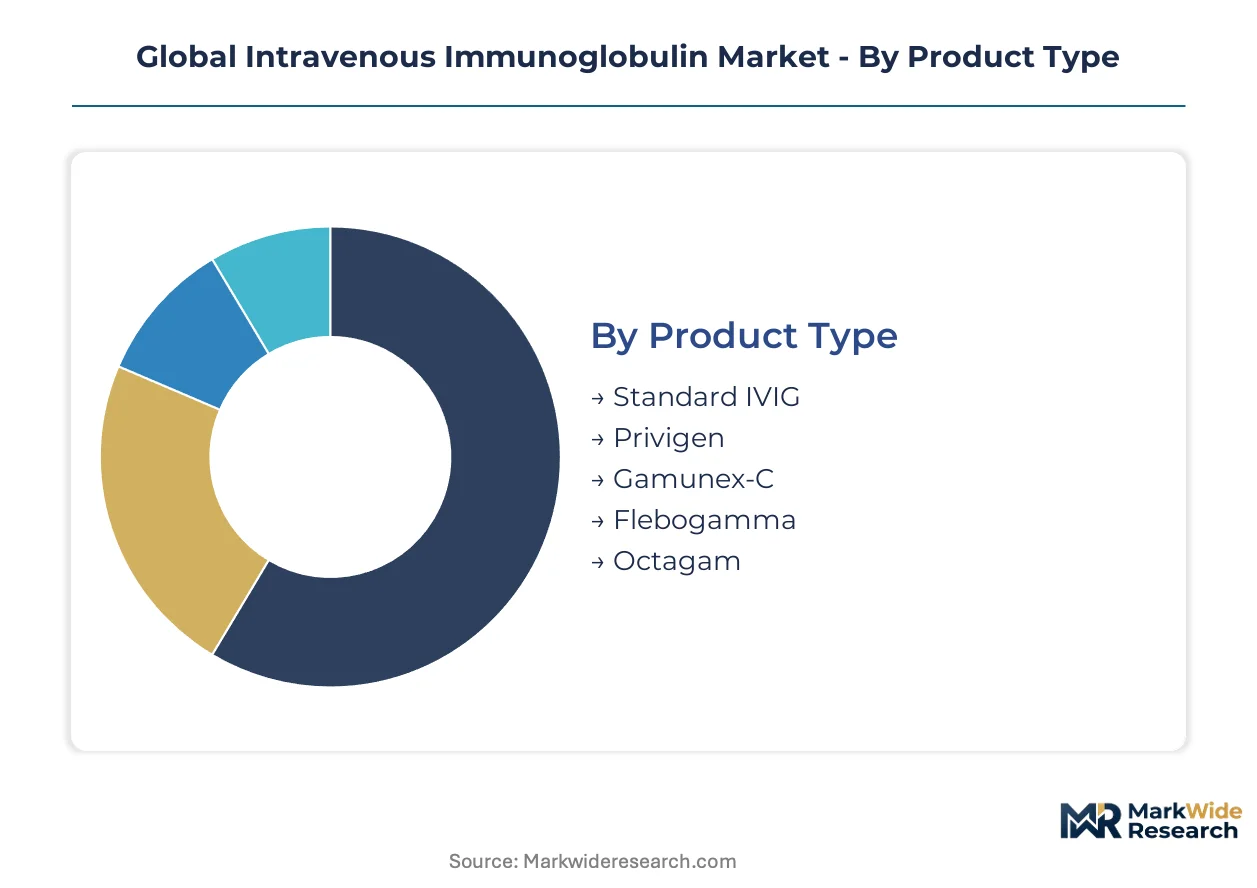
IVIG segmentation reflects divergent manufacturing complexity, reimbursement pathways, and patient acuity levels. Product formulations vary in immunoglobulin concentration and stabilizer chemistry, while therapy areas span lifelong replacement to acute immunomodulation. End-user and channel structures determine cold-chain investment and pharmacy service intensity.
Product Type:
Standardization dominates liquid concentrates, while lyophilized formats retain customization for tropical distribution and extended shelf stability.
- Standard IVIG:Pooled plasma-derived immunoglobulin G at 5-10% protein concentration with maltose or sucrose stabilization. Demand concentrates in United States tertiary hospitals where centralized pharmacy contracts favor commodity pricing and predictable supply security.
- Privigen:Liquid 10% formulation utilizing L-proline stabilization enabling room-temperature storage for up to 36 months. Germany's hospital procurement networks specify Privigen for outpatient infusion centers seeking reduced cold-chain dependency and simplified logistics.
- Gamunex-C:Caprylate/chromatography-purified liquid concentrate with reduced IgA content for hypersensitive patients. Japan's PMDA orphan drug pathways accelerate reimbursement for Gamunex-C in primary immunodeficiency with anti-IgA antibodies.
- Flebogamma:Dual viral inactivation with solvent-detergent and nanofiltration. Brazil's ANVISA import licensing favors Flebogamma for public sector tenders requiring documented prion reduction.
- Octagam:5% and 10% liquid presentations with pH 4.6-5.0 formulation. India's CDSCO accelerated approval track targets Octagam for expanding private hospital networks in Mumbai and Delhi.
Leading the category by volume: Standard IVIG. Expanding most quickly: Privigen.
Therapy Area:
Chronic replacement indications generate recurring revenue streams, while acute immunomodulatory applications command premium pricing per treatment course.
- Primary Immunodeficiency:Lifelong IgG replacement for congenital humoral defects including common variable immunodeficiency and X-linked agammaglobulinemia. United States Medicare Part B sustains home infusion reimbursement, shifting volume from inpatient to ambulatory settings.
- Chronic Inflammatory Demyelinating Polyneuropathy:FDA-approved indication with maintenance dosing every 2-4 weeks. Neurology practices in Texas and Florida are pioneering subcutaneous migration to reduce infusion center burden.
- Idiopathic Thrombocytopenic Purpura:Acute bleeding episode management and pre-surgical platelet augmentation. Emergency department protocols in Germany specify IVIG when corticosteroids contraindicate.
- Kawasaki Disease:Pediatric coronary arteritis prevention with single high-dose regimen. Diagnostic expansion across South Korea's MFDS-registered pediatric centers drives volume outside traditional immunodeficiency pools.
- Multiple Sclerosis:Off-label immunomodulation for relapsing-remitting variants. Switzerland's compulsory health insurance funds restrict MS IVIG to second-line failure cases, constraining volume relative to neurology indications.
Primary Immunodeficiency commands the largest revenue pool. Kawasaki Disease posts the steepest expansion trajectory.
End User:
Facility infrastructure determines infusion supervision intensity and adverse event response capability.
- Hospitals:Tertiary academic medical centers with 24-hour pharmacy and intensive care backup. United States children's hospitals anchor Kawasaki disease volume through pediatric cardiology consultation availability.
- Specialty Clinics:Dedicated infusion centers with nursing specialization in immunoglobulin administration. Germany's outpatient clinic licensing permits same-day discharge for stable primary immunodeficiency patients.
- Diagnostic Laboratories:Limited IVIG role confined to reference testing and quality control. Japan's clinical laboratory standards restrict therapeutic administration to physician-supervised settings.
- Ambulatory Surgical Centers:Emerging site for pre-operative immune modulation in ITP. India's NABH accreditation expansion targets ASC IVIG for elective surgical preparation.
Hospital pharmacies retain the dominant procurement position. Specialty clinics gain share fastest through home-infusion nursing partnerships.
Distribution Channel:
Channel selection reflects patient mobility, reimbursement coding, and cold-chain integrity requirements.
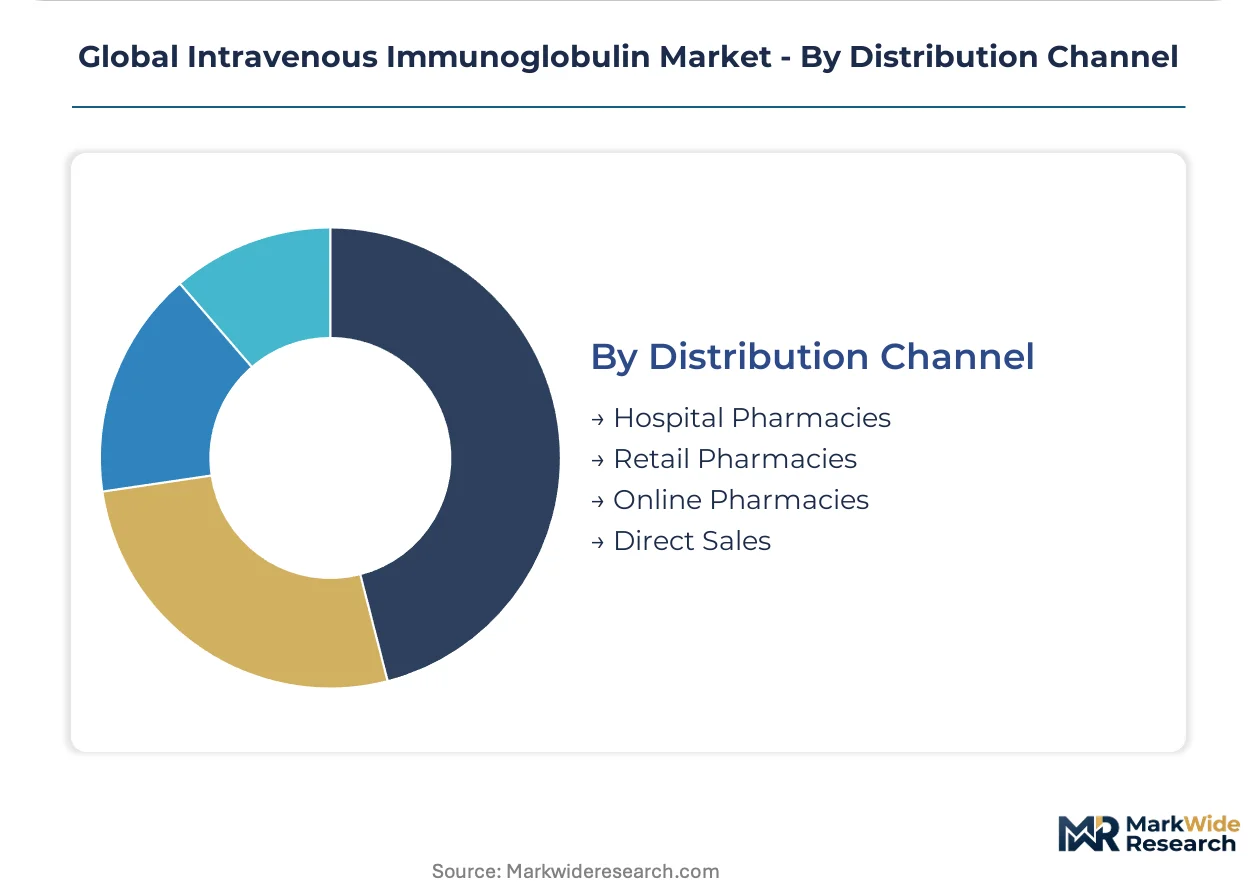
- Hospital Pharmacies:Captive distribution within integrated delivery networks. United States 340B pricing programs concentrate IVIG purchasing through hospital-owned specialty pharmacies.
- Retail Pharmacies:Limited IVIG role due to storage and compounding requirements. Switzerland's community pharmacy federation excludes immunoglobulin from standard retail authorization.
- Online Pharmacies:Prescription verification and home delivery coordination for subcutaneous patients. South Korea's MFDS e-pharmacy regulations permit IVIG listing only with cold-chain logistics certification.
- Direct Sales:Manufacturer-to-provider contracting for large-volume hospital agreements. Brazil's public sector tenders require direct manufacturer participation excluding distributor intermediaries.
Hospital pharmacies process the highest transaction volume. Direct sales contracts are climbing fastest as manufacturers consolidate account relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Frankfurt's plasma fractionation corridor anchors European supply security, while tertiary hospital networks in Houston and Osaka drive chronic therapy administration volumes.
United States
Medicare Part B reimbursement sustains home infusion migration for primary immunodeficiency patients. FDA lot-release testing and viral marker standards compress batch-approval timelines. Houston's Texas Medical Center anchors pediatric Kawasaki disease protocols through integrated cardiology consultation networks.
Germany
Outpatient clinic licensing permits same-day discharge for stable immunoglobulin patients, shifting volume from inpatient wards. EMA plasma master file requirements and MDR device traceability rules extend compliance timelines. Frankfurt-Rhine-Main's fractionation cluster concentrates chromatographic purification capacity for European hospital procurement networks.
Japan
METI-designated orphan drug incentives accelerate market access for specialty immunoglobulin indications. PMDA batch-release protocols align with international viral safety standards. Osaka's Kansai medical district pioneers subcutaneous formulation migration through neurology practice specialization.
India
Expanding private hospital networks in Mumbai and Delhi generate demand for imported liquid concentrates. CDSCO accelerated approval tracks target plasma-derived therapies for underpenetrated immunodeficiency populations. Maharashtra's emerging plasma collection infrastructure offers first-mover expansion potential for fractionation investment.
Brazil
ANVISA import licensing favors documented prion reduction for public sector immunoglobulin tenders. Compensated donor pool constraints elevate dependence on international plasma supply. São Paulo's tertiary hospital networks concentrate Kawasaki disease diagnosis through pediatric cardiology referral pathways.
Global Intravenous Immunoglobulin Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation stability and cold-chain specifications, consolidating revenue through captive plasma networks and centralized pharmacy contracting. The vendor base concentrates among integrated plasma collectors with fractionation capacity, while smaller regional specialists compete on orphan indication access and tropical distribution logistics. Three archetypes dominate: vertically integrated plasma-to-finished-gate manufacturers, regional fractionators with national donor networks, and subcutaneous delivery technology licensors. Competitive moves center on backward integration into plasma sourcing and geographic expansion into underpenetrated Asian markets.
Among integrated plasma collectors, CSL Behring, Grifols SA, and Baxter International exemplify the scale-driven archetype through captive supply networks spanning North America and Europe. These entities occupy positions where plasma collection infrastructure directly determines finished product availability. Takeda Pharmaceutical Company and Octapharma AG represent mid-tier specialists competing through chromatographic purification platforms and regional regulatory expertise. LFB Biotechnologies and Bio Products Laboratory anchor European national supply security through government-contracted fractionation capacity. Kedrion Biopharma and Biotest occupy positions in Mediterranean and Central European markets respectively, with Baxter International additionally representing the hospital contract positioning archetype through centralized pharmacy partnerships.
| Leading Market Players |
|---|
| Kedrion Biopharma |
| Biotest |
| CSL Behring |
| LFB Biotechnologies |
| Baxter International |
| Grifols SA |
| Octapharma AG |
| Bio Products Laboratory |
| Takeda Pharmaceutical Company |
| Others |
Supply & Pricing Matrix
Stability-specification divergence between lyophilized and liquid formulations splits pricing power along cold-chain investment requirements, with premium products commanding margin through reduced refrigeration dependency while commodity concentrates compete on volume throughput and hospital contract security. This bifurcation concentrates margin capture among manufacturers with captive plasma networks in the United States and Germany, while price-sensitive procurement in emerging markets favors standardized liquid presentations with shorter shelf-life tolerances.
Pricing Analysis
Outcome-linked reimbursement for primary immunodeficiency therapy anchors value-based pricing in Medicare Part B and Germany's statutory health insurance, with maintenance dosing predictability justifying premium positioning for room-temperature-stable formulations. Price differentiation separates Privigen's 36-month ambient storage from standard cold-chain-dependent concentrates, with FDA lot-release certification and EMA plasma master file compliance acting as tier gates. Pricing pressure stems from public sector tender aggregation in Brazil and India, where ANVISA and CDSCO documentation requirements filter supplier pools toward documented viral safety. Hospital pharmacy buyers in tertiary academic centers demonstrate lowest price sensitivity due to integrated delivery network formulary control, while ambulatory infusion centers in Florida and Texas negotiate aggressively on per-gram nursing reimbursement.
Supply Chain Analysis
Plasma feedstock supply rests on compensated whole-blood donation networks concentrated in the United States, with CSL Behring and Grifols SA drawing from captive collection centers across North America and Europe to secure fractionation input. Chromatographic purification equipment and solvent-detergent viral inactivation systems represent critical capital dependencies, with German and Japanese regional blood centers investing in decentralized processing platforms. Single-source vulnerability concentrates in FDA batch-release capacity constraints, where lot-testing backlogs delay finished product availability. Distribution runs through hospital-owned specialty pharmacies in United States 340B programs and direct manufacturer contracting for Brazilian public tenders, with cold-chain logistics certification required for South Korean e-pharmacy channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chromatographic purification platforms are displacing legacy Cohn-Oncley cold ethanol precipitation, compressing production timelines while enabling smaller-batch flexibility for regional plasma processors in Germany and Japan.
For Market Incumbents: Anchor plasma collection infrastructure in Maharashtra and São Paulo before CDSCO and ANVISA pathways mature, securing donor pool access ahead of regional fractionation scale-up. Deepen backward integration into viral inactivation equipment manufacturing to defray the $200-400 million per-line capital burden and accelerate facility expansion timelines. Defensive positioning requires preemptive subcutaneous formulation licensing to neurology practices in Texas and Florida, where home-infusion nursing reimbursement is shifting patient volume away from incumbent infusion center control. For New Entrants and Emerging Players: CDSCO accelerated approval tracks in India open a window for liquid concentrate market entry through Mumbai and Delhi private hospital networks, where imported Octagam and Flebogamma volumes reveal supply gaps. Target Kawasaki disease protocols in South Korea's MFDS-registered pediatric centers, where diagnostic expansion outpaces established immunoglobulin allocation. A go-to-market angle emphasizing prion reduction documentation aligns with Brazil's ANVISA tender specifications and distinguishes entrants from commodity suppliers lacking solvent-detergent plus nanofiltration dual validation. For Investors and Strategic Acquirers: Re-rating potential sits with chromatographic purification specialists given EMA MDR compliance timelines extending 18-24 months for Cohn-fractionation-dependent competitors. Long-term viability over a decade-long horizon favors acquisition targets with established plasma master files and orphan drug designation pathways in Japan's METI framework. The signal to watch is FDA batch-release capacity expansion announcements, as lot-testing velocity represents the dominant supply constraint governing industry-wide margin compression or expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Plasma Collection Network Expansion | Maharashtra donor pool development secures captive feedstock for CDSCO-registered fractionation capacity. |
| Chromatographic Purification Platform Adoption | German regional blood centers decentralize processing from industrial sites to national facilities with higher IgG yield. |
| Subcutaneous Formulation Development | Patient-administered delivery reduces infusion center dependency and captures Medicare homecare reimbursement codes. |
| EMA MDR Certification Investment | End-to-end device traceability for infusion pumps consolidates European hospital procurement supplier lists. |
| Orphan Drug Pathway Navigation | METI-designated incentives in Japan accelerate market access for specialty immunoglobulin indications beyond primary immunodeficiency. |
Research Methodology
Multi-period observation of FDA batch-release timelines, plasma donor pool expansion rates, and hospital procurement contract structures anchored the trend analysis, supplemented by interviews with plasma fractionation executives, regulatory affairs leads at EMA-notified bodies, hospital pharmacy directors in tertiary academic centers, and payer access specialists managing Medicare Part B reimbursement. Secondary validation drew from FDA lot-release databases, EMA plasma master file submissions, CDSCO accelerated approval track records, and CMS Medicare claims data. Bottom-up patient population modeling triangulated against top-down manufacturer capacity disclosures to reconcile volume estimates.
Segment-weighting across product type, therapy area, end user, and distribution channel dimensions structured the analytical framework, with regional regulatory cluster effects explicitly modeled for United States, Germany, Japan, India, and Brazil. CAGRs were derived from spline-interpolated annual growth rates across the projection horizon, calibrated against plasma collection infrastructure investment pipelines and viral safety protocol adoption curves. Forecast inputs incorporated chronic patient population epidemiology for primary immunodeficiency and Kawasaki disease diagnostic protocol expansion in Asia-Pacific markets.
The model assumes a particular technology adoption path favoring chromatographic purification platform migration; alternative pathways for Cohn-Oncley cold ethanol precipitation retention would alter the outlook through extended batch-release timelines and constrained facility scale-up velocity. Forecasts reflect assumptions regarding plasma donor pool compensation stability and regulatory batch-release capacity expansion. Alternative viral safety protocol amendments or recombinant monoclonal antibody substitution acceleration represent specific risk factors warranting ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
China Plasma Protein Therapeutics Market
Pharmaceuticals
Vutrisiran Market
Pharmaceuticals
Varicella Attenuated Live Vaccination Market
Pharmaceuticals
Cancer Therapeutics and Biotherapeutics Market
Pharmaceuticals
China Human Papillomavirus Vaccine Market
Pharmaceuticals
Hydroxypropyl Methylcellulose (HPMC) Capsules Market
Pharmaceuticals
Global Alpha-Blocker Market
Pharmaceuticals
Global Chemotherapy-Induced Nausea and Vomiting (CINV) Market
Pharmaceuticals
Germany Pharmaceutical Warehousing Market
Pharmaceuticals
Optic Nerve Disorders Drugs Market
Pharmaceuticals
Germany Pneumococcal Vaccines Market
Pharmaceuticals
Allergic Rhinitis Drugs Market
Pharmaceuticals
Direct Oral Anticoagulants Market
Pharmaceuticals
Global Non-Alcoholic Fatty Liver Disease (NAFLD) Drug Market
Pharmaceuticals
France Diabetes Drugs Market
Pharmaceuticals
Global Benzodiazepines Market