
 Global Gastroparesis Drug Market | 2026-2036
Global Gastroparesis Drug Market Size, Share, and Industry Trends Forecast 2026-2036
Global Gastroparesis Drug Market Foresight
Subscription-based patient support programs is restructuring how pharmaceutical firms monetize chronic gastroparesis therapy. Evoke Pharma leverages direct-to-specialist marketing to sustain prescriber loyalty for its flagship prokinetic offering. Takeda Pharmaceutical anchors its position through extensive hospital formulary contracts across North American and European markets. AbbVie differentiates via integrated diagnostic-to-treatment protocols that streamline patient identification.
Gastroparesis drugs encompass pharmacological agents that modulate gastric motility through dopamine receptor antagonism, serotonin 5-HT4 agonism, or motilin receptor activation, typically administered via oral, intravenous, or subcutaneous routes to accelerate gastric emptying and relieve nausea in patients with delayed gastric transit. These therapeutics serve the primary commercial purpose of reducing hospitalization frequency and improving nutritional outcomes in chronic gastroparesis populations. Prokinetic agents command the largest revenue pool due to established reimbursement codes and long prescriber familiarity, while ghrelin receptor agonists represent the fastest-expanding category driven by novel mechanisms addressing refractory cases. Idiopathic gastroparesis indication segments attract disproportionate R&D investment because diagnostic ambiguity creates substantial unmet need and pricing flexibility.
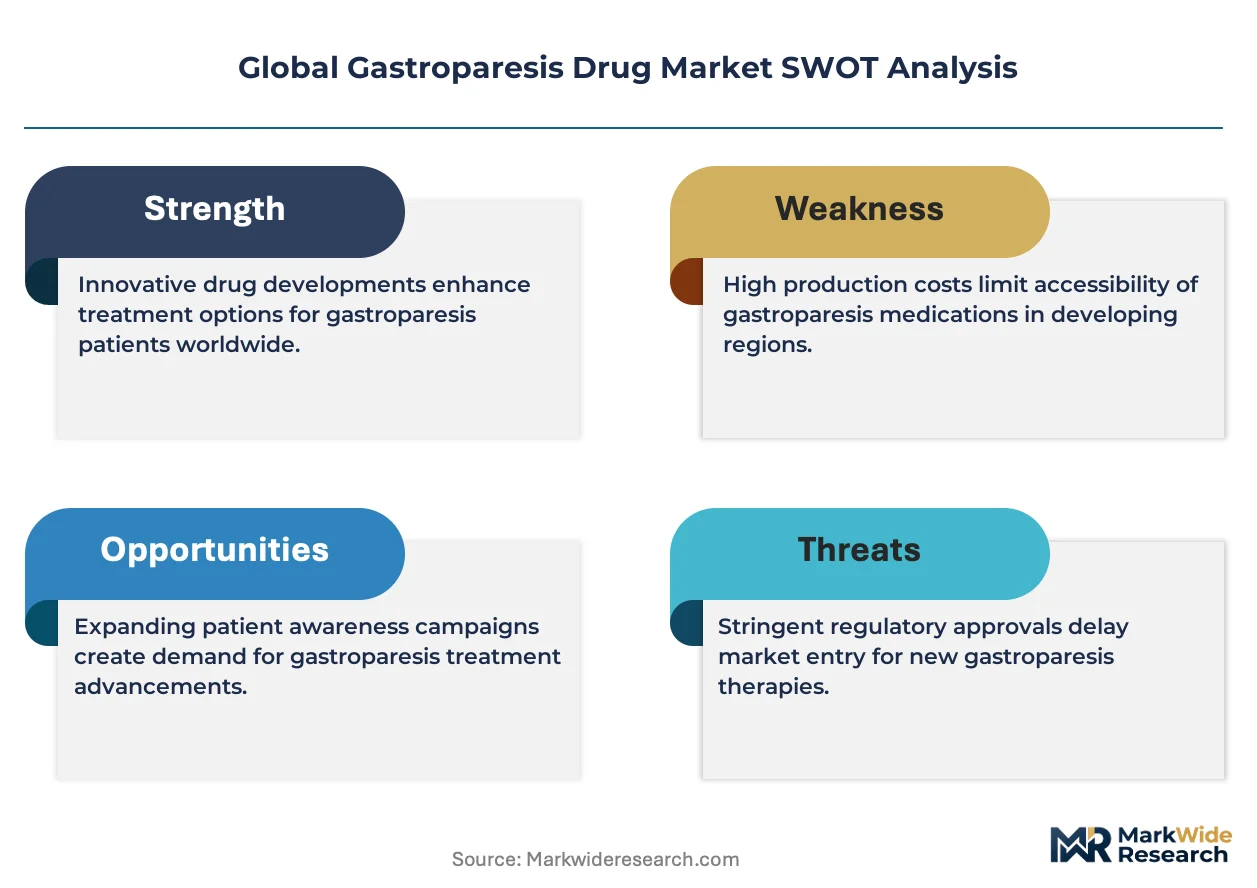
The FDA's orphan drug designation framework and the EMA's conditional marketing authorization pathway shape clinical trial design and market access strategies for novel gastroparesis therapeutics, with both regulators emphasizing biomarker-validated gastric emptying endpoints. Japan's PMDA accelerates review timelines for gastrointestinal motility disorders through its Sakigake designation system, creating parallel development tracks for Asia-Pacific market entry. Stakeholders must monitor evolving biomarker qualification standards and payer evidence requirements that will determine which drug classes secure sustainable formulary placement.
Market Dynamics
The FDA's accelerated approval pathways for rare disease therapeutics are compressing development timelines and reshaping how pharmaceutical firms sequence clinical trials across diabetic, idiopathic, and post-surgical gastroparesis indications. This regulatory velocity is forcing portfolio reallocation toward biomarker-validated endpoints that satisfy both the FDA and EMA simultaneously.
Growth Catalysts
- Orphan Drug Designation:The FDA's framework grants market exclusivity and tax incentives for novel gastroparesis therapeutics, accelerating investment into refractory patient populations with limited treatment options.
- Hospital Formulary Expansion:Specialized gastroenterology centers in the United States and Germany are broadening prokinetic therapy protocols to reduce readmission rates among diabetic gastroparesis patients.
- Biomarker Qualification:Validated gastric emptying scintigraphy endpoints are streamlining Phase III trial designs and enabling earlier go/no-go decisions for motilin receptor agonist programs.
Market Restraints
- Reimbursement Code Fragmentation:Inconsistent CPT and HCPCS coverage across US commercial payers creates prior authorization bottlenecks that delay therapy initiation for oral prokinetic agents.
- Active Pharmaceutical Ingredient Concentration:Synthesis of 5-HT4 agonist compounds depends on a limited supplier base concentrated in Switzerland and India, exposing manufacturers to single-source disruption risk.
- Placebo Response Variability:High spontaneous symptom fluctuation in idiopathic gastroparesis trials inflates required sample sizes and extends study duration beyond typical gastrointestinal drug development timelines.
Strategic Opportunities
- Japan's Sakigake Pathway:The PMDA's priority review system for gastrointestinal motility disorders enables first-in-Asia launches with condensed regulatory review periods and dedicated consultation support.
- Subcutaneous Delivery Convergence:Combination of wearable infusion devices with ghrelin receptor agonists addresses swallowing difficulties in severe gastroparesis patients who cannot tolerate oral formulations.
- Integrated Diagnostic Protocols:Partnerships between academic medical centers and device manufacturers to embed gastric emptying testing within standard endoscopy workflows are capturing undiagnosed patient pools.
Industry Challenges
- Gastric Motility Specialist Shortage:Fellowship-trained neurogastroenterologists remain concentrated at tertiary referral centers, limiting patient access to guideline-concordant care in community hospital settings.
- Legacy EHR Integration:Electronic health record systems at mid-sized health systems lack structured fields for gastroparesis severity scoring, complicating real-world evidence collection for payers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Gastroparesis Drug Market |
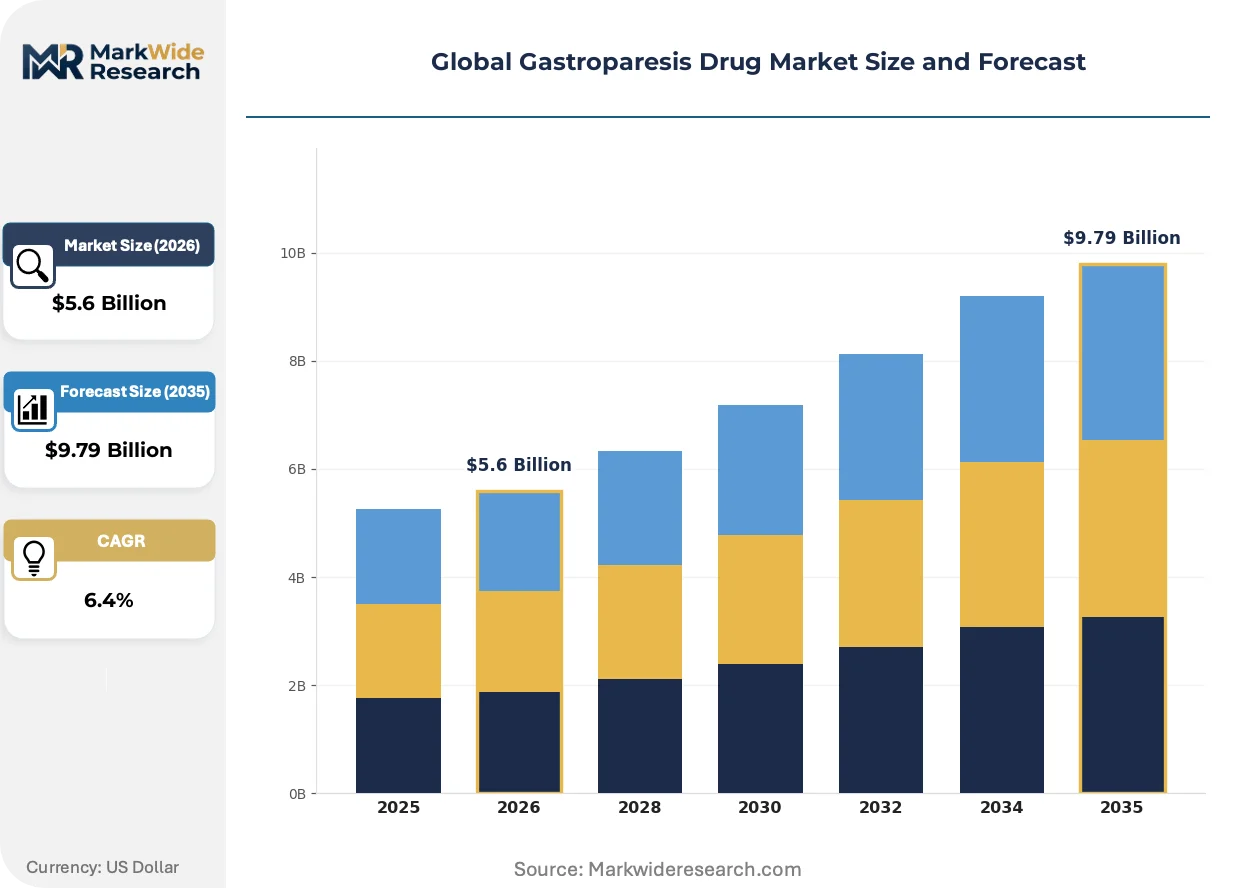
| Market Size in 2026 | $5.6 Billion |
| Market Size in 2035 | $9.79 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Class: Prokinetic Agents, Antiemetics, Motilin Receptor Agonists, Ghrelin Receptor Agonists, Anticholinergics Indication: Diabetic Gastroparesis, Idiopathic Gastroparesis, Post-Surgical Gastroparesis, Drug-Induced Gastroparesis End User: Hospitals, Specialty Clinics, Ambulatory Care Centers, Research Institutes Distribution Channel: Hospital Pharmacies, Retail Pharmacies, Online Pharmacies, Direct Sales |
| Companies Covered | Evoke Pharma, AbbVie, Neurogastrx, AstraZeneca, Takeda Pharmaceutical, CinDome Pharma, RaQualia Pharma, Vanda Pharmaceuticals, Theravance Biopharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Gastroparesis Drug Market Shifts & Advancements
Digital biomarker platforms and decentralized trial infrastructure are displacing traditional site-based gastric emptying assessment, enabling continuous physiological monitoring that captures symptom variability invisible to periodic clinic visits.
Continuous glucose monitoring integration with gastric emptying sensors is decentralizing the diagnostic pathway for diabetic gastroparesis. Endocrinology practices in the United States are adopting combined metabolic-motility monitoring protocols that identify delayed gastric transit before symptomatic progression. This convergence is compressing referral delays and shifting diagnostic volume from specialized motility laboratories to primary diabetes management settings.
The EMA's conditional marketing authorization pathway is accelerating post-approval evidence generation requirements for novel prokinetic therapies. Sponsors must now design adaptive trial structures that satisfy both initial approval and full authorization endpoints within a single protocol framework. European hospital pharmacy committees are responding by structuring formulary contracts with performance-linked rebate provisions tied to real-world gastric emptying outcomes.
Specialized gastroenterology practices are consolidating procurement decisions through group purchasing organizations that negotiate exclusive therapeutic contracts. This channel concentration is displacing traditional pharmaceutical sales representative access models in favor of centralized value-demonstration presentations to pharmacy and therapeutics committees. The United States exhibits the most pronounced consolidation, with regional health systems in Texas and Florida leading the shift toward standardized therapeutic protocols across affiliated ambulatory centers.
Global Gastroparesis Drug Market Segmentation
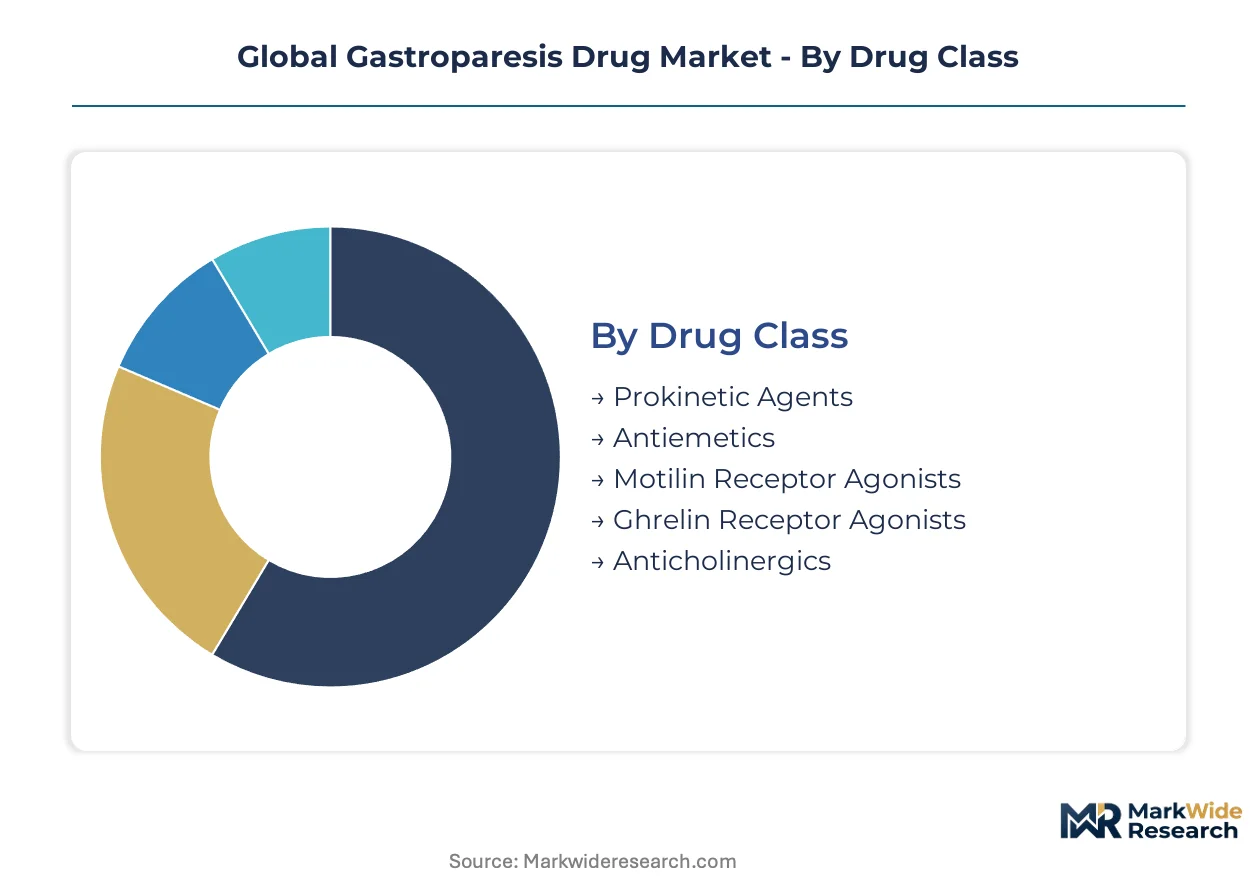
Segmentation in gastroparesis therapeutics reveals distinct regulatory pathways, reimbursement profiles, and prescriber behaviors across drug classes and care settings. Understanding these divisions enables targeted portfolio allocation and market access strategies.
Drug Class:
Prokinetic agents and ghrelin receptor agonists carry the heaviest certification burden, requiring FDA-validated gastric emptying endpoints and EMA biomarker qualification, while antiemetics navigate abbreviated pathways due to established safety databases.
- Prokinetic Agents:Dopamine receptor antagonists and serotonin 5-HT4 agonists that accelerate gastric emptying through neural pathway modulation. Hospital formularies in the United States and Germany prioritize these agents for diabetic gastroparesis protocols to reduce readmission rates.
- Ghrelin Receptor Agonists:Novel compounds stimulating growth hormone secretagogue receptors to enhance gastric motility in refractory cases. Subcutaneous delivery formats are gaining traction among severe gastroparesis patients who cannot tolerate oral medications.
- Motilin Receptor Agonists:Macrolide-derived compounds activating the motilin receptor to induce phase III migrating motor complexes.
- Antiemetics:Established agents targeting nausea and vomiting symptoms without direct prokinetic action.
- Anticholinergics:Muscarinic receptor antagonists used adjunctively to manage cramping and pain symptoms.
Prokinetic agents sit at the top of the volume ranking, with ghrelin receptor agonists climbing the fastest.
Indication:
Diabetic gastroparesis commands premium pricing due to clear etiology and established reimbursement codes, whereas idiopathic cases face diagnostic ambiguity that complicates payer negotiations.
- Diabetic Gastroparesis:Gastroparesis secondary to autonomic neuropathy in diabetes mellitus, characterized by measurable gastric emptying delay. Endocrinology practices in the United States are adopting combined metabolic-motility monitoring that compresses referral delays and expands the addressable patient pool.
- Idiopathic Gastroparesis:Gastroparesis without identifiable underlying cause, representing substantial unmet need due to diagnostic complexity. High placebo response variability in clinical trials inflates required sample sizes and extends study duration.
- Post-Surgical Gastroparesis:Delayed gastric emptying following bariatric or other upper gastrointestinal procedures.
- Drug-Induced Gastroparesis:Gastroparesis resulting from pharmacological agents such as opioids or anticholinergics.
Diabetic gastroparesis generates the highest prescription volumes, with idiopathic gastroparesis showing the steepest expansion trajectory as diagnostic protocols improve.
End User:
Procurement authority concentrates at hospital pharmacy committees for intravenous prokinetics, while specialty clinics retain autonomy for oral outpatient regimens.
- Hospitals:Tertiary care centers with specialized gastroenterology infrastructure managing acute exacerbations and parenteral nutrition support. Texas and Florida health systems are consolidating procurement through group purchasing organizations that displace traditional sales representative access models.
- Specialty Clinics:Dedicated neurogastroenterology practices offering comprehensive motility testing and long-term disease management.
- Ambulatory Care Centers:Outpatient facilities providing infusion services and chronic disease monitoring.
- Research Institutes:Academic medical centers conducting clinical trials and biomarker validation studies.
Hospitals dominate absolute prescription volume, with specialty clinics gaining share fastest as diagnostic referral networks mature.
Distribution Channel:
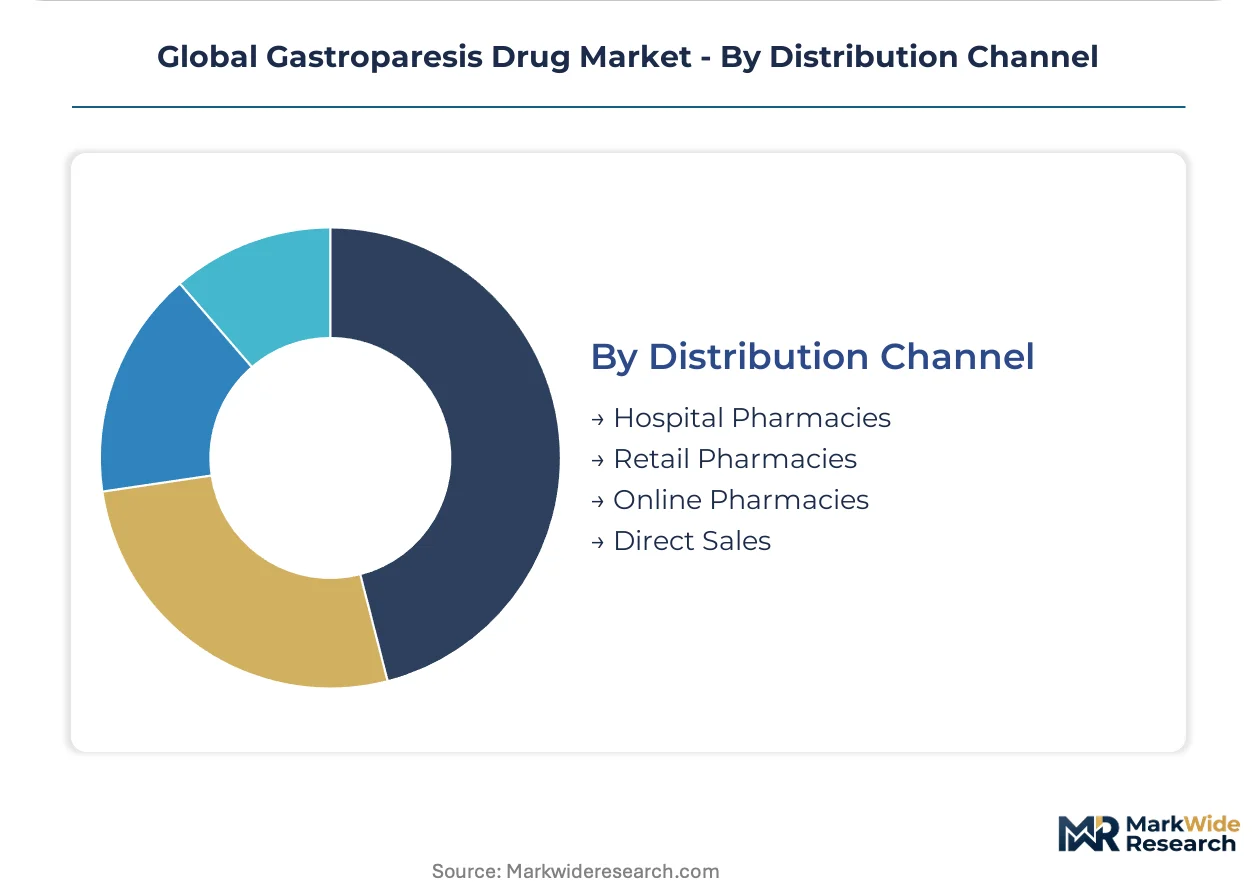
Channel selection correlates with therapy urgency and reimbursement complexity, with hospital pharmacies capturing acute inpatient starts and retail channels handling maintenance oral therapies.
- Hospital Pharmacies:Institutional dispensaries managing formulary-controlled inpatient and emergency department prescribing. European hospital pharmacy committees are structuring contracts with performance-linked rebate provisions tied to real-world gastric emptying outcomes.
- Retail Pharmacies:Community-based dispensaries handling outpatient prescription fulfillment for oral prokinetic agents.
- Online Pharmacies:Digital platforms offering direct-to-patient delivery for chronic maintenance therapies.
- Direct Sales:Manufacturer-controlled distribution for specialty biologics and limited-distribution drugs.
Hospital pharmacies lead by prescription volume, with online pharmacies expanding most quickly as patient support programs digitize medication access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping clinical trial placement as sponsors migrate studies toward jurisdictions with streamlined rare-disease pathways and favorable reimbursement climates.
United States
Hospital formulary expansion at tertiary gastroenterology centers in Texas and Florida drives prokinetic adoption for diabetic gastroparesis protocols. The FDA's orphan drug designation framework grants market exclusivity and tax incentives that accelerate investment into refractory patient populations. The Greater Boston cluster anchors biomarker validation research through academic medical center partnerships with device manufacturers.
Germany
Specialized neurogastroenterology infrastructure supports advanced therapy access and performance-linked rebate contracting for hospital pharmacy committees. The EMA's conditional marketing authorization pathway compresses post-approval evidence generation timelines for novel prokinetic therapies. The North Rhine-Westphalia region concentrates Phase III trial sites that satisfy both FDA and EMA endpoint requirements simultaneously.
Japan
Endocrinology practices adopting combined metabolic-motility monitoring expand the addressable diabetic gastroparesis pool through earlier diagnostic capture. The PMDA's Sakigake designation system accelerates review timelines for gastrointestinal motility disorders with dedicated consultation support. The Kanto region surrounding Tokyo hosts the highest density of gastric motility specialists and decentralized trial infrastructure.
Switzerland
Active pharmaceutical ingredient synthesis for 5-HT4 agonist compounds concentrates manufacturing investment despite single-source disruption exposure. Swissmedic maintains alignment with EMA qualification standards while offering specialized consultation for rare disease therapeutics. The Basel pharmaceutical cluster houses contract manufacturers supplying prokinetic programs across European and North American markets.
India
Growing diagnostic protocol standardization at metropolitan gastroenterology centers creates downstream demand for oral prokinetic agents in idiopathic cases. The CDSCO's accelerated approval pathways for orphan indications are adapting toward biomarker-validated endpoints similar to FDA and EMA frameworks. The Maharashtra-Gujarat pharmaceutical manufacturing corridor supplies generic active pharmaceutical ingredients to global prokinetic developers.
Global Gastroparesis Drug Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated pharmaceutical firms controlling hospital formulary access while biotechnology developers capture specialty clinic prescribing through direct-to-specialist engagement. Market structure tilts toward consolidation at the commercialization tier, where extensive distribution infrastructure and payer contracting capabilities determine volume capture. Three archetypes dominate: large-cap diversified pharmaceutials with hospital pharmacy committee relationships, mid-cap biotech specialists with orphan disease focus, and emerging developers with novel mechanism assets. Competitive intensity centers on M&A activity targeting Phase II-ready ghrelin receptor agonist programs and strategic partnerships embedding gastric emptying diagnostics within endoscopy workflows.
Within the large-cap pharmaceutical tier, Takeda Pharmaceutical and AbbVie occupy positions defined by hospital formulary scale and integrated diagnostic-to-treatment protocol development. Evoke Pharma exemplifies the mid-cap biotech specialist archetype through direct-to-specialist marketing models that sustain prescriber loyalty in neurogastroenterology practices. These three firms collectively represent the competitive frontier where regulatory pathway expertise and reimbursement navigation capabilities determine market access velocity.
| Leading Market Players |
|---|
| Evoke Pharma |
| AbbVie |
| Neurogastrx |
| AstraZeneca |
| Takeda Pharmaceutical |
| CinDome Pharma |
| RaQualia Pharma |
| Vanda Pharmaceuticals |
| Theravance Biopharma |
| Others |
Supply & Pricing Matrix
Specialized 5-HT4 agonist precursor costs cascade through Swiss and Indian manufacturing nodes into three-tier pricing structures across premium, standard, and economy levels, with hospital pharmacy committees extracting performance-linked rebates that compress margins at the contract tier while leaving list prices intact for cash-pay specialty clinic segments.
Pricing Analysis
Hospital distributor margin layers absorb the steepest compression as group purchasing organizations in Texas and Florida consolidate procurement authority. Pricing stratifies across premium, standard, and economy tiers based on FDA orphan drug designation status and gastric emptying scintigraphy certification grade. Cost compression in the standard tier intensifies because Indian API suppliers face regulatory inspection backlogs. Academic medical centers exhibit the lowest price sensitivity due to research funding offsets, while community hospitals in mid-sized US health systems negotiate most aggressively.
Supply Chain Analysis
Regional distribution centers in Basel, Mumbai, and Research Triangle Park anchor hub-and-spoke patterns that feed hospital pharmacies and specialty clinics. Active pharmaceutical ingredient synthesis concentrates in Switzerland and India, with formulation finishing split between North American and European contract manufacturers. Supply chain risk centers on single-source vulnerability for motilin receptor agonist precursors. Distribution runs through manufacturer-controlled direct sales for parenteral ghrelin receptor agonists and wholesale distributors for oral prokinetic agents.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The gastroparesis drug market compounds steadily as diabetic population growth sustains addressable patient pool expansion regardless of cyclical pharmaceutical investment cycles.
For Market Incumbents: To counter emerging biotech developers with novel ghrelin receptor mechanisms, Takeda Pharmaceutical and AbbVie should deepen backward integration into API manufacturing to secure 5-HT4 agonist supply continuity, while embedding gastric emptying diagnostics within endoscopy workflows to capture undiagnosed idiopathic cases before competitors reach prescribing specialists. For New Entrants and Emerging Players: Wearable infusion device compatibility offers the most penetrable wedge for subcutaneous ghrelin receptor agonists targeting severe gastroparesis patients who cannot tolerate oral formulations. Japan's Sakigake pathway provides the fastest regulatory validation for first-in-Asia positioning. Direct-to-specialist marketing through neurogastroenterology practice networks bypasses consolidated hospital pharmacy gatekeepers. For Investors and Strategic Acquirers: Asymmetric upside sits with Phase II-ready ghrelin receptor agonist programs with validated biomarker endpoints. Five-to-ten-year viability hinges on securing sustainable formulary placement through performance-linked contracting structures. Watch for FDA biomarker qualification decisions as the inflection signal that separates mechanistically novel assets from incremental prokinetic improvements.| Strategic Initiative | Industry Significance |
|---|---|
| Biomarker-Validated Endpoint Development | FDA qualification of gastric emptying scintigraphy standards accelerates Phase III trial designs for motilin receptor agonists. |
| Hospital Formulary Contracting | Performance-linked rebate provisions tied to real-world outcomes secure sustainable placement against generic substitution pressure. |
| Subcutaneous Delivery Platform Partnership | Wearable infusion device integration addresses swallowing difficulties in severe gastroparesis populations. |
| Integrated Diagnostic Protocol Embedding | Academic medical center partnerships with device manufacturers capture undiagnosed idiopathic patient pools. |
| Orphan Drug Designation Pathway Navigation | EMA conditional marketing authorization and FDA accelerated approval frameworks compress commercialization timelines. |
Research Methodology
Bottom-up hospital and specialty clinic prescribing volume modeling reconciled against top-down API production and finished dose tracking forms the analytical core of this study. Primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists combined with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Triangulation between demand-side prescription analytics and supply-side manufacturing capacity assessments ensures cross-verified volume estimates.
Historical trendline analysis of prokinetic agent adoption rates across diabetic, idiopathic, and post-surgical indication segments established baseline growth patterns. The projection framework models drug class, indication, end user, and distribution channel dimensions across the analysis window. CAGRs derive from segmented patient population forecasts, reimbursement code expansion trajectories, and regulatory pathway velocity assumptions. Forecast inputs include biomarker qualification timelines, hospital formulary contract renewal cycles, and specialist workforce growth projections.
The model holds under stable regulatory endorsement of gastric emptying scintigraphy endpoints; deviation in FDA biomarker qualification standards or EMA conditional authorization requirements would shift commercialization timelines and revenue recognition patterns. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Viral Conjunctivitis Pipeline Drugs Market
Pharmaceuticals
Ebola Drug and Vaccine Market
Pharmaceuticals
Malaysia Oral Anti-Diabetic Drug Market
Pharmaceuticals
Lansoprazole API Market
Pharmaceuticals
Global Vaccine Market
Pharmaceuticals
Global Antiemetics Market
Pharmaceuticals
Telmisartan Market
Pharmaceuticals
Veterinary Insulin Drugs Market
Pharmaceuticals
Antiplatelet Market
Pharmaceuticals
Anticancer Drugs Market
Pharmaceuticals
Marine Derived Pharmaceuticals Market
Pharmaceuticals
Acetaminophen Market
Pharmaceuticals
United Kingdom (UK) Diabetes Drugs Market
Pharmaceuticals
Global Polio Vaccines Market
Pharmaceuticals
Latin America Generic Injectables Market
Pharmaceuticals
Italy Pharmaceutical Market