
 Asia-Pacific Alpha-Glucosidase Inhibitors Market | 2026-2036
Asia-Pacific Alpha-Glucosidase Inhibitors Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Alpha-Glucosidase Inhibitors Market Outlook
Aftermarket patient support and medication adherence programs is rewriting how pharmaceutical firms capture recurring value in the Asia-Pacific diabetes care ecosystem. Takeda Pharmaceutical Company Limited leverages its established endocrinology franchise to sustain physician loyalty across Japan and Southeast Asia. Sun Pharmaceutical Industries Ltd. anchors its competitive position through cost-efficient acarbose manufacturing and deep distribution into India's tier-two and tier-three cities. Glenmark Pharmaceuticals Ltd. differentiates through voglibose formulations tailored to regional metabolic profiles and prescribing habits.
Alpha-glucosidase inhibitors are oral antidiabetic agents that delay carbohydrate digestion in the small intestine by competitively inhibiting alpha-glucosidase enzymes at the brush border, with acarbose derived from microbial fermentation and voglibose synthesized through stereoselective catalytic processes, primarily prescribed for postprandial glucose control in type 2 diabetes patients. Among product types, voglibose dominates Japanese and Korean prescribing patterns due to its favorable gastrointestinal tolerability profile and established reimbursement status, while acarbose maintains volume leadership across China and India where cost sensitivity shapes formulary decisions. The hospital end-user segment captures the highest-margin transactions through institutional procurement contracts, though home care channels represent the fastest-growing distribution point as chronic disease management shifts toward patient self-administration models.
Japan's Pharmaceuticals and Medical Devices Agency (PMDA) and India's Central Drugs Standard Control Organization (CDSCO) enforce bioequivalence and stability standards that determine which generic formulations gain market access, while China's National Medical Products Administration (NMPA) implements centralized procurement mechanisms that compress pricing for mature molecules. Australia's Therapeutic Goods Administration (TGA) and South Korea's Ministry of Food and Drug Safety (MFDS) maintain pharmacovigilance frameworks that shape post-market surveillance obligations for manufacturers operating across the region. Stakeholders must monitor how biosimilar competition and evolving national essential medicine lists will reshape portfolio prioritization decisions for alpha-glucosidase inhibitor portfolios.
Market Dynamics
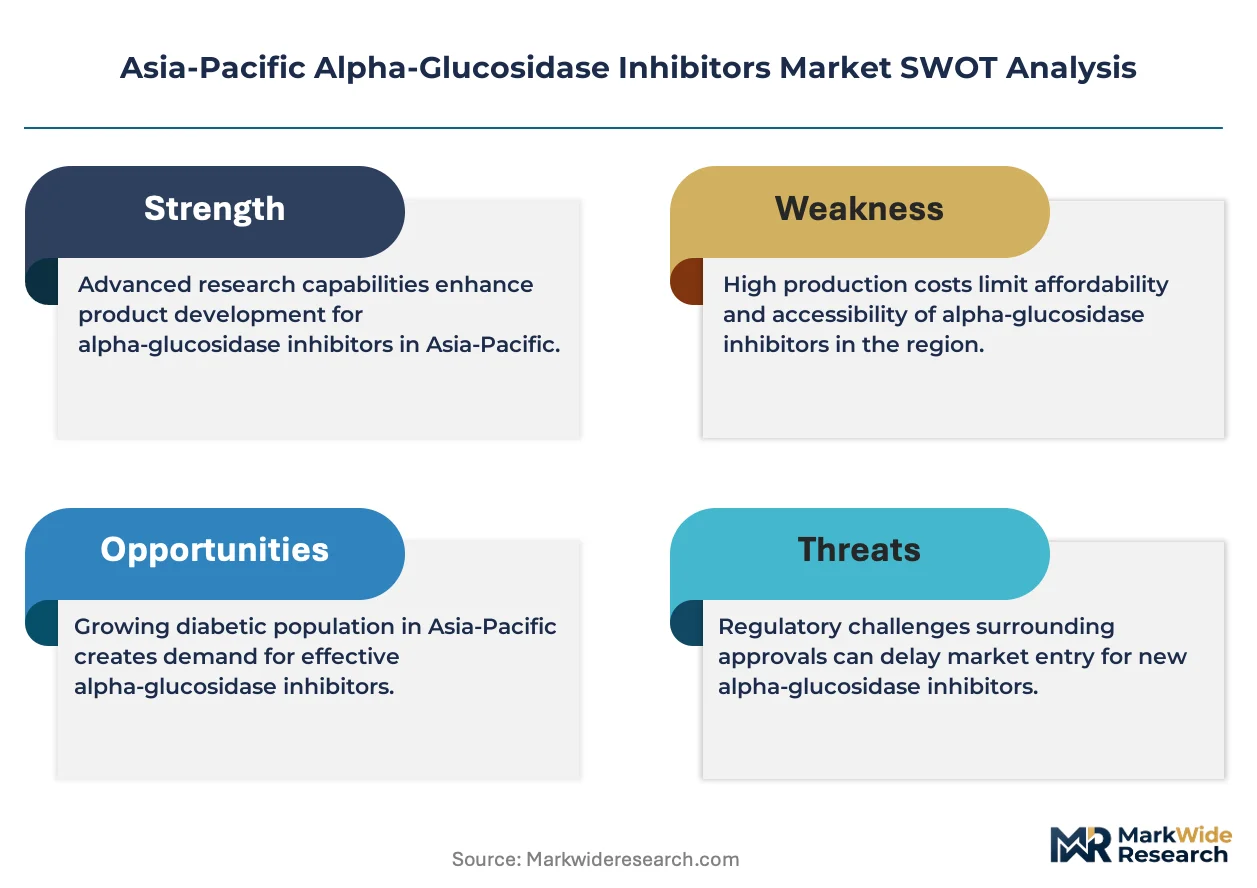
Centralized procurement mechanisms at China's NMPA are compressing margins for mature alpha-glucosidase inhibitors while simultaneously expanding patient access through volume-based purchasing agreements across provincial hospital networks.
Growth Catalysts
- National Reimbursement Expansion:India's Ayushman Bharat scheme extends coverage for oral antidiabetic therapies into tier-two and tier-three cities, broadening the addressable patient base beyond metropolitan specialist centers.
- Postprandial Glucose Monitoring Integration:Continuous glucose monitoring systems are hybridizing with alpha-glucosidase inhibitor prescriptions in Japanese endocrinology practices, creating protocol-driven demand for brush-border enzyme inhibitors.
- Specialist Infrastructure Buildout:Western Indian states Maharashtra and Gujarat are constructing dedicated diabetes management wings within district hospitals, embedding voglibose and acarbose into standard care pathways.
Market Restraints
- Fermentation Input Volatility:Acarbose production depends on microbial fermentation substrates whose agricultural supply chains face climate-induced yield fluctuations across Southeast Asian sourcing regions.
- Generic Concentration Risk:China's NMPA centralized procurement has collapsed pricing for acarbose to sub-manufacturing-cost levels for non-vertically integrated producers, eliminating marginal competitors.
- Gastrointestinal Tolerability Ceiling:Flatulence and diarrhea incidence rates limit alpha-glucosidase inhibitor adherence compared to DPP-4 inhibitors and SGLT2 inhibitors in Korean prescribing guidelines.
Strategic Opportunities
- Home Care Channel Penetration:Australia's community pharmacy network is developing chronic disease management accreditation programs that position pharmacists to initiate and monitor alpha-glucosidase inhibitor therapy outside hospital settings.
- Fixed-Dose Combination Formulations:Regulatory pathways at Japan's PMDA for voglibose-metformin combinations offer patent-protected positioning distinct from commoditized monotherapy markets.
- Indonesia's Universal Health Coverage:Jaminan Kesehatan Nasional expansion into rural Java and Sumatra creates reimbursement infrastructure previously absent for oral antidiabetic portfolios.
Industry Challenges
- Bioequivalence Study Bottlenecks:CDSCO's tightened stability requirements for voglibose generics have extended approval timelines to 24-36 months, freezing pipeline products in regulatory limbo.
- Cold Chain Reconfiguration Costs:Temperature-sensitive fermentation-derived acarbose requires refrigerated distribution infrastructure that India's fragmented last-mile networks struggle to maintain consistently.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Alpha-Glucosidase Inhibitors Market |
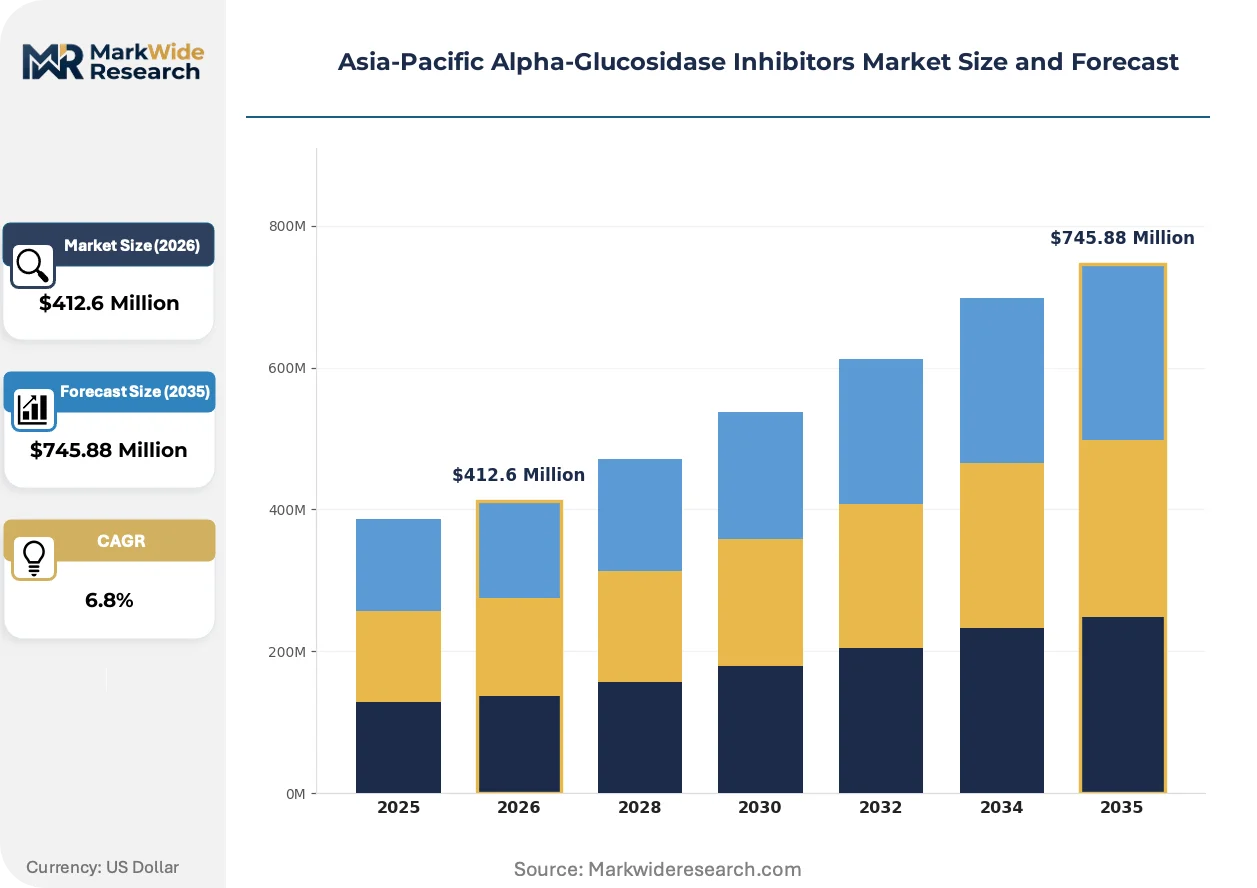
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $745.88 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acarbose, Miglitol, Voglibose, Others End User: Clinics, Hospitals, Home Care, Pharmacies Distribution Channel: Retail, Online, Wholesalers, Distributors Application: Type 2 Diabetes, Pre-Diabetes, Weight Management, Others |
| Companies Covered | Bayer AG, Takeda Pharmaceutical Company Limited, Sun Pharmaceutical Industries Ltd., Glenmark Pharmaceuticals Ltd., Pfizer Inc., Astellas Pharma Inc., Merck & Co., Sanofi, Novartis AG, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Alpha-Glucosidase Inhibitors Market Strategic Shifts
Digital therapeutics and connected care platforms are embedding alpha-glucosidase inhibitor adherence into broader metabolic management ecosystems, shifting value capture from molecule sales to integrated disease management outcomes.
Extended-release voglibose formulations are hybridizing conventional brush-border enzyme inhibition with modified-release polymer matrices that flatten postprandial glucose curves over six-hour windows. Japanese diabetology clinics are adopting these formulations for elderly patients with erratic meal timing. This technology is hybridizing competitive positioning away from pure cost competition toward adherence-driven clinical differentiation.
China's NMPA Volume-Based Procurement policy mandates 50-70% price reductions for listed molecules in exchange for guaranteed hospital purchase volumes across provincial consortiums. Domestic manufacturers with captive fermentation capacity absorb margin compression through backward integration into raw material production. Multinational suppliers without upstream manufacturing presence are exiting the acarbose category entirely.
Patient self-administration models are displacing hospital-centric dispensing for stable type 2 diabetes cases across South Korea's Health Insurance Review and Assessment Service reimbursement tiers. Community pharmacies in Seoul and Busan are capturing prescription transfers through medication therapy management certifications. This channel rotation concentrates in urban corridors where specialist density previously mandated institutional care settings.
Asia-Pacific Alpha-Glucosidase Inhibitors Market Segmentation
Alpha-glucosidase inhibitor portfolios require granular segmentation to capture divergent prescribing economics across Asia-Pacific reimbursement environments. Product chemistry, institutional setting, and disease staging each create distinct margin profiles and access barriers.
Product Type:
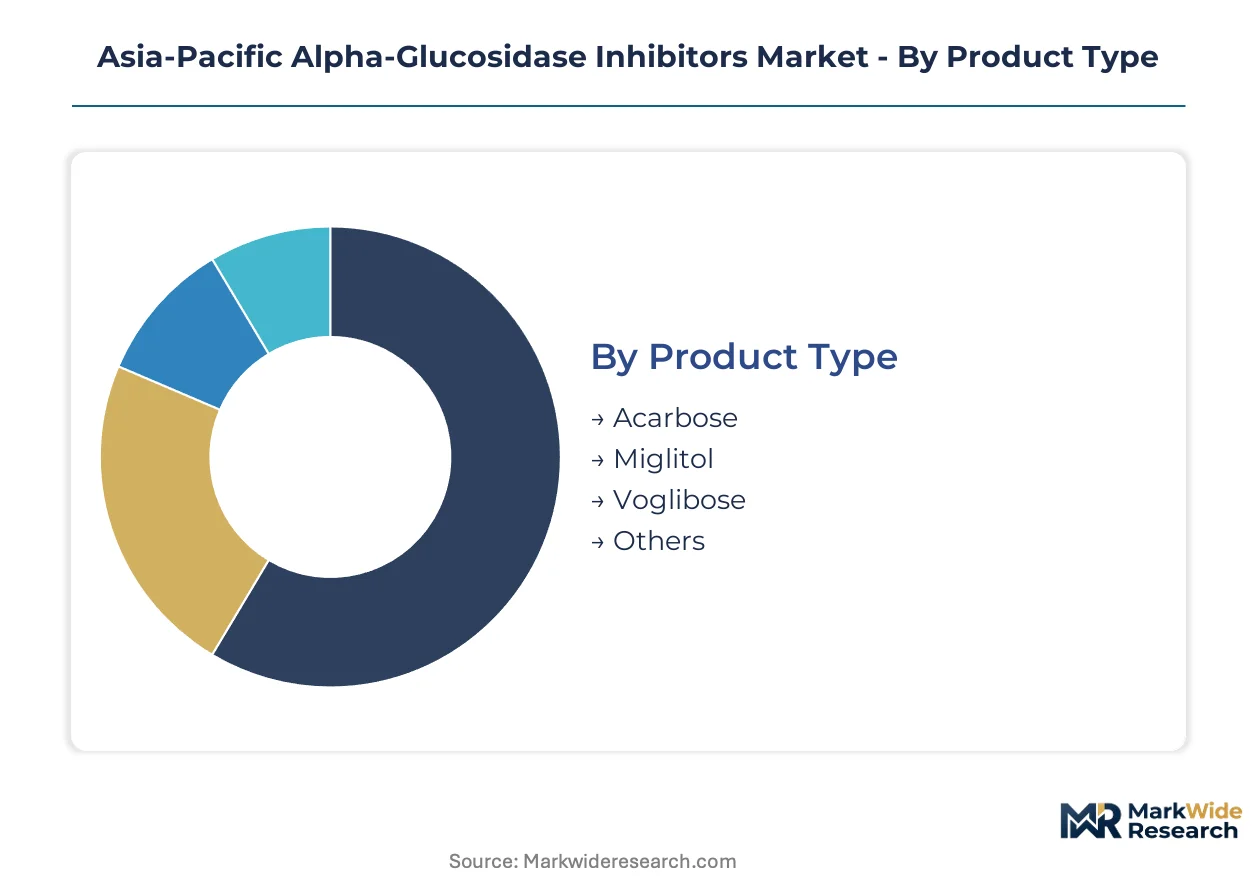
Mature fermentation-derived molecules dominate volume while synthetic alternatives command premium positioning in selective markets.
- Acarbose:Microbial fermentation yields this pseudotetrasaccharide that competitively inhibits pancreatic alpha-amylase and intestinal alpha-glucosidases. China's NMPA centralized procurement has collapsed pricing to manufacturing-floor levels, eliminating non-integrated suppliers.
- Voglibose:Stereoselective catalytic synthesis produces this aminocyclitol with superior gastrointestinal tolerability. Japanese and Korean formularies favor voglibose for elderly populations where flatulence-driven discontinuation threatens adherence.
- Miglitol:Absorbed systemically unlike brush-border-restricted alternatives, this desoxynojirimycin derivative offers broader glucosidase inhibition. Limited Asia-Pacific penetration reflects patent expiry timing and generic concentration in Western markets.
- Others:Emerging enzymatic inhibitors and botanical derivatives occupy preclinical and early clinical pipelines. Australia's TGA has granted orphan designation to one experimental compound for rare glycogen storage disorders.
Acarbose retains volume leadership; voglibose holds the steepest expansion curve.
End User:
Institutional procurement contracts anchor revenue stability while ambulatory channels capture patient lifetime value.
- Hospitals:Tertiary endocrinology centers in Shanghai, Tokyo, and Mumbai execute high-volume purchasing agreements. India's western states are embedding diabetes management wings within district hospitals, standardizing acarbose and voglibose in discharge protocols.
- Home Care:Self-administration models for stable type 2 diabetes displace institutional dispensing. South Korea's HIRA reimbursement tiers now permit community pharmacy initiation without specialist referral in Seoul and Busan corridors.
- Clinics:Specialist endocrinology practices in China's tier-one cities integrate continuous glucose monitoring with alpha-glucosidase inhibitor titration. These settings capture newly diagnosed cases before therapeutic switching to newer drug classes.
- Pharmacies:Australia's community pharmacy accreditation programs for chronic disease management enable pharmacist-led therapy initiation. This channel expansion depends on therapeutic guidelines recognizing non-physician prescribing authority.
Hospitals retain volume leadership; home care holds the steepest expansion curve.
Distribution Channel:
Cold chain requirements and reimbursement verification systems shape channel economics and geographic reach.
- Retail:Brick-and-mortar pharmacies dominate chronic prescription refill capture. India's fragmented retail network struggles with temperature-controlled storage for fermentation-derived acarbose.
- Wholesalers:Provincial consortia in China aggregate hospital demand for NMPA volume-based procurement. Backward-integrated domestic manufacturers bypass wholesale markups through direct institutional contracts.
- Distributors:Specialized diabetes care distributors serve clinic and home care segments with patient education bundling. Japan's PMDA pharmacovigilance requirements impose traceability obligations on distribution partners.
- Online:Telemedicine-integrated pharmacies capture prescription transfers from hospital discharges. Regulatory frameworks at India's CDSCO and South Korea's MFDS are tightening online controlled-substance dispensing rules.
Retail retains volume leadership; online holds the steepest expansion curve.
Application:
Disease severity and comorbidity profiles determine dosing intensity and combination therapy eligibility.
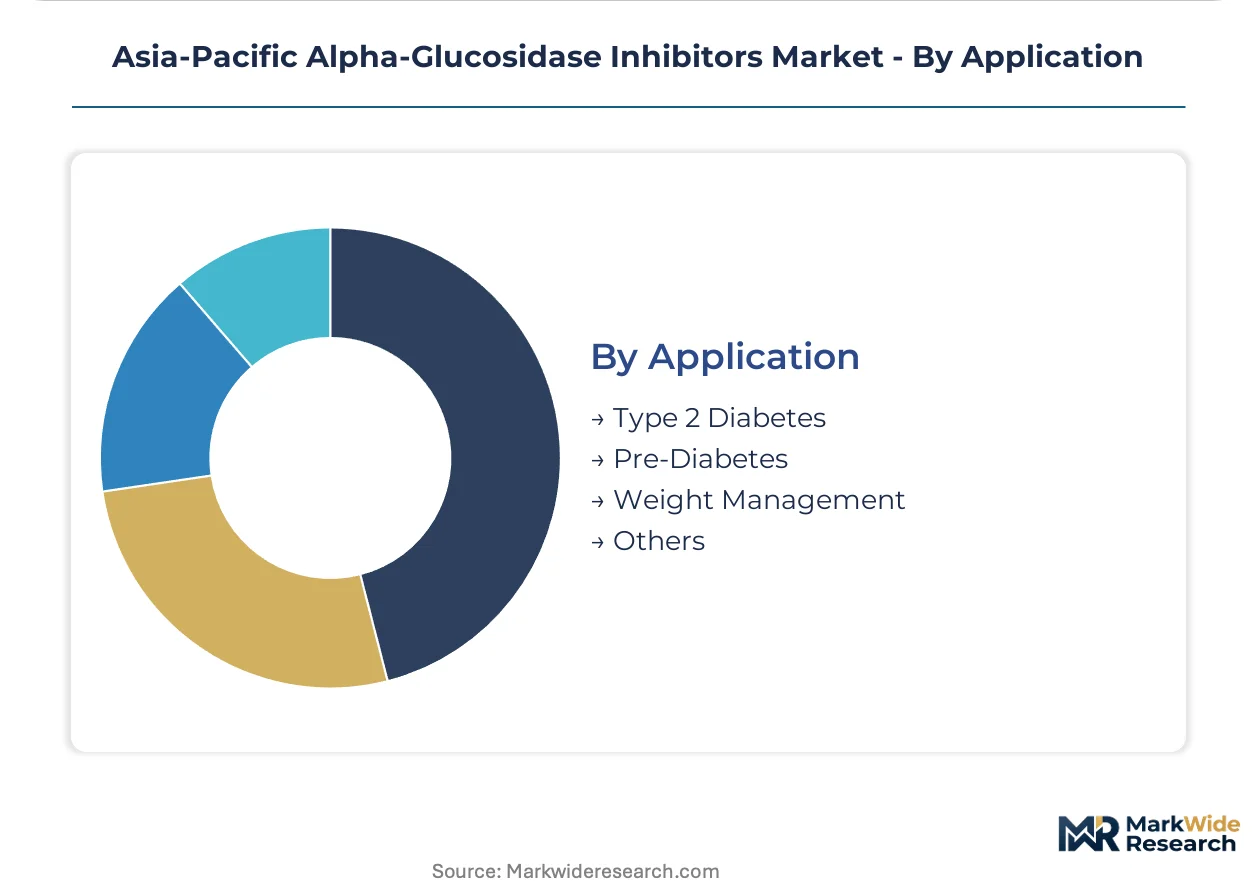
- Type 2 Diabetes:Established indication for postprandial glucose control in patients inadequately controlled on diet and exercise alone. Prescribing concentrates in patients with preserved beta-cell function where mealtime glucose spikes dominate metabolic dysfunction.
- Pre-Diabetes:Pharmacologic intervention for impaired glucose tolerance remains off-label in most Asia-Pacific markets. Japan's diabetology societies have issued consensus guidelines supporting voglibose for high-risk pre-diabetic cohorts.
- Weight Management:Carbohydrate malabsorption effects produce modest weight reduction. Limited formulary inclusion reflects superior efficacy of GLP-1 receptor agonists for obesity indications.
- Others:Experimental applications include polycystic ovary syndrome and reactive hypoglycemia prevention. Australia's TGA has not approved any alpha-glucosidase inhibitor for non-diabetes indications.
Type 2 diabetes retains volume leadership; pre-diabetes holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China and India drive acarbose consumption through cost-sensitive hospital procurement, while Japan and South Korea favor voglibose for elderly populations with lower gastrointestinal tolerance thresholds. This consumption-mix differential creates distinct margin architectures across the region.
China
Provincial hospital networks execute volume-based purchasing agreements through NMPA centralized procurement, collapsing acarbose pricing to manufacturing-floor levels. Domestic manufacturers with captive fermentation capacity absorb margin compression through backward integration into raw material production. Yangtze River Delta clusters around Shanghai and Hangzhou concentrate vertically integrated production facilities serving eastern provincial consortia.
India
Ayushman Bharat reimbursement expansion drives oral antidiabetic adoption into tier-two and tier-three cities beyond metropolitan specialist centers. CDSCO enforces tightened stability requirements for voglibose generics, extending approval timelines to 24-36 months. Western states Maharashtra and Gujarat embed diabetes management wings within district hospitals, standardizing acarbose and voglibose in discharge protocols.
Japan
Elderly populations with erratic meal timing drive demand for extended-release voglibose formulations that flatten postprandial glucose curves over six-hour windows. PMDA maintains pharmacovigilance frameworks shaping post-market surveillance obligations for manufacturers. Kanto region diabetology clinics in Tokyo and Yokohama integrate continuous glucose monitoring with alpha-glucosidase inhibitor titration protocols.
South Korea
Health Insurance Review and Assessment Service reimbursement tiers now permit community pharmacy initiation without specialist referral for stable type 2 diabetes cases. MFDS pharmacovigilance requirements impose traceability obligations on distribution partners. Seoul and Busan urban corridors capture prescription transfers through medication therapy management certifications as self-administration models displace hospital-centric dispensing.
Australia
Community pharmacy networks develop chronic disease management accreditation programs positioning pharmacists to initiate and monitor alpha-glucosidase inhibitor therapy outside hospital settings. TGA maintains pharmacovigilance frameworks distinct from hospital procurement systems. New South Wales and Victoria concentrate specialist endocrinology infrastructure supporting patient access to brush-border enzyme inhibitors.
Asia-Pacific Alpha-Glucosidase Inhibitors Market Competitive Environment
Capability concentration sits with fermentation-integrated domestic manufacturers; scale advantage sits with multinational pharmaceutical conglomerates with established endocrinology franchises. The market structures around three tiers: vertically integrated Chinese producers absorbing NMPA price compression, Indian generic specialists penetrating tier-two and tier-three distribution, and Japanese-Korean innovators commanding premium positioning through tolerability differentiation. Dominant competitive moves include backward integration into raw material production and fixed-dose combination formulation development for patent-protected positioning.
Within the multinational tier, Takeda Pharmaceutical Company Limited and Bayer AG occupy positions anchored by established endocrinology franchises across Japan and Southeast Asia. Among Indian generic specialists, Sun Pharmaceutical Industries Ltd. and Glenmark Pharmaceuticals Ltd. exemplify cost-efficient manufacturing and deep distribution penetration. These named entities represent strategic archetypes rather than exhaustive market coverage, with competitive dynamics further shaped by domestic Chinese manufacturers with captive fermentation capacity and Korean innovators pursuing extended-release formulation differentiation.
| Leading Market Players |
|---|
| Bayer AG |
| Takeda Pharmaceutical Company Limited |
| Sun Pharmaceutical Industries Ltd. |
| Glenmark Pharmaceuticals Ltd. |
| Pfizer Inc. |
| Astellas Pharma Inc. |
| Merck & Co. |
| Sanofi |
| Novartis AG |
| Others |
Value Chain & Pricing Dynamics
The Shanghai-Yokohama pharmaceutical freight corridor carries temperature-sensitive fermentation-derived acarbose across the East China Sea, with per-unit logistics costs creating pricing power concentration among manufacturers with captive cold storage infrastructure while fragmenting margins for distributors lacking refrigerated last-mile networks in India's tier-three cities.
Pricing Analysis
Long-term offtake contracts dominate hospital procurement across China's NMPA provincial consortia, locking in volume guarantees at 50-70% below list price for vertically integrated domestic manufacturers. Spot purchasing persists in India's fragmented retail pharmacy tier where acarbose price sensitivity peaks among uninsured patients. Premium voglibose formulations in Japan and South Korea command brand premiums through PMDA and MFDS bioequivalence certifications. Cost compression in China's acarbose segment is intensifying because NMPA centralized procurement has collapsed pricing to manufacturing-floor levels.
Supply Chain Analysis
Tariff exposure between China and India dominates pharmaceutical API trade flows, with CDSCO's tightened stability requirements creating regulatory friction for cross-border voglibose shipments. Manufacturing concentrates in China's Yangtze River Delta fermentation clusters, India's western states, and Japan's Kanto pharmaceutical corridor. Raw material dependencies include microbial fermentation substrates from Southeast Asian agricultural regions, stereoselective catalytic precursors from South Korean chemical plants, and modified-release polymer matrices from Japanese specialty chemical producers. Single-source vulnerability runs through China's captive fermentation capacity for acarbose. Distribution runs through hospital procurement consortia in China, community pharmacy networks in Australia, and medication therapy management certified channels in South Korea.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aftermarket patient support and medication adherence programs expand faster than molecule sales across the Asia-Pacific diabetes care ecosystem, with pharmaceutical service-attach revenue outpacing pure prescription growth as chronic disease management shifts toward integrated outcomes models.
For Market Incumbents: Pre-empt generic substitution in Japan and South Korea by accelerating fixed-dose combination filings at PMDA and MFDS before voglibose patent cliffs. Backward integration into fermentation substrate production secures margin absorption capacity against NMPA procurement compression. Channel control through direct hospital contracts in China's tier-one cities limits distributor disintermediation. For New Entrants and Emerging Players: Pursue Australia's community pharmacy chronic disease management accreditation pathway, where pharmacist-led therapy initiation remains underpenetrated relative to hospital-centric models. Indonesia's Jaminan Kesehatan Nasional rural expansion offers the most penetrable geography for oral antidiabetic portfolios lacking established reimbursement infrastructure. A go-to-market angle bundling continuous glucose monitoring integration with alpha-glucosidase inhibitor adherence programs differentiates against commoditized monotherapy positioning. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational pharmaceutical parents divesting mature oral antidiabetic franchises without upstream fermentation assets. Long-term viability over a multi-year window favors manufacturers with captive raw material production and extended-release formulation capabilities. The signal to watch is NMPA centralized procurement expansion into voglibose categories, which would replicate acarbose margin collapse dynamics.| Strategic Initiative | Industry Significance |
|---|---|
| Fixed-Dose Combination Development | PMDA pathways for voglibose-metformin combinations create patent-protected positioning distinct from commoditized monotherapy markets. |
| Backward Integration into Fermentation | Captive substrate production absorbs NMPA price compression that eliminates non-vertically integrated acarbose suppliers. |
| Community Pharmacy Accreditation | Australia's chronic disease management programs position pharmacists to initiate therapy outside hospital settings. |
| Extended-Release Formulation Investment | Modified-release voglibose polymer matrices command premium positioning for elderly patients with erratic meal timing. |
| Indonesia Universal Health Coverage Expansion | Jaminan Kesehatan Nasional rural penetration creates reimbursement infrastructure for oral antidiabetic portfolios. |
Study Parameters
Operator-level perspectives from drug development executives, regulatory affairs leads at CDSCO and NMPA, hospital procurement managers across provincial Chinese consortia, and payer access specialists anchored the qualitative base. Secondary validation drew from FDA Orange Book filings, PMDA approval summaries, ClinicalTrials.gov intervention records, and hospital formulary databases across Japan, South Korea, and Australia. Bottom-up prescription volume modeling and top-down therapeutic class expenditure analysis provided triangulation.
Scenario-bracketing framed the analytical approach across the analysis window, with volume and value outputs reflecting segmented modeling across product chemistry, institutional setting, disease staging, and regional regulatory cluster dimensions. CAGRs were derived from prescription volume trajectories, pricing elasticity coefficients, and reimbursement expansion schedules. Forecast inputs included NMPA centralized procurement volume commitments, Ayushman Bharat beneficiary enrollment curves, and PMDA pharmacovigilance reporting obligations.
Sensitivities concentrate around NMPA procurement expansion timing, CDSCO generic approval timeline variability, and climate-induced fermentation substrate yield fluctuations. Forecasts reflect documented assumptions on reimbursement policy continuity and regulatory pathway stability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Digital Pharmaceutical Supply Chain Management Market
Pharmaceuticals
Antidiuretic Drugs Market
Pharmaceuticals
Zimbabwe Pharmaceutical Market
Pharmaceuticals
Mexico Diabetes Drugs Market
Pharmaceuticals
Wujibaifeng Pills Market
Pharmaceuticals
Blood Market
Pharmaceuticals
Acetaminophen Injection Market
Pharmaceuticals
Long-Acting Beta-Agonists Market
Pharmaceuticals
Istradefylline API Market
Pharmaceuticals
Asia-Pacific Anesthesia Drugs Market
Pharmaceuticals
Anthelmintic Drugs Market
Pharmaceuticals
Korea Pharmaceutical Market
Pharmaceuticals
Global Raloxifene Hydrochloride Market
Pharmaceuticals
Marine Derived Pharmaceuticals Market
Pharmaceuticals
Global Rheumatoid Arthritis Therapeutics Market
Pharmaceuticals
South Korea Human Papillomavirus Vaccine Market