
 Global Psychotropic Drugs Market | 2026-2036
Global Psychotropic Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Global Psychotropic Drugs Market Foresight
Hospital pharmacy procurement is fragmenting as institutional buyers split contracts between originator long-acting injectables and biosimilar entrants. Pfizer Inc. leverages its manufacturing scale to secure multi-year supply agreements with integrated health networks. Johnson & Johnson anchors the antipsychotic long-acting injectable segment through depot formulation expertise. Eli Lilly and Company differentiates via its GLP-1 receptor investigations in neuropsychiatric applications.
Psychotropic drugs comprise centrally acting chemical entities that modulate neurotransmitter systems—primarily serotonin, dopamine, norepinephrine, and GABA pathways—through synthetic small molecules or biologic constructs, formulated for oral, parenteral, or transdermal delivery to treat diagnosed mental health conditions. Their commercial purpose centers on symptom management and functional restoration in chronic psychiatric disease. Antidepressants occupy the largest revenue pool due to broad prescribing in primary care, while antipsychotics command premium pricing through long-acting depot formulations. Stimulants represent the fastest-expanding category as adult ADHD diagnosis rates climb and digital prescribing platforms expand reach.
FDA's Risk Evaluation and Mitigation Strategies restrict distribution of certain antipsychotics and antidepressants to certified prescribers, directly shaping product access and liability exposure for manufacturers. EMA's centralized marketing authorization process under the EU Pharmaceutical Strategy tightens clinical evidence requirements for CNS agents entering European markets. China's NMPA accelerated review pathways for innovative psychotropic mechanisms are redirecting regional trial investment. Stakeholders must monitor evolving digital biomarker endpoints and decentralized trial designs that regulators in multiple jurisdictions are piloting for psychiatric drug development.
Market Dynamics
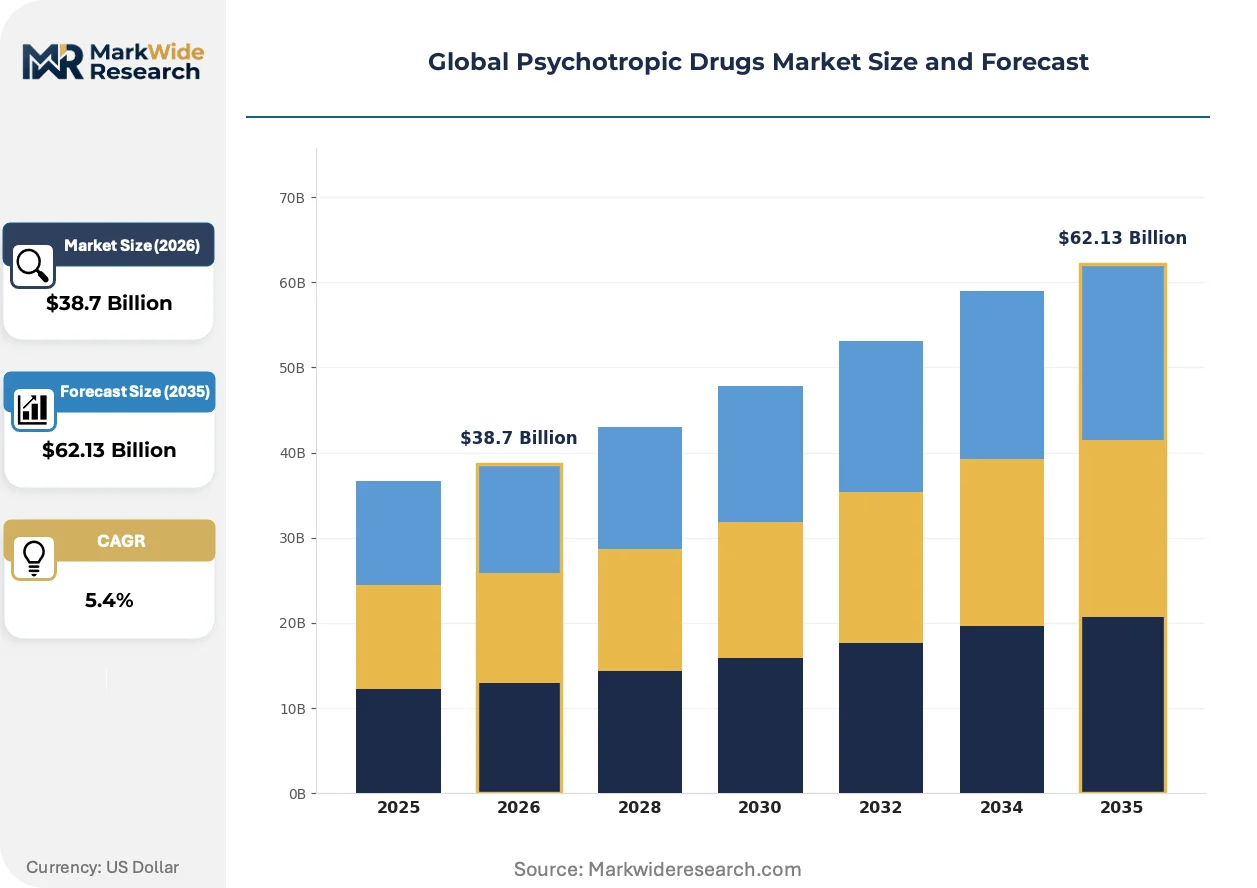
FDA's accelerated approval pathways for novel psychotropic mechanisms are compressing development timelines and forcing incumbent manufacturers to defend formulation portfolios against mechanism-of-action challengers. This regulatory velocity is redistributing competitive advantage toward biotech developers with biomarker-validated targets.
Growth Catalysts
- Long-acting injectable demand:Reimbursement frameworks in the United States and Germany favor depot formulations that reduce hospitalization rates. Psychiatric clinics are expanding formularies to capture these cost savings.
- EMA's EU Pharmaceutical Strategy:Centralized marketing authorization for CNS agents streamlines multi-country commercialization. This reduces regulatory duplication costs for developers targeting European markets.
- Adult ADHD diagnostic expansion:Digital prescribing platforms extend stimulant access beyond traditional psychiatric settings. Primary care networks now initiate therapy previously managed by specialists.
Market Restraints
- Active pharmaceutical ingredient concentration:Synthetic serotonin modulator precursors depend on Chinese and Indian bulk chemical manufacturers. Geographic supply concentration creates vulnerability to export restriction cascades.
- FDA Risk Evaluation and Mitigation Strategies:Distribution restrictions for certain antipsychotics limit prescriber pools and inflate compliance overhead. Certified prescriber networks constrain product reach in rural markets.
- Generic oral antidepressant substitution:Patent-expired SSRIs and SNRIs command pharmacy benefit manager preference. Branded novel mechanisms face reimbursement exclusion without demonstrated superiority.
Strategic Opportunities
- Japan's aging psychiatric population:METI and PMDA pathways for cognitive-enhancing psychotropics address unmet need in geriatric mental health. Depot formulations suit medication adherence challenges in elderly care facilities.
- GLP-1 receptor investigations:Metabolic pathway modulation converges with neuropsychiatric applications. Eli Lilly's research program signals mechanistic expansion beyond traditional monoamine targets.
- Digital therapeutics combinations:Software-based cognitive behavioral therapy paired with pharmacotherapy creates reimbursement-advantaged bundles. Germany's DiGA framework provides regulatory precedent for prescription digital tools.
Industry Challenges
- Psychiatric biomarker validation:FDA and EMA pilot programs for digital endpoints require novel clinical trial infrastructure. CRO capacity for decentralized psychiatric trials remains constrained.
- Depot formulation manufacturing scale-up:Microsphere and nanoparticle suspension production demands specialized sterile capacity. Contract manufacturers with CNS-compatible facilities command premium pricing and extended lead times.
- Cross-border data governance:GDPR in Europe and state-level privacy fragmentation in the United States complicate digital biomarker collection. Multi-site trials face consent and data localization friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Psychotropic Drugs Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $62.13 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Category: Antidepressants, Antipsychotics, Anxiolytics, Mood Stabilizers, Stimulants Therapy Area: Depression, Schizophrenia, Anxiety Disorders, Bipolar Disorder, ADHD End User: Psychiatric Clinics, Mental Wellness Centers, Rehabilitation Facilities, Research Institutions Distribution Channel: Hospital Pharmacies, Retail Pharmacies, Online Pharmacies, Institutional Procurement |
| Companies Covered | Pfizer Inc., Johnson & Johnson, Eli Lilly and Company, Otsuka Holdings Co., Ltd., AstraZeneca Plc, AbbVie Inc., Bristol-Myers Squibb, Alkermes Plc, Lundbeck, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Psychotropic Drugs Market Shifts & Advancements
Psychotropic development is hybridizing digital measurement with biological intervention, creating hybrid products that regulators struggle to classify within traditional pharmaceutical frameworks. This convergence is rewriting competitive boundaries between drug developers and health technology firms.
Digital biomarker platforms are hybridizing passive smartphone sensor data with active cognitive task performance to quantify treatment response. Psychiatric clinics in the United States and Germany are piloting these tools for treatment-resistant depression monitoring. The technology is hybridizing clinical trial endpoints and real-world evidence collection, compressing the gap between regulatory approval and post-market effectiveness confirmation.
China's NMPA accelerated review pathways for innovative psychotropic mechanisms are redirecting regional trial investment toward Shanghai and Beijing clusters. Domestic sponsors gain priority queue positioning for novel targets addressing schizophrenia and bipolar disorder. Multinational developers are responding by establishing captive clinical operations and local regulatory affairs capabilities.
Integrated health networks are consolidating pharmacy procurement decisions across inpatient and outpatient settings. Hospital systems in the United States now negotiate multi-year supply agreements covering oral, injectable, and digital therapeutic portfolios simultaneously. This consolidation is most visible in California and Texas, where large Catholic and nonprofit systems command formulary gatekeeper status.
Global Psychotropic Drugs Market Segmentation
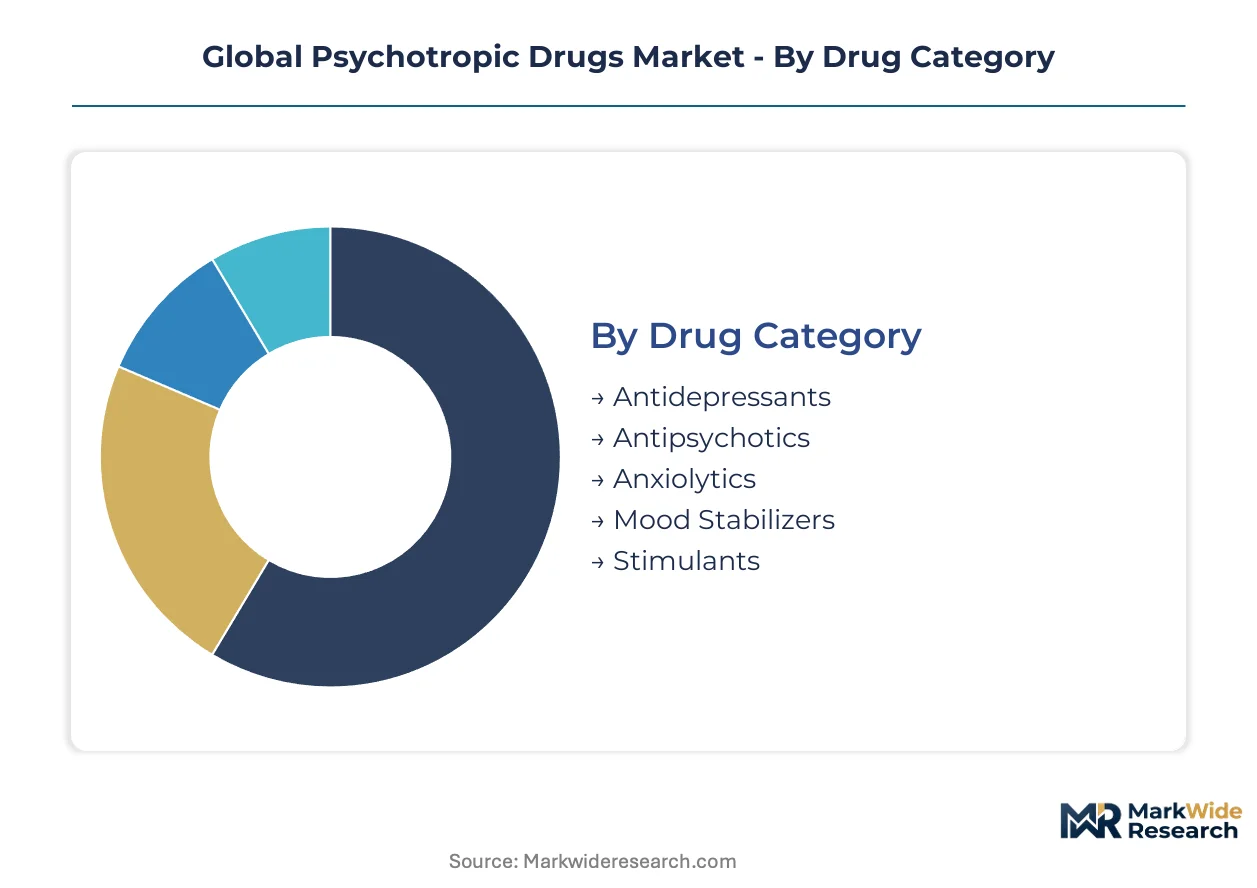
Psychotropic drug purchasing patterns diverge sharply across therapeutic categories and care settings. Manufacturers must align formulation portfolios with distinct reimbursement pathways and prescriber behaviors that govern each segment's commercial dynamics.
Drug Category:
After-sales service intensity varies dramatically across drug categories, with long-acting injectables demanding specialized nurse training programs and adherence monitoring infrastructure that oral generics simply do not require.
- Antidepressants:Synthetic small molecules targeting serotonin, norepinephrine, and dopamine reuptake inhibition dominate prescribing volume. Primary care networks in the United States and Germany drive demand for once-daily oral formulations with established reimbursement codes.
- Antipsychotics:Dopamine receptor antagonists and partial agonists formulated as depot injections command premium pricing through reduced hospitalization cost offsets. Johnson & Johnson's manufacturing expertise in microsphere suspension technology anchors this segment's supply security.
- Anxiolytics:GABA-A receptor modulators, primarily benzodiazepines and buspirone derivatives, face prescribing restrictions due to dependence liability.
- Mood Stabilizers:Lithium carbonate and anticonvulsant derivatives remain foundational for bipolar disorder maintenance therapy.
- Stimulants:Amphetamine and methylphenidate formulations for ADHD treatment are climbing the fastest as digital prescribing platforms expand adult diagnosis access beyond traditional psychiatric settings.
Antidepressants hold the largest share; momentum sits with stimulants.
Therapy Area:
Cost tier stratification separates chronic maintenance indications from acute intervention markets, with schizophrenia and bipolar disorder commanding sustained premium pricing while depression faces generic substitution pressure.
- Depression:Treatment-resistant subpopulations drive demand for novel mechanisms including ketamine derivatives and glutamate modulators. FDA's accelerated approval pathways compress development timelines for mechanism-of-action challengers.
- Schizophrenia:Long-acting injectable antipsychotics reduce relapse-driven hospitalization costs, creating favorable pharmacoeconomic profiles for depot formulations in United States and German reimbursement frameworks.
- Anxiety Disorders:Selective serotonin reuptake inhibitors and cognitive-behavioral therapy combinations dominate first-line intervention.
- Bipolar Disorder:Mood stabilizer maintenance therapy requires lithium monitoring infrastructure that constrains prescribing to specialized psychiatric settings.
- ADHD:Adult diagnosis expansion through telehealth platforms is expanding most quickly among therapy areas, with stimulant demand climbing beyond pediatric populations into workplace productivity applications.
Depression commands the greatest revenue pool; ADHD represents the steepest expansion trajectory.
End User:
Customer type determines formulary access and procurement scale, with integrated health networks consolidating purchasing decisions across outpatient and inpatient settings while research institutions drive early-stage adoption of novel mechanisms.
- Psychiatric Clinics:Specialized prescribers manage complex polypharmacy for treatment-resistant conditions. These facilities in the United States and Japan are expanding long-acting injectable formularies to capture hospitalization cost savings.
- Mental Wellness Centers:Outpatient facilities focus on stable maintenance therapy with oral generic preference.
- Rehabilitation Facilities:Substance use disorder comorbidity drives demand for non-addictive alternatives to traditional anxiolytics.
- Research Institutions:Academic medical centers pilot digital biomarker endpoints and decentralized trial designs for FDA and EMA pilot programs.
Psychiatric clinics anchor volume commitment; research institutions signal technology adoption curves.
Distribution Channel:
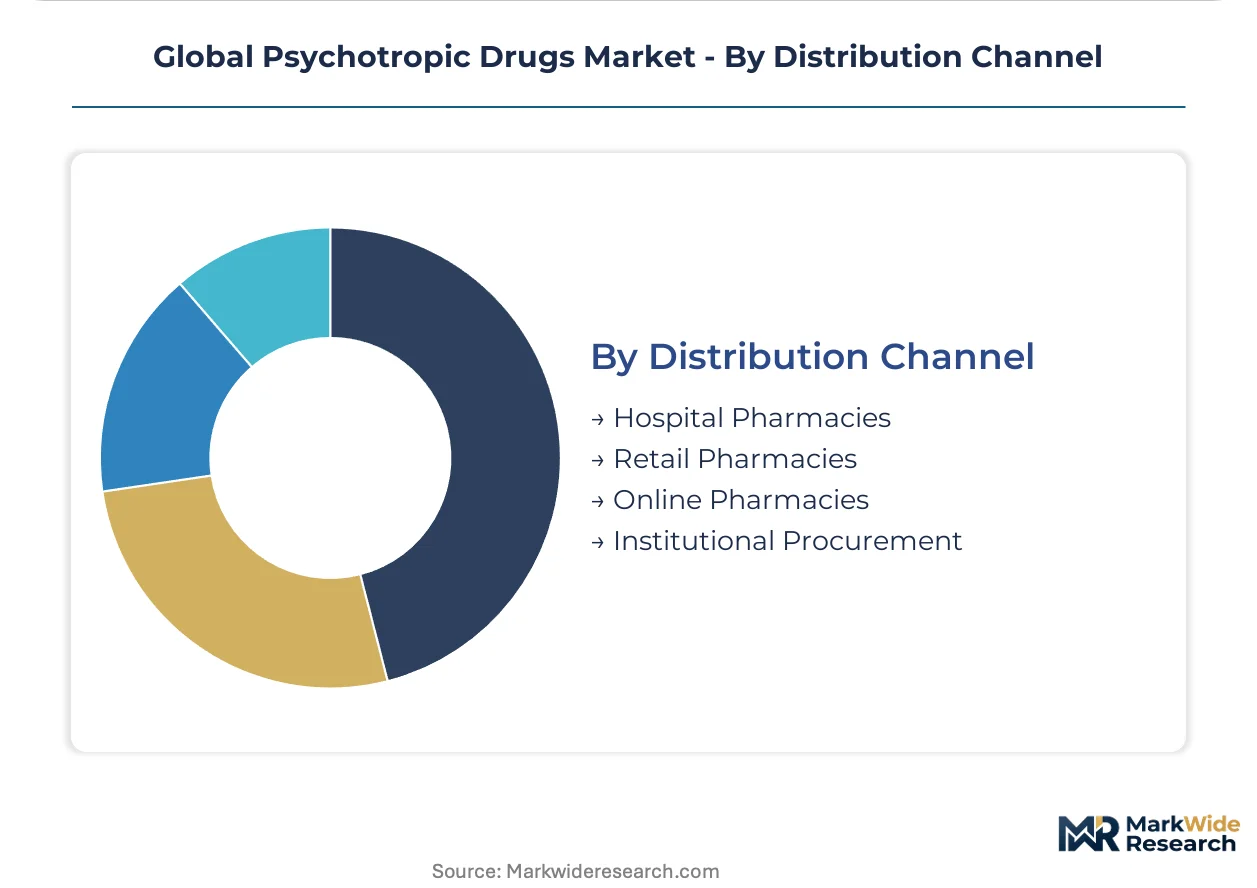
Supply concentration in hospital pharmacy procurement is fragmenting as institutional buyers split contracts between originator long-acting injectables and biosimilar entrants, while online pharmacies face DEA scheduling restrictions for controlled substances.
- Hospital Pharmacies:Inpatient formularies prioritize acute intervention agents with rapid onset. California and Texas health systems negotiate multi-year supply agreements covering oral, injectable, and digital therapeutic portfolios simultaneously.
- Retail Pharmacies:Community dispensing faces pharmacy benefit manager generic substitution pressure for antidepressants.
- Online Pharmacies:Digital prescribing platforms extend stimulant access for ADHD, though controlled substance scheduling limits this channel's scope.
- Institutional Procurement:Integrated health network consolidation concentrates purchasing power across inpatient and outpatient settings.
Hospital pharmacies dominate value capture; institutional procurement is gaining share fastest through network consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical pricing power in the United States exceeds German reimbursement rates by a substantial margin, while Japanese procurement frameworks impose stringent cost-effectiveness thresholds that compress manufacturer margins. This asymmetry redirects R&D investment toward markets with favorable long-acting injectable coverage and accelerated approval pathways.
United States
Integrated health networks in California and Texas consolidate pharmacy procurement across inpatient and outpatient settings, capturing volume discounts on depot formulations. FDA Risk Evaluation and Mitigation Strategies restrict distribution of certain antipsychotics to certified prescribers, limiting rural market penetration. The Boston-Cambridge cluster anchors digital biomarker pilot programs for decentralized psychiatric trials.
Germany
Psychiatric clinics expand long-acting injectable formularies to reduce hospitalization-driven costs within statutory health insurance frameworks. EMA centralized marketing authorization streamlines multi-country commercialization for CNS agents entering European markets. The Rhine-Ruhr metropolitan region concentrates hospital pharmacy procurement decisions for integrated care networks.
Japan
Depot formulations address medication adherence challenges in elderly care facilities serving the aging psychiatric population. METI and PMDA pathways prioritize cognitive-enhancing psychotropics for geriatric mental health indications. The Tokyo-Yokohama corridor hosts clinical operations established by multinational developers seeking accelerated review positioning.
China
Domestic sponsors gain priority queue positioning for novel schizophrenia and bipolar disorder targets under NMPA accelerated review pathways. Shanghai and Beijing clusters redirect regional trial investment toward innovative psychotropic mechanisms. Bulk chemical manufacturers in Jiangsu and Zhejiang supply synthetic serotonin modulator precursors to global formulation networks.
India
Active pharmaceutical ingredient production for generic antidepressants concentrates in Hyderabad and Ahmedabad manufacturing zones. CDSCO regulatory frameworks govern import and local production of psychotropic substances under international scheduling conventions. Contract research organizations in Bangalore and Pune support decentralized trial designs for multinational sponsors.
Global Psychotropic Drugs Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with formulation expertise and manufacturing scale. The market structure consolidates around multinational pharmaceutical conglomerates with depot formulation capabilities and biotech developers with biomarker-validated targets. Three archetypes dominate: originator long-acting injectable manufacturers, biosimilar entrants, and mechanism-of-action challengers leveraging accelerated approval pathways. Competitive moves center on multi-year supply agreements with integrated health networks and captive clinical operations in priority regulatory jurisdictions.
Among U.S.-based pharmaceutical conglomerates, Pfizer Inc., Johnson & Johnson, and Eli Lilly and Company occupy distinct strategic positions. Pfizer represents the manufacturing-scale archetype securing institutional procurement contracts through volume commitments. Johnson & Johnson exemplifies depot formulation expertise anchoring the antipsychotic long-acting injectable segment. Eli Lilly sits within the mechanism-expansion tier, signaling research directions beyond traditional monoamine targets through metabolic pathway investigations. Danish Lundbeck and Japanese Otsuka Holdings Co., Ltd. represent regional specialists with concentrated CNS portfolios. Alkermes Plc exemplifies the drug-delivery technology archetype with specialized microsphere suspension capabilities.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Johnson & Johnson |
| Eli Lilly and Company |
| Otsuka Holdings Co., Ltd. |
| AstraZeneca Plc |
| AbbVie Inc. |
| Bristol-Myers Squibb |
| Alkermes Plc |
| Lundbeck |
| Others |
Supply & Pricing Matrix
Single-source dependency on Chinese and Indian active pharmaceutical ingredient manufacturers determines both pricing tier spreads and supply chain shape. FDA Risk Evaluation and Mitigation Strategies create regulatory chokepoints that inflate compliance costs for antipsychotic distribution, compressing margins at the standard tier while premium depot formulations retain pricing power through hospitalization cost offsets.
Pricing Analysis
The customization-premium spread separates standard oral generics from configured-to-order long-acting injectables with adherence monitoring bundles. Three-tier pricing structure across premium depot formulations, standard oral brands, and economy generics reflects formulation complexity and prescriber certification requirements. Price differentiation hinges on microsphere suspension technology and nurse training program inclusion. Cost compression in the oral antidepressant tier intensifies because pharmacy benefit managers enforce generic substitution. Mental wellness centers exhibit highest price sensitivity; psychiatric clinics managing treatment-resistant populations demonstrate lowest sensitivity due to pharmacoeconomic justification requirements.
Supply Chain Analysis
Contract-manufacturing concentration sits with specialized sterile facilities capable of microsphere and nanoparticle suspension production. Bulk chemical manufacturing draws from China and India for synthetic serotonin modulator precursors. Formulation networks rest on German and Japanese depot expertise for long-acting injectable finishing. Supply chain risk centers on export restriction cascades from concentrated API geographies. Distribution runs through hospital pharmacy procurement with integrated health networks consolidating multi-year supply agreements across oral, injectable, and digital therapeutic portfolios.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The psychotropic drugs market functions as a service-attach opportunity where adherence monitoring infrastructure and nurse training programs expand faster than molecule revenue. Digital therapeutics combinations with software-based cognitive behavioral therapy create recurring-revenue layers that pharmaceutical manufacturers are only beginning to capture.
For Market Incumbents: Entrench depot formulation advantages through captive sterile manufacturing capacity additions in Germany and Japan. Secure multi-year supply agreements with California and Texas integrated health networks before biosimilar entrants fragment procurement. Vertical integration into digital biomarker platforms defends against mechanism-of-action challengers leveraging FDA accelerated approval pathways. For New Entrants and Emerging Players: Pursue Japan's geriatric mental health segment where METI and PMDA pathways prioritize cognitive-enhancing psychotropics for elderly care facilities. Target adult ADHD diagnosis expansion through telehealth-integrated digital prescribing platforms. License depot formulation technology from specialized drug-delivery partners rather than building sterile suspension capacity internally. For Investors and Strategic Acquirers: FDA's pilot programs for digital biomarker endpoints reshape the acquisition landscape toward biotech developers with validated CNS targets and decentralized trial capabilities. Long-term viability across the analysis window favors platform integrators combining pharmacotherapy with prescription digital tools. Monitor EMA centralized marketing authorization timelines as inflection indicators for European commercialization feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Depot Formulation Manufacturing Scale-Up | Specialized sterile capacity commands premium pricing from psychiatric clinics seeking hospitalization cost reductions. |
| Digital Therapeutics Regulatory Approval Pathway | Germany's DiGA framework provides precedent for prescription software bundled with pharmacotherapy reimbursement. |
| Clinical Trial Advancement | Biomarker-validated targets accelerate through FDA pilot programs compressing development timelines for novel mechanisms. |
| Long-term Supply Agreement | Integrated health networks in California consolidate procurement decisions across inpatient and outpatient settings. |
| Pipeline Diversification | GLP-1 receptor investigations signal mechanistic expansion beyond traditional monoamine targets into metabolic pathways. |
Research Methodology
The analysis maps antidepressant, antipsychotic, and stimulant sub-sectors, each validated through formulary directors, regulatory affairs leads, and hospital procurement managers. Primary interviews with psychiatric clinic administrators and payer access specialists combine with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases. Bottom-up prescription volume modeling and top-down revenue triangulation cross-verify segment estimates across the analysis window.
Assumptions held fixed include reimbursement framework structures in the United States, Germany, and Japan; variables include FDA accelerated approval pathway utilization rates and digital biomarker endpoint adoption. The forecast framework models drug category, therapy area, end user, and distribution channel dimensions with administration route and regional regulatory cluster overlays. CAGRs derive from prescription volume trajectories adjusted for generic substitution elasticity and long-acting injectable formulary expansion rates. Pipeline progression probabilities and digital therapeutic bundling penetration serve as industry-specific forecast inputs.
Sensitivities concentrate around API export restrictions from China and India, FDA Risk Evaluation and Mitigation Strategy expansion to additional drug classes, and digital biomarker validation timeline acceleration. Forecasts reflect documented assumptions regarding reimbursement stability and regulatory pathway continuity. Quarterly review of NMPA accelerated review queue positioning, EMA centralized authorization timelines, and integrated health network procurement consolidation indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Antibody Therapy Market
Pharmaceuticals
Global Cholera Vaccines Market
Pharmaceuticals
Italy Diabetes Drugs Market
Pharmaceuticals
Powder-Filled Hard Gelatin Capsules Market
Pharmaceuticals
Hyperphosphatemia Market
Pharmaceuticals
Carbetocin Acetate Market
Pharmaceuticals
Specialty Active Pharmaceutical Ingredients Market
Pharmaceuticals
Global Gout Therapeutics Market
Pharmaceuticals
Focal Segmental Glomerulosclerosis (FSGS) Therapeutics Market
Pharmaceuticals
South Africa Diabetes Drugs Market
Pharmaceuticals
Carbapenem Antibiotics Market
Pharmaceuticals
Global Calcitonin Salmon Market
Pharmaceuticals
Global Antiemetics Market
Pharmaceuticals
Carbetocin Injection Market
Pharmaceuticals
Retinal Drugs and Biologics Market
Pharmaceuticals
Indobufen API Market