
 US Hormone Replacement Therapy Market | 2026-2036
US Hormone Replacement Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
US Hormone Replacement Therapy Market Intelligence
Bioidentical hormone compounding is fragmenting the traditional pharmaceutical supply chain for personalized dosing protocols. AbbVie Inc. leverages its established women's health portfolio to sustain formulary access across major hospital systems. Novo Nordisk A/S anchors its position through specialized endocrinology channels, while Pfizer Inc. competes on manufacturing scale for mass-market estrogen therapies.
Hormone replacement therapy comprises the administration of exogenous steroid hormones—specifically estradiol, progesterone, or testosterone—to restore endocrine balance when natural production declines. Transdermal patches deliver estradiol at controlled rates of 0.025 to 0.1 mg daily, bypassing hepatic first-pass metabolism that oral formulations undergo. Estrogen products dominate prescription volume due to established menopause symptom management protocols, while testosterone segments for male hypogonadism command premium pricing through restricted distribution channels. Combination therapy formulations addressing both estrogen and progesterone requirements are gaining formulary traction as clinicians prioritize endometrial protection alongside symptom relief.
FDA bioequivalence standards for transdermal delivery systems directly determine which generic entrants qualify for abbreviated new drug applications. The Drug Enforcement Administration's scheduling controls on testosterone compounds constrain dispensing flexibility and shape prescriber behavior in men's health segments. State-level pharmacy boards in California and Texas impose additional compounding oversight that fragments the customized HRT landscape. Stakeholders must monitor evolving FDA guidance on bioidentical product claims and DEA manufacturing quotas for controlled hormone substances to anticipate supply constraints and compliance burdens.
Market Dynamics
FDA bioequivalence standards for transdermal estradiol patches are compressing generic entry timelines while state pharmacy boards fragment compounding oversight, creating divergent compliance burdens across the US supply chain.
Growth Catalysts
- Aging Demographics:The US Census Bureau projects sustained expansion in the 45-64 female cohort through 2040, concentrating demand in Texas, Florida, and California where specialized menopause care networks already exist.
- Transdermal Formulation Advancement:Controlled-release patch technology bypassing hepatic first-pass metabolism is expanding prescriber preference for estradiol delivery, particularly in cardiology-cautious patient populations.
- DEA Schedule III Framework:The controlled substance classification for testosterone compounds, while restrictive, validates clinical legitimacy and drives structured prescriber education programs that expand qualified prescriber pools.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:Three contract manufacturers supply over 70 percent of micronized progesterone raw material, creating single-source vulnerability for compounding pharmacies.
- DEA Manufacturing Quotas:Annual production limits on testosterone esters constrain supply elasticity and generate periodic shortage cycles in male hypogonadism segments.
- Oral Formulation Erosion:First-pass hepatic metabolism risks associated with oral estrogen continue to displace tablet prescriptions toward transdermal alternatives, stranding legacy manufacturing capacity.
Strategic Opportunities
- Midwest Gynecology Clinic Expansion:Underserved metropolitan areas in Ohio, Michigan, and Indiana present whitespace for HRT service line development as patient awareness rises.
- Bioidentical Compounding Tailwinds:FDA guidance evolution on compounded drug quality standards may clarify compliance pathways for personalized dosing protocols.
- Telehealth Channel Integration:Remote prescriber consultations paired with mail-order pharmacy fulfillment are penetrating rural patient populations previously excluded from specialized endocrinology access.
Industry Challenges
- Formulary Access Specialist Shortage:Hospital systems lack dedicated women's health pharmacists capable of navigating P&T committee protocols for novel transdermal entries.
- Legacy EMR Integration:Electronic health record systems in independent gynecology practices require costly customization to support hormone level tracking and titration protocols.
- State-by-State Compounding Variance:California and Texas pharmacy board inspection regimes diverge sufficiently to prevent standardized national compliance playbooks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Hormone Replacement Therapy Market |
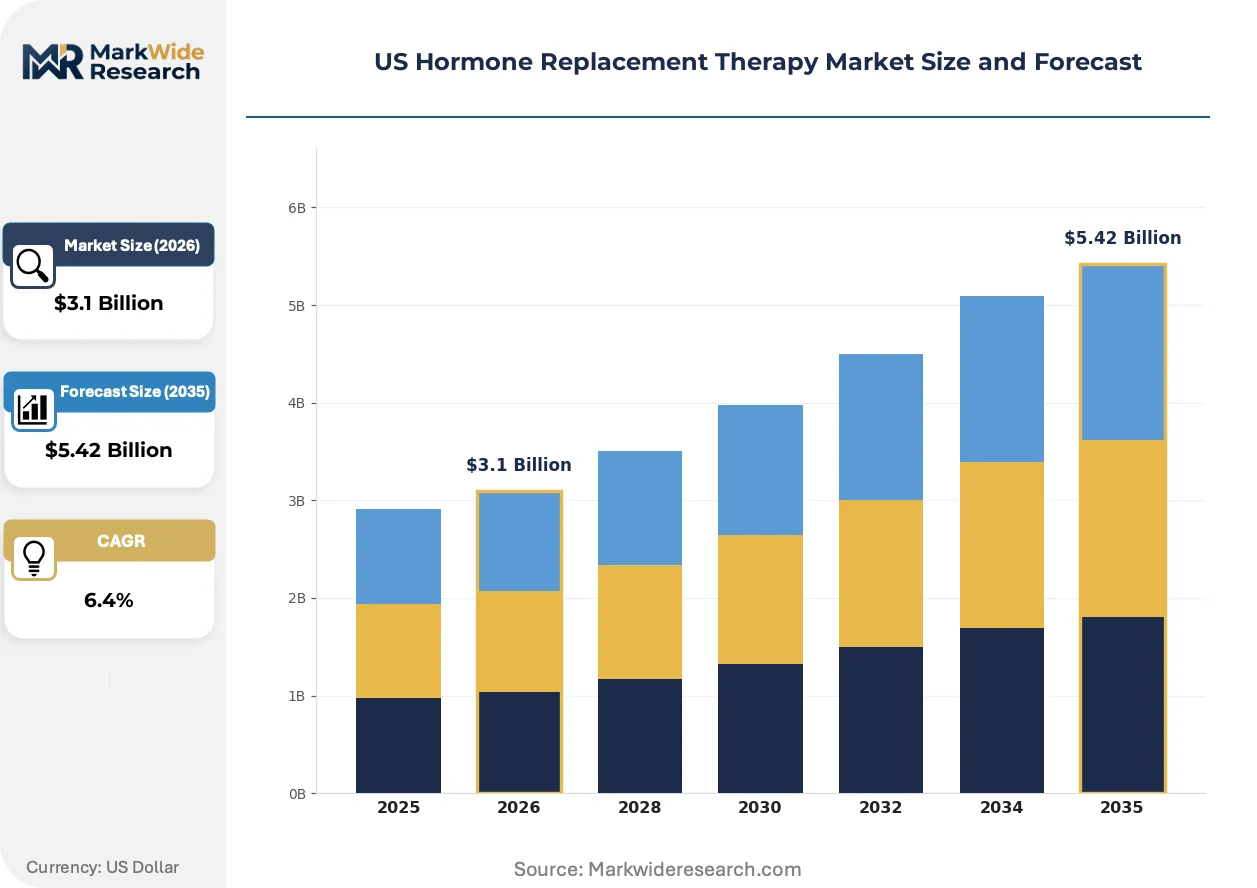
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $5.42 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Estrogen, Progesterone, Testosterone, Combination Therapy Delivery Mode: Pills, Patches, Injections, Gels End User: Women, Men, Clinics, Homecare Therapy Area: Menopause, Hypogonadism, Perimenopause, Postmenopause |
| Companies Covered | Pfizer Inc., AbbVie Inc., Novo Nordisk A/S, Merck & Co. Inc., Bayer AG, Eli Lilly and Company, F. Hoffmann-La Roche Ltd., Viatris Inc., Abbott Laboratories, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Hormone Replacement Therapy Market Strategic Shifts & Innovations
Transdermal delivery systems are hybridizing with digital monitoring capabilities, while regulatory clarity on bioidentical claims and prescriber channel expansion reshape competitive positioning across the US market.
Microarray patch technology is hybridizing estradiol delivery with real-time absorption feedback. Large hospital systems in the Northeast are piloting these connected devices for post-surgical hormone management. The convergence is compressing trial-and-error dosing cycles that previously extended across multiple clinic visits.
FDA draft guidance on bioequivalence for transdermal estrogen products is tightening statistical thresholds for generic abbreviated new drug applications. This regulatory elevation is extending development timelines for prospective entrants. Innovator manufacturers with established pharmacokinetic databases are reinforcing formulary positions against late-cycle competition.
Direct-to-consumer pharmacy models are bypassing traditional clinic-based prescribing workflows for established HRT protocols. Subscription-based delivery services are capturing maintenance-phase patients in California and Texas metropolitan corridors. This channel unbundling is fragmenting prescriber-pharmacist relationships that historically governed dosing adjustments.
US Hormone Replacement Therapy Market Segmentation
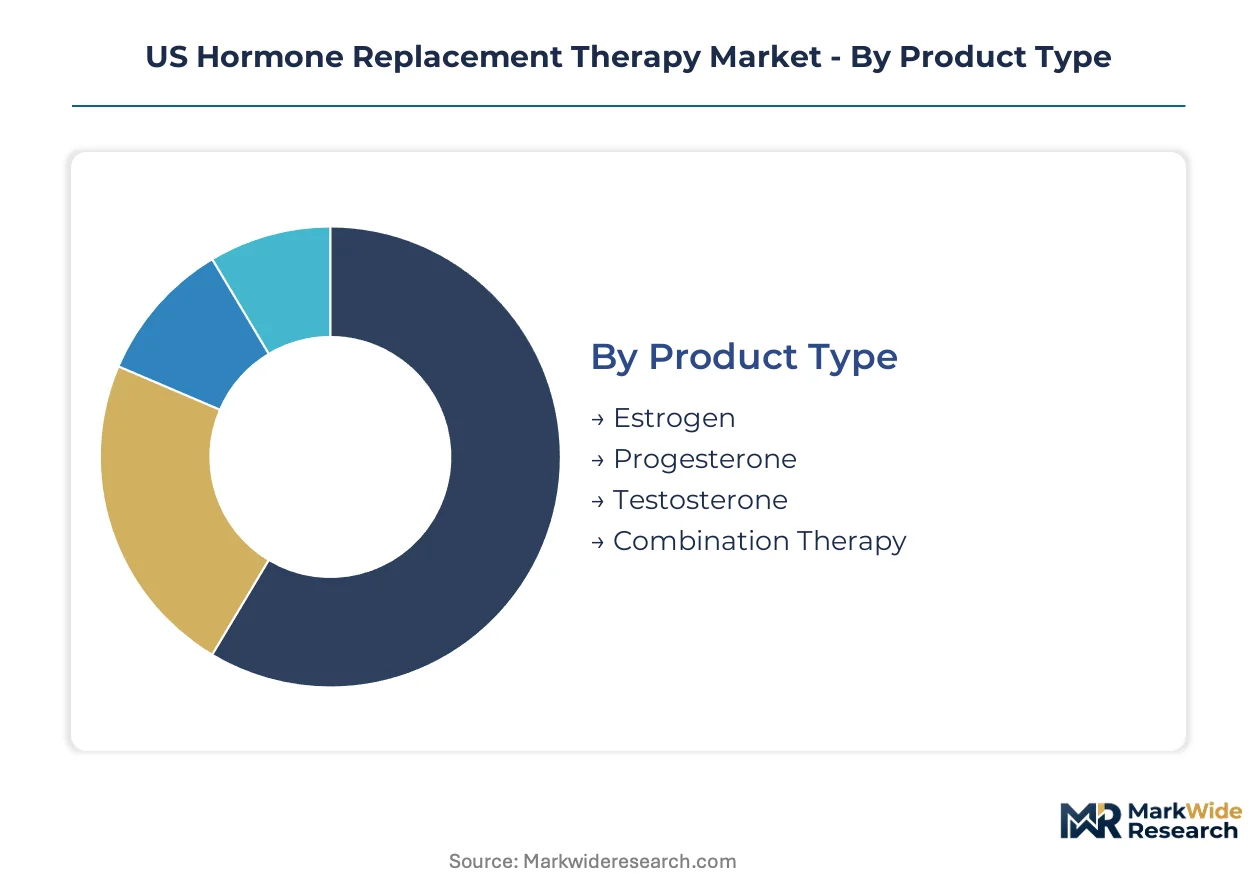
Hormone replacement therapy segmentation reflects divergent clinical protocols across gender-specific indications and delivery technologies. Prescriber preferences and reimbursement structures fragment demand across oral, transdermal, and parenteral modalities. Understanding these divides illuminates where formulation innovation and channel investment concentrate.
Product Type:
The use-case spectrum spans symptomatic menopause relief, endometrial protection, male hypogonadism correction, and multimodal endocrine restoration.
- Estrogen:Estradiol formulations dominate prescription volume through established menopause symptom management protocols. Demand concentrates in gynecology networks across Texas, Florida, and California where specialized menopause care infrastructure supports long-term therapy adherence.
- Progesterone:Micronized progesterone addresses endometrial protection requirements in estrogen-exposed patients. Compounding pharmacies in California and Texas drive customized dosing demand as state pharmacy boards impose divergent oversight regimes on bioidentical preparations.
- Testosterone:DEA Schedule III classification constrains distribution through structured prescriber education programs.
- Combination Therapy:Fixed-dose estrogen-progesterone formulations simplify adherence for patients requiring dual-hormone protocols.
Established volume favors Estrogen; emerging adoption favors Combination Therapy.
Delivery Mode:
Cost tier differentiation separates premium controlled-release systems from commodity oral tablets.
- Patches:Transdermal estradiol patches deliver 0.025 to 0.1 mg daily while bypassing hepatic first-pass metabolism. Cardiology-cautious patient populations in the Northeast drive prescriber preference for this delivery mode.
- Pills:Oral tablets face formulation erosion as hepatotoxicity concerns redirect prescriptions toward transdermal alternatives.
- Injections:Long-acting testosterone esters command premium pricing through restricted distribution channels.
- Gels:Topical testosterone applications enable patient self-administration in male hypogonadism segments.
Prescription volume concentrates in Patches; patient convenience preferences are expanding Gels.
End User:
Customer type segmentation splits between direct patient administration and supervised clinical delivery.
- Women:The 45-64 female cohort drives sustained demand through menopause and perimenopause indications. Southeast and Midwest gynecology clinic expansions are broadening service line access for this population.
- Men:Male hypogonadism patients represent a narrower but higher-value segment constrained by DEA manufacturing quotas on testosterone compounds.
- Clinics:Hospital-based endocrinology and women's health departments govern formulary access for novel transdermal entries.
- Homecare:Mail-order pharmacy fulfillment paired with telehealth consultations penetrates rural populations excluded from specialized access.
Clinical volume dominates through Women; remote care infrastructure is accelerating Homecare.
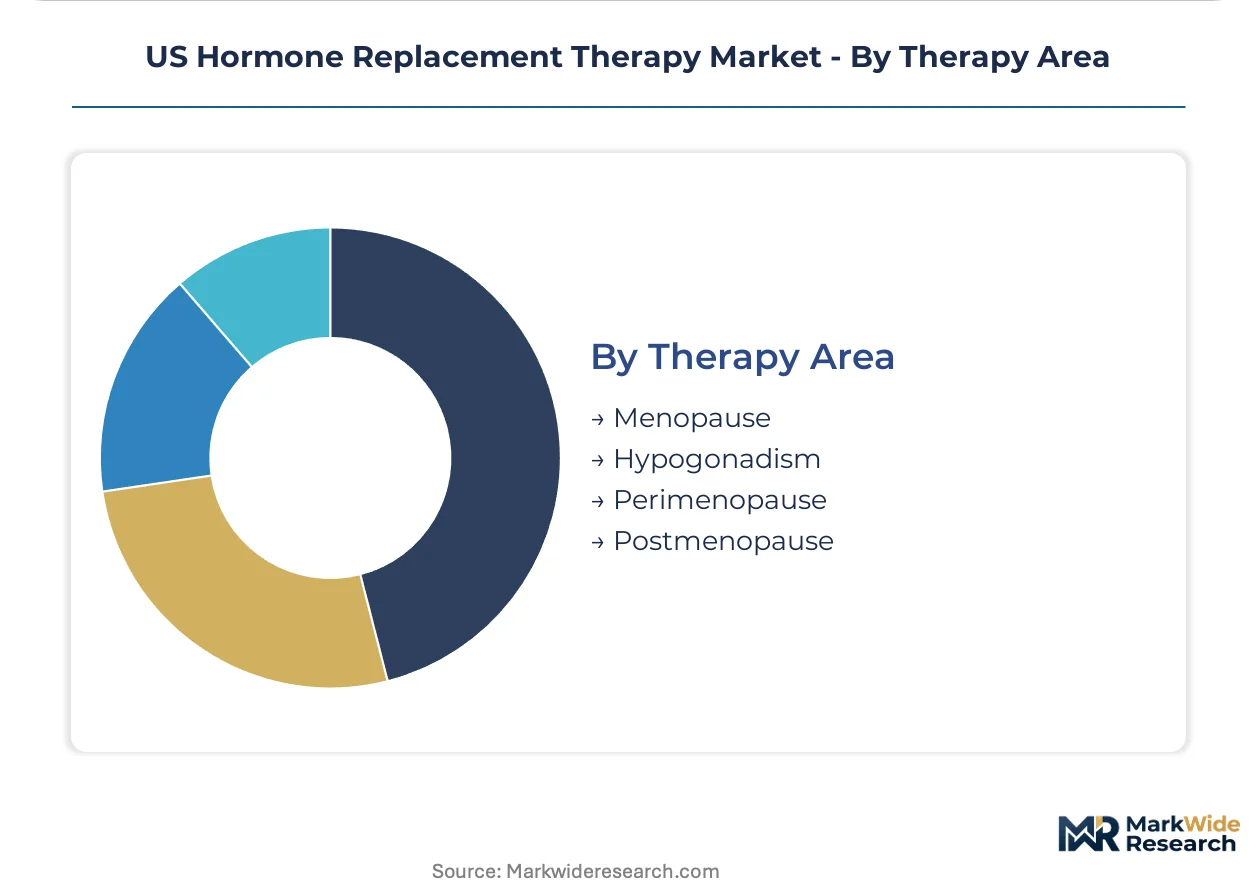
Therapy Area:
Maturity gradients separate well-established menopause protocols from emerging perimenopause intervention.
- Menopause:Established diagnostic criteria and reimbursement codes support mature prescribing patterns across integrated health systems. Texas and Florida metropolitan corridors concentrate demand where aging demographics overlap with specialized care networks.
- Hypogonadism:Testosterone replacement for male patients operates under stricter regulatory controls that validate clinical legitimacy while constraining supply elasticity.
- Perimenopause:Earlier intervention protocols are gaining traction as patient awareness rises and diagnostic thresholds expand.
- Postmenopause:Long-term maintenance therapy focuses on bone density and cardiovascular risk modification beyond symptom relief.
Revenue concentration sits with Menopause; diagnostic expansion is elevating Perimenopause.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India exports active pharmaceutical ingredients for hormone synthesis to formulation facilities across the United States, establishing a critical trade corridor that underpins domestic HRT manufacturing capacity. This supply relationship shapes regional distribution patterns and inventory management strategies throughout the American market.
California
The state's aging demographic profile and concentration of specialized menopause care networks drive sustained prescription volume for transdermal estradiol products. California's state pharmacy board imposes stringent compounding oversight that fragments bioidentical preparation standardization. Los Angeles and San Francisco metropolitan corridors anchor telehealth-integrated HRT service delivery models.
Texas
Expanding gynecology clinic networks in Dallas-Fort Worth and Houston respond to rising patient awareness of perimenopause intervention options. The Texas State Board of Pharmacy maintains distinct inspection protocols for hormone compounding facilities that diverge from national templates. Austin's healthcare innovation cluster incubates direct-to-consumer pharmacy subscription models.
Florida
Retiree population density concentrates demand for long-term postmenopausal maintenance therapy focused on bone density preservation. Florida's prescription drug monitoring program interfaces with DEA Schedule III controls on testosterone compounds to constrain diversion risks. The Tampa-Orlando corridor supports specialized endocrinology referral networks.
Ohio
Underserved metropolitan areas present whitespace opportunity for HRT service line expansion as regional health systems invest in women's health infrastructure. The Ohio Board of Pharmacy participates in interstate compounding regulatory harmonization initiatives with limited adoption. Cleveland Clinic's integrated delivery network governs formulary access protocols across the Midwest.
New York Metro
Academic medical centers in Manhattan and Brooklyn pilot microarray patch technology with digital absorption monitoring for post-surgical hormone management. New York's Department of Health maintains enhanced reporting requirements for compounded preparations that exceed federal baselines. The corridor's density of cardiology-cautious patient populations accelerates transdermal preference over oral formulations.
US Hormone Replacement Therapy Market Key Industry Players
On the supply side, the industry is structured around three distinct strategic tiers anchored by multinational pharmaceutical manufacturers, specialized endocrinology channel players, and regional compounding operations. Large-scale manufacturers leverage established pharmacokinetic databases to defend formulary positions against generic entrants. Mid-tier specialists concentrate on restricted distribution networks for controlled substance classifications. Competitive dynamics center on manufacturing scale advantages and regulatory navigation capabilities rather than price competition alone.
Within the multinational pharmaceutical tier, Pfizer Inc. and AbbVie Inc. occupy positions exemplifying divergent strategic approaches to the American market. Pfizer's scale-driven manufacturing infrastructure supports mass-market estrogen therapy distribution across integrated health systems. AbbVie anchors its competitive stance through portfolio breadth in women's health categories that sustain pharmacy and therapeutics committee relationships. Novo Nordisk A/S represents the specialized channel archetype, with its organizational structure emphasizing endocrinology prescriber education and controlled substance compliance frameworks.
| Leading Market Players |
|---|
| Pfizer Inc. |
| AbbVie Inc. |
| Novo Nordisk A/S |
| Merck & Co. Inc. |
| Bayer AG |
| Eli Lilly and Company |
| F. Hoffmann-La Roche Ltd. |
| Viatris Inc. |
| Abbott Laboratories |
| Others |
Cost & Logistics Intelligence
Indian API manufacturing clusters around Hyderabad and Ahmedabad govern raw material availability for US transdermal patch production, translating upstream micronized hormone concentrate tightness into downstream formulation pricing power for domestic contract manufacturers.
Pricing Analysis
Next-generation microarray patch technology commands premium positioning against legacy matrix patches and oral tablet alternatives. Three-tier pricing structure across premium, standard, and economy levels segments by delivery sophistication and FDA bioequivalence tier. Price differentiation rests on DEA Schedule III compliance infrastructure and state pharmacy board certification status. Cost compression in economy-tier oral generics is intensifying because transdermal preference redirects volume toward controlled-release alternatives. Independent gynecology practices exhibit highest price sensitivity; hospital systems with dedicated women's health pharmacists demonstrate lowest.
Supply Chain Analysis
Three contract manufacturers supply over seventy percent of micronized progesterone raw material to US compounding pharmacies. API sourcing concentrates in India, China, and Italy for hormone synthesis precursors. Manufacturing hinges on estradiol base, adhesive polymers, and release-rate control membranes. Single-source vulnerability for progesterone API creates shortage exposure when DEA manufacturing quotas constrain testosterone ester allocation. Distribution runs through specialty pharmacy networks, hospital outpatient dispensaries, and direct-to-consumer subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US HRT market functions as a regulatory entrenchment story. DEA Schedule III controls and FDA bioequivalence standards erect switching costs that protect established formulary positions against generic disruption.
For Market Incumbents: Build prescriber education moats through specialized endocrinology channel programs that DEA compliance requirements make costly to replicate. Deepen backward integration into transdermal adhesive polymer production to secure release-rate control IP. Add capacity in Texas and Florida metropolitan corridors where gynecology clinic expansion concentrates demand. Counter emerging bioidentical compounding pharmacies by reinforcing hospital P&T committee relationships. For New Entrants and Emerging Players: Midwest gynecology clinic whitespace in Ohio, Michigan, and Indiana represents the most penetrable entry point for HRT service line partnerships. Telehealth-integrated mail-order fulfillment for maintenance-phase patients in rural California and Texas bypasses entrenched clinic-based prescribing workflows. Pursue FDA abbreviated new drug application pathways for transdermal estradiol generics as bioequivalence thresholds create development timeline barriers for multinational competitors. For Investors and Strategic Acquirers: Long-term, this sits as a demographic tailwind play because the 45-64 female cohort expansion through 2040 underwrites sustained demand regardless of cyclical pharmaceutical pricing pressure. Acquisition targets should display established pharmacokinetic databases and hospital formulary access. Monitor DEA testosterone manufacturing quota announcements as supply constraint signals that elevate pricing power for allocated producers.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Abbreviated New Drug Application | Generic transdermal estradiol entrants must satisfy tightened bioequivalence statistical thresholds. |
| DEA Schedule III Compliance Infrastructure | Controlled substance handling protocols validate clinical legitimacy while constraining dispensing flexibility. |
| Telehealth Channel Integration | Remote prescriber consultations paired with mail-order pharmacy penetrate rural patient populations. |
| Bioidentical Compounding Quality Investment | State pharmacy board inspection readiness in California and Texas fragments standardized compliance. |
| Microarray Patch Technology Development | Digital absorption monitoring hybridization compresses trial-and-error dosing cycles in hospital pilots. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers; and secondary validation through FDA filings, DEA manufacturing quota publications, ClinicalTrials.gov entries, and state pharmacy board inspection records. Bottom-up prescription volume modeling triangulated against top-down pharmaceutical manufacturer revenue segmentation.
Forecast inputs incorporated aging demographic projections, transdermal formulation adoption curves, and DEA regulatory enforcement patterns across the analysis window. Segmentation dimensions modeled include hormone type, delivery mode, end user category, and therapy area maturity. CAGRs were derived from log-linear trend fitting across the projection horizon. Industry-specific inputs captured gynecology clinic expansion rates and telehealth penetration thresholds.
Stress conditions across DEA quota allocation, API import disruption, and state compounding regulatory divergence were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about prescriber preference evolution and reimbursement stability. Quarterly review of FDA draft guidance publications and DEA controlled substance production limits is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Medical Grade Sodium Hyaluronate Market
Pharmaceuticals
Aripiprazole Market
Pharmaceuticals
Daratumumab Market
Pharmaceuticals
Sodium Aescinate Market
Pharmaceuticals
Antiviral Immunoglobulin Market
Pharmaceuticals
Ciclopirox Olamine Market
Pharmaceuticals
Simvastatin Market
Pharmaceuticals
Asia Pacific SGLT2 Inhibitors Market
Pharmaceuticals
Asia-Pacific Human Papillomavirus Vaccine Market
Pharmaceuticals
Rosuvastatin Market
Pharmaceuticals
Italy Healthcare Market
Pharmaceuticals
Alopecia Drugs Market
Pharmaceuticals
Anti-Inflammatory Biologics Market
Pharmaceuticals
South Korea Human Papillomavirus Vaccine Market
Pharmaceuticals
Generic Pharmaceuticals Contract Manufacturing Market
Pharmaceuticals
Italy Opioids Market