
 Italy Opioids Market | 2026-2036
Italy Opioids Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Opioids Market Insights
The buyer base for opioid formulations is broadening as home care agencies and regional hospice networks gain purchasing autonomy alongside traditional hospital procurement committees. Mundipharma leverages its transdermal portfolio to sustain relationships with chronic pain centers across the peninsula. Teva Pharmaceuticals competes through generic injectable offerings that anchor its position in oncology wards. Johnson & Johnson differentiates via sustained-release technologies that dominate premium hospital contracts.
Opioids constitute semi-synthetic and synthetic alkaloid derivatives that bind to mu, kappa, and delta receptors in the central nervous system, with morphine sulfate exhibiting bioavailability ranging from 24% to 30% following oral administration. These compounds serve primarily as analgesic interventions for moderate-to-severe nociceptive and neuropathic pain across acute surgical and terminal care settings. Fentanyl and oxycodone formulations command the largest revenue pools within product type segmentation due to their established reimbursement profiles and potency-adjusted dosing protocols. Palliative care applications are outpacing anesthesia in growth velocity as Italy's aging demographic intensifies demand for end-of-life pain management. Oral delivery modes retain volume leadership, though transdermal patches are capturing margin-rich long-therapy segments where patient compliance drives clinical outcomes.
AIFA, Italy's national pharmaceutical regulator, enforces stringent prescription tracking and morphine-equivalent dosing ceilings that directly constrain physician prescribing behavior and wholesale distribution volumes. EMA pharmacovigilance frameworks and Italy's national opioid stewardship protocols jointly mandate real-world outcome reporting, elevating documentation burdens for manufacturers seeking market access. Stakeholders must monitor evolving reimbursement thresholds for combination therapies and the pace of regional health authority consolidation to anticipate procurement leverage shifts.
Market Dynamics
AIFA's morphine-equivalent dosing ceilings and real-time prescription tracking systems are compressing physician autonomy and reshaping wholesale distribution economics across the peninsula.
Growth Catalysts
- Palliative care expansion:Regional health authorities in Lombardy and Emilia-Romagna are broadening hospice network coverage, creating dedicated procurement channels for sustained-release and transdermal formulations.
- Aging demographic pressure:Italy's geriatric population intensifies demand for terminal pain management protocols that prioritize patient compliance over acute intervention.
- Home care agency autonomy:Decentralized purchasing authority among community-based nursing services is diversifying the buyer base beyond traditional hospital committees.
Market Restraints
- Active pharmaceutical ingredient concentration:Synthesis of fentanyl citrate and oxycodone base relies on a limited supplier base concentrated in South Asian manufacturing clusters, exposing formulators to input volatility.
- Regulatory documentation burden:EMA pharmacovigilance frameworks mandate real-world outcome reporting that extends market access timelines for novel formulations.
- Non-opioid substitution:Gabapentinoids and regional nerve block protocols are capturing neuropathic pain segments previously served by synthetic alkaloids.
Strategic Opportunities
- Southern Italy underpenetration:Campania and Sicily exhibit lower morphine consumption rates per capita than northern regions, suggesting latent demand for education-driven formulary expansion.
- Combination therapy reimbursement:Emerging AIFA thresholds for opioid-adjuvant protocols create white space for fixed-dose products that reduce pill burden.
- Transdermal patch convergence with telemedicine:Remote monitoring platforms enable adherence verification for long-therapy patients, supporting margin-rich patch prescriptions outside institutional settings.
Industry Challenges
- Pain specialist workforce scarcity:Certified palliative care physicians remain concentrated in academic medical centers, constraining protocol rollout to peripheral provinces.
- Cold chain infrastructure gaps:Injectable fentanyl formulations require temperature-controlled distribution networks that lack redundancy in rural Apennine corridors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Opioids Market |
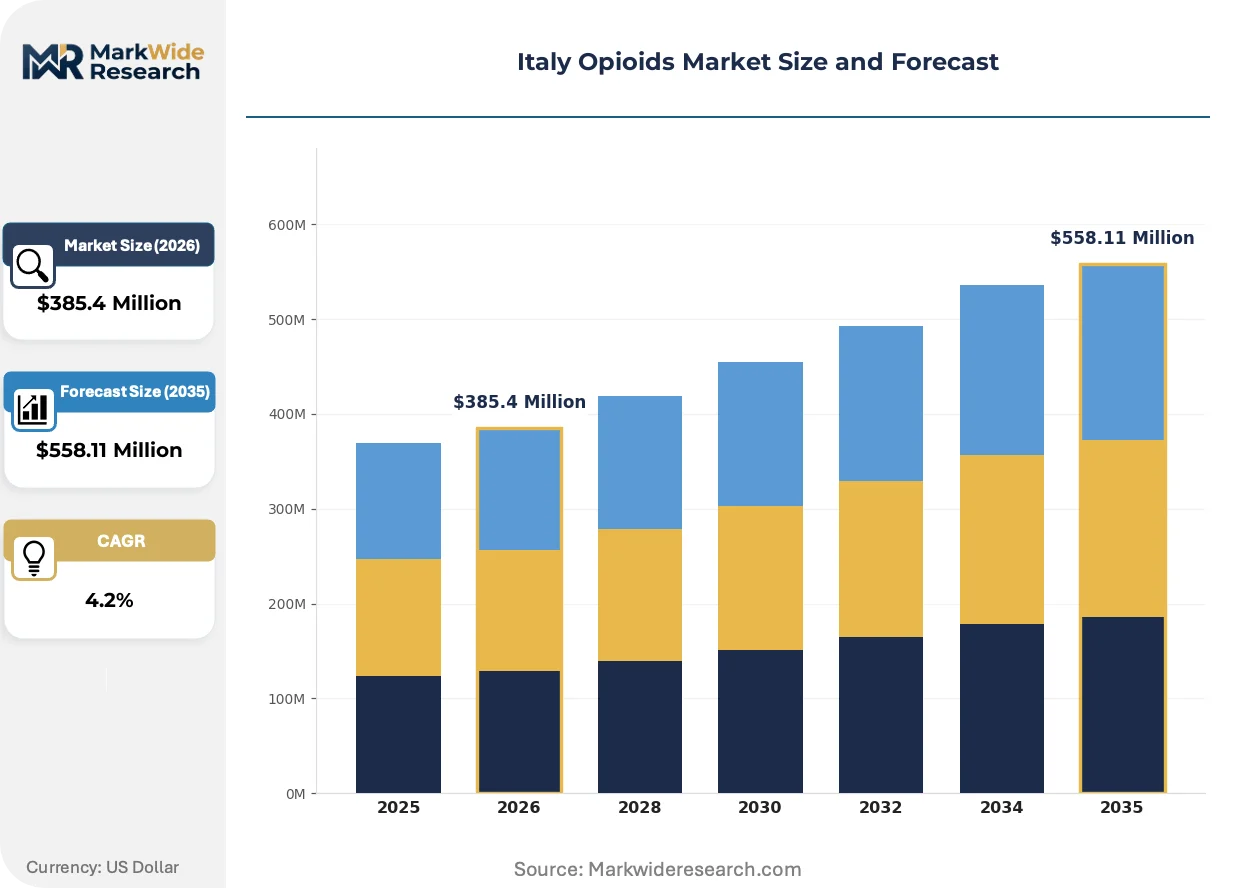
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $558.11 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Morphine, Oxycodone, Fentanyl, Hydromorphone Application: Pain Management, Anesthesia, Cancer Treatment, Palliative Care Delivery Mode: Oral, Transdermal, Injection, Inhalation End User: Hospitals, Clinics, Home Care, Rehabilitation Centers |
| Companies Covered | Mundipharma, Grünenthal, Purdue Pharma, Teva Pharmaceuticals, Mallinckrodt Pharmaceuticals, Hikma Pharmaceuticals, Johnson & Johnson, Pfizer, Sun Pharmaceutical Industries, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Opioids Market Trends and Innovations
Formulation science and regulatory technology are converging to reshape competitive advantage, with delivery mechanism innovation and compliance automation emerging as decisive differentiators.
Transdermal matrix technology is overtaking oral sustained-release tablets in chronic pain segments where steady-state plasma levels reduce breakthrough episodes. Pain centers in Milan and Bologna are accelerating patch adoption for osteoarthritis and cancer-related nociception. This shift is compressing generic oral tablet margins while elevating barrier-to-entry requirements for adhesive polymer expertise.
AIFA's integration of centralized prescription databases with regional health information exchanges tightens real-time monitoring of morphine-equivalent consumption. The industrial consequence is elevated compliance infrastructure costs for distributors serving multi-regional hospital networks. Wholesale operators are responding by segmenting inventory systems to isolate high-ceiling products within traceable distribution nodes.
Home hospice networks are consolidating purchasing decisions through regional consortium structures that displace fragmented municipal procurement. These aggregators negotiate directly with manufacturers for transdermal and sublingual portfolios, bypassing traditional hospital pharmacy committees. The phenomenon is most visible in Veneto and Tuscany, where integrated care organizations now control formulary access for terminal patients discharged to residential settings.
Italy Opioids Market Segmentation
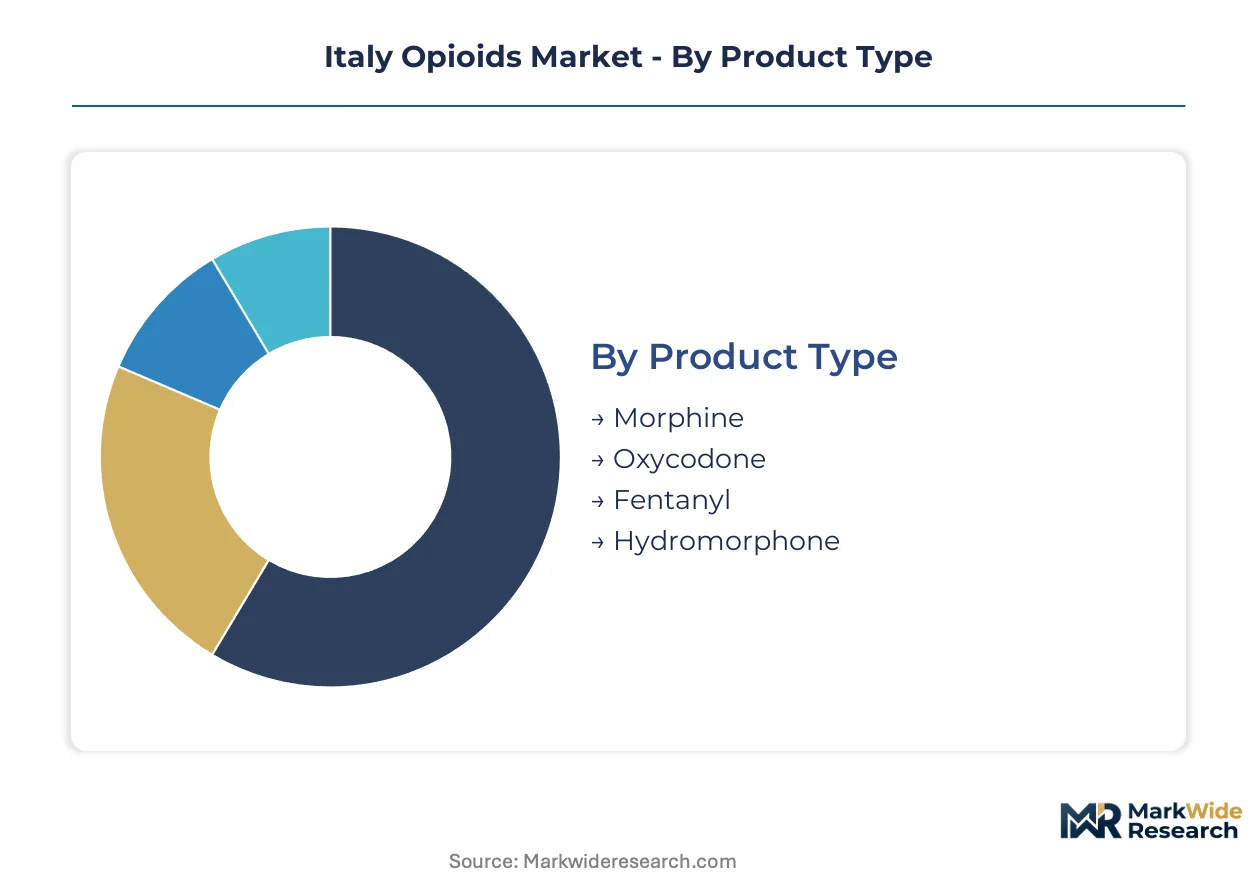
Opioid formularies in Italy fragment across therapeutic intensity, institutional setting, and reimbursement tier. Each segmentation axis reveals distinct procurement patterns and margin structures that shape manufacturer positioning.
Product Type:
Fentanyl and oxycodone concentrate premium revenue pools while morphine anchors high-volume, cost-constrained protocols.
- Fentanyl:Synthetic phenylpiperidine derivative with 100-fold morphine potency enables microgram-precision dosing in transdermal and injectable matrices. Demand clusters in Lombardy cancer centers and Emilia-Romagna surgical wards where AIFA reimbursement favors high-potency formulations for breakthrough pain. Cold chain requirements and polymer expertise erect formulation barriers that protect margin structures.
- Oxycodone:Semi-synthetic thebaine derivative delivers equivalent analgesia at lower morphine-equivalent doses, reducing AIFA ceiling constraints. Oral sustained-release tablets dominate hospital discharge protocols across Veneto and Tuscany hospice networks, with generic competition intensifying in standard-release segments.
- Morphine:Gold-standard alkaloid for terminal pain management with established palliative care protocols throughout the peninsula.
- Hydromorphone:Hydrogenated ketone variant reserved for opioid-tolerant patients in tertiary referral centers.
Today's leader: Fentanyl. Tomorrow's challenger: Oxycodone.
Application:
Palliative care applications are climbing the fastest as demographic pressure reshapes clinical priorities.
- Palliative Care:End-of-life pain protocols prioritize patient compliance and caregiver convenience over acute intervention speed. Regional health authorities in northern Italy are expanding dedicated procurement channels for sustained-release and transdermal portfolios, with home hospice networks in Veneto consolidating purchasing through consortium structures.
- Pain Management:Acute and chronic nociceptive intervention spans post-surgical wards, trauma centers, and outpatient clinics. Demand concentrates in hospital-based protocols within Lombardy and Emilia-Romagna where AIFA morphine-equivalent ceilings constrain prescribing autonomy.
- Cancer Treatment:Oncology ward formularies require potency-calibrated dosing for tumor-related nociception and chemotherapy-induced neuropathy.
- Anesthesia:Perioperative analgesia and sedation protocols in surgical theaters favor rapid-onset, short-acting formulations.
Palliative care commands margin expansion; pain management retains volume dominance.
Delivery Mode:
Oral formulations retain procurement volume leadership while transdermal patches capture adherence-premium segments.
- Oral:Tablets and capsules dominate hospital discharge prescriptions and community pharmacy fulfillment across the peninsula. Bioavailability constraints and first-pass metabolism drive dose escalation requirements, compressing margins in generic-saturated immediate-release categories.
- Transdermal:Matrix patches deliver steady-state plasma levels that reduce breakthrough episodes and caregiver burden. Pain centers in Milan and Bologna are accelerating adoption for osteoarthritis and cancer-related nociception, with adhesive polymer expertise differentiating formulation quality.
- Injection:Intravenous and subcutaneous formulations serve perioperative and breakthrough pain protocols in institutional settings.
- Inhalation:Nebulized and intranasal routes address rapid-onset requirements in emergency and palliative contexts.
Oral delivery defends volume position; transdermal patches represent the fastest-growing trajectory.
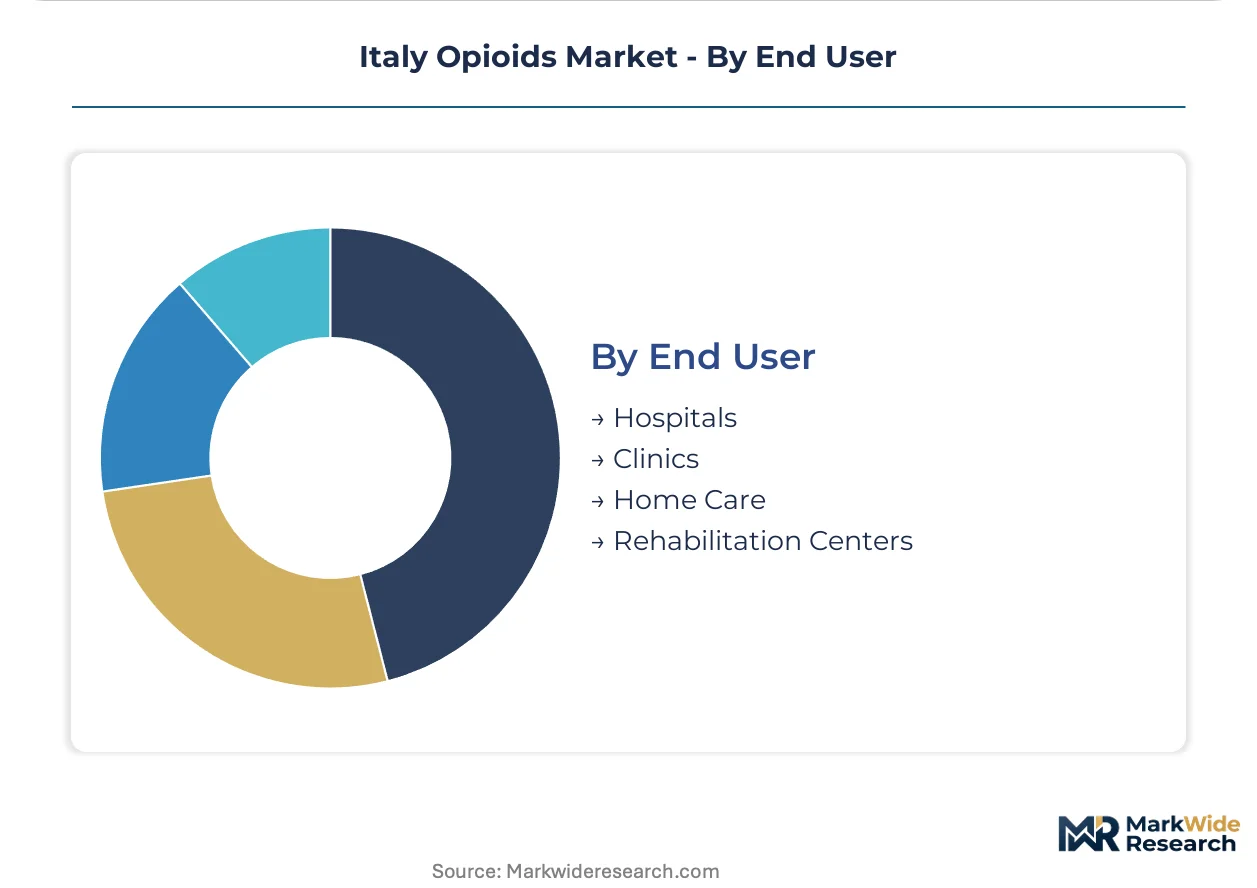
End User:
Hospital procurement committees retain contract leverage as home care agencies gain decentralized purchasing autonomy.
- Hospitals:Academic medical centers and regional hospitals in Lombardy, Emilia-Romagna, and Veneto anchor formulary decisions through centralized pharmacy committees. Premium sustained-release and injectable portfolios require direct manufacturer negotiation for tender access.
- Home Care:Community-based nursing services and residential hospice networks are consolidating purchasing through regional consortium structures in Tuscany and Veneto. These aggregators negotiate directly for transdermal and sublingual formulations, bypassing traditional hospital procurement channels.
- Clinics:Outpatient pain centers and oncology day units require flexible procurement for mixed acute-chronic protocols.
- Rehabilitation Centers:Post-acute facilities manage tapering protocols and long-term pain stabilization.
Hospitals control premium access; home care networks are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and France maintain higher per-capita opioid consumption rates than Italy, yet the peninsula's northern regions are accelerating formulary expansion to close this gap. AIFA's centralized oversight creates uniform regulatory constraints across sub-regional markets, though procurement autonomy varies significantly between autonomous regional health authorities.
Lombardy
Milan's academic medical centers anchor the peninsula's largest concentration of palliative care beds and pain management protocols. Regional health authority Lombardia has expanded dedicated procurement channels for transdermal fentanyl and sustained-release oxycodone through its centralized pharmaceutical purchasing consortium. The Monza-Brianza cluster hosts specialized chronic pain centers that drive adoption of polymer-matrix patch technologies for osteoarthritis and cancer-related nociception.
Emilia-Romagna
Bologna's oncology wards generate concentrated demand for high-potency injectable formulations in breakthrough pain protocols. The regional health authority has negotiated direct manufacturer contracts for fentanyl citrate vials that bypass traditional wholesale distribution tiers. Parma's pharmaceutical manufacturing corridor supplies active pharmaceutical ingredients to formulators serving this high-volume hospital segment.
Veneto
Home hospice networks in Verona and Padua are consolidating purchasing decisions through regional consortium structures that displace fragmented municipal procurement. These aggregators negotiate directly for transdermal and sublingual portfolios, creating alternative access channels outside hospital pharmacy committees. The regional health authority's integrated care organizations now control formulary decisions for terminal patients discharged to residential settings.
Tuscany
Florence's geriatric care infrastructure drives demand for compliance-optimized delivery modes as the regional population ages faster than northern counterparts. Community-based nursing services have gained decentralized purchasing authority for long-therapy opioid protocols. The regional health authority is piloting telemedicine-enabled adherence verification for patch-based pain management in rural provinces.
Campania
Naples exhibits morphine consumption rates per capita that lag Lombardy by substantial margins, suggesting latent demand for education-driven formulary expansion. The national pharmaceutical regulator's prescription tracking systems have limited penetration in peripheral provinces where pain specialist workforce scarcity constrains protocol rollout. Regional health authorities are targeting this underpenetration through academic detailing programs and centralized procurement incentives.
Italy Opioids Market Competitive Landscape
Swiss and German producers anchor the premium formulation tier; Israeli and Indian specialists hold positions in generic injectable supply. The vendor base concentrates around three strategic poles: transdermal patch innovators with polymer expertise, sustained-release tablet manufacturers with hospital tender access, and injectable formulators with cold chain distribution capabilities. Market structure favors incumbents with established AIFA reimbursement dossiers over new entrants facing extended pharmacovigilance documentation timelines. Dominant competitive moves include direct negotiation with regional health authority consortiums and backward integration into active pharmaceutical ingredient sourcing.
Within the transdermal innovation tier, Mundipharma and Grünenthal occupy positions defined by adhesive polymer expertise and chronic pain center relationships. Among diversified pharmaceutical conglomerates, Johnson & Johnson and Pfizer exemplify scale-driven archetypes with portfolio breadth spanning sustained-release technologies and hospital contract leverage. Teva Pharmaceuticals represents the generic-specialist position, anchoring injectable supply to oncology wards through cost-competitive manufacturing economics.
| Leading Market Players |
|---|
| Mundipharma |
| Grünenthal |
| Purdue Pharma |
| Teva Pharmaceuticals |
| Mallinckrodt Pharmaceuticals |
| Hikma Pharmaceuticals |
| Johnson & Johnson |
| Pfizer |
| Sun Pharmaceutical Industries |
| Others |
Pricing and Supply Chain Analysis
Regional health authority procurement consolidation across Lombardy and Emilia-Romagna is forcing manufacturers to reconfigure distribution networks toward direct-contract models that compress wholesale margins while elevating price transparency for transdermal and sustained-release portfolios.
Pricing Analysis
Capacity additions in South Asian API manufacturing clusters are reshaping price floors for fentanyl citrate and oxycodone base, intensifying cost competition in generic injectable segments. Three-tier pricing structure across premium polymer-matrix patches, standard sustained-release tablets, and economy immediate-release generics dominates hospital tender negotiations. Pricing pressure stems from AIFA reimbursement ceiling compression and regional consortium bargaining leverage. Home care agencies exhibit highest price sensitivity due to budget-constrained municipal funding, while academic medical centers prioritize clinical outcomes over unit cost.
Supply Chain Analysis
EMA Good Manufacturing Practice certification and AIFA import authorization requirements gate market access for API suppliers and finished dose formulators. Active pharmaceutical ingredient production concentrates in India, China, and selected Swiss manufacturing sites. Fentanyl synthesis depends on specialized phenylpiperidine precursor chemicals, specialized polymer substrates for transdermal matrices, and cold chain infrastructure for injectable formulations. Single-source vulnerability in South Asian API clusters exposes formulators to geopolitical disruption and regulatory inspection delays. Distribution runs through regional health authority pharmaceutical purchasing consortia that consolidate hospital and hospice network procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Transdermal patch adoption in northern Italian pain centers creates margin-expansion headroom as polymer-formulation expertise commands premium pricing against commoditized oral generic competition.
For Market Incumbents: Anchor formulary position through backward integration into API sourcing for fentanyl and oxycodone base, reducing exposure to South Asian supply volatility. Deepen relationships with Veneto and Tuscany regional consortiums before home hospice purchasing consolidation completes. Counter non-opioid substitution threats by co-developing combination therapy protocols with academic medical centers. For New Entrants and Emerging Players: Capture white space in Campania and Sicily through education-driven detailing programs targeting pain specialist workforce scarcity. Penetrate the telemedicine-enabled adherence verification segment by partnering with Tuscany's pilot remote monitoring platforms. Pursue go-to-market positioning as a regional consortium direct supplier, bypassing established wholesale distribution tiers. For Investors and Strategic Acquirers: Asymmetric upside sits with transdermal patch specialists possessing adhesive polymer expertise and established AIFA reimbursement dossiers. Long-term viability hinges on regulatory compliance infrastructure rather than manufacturing scale alone. Watch for AIFA morphine-equivalent ceiling adjustments as the primary demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Regional Consortium Direct Contracting | Bypasses wholesale tiers to secure formulary access in Veneto and Tuscany hospice networks. |
| Backward Integration into API Sourcing | Reduces South Asian supply concentration risk for fentanyl citrate and oxycodone base. |
| Telemedicine Adherence Platform Partnership | Enables margin-rich transdermal prescriptions outside institutional settings in rural provinces. |
| Combination Therapy Reimbursement Dossier | Positions fixed-dose products within emerging AIFA opioid-adjuvant protocol thresholds. |
| Pain Specialist Education Program | Addresses workforce scarcity constraints limiting protocol rollout in Campania and Sicily. |
Research Methodology
Direct dialogue with regional health authority procurement directors, hospital pharmacy committee chairs, palliative care physicians, and AIFA regulatory affairs specialists grounded qualitative insights. Secondary validation drew from EMA pharmacovigilance databases, AIFA reimbursement bulletins, regional health authority pharmaceutical purchasing records, and hospital formulary listings. Bottom-up demand modeling triangulated against top-down market sizing across the analysis window.
Segmented outputs across product type, application, delivery mode, and end user dimensions informed the analytical framework throughout the projection horizon. CAGRs derived from patient population growth trajectories, regional hospice bed expansion rates, and AIFA prescription volume trends. Forecast inputs incorporated morphine-equivalent dosing ceiling policy scenarios and transdermal patch adoption curve assumptions.
EMA regulatory inspection delays, AIFA reimbursement threshold revisions, and API supply chain disruptions are the dominant revision risks to modeled assumptions. A model refresh is warranted upon material change in regional health authority procurement consolidation pace or AIFA morphine-equivalent policy adjustment.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Primary Biliary Cirrhosis Drug Market
Pharmaceuticals
Quinolones Market
Pharmaceuticals
Global Chickenpox Vaccine Market
Pharmaceuticals
Propofol Market
Pharmaceuticals
Global Fluorouracil (5FU) Market
Pharmaceuticals
Asia-Pacific GLP 1 Agonist Market
Pharmaceuticals
Oral Vaccines Market
Pharmaceuticals
Calcimimetic Market
Pharmaceuticals
Carglumic Acid Market
Pharmaceuticals
Mycoses Treatment Market
Pharmaceuticals
Veterinary Insulin Drugs Market
Pharmaceuticals
Angiopoietin Inhibitors Therapeutic Market
Pharmaceuticals
Hepatitis B Treatment Market
Pharmaceuticals
Pharmaceuticals Lipids Market
Pharmaceuticals
Chronic Obstructive Pulmonary Disease Drugs Market
Pharmaceuticals
Hydroxycarbamide Market