
 Simvastatin Market | 2026-2036
Simvastatin Market Size, Share, and Industry Trends Forecast 2026-2036
Simvastatin Market Analysis
Active pharmaceutical ingredient chemist availability is reorganizing production economics for statin manufacturers across emerging supply hubs. Pfizer Inc. sustains brand equity through legacy Lipitor positioning while maintaining simvastatin portfolio depth. Teva Pharmaceutical Industries Ltd. anchors generic volume leadership through vertically controlled API-to-tablet manufacturing. Aurobindo Pharma Ltd. differentiates via USFDA-inspected facilities and aggressive ANDA filing rates for cardiovascular portfolios.
Simvastatin is a synthetic lipid-lowering agent derived from fermentation of Aspergillus terreus, functioning as a competitive inhibitor of HMG-CoA reductase to reduce hepatic cholesterol synthesis; standard oral tablets contain 5 mg to 80 mg doses with specified dissolution profiles per USP monographs. Tablet formulations dominate volume shipments due to established reimbursement pathways and patient compliance familiarity, while extended-release variants capture niche premium positioning where gastrointestinal tolerability limits immediate-release adoption. Hyperlipidemia therapy applications anchor demand stability, though preventive care segments are gaining script volume as cardiovascular risk screening protocols expand in primary care settings.
FDA bioequivalence requirements under 21 CFR 320 and USP dissolution standards govern generic market entry timelines and manufacturing investment decisions. EMA's MDR and REACH frameworks shape API import compliance for European finished-dose supply chains. India's CDSCO and BIS standards coordinate with DGFT export incentives to accelerate facility upgrades for regulated-market shipments. Stakeholders must monitor evolving pharmacovigilance signal requirements for statin-associated muscle symptoms, as regulatory label revisions could reshape prescribing patterns and formulary positioning across key reimbursement markets.
Market Dynamics
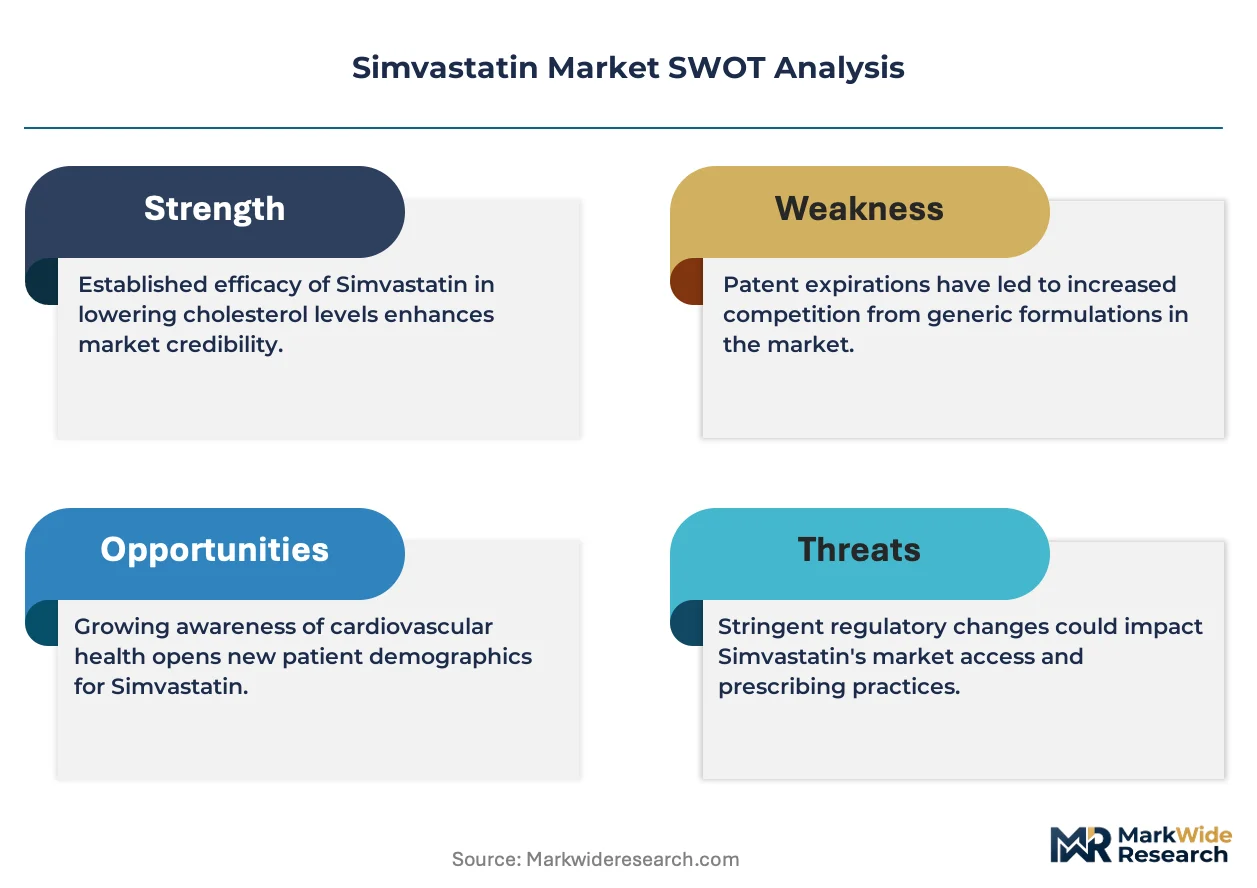
Generic substitution protocols in hospital procurement channels are compressing branded margins while accelerating volume throughput for API-to-tablet manufacturers with USFDA-inspected facilities.
Growth Catalysts
- EMA MDR compliance deadlines:European regulatory alignment is forcing facility upgrades among Indian API exporters, creating quality-tier separation that rewards CDSCO-certified manufacturers with preferential tender access.
- Preventive care protocol expansion:Cardiovascular risk screening programs in primary care settings are extending statin therapy to pre-symptomatic populations, broadening addressable patient pools beyond established hyperlipidemia segments.
- Hyderabad-Visakhapatnam manufacturing corridor:Concentrated fermentation capacity and BIS-standard laboratory infrastructure are reducing batch-to-batch variability for Aspergillus terreus-derived API supply.
Market Restraints
- Fermentation input volatility:Soybean meal and corn steep liquor prices fluctuate with agricultural commodity cycles, compressing margin predictability for statin API producers.
- Single-source dependency for high-purity intermediates:Lovastatin-derived starting material supply concentrates among three Indian manufacturers, creating bottleneck vulnerability for downstream simvastatin synthesis.
- REACH framework complexity:ECHA registration requirements for API intermediates extend European market entry timelines by 18-24 months for new manufacturing entrants.
Strategic Opportunities
- DGFT export incentive capture:India's pharmaceutical PLI scheme and duty drawback structures reward capacity expansion for regulated-market shipments with 6-10% cost offsets.
- Extended-release formulation development:Gastrointestinal tolerability limitations in immediate-release tablets create white space for modified-release variants in statin-intolerant patient segments.
- Direct hospital contracting models:Bypassing wholesale distribution through tender-based supply agreements is capturing volume commitments from integrated delivery networks in the United States.
Industry Challenges
- Analytical method transfer bottlenecks:USP dissolution testing protocol validation requires 12-18 month stability studies, delaying ANDA approval timelines for new generic entrants.
- Pharmacovigilance signal management:Statin-associated muscle symptom reporting thresholds under 21 CFR 314.80 are intensifying post-market surveillance costs and label revision risks.
- Legacy equipment retrofit requirements:Continuous manufacturing transition demands capital deployment for fermentation-to-isolation process redesign, straining mid-cap manufacturer balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Simvastatin Market |
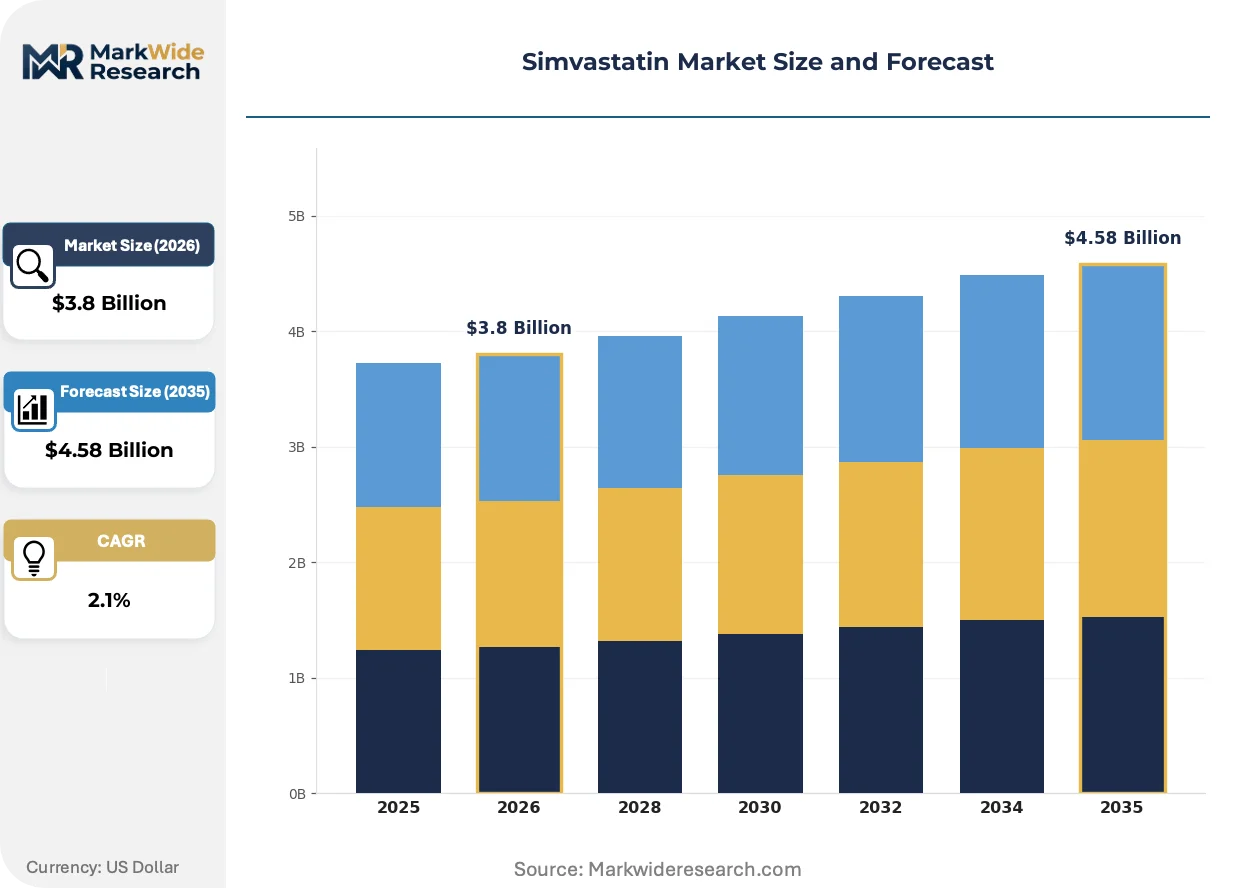
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $4.58 Billion |
| CAGR (2026 – 2036) | 2.1% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Oral Suspension, Injectable, Extended-Release End User: Hospitals, Clinics, Pharmacies, Home Healthcare Therapy Area: Cardiology, Diabetes Management, Preventive Care, Hyperlipidemia Packaging Type: Blister Packs, Bottles, Ampoules, Sachets |
| Companies Covered | Pfizer Inc., Merck & Co., Inc., Teva Pharmaceutical Industries Ltd., AstraZeneca, Aurobindo Pharma Ltd., Sun Pharmaceutical Industries Ltd., Novartis AG, GlaxoSmithKline Plc., Biocon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Simvastatin Market Emerging Trajectories
Process analytical technology integration is reshaping quality assurance economics, while regulatory data integrity enforcement and channel consolidation are compressing traditional competitive moats across the value chain.
Continuous flow chemistry for statin synthesis is supplanting batch fermentation in greenfield API facilities. Teva Pharmaceutical Industries and Aurobindo Pharma are piloting microreactor systems at Hyderabad sites to reduce solvent consumption and improve yield consistency. This technology shift is enabling real-time release testing that compresses batch release cycles from weeks to days.
FDA's enhanced bioequivalence guidance under 21 CFR 320.24 is tightening dissolution profile matching requirements for generic simvastatin tablets. The industrial consequence is elevated R&D investment in formulation science to achieve Q1/Q2 sameness with reference listed drugs. First-to-file ANDA sponsors with demonstrated bioequivalence are securing 180-day exclusivity windows that block subsequent entrants.
Hospital system procurement consolidation is displacing independent pharmacy purchasing across the United States. Integrated delivery networks representing 40+ facilities are centralizing cardiovascular formulary decisions under pharmacy benefit managers. This concentration is most visible in the Midwest and Southeast regions, where Catholic health initiatives and for-profit chains are aggregating volume for price leverage.
Simvastatin Market Segmentation
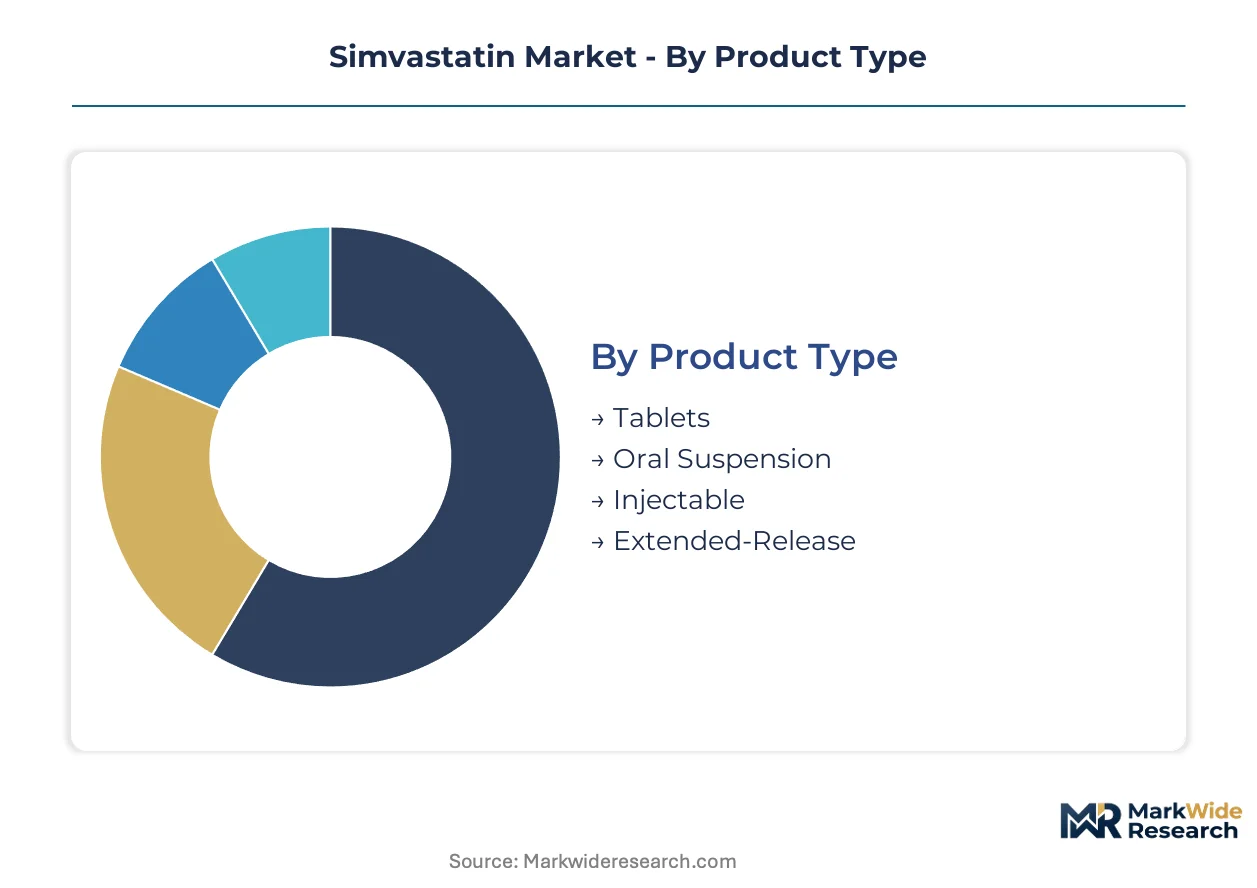
Simvastatin market segmentation reveals distinct channel economics where tablet formulations dominate procurement tenders while extended-release variants capture premium positioning through specialty pharmacy networks. Understanding segment flow through hospital formularies versus retail channels determines margin capture for API-to-tablet manufacturers.
Product Type:
Channel mix varies sharply by formulation: tablets flow through centralized hospital procurement, extended-release through specialty pharmacies, oral suspension through pediatric clinics, and injectable through institutional critical care.
- Tablets:Standard oral solid dosage containing 5 mg to 80 mg simvastatin with USP-specified dissolution profiles. Hospital procurement channels in India and the United States concentrate volume demand where generic substitution protocols accelerate throughput for USFDA-inspected manufacturers.
- Extended-Release:Modified-release matrix formulations designed for gastrointestinal tolerability in statin-intolerant populations. Specialty pharmacy distribution in Germany and France captures premium pricing where EMA MDR compliance creates quality-tier separation.
- Oral Suspension:Liquid formulation for pediatric and geriatric patients with dysphagia. Compounding pharmacies in Canada and Australia handle most dispensing.
- Injectable:Intravenous lipid emulsion for acute coronary syndrome settings. Critical care units in tertiary hospitals represent concentrated demand.
By volume, Tablets leads. By growth pace, Extended-Release is ahead.
End User:
Customer type determines contracting structure: hospitals negotiate tender-based volume commitments, clinics manage physician-directed prescribing, pharmacies handle reimbursement-driven dispensing, and home healthcare coordinates long-term adherence programs.
- Hospitals:Integrated delivery networks centralizing cardiovascular formulary decisions under pharmacy benefit managers. Catholic health initiatives in the United States Midwest aggregate 40+ facility purchasing for price leverage.
- Clinics:Primary care settings where cardiovascular risk screening protocols expand statin therapy to pre-symptomatic populations. India's National Health Mission clinics drive rural access.
- Pharmacies:Retail and mail-order channels governed by reimbursement tiering. Germany's Apotheken network maintains strict generic substitution rules.
- Home Healthcare:Long-term adherence management for chronic hyperlipidemia patients. Japan's visiting nurse associations coordinate polypharmacy compliance.
Hospitals command the largest volume share; home healthcare shows the steepest expansion trajectory as aging-in-place models proliferate.
Therapy Area:
Application focus shapes regulatory investment: cardiology requires extensive outcome data, preventive care demands population health economics, diabetes management needs combination therapy approvals, and hyperlipidemia anchors established reimbursement pathways.
- Cardiology:Secondary prevention post-acute coronary syndrome with aggressive LDL targets. German and Italian hospital cardiology departments drive high-dose prescribing.
- Preventive Care:Primary prevention in intermediate-risk populations identified through expanded screening. UK's NHS Health Check program extends statin eligibility.
- Diabetes Management:Comorbidity protocols where statins accompany metformin or insulin regimens. Endocrinology clinics in Brazil and Mexico concentrate demand.
- Hyperlipidemia:Established diagnosis with familial or acquired lipid disorders. Lipid specialist practices in the United States and Switzerland maintain brand loyalty.
Hyperlipidemia retains the deepest volume base; preventive care is climbing the fastest as risk calculators expand eligible populations.
Packaging Type:
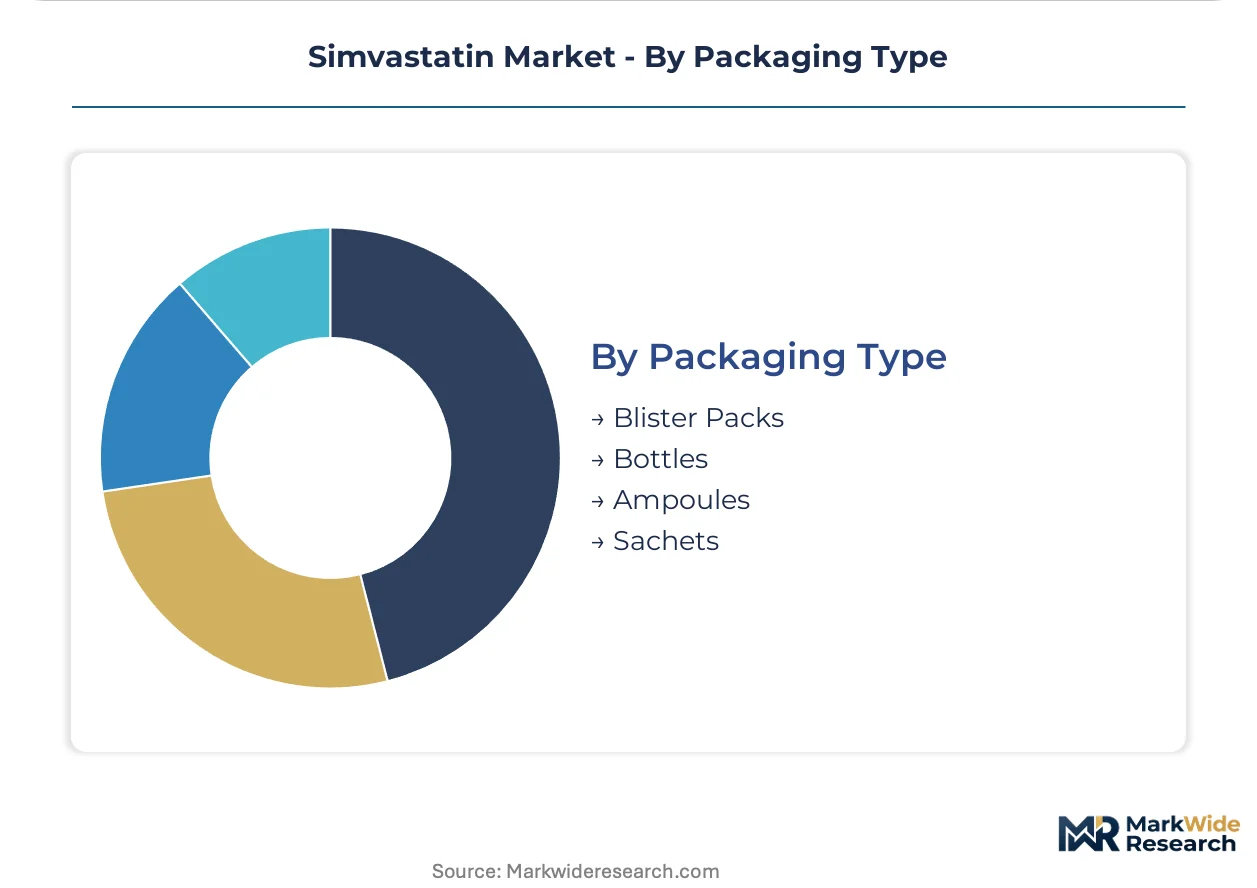
Packaging economics align with supply chain configuration: blister packs suit high-volume retail, bottles serve institutional dispensing, ampoules protect sterile injectable integrity, and sachets enable emerging market affordability.
- Blister Packs:Unit-dose aluminum-PVC configurations supporting adherence monitoring and retail pharmacy automation. India's domestic market and African export shipments favor this format.
- Bottles:HDPE containers with desiccant for 30-90 count tablets. Hospital central fill pharmacies in the United States prefer bulk packaging.
- Ampoules:Glass or polymer sterile containers for injectable lipid emulsions. Critical care supply chains in Japan and South Korea require cold-chain integrity.
- Sachets:Single-dose foil laminates for oral suspension powder. Southeast Asian and Latin American markets prioritize cost minimization.
Blister packs dominate unit volume; ampoules command the highest per-unit value as sterile manufacturing requirements constrain supply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Simvastatin consumption patterns diverge sharply across geographies: the United States favors high-dose tablet regimens through integrated delivery networks, while India channels volume through API export corridors serving regulated markets, and European markets segment by EMA MDR compliance tiers.
United States
Hospital procurement consolidation drives volume concentration through Catholic health initiatives and for-profit chains aggregating 40-plus facility purchasing. FDA bioequivalence standards under 21 CFR 320 govern generic substitution protocols. The Midwest and Southeast regions centralize cardiovascular formulary decisions under pharmacy benefit managers.
India
API manufacturing clusters in Hyderabad and Visakhapatnam supply finished-dose exports to regulated markets. CDSCO certification aligns with DGFT export incentives rewarding facility upgrades. The Hyderabad-Visakhapatnam corridor concentrates fermentation capacity with BIS-standard laboratory infrastructure reducing batch variability.
Germany
The Apotheken network maintains strict generic substitution rules channeling tablet volume through retail pharmacy automation. EMA MDR compliance deadlines force quality-tier separation among API suppliers. Bavaria and North Rhine-Westphalia anchor hospital procurement centralization for cardiovascular therapeutics.
Japan
Visiting nurse associations coordinate long-term adherence programs for aging-in-place hyperlipidemia patients. PMDA pharmacovigilance requirements intensify post-market surveillance for statin-associated muscle symptoms. The Kanto region around Tokyo concentrates critical care demand for injectable lipid emulsion formulations.
Brazil
Endocrinology clinics in São Paulo and Rio de Janeiro concentrate demand for diabetes management protocols combining statins with metformin regimens. ANVISA registration timelines extend market entry for new generic entrants. The Southeast region drives script volume through expanded cardiovascular risk screening in primary care settings.
Simvastatin Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with vertical control over API-to-tablet manufacturing separating price-competitive volume players from premium-positioned innovators. The market structure rewards backward integration into fermentation capacity and USFDA-inspected facility networks. Three archetypes dominate: legacy brand holders maintaining portfolio depth, vertically controlled generic manufacturers, and API-focused exporters with aggressive ANDA filing rates. Competitive moves center on capacity expansion in Indian manufacturing corridors and strategic partnerships securing high-purity intermediate supply.
Among legacy pharmaceutical conglomerates, Pfizer Inc. and Merck & Co., Inc. occupy positions representing brand equity preservation alongside generic portfolio participation. Teva Pharmaceutical Industries Ltd., Aurobindo Pharma Ltd., and Sun Pharmaceutical Industries Ltd. exemplify the vertically integrated specialist tier with API-to-tablet control and USFDA-inspected facility networks. These five entities collectively represent the competitive spectrum from originator heritage to emerging-market export specialization.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Merck & Co., Inc. |
| Teva Pharmaceutical Industries Ltd. |
| AstraZeneca |
| Aurobindo Pharma Ltd. |
| Sun Pharmaceutical Industries Ltd. |
| Novartis AG |
| GlaxoSmithKline Plc. |
| Biocon |
| Others |
Supply Flow & Price Mechanics
Eighteen-to-twenty-four month REACH registration timelines for API intermediates compress inventory turnover and amplify pricing power for ECHA-registered manufacturers serving European hospital networks. This lead-time band concentrates procurement decisions on suppliers with pre-validated regulatory dossiers, creating tiered access economics that separate incumbent API-to-tablet producers from aspirant entrants.
Pricing Analysis
Long-term offtake contracts dominate hospital procurement channels, with three-tier pricing structure across premium, standard, and economy levels separating USFDA-inspected manufacturers from CDSCO-certified regional suppliers and non-certified commodity producers. Price differentiation rests on bioequivalence validation status and dissolution profile consistency. Cost compression in the economy tier intensifies as Indian API exporters expand fermentation capacity. Integrated delivery networks exhibit highest price sensitivity; specialty pharmacies serving statin-intolerant populations show lowest.
Supply Chain Analysis
Strategic stockpiling of lovastatin-derived starting materials prevails among downstream simvastatin manufacturers, mitigating single-source vulnerability concentrated across three Indian intermediate suppliers. API production anchors in India and China, with finished-dose tableting in the United States and Germany. Soybean meal and corn steep liquor feed fermentation economics. Tariff exposure on Chinese-sourced raw materials threatens margin stability. Distribution runs through wholesale channels to hospital central fill pharmacies and retail automation networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The simvastatin market functions as a defensive-moat structure where regulatory entrenchment—specifically USFDA inspection status and validated ANDA portfolios—creates switching costs that protect incumbent volume positions from price-only competition.
For Market Incumbents: Fortify backward integration into Aspergillus terreus fermentation capacity at Hyderabad-Visakhapatnam corridor sites to capture DGFT export incentives and insulate against lovastatin intermediate supply bottlenecks. Deepen hospital system partnerships through direct tender-based contracting models that bypass wholesale distribution layers. Prioritize extended-release formulation R&D to serve statin-intolerant patient segments where premium positioning remains defensible against immediate-release commoditization. For New Entrants and Emerging Players: Gastrointestinal tolerability-focused patient support services represent an underserved service-layer gap where incumbent manufacturers under-invest. Target specialty pharmacy networks in Germany and France for modified-release simvastatin distribution, leveraging EMA MDR compliance deadlines to position as quality-tier alternatives. Pursue compounding pharmacy relationships for oral suspension formulations serving pediatric and geriatric dysphagia populations in Canada and Australia. For Investors and Strategic Acquirers: Carve-out targets emerge from mid-cap pharmaceutical conglomerates divesting cardiovascular portfolios to refocus on oncology or immunology. Five-to-ten year viability favors API-to-tablet manufacturers with captive fermentation capacity and established USFDA inspection histories. Monitor pharmacovigilance signal thresholds for statin-associated muscle symptoms under 21 CFR 314.80 as the inflection indicator for label revision risk and formulary repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Manufacturing Transition | Microreactor adoption at Hyderabad sites reduces solvent consumption and enables real-time release testing under FDA guidance. |
| Extended-Release Formulation Development | Modified-release matrix designs capture premium positioning in statin-intolerant populations across German specialty pharmacy networks. |
| Direct Hospital Contracting Models | Bypassing wholesale distribution secures volume commitments from Midwest and Southeast integrated delivery networks. |
| EMA MDR Compliance Investment | Facility upgrades create quality-tier separation that rewards CDSCO-certified manufacturers with preferential European tender access. |
| API Export Capacity Expansion | DGFT incentive capture through PLI scheme participation offsets 6-10% of regulated-market shipment costs for Indian manufacturers. |
Methodological Framework
A standing panel of regulatory affairs leads, hospital procurement managers, API manufacturing executives, and formulary directors provided ongoing calibration across primary interview cycles, with secondary validation drawing from FDA ANDA filings, EMA MDR submission databases, USP dissolution monographs, and Indian DGFT export incentive records. Bottom-up volume modeling triangulated against top-down pharmaceutical trade flow analysis.
Consistency checks validated volume and value outputs against external benchmarks across the analysis window, with segmentation modeling spanning dosage form, therapy area, end-user channel, and regional regulatory cluster dimensions. CAGRs derived from fitted growth curves incorporating fermentation capacity expansion timelines, hospital procurement consolidation patterns, and preventive care protocol penetration rates.
Underlying assumptions cover bioequivalence approval timelines, agricultural commodity input stability, and REACH registration progression, with deviation risk concentrated in pharmacovigilance signal thresholds and single-source intermediate supply disruptions. Revision becomes warranted when FDA dissolution guidance stringency or EMA MDR enforcement intensity crosses material threshold shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Pharmacy Market
Pharmaceuticals
Palonosetron Hydrochloride Market
Pharmaceuticals
Intravenous Pegloticase Market
Pharmaceuticals
Steroid-Free Nasal Sprays Market
Pharmaceuticals
Bulbospinal Muscular Atrophy Drugs Market
Pharmaceuticals
Galculus Bovis and Metronidazole Market
Pharmaceuticals
Botulinum Toxin Market
Pharmaceuticals
India Pharmaceutical Contract Sales Organizations Market
Pharmaceuticals
Hepatitis B Treatment Market
Pharmaceuticals
Global Atosiban Market
Pharmaceuticals
Zoledronic Acid Market
Pharmaceuticals
Saudi Arabia Diabetes Drugs Market
Pharmaceuticals
B7-H3 Antibody Market
Pharmaceuticals
Large Volume Parenteral (LVP) Market
Pharmaceuticals
Allergic Rhinitis Drugs Market
Pharmaceuticals
Global HER2 Antibodies Market