
 Home Menopause Testing Market | 2026-2036
Home Menopause Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Home Menopause Testing Market Analytics
FDA 510(k) de novo pathways for over-the-counter hormone diagnostics is recalibrating the cost-of-entry calculus for new entrants. Everlywell Inc. leverages its vertically integrated digital health platform to control the full consumer journey from sample collection to telehealth consultation. LetsGetChecked sustains competitive moats through ISO-certified laboratory partnerships that anchor its clinical credibility. Labcorp dominates institutional channel access, extending its diagnostic infrastructure into home-based collection workflows.
Home menopause testing comprises self-administered diagnostic systems that quantify follicle-stimulating hormone, estradiol, or luteinizing hormone levels through capillary blood, urine, or saliva matrices, typically employing lateral flow immunoassay or enzyme-linked immunosorbent assay methodologies to generate semi-quantitative or quantitative results within minutes to hours. These devices serve the commercial purpose of enabling women to identify perimenopausal or menopausal status without clinical intermediation, supporting hormone therapy decisions and lifestyle modifications. Urine test kits occupy the largest volume position due to collection simplicity and consumer familiarity, while molecular testing methods represent the fastest-growing category as PCR-based hormone metabolite detection improves specificity. Online stores capture expanding margin pools by eliminating pharmacy intermediaries and enabling subscription-based replenishment models.
FDA oversight of in vitro diagnostics, CLIA-waived status requirements, and ISO 13485 quality management standards collectively determine which products achieve commercial viability in the United States market. The Federal Trade Commission monitors advertising claims for at-home health products, constraining how manufacturers communicate diagnostic accuracy to consumers. Stakeholders must monitor evolving FDA guidance on software-as-a-medical-device classifications that could reclassify algorithmic interpretation features as regulated components.
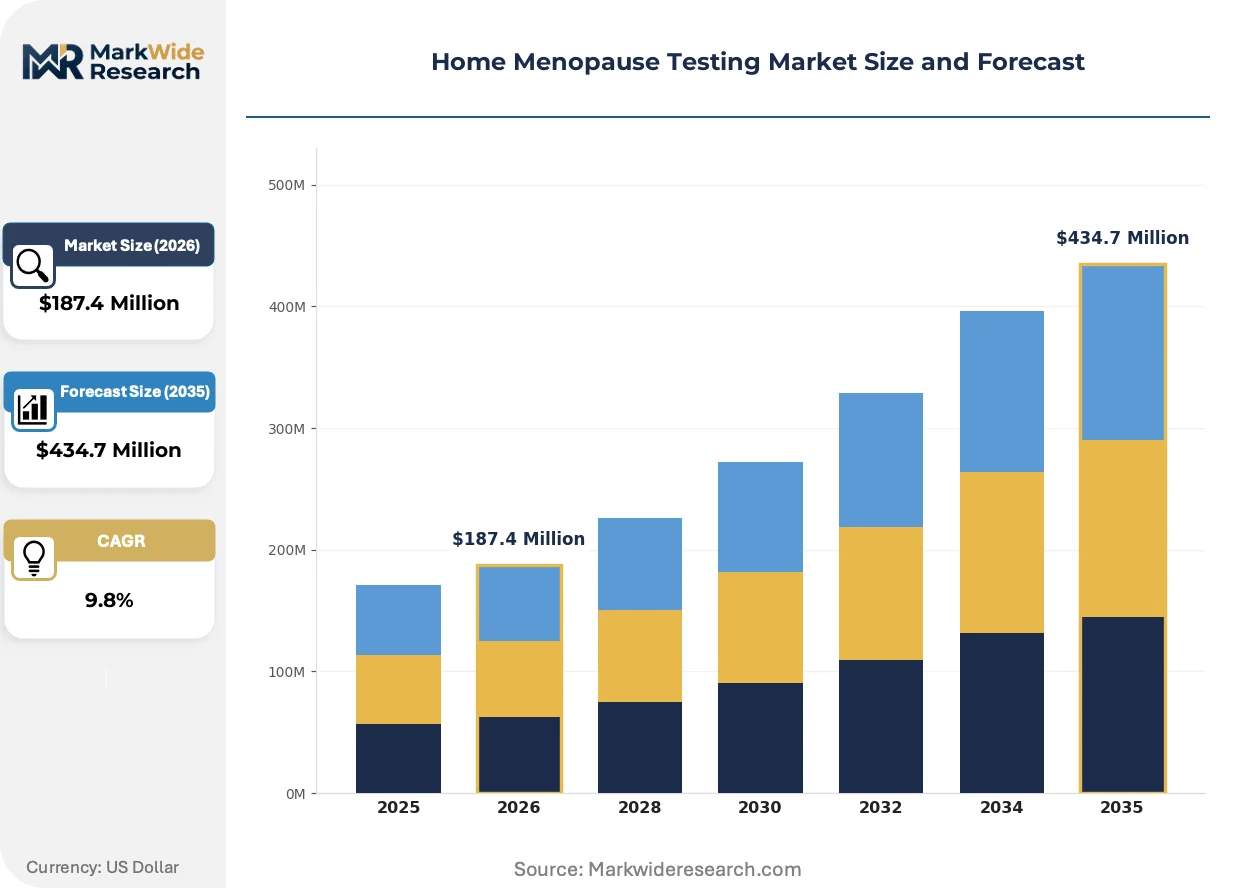
Market Dynamics
FDA 510(k) de novo clearance pathways for over-the-counter hormone diagnostics are compressing commercialization timelines from years to months, triggering a wave of new entrants armed with lateral flow immunoassay platforms and direct-to-consumer distribution models.
Growth Catalysts
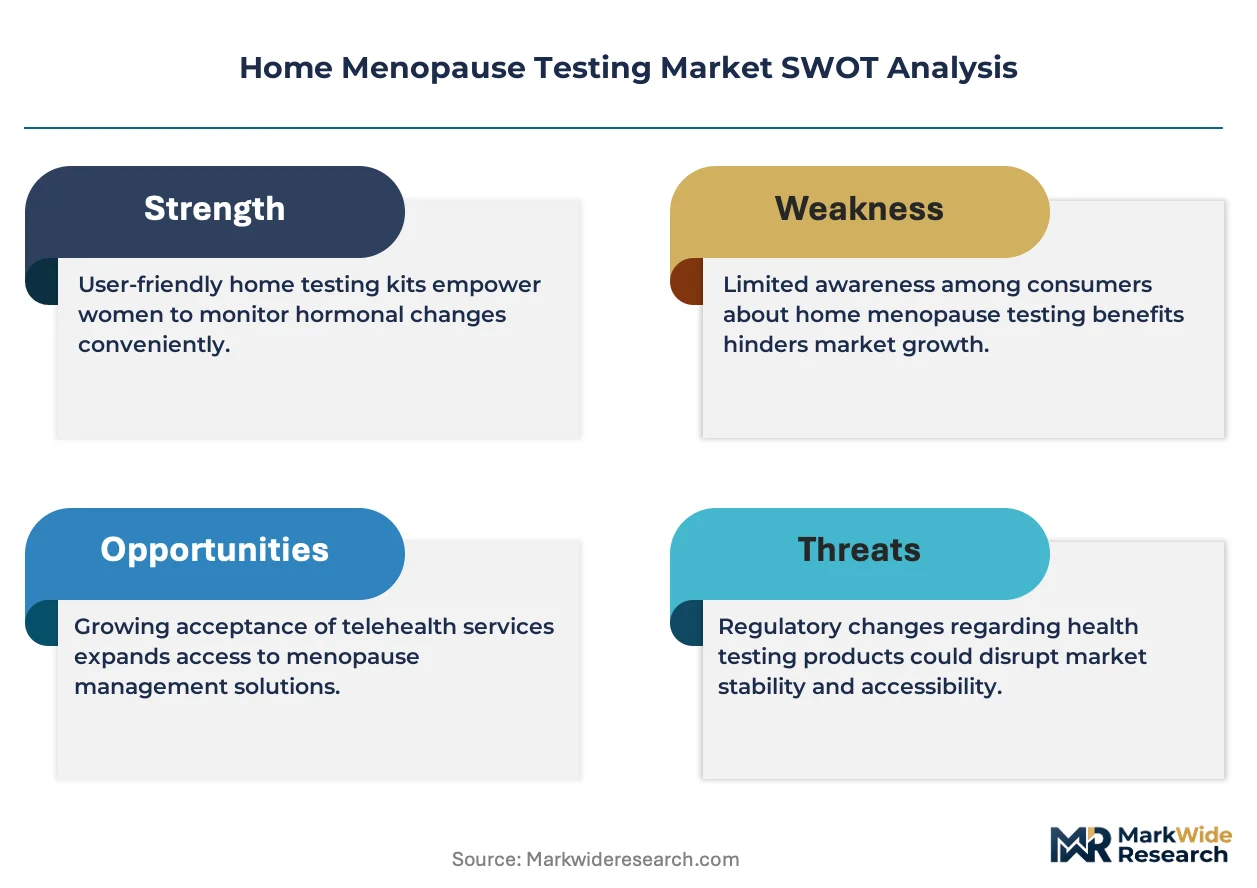
- CLIA-waived status expansion:FDA's streamlined classification for moderate-complexity testing performed outside laboratories is enabling retail pharmacy deployment of capillary blood collection devices.
- Telehealth integration:Virtual consultation platforms are absorbing diagnostic results into longitudinal care records, creating stickiness for subscription-based test replenishment.
- Saliva-based detection maturation:Enzyme-linked immunosorbent assay sensitivity improvements for estradiol quantification are eliminating venipuncture barriers for perimenopausal women.
Market Restraints
- Reference range variability:FSH and LH thresholds for menopause staging lack harmonization across CLIA-certified laboratories, producing conflicting status determinations.
- Reimbursement exclusion:CMS and commercial payers classify home hormone testing as wellness rather than diagnostic, forcing full out-of-pocket payment.
- Single-supplier enzyme dependence:Horseradish peroxidase conjugate production concentrates in Chinese contract manufacturers, exposing lateral flow kit assemblers to input volatility.
Strategic Opportunities
- Menopausal hormone therapy monitoring:Post-prescription estradiol and progesterone tracking creates recurring revenue streams beyond initial status confirmation.
- Employer wellness programs:Self-insured corporations are subsidizing at-home testing as retention tools for female employees aged 45-55.
- PCR metabolite detection:Polymerase chain reaction-based hormone metabolite quantification offers specificity advantages over immunoassay methods for complex endocrine presentations.
Industry Challenges
- ISO 13485 quality management implementation:Small device developers lack documented design control processes for FDA submission packages.
- Algorithm validation requirements:Software-as-a-medical-device classification uncertainty surrounding result interpretation apps is freezing feature roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Home Menopause Testing Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $434.7 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Urine Test Kits, Blood Test Kits, Saliva Test Kits, Combination Test Kits Distribution Channel: Retail Pharmacies, Online Stores, Supermarkets, Health Clinics End User: Individual Consumers, Healthcare Providers, Research Institutions, Wellness Centers Testing Method: Hormonal Assays, Immunoassays, Molecular Testing, Traditional Methods |
| Companies Covered | Everlywell Inc., LetsGetChecked, Labcorp, myLAB Box, Rapikit, Verisana Laboratories, Wondfo, PRIMA Lab SA, Recombigen Laboratories Pvt. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Home Menopause Testing Market Evolving Landscape
Digital health platforms are absorbing home diagnostic hardware into integrated care workflows, transforming standalone test kits into data capture nodes within subscription-based menopause management ecosystems.
Multiplexed lateral flow cassettes capable of simultaneous FSH, estradiol, and AMH quantification are rewriting the economics of perimenopausal staging. Women aged 40-50 in employer-sponsored wellness programs are adopting these panels at accelerating velocity. The technology is compressing the addressable market for single-analyte legacy devices.
FDA's evolving guidance on clinical decision support software is reclassifying algorithmic hormone interpretation as regulated medical device functionality. Manufacturers must now submit premarket notifications for smartphone apps previously treated as unregulated wellness tools. This regulatory recalibration most acutely affects direct-to-consumer brands lacking established 510(k) clearance infrastructure.
Subscription replenishment models are displacing one-time pharmacy purchases as the dominant acquisition pattern. Online stores capture margin pools formerly allocated to retail intermediaries. The United States exhibits the most advanced channel migration, with telehealth-integrated platforms commanding preferred positioning.
Home Menopause Testing Market Segmentation
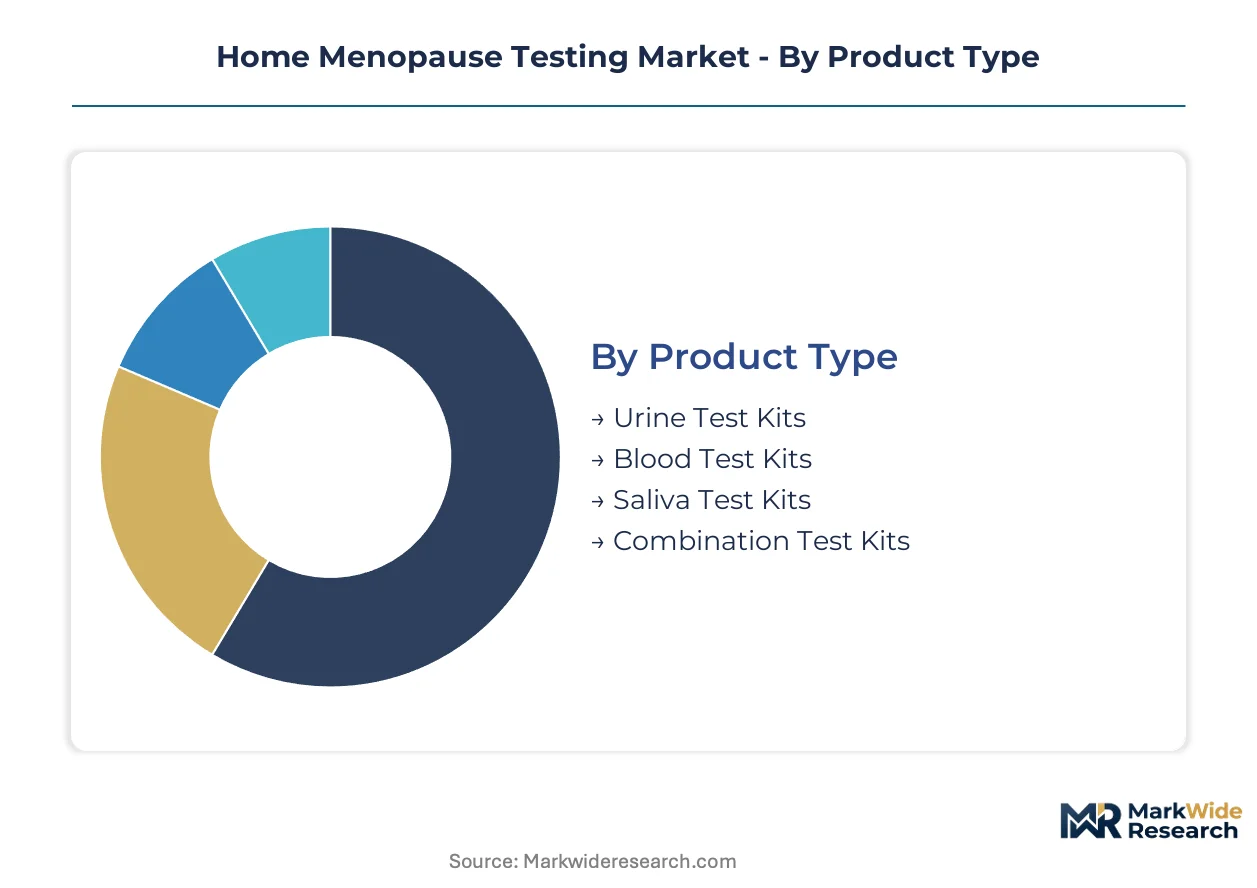
Segmentation in home menopause testing reveals how collection convenience, channel economics, and result specificity shape purchase decisions. Manufacturers calibrate R&D investments and regulatory pathways against these distinct demand profiles.
Product Type:
Collection simplicity drives initial purchase decisions, while accuracy expectations determine repeat buying and subscription retention.
- Urine Test Kits:Lateral flow immunoassay strips detect FSH surges in morning urine samples with 99% consumer completion rates. Demand concentrates in United States retail pharmacy channels where shelf visibility and pharmacist counseling reduce purchase hesitation. Medicare exclusion from reimbursement limits price elasticity among fixed-income perimenopausal women.
- Blood Test Kits:Capillary finger-stick devices quantify estradiol and AMH through CLIA-waived cartridge systems. Growth accelerates in telehealth-integrated platforms where virtual physicians order panels and interpret results within 48-hour turnaround windows.
- Saliva Test Kits:Enzyme-linked immunosorbent assay sensitivity now matches serum correlation for progesterone quantification.
- Combination Test Kits:Multiplexed cassettes simultaneously measure FSH, estradiol, and LH from single samples.
Urine test kits lead on scale; combination test kits lead on momentum.
Distribution Channel:
Margin capture and customer lifetime value separate channel strategies, with intermediation costs dicting pricing flexibility.
- Online Stores:Direct-to-consumer platforms eliminate 35-40% pharmacy markups while enabling subscription replenishment algorithms tied to cycle tracking apps. United States consumers aged 35-50 in metropolitan markets show highest conversion rates for bundled test-plus-consultation packages.
- Retail Pharmacies:CVS, Walgreens, and Rite Aid locations provide immediate gratification and pharmacist-mediated trust for first-time buyers. Foot traffic dependency constrains growth in rural ZIP codes with pharmacy deserts.
- Supermarkets:Mass merchandiser placement in feminine hygiene aisles captures impulse purchases during routine shopping trips.
- Health Clinics:Employer-sponsored onsite wellness programs subsidize testing for workforce retention objectives.
Online stores command the steepest expansion trajectory; retail pharmacies retain the largest transaction volume.
End User:
Information sophistication and clinical integration requirements segment users by how they act on results.
- Individual Consumers:Self-directed women aged 45-55 seeking hormone therapy initiation or lifestyle modification guidance represent the addressable core. United States direct-to-consumer wellness spending per capita exceeds comparable markets by 3:1 margins.
- Healthcare Providers:OB-GYN practices deploy home collection to reduce in-office phlebotomy bottlenecks. Reimbstruction friction for remote patient monitoring codes limits adoption in fee-for-service models.
- Research Institutions:Longitudinal menopause studies require standardized biomarker collection across decentralized populations.
- Wellness Centers:Functional medicine clinics integrate hormone panels into comprehensive metabolic assessments.
Individual consumers anchor volume; healthcare providers are gaining share fastest.
Testing Method:
Specificity thresholds and regulatory classification burden determine which methodologies achieve commercial viability.
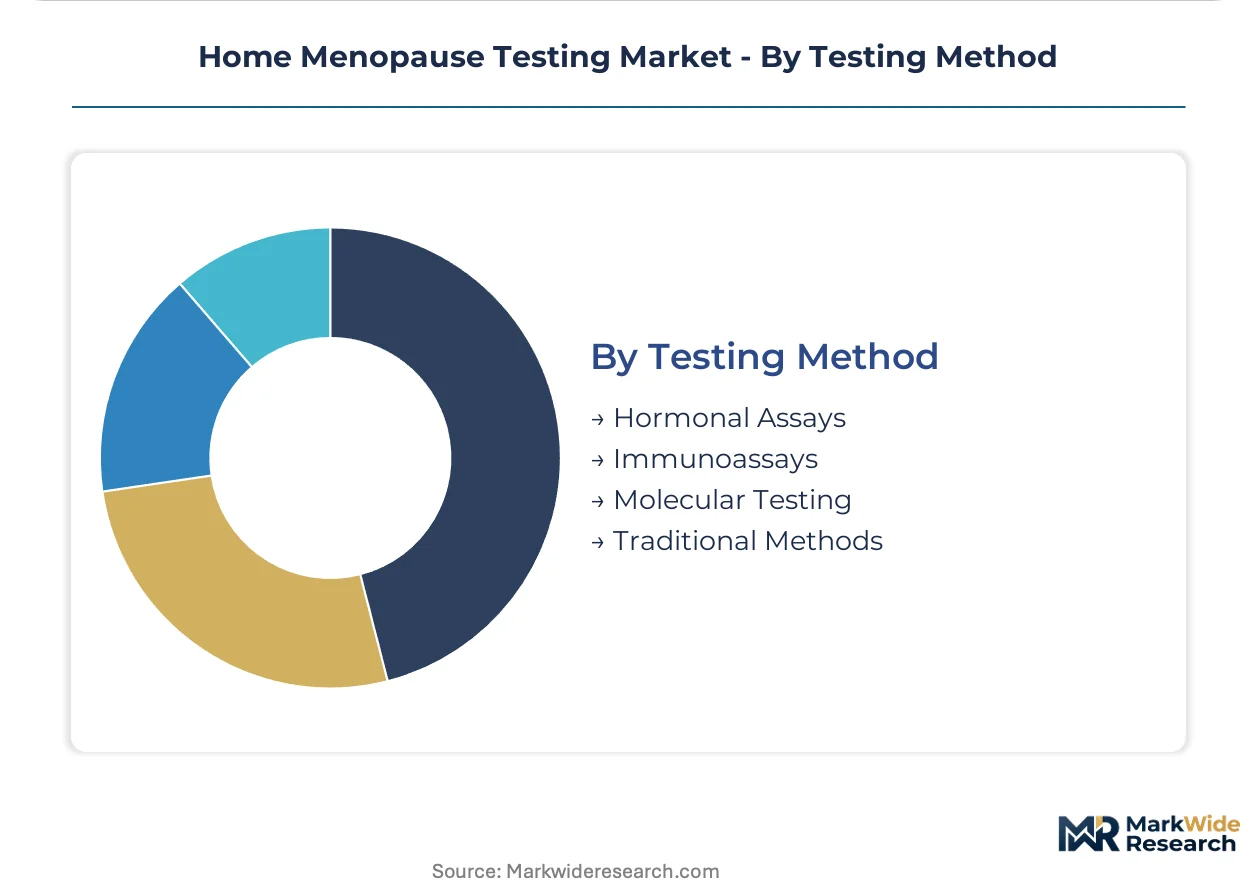
- Hormonal Assays:Colorimetric endpoint detection of FSH and estradiol dominates entry-level price tiers. CLIA-waived status under FDA 510(k) pathways accelerates market entry for lateral flow developers.
- Immunoassays:Chemiluminescence and ELISA platforms deliver quantitative results correlating with laboratory reference standards. Demand concentrates in subscription services targeting hormone therapy monitoring.
- Molecular Testing:PCR-based hormone metabolite detection eliminates cross-reactivity artifacts in complex endocrine presentations. FDA de novo pathway uncertainty delays commercialization timelines.
- Traditional Methods:Basal body temperature tracking and symptom diary apps persist among price-sensitive segments.
Immunoassays dominate current revenue; molecular testing shows the strongest forward momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized laboratory technicians and telehealth platform developers cluster in metropolitan innovation corridors across five key countries. Workforce density in digital health infrastructure and CLIA-certified laboratory networks shapes regional competitive positioning.
United States
FDA 510(k) de novo pathways for over-the-counter hormone diagnostics compress commercialization timelines from years to months. The Federal Trade Commission monitors advertising claims for at-home health products, constraining manufacturer communication of diagnostic accuracy. Boston and San Francisco anchor telehealth-integrated platform development, with venture capital flows concentrating in subscription-based menopause management ecosystems.
Germany
ISO 13485 quality management certification requirements create entry barriers for small device developers lacking documented design control processes. EMA oversight of in vitro diagnostics harmonizes with national implementation of EU Medical Device Regulation standards. The Rhine-Ruhr metropolitan region hosts precision diagnostic manufacturing clusters where lateral flow immunoassay production scales for European distribution.
United Kingdom
NHS England pilot programs for remote patient monitoring create institutional demand channels for home collection workflows. Medicines and Healthcare products Regulatory Agency guidance on software-as-a-medical-device classifications affects algorithmic interpretation feature roadmaps. London's digital health corridor attracts direct-to-consumer brands seeking European market entry points post-Brexit regulatory realignment.
China
NMPA regulatory pathways for Class II medical devices determine which hormone diagnostic kits achieve domestic commercialization approval. Horseradish peroxidase conjugate production concentrates in contract manufacturing zones, exposing lateral flow kit assemblers to input volatility. The Yangtze River Delta manufacturing belt supplies enzyme-linked immunosorbent assay components to global kit assemblers.
Japan
PMDA quality standards for in vitro diagnostics mandate extensive clinical validation studies for home-use hormone quantification devices. METI industrial policy supports domestic production of high-sensitivity estradiol detection platforms. The Kansai region's precision instrumentation sector develops chemiluminescence platforms correlating with laboratory reference standards.
Home Menopause Testing Market Competitive Landscape
The competitive structure tilts toward vertically integrated digital health platforms controlling full consumer journeys from sample collection to telehealth consultation. Three archetypes dominate: direct-to-consumer brands with subscription replenishment models, clinical laboratory incumbents extending infrastructure into home-based collection, and contract manufacturers supplying lateral flow components to private-label assemblers. Strategic moves concentrate on telehealth integration partnerships and ISO-certified laboratory network expansion.
Among United States-based direct-to-consumer specialists, Everlywell Inc. and LetsGetChecked exemplify the platform-integrated archetype, while Labcorp represents the clinical infrastructure extension model. These three entities occupy positions spanning the consumer-facing and institutional channel spectrum, with each anchoring distinct competitive vectors in sample collection methodology and result interpretation delivery.
| Leading Market Players |
|---|
| Everlywell Inc. |
| LetsGetChecked |
| Labcorp |
| myLAB Box |
| Rapikit |
| Verisana Laboratories |
| Wondfo |
| PRIMA Lab SA |
| Recombigen Laboratories Pvt. Ltd. |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up diagnostic platform specialists concentrate pricing power through captive laboratory networks and subscription lock-in mechanisms, while family-owned lateral flow component suppliers in the Yangtze River Delta maintain cost discipline through multi-generational manufacturing relationships. This ownership-financing duality produces divergent margin structures: digital health platforms capture recurring revenue premiums, whereas contract manufacturers absorb commodity enzyme volatility without pricing recourse.
Pricing Analysis
Bundled test-plus-telehealth packages command premium positioning against unbundled single-analyte strips, with three-tier pricing structure across premium, standard, and economy levels separating subscription services from pharmacy retail from mass-merchandiser impulse SKUs. Price differentiation rests on ISO 13485 certification tier and telehealth integration depth. Cost compression in the economy tier is intensifying because Medicare reimbursement exclusion forces price competition among fixed-income perimenopausal women. Employer-sponsored wellness programs exhibit lowest price sensitivity; uninsured individual consumers in pharmacy deserts face highest.
Supply Chain Analysis
Regional distribution centers in the United States, Germany, and China operate hub-and-spoke patterns radiating from CLIA-certified laboratory clusters, ISO 13485 manufacturing zones, and NMPA-registered assembly facilities. Horseradish peroxidase conjugate production concentrates in Chinese contract manufacturing zones, lateral flow membrane substrates draw from Japanese precision polymer suppliers, and capillary blood collection devices source from German medical plastics specialists. Single-source enzyme dependency creates vulnerability to input volatility. Distribution runs through direct-to-consumer platforms, retail pharmacy networks, and employer wellness program administrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in home menopause testing rests on two structural levers: telehealth integration reducing customer acquisition costs and multiplexed panel adoption shifting unit economics toward premium-tier realization.
For Market Incumbents: Anticipate regulatory recalibration of software-as-a-medical-device classifications by accelerating FDA 510(k) pre-submissions for algorithmic interpretation features. Defend against direct-to-consumer entrants by deepening backward integration into CLIA-waived cartridge production and securing exclusive telehealth platform partnerships that embed testing into longitudinal care workflows. For New Entrants and Emerging Players: Launch via employer-sponsored wellness program channels where procurement decisions centralize and subsidy mechanisms neutralize price sensitivity. Target saliva-based detection white space among perimenopausal women aged 40-50 seeking venipuncture alternatives. Pursue white-label supply agreements with retail pharmacy chains lacking in-house diagnostic development capabilities. For Investors and Strategic Acquirers: Telehealth-integrated diagnostic platforms are the most active acquirer in this space, seeking to consolidate sample-to-consultation consumer journeys under single ownership. Long-term viability hinges on recurring revenue attachment rates rather than one-time test transactions. Monitor FDA de novo clearance velocity for molecular testing platforms as the inflection signal distinguishing scalable platform investments from stranded lateral flow assets.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) De Novo Clearance | Accelerates commercialization timelines for over-the-counter hormone diagnostics by compressing regulatory review from years to months. |
| Telehealth Platform Integration | Transforms standalone test kits into data capture nodes within subscription-based menopause management ecosystems. |
| Multiplexed Panel Development | Simultaneous FSH, estradiol, and AMH quantification rewrites perimenopausal staging economics and displaces single-analyte legacy devices. |
| ISO 13485 Laboratory Certification | Anchors clinical credibility for direct-to-consumer brands seeking differentiation through quality management standards. |
| Employer Wellness Program Partnership | Creates institutional demand channels subsidized by self-insured corporations targeting female employee retention. |
Research Methodology
Direct dialogue with diagnostic platform executives, CLIA laboratory directors, FDA regulatory consultants, telehealth integration specialists, and employer benefits managers grounded qualitative assessment. Secondary validation drew from FDA 510(k) filings, EMA in vitro diagnostic guidance documents, ClinicalTrials.gov menopause biomarker studies, and CMS reimbursement coding databases. Bottom-up demand modeling across consumer segments triangulated against top-down market sizing from diagnostic industry trade associations.
Bottom-up unit economics modeled pricing tiers, subscription renewal rates, and telehealth attach frequencies across the projection horizon. Segmentation dimensions included collection methodology, distribution channel, end-user archetype, and testing technology platform. CAGRs derived from installed base expansion curves and replacement cycle assumptions. Forecast inputs incorporated FDA clearance velocity scenarios and employer wellness program adoption curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under software-as-a-medical-device reclassification delays or horseradish peroxidase supply disruptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Asia-Pacific Hereditary Cancer Testing Market
Testing Services
Platelet Function Testing Market
Testing Services
Pharmaceutical Sterility Testing Market
Testing Services
Asia-Pacific Viral Clearance Market
Testing Services
Pancreatic Stone Protein Testing Market
Testing Services
Special Coagulation Tests Market
Testing Services
Global Sleep Testing Services Market
Testing Services
Industrial Radiography Testing Market
Testing Services
Service Laboratory Market
Testing Services
Adenovirus Testing Market
Testing Services
Addison Disease Testing Market
Testing Services
Rapid Test Cards Market
Testing Services
Global Bilirubin Colorimeter Assay Market
Testing Services
Anti-Nuclear Antibody (ANA) Testing Market
Testing Services
Global Coagulation Testing Market
Testing Services
Nanoparticle Drug Delivery Size and Zeta Potential Measurement Instruments Market