
 Medical Grade Sodium Hyaluronate Market | 2026-2036
Medical Grade Sodium Hyaluronate Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Grade Sodium Hyaluronate Market Analysis
Aesthetic clinics is collapsing the historical hospital-centric procurement model for medical grade sodium hyaluronate. Allergan leverages its vertically integrated dermal filler portfolio to capture premium positioning in elective procedures. LG Chem anchors East Asian supply through captive fermentation capacity and pharmaceutical-grade purification infrastructure. Galderma differentiates via cross-channel execution spanning therapeutic ophthalmology and cosmetic dermatology segments.
Medical grade sodium hyaluronate denotes non-animal stabilized hyaluronic acid meeting pharmacopeial purity thresholds exceeding 95% with endotoxin levels below 0.5 EU/mg, manufactured through microbial fermentation of Streptococcus zooepidemicus or recombinant Bacillus subtilis platforms for intra-articular, intraocular, and subcutaneous applications. The injectable product type commands the dominant value share due to higher unit economics in aesthetic and orthopedic indications, while viscous gel formulations represent the fastest-expanding segment driven by viscosupplementation adoption in ambulatory surgical centers. Ophthalmology applications retain mature volume foundations through cataract surgery adjunct use, though aesthetic treatments concentrate margin pools through direct-to-consumer channel premiums and practitioner certification requirements.
FDA biologics guidance, EMA MDR compliance pathways, and ISO 13485 quality management standards collectively elevate barriers for new entrants while mandating post-market surveillance for adverse event reporting. The FDA's 510(k) clearance framework for dermal fillers demands clinical safety datasets that extend development timelines and capital requirements for formulation innovators. Stakeholders must monitor evolving reimbursement classifications for hyaluronic acid injections across Medicare Advantage plans and European statutory health insurance systems to anticipate volume shifts between institutional and outpatient settings.
Market Dynamics
Aesthetic clinics in Seoul-Gyeonggi and comparable med-aesthetic clusters are collapsing the hospital-centric procurement model that historically dominated medical grade sodium hyaluronate distribution. Direct-to-practitioner channels now capture margin pools previously absorbed by institutional procurement offices.
Growth Catalysts
- FDA Biologics Guidance:Tightened safety datasets for dermal fillers elevate qualification barriers, concentrating volume among established manufacturers with clinical infrastructure.
- Viscosupplementation Adoption:Ambulatory surgical centers deploy hyaluronic acid gel formulations for osteoarthritis management, expanding addressable patient populations beyond aesthetic applications.
- Seoul-Gyeonggi Cluster:South Korea's med-aesthetic concentration generates practitioner certification networks that accelerate product penetration across East Asian markets.
Market Restraints
- Fermentation Input Volatility:Streptococcus zooepidemicus culture media and pharmaceutical-grade purification reagents face price instability from biologics manufacturing demand.
- East Asian Supply Concentration:Captive fermentation capacity in South Korea and China creates geographic vulnerability for non-integrated buyers in North America and Europe.
- Endotoxin Threshold Technical Ceiling:Pharmacopeial standards below 0.5 EU/mg require capital-intensive purification infrastructure that excludes mid-scale entrants.
Strategic Opportunities
- Recombinant Bacillus subtilis Platforms:Microbial expression systems eliminate animal-derived raw material dependencies while simplifying regulatory pathways in EMA jurisdictions.
- Therapeutic Ophthalmology Convergence:Cross-channel execution spanning cataract surgery adjuncts and cosmetic dermatology creates portfolio diversification for integrated manufacturers.
- ISO 13485 Certification Networks:Quality management standardization enables supplier qualification for Medicare Advantage reimbursement classifications in outpatient settings.
Industry Challenges
- Post-Market Surveillance Infrastructure:FDA adverse event reporting mandates require dedicated pharmacovigilance systems that strain emerging manufacturer capabilities.
- 510(k) Clinical Dataset Compilation:Extended development timelines for dermal filler safety documentation compresses competitive response windows.
- Practitioner Certification Complexity:Direct-to-consumer channel premiums depend on training program scalability that outpaces qualified injector supply.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Grade Sodium Hyaluronate Market |
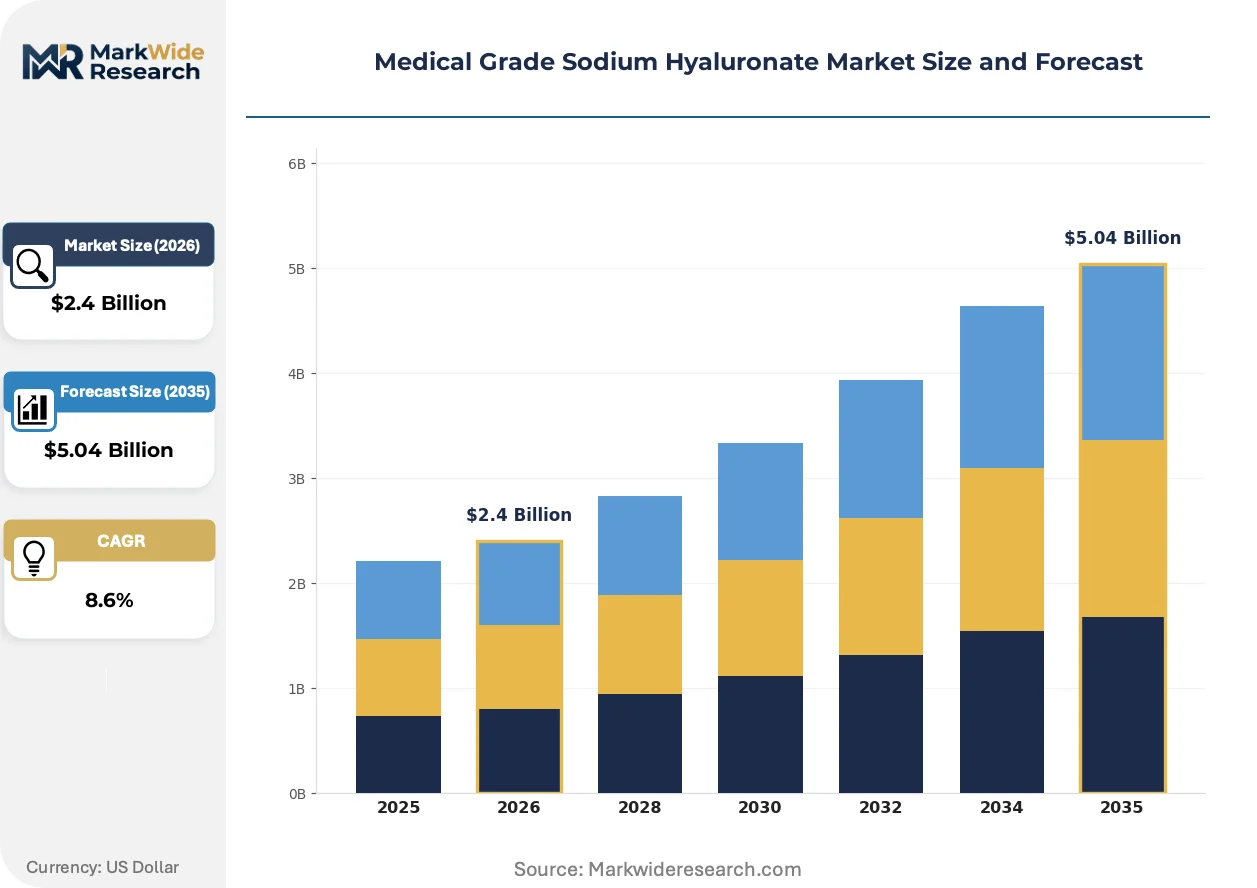
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.04 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectable, Viscous Gel, Eye Drops, Cream Application: Ophthalmology, Dermatology, Orthopedics, Aesthetic Treatments End User: Hospitals, Clinics, Research Institutions, Homecare Packaging Type: Syringes, Bottles, Ampoules, Pre-filled Pens |
| Companies Covered | Allergan, LG Chem, Galderma, Anika Therapeutics, Bausch and Lomb, Johnson and Johnson, Santen, Zydus Cadila Pharmaceuticals, Fidia Farmaceutici, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Grade Sodium Hyaluronate Market Emerging Trajectories
Recombinant microbial platforms and tightened biologics oversight are jointly restructuring manufacturing economics and competitive qualification pathways across medical grade sodium hyaluronate supply chains.
Microbial fermentation using recombinant Bacillus subtilis expression systems is decomposing the historical dominance of Streptococcus zooepidemicus-derived production. Pharmaceutical-grade manufacturers in East Asia adopt these platforms to eliminate animal-derived raw material risks and streamline endotoxin control. The shift compresses capital requirements for new entrants while enabling regulatory pathway simplification in EMA and FDA jurisdictions.
EMA MDR compliance pathways and FDA 510(k) clearance frameworks are mandating clinical safety datasets that extend development timelines for formulation innovators. These requirements elevate barriers for new market entrants while institutionalizing post-market surveillance obligations. Injectable dermal filler segments face the most pronounced timeline compression as biologics classification triggers enhanced scrutiny.
Direct-to-practitioner distribution is displacing hospital procurement offices as the dominant channel for aesthetic-grade hyaluronic acid. Aesthetic clinics in South Korea's Seoul-Gyeonggi corridor and comparable clusters now source through manufacturer-certified practitioner networks rather than institutional buyers. This channel rotation concentrates margin capture with vertically integrated suppliers while fragmenting procurement authority across independent clinic operators.
Medical Grade Sodium Hyaluronate Market Segmentation
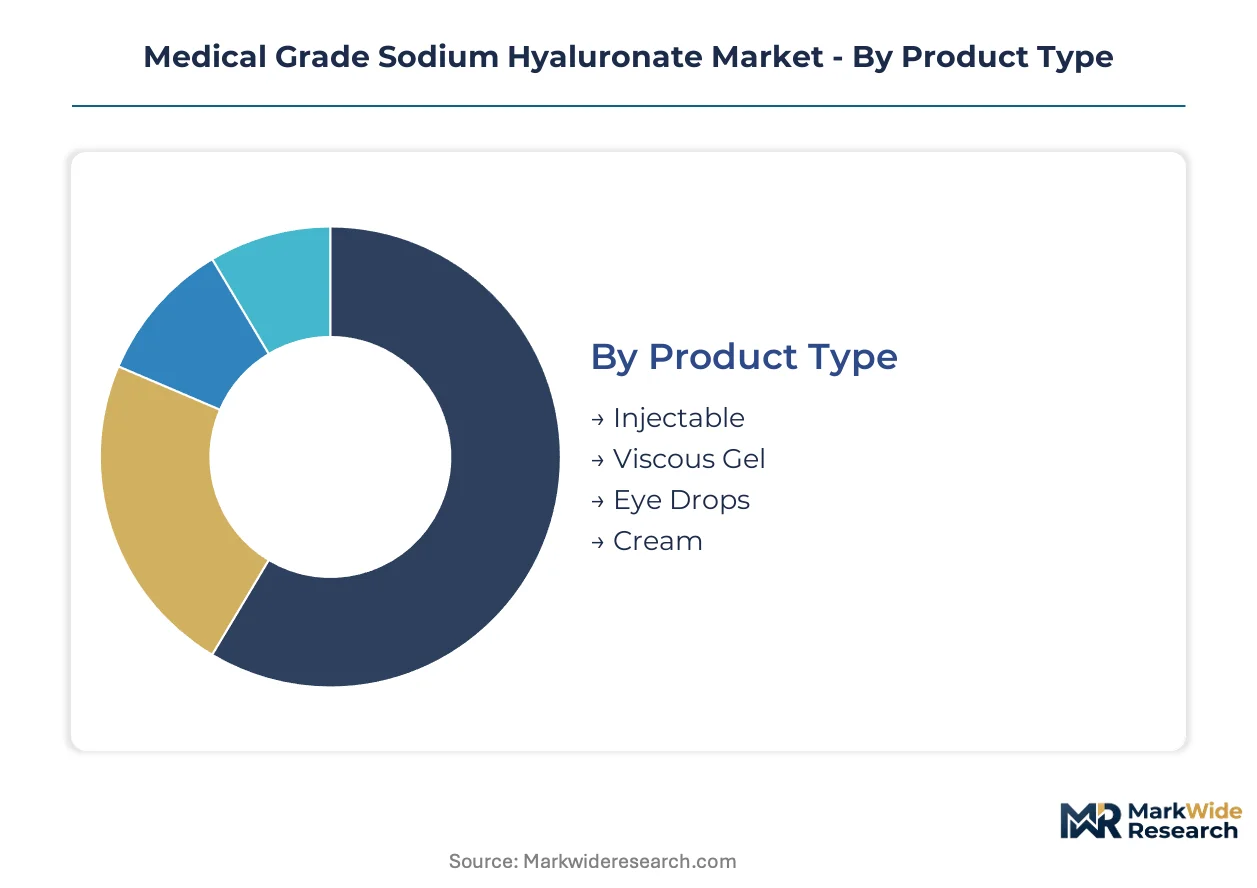
Product form factor determines manufacturing capital intensity and regulatory pathway complexity for sodium hyaluronate suppliers. Margin distribution varies sharply across sterile injectables versus topical formulations due to endotoxin control requirements and practitioner certification premiums.
Product Type:
Injectable formats command the steepest margin pools through aesthetic practitioner networks and orthopedic viscosupplementation protocols.
- Injectable:Sterile solutions meeting pharmacopeial endotoxin thresholds below 0.5 EU/mg serve intra-articular and subcutaneous indications. Seoul-Gyeonggi aesthetic clinics and ambulatory surgical centers in the US drive volume concentration through direct-to-practitioner procurement channels.
- Viscous Gel:Cross-linked hyaluronic acid matrices with elevated molecular weight enable sustained residence time in synovial spaces. Osteoarthritis management adoption in Medicare Advantage-covered outpatient settings is climbing the fastest among product formats.
- Eye Drops:Preservative-free ophthalmic solutions lubricate corneal surfaces post-cataract surgery. Japan's PMDA maintains stringent sterility standards for intraocular formulations.
- Cream:Topical emulsions with lower molecular weight hyaluronate penetrate epidermal barriers for wound healing adjuncts. Homecare settings in Germany purchase through pharmacy distribution.
Injectable holds installed capacity. Viscous Gel is rotating up the share rankings.
Application:
Revenue concentration tilts toward elective procedures where direct-to-consumer marketing bypasses institutional procurement controls.
- Ophthalmology:Cataract surgery adjuncts represent mature volume foundations with standardized reimbursement protocols. FDA 510(k) clearance frameworks govern intraocular viscoelastic devices.
- Aesthetic Treatments:Dermal filler injections targeting facial volume restoration generate premium pricing through manufacturer-certified practitioner networks. South Korea's MFDS regulates biologics classification for these products.
- Dermatology:Topical and injectable formulations address wound healing and scar revision. EMA MDR compliance pathways extend development timelines for novel formulations.
- Orthopedics:Viscosupplementation for knee osteoarthritis competes with corticosteroid injections in ambulatory settings. Germany's statutory health insurance system covers specific hyaluronic acid injection protocols.
Aesthetic Treatments captures margin premiums. Orthopedics is gaining procedural volume fastest.
End User:
Procurement authority fragmentation between institutional buyers and independent clinic operators reshapes pricing architecture.
- Clinics:Aesthetic and orthopedic specialty practices source through manufacturer-direct channels, capturing margin pools previously absorbed by hospital procurement offices. Seoul-Gyeonggi med-aesthetic clusters exemplify this channel rotation.
- Hospitals:Integrated health systems maintain centralized purchasing for ophthalmic viscoelastics and surgical adjuncts. US hospital networks negotiate through group purchasing organizations.
- Research Institutions:Academic medical centers procure pharmaceutical-grade material for clinical trial formulations. EMA Good Manufacturing Practice standards govern supply qualification.
- Homecare:Patients self-administer topical formulations and selected ophthalmic drops. German pharmacy retail chains distribute consumer-facing products.
Hospitals retain ophthalmic volume. Clinics is displacing institutional procurement fastest.
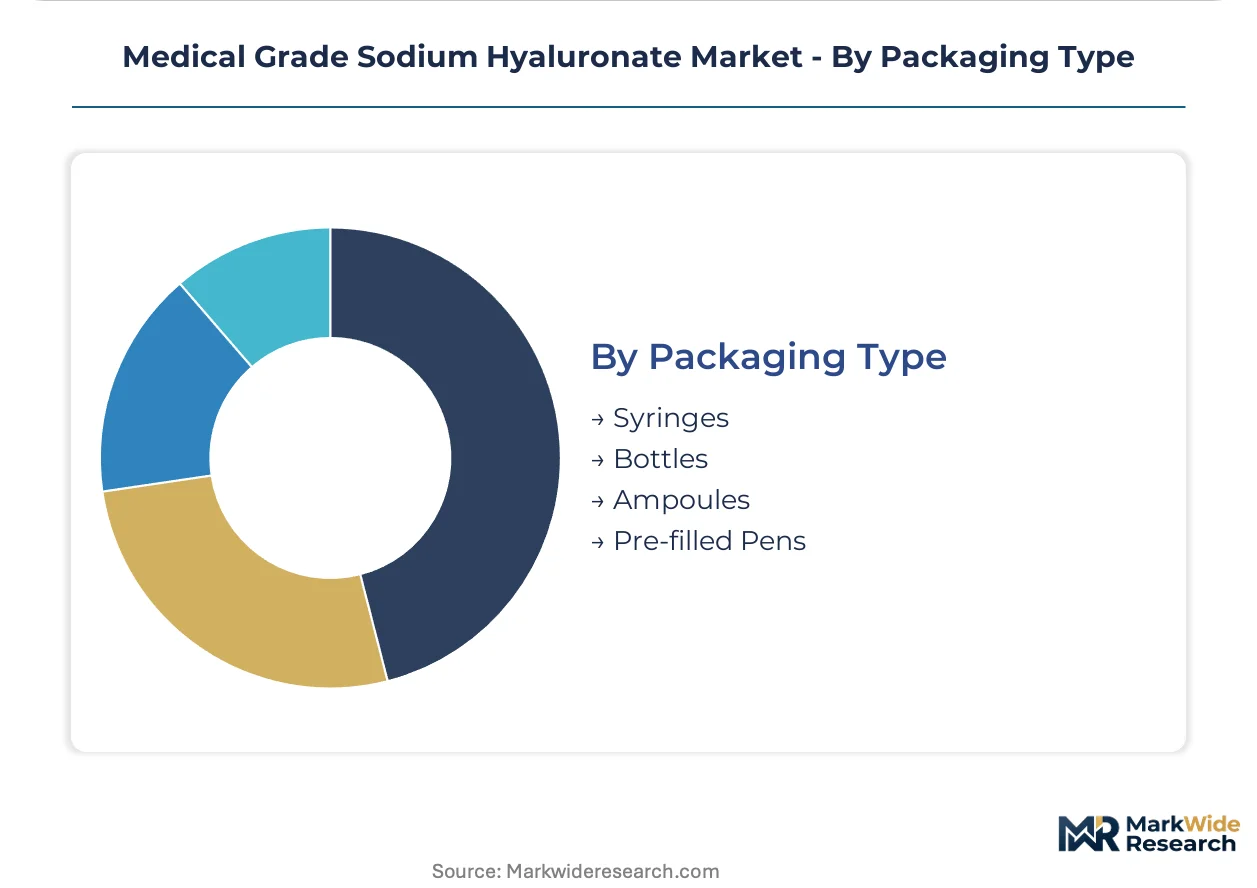
Packaging Type:
Unit-dose presentation formats align with sterility assurance and practitioner workflow efficiency requirements.
- Syringes:Luer-lock and integrated-needle designs dominate injectable dermal filler and orthopedic applications. FDA biologics guidance mandates particulate testing for sterile syringe assemblies.
- Pre-filled Pens:Auto-injector devices enable patient self-administration for selected therapeutic indications. EMA MDR technical documentation requirements apply to combination product classifications.
- Ampoules:Glass single-dose containers preserve sterility for ophthalmic and research-grade formulations. Japan's PMDA specifies break-force standards for ampoule neck design.
- Bottles:Multi-dose presentations with preservative systems serve topical cream and eye drop categories. USP sterility testing protocols govern refillable container validation.
Syringes commands manufacturing scale. Pre-filled Pens is ascending fastest in development pipelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul's Incheon International Airport and the Gyeonggi-do logistics corridor underwrite South Korea's dominance in med-aesthetic distribution, while Rotterdam's pharmaceutical port infrastructure anchors European supply security for fermentation-derived inputs.
United States
FDA's 510(k) clearance framework for dermal fillers drives clinical dataset investments by formulation innovators. Medicare Advantage reimbursement classifications for hyaluronic acid injections shift volume toward ambulatory surgical centers. The Greater Boston corridor hosts ophthalmic viscoelastic research clusters supplying cataract surgery adjuncts.
Germany
EMA MDR compliance pathways extend development timelines for novel formulations targeting orthopedic viscosupplementation. Statutory health insurance coverage protocols for knee osteoarthritis injections create predictable demand baselines. The Rhine-Main cluster around Frankfurt concentrates pharmaceutical-grade purification infrastructure.
South Korea
MFDS biologics classification for aesthetic products mandates post-market surveillance that institutionalizes quality barriers. Seoul-Gyeonggi med-aesthetic clusters generate practitioner certification networks accelerating East Asian penetration. Captive fermentation capacity in Gyeonggi-do supplies non-animal stabilized hyaluronic acid.
Japan
PMDA sterility standards for intraocular formulations exceed pharmacopeial thresholds elsewhere, filtering supplier qualification. Cataract surgery adjunct demand maintains mature volume foundations through aging demographics. The Kansai corridor around Osaka anchors ophthalmic viscoelastic manufacturing.
China
NMPA regulatory harmonization with ICH guidelines accelerates approval pathways for recombinant microbial platforms. Domestic fermentation capacity expansion targets pharmaceutical-grade endotoxin control below 0.5 EU/mg. The Yangtze River Delta cluster concentrates dermal filler production for Asia-Pacific distribution.
Medical Grade Sodium Hyaluronate Market Vendor Landscape
Concentration sits with vertically integrated pharmaceutical conglomerates possessing captive fermentation infrastructure and clinical trial capabilities. Three archetypes define competitive positioning: East Asian chemical conglomerates with backward integration into raw material supply, European dermatology specialists with cross-channel therapeutic-cosmetic portfolios, and diversified healthcare multinationals leveraging hospital procurement relationships. Dominant competitive moves include capacity expansion in recombinant Bacillus subtilis platforms and geographic licensing partnerships to bypass endotoxin purification bottlenecks.
Within the integrated chemical conglomerate tier, LG Chem anchors East Asian supply positioning through Gyeonggi-do fermentation assets. Among dermatology-focused specialists, Galderma exemplifies cross-channel execution spanning therapeutic ophthalmology and aesthetic segments. At the diversified healthcare multinational tier, Allergan and Johnson and Johnson occupy positions leveraging hospital system procurement networks and direct-to-practitioner channel development.
| Leading Market Players |
|---|
| Allergan |
| LG Chem |
| Galderma |
| Anika Therapeutics |
| Bausch and Lomb |
| Johnson and Johnson |
| Santen |
| Zydus Cadila Pharmaceuticals |
| Fidia Farmaceutici |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between Seoul-Gyeonggi fermentation facilities and North American aesthetic clinic networks lock in supply access while anchoring price visibility through volume-commitment floors. These arrangements insulate integrated manufacturers from Streptococcus zooepidemicus culture media volatility while compressing margin pools for non-captive distributors.
Pricing Analysis
Volume-discount tiering structures separate pharmaceutical-grade injectables certified below 0.5 EU/mg endotoxin thresholds from standard viscosupplementation gels and economy topical formulations. Price differentiation rests on ISO 13485 certification status and practitioner network exclusivity premiums in direct-to-consumer channels. Cost compression in economy topical tiers is intensifying because German pharmacy retail chains consolidate procurement volumes. Ambulatory surgical centers exhibit highest price sensitivity due to Medicare Advantage reimbursement caps, while Seoul-Gyeonggi aesthetic clinics absorb premium positioning through direct manufacturer relationships.
Supply Chain Analysis
Strategic stockpiling of pharmaceutical-grade purification reagents dominates inventory strategy among East Asian manufacturers buffering against fermentation input volatility. Supply concentrates in South Korea, China, and Japan through captive Bacillus subtilis and Streptococcus zooepidemicus fermentation platforms. Raw material dependencies include culture media, endotoxin removal resins, and sterile packaging assemblies. Single-source vulnerability in Gyeonggi-do purification infrastructure exposes non-integrated buyers to allocation risk. Distribution runs through manufacturer-certified practitioner networks displacing hospital procurement offices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward aesthetic clinic operators as Seoul-Gyeonggi procurement consolidation fragments institutional purchasing authority across independent practitioner networks.
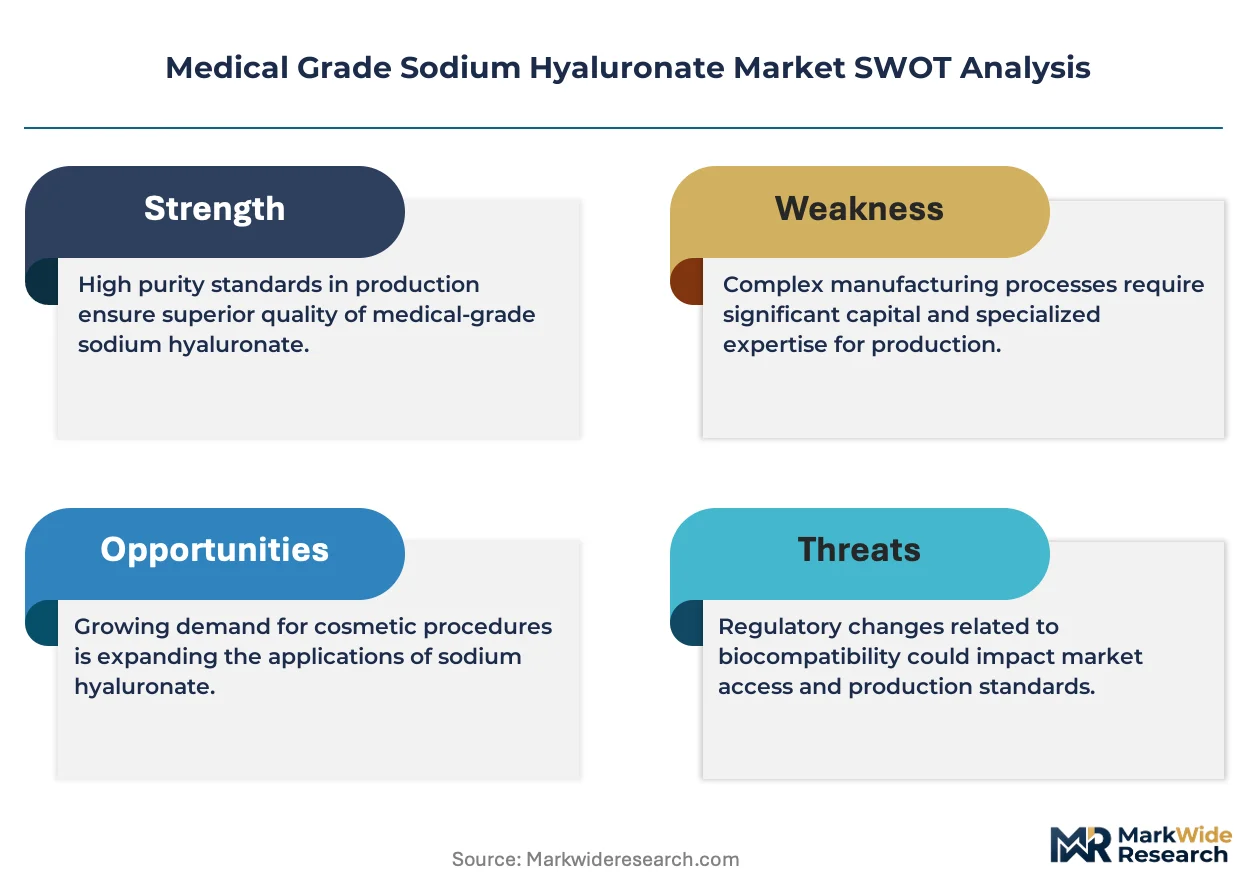
For Market Incumbents: Fortify captive fermentation capacity in Gyeonggi-do and expand recombinant Bacillus subtilis platforms to eliminate animal-derived raw material risks. Deepen ISO 13485 certification networks to lock out mid-scale entrants lacking capital-intensive purification infrastructure. Threat: EMA MDR compliance pathways extending development timelines for formulation innovators. Lever: backward integration into pharmaceutical-grade culture media supply. For New Entrants and Emerging Players: Anchor in Medicare Advantage-covered orthopedic viscosupplementation segments where reimbursement protocols create predictable demand baselines absent practitioner certification barriers. Most penetrable target: ambulatory surgical centers in US markets seeking alternatives to corticosteroid injections. Go-to-market angle: auto-injector pre-filled pens enabling patient self-administration with simplified EMA MDR technical documentation. For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale manufacturers possessing recombinant microbial platforms and existing ISO 13485 quality management systems but lacking geographic licensing partnerships. Long-term viability across the analysis window favors assets with demonstrated endotoxin control below pharmacopeial thresholds and established supplier qualification for hospital system procurement. Signal to monitor: FDA adverse event reporting mandate compliance rates as a proxy for pharmacovigilance infrastructure maturity.| Strategic Initiative | Industry Significance |
|---|---|
| Recombinant Bacillus subtilis Platform Adoption | Eliminates animal-derived raw material dependencies while streamlining EMA regulatory pathways. |
| ISO 13485 Certification Network Expansion | Enables supplier qualification for Medicare Advantage reimbursement in outpatient settings. |
| Direct-to-Practitioner Channel Development | Captures margin pools previously absorbed by hospital procurement offices in aesthetic segments. |
| Post-Market Surveillance Infrastructure Buildout | Satisfies FDA biologics guidance mandates for dermal filler adverse event reporting. |
| Geographic Licensing Partnership Formation | Bypasses endotoxin purification bottlenecks through technology transfer to non-integrated buyers. |
Methodological Framework
Initial hypotheses were tested against primary input from fermentation operations directors, aesthetic clinic procurement managers, regulatory affairs leads at dermal filler manufacturers, and hospital GPO contracts specialists and refined through secondary validation. Primary data synthesis drew from FDA 510(k) clearance filings, EMA MDR submission databases, MFDS biologics classification records, and hospital procurement contract aggregators. Bottom-up volume estimates from product-form factor segments were triangulated against top-down market sizing from pharmaceutical-grade purification capacity assessments.
Variance-decomposition across product type, application, end user, and packaging format segments informed the analytical framework throughout the projection horizon. CAGRs were derived from segment-level volume trajectories weighted by unit economics in aesthetic versus therapeutic indications. Forecast inputs included practitioner certification network expansion rates in Seoul-Gyeonggi clusters and Medicare Advantage reimbursement classification shifts for hyaluronic acid injections.
Decision-makers should treat outputs as directional under assumptions of stable FDA biologics guidance enforcement and continued EMA MDR compliance pathway duration; material deviation would warrant model refresh. Forecasts reflect base-case assumptions regarding fermentation input price stability and endotoxin threshold technical ceilings. Revision becomes warranted when MFDS post-market surveillance mandate stringency crosses thresholds affecting manufacturer qualification rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
France Diabetes Drugs Market
Pharmaceuticals
Global Manidipine Hydrochloride Market
Pharmaceuticals
Methylphenidate Hydrochloride Market
Pharmaceuticals
Diuretic Drugs Market
Pharmaceuticals
RAS-Acting Agents Market
Pharmaceuticals
Global Prefilled Syringes Drug Molecules Market
Pharmaceuticals
Global Vaccine Market
Pharmaceuticals
B7-H3 Antibody Market
Pharmaceuticals
Europe Anesthesia Drugs Market
Pharmaceuticals
Tramadol Drug Market
Pharmaceuticals
Hepatocellular Carcinoma Drugs Market
Pharmaceuticals
Norovirus Treatment Market
Pharmaceuticals
Nasal Vaccines Market
Pharmaceuticals
India Pharmaceutical Contract Sales Organizations Market
Pharmaceuticals
Rabeprazole Sodium Market
Pharmaceuticals
Atypical Antipsychotic Market