
 Ciclopirox Olamine Market | 2026-2036
Ciclopirox Olamine Market Size, Share, and Industry Trends Forecast 2026-2036
Ciclopirox Olamine Market Insights
Retail pharmacy distribution is reconfiguring how patients access ciclopirox olamine formulations across North America and Europe. Teva Pharmaceutical Industries leverages its generic dermatology portfolio to sustain shelf presence in major pharmacy chains. Bayer AG anchors its position through established brand recognition in topical antifungal segments. Sun Pharmaceutical Industries competes on manufacturing scale, supplying multiple dosage forms to contract buyers.
Ciclopirox olamine is a synthetic hydroxypyridone antifungal agent with a broad spectrum of activity against dermatophytes, yeasts, and molds, typically formulated at concentrations of 0.77% to 1% in topical vehicles. It functions by chelating polyvalent metal cations and interfering with iron-dependent enzyme systems essential to fungal metabolism. Cream formulations occupy the largest share of the product type landscape, while gels are gaining traction among younger patient demographics seeking non-greasy application options. The hospital end-user segment maintains stable procurement volumes, though retail pharmacies capture the fastest growth as over-the-counter accessibility expands in select markets.
FDA bioequivalence guidelines for topical generics shape how manufacturers design formulation and clinical study programs for ciclopirox olamine products. EMA quality standards under the EU pharmaceutical framework govern market access for European suppliers, while ISO 13485 certification requirements influence contract manufacturing relationships. Stakeholders must monitor evolving regulatory expectations for in-vitro release testing and therapeutic equivalence demonstration as agencies refine their assessment methodologies.
Market Dynamics
FDA bioequivalence scrutiny for topical generics is compressing formulation flexibility while retail pharmacy consolidation concentrates patient access channels in fewer hands.
Growth Catalysts
- Expanded OTC pathways:The FDA's streamlined review process for prescription-to-OTC switches enables broader patient self-selection of topical antifungal therapies in US pharmacy settings.
- EMA quality harmonization:Centralized EU pharmaceutical framework assessments reduce redundant national filings, accelerating market entry for compliant ciclopirox olamine formulations across member states.
- Dermatology clinic expansion:Specialized skin care centers in Germany and the United States are elevating topical antifungal protocols within standard treatment regimens.
Market Restraints
- Active pharmaceutical ingredient concentration:Limited qualified suppliers of pharmaceutical-grade ciclopirox olamine base material create supply vulnerability concentrated in South Asian contract manufacturing clusters.
- Topical bioequivalence complexity:The FDA's evolving in-vitro release testing requirements extend clinical study timelines and inflate development costs for generic entrants.
- Azole antifungal substitution:Clinician familiarity with ketoconazole and clotrimazole alternatives limits formulary expansion for hydroxypyridone-class agents in institutional procurement.
Strategic Opportunities
- Non-greasy vehicle innovation:Gel and serum formulations targeting younger patient demographics are capturing shelf space previously dominated by cream vehicles in US retail chains.
- ISO 13485 contract manufacturing:Certification-compliant production partnerships enable mid-tier pharmaceutical firms to access European hospital procurement networks without captive manufacturing investment.
- Telehealth prescribing integration:Digital dermatology platforms are creating direct-to-patient dispensing channels that bypass traditional wholesale distribution.
Industry Challenges
- Formulation scientist scarcity:Specialized expertise in topical vehicle rheology and skin permeation modeling commands premium compensation, constraining R&D team expansion.
- Therapeutic equivalence demonstration:The FDA's refined statistical criteria for topical generic approval require larger subject populations, extending study duration and patient recruitment burden.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ciclopirox Olamine Market |
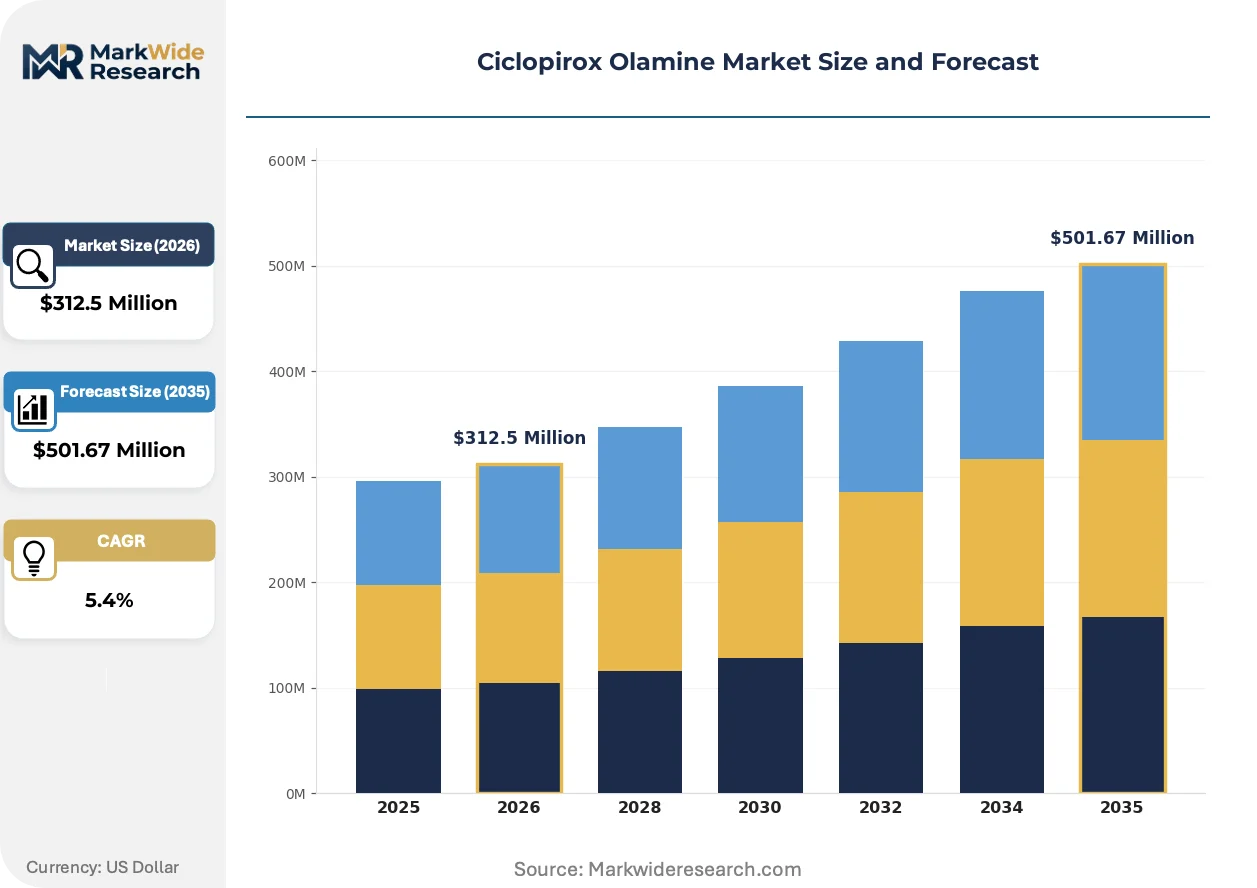
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $501.67 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Solutions, Creams, Gels, Ointments End User: Hospitals, Clinics, Retail Pharmacies, Home Care Application: Fungal Infections, Dermatitis, Acne Treatment, Antifungal Prophylaxis Packaging Type: Tube, Bottle, Spray, Jar |
| Companies Covered | Teva Pharmaceutical Industries Ltd., Medimetriks Pharmaceuticals, Bayer AG, Sun Pharmaceutical Industries Ltd., Taro Pharmaceuticals, Apotex Corporation, Hikma Pharmaceuticals, GSK (Glades Pharmaceuticals), Sandoz (Fougera Pharmaceuticals), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ciclopirox Olamine Market Trends and Innovations
Digital formulation design tools and patient-centric vehicle development are compressing traditional product development cycles while regulatory agencies refine equivalence assessment methodologies.
Advanced in-silico skin permeation modeling is virtualizing preclinical screening for ciclopirox olamine vehicle optimization. Dermatology-focused contract research organizations in Switzerland and the United States are adopting these platforms to reduce animal study dependency. The technology is virtualizing early-stage formulation selection, compressing the traditional 18-month development window into iterative computational cycles.
REACH chemical safety dossier updates under the EU Green Deal framework are tightening excipient disclosure requirements for topical pharmaceutical products. Manufacturers must now document full supply chain substance volumes and hazard classifications for cream and gel bases. European formulators are responding by qualifying bio-based emulsifiers and replacing petrolatum-derived vehicles to preempt authorization restrictions.
Patients are gravitating toward subscription-based dermatology services that bundle diagnosis, prescription, and home delivery. Younger demographics in US metropolitan markets are displacing traditional pharmacy counter pickup with app-managed refill cycles. This channel shift is most pronounced in California and New York, where telehealth prescribing regulations accommodate asynchronous clinician consultation models.
Ciclopirox Olamine Market Segmentation
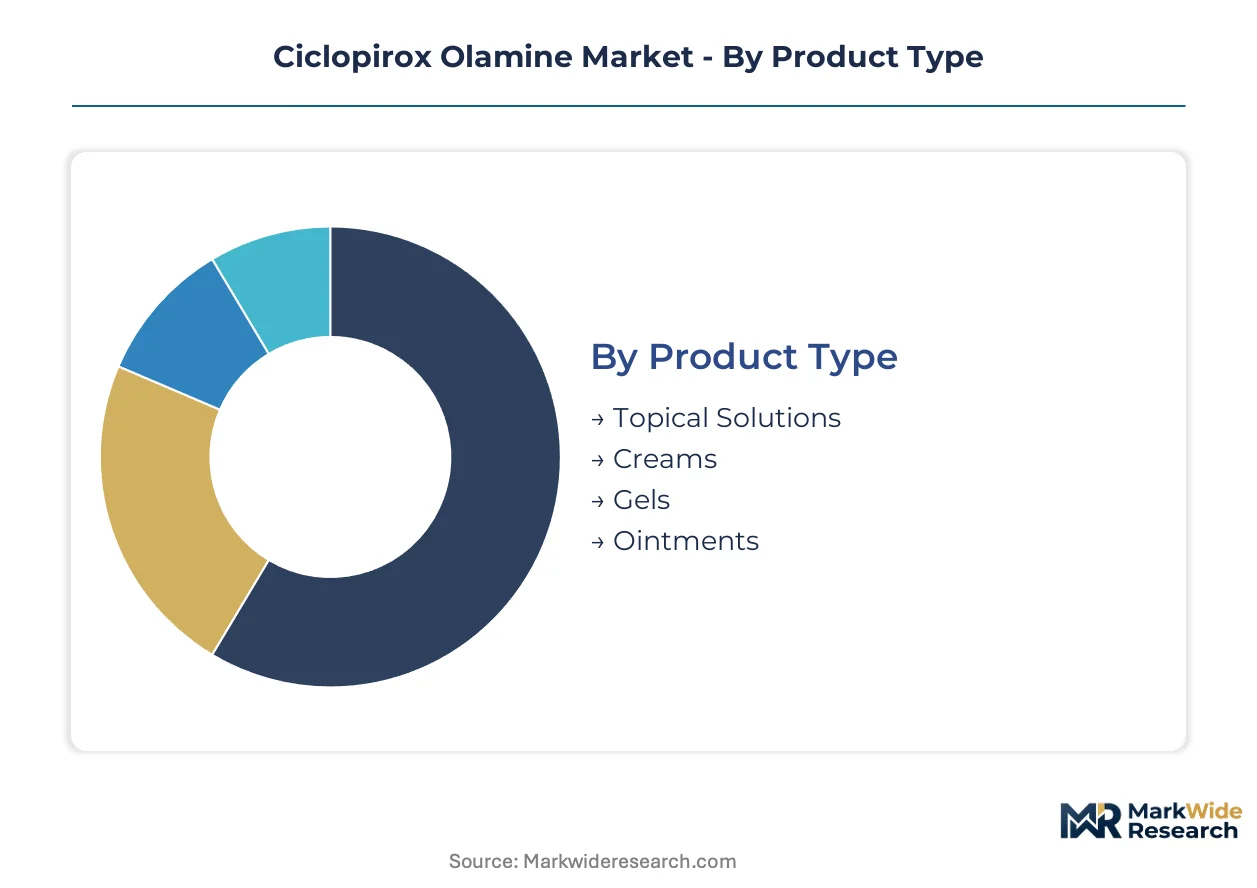
Segmentation in the ciclopirox olamine market reveals how formulation choices, distribution channels, and patient settings create distinct competitive arenas with varying service intensity requirements. Each category reflects divergent margin structures and regulatory exposure that shape manufacturer strategic priorities.
Product Type:
After-sales service intensity varies sharply across topical vehicles, with cream formulations demanding minimal patient education while gel and serum variants require sustained dermatologist consultation support to ensure proper application technique and adherence.
- Creams:Oil-in-water emulsions at 0.77% to 1% concentration deliver sustained drug release through occlusive hydration. Hospital procurement in Germany favors cream vehicles for inpatient dermatophyte protocols due to established formulary familiarity and lower per-unit cost. The segment commands the largest prescription volume but faces margin compression from generic substitution.
- Gels:Hydroalcoholic bases with rapid drying properties appeal to younger patients in US metropolitan markets seeking cosmetically acceptable alternatives. California and New York telehealth platforms are driving gel adoption through subscription-based dermatology services that emphasize patient experience metrics.
- Topical Solutions:Alcohol-based liquids penetrate intertriginous areas effectively for nail bed and scalp applications. The vehicle requires precise dosing guidance that increases pharmacy counseling burden.
- Ointments:Petrolatum-based occlusive formulations serve severe xerosis cases with compromised barrier function. REACH chemical safety dossier updates under the EU Green Deal are pressuring formulators to qualify bio-based alternatives to traditional mineral oil vehicles.
By volume, creams lead. By growth pace, gels are ahead.
End User:
Cost tier stratification separates institutional buyers operating on annual procurement cycles from retail channels capturing cash-pay and insured patients with immediate access expectations.
- Retail Pharmacies:Chain pharmacies in the United States dominate patient access through centralized distribution networks that compress working capital requirements for manufacturers. CVS and Walgreens formulary placement determines generic ciclopirox olamine volume allocation, with shelf space negotiations favoring suppliers offering multi-SKU portfolios spanning cream, gel, and solution vehicles.
- Hospitals:German dermatology wards and US academic medical centers maintain stable procurement volumes through group purchasing organizations. The segment prioritizes therapeutic equivalence documentation and lot traceability over price minimization.
- Clinics:Specialized dermatology centers in Switzerland and the United States are elevating topical antifungal protocols within standard treatment regimens. These settings generate higher per-prescription revenue but require field-based clinical specialist support.
- Home Care:Long-term care facilities and visiting nurse services represent emerging demand for bulk packaging formats. The segment exhibits price sensitivity and limited brand loyalty.
Retail pharmacies capture the steepest expansion trajectory. Hospitals maintain the most stable procurement base.
Application:
Application-driven demand concentrates in therapeutic areas where ciclopirox olamine's hydroxypyridone mechanism offers distinct advantages over azole alternatives, particularly in cases of documented resistance or polypharmacy concerns.
- Fungal Infections:Dermatophyte and yeast infections constitute the primary labeled indication, with tinea pedis and onychomycosis representing high-volume prescriptions. US retail chains report seasonal demand spikes correlating with summer footwear transitions.
- Dermatitis:Off-label use in seborrheic dermatitis leverages the agent's anti-inflammatory and antimicrobial dual action. German dermatology clinics have incorporated ciclopirox olamine into standardized protocols for refractory cases.
- Acne Treatment:Adjunctive therapy for inflammatory lesions exploits the compound's broad antimicrobial spectrum against Cutibacterium acnes. The application remains niche with limited payer coverage.
- Antifungal Prophylaxis:Immunocompromised patient populations in hospital settings receive preventive topical therapy. EMA quality standards govern manufacturing specifications for this sensitive indication.
Fungal infection applications generate the highest prescription volume. Dermatitis use is climbing the fastest as clinicians seek alternatives to corticosteroid-dependent regimens.
Packaging Type:
Packaging configuration directly influences supply chain economics, with tube formats dominating prescription fulfillment and spray vehicles capturing specific anatomical application needs.
- Tube:Laminated aluminum-plastic collapsible tubes represent the standard primary packaging for cream and ointment formulations. The format supports precise dosing and extended shelf stability.
- Bottle:HDPE containers with pump or flip-cap closures serve solution and gel volumes exceeding 60ml. The format enables efficient manufacturing scale but increases shipping cube and warehousing cost.
- Spray:Aerosol and mechanical pump spray systems target scalp and large surface area applications where manual spreading is impractical. FDA bioequivalence scrutiny extends to spray device performance characteristics.
- Jar:Wide-mouth containers accommodate ointment viscosity and facilitate fingertip application. The format faces patient hygiene concerns and regulatory scrutiny regarding multi-dose contamination risk.
Tubes dominate unit volume. Spray formats are gaining share fastest in US retail channels targeting convenience-oriented patient segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Prescription-to-OTC regulatory pathways in the United States and EMA quality harmonization across EU member states are redrawing competitive boundaries for topical antifungal manufacturers. FDA streamlined review processes accelerate patient self-selection, while REACH chemical safety dossier updates force formulation changes in European production facilities.
United States
CVS and Walgreens formulary placement determines generic ciclopirox olamine volume allocation across retail pharmacy chains. FDA bioequivalence scrutiny for topical generics extends clinical study timelines and inflates development costs for new entrants. California and New York telehealth platforms are driving gel adoption through subscription-based dermatology services that emphasize patient experience metrics.
Germany
Specialized dermatology centers in Munich and Berlin are elevating topical antifungal protocols within standard treatment regimens. EMA quality standards under the EU pharmaceutical framework govern market access for European suppliers of hydroxypyridone-class agents. Hospital procurement through group purchasing organizations prioritizes therapeutic equivalence documentation and lot traceability over price minimization.
Switzerland
Dermatology-focused contract research organizations in Basel and Zurich are adopting in-silico skin permeation modeling platforms to reduce animal study dependency. Swissmedic certification requirements influence contract manufacturing relationships for mid-tier pharmaceutical firms seeking European hospital network access. The country's precision medicine infrastructure supports advanced formulation development for niche patient populations.
India
Limited qualified suppliers of pharmaceutical-grade ciclopirox olamine base material create supply vulnerability concentrated in South Asian contract manufacturing clusters. CDSCO quality benchmarks shape export competitiveness for domestic formulators serving regulated markets. Maharashtra and Gujarat pharmaceutical corridors anchor production scale for multiple dosage form supplies to international contract buyers.
United Kingdom
London-based dermatology clinics are incorporating ciclopirox olamine into standardized protocols for refractory seborrheic dermatitis cases. MHRA post-Brexit regulatory autonomy permits tailored approval pathways distinct from EMA centralized procedures. The Southeast England life sciences cluster supports specialized topical vehicle development for premium patient segments.
Ciclopirox Olamine Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic archetypes: generic dermatology specialists leveraging multi-SKU portfolios, research-intensive innovators with established brand recognition, and scale-driven contract manufacturers supplying institutional buyers. Competitive dynamics center on formulary placement negotiations with retail pharmacy chains and certification-compliant production partnerships for European hospital procurement networks. M&A activity targets specialized formulation capabilities, while capacity expansion concentrates in South Asian pharmaceutical corridors.
Within the generic dermatology tier, Teva Pharmaceutical Industries Ltd. and Sun Pharmaceutical Industries Ltd. represent scale-driven manufacturing archetypes, while Bayer AG exemplifies brand-anchored positioning in topical antifungal segments. Apotex Corporation occupies a position among North American generic specialists competing on portfolio breadth. These entities collectively illustrate how shelf presence in major pharmacy chains and manufacturing scale determine competitive viability across distinct regional regulatory environments.
| Leading Market Players |
|---|
| Teva Pharmaceutical Industries Ltd. |
| Medimetriks Pharmaceuticals |
| Bayer AG |
| Sun Pharmaceutical Industries Ltd. |
| Taro Pharmaceuticals |
| Apotex Corporation |
| Hikma Pharmaceuticals |
| GSK (Glades Pharmaceuticals) |
| Sandoz (Fougera Pharmaceuticals) |
| Others |
Pricing and Supply Chain Analysis
Single-source dependency on South Asian API manufacturers generates acute pricing tier spreads while compressing procurement flexibility across formulation grades. FDA bioequivalence scrutiny and REACH chemical safety mandates simultaneously inflate compliance costs and reshape supplier qualification thresholds, forcing buyers to absorb premium spreads for certified-grade material or accept extended lead times from unqualified sources.
Pricing Analysis
Certification level creates the primary spread between FDA-grade, EMA-compliant, and uncertified ciclopirox olamine base material. Three-tier pricing structure across premium certified, standard compliant, and economy unverified levels dominates transactional dynamics. Pricing pressure stems from azole antifungal substitution in institutional procurement, where ketoconazole familiarity drives formulary exclusion of hydroxypyridone alternatives. Retail pharmacy chains exhibit highest price sensitivity due to generic substitution protocols, while hospital group purchasing organizations prioritize therapeutic equivalence documentation over unit cost minimization.
Supply Chain Analysis
Export-control scrutiny over pharmaceutical precursor chemicals constrains API flow from concentrated South Asian manufacturing clusters. Active pharmaceutical ingredient production centers on Maharashtra and Gujarat pharmaceutical corridors in India, with formulation finishing distributed across Germany, Switzerland, and the United States. Supply chain risk manifests as single-source vulnerability for pharmaceutical-grade ciclopirox olamine base, where limited qualified suppliers create procurement bottlenecks during regulatory inspection cycles. Distribution runs through centralized retail pharmacy chain networks in North America and group purchasing organization channels for European hospital procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Retail pharmacy consolidation across CVS and Walgreens networks has shifted bargaining power decisively toward buyers, compressing manufacturer margins and elevating formulary placement fees as the critical competitive gate.
For Market Incumbents: Pre-empt azole antifungal substitution by embedding ciclopirox olamine into standardized dermatology protocols through field-based clinical specialist teams. Deepen backward integration into API supply through captive production partnerships in South Asian pharmaceutical corridors to insulate against single-source vulnerability. Prioritize ISO 13485 certification maintenance to defend European hospital network access against emerging contract manufacturers. For New Entrants and Emerging Players: Establish a beachhead in gel formulation segments targeting California and New York telehealth subscription platforms, where patient experience metrics override legacy brand loyalty. Exploit white-space opportunity in non-greasy vehicle innovation for younger demographics seeking cosmetically acceptable alternatives to cream formulations. Pursue direct-to-patient dispensing partnerships with digital dermatology platforms that bypass traditional wholesale distribution markups. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialized formulation capabilities over pure manufacturing scale. Long-term viability hinges on regulatory navigation expertise across FDA bioequivalence and EMA quality harmonization frameworks. Acquisition targets should demonstrate proven topical vehicle rheology capabilities and established contract research organization relationships. Monitor prescription-to-OTC switch approvals as the primary inflection signal for volume expansion potential.| Strategic Initiative | Industry Significance |
|---|---|
| Non-Greasy Vehicle Innovation | Gel and serum formulations capture younger patient demographics in US metropolitan telehealth channels. |
| ISO 13485 Certification Investment | Compliance enables access to European hospital procurement networks without captive manufacturing infrastructure. |
| API Supply Backward Integration | In-house production of pharmaceutical-grade base material reduces dependency on South Asian contract manufacturers. |
| Telehealth Platform Partnership | Direct-to-patient dispensing through digital dermatology services bypasses traditional pharmacy chain markups. |
| In-Silico Permeation Modeling Adoption | Computational screening platforms compress formulation development timelines and reduce animal study requirements. |
Research Methodology
Cross-validation between primary interviews with dermatology clinic directors, hospital formulary managers, retail pharmacy procurement leads, and topical formulation scientists anchors the qualitative findings. Secondary sources include FDA bioequivalence guidance documents, EMA quality framework assessments, REACH chemical safety dossiers, and pharmaceutical trade flow records. Bottom-up prescription volume modeling triangulates against top-down market value estimates derived from manufacturer revenue disclosures and group purchasing organization contract values.
Calibration against historical prescription data and regulatory approval timelines informs the analytical framework across the projection horizon. Segmentation dimensions encompass product type, end user channel, therapeutic application, and regional regulatory cluster. CAGRs derive from iterative convergence between volume-based and value-based modeling approaches. Forecast inputs incorporate prescription-to-OTC switch probability assessments and telehealth platform penetration trajectories in US metropolitan markets.
Stress conditions across API supply disruption, regulatory timeline extension, and azole substitution acceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding EMA quality harmonization progress and FDA bioequivalence methodology refinement. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Asia-Pacific Adenomyosis Drugs Market
Pharmaceuticals
Photophobia Drug Market
Pharmaceuticals
Alpha-Glucosidase Inhibitors Market
Pharmaceuticals
Hepatitis - B Therapeutics Market
Pharmaceuticals
Intravenous (IV) Iron Drugs Market
Pharmaceuticals
Renal Drugs Market
Pharmaceuticals
Global Ethical Pharmaceuticals Market
Pharmaceuticals
Global Acne Medication Market
Pharmaceuticals
North America Meglitinide Market
Pharmaceuticals
Etomidate Market
Pharmaceuticals
Soft Capsules Drugs CMO Market
Pharmaceuticals
Global Chemotherapy-Induced Neutropenia (CIN) Treatment Market
Pharmaceuticals
Soft Capsules Drugs Market
Pharmaceuticals
Injectable Ketamine Market
Pharmaceuticals
HIV Antivirals Market
Pharmaceuticals
Opioid Induced Constipation Drug Market