
 Aripiprazole Market | 2026-2036
Aripiprazole Market Size, Share, and Industry Trends Forecast 2026-2036
Aripiprazole Market Insights
Long-acting injectable (LAI) subscription and replenishment programs is restructuring how aripiprazole value gets captured across treatment episodes. Otsuka Pharmaceutical Co. Ltd. anchors the branded LAI segment through depot formulation expertise and direct-to-clinic service infrastructure. Teva Pharmaceutical Industries Ltd. competes on generic oral tablet scale and pharmacy benefit manager channel control. Sun Pharmaceutical Industries Ltd. leverages backward integration into active pharmaceutical ingredient production to sustain margin on commoditized oral doses.
Aripiprazole is a partial dopamine agonist and serotonin 5-HT1A receptor partial agonist with a molecular formula of C23H27Cl2N3O2, synthesized through multi-step organic coupling and crystallization processes to achieve polymorphic purity for bioequivalence. The compound serves primarily as a maintenance therapy for schizophrenia and bipolar disorder, modulating neurotransmitter activity without full dopamine blockade. Tablet formulations occupy the mature volume base, while extended-release tablet and long-acting injectable delivery modes represent the fastest-growing margin pools as adherence programs expand. Therapy area concentration in schizophrenia and bipolar disorder creates demand stability, though autism spectrum disorder prescriptions are gaining share in pediatric outpatient facilities.
The US FDA's bioequivalence standards for generic aripiprazole, alongside the Drug Enforcement Administration's scheduling oversight for controlled substance analogs, shape product development timelines and market access conditions. India's CDSCO enforces local clinical trial requirements for imported depot formulations, affecting multinational launch sequencing. The European Medicines Agency's centralized authorization for atypical antipsychotics determines reimbursement eligibility across EU member states. Stakeholders must monitor how FDA guidance on complex generic depot formulations will reshape competitive barriers for injectable entrants.
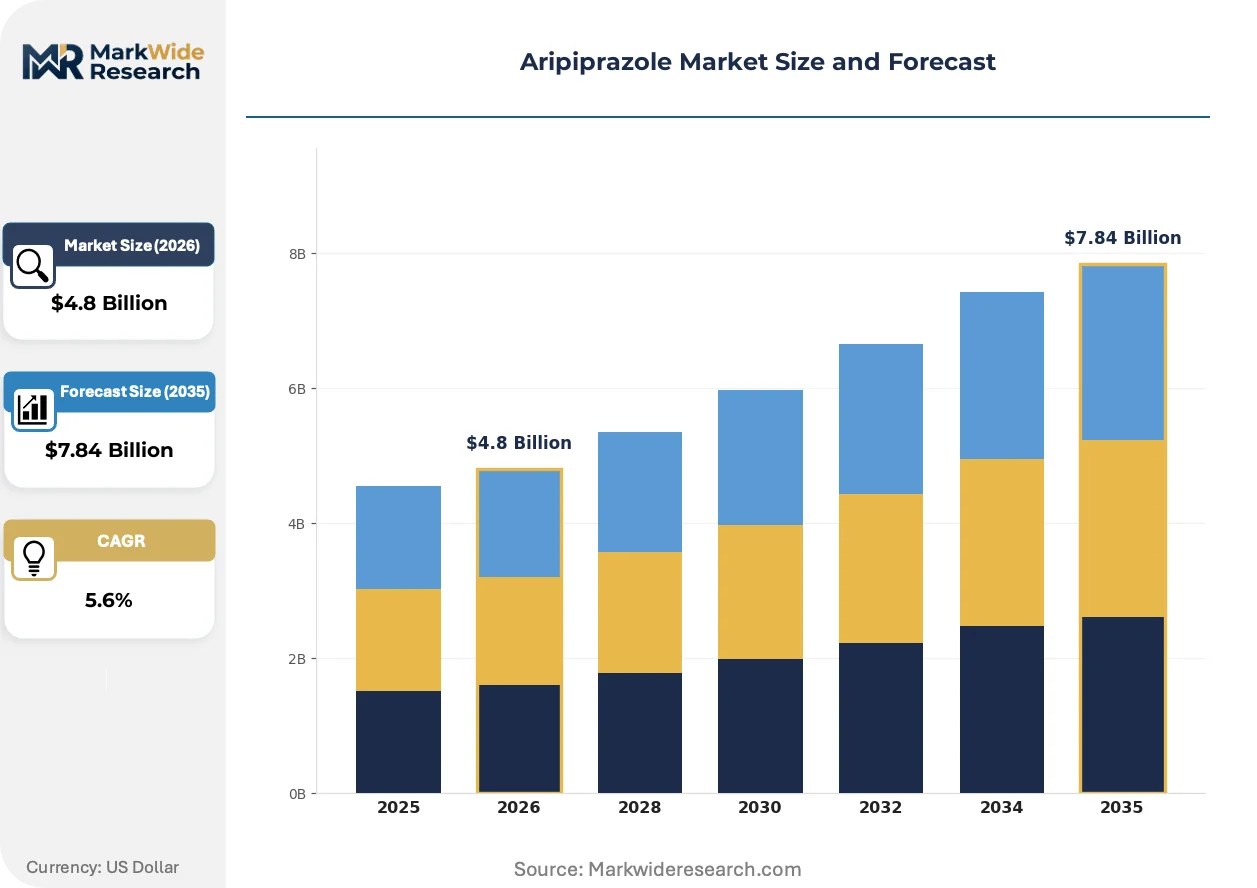
Market Dynamics
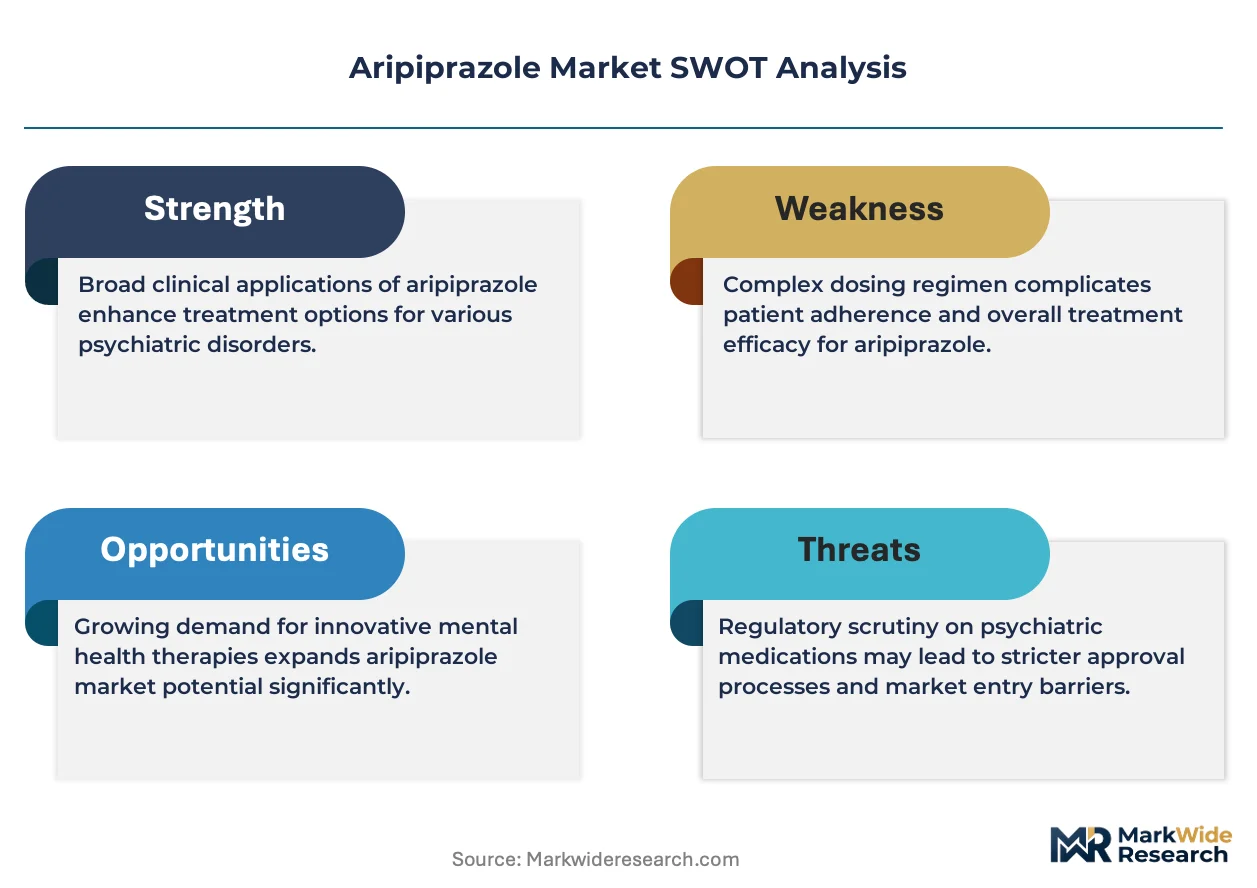
Long-acting injectable (LAI) formulations are restructuring competitive positioning in the aripiprazole market, as adherence programs shift value capture from pill volume to treatment episode management and clinic service bundling.
Growth Catalysts
- Medicaid formulary expansion:State-level reimbursement policies in the United States favor atypical antipsychotics with demonstrated adherence metrics, driving LAI prioritization in hospital discharge protocols.
- Schizophrenia maintenance protocols:Psychiatric treatment guidelines increasingly mandate depot formulations for patients with documented non-adherence to oral regimens.
- Depot manufacturing scale-up:Specialized sterile fill-finish capacity in India and the United States enables cost-efficient LAI production for emerging markets.
Market Restraints
- API supply concentration:Active pharmaceutical ingredient production clusters in specific Indian states create vulnerability to environmental compliance shutdowns.
- FDA bioequivalence complexity:The agency's evolving guidance on complex generic depot formulations extends development timelines for prospective LAI entrants.
- Substitution pressure from oral generics:Commoditized tablet pricing in pharmacy benefit manager channels compresses margin pools for differentiated delivery modes.
Strategic Opportunities
- Pediatric autism spectrum expansion:Off-label prescribing in United States outpatient facilities for irritability associated with autism represents an underpenetrated indication.
- European centralized authorization pathways:The European Medicines Agency's streamlined procedures for atypical antipsychotics reduce time-to-reimbursement across Germany, France, and Italy.
- Direct-to-clinic distribution models:Specialty pharmacy and physician office dispensing channels bypass traditional wholesale markups in high-volume psychiatric practices.
Industry Challenges
- Sterile manufacturing workforce scarcity:Aseptic processing technicians with depot formulation experience command premium wages in competitive labor markets.
- Polymorphic purity validation:Crystallization process control for bioequivalence requires extended analytical method development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aripiprazole Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.84 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablet, Injection, Oral Solution, Extended-Release Tablet End User: Hospitals, Clinics, Community Health Services, Outpatient Facilities Delivery Mode: Intravenous, Intramuscular, Oral, Subcutaneous Therapy Area: Schizophrenia, Major Depressive Disorder, Bipolar Disorder, Autism Spectrum Disorder |
| Companies Covered | Cipla Limited, Aurobindo Pharma Ltd., Otsuka Pharmaceutical Co. Ltd., Hetero Drugs, Apotex Inc., Teva Pharmaceutical Industries Ltd., Zydus Lifesciences, Alkem Laboratories Ltd., Sun Pharmaceutical Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aripiprazole Market Trends and Innovations
Formulation science and regulatory science are converging to redefine how aripiprazole value gets delivered, with delivery mechanism innovation outpacing molecular modification as the primary vector of differentiation.
Extended-release tablet technologies are overtaking immediate-release oral formats in new prescription volume across United States psychiatric practices. Clinicians managing bipolar disorder maintenance increasingly prefer once-daily regimens that reduce pill burden and support adherence tracking. The shift is compressing demand for generic immediate-release tablets while expanding margin capture for formulation specialists with controlled-release expertise.
The FDA's draft guidance on complex generic depot formulations is tightening evidentiary standards for abbreviated new drug applications covering long-acting injectables. Manufacturers must now demonstrate equivalent pharmacokinetic profiles across multiple time points, extending bioequivalence study duration. Generic firms with limited clinical trial infrastructure face exclusion from the LAI segment as development costs escalate.
Hospital discharge planners now specify depot antipsychotics in post-acute care protocols, replacing oral starter regimens that dominated prior standard of care. This procurement pattern shift elevates manufacturer service capabilities—cold chain logistics, nurse training, and injection scheduling—above pure product attributes in vendor selection. The change is most pronounced in United States Medicaid-funded psychiatric units with mandatory adherence reporting requirements.
Aripiprazole Market Segmentation
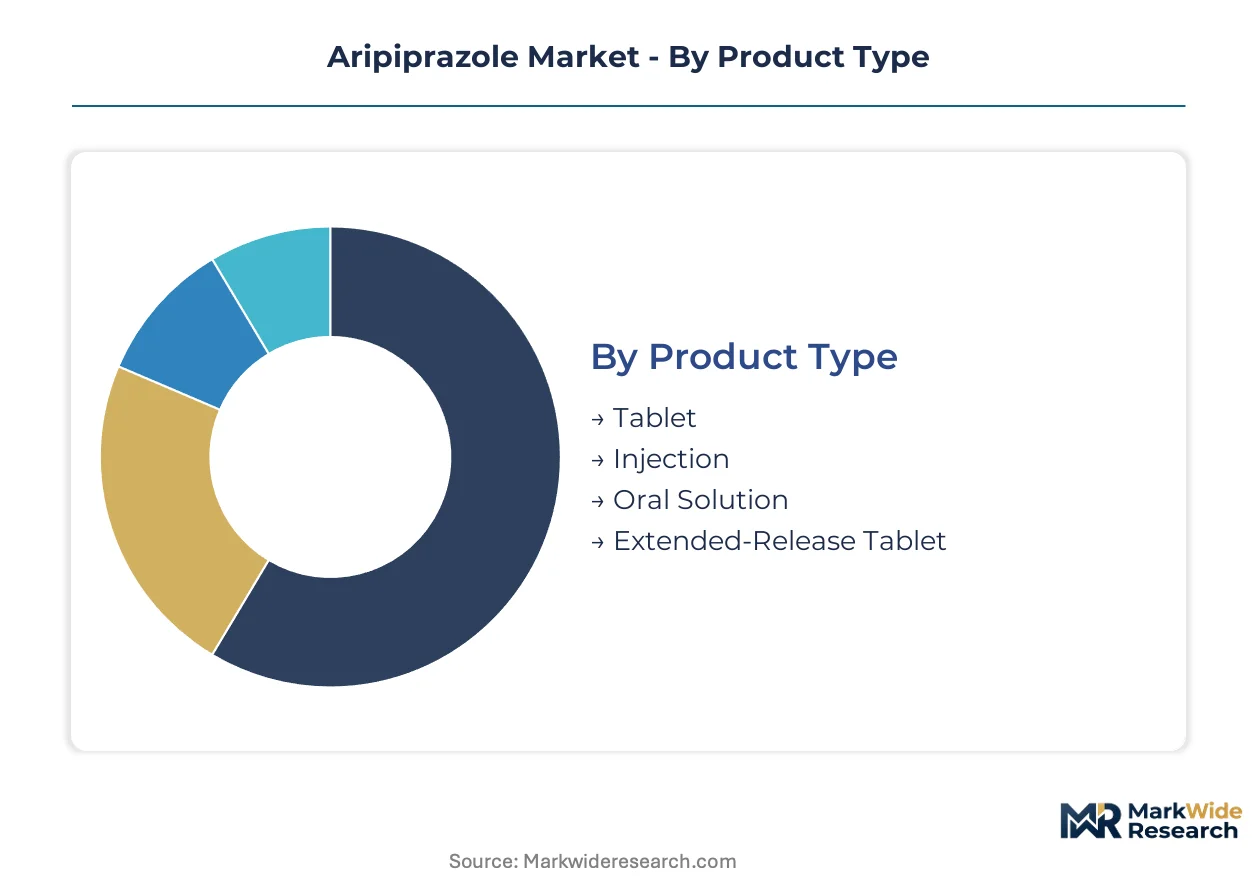
Aripiprazole's value capture varies dramatically across formulation types and care settings. Manufacturers align portfolio investments to segments where reimbursement durability and clinical protocol integration create defendable margin pools.
Product Type:
Manufacturing complexity and sterile processing requirements concentrate supply capability among firms with depot formulation expertise and polymorphic crystallization control.
- Tablet:Immediate-release oral tablets contain aripiprazole as the active moiety with standard excipient matrices for dissolution control. United States Medicaid formularies drive volume concentration here, though pharmacy benefit manager substitution pressure compresses unit economics for undifferentiated generics.
- Injection:Long-acting injectable suspensions require aseptic microsphere or nanocrystal engineering to achieve sustained release over weeks. Hospital discharge planners in United States psychiatric units increasingly mandate depot formulations for adherence-mandated patients, shifting value toward service-integrated delivery.
- Oral Solution:Liquid formulation enables dose titration flexibility for geriatric or pediatric populations with swallowing difficulties.
- Extended-Release Tablet:Matrix-controlled or osmotic pump technologies extend absorption windows to support once-daily bipolar maintenance regimens.
Today's leader: Tablet. Tomorrow's challenger: Injection.
End User:
Procurement authority and reimbursement pathway complexity determine which care settings command manufacturer attention and service infrastructure investment.
- Hospitals:Inpatient psychiatric units and emergency departments administer acute stabilization doses with formulary committees controlling vendor selection through group purchasing organization contracts.
- Clinics:Community mental health centers and private psychiatric practices manage maintenance therapy with direct-to-clinic distribution bypassing wholesale markups.
- Community Health Services:Federally qualified health centers and county behavioral health programs serve uninsured populations with 340B drug pricing program eligibility.
- Outpatient Facilities:Standalone psychiatric urgent care and telehealth platforms are expanding fastest as site-of-care migration accelerates.
Procurement gravity centers on Hospitals. Volume expansion is climbing the fastest in Outpatient Facilities.
Delivery Mode:
Pharmacokinetic profile requirements and patient adherence risk stratification dictate route selection across treatment episodes.
- Intravenous:Reserved for acute agitation management in emergency department settings where rapid onset is clinically necessary.
- Intramuscular:Depot suspensions administered in gluteal or deltoid muscle achieve therapeutic concentrations for weeks, dominating schizophrenia maintenance protocols.
- Oral:First-line initiation and stable maintenance dosing for bipolar disorder and adjunctive major depressive disorder treatment.
- Subcutaneous:Emerging delivery route for patient-administered long-acting formulations under development.
Standard of care: Intramuscular. Development priority: Subcutaneous.
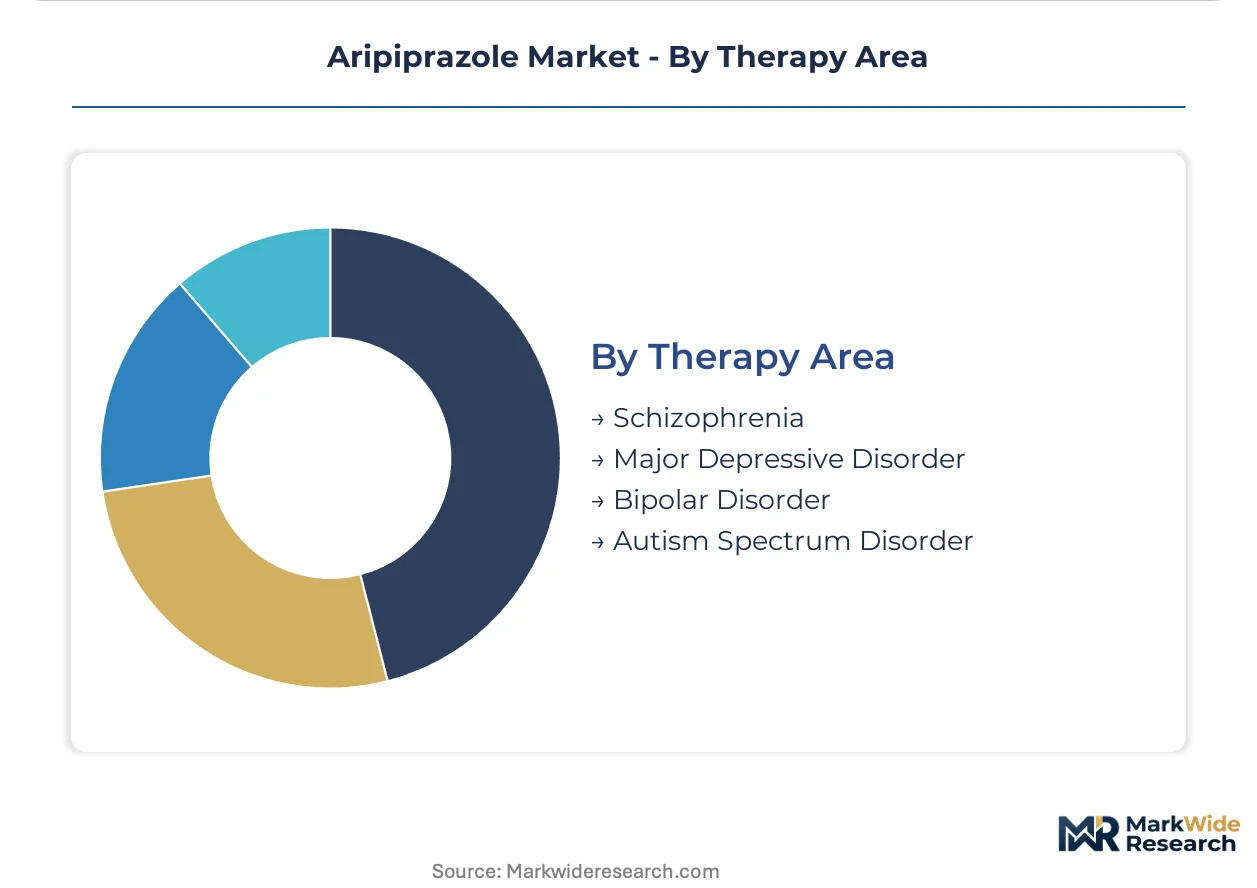
Therapy Area:
Indication-specific clinical guidelines and pediatric label expansion opportunities reshape demand composition across psychiatric and neurodevelopmental conditions.
- Schizophrenia:Maintenance therapy represents the foundational indication with treatment guidelines mandating depot antipsychotics for non-adherent patients, concentrating LAI demand in this segment.
- Major Depressive Disorder:Adjunctive use with antidepressants in treatment-resistant cases drives oral tablet volume in United States outpatient psychiatric practices.
- Bipolar Disorder:Mania and mixed episode management with maintenance protocols favoring extended-release formulations for adherence support.
- Autism Spectrum Disorder:Irritability indication in pediatric patients represents the expanding frontier with off-label prescribing gaining traction in developmental-behavioral pediatric clinics.
Volume anchor: Schizophrenia. Steepest expansion trajectory: Autism Spectrum Disorder.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost differentials between mature and emerging markets are redirecting aripiprazole API production toward jurisdictions with streamlined environmental compliance frameworks. Indian states with concentrated pharmaceutical manufacturing clusters now supply the majority of active pharmaceutical ingredient feedstock for oral tablet formulations consumed in Western markets.
United States
Medicaid formulary committees in 40 states now mandate prior authorization for oral aripiprazole when long-acting injectable alternatives are clinically indicated. FDA bioequivalence standards for generic depot formulations have tightened evidentiary requirements, extending development timelines for prospective entrants. New Jersey and Massachusetts host the primary sterile fill-finish capacity for branded LAI production serving hospital discharge protocols.
Germany
The Federal Joint Committee's benefit assessment procedures for atypical antipsychotics prioritize adherence-demonstrated formulations in reimbursement calculations. EMA centralized authorization pathways enable parallel market access across EU member states, reducing regulatory duplication for depot formulation sponsors. Baden-Württemberg's pharmaceutical manufacturing corridor concentrates oral tablet packaging operations for Central European distribution.
India
CDSCO mandates local clinical trial bridging studies for imported depot formulations, delaying multinational launch sequencing by 12-18 months. Telangana and Gujarat host backward-integrated API production facilities supplying crystalline aripiprazole to generic tablet manufacturers worldwide. Andhra Pradesh's Visakhapatnam pharmaceutical cluster is expanding sterile suspension capacity for emerging market LAI demand.
Japan
PMDA's Sakigake designation system accelerates review timelines for novel antipsychotic delivery mechanisms, though aripiprazole generics face standard abbreviated approval pathways. The Ministry of Health, Labour and Welfare's drug price revision cycle compresses margin retention for oral tablet formulations after patent expiry. Osaka-Kobe pharmaceutical manufacturing zone maintains specialized microsphere engineering capability for regional LAI supply.
Brazil
ANVISA's reliance on prior FDA or EMA approvals streamlines registration for aripiprazole generics, reducing time-to-market for Indian and Chinese exporters. The Unified Health System's psychiatric medication procurement favors oral tablet cost efficiency over adherence-optimized delivery modes. São Paulo state's pharmaceutical industrial park hosts the primary importation and tableting operations for national distribution.
Aripiprazole Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with formulation complexity determining competitive moat depth. The oral tablet category exhibits commoditized pricing pressure from pharmacy benefit manager channel control, while long-acting injectable supply concentrates among firms with depot engineering heritage and sterile processing infrastructure. Three archetypes dominate: originator companies with service-integrated delivery models, generic scale players with API backward integration, and regional specialists with regulatory pathway expertise. Capacity expansion in Indian sterile fill-finish facilities and strategic partnerships for pediatric indication development represent the primary competitive vectors.
Within the originator tier, Otsuka Pharmaceutical Co. Ltd. exemplifies service-integrated positioning through direct-to-clinic infrastructure and adherence program bundling. Among generic scale fabricators, Teva Pharmaceutical Industries Ltd. and Sun Pharmaceutical Industries Ltd. occupy positions defined by pharmacy benefit manager channel relationships and captive API supply respectively. These three anchors illustrate how competitive advantage migrates from molecular patent protection toward delivery mechanism engineering and supply chain configuration in the post-patent aripiprazole market.
| Leading Market Players |
|---|
| Cipla Limited |
| Aurobindo Pharma Ltd. |
| Otsuka Pharmaceutical Co. Ltd. |
| Hetero Drugs |
| Apotex Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Zydus Lifesciences |
| Alkem Laboratories Ltd. |
| Sun Pharmaceutical Industries Ltd. |
| Others |
Pricing and Supply Chain Analysis
Polymorphic crystallization process control costs cascade from Indian API manufacturers through oral tablet tiers to Medicaid formulary pricing bands in the United States. This cost transmission mechanism separates depot formulation premiums from commoditized generic tablet economics.
Pricing Analysis
Distributor margin compression in pharmacy benefit manager channels is intensifying because Teva and Sun Pharmaceutical Industries Ltd. compete on scale-based unit economics. Pricing stratifies across premium depot formulations, standard extended-release tablets, and economy immediate-release generics. Price differentiation hinges on bioequivalence certification tier and sterile manufacturing complexity. Hospital procurement committees show lowest price sensitivity for LAI adherence programs, while 340B community health centers face acute cost pressure on oral volumes.
Supply Chain Analysis
FDA bioequivalence certification gating for complex generic depot formulations restricts sterile fill-finish capacity to New Jersey, Massachusetts, and Visakhapatnam pharmaceutical clusters. Active pharmaceutical ingredient production draws from Telangana and Gujarat backward-integrated facilities, with crystalline aripiprazole feeding global tablet manufacturers. Single-source vulnerability concentrates in Indian environmental compliance zones. Distribution runs through direct-to-clinic specialty pharmacy channels for LAI, bypassing wholesale markups in high-volume psychiatric practices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The aripiprazole market compounds steadily through schizophrenia maintenance protocol mandates that institutionalize depot formulation demand across Medicaid-funded psychiatric units.
For Market Incumbents: Acquire sterile suspension manufacturing assets in Andhra Pradesh to capture emerging market LAI demand. Defend against Sun Pharmaceutical's API backward integration by securing polymorphic purity validation partnerships with analytical method development specialists. Prioritize pediatric autism spectrum indication expansion before label competitors consolidate developmental-behavioral pediatric clinic relationships. For New Entrants and Emerging Players: Launch via direct-to-clinic distribution models targeting United States outpatient facilities with telehealth-enabled psychiatric urgent care platforms. Penetrate European centralized authorization pathways for depot formulations in Germany, France, and Italy where EMA procedures reduce regulatory duplication. White-space concentration exists in subcutaneous patient-administered long-acting formulations under development. For Investors and Strategic Acquirers: Consolidation pressure builds where sterile manufacturing workforce scarcity commands premium wages in competitive labor markets. Five-to-ten year viability favors firms with depot engineering heritage and service-integrated delivery infrastructure over pure generic tablet scale. Target acquisition archetype: regional specialists with CDSCO regulatory pathway expertise and Indian sterile fill-finish partnerships. Monitor FDA draft guidance finalization on complex generic depot evidentiary standards as inflection signal for LAI competitive barrier reshaping.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Pediatric autism spectrum indication expansion opens developmental-behavioral pediatric clinic access. |
| Regulatory Approval Pathway | EMA centralized authorization reduces time-to-reimbursement across Germany, France, and Italy. |
| Manufacturing Scale-Up | Visakhapatnam sterile suspension capacity expansion serves emerging market LAI demand growth. |
| Backward Integration | Telangana API production facilities sustain margin on commoditized oral tablet volumes. |
| Strategic Partnership | Direct-to-clinic service infrastructure bundling elevates vendor selection above pure product attributes. |
Research Methodology
Bottom-up psychiatric practice prescribing modeling reconciled against top-down API production tracking forms the analytical core of this study. Primary interviews with drug development executives, formulary directors, hospital procurement managers, and payer access specialists combined with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and Medicaid formulary databases. Triangulation across stakeholder perspectives and regulatory documentation ensures segmentation accuracy.
Historical trendline analysis of treatment episode volumes and formulation mix shifts informed projection architecture across the modeling period. Segmentation dimensions include dosage form, administration route, patient population, and regional regulatory cluster. CAGRs derive from compounded annual growth patterns in prescription volume and reimbursement rate trajectories. Forecast inputs incorporate Medicaid formulary expansion timelines and sterile manufacturing capacity utilization rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA bioequivalence guidance revision or Indian environmental compliance enforcement actions. Model assumptions reflect documented treatment protocol mandates and payer reimbursement policies. A model refresh is warranted upon material change in depot formulation evidentiary standards or Medicaid prior authorization requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Compound Acetaminophen Market
Pharmaceuticals
Istradefylline API Market
Pharmaceuticals
Advanced Therapy Medicinal Products (Atmps) Market
Pharmaceuticals
Global Pharmaceuticals Market
Pharmaceuticals
PD-1/PD-L1 Inhibitor Market
Pharmaceuticals
Global Topical Analgesic Market
Pharmaceuticals
Tenecteplase Drugs Market
Pharmaceuticals
Europe Veterinary Pharmaceuticals Market
Pharmaceuticals
Global Aromatase Inhibitors Drug Market
Pharmaceuticals
Global Pulmonary Drugs Market
Pharmaceuticals
Pembrolizumab Market
Pharmaceuticals
Middle-East and Africa Meglitinide Market
Pharmaceuticals
Global Transdermal Drug Delivery Systems Market
Pharmaceuticals
Over-The-Counter (OTC) Analgesics Market
Pharmaceuticals
Wujibaifeng Pills Market
Pharmaceuticals
Global Pharmaceutical Gelatin Market