
 Italy Healthcare Market | 2026-2036
Italy Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Healthcare Market Insights
Home care is repositioning patient flow away from traditional acute facilities across Italy's regional health systems. Recordati Industria Chimica e Farmaceutica S.p.A. leverages its specialty pharmaceutical portfolio to anchor chronic disease management outside hospital walls. DiaSorin S.p.A. dominates in-vitro diagnostics supply to regional laboratory networks. Amplifon S.p.A. extends its audiology service model into home-fitted hearing solutions, competing with clinic-based distribution.
Healthcare encompasses the organized provision of medical services, therapeutic interventions, and preventive care delivered through institutional and ambulatory channels, with quality metrics measured by patient outcomes, access times, and clinical pathway adherence. Pharmaceuticals commands the largest revenue pool within product type segmentation, while AI Diagnostics registers the fastest structural expansion as hospitals integrate machine learning into radiology and pathology workflows. Telemedicine matures from emergency pandemic infrastructure into permanent reimbursement-eligible delivery mode under regional tariff agreements.
AIFA, the national pharmaceutical regulator, shapes market access through pricing and reimbursement negotiations that determine product commercialization timelines. The EU Medical Device Regulation and GDPR constrain data-driven diagnostic platforms, forcing compliance investments from technology developers. Stakeholders must monitor regional health authority procurement centralization as Lombardy and Veneto consolidate supplier contracts to extract volume discounts.
Market Dynamics
Regional devolution under the Servizio Sanitario Nazionale fragments procurement authority, creating divergent adoption velocities across Lombardy, Veneto, and Campania as each health authority negotiates independent supplier contracts and technology roadmaps.
Growth Catalysts
- EU Medical Device Regulation (MDR):The MDR's stricter clinical evidence requirements accelerate hospital IT upgrade cycles, concentrating demand for AI-enabled diagnostic platforms that automate compliance documentation.
- Home care patient flow:Chronic disease management outside acute facilities expands serviceable addressable market for remote monitoring devices and specialty pharmaceuticals delivered through regional pharmacy networks.
- Lombardy procurement centralization:Volume consolidation across Milan's hospital clusters extracts supplier discounts, freeing capital for digital pathology and radiology AI investments.
Market Restraints
- GDPR data governance:Cross-border health data transfers face Article 49 derogation complexity, forcing diagnostic platform developers to maintain Italy-only cloud infrastructure.
- Regional reimbursement variance:Telemedicine tariff eligibility differs between Veneto's autonomous pricing and Campania's national tariff adherence, fragmenting service rollout economics.
- Legacy EHR interoperability:Hospital information systems from disparate vendors resist API standardization, delaying AI diagnostic integration into clinical workflows.
Strategic Opportunities
- Sicily and Calabria infrastructure gap:Underserved southern regions present first-mover advantage for mobile diagnostic units and hub-and-spoke laboratory networks.
- AI-radiology convergence:Machine learning integration with PACS systems enables automated lesion detection, compressing radiologist report turnaround times.
- Regional health authority joint procurement:Emerging inter-regional purchasing consortia create single-entry-point contracts for multi-site technology deployment.
Industry Challenges
- Specialized AI-ML engineering talent:Scarce data science capacity within hospital IT departments delays model validation and clinical integration timelines.
- MDR notified body bottleneck:Extended conformity assessment queues stall market authorization for novel diagnostic algorithms.
- Multi-vendor system integration:Fragmented legacy infrastructure across regional health networks complicates unified platform deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Healthcare Market |
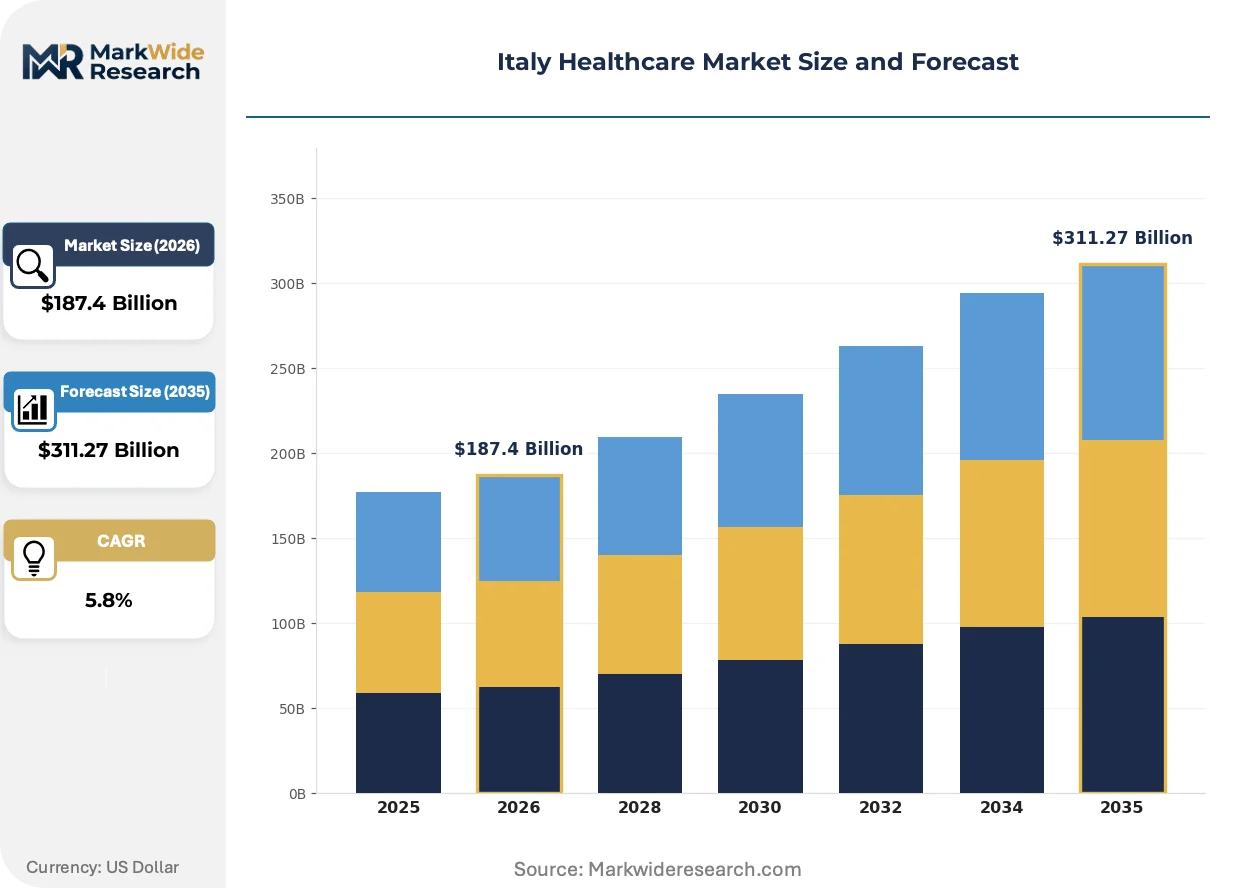
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $311.27 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medical Devices, Pharmaceuticals, Diagnostics, Nutraceuticals End User: Hospitals, Clinics, Home Care, Laboratories Delivery Mode: Online, Retail, Distributors, Direct Sales Technology: Telemedicine, Wearable Devices, AI Diagnostics, Electronic Health Records |
| Companies Covered | Recordati Industria Chimica e Farmaceutica S.p.A., DiaSorin S.p.A., Amplifon S.p.A., Safilo Group S.p.A., Newron Pharmaceuticals SpA, Pharmanutra S.p.A., Garofalo Health Care SpA, Health Italia S.p.A., Claire SpA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Healthcare Market Trends and Innovations
Telemedicine infrastructure hardens from emergency pandemic deployment into permanent reimbursement-eligible delivery mode, while AI diagnostics penetrates radiology and pathology workflows and regional procurement models consolidate supplier relationships.
Remote patient monitoring technology is decentralizing chronic disease surveillance from hospital wards to domestic settings. Lombardy's ATS health authorities now prescribe connected glucose meters and blood pressure cuffs for diabetes and hypertension cohorts. This shift compresses routine outpatient visit volumes while expanding recurring device revenue pools for regional distributors.
The EU AI Act's risk-based classification system imposes conformity obligations on diagnostic algorithms that influence patient treatment decisions. Italian hospitals must now maintain algorithmic impact assessments and human oversight protocols for AI-assisted radiology reads. High-risk medical device software faces stricter post-market monitoring, accelerating vendor investment in explainable AI architectures.
Regional health authorities are consolidating supplier contracts into multi-year framework agreements that bundle devices, software, and maintenance. Veneto's ULSS procurement offices now negotiate three-year radiology equipment packages with single-source accountability. This concentration displaces fragmented spot purchasing, favoring vendors with integrated platform capabilities and Italy-based service networks.
Italy Healthcare Market Segmentation
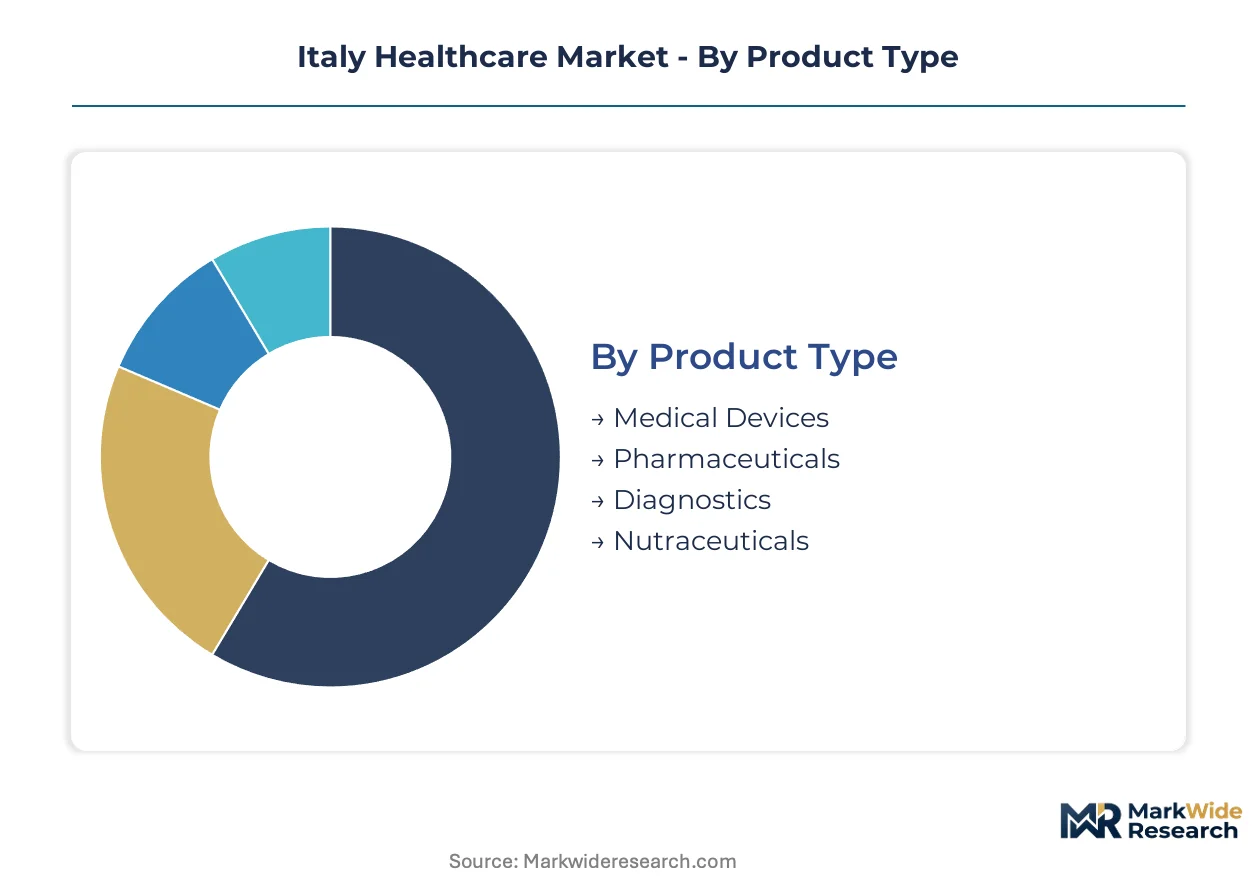
Italy's healthcare segmentation reflects the Servizio Sanitario Nazionale's dual pressure of aging infrastructure replacement and digital transformation mandates. Regional procurement fragmentation creates divergent upgrade cycles across Lombardy, Veneto, and southern health authorities.
Product Type:
Replacement cycles for capital equipment and therapeutic portfolios vary sharply between northern hospital clusters and underfunded southern networks.
- Medical Devices:Imaging systems, surgical instruments, and patient monitoring hardware face accelerated refresh timelines under EU MDR compliance deadlines. Lombardy's ATS health authorities consolidate MRI and CT scanner purchases into multi-year framework agreements, extracting volume discounts that free capital for AI-enabled upgrades.
- Pharmaceuticals:Specialty therapeutics and chronic disease management formulations anchor the largest revenue pool. AIFA pricing negotiations determine regional formulary placement, with oncology and immunology portfolios commanding priority access in Veneto's autonomous procurement zones.
- Diagnostics:In-vitro testing platforms and reagent supplies flow through regional laboratory networks.
- Nutraceuticals:Dietary supplements and medical nutrition products distribute through pharmacy channels and direct-to-patient subscription models.
Volume placements concentrate in Pharmaceuticals; the faster expansion belongs to Diagnostics as AI integration reshapes laboratory workflows.
End User:
Patient flow redirection from acute settings to decentralized care models restructures demand concentration across institutional and domestic channels.
- Hospitals:Acute care facilities in Milan, Rome, and Naples drive demand for high-value capital equipment and interventional technologies. EU AI Act compliance obligations now require algorithmic impact assessments for AI-assisted radiology and pathology departments, forcing IT infrastructure investments.
- Home Care:Remote monitoring devices and specialty pharmaceutical delivery expand the addressable market beyond traditional facility walls. Lombardy's diabetes and hypertension cohorts now receive prescribed connected glucose meters and blood pressure cuffs, compressing routine outpatient volumes while creating recurring device revenue streams.
- Clinics:Ambulatory surgical centers and specialist outpatient facilities concentrate in northern urban corridors.
- Laboratories:Regional hub-and-spoke networks process diagnostic samples from peripheral collection points.
Revenue concentration remains with Hospitals; Home Care climbs the fastest as regional authorities reallocate chronic disease management budgets.
Delivery Mode:
Channel economics shift toward consolidated procurement frameworks that bundle devices, software, and maintenance into single-accountability contracts.
- Distributors:Regional medical supply networks maintain inventory proximity to hospital clusters across Lombardy and Veneto. Veneto's ULSS procurement offices negotiate three-year radiology equipment packages with integrated service obligations, displacing fragmented spot purchasing.
- Direct Sales:Capital equipment manufacturers deploy Italy-based service teams for installation and compliance documentation. EU MDR's stricter clinical evidence requirements favor vendors with localized technical support capable of automating conformity documentation.
- Online:E-procurement platforms and telemedicine reimbursement portals gain tariff eligibility under regional agreements.
- Retail:Pharmacy networks handle nutraceuticals and select medical devices for home care patients.
Transaction volume pools with Distributors; Direct Sales gains share fastest as MDR complexity rewards vendor accountability consolidation.
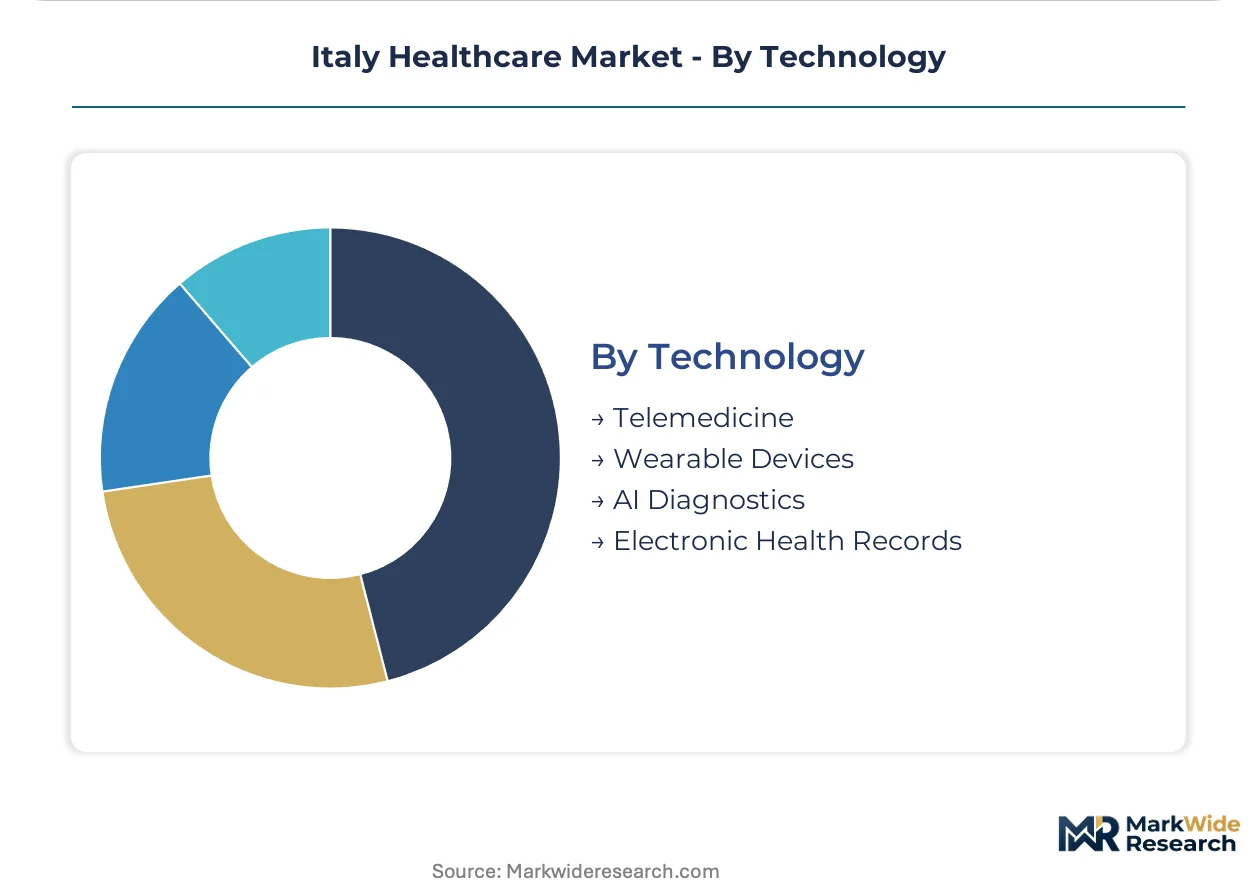
Technology:
Integration timelines for digital health platforms diverge between legacy EHR environments and greenfield AI deployments.
- AI Diagnostics:Machine learning algorithms for radiology lesion detection and pathology slide analysis compress report turnaround times. Italian hospitals must maintain human oversight protocols and explainable AI architectures under EU AI Act high-risk system classifications, accelerating vendor investment in compliant platforms.
- Telemedicine:Video consultation infrastructure hardens from emergency pandemic deployment into permanent reimbursement-eligible delivery mode. Regional tariff variance persists between Veneto's autonomous pricing and Campania's national tariff adherence, fragmenting service rollout economics.
- Wearable Devices:Connected monitoring hardware supports chronic disease surveillance in domestic settings.
- Electronic Health Records:Legacy hospital information systems from disparate vendors resist API standardization, delaying unified platform deployment.
Installed base concentrates in Electronic Health Records; AI Diagnostics shows the steepest expansion trajectory as PACS integration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lombardy's Zona Franca Milano special economic zone concentrates pharmaceutical manufacturing incentives, drawing production investment toward Milan's northern corridor while southern regions lag in comparable tax-advantaged infrastructure.
Lombardy
Milan's ATS health authorities drive demand for AI-enabled diagnostic platforms and multi-year radiology equipment frameworks. EU MDR compliance deadlines accelerate hospital IT refresh cycles across the region's hospital clusters. Brescia and Bergamo manufacturing zones anchor specialty pharmaceutical production for chronic disease management portfolios.
Veneto
Padua and Verona laboratory networks concentrate in-vitro diagnostics procurement under consolidated ULSS framework agreements. Veneto's autonomous tariff system enables telemedicine reimbursement models that diverge from national pricing schedules. Treviso-based health authorities negotiate three-year bundled contracts bundling devices, software, and maintenance obligations.
Campania
Naples metropolitan hospitals face infrastructure gaps that mobile diagnostic units and hub-and-spoke laboratory networks could address. National tariff adherence constrains telemedicine rollout economics compared to northern autonomous pricing zones. Caserta and Salerno peripheral collection points feed regional laboratory hubs with diagnostic samples.
Emilia-Romagna
Bologna's health technology assessment centers influence AIFA reimbursement negotiations for specialty therapeutics. The region's medical device distributors maintain inventory proximity to Modena and Parma hospital clusters. EU AI Act compliance obligations force algorithmic impact assessments for AI-assisted radiology departments across Rimini and Ravenna facilities.
Piedmont
Turin's hospital networks upgrade legacy EHR systems to accommodate API standardization for diagnostic platform integration. The region's pharmaceutical manufacturing base supplies oncology and immunology portfolios to northern European markets. GDPR Article 49 derogation complexity forces diagnostic developers to maintain Italy-only cloud infrastructure for cross-border data transfers.
Italy Healthcare Market Competitive Landscape
Top-tier vendors anchor hospital procurement frameworks, while mid-tier specialists compete for regional laboratory network contracts. The vendor base stratifies across integrated platform providers, single-product diagnostic manufacturers, and service-intensive audiology chains. Three archetypes dominate: pharmaceutical portfolio consolidators, in-vitro diagnostics platform operators, and retail-facing medical device distributors. M&A activity concentrates among specialty pharmaceutical targets, while regional procurement centralization rewards vendors with Italy-based service networks.
Within the pharmaceutical consolidator tier, Recordati Industria Chimica e Farmaceutica S.p.A. and Newron Pharmaceuticals SpA occupy positions anchored by chronic disease management portfolios. Among diagnostics specialists, DiaSorin S.p.A. exemplifies the in-vitro platform operator archetype serving regional laboratory networks. Amplifon S.p.A. represents the retail-medical convergence model, extending audiology services through clinic-based and home-fitted distribution channels. These three S.p.A. structures illustrate the dominant corporate form through which Italian healthcare competitors access capital markets and negotiate AIFA pricing frameworks.
| Leading Market Players |
|---|
| Recordati Industria Chimica e Farmaceutica S.p.A. |
| DiaSorin S.p.A. |
| Amplifon S.p.A. |
| Safilo Group S.p.A. |
| Newron Pharmaceuticals SpA |
| Pharmanutra S.p.A. |
| Garofalo Health Care SpA |
| Health Italia S.p.A. |
| Claire SpA |
| Others |
Pricing and Supply Chain Analysis
API and raw material price indices cascade through Italy's pharmaceutical supply chain into tiered procurement contracts, compressing margins for generic manufacturers while specialty therapeutics retain pricing power through AIFA-negotiated exclusivity windows.
Pricing Analysis
Short lead-time premiums dominate hospital procurement negotiations across Lombardy and Veneto, where ATS and ULSS health authorities pay contract premiums for guaranteed MRI scanner delivery within ninety-day windows versus spot-market discounts for inventory-clearing devices. Three-tier pricing structure across premium, standard, and economy levels separates AI-enabled diagnostic platforms from legacy imaging hardware and refurbished equipment. Cost compression in the economy tier is intensifying because regional procurement centralization extracts volume discounts from distributors. Public hospital purchasing committees exhibit highest price sensitivity; private clinic networks and home care providers demonstrate greater willingness to absorb premium pricing for integrated service bundles.
Supply Chain Analysis
Single-source vulnerability sits with German and Swiss precision imaging component suppliers, whose specialized manufacturing capacity feeds Italy's radiology equipment refresh cycles. Active pharmaceutical ingredients draw from India and China, while diagnostic reagents source predominantly from Germany and the United States. Tariff exposure on Chinese-sourced medical device electronics creates margin pressure for domestic distributors. Distribution runs through regional medical supply networks maintaining inventory proximity to hospital clusters, with Veneto's ULSS offices consolidating three-year framework agreements that displace fragmented spot purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Italy's healthcare market occupies a technology-transition phase where AI diagnostic platforms displace legacy imaging workflows and manual pathology review, forcing capital reallocation across regional health authority budgets.
For Market Incumbents: Cement procurement lock-in through multi-year service contracts bundling AI-enabled platform upgrades with legacy hardware maintenance, defending against emerging cloud-native diagnostic entrants. Pursue backward integration into Italy-based technical support networks to automate EU MDR compliance documentation and accelerate hospital IT refresh capture.
For New Entrants and Emerging Players: The price-point gap between premium AI diagnostic suites and economy-tier refurbished imaging hardware creates entry space for mid-market platforms targeting Campania and Sicily's infrastructure-starved health authorities. Mobile diagnostic units and hub-and-spoke laboratory networks represent the most penetrable white-space; partner with regional pharmacy distribution networks for last-mile device deployment.
For Investors and Strategic Acquirers: Distressed-cycle entries favor specialty pharmaceutical targets with chronic disease management portfolios in northern Italy's manufacturing corridors, where AIFA pricing negotiations determine long-term revenue visibility. Watch regional procurement centralization momentum across Lombardy and Veneto as the inflection signal for vendor consolidation opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR compliance accelerates market authorization for AI diagnostic algorithms under notified body assessment. |
| Hospital System Partnership | Lombardy's ATS procurement frameworks favor vendors with integrated platform capabilities and localized service networks. |
| Software Companion Development | Explainable AI architectures satisfy EU AI Act high-risk system obligations for radiology and pathology workflows. |
| Reimbursement Strategy | Veneto's autonomous tariff system enables telemedicine pricing models diverging from national schedules. |
| Backward Integration | In-house technical support capacity automates conformity documentation and compresses hospital sales cycles. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews involving hospital procurement managers, biomedical engineers, GPO contracts specialists, and AIFA regulatory affairs leads. AIFA pricing databases, EU MDR notified body registries, regional health authority procurement portals, and hospital IT expenditure surveys supplied quantitative benchmarks. Bottom-up demand modeling across product type, end user, and technology segments triangulated against top-down macroeconomic indicators.
Granularity-level modeling deployed product-type splits for medical devices, pharmaceuticals, diagnostics, and nutraceuticals; end-user segmentation across hospitals, home care, clinics, and laboratories; and technology disaggregation for AI diagnostics, telemedicine, wearables, and electronic health records. CAGRs derived from regression analysis against healthcare expenditure trends and digital adoption curves. Regional devolution patterns and procurement centralization timelines informed geographic allocation assumptions.
Underlying measurement precision varies by segment; AI diagnostics and telemedicine carry tighter precision than legacy EHR and nutraceutical categories due to disclosed contract values and tariff schedules. Forecasts reflect documented assumptions regarding AIFA pricing negotiation outcomes, EU AI Act implementation timelines, and regional procurement consolidation velocity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Atypical Antipsychotic Market
Pharmaceuticals
Endocarditis Drugs Market
Pharmaceuticals
Estrogen Replacement Therapy (ERT) Market
Pharmaceuticals
Global Immuno Oncology Drugs Market
Pharmaceuticals
Plasma-Derived Drugs Market
Pharmaceuticals
Otic Drugs Market
Pharmaceuticals
H2-Receptor Antagonists Market
Pharmaceuticals
Middle-East and Africa Diabetes Drugs Market
Pharmaceuticals
Global Seasonal Affective Disorder Therapeutics Market
Pharmaceuticals
Trenbolone Enanthate Market
Pharmaceuticals
Oral & Topical Anaesthetics Market
Pharmaceuticals
Nimodipine Market
Pharmaceuticals
Pembrolizumab Market
Pharmaceuticals
Iodine Deficiency Drug Market
Pharmaceuticals
Long-Acting Monoclonal Antibodies Market
Pharmaceuticals
Mail Order Pharmacy Market