
 Generic Pharmaceuticals Contract Manufacturing Market | 2026-2036
Generic Pharmaceuticals Contract Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Generic Pharmaceuticals Contract Manufacturing Market Intelligence
India's bulk drug and formulation corridor is reconfiguring global sourcing patterns for off-patent medicines. Catalent, Inc. leverages integrated biologics-to-sterile-injectable capabilities across North American and European facilities. Syngene International Ltd. anchors its competitive position through dedicated R&D campuses serving multinational pharmaceutical clients. Aurobindo Pharma dominates vertically integrated API-to-tablet supply, particularly in antiretroviral and cardiovascular categories.
Generic pharmaceuticals contract manufacturing encompasses the outsourced production of bioequivalent medicines after originator patent expiry, spanning active pharmaceutical ingredient synthesis, finished dosage form conversion, and regulatory-batch packaging under client or co-developed specifications. The discipline requires adherence to pharmacopeial standards—USP, EP, and ICH Q7 guidelines—governing potency uniformity, dissolution profiles, and impurity thresholds to secure therapeutic equivalence approvals. API manufacturing commands the deepest margin pools due to capital intensity and regulatory scrutiny, while injectable finished dosage forms represent the fastest-expanding segment driven by biologic patent cliffs and sterility-assurance complexity. Tablet production retains volume leadership but faces margin compression from commoditization in mature therapeutic areas.
FDA enforces Current Good Manufacturing Practice mandates through facility inspections and warning letters that determine market access eligibility for US-bound products. EMA's revised GMP Annex 1 on sterile manufacturing elevates environmental monitoring requirements, reshaping investment priorities for European-serving contractors. India's CDSCO aligns with WHO prequalification standards to accelerate export approvals for African and Southeast Asian markets. Stakeholders must monitor regulatory divergence between FDA's risk-based inspection model and EMA's quality metrics reporting requirements when siting multi-regional supply networks.
Market Dynamics
FDA's Quality Management Maturity program is compressing competitive margins for contract manufacturers serving US markets, forcing facility upgrades that smaller operators cannot finance. Hospital procurement of sterile injectables is accelerating in North America, creating demand-pull for high-containment manufacturing capacity that outstrips current supply.
Growth Catalysts
- Biologic patent cliffs:Monoclonal antibodies and insulin analogues losing exclusivity are expanding addressable demand for sterile injectable manufacturing. Hospital systems in the United States are consolidating purchasing around pre-qualified sterile capacity.
- EMA's revised GMP Annex 1:Elevated environmental monitoring requirements for aseptic processing are advantaging contractors with isolator technology and real-time particle monitoring systems.
- Andhra Pradesh and Telangana cluster formation:API-to-finished-dose integrated parks in these Indian states are reducing logistics costs and regulatory handoff friction for export-oriented production.
Market Restraints
- KSM and intermediate supply concentration:China dominates key starting material production for antiretroviral and oncology APIs, creating single-source vulnerability for Western formulators.
- FDA warning letter accumulation:Data integrity deficiencies cited at Indian and Chinese facilities are extending approval timelines for ANDA-dependent revenue streams.
- Energy cost volatility:Cryogenic storage and continuous manufacturing operations face margin pressure from natural gas and electricity price swings in European manufacturing zones.
Strategic Opportunities
- CDSCO-WHO prequalification alignment:India's streamlined export pathway for African and Southeast Asian markets opens volume contracts for antiretroviral and tuberculosis fixed-dose combinations.
- Continuous manufacturing retrofit:Batch-to-continuous conversion for oral solids reduces facility footprint and accelerates product changeover for high-mix, low-volume portfolios.
- Prefilled syringe and auto-injector assembly:Self-administration trends in chronic disease management are expanding demand for device-integrated sterile fill-finish capacity.
Industry Challenges
- Aseptic processing technician scarcity:Isolator operation and environmental monitoring expertise commands wage premiums that erode labor cost advantages in traditional outsourcing destinations.
- Legacy quality management system migration:Paper-based batch records and disconnected ERP implementations impede real-time release and continuous process verification.
- Multi-regional dossier divergence:FDA, EMA, and WHO prequalification requirements for stability data and impurity specifications force redundant analytical method development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Generic Pharmaceuticals Contract Manufacturing Market |
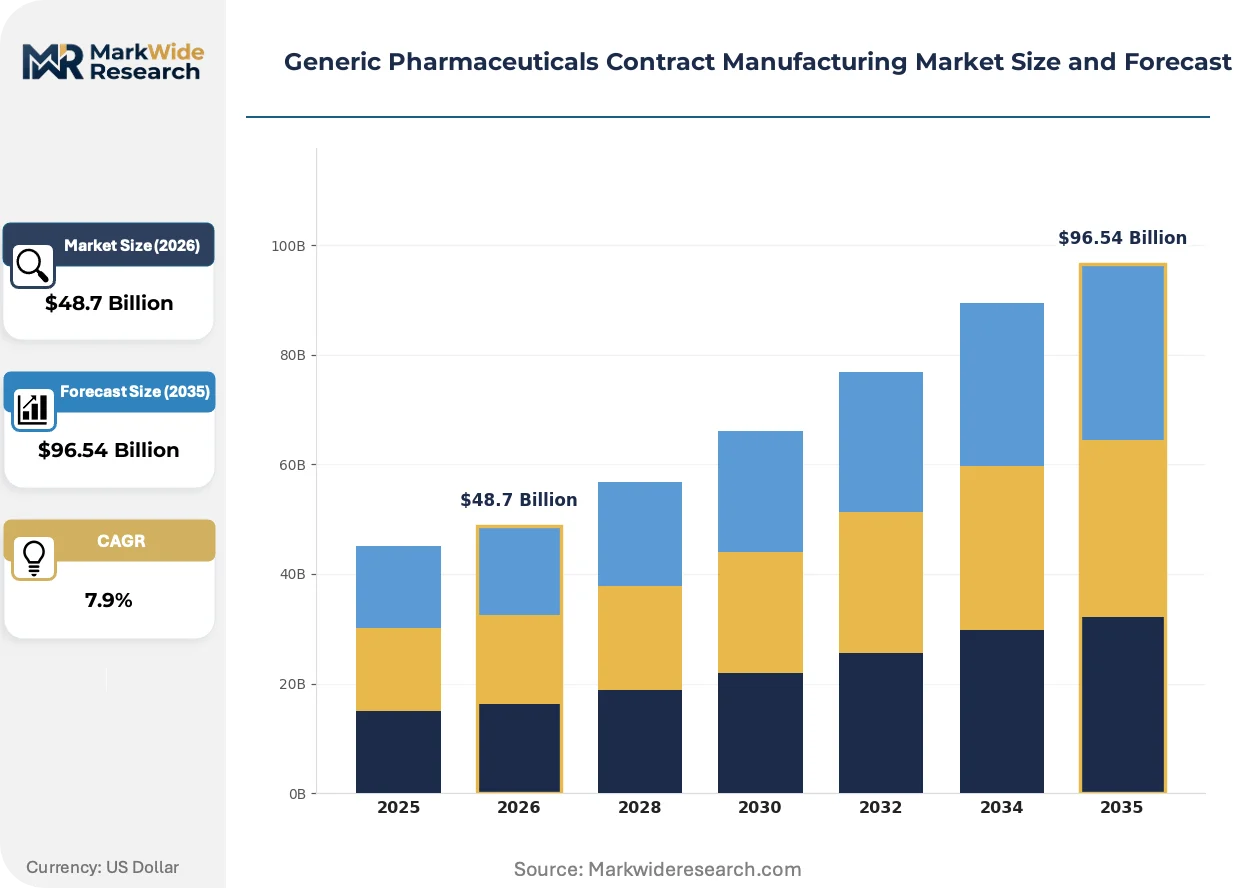
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $96.54 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: API Manufacturing, Finish Dosage Form Production, Packaging, Quality Control Product Type: Tablets, Capsules, Injectables, Ointments End User: Pharmaceutical Companies, Biotech Firms, Hospitals, Clinics Delivery Mode: Bulk Delivery, Direct Shipment, Retail Distribution, Online Sales |
| Companies Covered | Catalent, Inc., Curia Global, Inc., Pfizer CentreOne, Syngene International Ltd., Aurobindo Pharma, Recipharm AB, Siegfried Holding AG, Jubilant Generics Ltd., Alcami Corp., Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Generic Pharmaceuticals Contract Manufacturing Market Strategic Shifts & Innovations
Process analytical technology and real-time release testing are compressing batch release timelines from weeks to days. Regulatory convergence around ICH Q12 lifecycle management is enabling post-approval change management flexibility that rewards digitally mature contractors.
Single-use bioreactor systems are migrating from stainless-steel dominance in mammalian cell culture production. CDMOs serving biosimilar developers are adopting disposable mixing and storage to reduce cross-contamination risk and facility turnaround time. This migration from fixed equipment is enabling multi-product campaigns in smaller footprints, compressing capital intensity thresholds for market entry.
EMA's revised GMP Annex 1 on sterile manufacturing mandates barrier technology and automated environmental monitoring for all new aseptic facilities. European-serving contractors are retrofitting cleanrooms with isolators and restricted access barrier systems to maintain supply eligibility. Fill-finish operations for oncology injectables and ophthalmics face the steepest compliance investment requirements.
Hospital procurement consolidation is displacing fragmented purchasing through group purchasing organizations and direct manufacturer contracting. IDN-affiliated hospitals in the United States are narrowing supplier panels to three to five pre-qualified sterile injectable sources. This concentration is most visible in oncology and anti-infective therapeutic categories where supply security outweighs unit price optimization.
Generic Pharmaceuticals Contract Manufacturing Market Segmentation
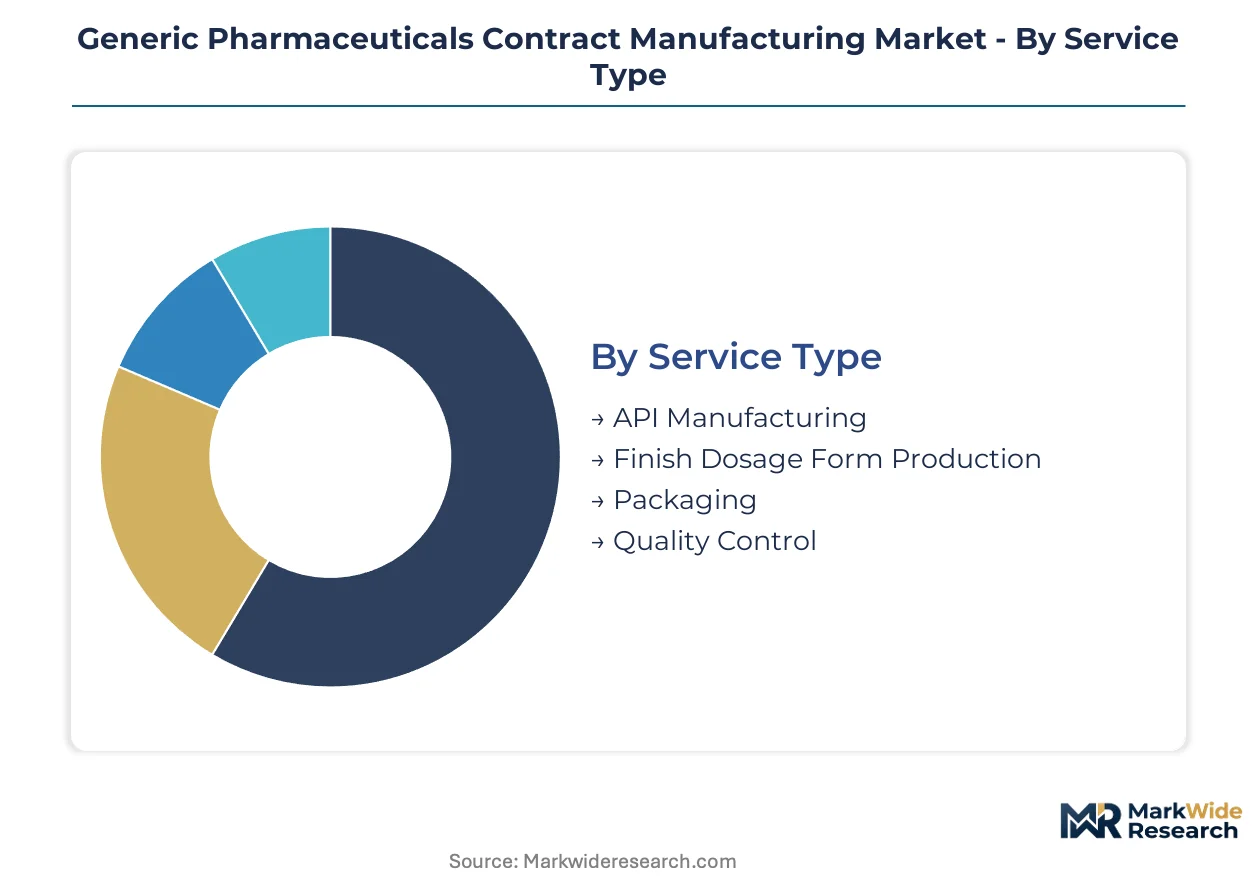
Contract manufacturing segmentation reveals distinct margin profiles and regulatory exposure across service tiers. Service type determines capital intensity and compliance burden. Product type governs sterility requirements and batch complexity. End-user concentration shapes volume predictability and pricing power.
Service Type:
After-sales service intensity varies sharply across service tiers, with API manufacturing demanding the most intensive technical support and regulatory maintenance.
- API Manufacturing:Active pharmaceutical ingredient synthesis requires multi-step organic chemistry, crystallization optimization, and impurity profiling under ICH Q7 guidelines. Demand concentrates in Andhra Pradesh and Telangana, where integrated parks reduce regulatory handoff friction for export-oriented production. FDA's Quality Management Maturity program is elevating compliance thresholds that favor capital-rich operators.
- Finish Dosage Form Production:Conversion of APIs into tablets, capsules, and sterile injectables demands formulation science and bioequivalence demonstration. Hospital procurement of sterile injectables is accelerating across North America, creating demand-pull for high-containment manufacturing capacity.
- Packaging:Regulatory-batch labeling, serialization, and cold-chain configuration for temperature-sensitive products.
- Quality Control:Analytical method development, stability testing, and release documentation under pharmacopeial standards.
By volume, Finish Dosage Form Production leads. By growth pace, API Manufacturing is ahead.
Product Type:
Cost tier stratification separates commodity oral solids from premium sterile formats requiring isolator technology and real-time environmental monitoring.
- Injectables:Sterile fill-finish for solutions, suspensions, and lyophilized products demands aseptic processing under EMA's revised GMP Annex 1. Biologic patent cliffs for monoclonal antibodies and insulin analogues are expanding addressable demand. Isolator operation and environmental monitoring expertise commands wage premiums that erode traditional labor cost advantages.
- Tablets:Compressed oral solids remain the volume foundation for chronic disease management and cardiovascular therapy. Production retains leadership but faces margin compression from commoditization in mature therapeutic areas.
- Capsules:Hard-shell and soft-gel formats for immediate-release and modified-release formulations.
- Ointments:Semi-solid topical preparations requiring homogenization and preservative efficacy validation.
By revenue contribution, Injectables commands premium positioning. By unit volume, Tablets dominates.
End User:
Customer type segmentation distinguishes between research-stage demand and commercial-scale procurement with divergent qualification timelines.
- Pharmaceutical Companies:Large generic sponsors outsourcing production to manage capacity constraints and geographic diversification. IDN-affiliated hospitals in the United States are narrowing supplier panels to three to five pre-qualified sterile injectable sources, concentrating purchasing power.
- Biotech Firms:Development-stage companies lacking internal manufacturing infrastructure for biosimilar and complex generic programs.
- Hospitals:Direct contracting for sterile injectables through group purchasing organizations, prioritizing supply security over unit price.
- Clinics:Smaller-volume procurement of prefilled syringes and auto-injectors for chronic disease management.
By contract value, Pharmaceutical Companies lead. By growth trajectory, Biotech Firms is expanding most quickly.
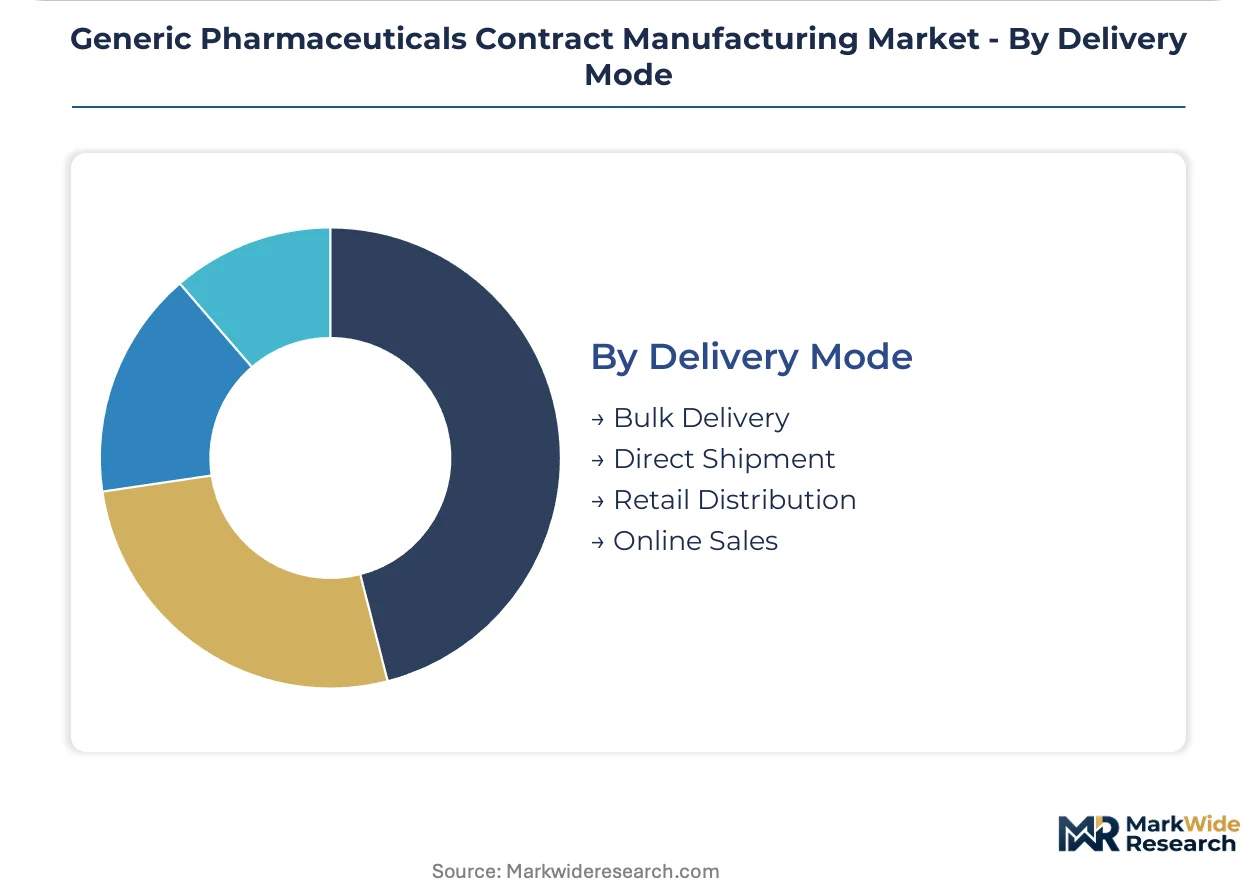
Delivery Mode:
Supply chain configuration determines working capital requirements and regulatory custody documentation across distribution pathways.
- Bulk Delivery:API and intermediate shipment to formulator facilities for further processing. KSM and intermediate supply concentration in China creates single-source vulnerability for Western formulators dependent on antiretroviral and oncology starting materials.
- Direct Shipment:Finished dose delivery from contract manufacturer to sponsor warehouse or designated distribution center.
- Retail Distribution:Packaged product routing through wholesale and pharmacy channels with serialization compliance.
- Online Sales:Direct-to-patient or direct-to-pharmacy platforms requiring temperature-controlled logistics and track-and-trace integration.
By shipment frequency, Bulk Delivery leads. By complexity growth, Online Sales shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
API synthesis and sterile fill-finish capacity cluster in jurisdictions with established regulatory pathways and cost-advantaged manufacturing ecosystems. Contract manufacturers site facilities based on FDA, EMA, and CDSCO alignment, with logistics infrastructure and skilled labor pools determining sub-national concentration.
United States
Hospital procurement consolidation through IDN-affiliated networks is narrowing sterile injectable supplier panels to pre-qualified domestic sources. FDA's Quality Management Maturity program elevates compliance thresholds that favor capital-rich operators with isolator technology. North Carolina and Massachusetts host the densest concentrations of biologics-to-sterile-injectable integrated facilities.
Germany
EMA's revised GMP Annex 1 on sterile manufacturing is retrofitting cleanrooms with restricted access barrier systems across Bavaria and Baden-Württemberg. German contractors serve as the primary fill-finish gateway for biosimilar developers targeting European markets. Frankfurt-Rhine-Main logistics corridors enable rapid distribution to hospital networks across the continent.
India
CDSCO-WHO prequalification alignment is accelerating export approvals for antiretroviral and tuberculosis fixed-dose combinations bound for African markets. Andhra Pradesh and Telangana states are multiplying API-to-finished-dose integrated parks that reduce regulatory handoff friction. Hyderabad anchors the densest cluster of US FDA-inspected formulation facilities outside North America.
Switzerland
Swissmedic's alignment with EMA standards positions Basel and Zurich-based contractors as premium-tier suppliers for complex generics and oncology injectables. The country's dual-track regulatory recognition with FDA and EMA reduces multi-regional dossier redundancy. Precision manufacturing heritage from pharmaceutical multinationals migrates into specialized CDMO operations.
China
NMPA's accelerated generic approval pathways are expanding domestic contract manufacturing capacity for oral solids and injectables. Key starting material production for antiretroviral and oncology APIs concentrates in Jiangsu and Zhejiang provinces, creating supply-chain leverage over Western formulators. Shanghai and Suzhou industrial parks attract multinational sponsors seeking cost-advantaged technical capabilities.
Generic Pharmaceuticals Contract Manufacturing Market Key Industry Players
Vertically integrated specialists and platform-scale operators split the market between margin-capture depth and portfolio breadth. The vendor base stratifies across three tiers: capital-intensive API manufacturers with captive intermediate supply, multi-modality CDMOs with biologics-to-small-molecule flexibility, and regional formulators serving domestic generics markets. Competitive moves center on isolator technology deployment for EMA Annex 1 compliance and backward integration into key starting material production to reduce China-dependent vulnerability.
Among North American platform operators, Catalent, Inc. and Curia Global, Inc. exemplify the biologics-to-sterile-injectable capability integration that hospital procurement consolidation rewards. Indian vertically integrated specialists including Syngene International Ltd. occupy positions anchored by dedicated R&D campuses and US FDA-inspected manufacturing footprints. These archetypes represent divergent bets on whether sterile injectable complexity or API-to-tablet margin capture delivers superior returns through the biologic patent cliff cycle.
| Leading Market Players |
|---|
| Catalent, Inc. |
| Curia Global, Inc. |
| Pfizer CentreOne |
| Syngene International Ltd. |
| Aurobindo Pharma |
| Recipharm AB |
| Siegfried Holding AG |
| Jubilant Generics Ltd. |
| Alcami Corp., Inc. |
| Others |
Cost & Logistics Intelligence
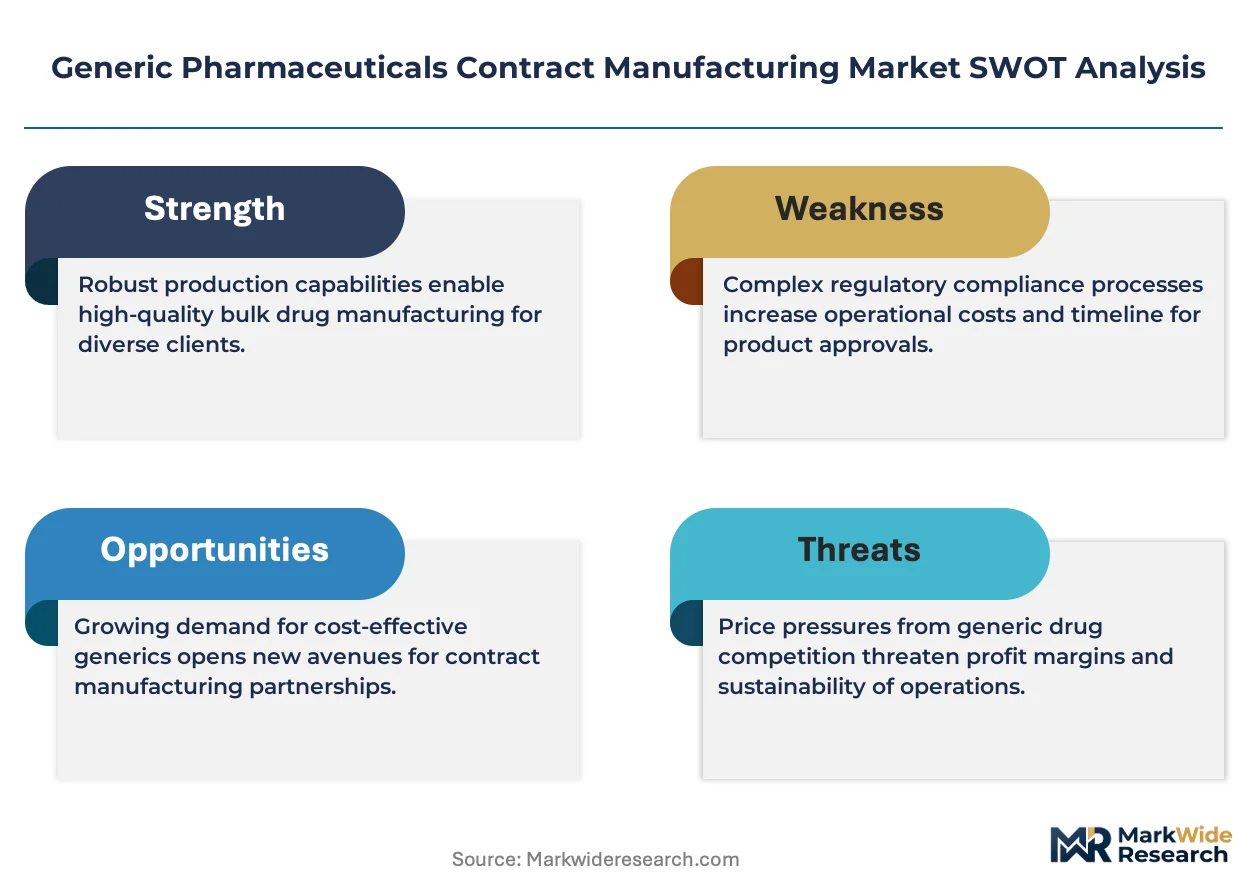
China's dominance in key starting material production for antiretroviral and oncology APIs concentrates upstream margin capture, forcing Western formulators to absorb cost volatility or pursue backward integration into intermediate synthesis. Hospital procurement consolidation through IDN-affiliated networks downstream creates tiered pricing power that separates pre-qualified sterile capacity from commodity oral solid suppliers.
Pricing Analysis
FDA's Quality Management Maturity program dictates the pricing tier structure across contract manufacturing services, separating isolator-equipped facilities from conventional cleanroom operations. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and sterility assurance complexity. Cost compression in oral solid tablets is intensifying because of commoditization in cardiovascular and antiretroviral categories. Biotech firms exhibit highest price sensitivity due to development-stage capital constraints, while hospital systems prioritize supply security over unit cost.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk assessment for Western generic sponsors dependent on Jiangsu and Zhejiang province KSM production. API synthesis draws from India, China, and Switzerland, with sterile fill-finish capacity clustering in Germany and the United States. Single-source vulnerability concentrates in oncology and antiretroviral starting materials. Distribution runs through bulk API shipment to integrated formulation parks, with direct finished dose delivery to sponsor warehouses or IDN-designated distribution centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across the vendor base creates entry niches as hospital procurement consolidation displaces fragmented purchasing through pre-qualified supplier panels.
For Market Incumbents: Entrench market position through isolator technology deployment for EMA Annex 1 compliance and captive intermediate production to reduce China-dependent vulnerability. FDA warning letter accumulation at competitor facilities creates qualification timeline advantages for capital-rich operators with established US FDA inspection records. Capacity addition in Andhra Pradesh and Telangana integrated parks reinforces geographic diversification against single-country regulatory risk. For New Entrants and Emerging Players: Prefilled syringe and auto-injector assembly for chronic disease management represents the most penetrable entry point, given self-administration trends and device-integrated sterile fill-finish capacity scarcity. CDSCO-WHO prequalification alignment for African and Southeast Asian antiretroviral markets offers volume contracts with streamlined export pathways. Partner with established API suppliers for regulatory-batch packaging and serialization rather than greenfield manufacturing investment. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed multi-modality CDMOs lacking biologics-to-sterile-injectable integration. Five-to-ten year viability hinges on isolator technology deployment and real-time release testing capability. Watch FDA Quality Management Maturity program enforcement intensity as inflection indicator for competitive margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Isolator Technology Deployment | EMA Annex 1 compliance secures European hospital procurement eligibility for oncology injectables. |
| Backward Integration into KSM Production | Captive intermediate synthesis reduces China-dependent supply chain vulnerability for antiretroviral APIs. |
| Continuous Manufacturing Retrofit | Batch-to-continuous conversion compresses facility footprint for high-mix oral solid portfolios. |
| CDSCO-WHO Prequalification Alignment | Streamlined export pathway opens volume contracts for African and Southeast Asian markets. |
| Prefilled Syringe Assembly Capacity | Device-integrated fill-finish captures self-administration trend in diabetes and autoimmune therapy. |
Research Approach
A standing panel of regulatory affairs leads, hospital procurement managers, CDSCO inspection officers, and sterile manufacturing engineers provided ongoing calibration across primary interview rounds. Secondary validation drew from FDA warning letter databases, EMA GMP inspection reports, WHO prequalification listings, and CDSCO export approval records. Bottom-up facility capacity modeling triangulated against top-down therapeutic category demand projections.
Scenario-bracketing framed analytical approach across the analysis window, with segmentation dimensions spanning service type, product format, end-user concentration, and regional regulatory cluster. CAGRs derived from facility utilization rates, patent expiry calendars, and hospital procurement consolidation trajectories. Forecast inputs incorporated biologic patent cliff timing and EMA Annex 1 retrofit investment cycles.
Practitioners should monitor FDA Quality Management Maturity program enforcement intensity and China KSM export policy shifts for early signals of competitive margin compression. Forecasts reflect assumptions around regulatory inspection cadence and hospital procurement panel consolidation pace. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Vasopressin Antagonists Market
Pharmaceuticals
Contraceptive Drugs Market
Pharmaceuticals
MRI Contrast Media Agents Market
Pharmaceuticals
Alprazolam Powder Market
Pharmaceuticals
Carbapenem Market
Pharmaceuticals
Saline Laxative Market
Pharmaceuticals
Sitagliptin Market
Pharmaceuticals
Global Colorectal Cancer Therapeutics Market
Pharmaceuticals
PD-1/PD-L1 Inhibitor Market
Pharmaceuticals
Asia-Pacific Small Molecule Sterile Injectable Drugs Market
Pharmaceuticals
Performance Enhancing Drugs Market
Pharmaceuticals
Short-Acting Insulin Market
Pharmaceuticals
Global Antiemetic Drugs Market
Pharmaceuticals
Croatia Pharmaceutical Market
Pharmaceuticals
Antiplatelet Market
Pharmaceuticals
United States Over the Counter (OTC) Drugs Market