
 Asia Pacific SGLT2 Inhibitors Market | 2026-2036
Asia Pacific SGLT2 Inhibitors Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific SGLT2 Inhibitors Market Insights
Dapagliflozin is hardening its position as the preferred molecular backbone across combination therapies in Asia Pacific, displacing older oral hypoglycemic agents in hospital formularies. AstraZeneca leverages its cardiovascular outcome data to anchor premium positioning in Japan and Australia. Boehringer Ingelheim sustains manufacturing scale through its alliance with Eli Lilly, while Merck & Co. competes on cost-access programs in Southeast Asian markets.
SGLT2 inhibitors are a class of oral antihyperglycemic agents that block sodium-glucose cotransporter-2 in renal proximal tubules to promote urinary glucose excretion, with select compounds also demonstrating blood-pressure-lowering and cardioprotective effects through hemodynamic and metabolic pathways. Their primary purpose is glycemic management in type 2 diabetes patients with comorbid cardiovascular or chronic kidney disease risk. Dapagliflozin and empagliflozin dominate current prescription volumes across hospital and specialty pharmacy channels, while canagliflozin faces structural headwinds from renal safety monitoring requirements that have shifted margin pools toward the former two agents. The chronic kidney disease application segment is expanding fastest as nephrologists integrate SGLT2 inhibitors into standard-of-care protocols ahead of dialysis progression curves.
Japan's PMDA, Australia's TGA, and China's NMPA each maintain distinct cardiovascular outcome evidence requirements that shape trial investment priorities and label expansion timelines for manufacturers seeking broad reimbursement. India's CDSCO and state-level pharmacy councils are developing bioequivalence standards for domestic ertugliflozin copies that will determine market access for local producers like Glenmark Pharmaceuticals. Stakeholders must monitor how China's volume-based procurement reforms and Japan's biennial price revision cycles interact to reshape regional pricing corridors and portfolio allocation decisions.
Market Dynamics
Hospital formularies across Asia Pacific are consolidating prescribing authority around SGLT2 inhibitors with cardiovascular outcome labeling, compressing the competitive window for older oral hypoglycemic agents and reshaping manufacturer access strategies.
Growth Catalysts
- Japan's PMDA cardiovascular outcome labeling requirements:These standards accelerate clinician familiarity with renal-protective indications, expanding hospital-based prescribing authority.
- Chronic kidney disease protocols:Nephrologists integrate SGLT2 inhibitors into standard-of-care ahead of dialysis progression curves, creating new prescriber segments.
- China's volume-based procurement reforms:Provincial reimbursement lists widen for domestic API production, concentrating demand within national procurement corridors.
Market Restraints
- API supply concentration:Active pharmaceutical ingredient manufacturing clusters in specific coastal Chinese provinces create geographic vulnerability to environmental compliance shutdowns.
- Renal safety monitoring requirements:Canagliflozin faces structural headwinds from ongoing nephrotoxicity surveillance protocols that elevate total cost of therapy.
- Biosimilar substitution pressure:India's CDSCO bioequivalence standards for ertugliflozin copies threaten margin pools for originator compounds.
Strategic Opportunities
- Southeast Asian cost-access programs:Merck & Co.'s pricing models demonstrate viable pathways for volume penetration in underpenetrated markets.
- Combination therapy expansion:Dapagliflozin-backbone formulations displace sulfonylurea combinations in Australian hospital formularies.
- Japan's biennial price revision cycles:These regulatory timelines create predictable windows for portfolio reallocation and label expansion investment.
Industry Challenges
- Cross-functional medical affairs talent:The convergence of cardiology, nephrology, and endocrinology prescribing creates skill gaps in field force training.
- Multi-jurisdictional trial design:Australia's TGA, China's NMPA, and Japan's PMDA each demand distinct cardiovascular outcome evidence packages, fragmenting clinical development resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific SGLT2 Inhibitors Market |
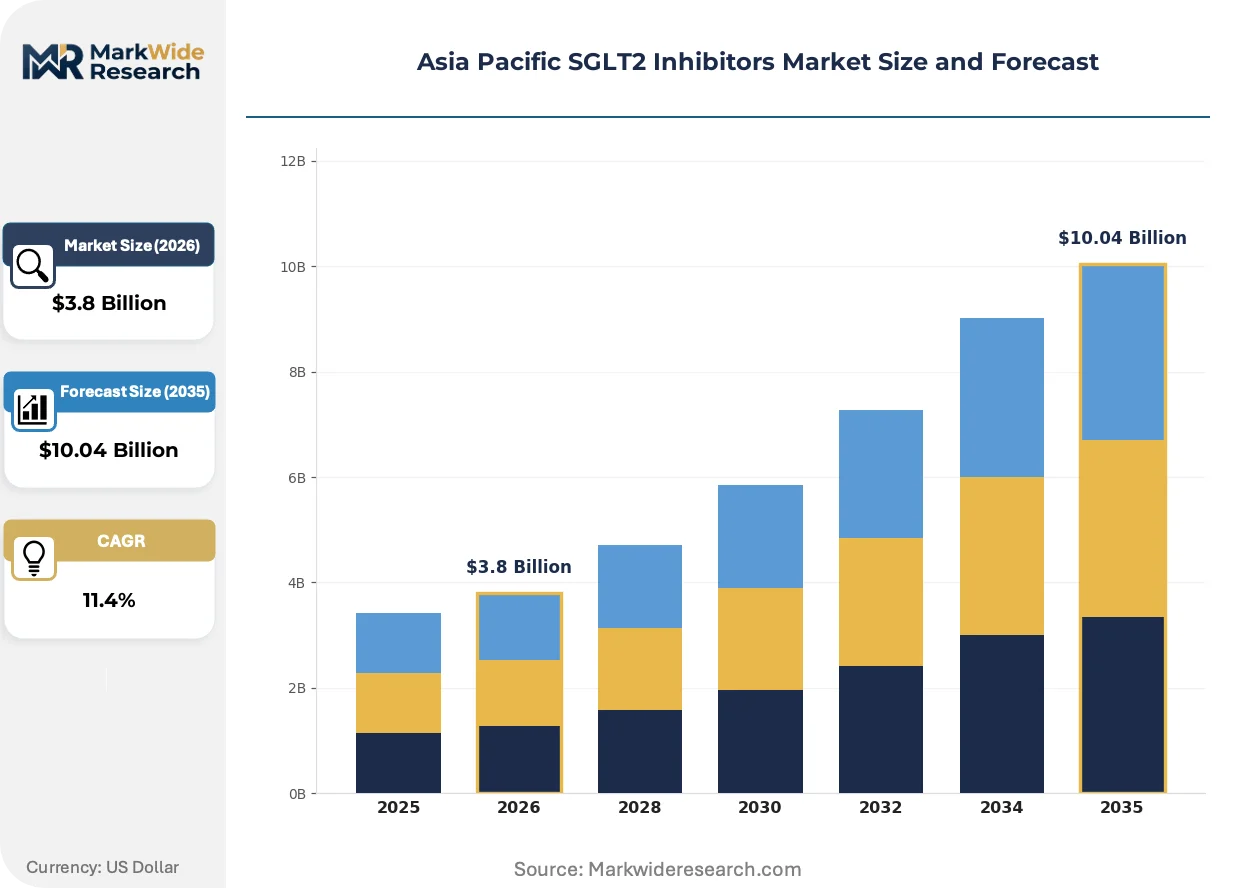
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dapagliflozin, Empagliflozin, Canagliflozin, Ertugliflozin End User: Hospitals, Clinics, Homecare Settings, Specialty Pharmacies Delivery Mode: Oral, Injectable, Transdermal, Intravenous Application: Type 2 Diabetes, Cardiovascular Disease, Chronic Kidney Disease, Weight Management |
| Companies Covered | Boehringer Ingelheim, Eli Lilly, AstraZeneca, Janssen Pharmaceuticals, Merck & Co., Bristol Myers Squibb, TheracosBio, Chong Kun Dang, Glenmark Pharmaceuticals, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific SGLT2 Inhibitors Market Trends and Innovations
Fixed-dose combination therapies are unifying glycemic, cardiovascular, and renal protection into single-pill regimens, altering how hospital pharmacies evaluate therapeutic equivalence and total cost of ownership.
Sodium-glucose cotransporter-2 inhibition is unifying metabolic and hemodynamic pathways in molecular design. Cardiology departments in Tokyo and Sydney academic medical centers adopt these agents at accelerating pace for heart failure with preserved ejection fraction. This convergence is unifying previously separate therapeutic categories, compressing the addressable market for diuretic and ACE inhibitor combinations.
China's NMPA has tightened cardiovascular outcome evidence requirements for label expansions beyond type 2 diabetes. Manufacturers must now submit renal endpoint data from dedicated trials rather than meta-analyses. The chronic kidney disease indication segment responds by extending trial timelines and increasing per-patient monitoring costs.
Hospital pharmacy committees now demand integrated cardiovascular-renal outcome data before formulary inclusion. Specialty pharmacy channels in Japan and Australia displace traditional retail dispensing for high-risk patient populations. This behavioral shift is most visible in Japanese tertiary care centers where pharmacists coordinate directly with cardiology-nephrology joint clinics.
Asia Pacific SGLT2 Inhibitors Market Segmentation
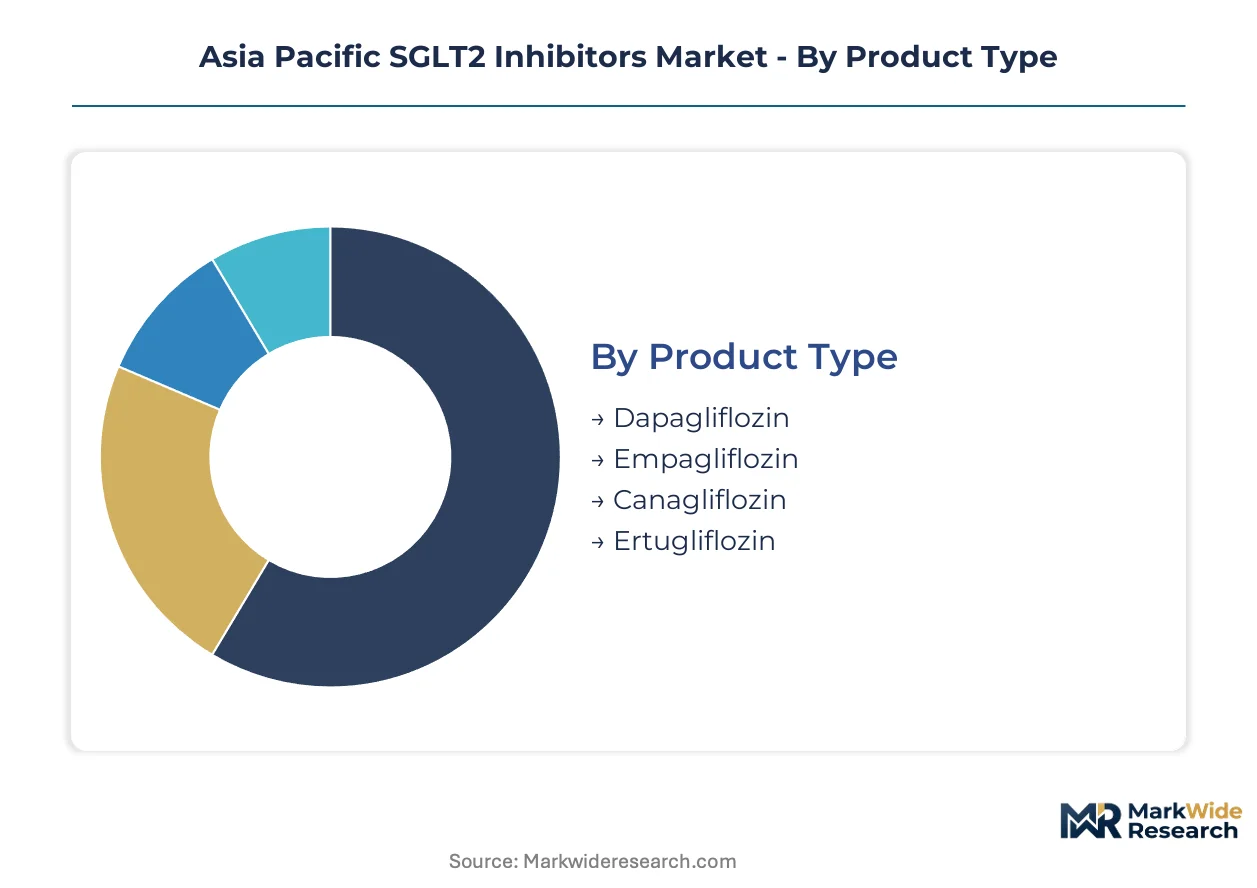
SGLT2 inhibitor prescribing patterns fragment across molecular classes, care settings, and comorbidity profiles. Manufacturers must align portfolio investments with where formulary decisions concentrate and where reimbursement pathways diverge.
Product Type:
API manufacturing clusters in coastal Chinese provinces concentrate supply for specific molecular backbones, creating differentiated vulnerability profiles across the four active compounds.
- Dapagliflozin:Selective SGLT2 inhibitor with established cardiovascular outcome labeling. Hospital formularies in Japan and Australia favor this backbone for combination therapies displacing sulfonylurea regimens.
- Empagliflozin:Demonstrates robust renal protective effects through hemodynamic modulation. Boehringer Ingelheim's manufacturing scale via the Eli Lilly alliance secures supply continuity for high-volume markets.
- Canagliflozin:Faces structural headwinds from ongoing nephrotoxicity surveillance protocols that elevate total cost of therapy and compress margin pools relative to newer entrants.
- Ertugliflozin:India's CDSCO is developing bioequivalence standards for domestic copies that will determine market access trajectory for local producers.
Today's leader: Dapagliflozin. Tomorrow's challenger: Empagliflozin.
End User:
Prescribing authority is migrating toward institutional settings where cardiovascular outcome data drives formulary decisions and specialty pharmacy coordination manages high-risk populations.
- Hospitals:Tertiary care centers in Tokyo and Sydney academic medical centers consolidate authority around agents with integrated cardiovascular-renal outcome data. Pharmacy committees demand trial evidence before inclusion.
- Specialty Pharmacies:Displace traditional retail dispensing in Japan and Australia for populations with heart failure or progressing chronic kidney disease. Pharmacists coordinate directly with cardiology-nephrology joint clinics.
- Clinics:Outpatient diabetes management sites in China face procurement pressure from volume-based reforms narrowing reimbursed options.
- Homecare Settings:Oral administration enables patient-managed therapy, though monitoring requirements for renal function limit unsupervised initiation.
Institutional gatekeepers now control access; retail channels retreat to stable maintenance populations.
Delivery Mode:
Manufacturing complexity and patient compliance requirements stratify competitive intensity across administration routes, with oral dominance reflecting SGLT2 mechanism specificity.
- Oral:Sodium-glucose cotransporter-2 inhibition achieves therapeutic effect through proximal tubule blockade accessible via gastrointestinal absorption. This route captures virtually all commercial volume.
- Injectable:No approved SGLT2 inhibitor utilizes parenteral delivery; this category captures investigational formulations and off-label compounded preparations.
- Transdermal:Skin permeation challenges for this drug class have prevented commercial development; research-stage programs explore patch formulations for patient convenience.
- Intravenous:Acute care settings occasionally employ IV formulations for perioperative glycemic management, though this represents minimal share.
Oral formulations command the field; alternative routes remain speculative.
Application:
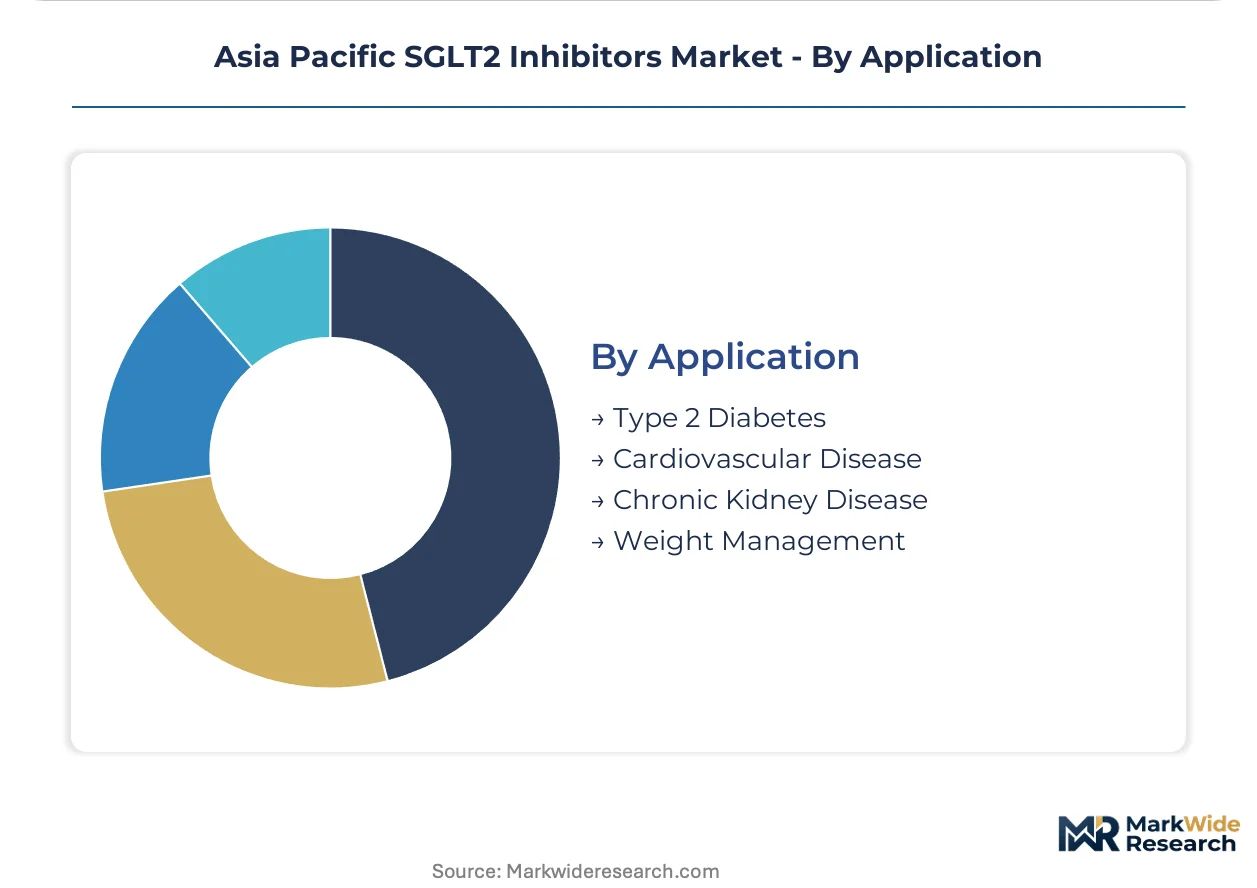
Label expansion beyond glycemic control is redrawing prescriber segments and trial investment priorities, with renal protection emerging as the fastest-expanding indication.
- Chronic Kidney Disease:Nephrologists integrate SGLT2 inhibitors ahead of dialysis progression curves. China's NMPA now demands dedicated renal endpoint trials rather than meta-analyses for label expansion.
- Cardiovascular Disease:Cardiology departments adopt these agents for heart failure with preserved ejection fraction, compressing addressable markets for diuretic and ACE inhibitor combinations.
- Type 2 Diabetes:Original approved indication now functions as entry pathway; reimbursement increasingly requires documented cardiovascular or renal comorbidity.
- Weight Management:Urinary glucose excretion produces modest caloric loss; this application lacks formal labeling and competes with dedicated anti-obesity pharmacotherapy.
Renal protection is climbing the fastest; cardiovascular maintenance holds volume; diabetes becomes the table stakes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai's pharmaceutical manufacturing corridor anchors API supply for SGLT2 inhibitors across Asia Pacific. Japan's PMDA cardiovascular outcome labeling and China's NMPA volume-based procurement reshape demand concentration. Australia's TGA standards influence trial design for regional label expansion.
China
Provincial reimbursement lists widen for domestic API production in Jiangsu and Zhejiang provinces. NMPA tightened cardiovascular outcome evidence requirements for label expansions beyond type 2 diabetes. Manufacturing clusters in coastal provinces face environmental compliance scrutiny that elevates supply vulnerability.
Japan
PMDA cardiovascular outcome labeling accelerates clinician familiarity with renal-protective indications. Biennial price revision cycles create predictable windows for portfolio reallocation. Tokyo's tertiary care centers consolidate prescribing authority around agents with integrated cardiovascular-renal outcome data.
Australia
TGA cardiovascular outcome evidence requirements shape trial investment priorities for manufacturers seeking broad reimbursement. Sydney academic medical centers adopt SGLT2 inhibitors for heart failure with preserved ejection fraction. Specialty pharmacy channels displace traditional retail dispensing for high-risk populations.
India
CDSCO bioequivalence standards for domestic ertugliflozin copies determine market access for local producers. State-level pharmacy councils develop regulatory frameworks for biosimilar substitution. Maharashtra-based manufacturers scale production for Southeast Asian export markets.
South Korea
MFDS cardiovascular outcome labeling aligns with regional standards for hospital formulary inclusion. Seoul's academic medical centers integrate SGLT2 inhibitors into chronic kidney disease protocols ahead of dialysis progression. Domestic manufacturers pursue partnerships with global originators for technology transfer.
Asia Pacific SGLT2 Inhibitors Market Competitive Landscape
Strategic partnerships dominate the current landscape as manufacturers secure manufacturing scale and regional market access. The vendor base concentrates around originator compounds with cardiovascular outcome labeling, while domestic producers in India and China compete on cost-access programs. Two strategic archetypes prevail: multinational originators with trial-backed label expansions, and regional generic manufacturers with bioequivalence-focused portfolios. Portfolio diversification and geographic expansion represent the dominant competitive moves as companies pursue nephrology and cardiology prescriber segments beyond endocrinology.
Within the originator compound tier, AstraZeneca, Boehringer Ingelheim, and Merck & Co. occupy positions reflecting distinct market access strategies. AstraZeneca exemplifies premium positioning anchored to cardiovascular outcome data in Japan and Australia. Boehringer Ingelheim represents manufacturing scale secured through alliance structures. Merck & Co. sits within the cost-access archetype targeting Southeast Asian volume penetration.
| Leading Market Players |
|---|
| Boehringer Ingelheim |
| Eli Lilly |
| AstraZeneca |
| Janssen Pharmaceuticals |
| Merck & Co. |
| Bristol Myers Squibb |
| TheracosBio |
| Chong Kun Dang |
| Glenmark Pharmaceuticals |
| Others |
Pricing and Supply Chain Analysis
Active pharmaceutical ingredient procurement costs in Jiangsu and Zhejiang provinces cascade through three distinct pricing tiers as manufacturers balance domestic volume-based procurement compliance against cardiovascular outcome data premiums in Japan and Australia. Coastal environmental compliance audits periodically disrupt API availability, forcing rapid cost reallocation across hospital formulary negotiations and provincial reimbursement corridors.
Pricing Analysis
Input-cost pass-through from API manufacturing clusters shapes competitive positioning across the region. Three-tier pricing structure across premium, standard, and economy levels separates originator compounds with PMDA cardiovascular labeling from domestic bioequivalent copies and volume-procured provincial tenders. Price differentiation hinges on cardiovascular outcome certification tier and manufacturing scale. Cost compression in the economy tier is intensifying because NMPA volume-based procurement narrows reimbursed options. Provincial hospital procurement committees exhibit highest price sensitivity; tertiary academic medical centers in Tokyo and Sydney demonstrate lowest sensitivity due to integrated outcome data requirements.
Supply Chain Analysis
Freight cost volatility from coastal Chinese ports to Japan, South Korea, and Southeast Asian markets elevates total landed cost for API-dependent formulations. Manufacturing concentrates in China, India, and Japan with distinct specialization: China dominates dapagliflozin and empagliflozin API synthesis, India scales ertugliflozin bioequivalent production, Japan anchors high-value finished dose manufacturing for regional export. Raw material dependencies include sodium-glucose cotransporter-2 selective scaffolds, crystallization solvents, and specialized filtration membranes. Single-source vulnerability pervades coastal Zhejiang province where environmental compliance shutdowns propagate rapidly. Distribution runs through hospital pharmacy committees and specialty pharmacy channels with direct clinician coordination.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where PMDA cardiovascular outcome labeling requirements accelerate prescriber familiarity and consolidate formulary authority around evidence-backed compounds. Demand expansion tracks directly behind regulatory milestone achievement.
For Market Incumbents: To counter biosimilar substitution pressure from India's CDSCO-approved ertugliflozin copies, anchor hospital formulary position through cardiovascular-renal outcome data bundling and deepen backward integration into API production to secure supply continuity against coastal environmental compliance disruptions. For New Entrants and Emerging Players: Rural clinic networks in China's central provinces represent the most penetrable buyer archetype currently underserved by originator cardiovascular outcome detailing. Target this segment through cost-access program partnerships with provincial procurement platforms, leveraging volume-based procurement corridor qualification as the primary go-to-market mechanism. For Investors and Strategic Acquirers: Consolidation pressure builds where bioequivalence certification capabilities overlap with cardiovascular outcome trial infrastructure. Long-term viability favors manufacturers with dual capability across generic API scale and originator evidence generation. Acquisition targets should display integrated cardiology-nephrology medical affairs teams. Monitor Japan's biennial price revision cycle announcements as the signal to watch for portfolio reallocation windows.| Strategic Initiative | Industry Significance |
|---|---|
| Cardiovascular Outcome Trial Advancement | PMDA labeling requirements in Japan accelerate clinician familiarity with renal-protective indications. |
| Regulatory Approval Pathway Optimization | NMPA's tightened renal endpoint data demands extend trial timelines but secure premium positioning. |
| Manufacturing Scale-Up in Coastal Clusters | Jiangsu and Zhejiang API production concentration requires environmental compliance investment. |
| Specialty Pharmacy Channel Partnership | Direct pharmacist-clinician coordination in Japan and Australia displaces traditional retail dispensing. |
| Pipeline Diversification into Fixed-Dose Combinations | Dapagliflozin-backbone formulations displace sulfonylurea combinations in Australian hospital formularies. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drug development executives, regulatory affairs leads, hospital formulary directors, and payer access specialists with secondary validation against PMDA filings, NMPA submissions, ClinicalTrials.gov records, and hospital procurement databases. Bottom-up prescription volume modeling and top-down market sizing triangulated segment-level estimates.
Segment-weighting approaches distributed analytical emphasis across molecular backbone, care setting, comorbidity indication, and regional regulatory cluster dimensions throughout the projection horizon. CAGRs derived from prescription volume trajectories, pricing corridor shifts, and formulary inclusion timelines. Forecast inputs incorporated cardiovascular outcome labeling expansion schedules and volume-based procurement corridor participation rates.
Underlying measurement precision varies by segment; chronic kidney disease and cardiovascular disease indications carry tighter precision than weight management due to formal labeling status. Forecasts reflect documented assumptions about regulatory approval timelines and reimbursement list expansion. Regulatory rejection, biosimilar acceleration, or environmental compliance disruption in coastal API clusters could materially revise projections. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
United Kingdom (UK) Diabetes Drugs Market
Pharmaceuticals
Tunisia Pharmaceutical Market
Pharmaceuticals
Prescription Stimulants Market
Pharmaceuticals
Global Pneumococcal Vaccines Market
Pharmaceuticals
Europe Obsessive-Compulsive Disorder (OCD) Drugs Market
Pharmaceuticals
Dual Antiplatelet Therapy Market
Pharmaceuticals
Middle-East and Africa Alpha-Glucosidase Inhibitors Market
Pharmaceuticals
Smoking Cessation Drugs Market
Pharmaceuticals
Europe Insulin Drugs and Glucagon-Like Peptide 1 (GLP-1) Receptor Agonist Market
Pharmaceuticals
Pain Management Drugs Market
Pharmaceuticals
Chloramphenicol Eye Drops Market
Pharmaceuticals
Alprazolam Powder Market
Pharmaceuticals
Global Pharmerging Market
Pharmaceuticals
Urban Pharma Micro-Depot and Delivery Network Market
Pharmaceuticals
Oncology Adjuvants Market
Pharmaceuticals
France Diabetes Drugs Market