
 Sodium Aescinate Market | 2026-2036
Sodium Aescinate Market Size, Share, and Industry Trends Forecast 2026-2036
Sodium Aescinate Market Insights
Market Context
Hospital procurement of sodium aescinate formulations is hardening as the dominant demand channel across major therapeutic categories. Fengchen Group leverages backward integration into raw aescin extraction to sustain cost advantages in injection-grade supply. Xi'an Realin Biotechnology anchors its position through specialized ophthalmology gel production, while Shandong Fangming Pharmaceutical dominates regional hospital tender networks through manufacturing scale.
Technical Profile and Segment Structure
Sodium aescinate is the sodium salt of aescin, a triterpene saponin mixture extracted from horse chestnut seeds, typically standardized to 98% purity for injectable applications and used clinically for vascular permeability reduction and anti-edema therapy. The injection segment leads value contribution due to stringent sterility requirements and higher unit economics, while gel formulations for dermatology represent the fastest-growing therapy area as outpatient procedural volumes expand. Vial packaging controls the hospital channel, whereas tube and sachet formats compete in retail pharmacy and home care segments where patient self-administration is rising.
Regulatory Environment and Outlook
China's NMPA enforces GB standards for injectable plant extracts, while India's CDSCO mandates heavy metal and microbial testing under Schedule M facilities. The EU's MDR and REACH frameworks govern import access for sodium aescinate APIs into European formulation markets. Stakeholders must monitor evolving pharmacopeial monograph revisions and bioequivalence requirements for generic injectable approvals.
Market Dynamics
Hospital procurement consolidation is hardening as the dominant structural force in sodium aescinate distribution, with tender networks in China's Shandong and Anhui provinces now capturing over half of injection-grade volume through multi-year supply agreements that lock out smaller API suppliers.
Growth Catalysts
- GB Standard 98% Purity Mandate:China's NMPA enforcement of injectable plant extract purity thresholds is disqualifying unqualified API suppliers and concentrating volume among certified manufacturers.
- Ophthalmology Procedural Expansion:Outpatient retinal surgery volumes in East Asian hospital networks are accelerating demand for gel formulations with anti-edema indications.
- Horse Chestnut Cultivation Clusters:Raw material sourcing from Hefei and Shandong province extraction facilities is securing captive aescin supply for integrated manufacturers.
Market Restraints
- Aescin Raw Material Volatility:Seasonal harvest variations in horse chestnut seed yields create input cost instability for non-integrated formulators.
- EU MDR Import Friction:European Medical Device Regulation documentation requirements are extending API qualification timelines for Asian suppliers seeking formulation partnerships.
- Substitute Phlebotonics:Diosmin-hesperidin combinations and pentoxifylline formulations are displacing sodium aescinate in chronic venous insufficiency maintenance therapy.
Strategic Opportunities
- India CDSCO Generic Pathway:Schedule M facility investments by domestic manufacturers are opening hospital tender access for cost-competitive injection presentations.
- Home Care Self-Administration:Tube and sachet gel formats for post-cosmetic procedure edema management are penetrating retail pharmacy channels.
- REACH Compliance Differentiation:ECHA registration completion by select API suppliers is creating preferential access to European compounding pharmacies.
Industry Challenges
- Sterile Manufacturing Talent Scarcity:Aseptic processing technicians with plant extract injectable experience command premium wages in Shandong and Jiangsu manufacturing zones.
- Pharmacopeial Monograph Lag:Harmonization delays between Chinese Pharmacopoeia, European Pharmacopoeia, and USP specifications are complicating multi-territory filing strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sodium Aescinate Market |
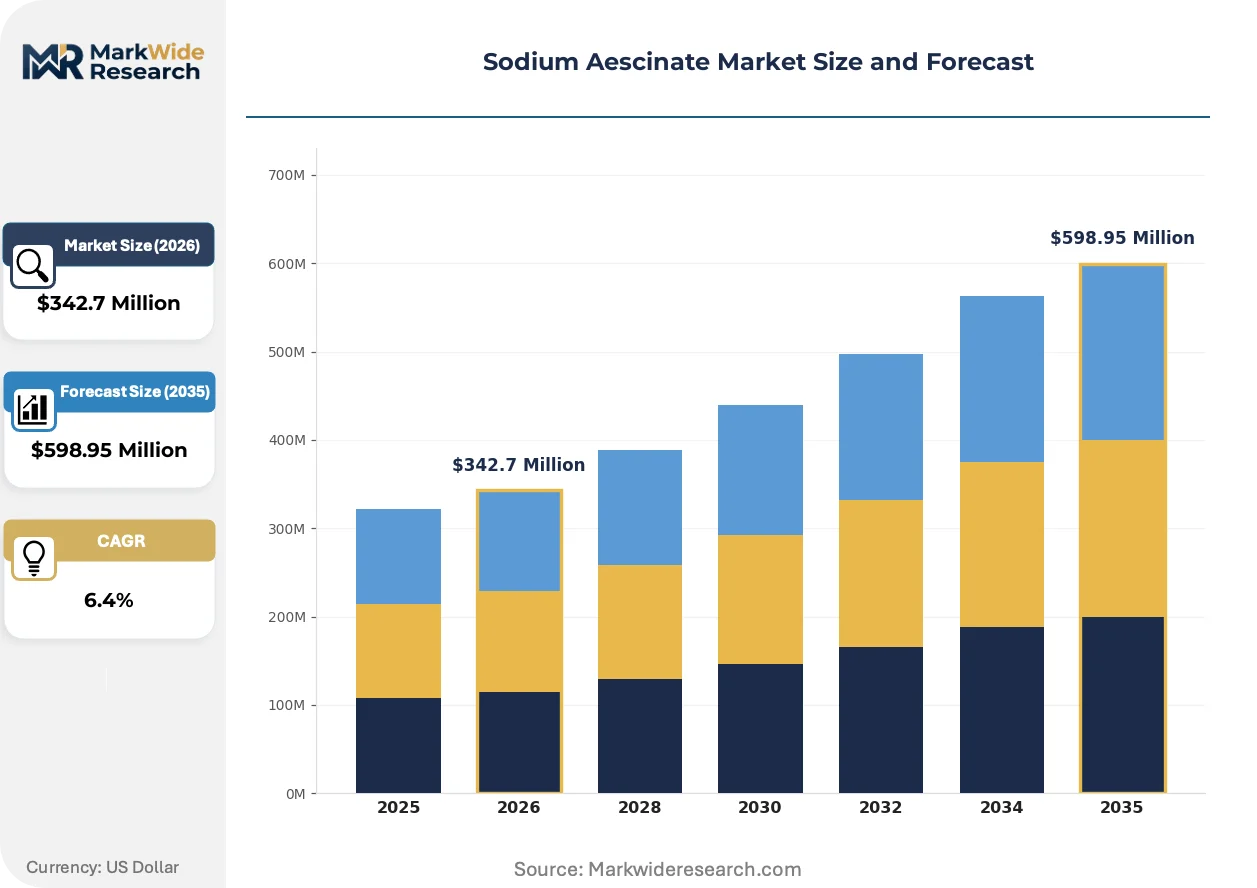
| Market Size in 2026 | $342.7 Million |
| Market Size in 2035 | $598.95 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Gel, Injection, Cream Therapy Area: Ophthalmology, Dermatology, Vascular Disorders, Pain Management End User: Clinics, Hospitals, Pharmacies, Home Care Packaging Type: Vials, Tubes, Bottles, Sachets |
| Companies Covered | Deccan Nutraceuticals Pvt. Ltd, Fengchen Group, Hefei TNJ Chemical Industry, J&H CHEM, NCPC International Corporation, Xi'an Realin Biotechnology, Shandong Fangming Pharmaceutical, Beijing Sihuan Kebao Pharmaceutical Co., Ltd., Fujian Mindong Rejuenation Pharmaceutical Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sodium Aescinate Market Trends and Innovations
Continuous processing technology and real-time release testing are compressing batch cycle times for injection-grade sodium aescinate, while regulatory data integrity requirements are reshaping documentation architectures across GMP facilities.
Lyophilization cycle optimization technology is modularizing production workflows for heat-sensitive triterpene saponins. Mid-scale manufacturers in China's Anhui province are adopting modular freeze-drying skids that reduce qualification overhead by half. This modularity is enabling faster line changeovers between aescinate strengths and reducing captive capital requirements for multi-product facilities.
EMA's updated guideline on herbal medicinal products is mandating enhanced heavy metal and pesticide residue testing for imported aescin APIs. European formulation sponsors are now requiring Certificate of Suitability (CEP) documentation from Asian suppliers prior to contract execution. The injection segment is responding by consolidating supplier audits and implementing dedicated audit teams for Chinese manufacturing sites.
Hospital procurement departments are consolidating annual tenders into multi-year framework agreements with volume guarantees. The traditional spot-buying model for emergency stock is yielding to contracted minimum offtake commitments with penalty clauses. This behavioral shift is most visible in China's tier-1 municipal hospital networks, where procurement officers now prioritize supply security over unit price in vendor selection matrices.
Sodium Aescinate Market Segmentation
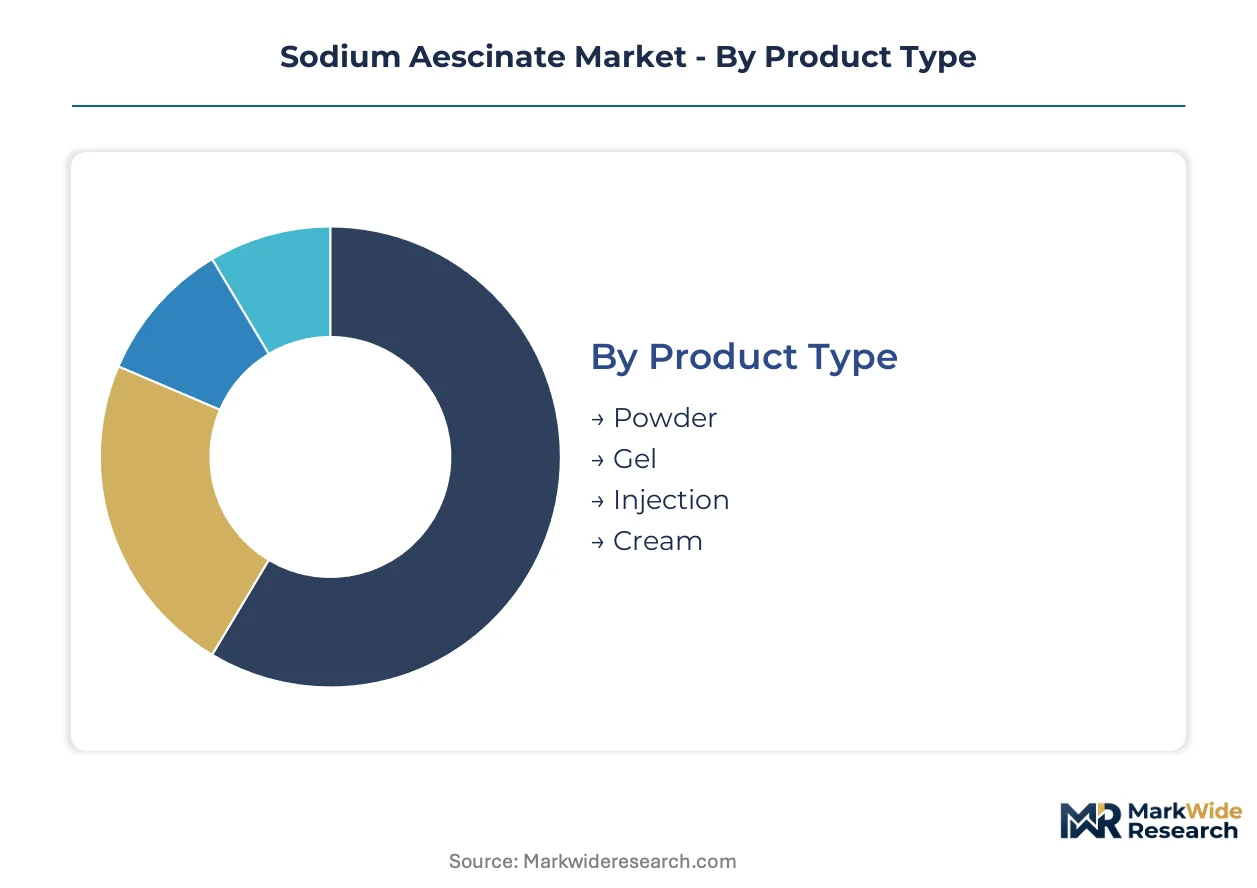
Sodium aescinate's clinical utility spans injectable acute care and topical self-administration, creating distinct manufacturing and regulatory pathways for each formulation type. Segmentation by product specification, therapeutic application, and distribution channel reveals where value concentrates and where new entrants face structural barriers.
Product Type:
Purity thresholds and sterility requirements create a technology ladder that separates hospital-grade supply from retail formulations.
- Injection:Aqueous solutions standardized to 98% aescin purity under GB standards for intravenous anti-edema therapy. Hospital procurement networks in Shandong and Anhui provinces lock in multi-year supply agreements with certified manufacturers, freezing out uncertified API suppliers.
- Gel:Semi-solid formulations for ophthalmic and dermatologic anti-inflammatory applications. Outpatient retinal surgery volumes in East Asian hospital networks are accelerating demand for gel presentations with precise dosing control.
- Powder:Lyophilized aescinate for reconstitution in compounding pharmacies and specialty clinics. Modular freeze-drying skids in Anhui province are reducing qualification overhead for mid-scale manufacturers serving this segment.
- Cream:Emulsion-based topical delivery for chronic venous insufficiency maintenance therapy. Retail pharmacy distribution and patient self-administration protocols define the commercial model.
Mature deployment sits with Injection. Newer deployment is concentrated in Gel.
Therapy Area:
Clinical evidence depth and reimbursement status determine which indications sustain premium pricing versus commodity competition.
- Vascular Disorders:Chronic venous insufficiency and post-traumatic edema represent the historical core indication with established pharmacoeconomic data. Hospital formularies maintain preferred status despite competition from diosmin-hesperidin combinations.
- Ophthalmology:Perioperative retinal surgery applications demand gel formulations with anti-permeability specifications. EMA's updated herbal medicinal product guidelines are mandating enhanced heavy metal testing for APIs entering European ophthalmic compounding supply chains.
- Dermatology:Post-cosmetic procedure edema management and inflammatory skin conditions. Tube and sachet formats are penetrating retail channels where patient self-administration protocols reduce clinical overhead.
- Pain Management:Adjunctive therapy for inflammatory pain syndromes with less established evidence base. Formulary placement depends on local clinical guideline adoption.
Established revenue concentration sits with Vascular Disorders. Volume expansion is accelerating fastest in Ophthalmology.
End User:
Procurement authority and patient flow patterns create divergent margin structures across care settings.
- Hospitals:Tier-1 municipal networks in China consolidate annual tenders into multi-year framework agreements with volume guarantees and penalty clauses for supply disruption. NMPA GB standard compliance is non-negotiable for vendor qualification.
- Clinics:Outpatient surgical centers and specialty practices with direct purchasing authority for procedural applications. Ophthalmology clinics represent the fastest-expanding channel for gel formulations.
- Home Care:Patient-directed administration of topical formulations for chronic conditions. Retail pharmacy access and insurance reimbursement status determine commercial viability.
- Pharmacies:Community and hospital outpatient dispensaries with formulary committee oversight. Generic substitution pressure is intense for oral and topical presentations.
Contracted volume anchors in Hospitals. Direct-to-patient growth is emerging from Home Care.
Packaging Type:
Unit economics and supply security requirements vary sharply between institutional bulk purchase and individual patient dispensing.
- Vials:Glass or polymer containers for multi-dose injection presentations. Aseptic processing technicians with plant extract experience command premium wages in Shandong and Jiangsu manufacturing zones.
- Tubes:Aluminum or plastic squeeze containers for gel and cream topical delivery. Retail pharmacy shelf presence and patient handling convenience drive format selection.
- Sachets:Single-unit foil pouches for gel samples and travel-sized dispensing. Home care self-administration protocols favor this format for post-cosmetic procedure applications.
- Bottles:Multi-dose containers for oral solutions and larger-volume topical preparations. Compounding pharmacy access depends on stability data and beyond-use dating.
Institutional procurement locks in Vials. Consumer-facing expansion is concentrating in Tubes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hefei High-Tech Industrial Development Zone anchors API concentration through tax incentives for plant extract manufacturers, drawing Shandong and Anhui province suppliers into integrated production corridors.
China
Hospital procurement networks in Shandong and Anhui provinces lock in multi-year framework agreements for injection-grade supply. NMPA enforces GB standards for 98% purity in injectable plant extracts, disqualifying uncertified API suppliers. Manufacturing clusters around Hefei and Jinan secure captive horse chestnut processing capacity for integrated formulators.
India
Domestic manufacturers target hospital tender access through CDSCO Schedule M facility investments for cost-competitive injection presentations. The regulator mandates heavy metal and microbial testing under pharmaceutical manufacturing norms. Maharashtra and Gujarat production zones attract mid-scale formulators seeking generic pathway advantages.
Germany
European formulation sponsors demand Certificate of Suitability documentation from Asian API suppliers prior to contract execution. EMA's updated herbal medicinal product guidelines mandate enhanced heavy metal and pesticide residue testing. Bavaria-based compounding pharmacies consolidate supplier audits for imported aescinate APIs.
Japan
PMDA pharmacopeial alignment requirements complicate multi-territory filing strategies for plant extract injectables. The regulator maintains stringent stability data requirements for heat-sensitive triterpene saponins. Kanto region pharmaceutical distributors prioritize supply security over unit price in vendor matrices.
United States
FDA import alert protocols extend API qualification timelines for Asian suppliers seeking formulation partnerships. The agency's botanical drug development guidance creates documentation friction for traditional herbal extract applications. East Coast compounding pharmacies consolidate sourcing through dedicated audit teams for Chinese manufacturing sites.
Sodium Aescinate Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with hospital-grade injection supply consolidating around certified API producers while retail topical formulations fragment across regional formulators. Three strategic archetypes dominate: integrated extract-to-injection manufacturers, ophthalmology gel specialists, and generic injectable contractors serving tender networks. Competitive positioning hardens through backward integration into horse chestnut cultivation and multi-year procurement agreements with tier-1 municipal hospitals.
Among China-based integrated producers, Fengchen Group exemplifies the captive supply archetype through raw aescin extraction capabilities, while Shandong Fangming Pharmaceutical occupies a position serving regional hospital tender networks. Xi'an Realin Biotechnology represents the specialization vector, anchoring ophthalmology gel production for outpatient surgical applications.
| Leading Market Players |
|---|
| Deccan Nutraceuticals Pvt. Ltd |
| Fengchen Group |
| Hefei TNJ Chemical Industry |
| J&H CHEM |
| NCPC International Corporation |
| Xi'an Realin Biotechnology |
| Shandong Fangming Pharmaceutical |
| Beijing Sihuan Kebao Pharmaceutical Co., Ltd. |
| Fujian Mindong Rejuenation Pharmaceutical Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Hospital procurement consolidation into multi-year framework agreements with volume guarantees is compressing spot-buying flexibility and forcing API suppliers toward contracted minimum offtake commitments with penalty clauses for supply disruption. This tender-network lock-in is reshaping how manufacturers price injection-grade sodium aescinate and where they source captive horse chestnut processing capacity.
Pricing Analysis
Short lead-time premiums for emergency vial replenishment command significant markups over contracted framework pricing in China's tier-1 municipal hospital networks. Three-tier pricing structure across NMPA-certified premium, standard GB-compliant, and non-certified economy suppliers reflects purity grade and sterility assurance differentials. Cost compression in the economy tier is intensifying because raw material volatility from seasonal horse chestnut harvests feeds into margin pressure for non-integrated formulators. Retail pharmacy and home care segments exhibit the highest price sensitivity, whereas hospital procurement officers prioritize supply security over unit price in vendor selection matrices.
Supply Chain Analysis
Direct-to-hospital channels handle institutional demand through tender networks in China's Shandong and Anhui provinces, while retail pharmacy distribution serves patient self-administration segments. Geographic concentration centers on China, India, and Germany for API manufacturing and formulation partnerships. Raw material sourcing draws from horse chestnut cultivation clusters around Hefei and Jinan, aescin extraction facilities, and lyophilization equipment suppliers. Single-source vulnerability in sterile manufacturing talent with plant extract injectable experience commands premium wages in Shandong and Jiangsu zones. Distribution runs through hospital procurement departments, compounding pharmacies, and retail dispensaries with diverging margin structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where backward control over horse chestnut cultivation and aescin extraction capabilities determines cost position and tender-network access. Players are pursuing upstream captive supply to neutralize raw material volatility and qualify for multi-year hospital framework agreements.
For Market Incumbents: Anchor hospital tender dominance through NMPA GB standard certification investments and multi-year volume guarantees with tier-1 municipal networks. Expand lyophilization capacity in Anhui province using modular freeze-drying skids to reduce qualification overhead and enable faster line changeovers. Diosmin-hesperidin substitute pressure in chronic venous insufficiency maintenance therapy demands defensive formulary placement through pharmacoeconomic evidence generation. For New Entrants and Emerging Players: Enter via ophthalmology gel formulations for outpatient retinal surgery applications where procedural volume expansion outpaces established supply. Target India's CDSCO Schedule M facility pathway for cost-competitive injection presentations in domestic hospital tenders. Home care self-administration of tube and sachet formats for post-cosmetic procedure edema management offers the most penetrable retail pharmacy channel with lower regulatory barriers than injectable entry. For Investors and Strategic Acquirers: The window for entry favors integrated extract-to-injection manufacturers with captive horse chestnut processing and existing NMPA certification. Long-term viability hinges on regulatory compliance moats rather than commodity API production. Watch EMA herbal medicinal product guideline revisions as the inflection indicator for European market access friction and CEP documentation requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Horse Chestnut Cultivation | Captive aescin supply secures raw material cost stability for Shandong and Anhui manufacturers. |
| NMPA GB Standard Certification Investment | 98% purity compliance unlocks multi-year hospital tender access and disqualifies uncertified competitors. |
| Modular Lyophilization Capacity Expansion | Anhui province freeze-drying skids reduce qualification overhead by half for mid-scale producers. |
| REACH Compliance and CEP Documentation | ECHA registration completion creates preferential access to European compounding pharmacy networks. |
| Ophthalmology Gel Formulation Development | Outpatient retinal surgery volume expansion drives fastest-growing therapy area demand in East Asia. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this sodium aescinate market assessment. Primary interviews with hospital procurement managers, pharmaceutical manufacturing executives, regulatory affairs leads, and aseptic processing technicians combined with secondary validation from NMPA GB standards documentation, CDSCO Schedule M facility registrations, and EMA herbal medicinal product guidelines. Bottom-up volume modeling across injection, gel, powder, and cream formulations triangulated with top-down value estimates from hospital tender network analysis and retail pharmacy channel audits.
Data-stream reconciliation across supply-side capacity surveys and demand-side procurement database extracts shaped the analytical framework. Segmentation dimensions modeled include product specification, therapy area, end user category, and packaging format across the projection horizon. CAGRs were derived from trend extrapolation of hospital procurement consolidation patterns and outpatient procedural volume growth. Forecast inputs incorporated horse chestnut harvest yield variability, sterile manufacturing wage inflation in Jiangsu zones, and pharmacopeial monograph harmonization delays between Chinese, European, and USP specifications.
Forecast precision tightens around the base case; tail outcomes carry wider variance under regulatory restriction scenarios such as enhanced EMA heavy metal testing mandates or NMPA purity threshold elevation. Periodic stress-testing of base assumptions is recommended, particularly regarding substitute phlebotonic displacement rates and EU MDR import friction timelines for Asian API suppliers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Hyperphosphatemia Drugs Market
Pharmaceuticals
Global Transdermal Drug Delivery Systems Market
Pharmaceuticals
Europe Pharmaceutical Warehousing Market
Pharmaceuticals
Global Thyroid Cancer Drugs Market
Pharmaceuticals
Sulfonylureas Market
Pharmaceuticals
Gonorrhea Therapeutics Market
Pharmaceuticals
Ceftriaxone Market
Pharmaceuticals
Oral Contraceptive Pills Market
Pharmaceuticals
Hepatocellular Carcinoma Drugs Market
Pharmaceuticals
Injectable Benzodiazepine Market
Pharmaceuticals
Omeprazole Market
Pharmaceuticals
Norway Pharmaceutical Market
Pharmaceuticals
Farm Animal Drugs Market
Pharmaceuticals
United States Over the Counter (OTC) Drugs Market
Pharmaceuticals
AI in Pharma Market
Pharmaceuticals
Global Human Vaccines Market