
 Alopecia Drugs Market | 2026-2036
Alopecia Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Alopecia Drugs Market Analysis
Specialty pharmacy distribution is fragmenting as oral and injectable alopecia therapies bypass traditional retail channels. Pfizer Inc. leverages its inflammation and immunology infrastructure to navigate specialty drug logistics for autoimmune hair loss indications. Johnson & Johnson anchors its position through dermatology clinic partnerships that prioritize topical minoxidil formulations. Cipla Limited competes on manufacturing scale, supplying affordable oral finasteride across regulated and emerging markets.
Alopecia drugs comprise pharmaceutical agents designed to arrest hair follicle miniaturization, modulate androgenic signaling, or suppress autoimmune-mediated follicular destruction through topical, oral, or parenteral delivery. These therapies functionally target prostaglandin analog pathways, 5-alpha reductase inhibition, or janus kinase suppression to restore terminal hair density in pattern and patchy hair loss disorders. Topical treatments occupy the largest revenue pool due to established patient familiarity and minimal systemic exposure, while injectable therapies represent the fastest-expanding segment as intralesional corticosteroids and emerging biologics penetrate alopecia areata protocols. Oral medications sustain steady volume through finasteride and minoxidil prescriptions for androgenetic alopecia in male and off-label female populations.
FDA, EMA, and Japan's PMDA collectively govern the clinical evidence standards for alopecia drug approvals, with each regulator demanding distinct endpoints for hair count restoration and quality-of-life metrics that shape trial design and market entry sequencing. The FDA's breakthrough therapy designation for JAK inhibitor candidates in alopecia areata has accelerated sponsor investment in this previously underserved indication. Stakeholders must monitor how evolving dermatology reimbursement codes and biosimilar entry timelines for reference biologics will reshape prescribing economics across clinic and homecare settings.
Market Dynamics
JAK inhibitor development pipelines are compressing clinical trial timelines as the FDA breakthrough therapy designation accelerates sponsor investment in autoimmune hair loss indications. This regulatory velocity is restructuring competitive positioning around immunology infrastructure and specialty pharmacy distribution networks.
Growth Catalysts
- FDA Breakthrough Therapy Pathway:Expedited review timelines for alopecia areata biologics are pulling venture capital into follicular immunology research. Dermatology clinics are expanding dedicated hair restoration service lines to capture referral volume.
- Reimbursement Framework Maturation:Germany's statutory health insurance system now covers biologic hair loss therapies, reducing out-of-pocket burden and expanding addressable patient populations.
- Intralesional Corticosteroid Protocols:Patchy alopecia areata treatment algorithms are incorporating higher-frequency injection schedules, driving utilization of depot formulations in dermatology practices.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:Finasteride and minoxidil raw material supply clusters in Chinese manufacturing zones, exposing formulation sponsors to geopolitical trade friction and import inspection delays.
- Systemic Safety Surveillance:Oral JAK inhibitors carry FDA-mandated black box warnings for cardiovascular events, limiting prescribing confidence among primary care physicians relative to dermatology specialists.
- Topical Efficacy Ceiling:Patient adherence to twice-daily minoxidil application protocols degrades substantially after month six, constraining real-world outcomes versus clinical trial performance.
Strategic Opportunities
- Pediatric Alopecia Areata:The FDA's pediatric study requirements for JAK inhibitors are creating first-mover advantage for sponsors with adolescent trial data, an historically underserved demographic.
- Japan PMDA Fast-Track Designation:Severe alopecia areata therapies qualify for priority review, compressing market entry timelines relative to standard pharmaceutical approval pathways.
- Direct-to-Patient Subscription Models:Oral finasteride and topical combination kits are bypassing traditional pharmacy benefit managers through telehealth platforms, capturing margin from disintermediated distribution.
Industry Challenges
- Trichoscopy Training Shortages:Accurate alopecia subtype diagnosis requires specialized dermoscopy skills that residency programs inadequately cover, creating diagnostic bottlenecks in community dermatology.
- Biologic Cold Chain Integrity:Injectable JAK inhibitors require temperature-controlled logistics that specialty pharmacies struggle to maintain across last-mile delivery to patient homes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alopecia Drugs Market |
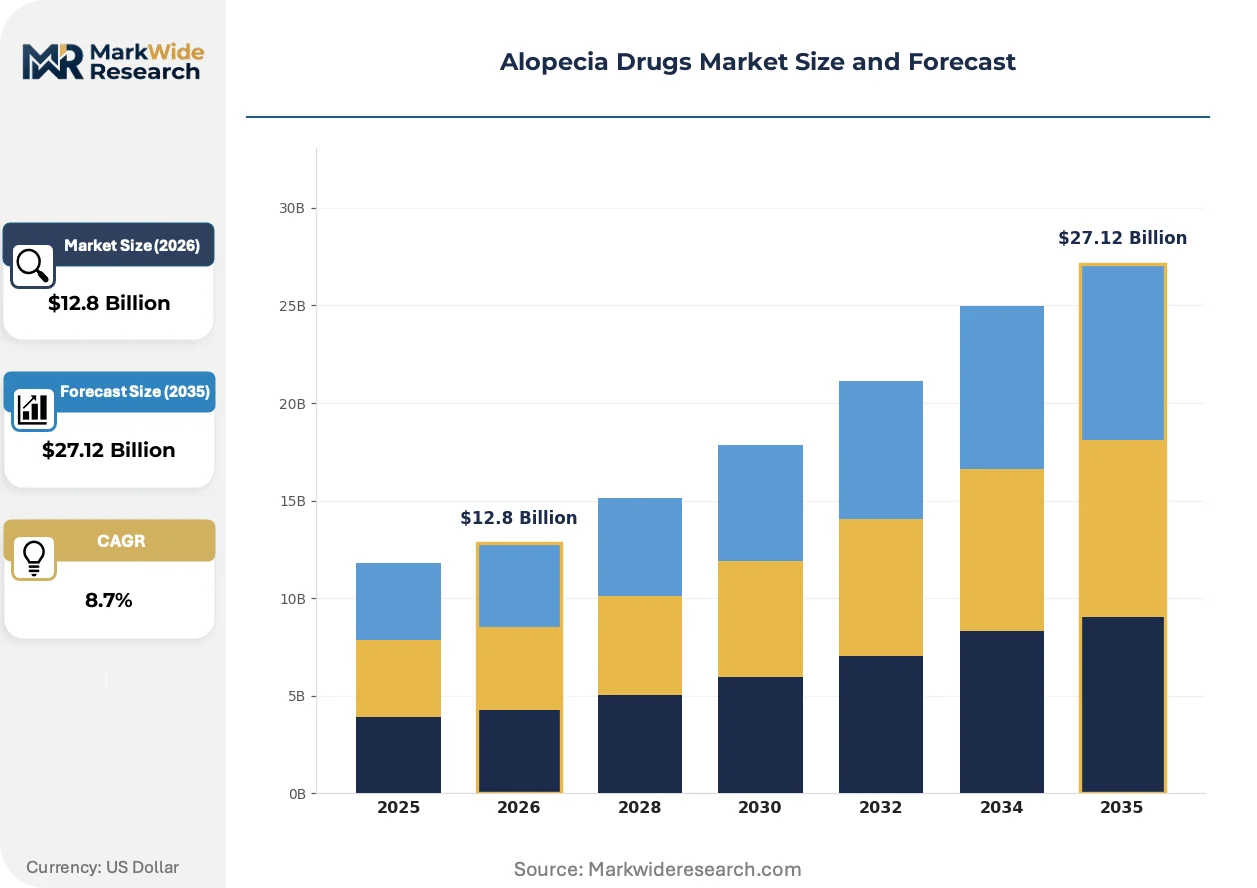
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $27.12 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Treatments, Oral Medications, Injectable Therapies, Herbal Remedies Indication: Androgenetic Alopecia, Alopecia Areata, Alopecia Totalis, Scarring Alopecia End User: Hospitals, Dermatology Clinics, Homecare Settings, Research Laboratories Administration Route: Topical, Oral, Intralesional, Intravenous |
| Companies Covered | Cipla Limited, Pfizer Inc., Johnson & Johnson, Aclaris Therapeutics, Inc., Dr. Reddy’s Laboratories Ltd., Merck & Co., Inc., GlaxoSmithKline plc, Follica, Inc., Sun Pharmaceutical Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alopecia Drugs Market Emerging Trajectories
Oral small-molecule therapies are displacing topical monotherapies as first-line intervention for moderate-to-severe alopecia areata. This shift is compressing formulation development timelines and rewiring distribution economics toward specialty pharmacy channels.
Topical JAK inhibitor formulations are collapsing the systemic exposure requirements previously necessary for follicular immunosuppression. Pfizer and Eli Lilly are advancing localized delivery systems through Phase III trials. Dermatology practices are preparing protocol transitions that minimize cardiovascular monitoring burdens. The FDA is evaluating whether reduced systemic absorption justifies relaxed Risk Evaluation and Mitigation Strategy requirements.
EMA's extended pharmacovigilance requirements for immunomodulatory dermatologics are extending post-market surveillance obligations from five to ten years. Sponsors must now commit to longitudinal hair density registries as a condition of marketing authorization. The regulatory friction is most acute for mid-cap developers lacking established pharmacovigilance infrastructure. Germany and France are implementing divergent national registry specifications, fragmenting compliance architecture.
Patient-initiated therapy switching is accelerating as direct-to-consumer advertising and social media peer networks compress information asymmetries. Telehealth platforms are disintermediating traditional dermatology referral pathways for oral finasteride prescribing. This behavioral shift is most pronounced in the United States, where asynchronous consultation models now account for substantial new patient acquisition. Retail pharmacy chains are responding with private-label topical minoxidil formulations to recapture volume.
Alopecia Drugs Market Segmentation
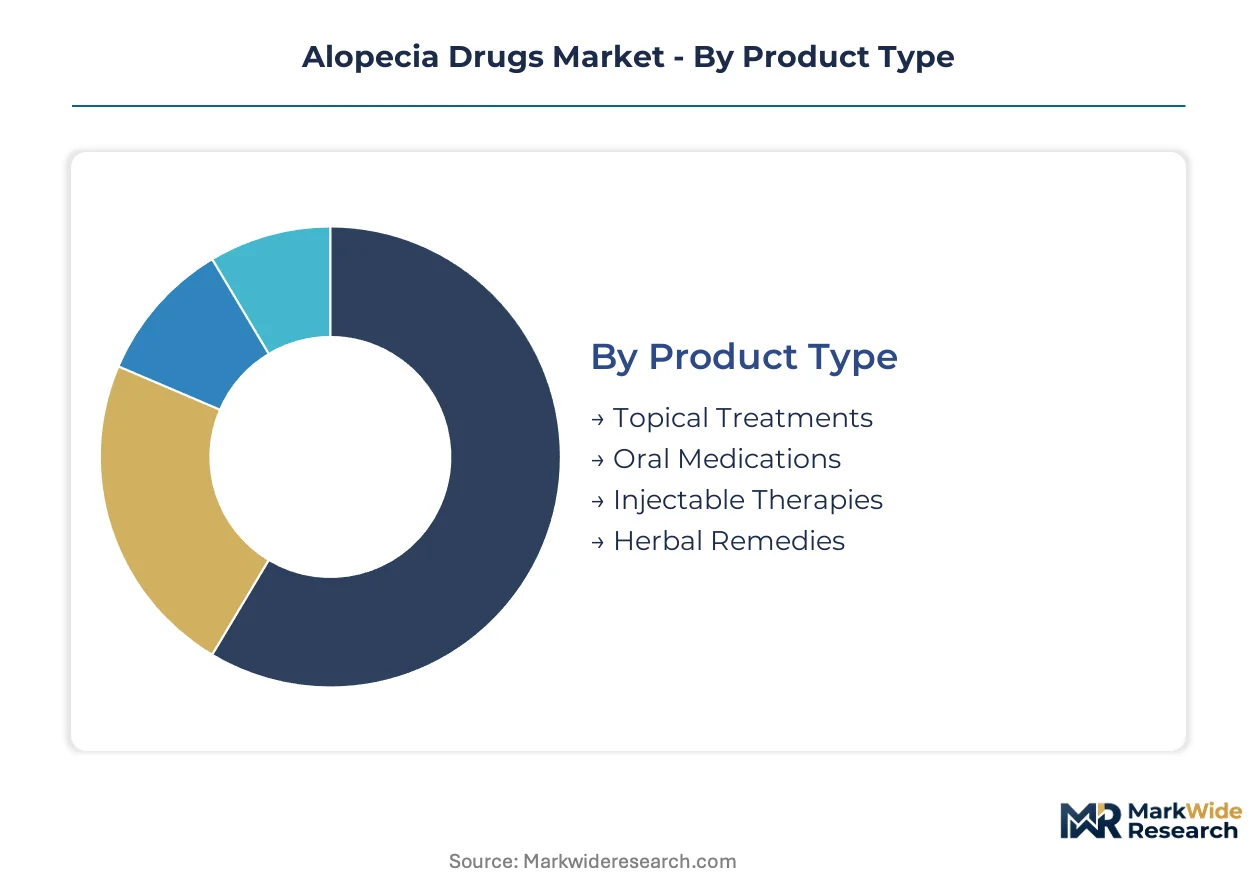
Segmentation in alopecia therapeutics reveals how delivery mechanisms, disease severity, and care settings reshape commercial priorities. Each dimension carries distinct reimbursement codes, cold-chain requirements, and patient adherence profiles that determine sponsor investment allocation.
Product Type:
Cost tier determines reimbursement complexity and margin structure across formulation categories.
- Topical Treatments:Minoxidil and prostaglandin analog solutions dominate first-line prescribing through minimal systemic exposure and over-the-counter accessibility in United States retail channels. Patient familiarity sustains volume despite efficacy ceilings that emerge after six months of continuous application.
- Injectable Therapies:Intralesional corticosteroid depot formulations and emerging biologic JAK inhibitors command premium pricing through specialty pharmacy distribution networks. Germany's statutory health insurance coverage expansion for biologic hair loss therapies is accelerating clinic adoption of higher-frequency injection protocols.
- Oral Medications:Finasteride and oral minoxidil prescriptions sustain steady volume through telehealth platforms that bypass traditional pharmacy benefit managers.
- Herbal Remedies:Saw palmetto and botanical extracts compete outside regulated pharmaceutical channels, concentrated in Asian markets with traditional medicine integration.
Topical Treatments hold installed capacity. Injectable Therapies is rotating up the share rankings.
Indication:
Application severity dictates whether therapy addresses cosmetic concern or autoimmune pathology with systemic monitoring requirements.
- Androgenetic Alopecia:Pattern hair loss in male and female populations drives the largest prescription volume through 5-alpha reductase inhibition and androgen receptor modulation. United States dermatology clinics are expanding dedicated hair restoration service lines to capture this referral base.
- Alopecia Areata:Patchy autoimmune follicular destruction is attracting JAK inhibitor development investment accelerated by FDA breakthrough therapy designation timelines. Pediatric study requirements are creating first-mover advantage for sponsors with adolescent trial data in this historically underserved demographic.
- Alopecia Totalis:Complete scalp hair loss represents the most severe disease spectrum with highest unmet need and biologic eligibility criteria.
- Scarring Alopecia:Permanent follicular destruction requires immunosuppressive intervention before fibrosis completion, with diagnosis dependent on specialized trichoscopy skills that residency programs inadequately cover.
Androgenetic Alopecia holds installed capacity. Alopecia Areata is rotating up the share rankings.
End User:
Customer type determines whether therapy delivery requires clinical infrastructure or supports direct-to-patient models.
- Dermatology Clinics:Specialized hair restoration service lines are expanding across United States metropolitan markets as patient referrals surge and intralesional injection protocols proliferate. These settings capture biologic prescribing through specialist confidence that exceeds primary care physician comfort with black-box cardiovascular warnings.
- Homecare Settings:Self-administered topical and oral therapies are migrating to subscription-based telehealth platforms that disintermediate traditional distribution. Cold-chain integrity challenges for injectable JAK inhibitors limit biologic penetration in this channel.
- Hospitals:Tertiary centers manage severe alopecia totalis cases requiring systemic immunomodulation with intensive safety monitoring.
- Research Laboratories:Academic medical centers conduct longitudinal hair density registries mandated by EMA extended pharmacovigilance requirements.
Dermatology Clinics hold installed capacity. Homecare Settings is rotating up the share rankings.
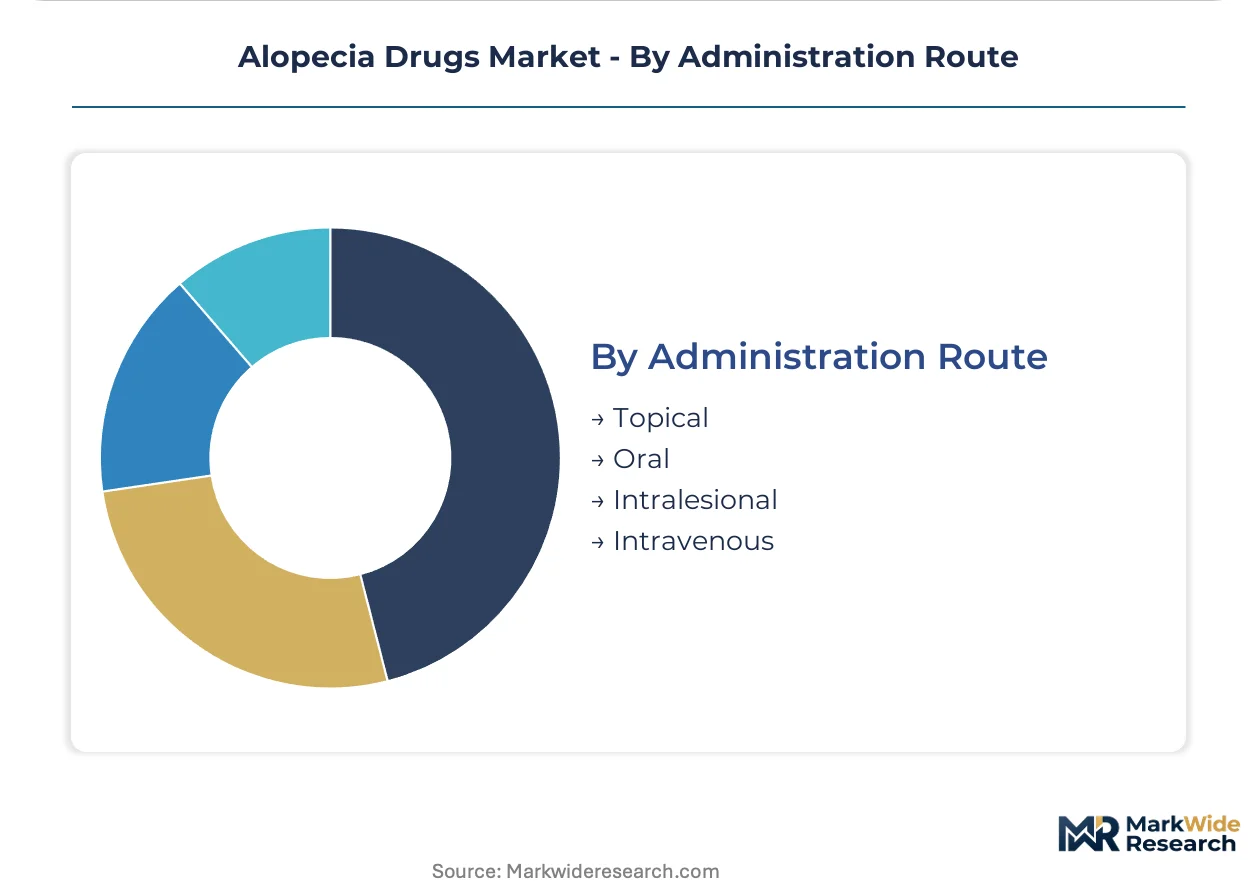
Administration Route:
Volume concentration varies by systemic exposure tolerance and patient self-efficacy in protocol adherence.
- Oral:Systemic delivery through finasteride and emerging small-molecule JAK inhibitors enables comprehensive follicular coverage but requires cardiovascular surveillance that concentrates prescribing in dermatology specialist networks.
- Topical:Localized application minimizes systemic burden and supports over-the-counter distribution, though twice-daily adherence degrades substantially after month six in real-world settings.
- Intralesional:Direct corticosteroid injection into patchy lesions delivers concentrated immunosuppression with depot formulation convenience.
- Intravenous:Hospital-based biologic infusion serves severe refractory cases with highest monitoring intensity.
Topical holds installed capacity. Oral is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Reimbursement policy maturation is redirecting patient flows toward biologic therapies in advanced economies. Germany's statutory health insurance coverage expansion and Japan's PMDA fast-track designation are compressing market entry timelines for autoimmune hair loss treatments. The United States maintains dominant prescription volume through dermatology clinic expansion and telehealth platform proliferation.
United States
Dermatology clinics in metropolitan markets are expanding dedicated hair restoration service lines to capture surging patient referrals. FDA breakthrough therapy designation for JAK inhibitor candidates has accelerated sponsor investment in alopecia areata drug development. Boston and San Francisco biotech clusters host follicular immunology research programs that feed into specialty pharmaceutical pipelines.
Germany
Statutory health insurance coverage for biologic hair loss therapies has reduced out-of-pocket burden and expanded addressable patient populations. EMA extended pharmacovigilance requirements for immunomodulatory dermatologics are extending post-market surveillance obligations to ten years. Munich and Frankfurt pharmaceutical hubs coordinate longitudinal hair density registries as conditions of marketing authorization.
Japan
PMDA fast-track designation for severe alopecia areata therapies compresses regulatory review timelines relative to standard pharmaceutical approval pathways. METI industrial policy supports domestic biologics manufacturing capacity expansion for autoimmune indications. Tokyo and Osaka dermatology centers are adopting higher-frequency intralesional corticosteroid protocols for patchy hair loss cases.
India
CDSCO regulatory pathways for generic finasteride formulations sustain manufacturing scale advantages in oral hair loss medications. Domestic pharmaceutical clusters in Hyderabad and Ahmedabad supply affordable oral therapies across regulated and emerging markets. Telehealth platforms are disintermediating traditional distribution channels for direct-to-patient subscription models.
Alopecia Drugs Market Vendor Landscape
On the supply side, the industry is consolidating around inflammation and immunology infrastructure holders with established specialty pharmacy distribution networks. Large-cap pharmaceutical groups anchor market structure through dermatology clinic partnerships and biologic cold-chain logistics. Mid-cap developers concentrate on topical formulation innovation and pediatric indication expansion. Dominant competitive moves include strategic partnerships with telehealth platforms and portfolio diversification into localized delivery systems.
Within the inflammation and immunology tier, Pfizer Inc. and Johnson & Johnson occupy positions reflecting established specialty drug logistics capabilities. Cipla Limited exemplifies the manufacturing-scale archetype serving oral generic markets across price-sensitive geographies. Aclaris Therapeutics, Inc. represents the development-stage specialist segment focused on novel mechanism pathways.
| Leading Market Players |
|---|
| Cipla Limited |
| Pfizer Inc. |
| Johnson & Johnson |
| Aclaris Therapeutics, Inc. |
| Dr. Reddy's Laboratories Ltd. |
| Merck & Co., Inc. |
| GlaxoSmithKline plc |
| Follica, Inc. |
| Sun Pharmaceutical Industries Ltd. |
| Others |
Supply Flow & Price Mechanics
API concentration in Chinese manufacturing zones for finasteride and minoxidil raw materials exposes formulation sponsors to tariff volatility and import inspection delays, compressing margin spreads between branded biologics and commodity generics while forcing supply chain redundancy investments.
Pricing Analysis
Certification level creates the primary spread between FDA-approved biologics and unregulated botanical alternatives. Subscription-based direct-to-patient models for oral finasteride bypass pharmacy benefit managers, capturing margin through disintermediation. Cost compression in the generic oral tier intensifies as Indian manufacturers scale CDSCO-approved production. Dermatology clinics show least price sensitivity for intralesional biologics with statutory reimbursement coverage.
Supply Chain Analysis
Upstream feedstock for prostaglandin analogs and 5-alpha reductase inhibitors draws from active pharmaceutical ingredient clusters in China, India, and Germany. Cold-chain logistics for injectable JAK inhibitors hinge on temperature-controlled specialty pharmacy networks with last-mile integrity challenges. Single-source vulnerability concentrates in Chinese minoxidil precursor manufacturing. Distribution runs through dermatology clinic channels for biologics and telehealth platforms for oral therapies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA breakthrough therapy designation for JAK inhibitors has compressed development timelines, creating a high-growth disruption window where regulatory velocity rewards immunology infrastructure holders and punishes late entrants lacking specialty pharmacy networks.
For Market Incumbents: Harden biologic cold-chain logistics through captive specialty pharmacy partnerships to defend against temperature-integrity failures that trigger formulary exclusion. Deepen backward integration into API manufacturing for finasteride precursors to offset Chinese tariff exposure and secure margin in the oral generic tier.
For New Entrants and Emerging Players: Build out pediatric alopecia areata trial infrastructure to capture first-mover advantage from FDA adolescent study requirements in this historically underserved demographic. Target direct-to-consumer subscription models for topical combination kits through asynchronous telehealth platforms with private-label positioning.
For Investors and Strategic Acquirers: PMDA fast-track designation for severe alopecia areata therapies reshapes the acquisition landscape toward Japanese regulatory strategy capabilities. Long-term viability favors developers with established pharmacovigilance infrastructure for EMA-extended surveillance obligations. Watch EMA hair density registry compliance costs as the inflection signal for mid-cap developer distress.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA breakthrough therapy designation compresses timelines for autoimmune hair loss indications. |
| Manufacturing Scale-Up | Indian CDSCO-approved facilities supply affordable oral finasteride across price-sensitive geographies. |
| Specialty Pharmacy Partnership | Cold-chain integrity agreements secure biologic distribution through dermatology clinic networks. |
| Pediatric Indication Expansion | Adolescent trial data creates exclusivity in the underserved alopecia areata pediatric segment. |
| Direct-to-Consumer Launch | Telehealth subscription models bypass pharmacy benefit managers for oral therapy margin capture. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA filings, ClinicalTrials.gov protocols, EMA assessment reports, and German statutory health insurance reimbursement databases. Interviews with dermatology clinic directors, specialty pharmacy logistics managers, regulatory affairs leads at inflammation-focused sponsors, and payer access specialists inform qualitative assessments. Bottom-up prescription volume modeling triangulates against top-down epidemiology-based prevalence estimates.
Forecast inputs span treatment line positioning, dosage form, administration route, and patient population severity across the projection horizon. CAGRs derive from segment-level volume trajectories weighted by reimbursement policy maturation timelines. Modeled inputs include JAK inhibitor pipeline advancement rates, biosimilar entry assumptions for reference biologics, and telehealth platform patient acquisition curves.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Indian generic manufacturers or accelerated FDA pediatric label expansions would shift outcomes. Cross-checking against CMS Medicare Part D utilization data and German GKV reimbursement statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Cyclosporine Drugs Market
Pharmaceuticals
Motilium Market
Pharmaceuticals
Pharmaceutical Elixir Market
Pharmaceuticals
Russia Diabetes Drugs Market
Pharmaceuticals
Saline Laxative Market
Pharmaceuticals
Structured Product Label Management Market
Pharmaceuticals
Global Finasteride Market
Pharmaceuticals
Penicillin Market
Pharmaceuticals
Minocycline Hydrochloride Market
Pharmaceuticals
Metaxalone Market
Pharmaceuticals
Drug-Induced Dyskinesia Market
Pharmaceuticals
Herpes Labialis Treatment Market
Pharmaceuticals
Myasthenia Gravis Therapeutics Market
Pharmaceuticals
Non-Sterile Compounding Pharmacy Market
Pharmaceuticals
Synthetic Drugs Market
Pharmaceuticals
North America Anticoccidial Drugs Market