
 Global Nursing Care Market | 2026-2036
Global Nursing Care Market Size, Share, and Industry Trends Forecast 2026-2036
Global Nursing Care Market Foresight
The gap between premium skilled nursing and commodity personal care is realigning as reimbursement rates diverge sharply across care settings. HCA Healthcare leverages its hospital-integrated network to sustain higher-acuity admissions, while Brookdale Senior Living anchors its position in assisted living through scale-driven operational density. Amedisys competes aggressively in home-based skilled nursing, navigating Medicare Advantage contracting complexity that commodity providers cannot match.
Nursing care encompasses continuous medical and non-medical assistance delivered by licensed professionals and trained aides, typically involving medication administration, mobility support, wound care, and activities of daily living supervision with staffing ratios often mandated by clinical acuity level. Its primary purpose is to maintain or restore patient functional status while preventing hospital readmission. Skilled nursing commands the largest revenue pool due to higher per-episode reimbursement and workforce credentialing barriers, while in-home care represents the fastest-expanding channel as payors redirect spending from institutional settings. Personal care services occupy a mature, margin-compressed tier where labor substitution and scheduling technology determine profitability.
The US Centers for Medicare & Medicaid Services sets reimbursement ceilings that directly shape provider capacity expansion and site-of-service decisions, while Japan's Ministry of Health, Labour and Welfare calibrates long-term care insurance eligibility to control fiscal outlays amid super-aging demographics. Germany's Federal Joint Committee regulates quality benchmarks for outpatient nursing that influence cross-border staffing flows within the European Union. Stakeholders must monitor how workforce immigration policy and AI-driven care coordination tools reshape cost structures before committing capital to fixed-site expansion.
Market Dynamics
Medicare Advantage penetration in the United States is compressing episode-based reimbursement timelines and forcing providers to absorb utilization risk that fee-for-service structures previously shielded.
Growth Catalysts
- Japan's Long-Term Care Insurance recalibration:Expanded eligibility for home-based services is redirecting institutional capacity toward community care models.
- Remote patient monitoring platforms:CMS reimbursement codes for connected devices are embedding telemetry into standard skilled nursing protocols.
- German outpatient nursing regulations:Federal Joint Committee quality benchmarks are standardizing cross-border staffing credentials within the European Union.
Market Restraints
- Workforce credentialing bottlenecks:State-level nursing licensure compact participation gaps create friction for multi-site operators.
- Reimbursement ceiling compression:Medicare prospective payment system annual updates lag wage inflation in high-cost metropolitan markets.
- Capital intensity of fixed-site expansion:Certificate-of-need requirements in 35 US states extend facility development timelines.
Strategic Opportunities
- India's geriatric care infrastructure:Underpenetrated home health segments in tier-2 cities offer first-mover positioning before regulatory formalization.
- AI-driven care coordination:Predictive analytics for hospital readmission risk are converging with electronic health record interoperability mandates.
- Brazil's ANVISA telehealth framework:Remote supervision protocols enable licensed nurses to oversee paraprofessional aides across dispersed geographies.
Industry Challenges
- Licensed practical nurse scarcity:Community college program throughput constraints limit pipeline replenishment in rural service areas.
- Legacy electronic health record integration:Proprietary data architectures impede real-time information exchange between acute and post-acute settings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Nursing Care Market |
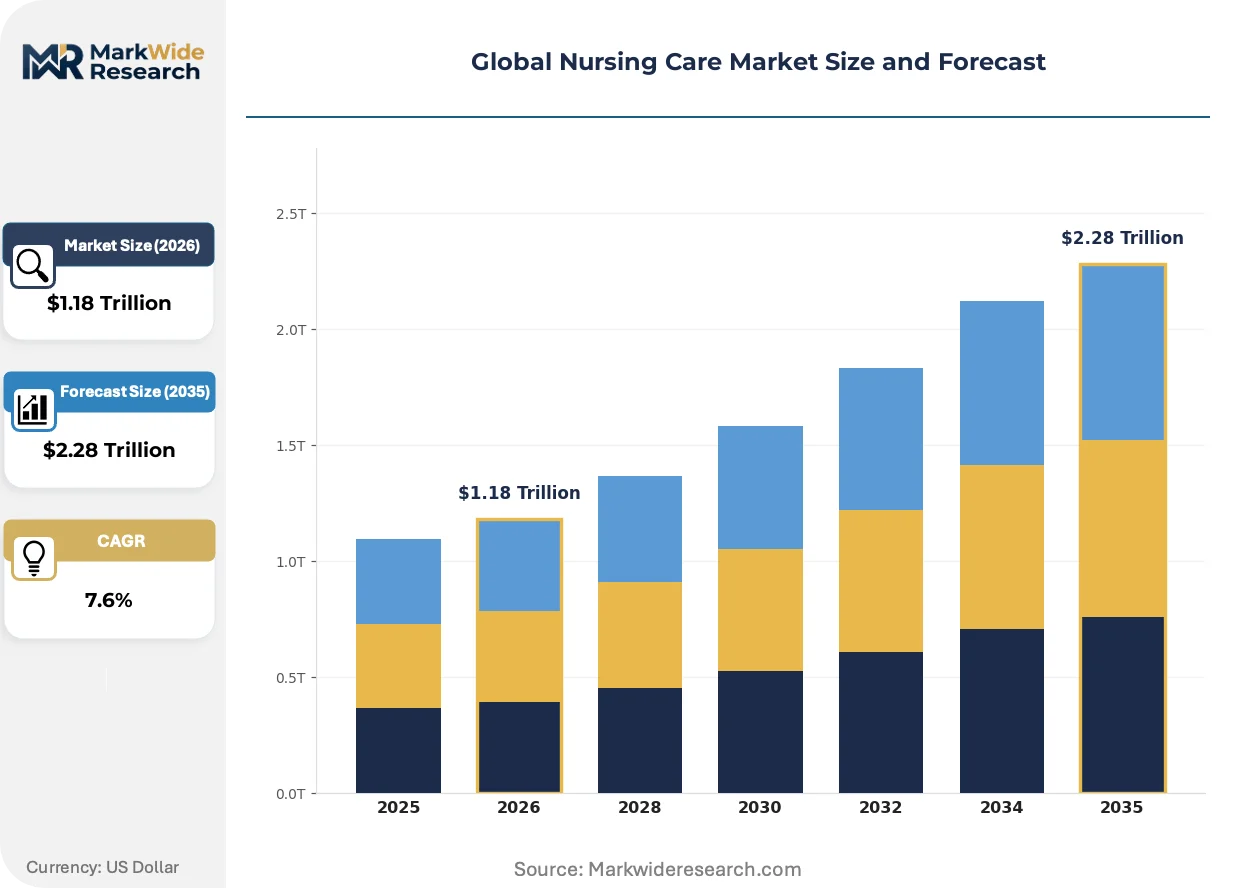
| Market Size in 2026 | $1.18 Trillion |
| Market Size in 2035 | $2.28 Trillion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Skilled Nursing, Personal Care, Hospice Care, Respite Care, Rehabilitation Services End User: Senior Living Communities, Homebound Patients, Assisted Living Facilities, Rehabilitation Centers Care Setting: In-Home Care, Nursing Homes, Community Care Centers, Adult Day Care Centers Funding Source: Private Insurance, Government Programs, Out-of-Pocket, Nonprofit Organizations |
| Companies Covered | HCA Healthcare, Brookdale Senior Living, Amedisys, LHC Group, Kindred Healthcare, Genesis HealthCare, Encompass Health Corporation, Visiting Angels, Comfort Keepers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Nursing Care Market Shifts & Advancements
Technology-enabled care delivery is fragmenting traditional site-of-service boundaries while regulatory frameworks race to catch up with decentralized clinical oversight models.
Remote physiological monitoring hardware is modularizing across wearable form factors and ambient sensor networks. Home health agencies serving Medicare Advantage populations are deploying these toolkits at scale to justify risk-based contract performance guarantees. This technology compression is modularizing the traditional skilled nursing visit into discrete, asynchronously billable interventions.
The European Union's AI Act risk classification framework is imposing documentation burdens on clinical decision-support algorithms deployed in nursing workflows. German outpatient providers must now maintain algorithmic impact assessments for staffing optimization tools. High-acuity home care segments in France and the Netherlands are responding by segregating EU-deployed software stacks from US-centric platforms.
Family caregiver compensation models are formalizing through Medicaid waiver programs and employer-sponsored backup care benefits. Direct-to-consumer care marketplaces are displacing traditional agency intermediaries in metropolitan markets with sufficient caregiver supply density. This channel fragmentation is most visible in California, New York, and Massachusetts where gig-economy platforms aggregate previously informal labor pools.
Global Nursing Care Market Segmentation
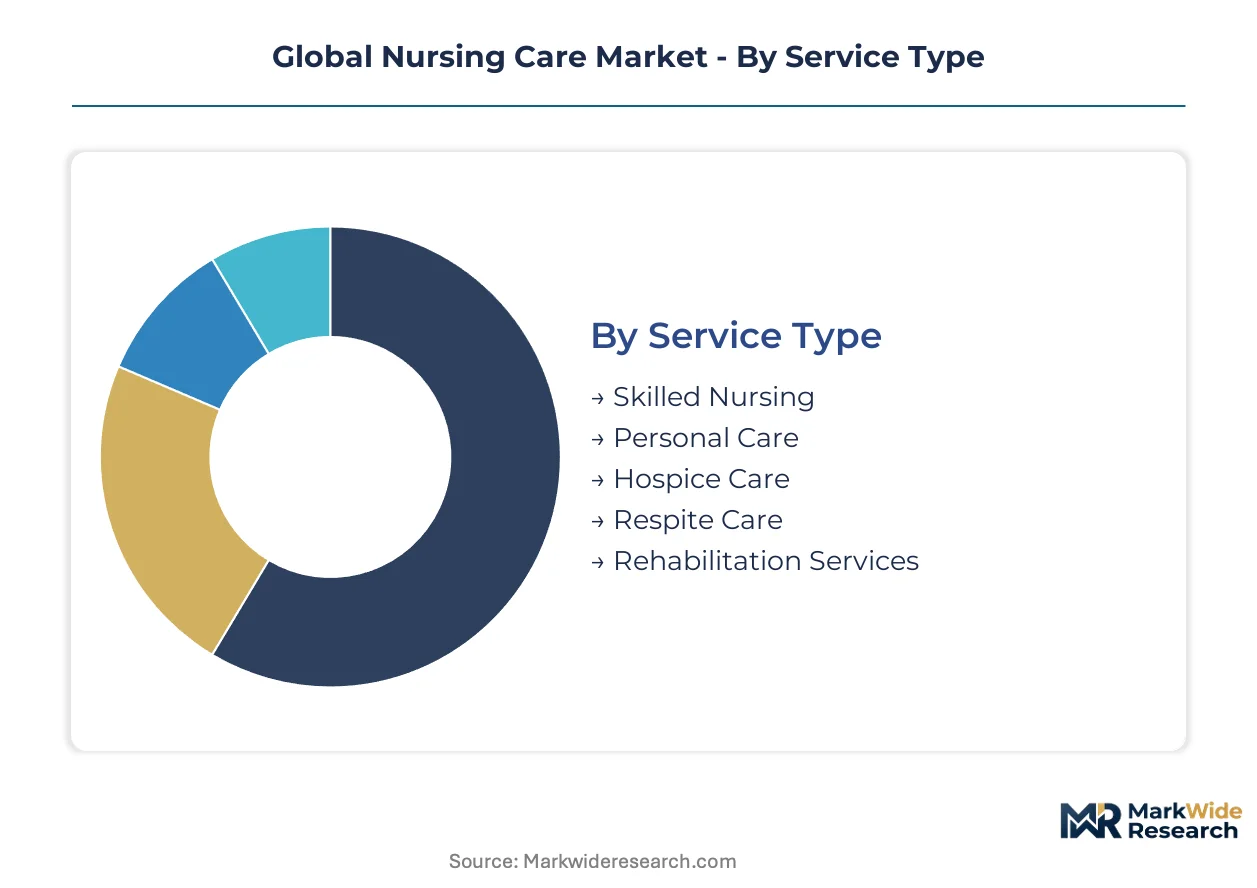
Reimbursement complexity across funding sources and care settings creates divergent margin structures that reward precise segment targeting. Providers must align workforce credentialing depth with the clinical acuity each service type demands.
Service Type:
Technology intensity and clinical oversight requirements separate premium-reimbursed services from commodity labor substitution.
- Skilled Nursing:Licensed registered nurses and therapists deliver wound care, IV therapy, and post-surgical monitoring under physician orders. Medicare prospective payment systems in the United States and Japan's long-term care insurance tiers sustain higher per-episode rates that justify specialized workforce investments.
- Personal Care:Trained aides assist with bathing, dressing, and meal preparation without clinical intervention. Medicaid waiver programs in California and New York cap reimbursement at levels where scheduling optimization software determines operator survival.
- Hospice Care:Interdisciplinary teams manage terminal symptom relief and family bereavement support.
- Respite Care:Temporary relief services for family caregivers prevent institutionalization.
- Rehabilitation Services:Physical, occupational, and speech therapy restore functional capacity post-acute event.
Skilled nursing leads on scale; personal care leads on momentum.
End User:
Site-of-service economics concentrate demand where capital requirements and regulatory burdens vary most sharply.
- Senior Living Communities:Campus-based independent and assisted living environments integrate hospitality with graduated care tiers. Germany's Federal Joint Committee quality benchmarks and US state licensure requirements create barriers that protect incumbent operators with scale.
- Homebound Patients:Individuals with functional limitations who require services delivered to private residences. CMS reimbursement codes for remote patient monitoring in the United States and Japan's expanded home-based eligibility are accelerating capacity shifts away from institutional settings.
- Assisted Living Facilities:Residential settings providing supervision and assistance with daily activities.
- Rehabilitation Centers:Dedicated facilities for intensive therapy following stroke, joint replacement, or trauma.
Homebound patients gain share fastest; senior living communities retain revenue concentration.
Care Setting:
Capital intensity and workforce mobility constraints determine which settings attract new entrant investment versus incumbent consolidation.
- In-Home Care:Services delivered in patient residences with distributed caregiver deployment. Brazil's ANVISA telehealth framework and India's emerging geriatric infrastructure in tier-2 cities enable remote nurse supervision that reduces per-visit labor costs.
- Nursing Homes:24-hour skilled nursing facilities with fixed-site overhead and certificate-of-need constraints in 35 US states.
- Community Care Centers:Neighborhood-based hubs coordinating medical and social services.
- Adult Day Care Centers:Structured daytime programs offering supervision and therapeutic activities.
In-home care climbs the fastest; nursing homes anchor revenue stability.
Funding Source:
Payer mix directly dictates pricing power, collection cycle length, and compliance burden intensity.
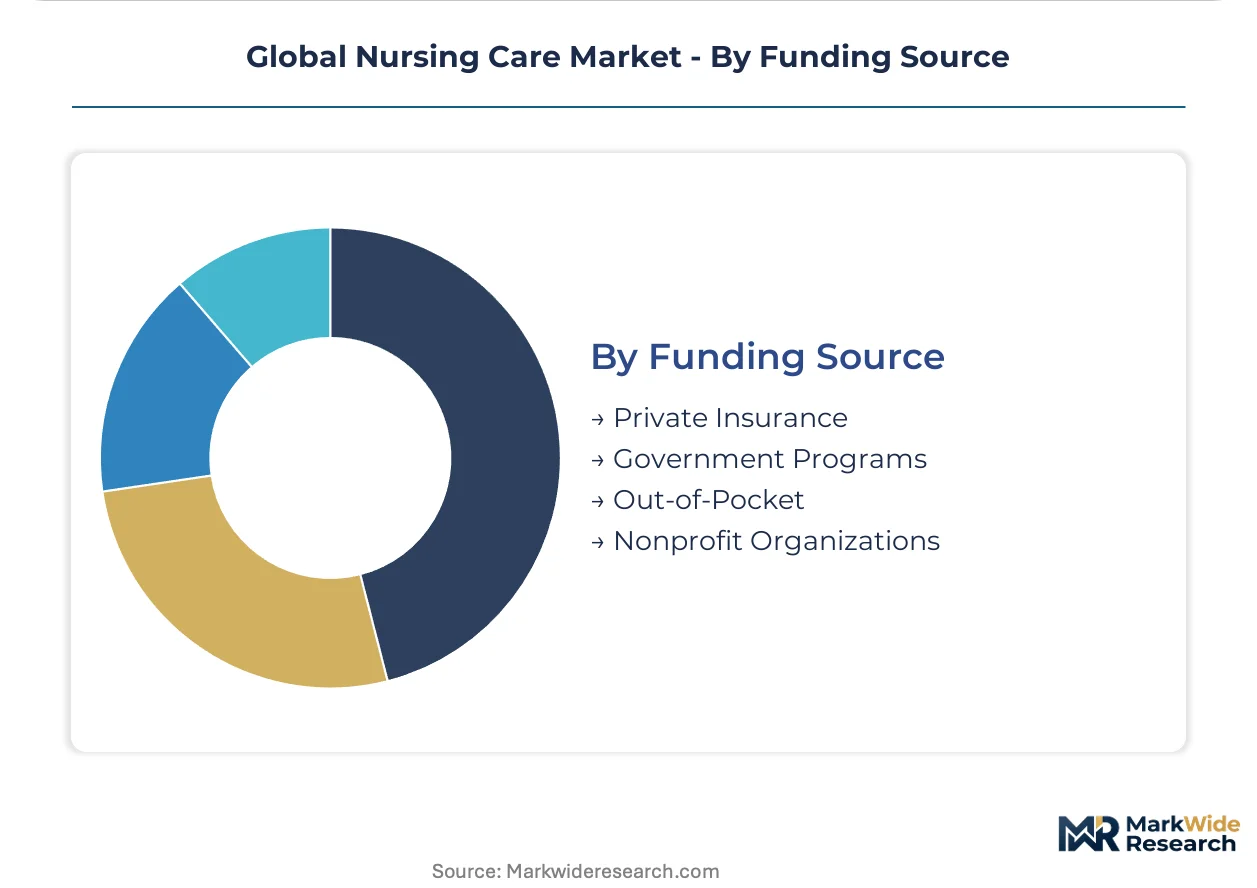
- Private Insurance:Medicare Advantage plans and employer-sponsored coverage in the United States compress episode timelines and transfer utilization risk to providers. Germany's statutory long-term care insurance and Japan's public LTCI system offer more predictable, if capped, reimbursement structures.
- Government Programs:Medicare, Medicaid, and analogous national health systems dominate volume in aging economies. US CMS reimbursement ceilings and Japan's Ministry of Health, Labour and Welfare eligibility recalibrations reshape provider economics annually.
- Out-of-Pocket:Direct consumer payment for services outside public program coverage.
- Nonprofit Organizations:Charitable and faith-based funding for uncompensated care segments.
Government programs lead on scale; private insurance leads on margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's outpatient nursing reforms and Japan's long-term care insurance recalibrations are outpacing United States policy velocity, creating divergent investment climates for cross-border operators.
United States
Medicare Advantage penetration and post-acute site-of-service shifts concentrate demand in home health channels. CMS reimbursement ceilings and certificate-of-need requirements in 35 states constrain fixed-site expansion. The Dallas-Fort Worth metroplex anchors multi-state home health network deployment with telehealth-integrated skilled nursing protocols.
Germany
Super-aging demographics and statutory long-term care insurance sustain outpatient nursing volume growth. The Federal Joint Committee quality benchmarks standardize cross-border staffing credentials within the European Union. North Rhine-Westphalia clusters ambulatory care centers leveraging Polish and Czech nursing workforce mobility.
Japan
Expanded home-based eligibility under Long-Term Care Insurance redirects institutional capacity toward community care models. The Ministry of Health, Labour and Welfare calibrates eligibility thresholds to control fiscal outlays. The Kanto region surrounding Tokyo concentrates technology-enabled care coordination pilot programs with remote patient monitoring integration.
India
Tier-2 city geriatric infrastructure remains underpenetrated, offering first-mover positioning before regulatory formalization. The country's national health regulator and state-level clinical establishment acts create fragmented compliance terrain. Bengaluru and Hyderabad anchor home health startup ecosystems with nurse training academies and telehealth platform development.
Brazil
ANVISA telehealth frameworks enable licensed nurses to oversee paraprofessional aides across dispersed geographies. Municipal health secretariats and supplemental health insurers negotiate divergent reimbursement structures. São Paulo state concentrates integrated care networks with hospital-at-home programs for post-surgical monitoring.
Global Nursing Care Market Competitive Landscape
Top-tier vendors anchor hospital-integrated and scale-driven assisted living positions, while mid-tier home health specialists compete on Medicare Advantage contracting sophistication and geographic density. The vendor base stratifies across three archetypes: acute-care-integrated systems leveraging referral capture, national assisted living platforms optimizing operational scale, and home-based skilled nursing operators navigating risk-based payment complexity. Consolidation accelerates through strategic partnerships between technology vendors and multi-site operators, alongside vertical integration into workforce training pipelines.
Within the acute-care-integrated tier, HCA Healthcare and Encompass Health Corporation exemplify network-based referral capture models. Amedisys occupies a position among home health specialists competing on Medicare Advantage penetration and remote monitoring capability. These three entities represent divergent strategic postures: hospital-anchored vertical integration, rehabilitation-focused site-of-service control, and distributed home-based risk absorption.
| Leading Market Players |
|---|
| HCA Healthcare |
| Brookdale Senior Living |
| Amedisys |
| LHC Group |
| Kindred Healthcare |
| Genesis HealthCare |
| Encompass Health Corporation |
| Visiting Angels |
| Comfort Keepers |
| Others |
Supply & Pricing Matrix
Labor cost inflation in high-metropolitan US markets flows through Medicare reimbursement ceilings into compressed margins across skilled nursing facilities, while home health operators offset wage pressure through remote monitoring technology that fragments traditional per-visit billing into asynchronous reimbursement tiers.
Pricing Analysis
Capacity additions in Brazil and India are reshaping price floors for paraprofessional aide services as remote supervision protocols reduce per-visit labor costs. Three-tier pricing structure across premium skilled nursing, standard home health, and economy personal care segments reflects workforce credentialing depth and clinical oversight intensity. Price differentiation hinges on Medicare Advantage risk absorption capability versus fee-for-service volume scale. Cost compression in commodity personal care is intensifying because Medicaid waiver reimbursement caps lag wage inflation, while premium skilled nursing retains pricing power through hospital-integrated referral capture.
Supply Chain Analysis
State-level nursing licensure compact participation gaps and Federal Joint Committee quality benchmarks in Germany create certification gating that fragments workforce mobility across jurisdictions. Supply concentrates in the United States, Germany, and Japan where aging demographics strain licensed practical nurse pipelines. Raw material dependencies include training academy infrastructure, telehealth platform licensing, and remote monitoring hardware. Single-source vulnerability runs through community college program throughput constraints in rural US service areas. Distribution runs through hospital-integrated networks, national assisted living platforms, and Medicare Advantage-contracted home health agencies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in nursing care rests on technology-enabled labor substitution in home health channels and premium-tier positioning through hospital-integrated referral capture that commands higher per-episode reimbursement rates.
For Market Incumbents: To counter Medicare Advantage utilization risk transfer, anchor capacity in hospital-integrated networks that capture post-acute referrals through physician alignment. Consolidate geographic density in metropolitan markets with sufficient caregiver supply to optimize scheduling algorithms. Backward integration into nurse training academies secures pipeline replenishment amid licensed practical nurse scarcity. For New Entrants and Emerging Players: ANVISA telehealth frameworks in Brazil open a window for remote supervision models that reduce per-visit labor costs below incumbent cost structures. Target India's tier-2 city geriatric infrastructure before regulatory formalization raises compliance barriers. Deploy direct-to-consumer care marketplaces in California, New York, and Massachusetts where gig-economy platform density displaces traditional agency intermediaries. For Investors and Strategic Acquirers: Roll-up economics work for home health specialists with Medicare Advantage contracting sophistication because payer concentration creates scale advantages in risk-based payment negotiation. Platform consolidation across distributed geographies generates procurement leverage on remote monitoring hardware and scheduling software. Watch for inflection when CMS reimbursement codes expand telemetry integration into standard skilled nursing protocols.| Strategic Initiative | Industry Significance |
|---|---|
| Remote Patient Monitoring Integration | CMS reimbursement codes for connected devices embed telemetry into skilled nursing protocols. |
| Medicare Advantage Contracting Scale | Risk-based payment absorption capability separates premium operators from commodity providers. |
| Workforce Training Pipeline Control | Captive nurse academies address licensed practical nurse scarcity in rural service areas. |
| Telehealth Platform Licensing | ANVISA frameworks in Brazil enable remote nurse supervision across dispersed geographies. |
| Geographic Density Optimization | Metropolitan clustering maximizes caregiver scheduling efficiency and reduces per-visit logistics cost. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with home health agency executives, skilled nursing facility administrators, Medicare Advantage contracting officers, and long-term care insurance specialists with secondary validation through CMS reimbursement databases, Japan Ministry of Health Labour and Welfare policy filings, and European Union AI Act implementation guidance. Bottom-up facility capacity counts and top-down payer expenditure estimates were triangulated against cross-border staffing flow data.
Segment-weighting approaches applied service type splits across skilled nursing, personal care, and hospice channels with end-user stratification by senior living communities versus homebound patients. CAGRs were derived from facility expansion timelines, workforce pipeline projections, and reimbursement rate trajectory modeling across the analysis window. Forecast inputs incorporated Medicare Advantage penetration curves, remote monitoring adoption rates, and certificate-of-need constraint intensity by US state.
Revisions become necessary when CMS reimbursement ceiling adjustments, Japan LTCI eligibility recalibrations, or EU AI Act enforcement interpretations materially alter provider economics. Forecasts reflect assumptions on workforce immigration policy stability and technology-enabled labor substitution velocity. A model refresh is warranted upon material change in Medicare Advantage risk transfer intensity or cross-border nursing credential recognition agreements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Healthcare
Elder Care Products Market
Home Healthcare
Global Home Health Care Services Market
Home Healthcare
US Home Healthcare Services Market
Home Healthcare
Virtual Companion Care Market
Home Healthcare
Smart Pillow Market
Home Healthcare
Home Care Market
Home Healthcare
Outpatient Home Therapy Market
Home Healthcare
Global Elderly Care Market
Home Healthcare
Europe Home Care Market
Home Healthcare
Elder Care Subscription Market
Home Healthcare
Home Care Service Market
Home Healthcare
Germany Home Healthcare Market
Home Healthcare
US House Calls Market
Home Healthcare
Senior in-Home Care Services Market
Home Healthcare
Global Ambient Assisted Living (AAL) Market
Home Healthcare
House Call Market