
 Chemotherapy at Home Services Market | 2026-2036
Chemotherapy at Home Services Market Size, Share, and Industry Trends Forecast 2026-2036
Chemotherapy at Home Services Market Analytics
High-complexity infusion protocols are rotating toward home administration as pump technology and remote monitoring capabilities mature. Sciensus Pharma Services Limited leverages specialized cold-chain logistics to sustain end-to-end medication integrity from pharmacy to patient residence. CVS Health Corporation anchors its position through dense retail pharmacy networks that facilitate same-day supportive drug dispensing. Portea Medical differentiates via trained oncology nursing teams operating across multiple Indian metropolitan markets.
Chemotherapy at home services encompass the supervised administration of cytotoxic, targeted, and immunotherapy agents within residential settings, requiring programmable infusion pumps, real-time telemetry, and emergency response protocols. The primary purpose is to replicate inpatient safety standards while eliminating travel burden for immunocompromised patients undergoing prolonged treatment courses. Infusion therapy commands the dominant service type position due to reimbursement alignment and established nursing competencies, while telemedicine delivery mode is expanding fastest as synchronous video platforms integrate with biometric monitoring devices. Pediatric patients represent a concentrated margin pool given the premium placed on family-centered care environments and reduced infection exposure.
FDA oversight of infusion pump safety standards and CMS site-neutral payment policies collectively shape service model economics and technology investment requirements across the United States. State-level nursing scope-of-practice regulations further determine whether advanced practice providers may independently adjust dosing protocols during home visits. Stakeholders must monitor evolving prior authorization requirements from commercial payers as these increasingly dictate patient eligibility criteria and episode-based reimbursement structures.
Market Dynamics
Site-neutral reimbursement from CMS is compressing hospital margins and redirecting oncology volume toward residential infusion models that leverage portable pump systems and cellular telemetry.
Growth Catalysts
- CMS Site-Neutral Payment Models:The 2024 Medicare Physician Fee Schedule expansion equalizes reimbursement across care settings, eliminating the hospital outpatient premium that previously discouraged home-based chemotherapy administration.
- Programmable Ambulatory Infusion Pumps:Next-generation elastomeric and electronic pumps with integrated dose-error reduction software enable safe unsupervised cytotoxic delivery outside clinical walls.
- Suburban Patient Concentration:Exurban corridors surrounding Houston, Phoenix, and Atlanta generate disproportionate demand for home services due to 40-plus mile commutes to accredited infusion centers.
Market Restraints
- Cold-Chain Integrity Costs:Temperature-sensitive biologics require validated packaging and real-time GPS tracking that adds 18-25% to per-dose logistics expenditure versus hospital-based distribution.
- State Nursing Scope Limitations:Twenty-three US states prohibit advanced practice registered nurses from independently adjusting chemotherapy protocols during home visits without physician co-signature.
- Substitution by Oral Oncolytics:Tyrosine kinase inhibitors and other self-administered tablets displace parenteral regimens in breast, lung, and renal cell indications.
Strategic Opportunities
- Underserved Rural Counties:Federally designated Health Professional Shortage Areas across Montana, Wyoming, and North Dakota present first-mover potential for mobile chemotherapy units with telemedicine oversight.
- Remote Patient Monitoring Convergence:Integration of wearable biosensors with synchronous video platforms enables continuous neutropenia surveillance without nursing presence.
- IRA Drug Pricing Negotiation:Selected Medicare Part B drug price caps create margin headroom for home infusion providers to capture volume from hospital outpatient departments.
Industry Challenges
- Oncology Nursing Shortage:Chemotherapy-certified RN recruitment lags demand in 34 metropolitan statistical areas, extending patient onboarding timelines.
- Legacy EHR Integration Friction:Home infusion platforms require custom API development to synchronize with Epic and Cerner hospital records for seamless care coordination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chemotherapy at Home Services Market |
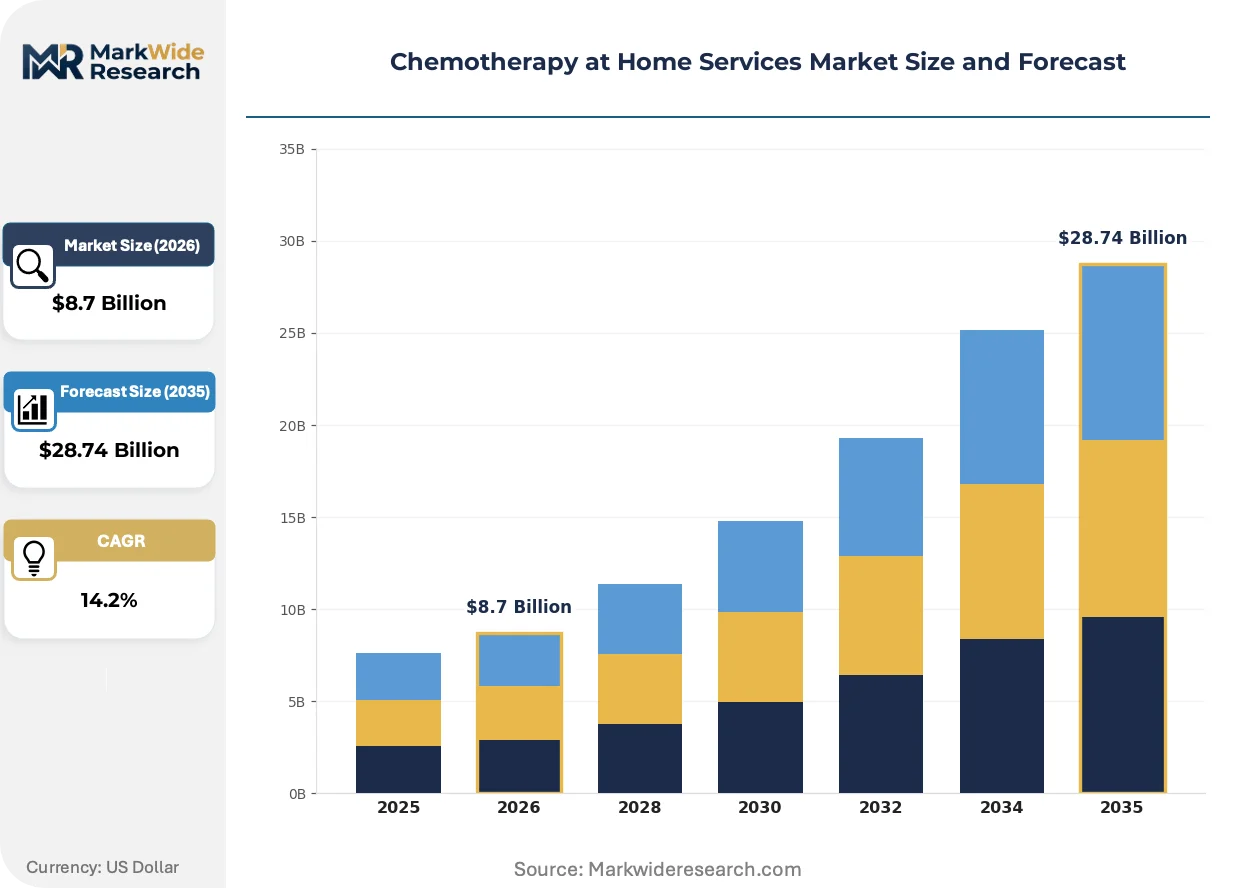
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Infusion Therapy, Oral Chemotherapy, Supportive Care, Palliative Care Patient Type: Adult Patients, Pediatric Patients, Geriatric Patients, Cancer Survivors Care Setting: Home Healthcare, Specialty Clinics, Hospital Outpatient, Rehabilitation Centers Delivery Mode: Telemedicine, In-Home Visits, Mobile Clinics, Remote Monitoring |
| Companies Covered | Sciensus Pharma Services Limited, Portea Medical, Ubiqare, Healthcare at Home, Phenix Health, HCA Healthcare, Advocate Health Care, Medibank Private Limited, CVS Health Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chemotherapy at Home Services Market Evolving Landscape
Technology convergence between medical devices and telecommunications infrastructure is dissolving the physical boundaries of cytotoxic drug delivery while regulatory pressure accelerates site-neutral payment adoption.
Smart infusion pump ecosystems are bifurcating the market between premium tethered systems with full EMR integration and lightweight disposable pumps for stable regimens. Community oncology practices in Florida and Texas are deploying the latter for 5-FU and gemcitabine protocols, compressing per-patient capital requirements while expanding treatable geography.
FDA's 2023 guidance on interoperable infusion pump cybersecurity mandates post-market surveillance reporting for connected devices. Device manufacturers must now submit software bill of materials and vulnerability disclosure policies, increasing compliance overhead most acutely for mid-tier pump suppliers serving regional home infusion networks.
Episode-based purchasing is consolidating oncology procurement around integrated delivery networks that bundle drug, device, and nursing labor. Hospital systems in California and Pennsylvania are displacing standalone home health agencies through captive infusion subsidiaries, capturing margin that previously leaked to third-party providers.
Chemotherapy at Home Services Market Segmentation
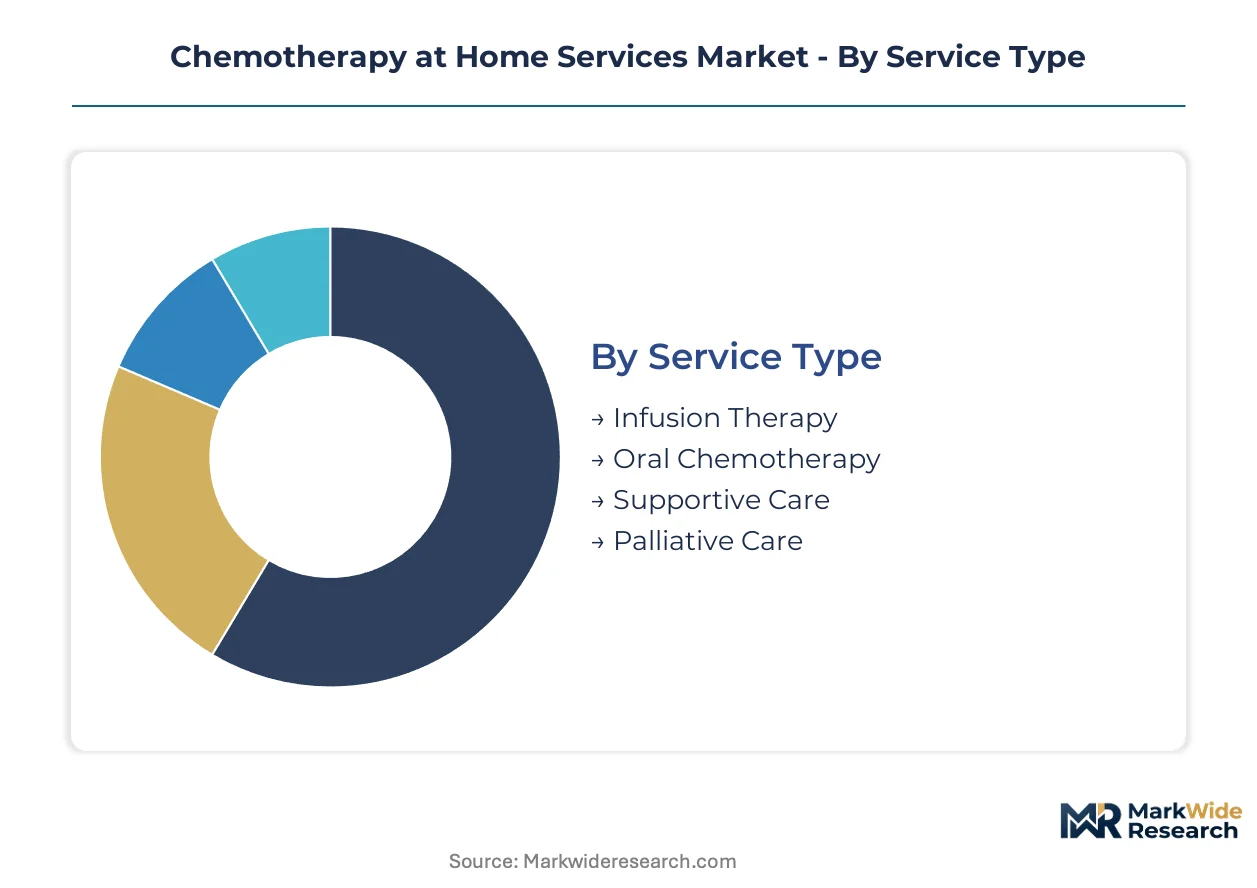
Segmentation in chemotherapy at home services reveals how reimbursement alignment, nursing competencies, and technology maturity distribute value across distinct service configurations. Understanding these divides enables stakeholders to match capital deployment with the specific regulatory and operational requirements governing each segment.
Service Type:
FDA infusion pump safety standards and CMS reimbursement codes create divergent margin profiles across service modalities, with device-dependent categories carrying higher compliance overhead.
- Infusion Therapy:Parenteral administration of cytotoxic, targeted, and immunotherapy agents via programmable ambulatory pumps with integrated dose-error reduction software. Demand concentrates in suburban corridors surrounding Houston, Phoenix, and Atlanta where 40-plus mile commutes to accredited centers drive residential preference. CMS site-neutral payment parity since 2024 has eliminated the hospital outpatient premium that previously suppressed home adoption.
- Oral Chemotherapy:Self-administered tyrosine kinase inhibitors and hormone therapies requiring pharmacy coordination but minimal nursing presence. Patient concentration clusters in managed care populations where prior authorization efficiency determines provider selection, though substitution by oral oncolytics in breast and lung indications constrains parenteral volume.
- Supportive Care:Antiemetics, growth factors, and hydration protocols delivered between active treatment cycles.
- Palliative Care:Symptom-focused regimens emphasizing comfort and family-centered decision-making in terminal disease stages.
Infusion therapy handles the majority of throughput; telemedicine-integrated delivery is expanding most quickly on share as synchronous platforms mature.
Patient Type:
Clinical complexity and caregiver burden vary sharply across age strata, with pediatric and geriatric populations requiring differentiated staffing ratios and emergency preparedness protocols.
- Adult Patients:Working-age populations managing multi-cycle regimens while maintaining employment, driving demand for evening and weekend scheduling flexibility.
- Pediatric Patients:Family-centered care environments command premium pricing due to infection exposure reduction and parental presence requirements. Demand concentrates in academic medical center catchments where subspecialty coordination spans oncology, cardiology, and neurology for syndrome-specific protocols.
- Geriatric Patients:Polypharmacy management and fall-risk assessment dominate service design, with Medicare Advantage penetration determining prior authorization burden and episode-based reimbursement capture.
- Cancer Survivors:Long-term surveillance and late-effect monitoring extending years beyond active treatment completion.
Adult patients generate the largest absolute volume; pediatric services command the steepest margin premium per episode.
Care Setting:
Capital intensity and regulatory jurisdiction shift dramatically based on whether services deploy within residential property, leased clinical space, or hospital-affiliated infrastructure.
- Home Healthcare:Licensed residential infusion with 24/7 nursing telephony backup and GPS-tracked cold-chain logistics. State nursing scope-of-practice regulations in 23 US states prohibit advanced practice registered nurses from independently adjusting chemotherapy protocols without physician co-signature, fragmenting operational standardization.
- Specialty Clinics:Community-based oncology practices with captive infusion capacity, capturing margin previously leaked to hospital outpatient departments through site-neutral payment arbitrage.
- Hospital Outpatient:Legacy delivery mode facing volume erosion as integrated delivery networks bundle drug, device, and nursing labor into episode-based purchasing.
- Rehabilitation Centers:Transitional settings for patients recovering from surgical interventions or acute toxicity events.
Home healthcare is gaining share fastest as pump technology and remote monitoring dissolve physical boundaries of safe cytotoxic delivery; hospital outpatient retains the largest installed base but bleeds volume quarter over quarter.
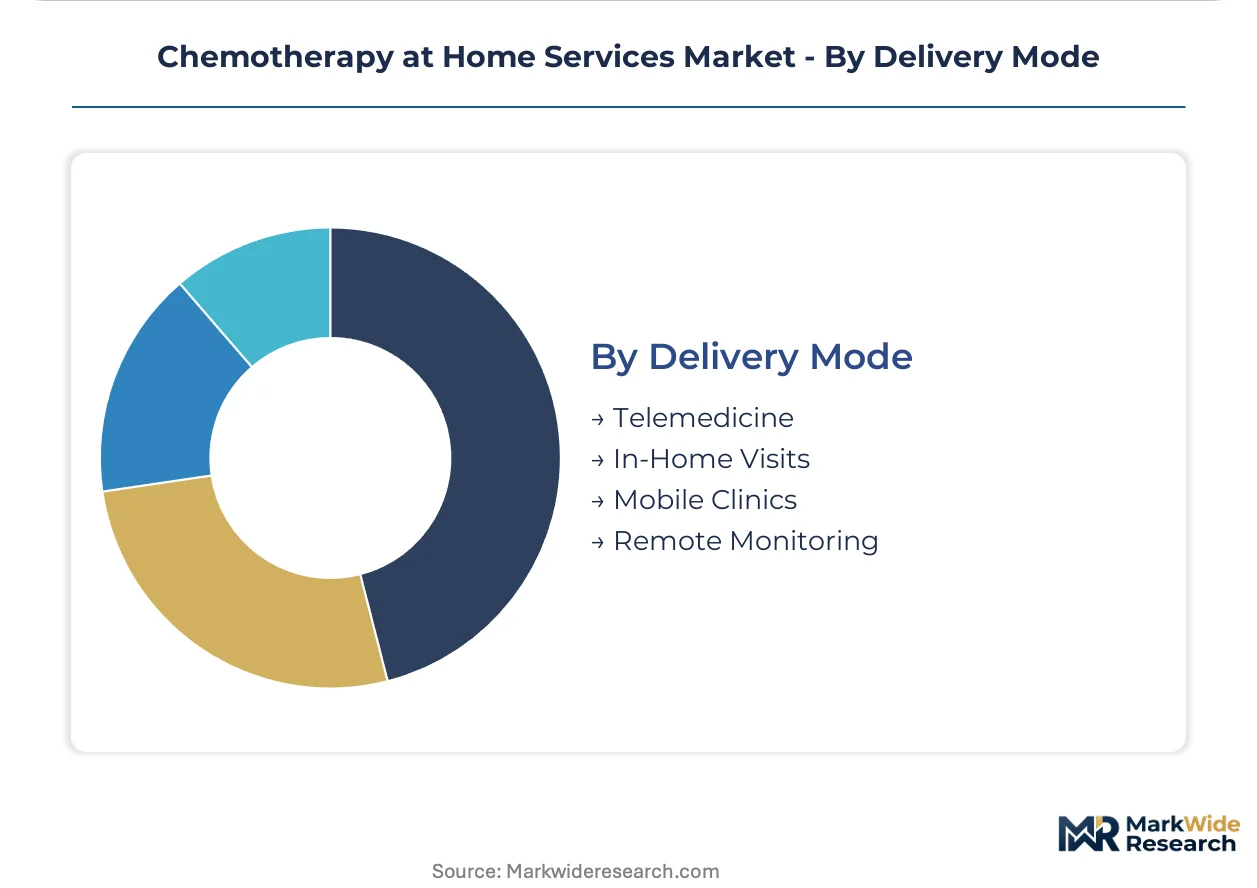
Delivery Mode:
Technology convergence between medical devices and telecommunications infrastructure is redistributing labor requirements across synchronous, asynchronous, and physical presence modalities.
- Telemedicine:Synchronous video platforms with biometric device integration enable real-time toxicity assessment without nursing travel time. FDA 2023 cybersecurity guidance mandates post-market surveillance reporting for connected devices, increasing compliance overhead for mid-tier platform suppliers.
- In-Home Visits:Chemotherapy-certified RN presence for high-complexity protocols requiring vascular access verification and acute reaction management. Recruitment lags demand in 34 metropolitan statistical areas, extending patient onboarding timelines.
- Mobile Clinics:Federally designated Health Professional Shortage Areas across Montana, Wyoming, and North Dakota present first-mover potential for equipped vehicles with telemedicine oversight.
- Remote Monitoring:Wearable biosensors tracking neutropenia, hydration status, and cardiac function with automated alert escalation.
In-home visits still process the majority of encounters; remote monitoring is climbing the fastest as continuous telemetry reduces nursing labor intensity per patient.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Home chemotherapy services concentrate where suburban sprawl collides with hospital consolidation, creating geographic arbitrage for residential infusion models. Regulatory divergence across jurisdictions fragments operational standardization while reimbursement parity accelerates volume shifts.
United States
CMS site-neutral payment expansion since 2024 eliminated hospital outpatient premiums that suppressed home adoption. FDA cybersecurity mandates for connected infusion pumps increase compliance overhead for mid-tier device suppliers. Demand clusters in exurban Houston, Phoenix, and Atlanta corridors where 40-plus mile commutes to accredited centers drive residential preference.
United Kingdom
NHS England's Cancer Strategy prioritizes treatment closer to home, expanding community oncology infrastructure. NICE technology appraisals determine reimbursement eligibility for home-administered biologics. London and Manchester health systems deploy mobile chemotherapy units with telemedicine oversight to reduce tertiary center congestion.
Germany
Outpatient chemotherapy reimbursement under G-DRG system favors hospital-affiliated home health subsidiaries. BfArM post-market surveillance requirements govern programmable pump safety standards. Bavaria and North Rhine-Westphalia integrated care networks bundle drug, device, and nursing labor into episode-based contracts.
India
CDSCO import licensing frameworks for temperature-sensitive biologics create cold-chain logistics barriers for residential delivery. Ayushman Bharat expansion extends insurance coverage to home-based cancer care in tier-1 cities. Bangalore, Mumbai, and Delhi metropolitan markets concentrate trained oncology nursing capacity for high-complexity protocols.
Australia
TGA medical device regulations align with FDA cybersecurity guidance for connected infusion systems. Medicare Benefits Schedule item numbers for home chemotherapy administration vary by state, fragmenting provider economics. Sydney and Melbourne private health networks anchor volume while rural Health Professional Shortage Areas present mobile clinic opportunities.
Chemotherapy at Home Services Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the chemotherapy at home services market. Integrated delivery networks with captive pharmacy and nursing operations capture margin through episode-based bundling, while standalone home health agencies compete on geographic coverage and scheduling flexibility. Three archetypes dominate: hospital-affiliated infusion subsidiaries, specialized oncology home health providers, and retail pharmacy networks with nursing dispatch capabilities. Consolidation accelerates through acquisition of regional home health licenses and strategic partnerships with cold-chain logistics specialists.
Among specialized oncology service providers, Sciensus Pharma Services Limited and Portea Medical occupy distinct positions. Sciensus anchors European markets through pharmaceutical supply chain integration, while Portea Medical exemplifies emerging-market scalability across Indian metropolitan regions. CVS Health Corporation represents retail pharmacy network expansion into clinical service delivery, leveraging dense storefront infrastructure for same-day supportive care dispensing.
| Leading Market Players |
|---|
| Sciensus Pharma Services Limited |
| Portea Medical |
| Ubiqare |
| Healthcare at Home |
| Phenix Health |
| HCA Healthcare |
| Advocate Health Care |
| Medibank Private Limited |
| CVS Health Corporation |
| Others |
Value Network & Pricing Analysis
FDA infusion pump cybersecurity certification gates both supplier qualification and price differentiation simultaneously, as manufacturers must absorb post-market surveillance overhead to access CMS-reimbursed service tiers while cold-chain logistics capabilities separate premium providers from commodity competitors.
Pricing Analysis
CMS site-neutral payment parity dictates the pricing tier structure across home chemotherapy services, compressing the historical hospital outpatient premium and forcing providers toward three-tier pricing structure across premium, standard, and economy levels based on nursing credential intensity and telemetry integration depth. Price differentiation rests on cold-chain certification grade and real-time GPS tracking capability, with pediatric family-centered protocols commanding the steepest premiums. Cost compression in standard-tier infusion therapy is intensifying because IRA drug pricing negotiations cap Medicare Part B reimbursement headroom. Managed care populations exhibit highest price sensitivity due to prior authorization friction, while self-pay pediatric segments remain least elastic.
Supply Chain Analysis
Inventory lead times for temperature-sensitive biologics stretch 72-96 hours from pharmacy to patient residence, necessitating validated packaging partnerships across United States, Germany, and India where pharmaceutical cold-chain infrastructure concentrates. Raw material dependencies center on programmable elastomeric pumps, cellular telemetry modules, and single-use infusion sets. Single-source vulnerability in GPS-tracked thermal packaging creates exposure to logistics disruption during seasonal demand surges. Distribution runs through integrated delivery networks that bundle drug, device, and nursing labor into episode-based contracts, displacing standalone home health agency channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
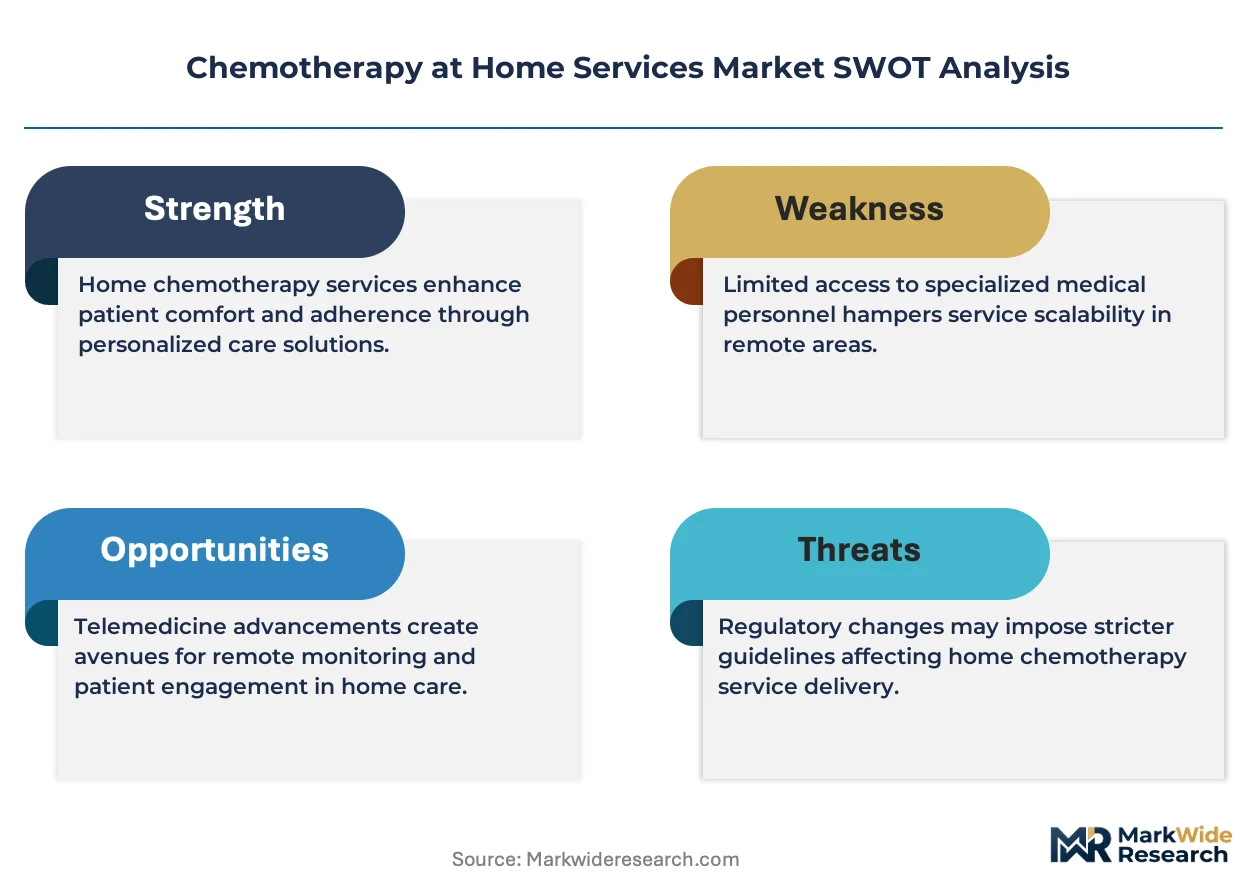
Home chemotherapy services represent a service-attach opportunity where remote patient monitoring subscriptions and 24/7 nursing telephony expand faster than infusion pump hardware deployment, creating recurring revenue layers with superior retention economics.
For Market Incumbents: Shield market position by acquiring chemotherapy-certified RN staffing pools in 34 underserved metropolitan statistical areas where recruitment lags extend patient onboarding timelines. Anchor backward integration into cold-chain logistics through partnerships with validated packaging specialists, neutralizing the 18-25% per-dose cost premium that erodes margin against hospital-affiliated competitors. Prioritize Epic and Cerner API certification to reduce EHR integration friction that currently fragments care coordination.
For New Entrants and Emerging Players: Differentiate on synchronous video platform integration with wearable biosensors, targeting the telemedicine delivery mode segment where regulatory compliance overhead has filtered out mid-tier suppliers. Penetrate federally designated Health Professional Shortage Areas across Montana, Wyoming, and North Dakota through mobile chemotherapy units with telemedicine oversight, exploiting first-mover absence in rural counties. Deploy direct-to-payer contracting that bypasses hospital system GPO capture.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across telemedicine-integrated delivery as software platforms displace nursing labor intensity per patient. Long-term viability favors integrated delivery networks with captive pharmacy and nursing operations over standalone home health agencies lacking episode-based bundling capability. Target acquisition archetypes: regional home health licenses with established CMS accreditation in exurban corridors surrounding Houston, Phoenix, and Atlanta. Monitor state nursing scope-of-practice liberalization as inflection signal for operational standardization arbitrage.
| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Logistics Partnership | Validated thermal packaging from pharmacy to patient residence sustains biologic integrity across 40-plus mile exurban corridors. |
| CMS Site-Neutral Reimbursement Strategy | Payment parity capture redirects oncology volume from hospital outpatient departments toward residential infusion models. |
| Remote Patient Monitoring Platform Integration | Wearable biosensor convergence with synchronous video enables continuous neutropenia surveillance without nursing presence. |
| Chemotherapy-Certified RN Staffing Expansion | Specialized nursing capacity in 34 underserved metropolitan areas compresses patient onboarding timelines against demand. |
| EHR Interoperability Certification | Epic and Cerner API synchronization eliminates care coordination friction between home infusion platforms and hospital records. |
Research Methodology
Operator-level perspectives from infusion therapy directors, oncology nursing supervisors, hospital procurement managers, and payer access specialists anchored the qualitative base. Primary interviews combined with secondary validation from FDA 510(k) filings, CMS Medicare Physician Fee Schedule releases, hospital GPO contract databases, and state nursing board regulatory updates. Bottom-up service volume modeling triangulated against top-down reimbursement flow analysis.
Sensitivity analysis tested forecast robustness across the projection horizon by varying CMS site-neutral payment adoption rates, oral oncolytic substitution trajectories, and state nursing scope liberalization timelines. Segmentation dimensions modeled include service type, patient age strata, care setting configuration, and delivery mode technology intensity. CAGRs derived from logistic diffusion curves fitted to historical home health adoption patterns, with infusion pump safety standard evolution and cold-chain logistics cost curves as industry-specific inputs.
The analysis sits within stated boundaries; outcomes outside sustained CMS reimbursement parity or accelerated FDA cybersecurity mandate enforcement would require recalibration. Forecasts reflect documented assumptions regarding nursing labor availability and telemedicine platform penetration. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Healthcare
UK Home Healthcare Market
Home Healthcare
Global Health Caregiving Market
Home Healthcare
Portable Toilet for Elderly Market
Home Healthcare
Elder Care Products Market
Home Healthcare
Elder Care Subscription Market
Home Healthcare
Global Home Health Care Services Market
Home Healthcare
House Call Market
Home Healthcare
Global Ambient Assisted Living (AAL) Market
Home Healthcare
Global Nursing Care Market
Home Healthcare
Global Elderly Care Market
Home Healthcare
Homecare Oxygen Concentrators Market
Home Healthcare
Smart Mattress Market
Home Healthcare
Adult Day Care Market
Home Healthcare
US House Calls Market
Home Healthcare
Canada Home Healthcare Market
Home Healthcare
Global Home Infusion Therapy Market