
 Electronic Pill Market | 2026-2036
Electronic Pill Market Size, Share, and Industry Trends Forecast 2026-2036
Electronic Pill Market Analysis
Project finance and leasing arrangements for connected drug delivery infrastructure is narrowing the competitive field to entities with capital access or institutional backing. Medtronic leverages its established cardiovascular device financing partnerships to extend into electronic pill ecosystems. CapsoVision, Inc. specializes in capsule endoscopy platforms and anchors its position through dedicated manufacturing scale. Olympus Corporation competes by controlling distribution channels across Asia-Pacific hospital networks.
An electronic pill is an ingestible device incorporating microsensors, wireless transmitters, and biocompatible housings to monitor physiological parameters or verify medication ingestion, typically operating at frequencies between 433 MHz and 2.4 GHz for body-area communication. These devices serve primarily to close the loop between prescribed therapy and verified patient compliance in chronic disease protocols. Smart pills command the largest revenue share within product type categories due to diagnostic imaging applications, while biosensors represent the fastest-expanding segment as continuous glucose and biomarker tracking gains clinical validation. RFID technology dominates the technology dimension through low-power requirements and established healthcare infrastructure compatibility, though Bluetooth-enabled platforms are gaining traction in home care settings where smartphone integration reduces dedicated reader costs.
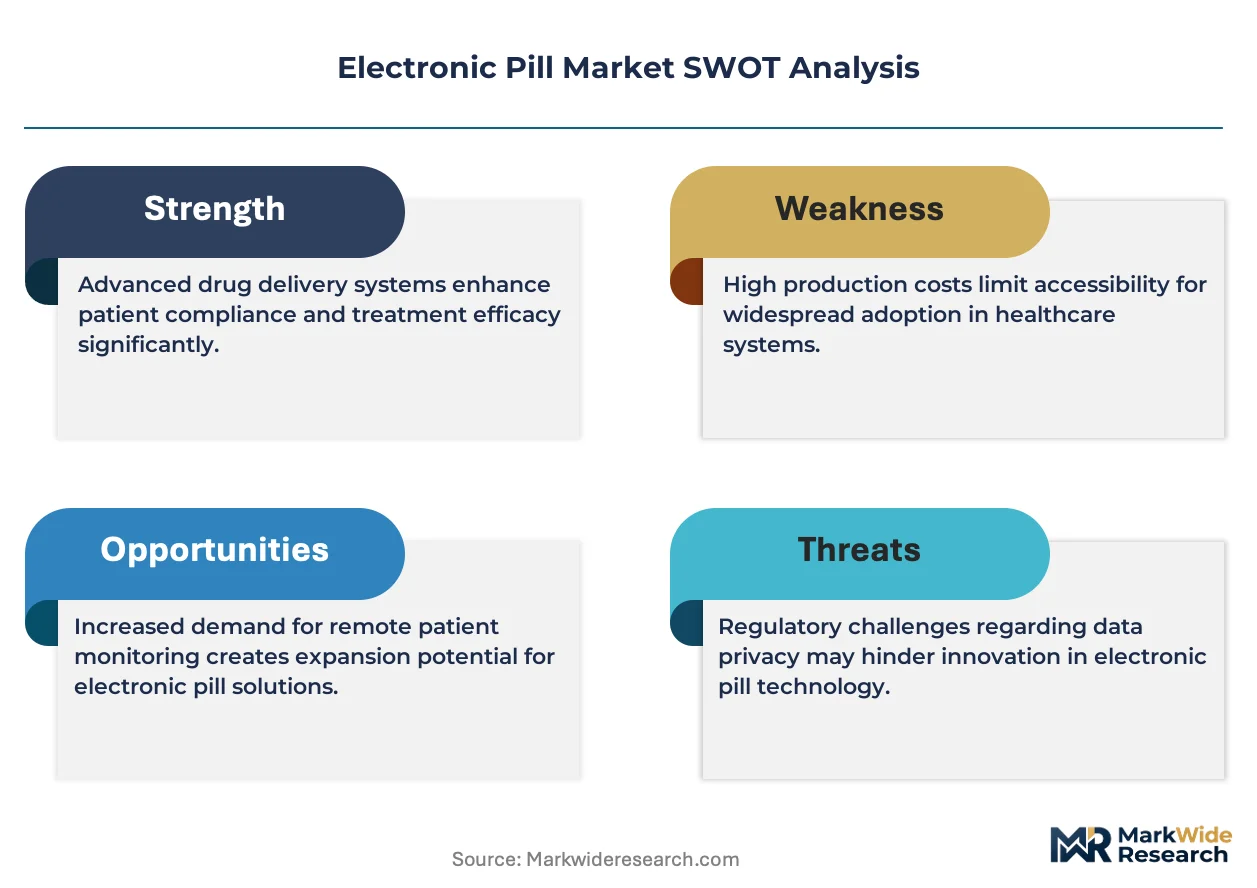
The FDA breakthrough device program and HIPAA data interoperability standards shape product development timelines and cybersecurity architecture requirements for electronic pill manufacturers seeking US market access. EMA's Medical Device Regulation imposes clinical evidence thresholds that favor established players with post-market surveillance capabilities. ISO 13485 quality management certification functions as a de facto market access gate across OECD jurisdictions. Stakeholders must evaluate whether to build captive cloud infrastructure for biomarker data or partner with existing health information exchanges as regulatory scrutiny intensifies on cross-border patient data flows.
Market Dynamics
Project finance structures for connected drug delivery infrastructure are consolidating competitive positioning around entities with demonstrated capital access, compressing the vendor landscape as hospital systems demand turnkey remote monitoring deployments rather than component procurement.
Growth Catalysts
- FDA Breakthrough Device Pathway:The designation compresses commercialization timelines for ingestible sensor platforms by enabling prioritized review queues and enhanced FDA feedback loops.
- Value-Based Care Contracts:Integrated US health networks tie reimbursement to verified medication compliance metrics, creating direct procurement pull for electronic pill verification systems.
- RFID Infrastructure Compatibility:Low-power 433 MHz transmission protocols leverage existing hospital asset-tracking networks, reducing dedicated reader deployment costs for early adopters.
Market Restraints
- Biocompatible Housing Material Costs:Medical-grade polymer and ceramic encapsulation for gastrointestinal transit durability carries raw material premiums that elevate unit economics above conventional pill formulations.
- Cloud Infrastructure Concentration:Biomarker data storage requirements create dependency on a limited set of HIPAA-compliant health information exchanges, amplifying vendor lock-in risk.
- EMA MDR Clinical Evidence Thresholds:Post-market surveillance mandates for Class III ingestible devices impose documentation burdens that favor established players with regulatory affairs scale.
Strategic Opportunities
- German Hospital System Expansion:Remote patient monitoring program rollouts across Bundesland health networks create demand for integrated electronic pill platforms with EHR interoperability.
- Bluetooth-Enabled Home Care:Smartphone integration eliminates dedicated reader hardware, opening ambulatory and post-acute settings previously cost-prohibitive for RFID-dependent systems.
- Continuous Glucose Validation:Biosensor segment expansion into metabolic monitoring applications leverages existing diabetes management reimbursement codes for faster payer acceptance.
Industry Challenges
- ISO 13485 Certification Timeline:Quality management system audits for ingestible device manufacturing create 12-18 month gaps between design freeze and commercial shipment authorization.
- Cybersecurity Architecture Talent:HIPAA data interoperability requirements demand specialized firmware engineers with body-area network encryption expertise, a skill set concentrated in cardiovascular device firms.
- Legacy EHR Integration:HL7 FHIR standard adoption varies across health network IT estates, forcing custom API development for biomarker data ingestion into existing clinical workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electronic Pill Market |
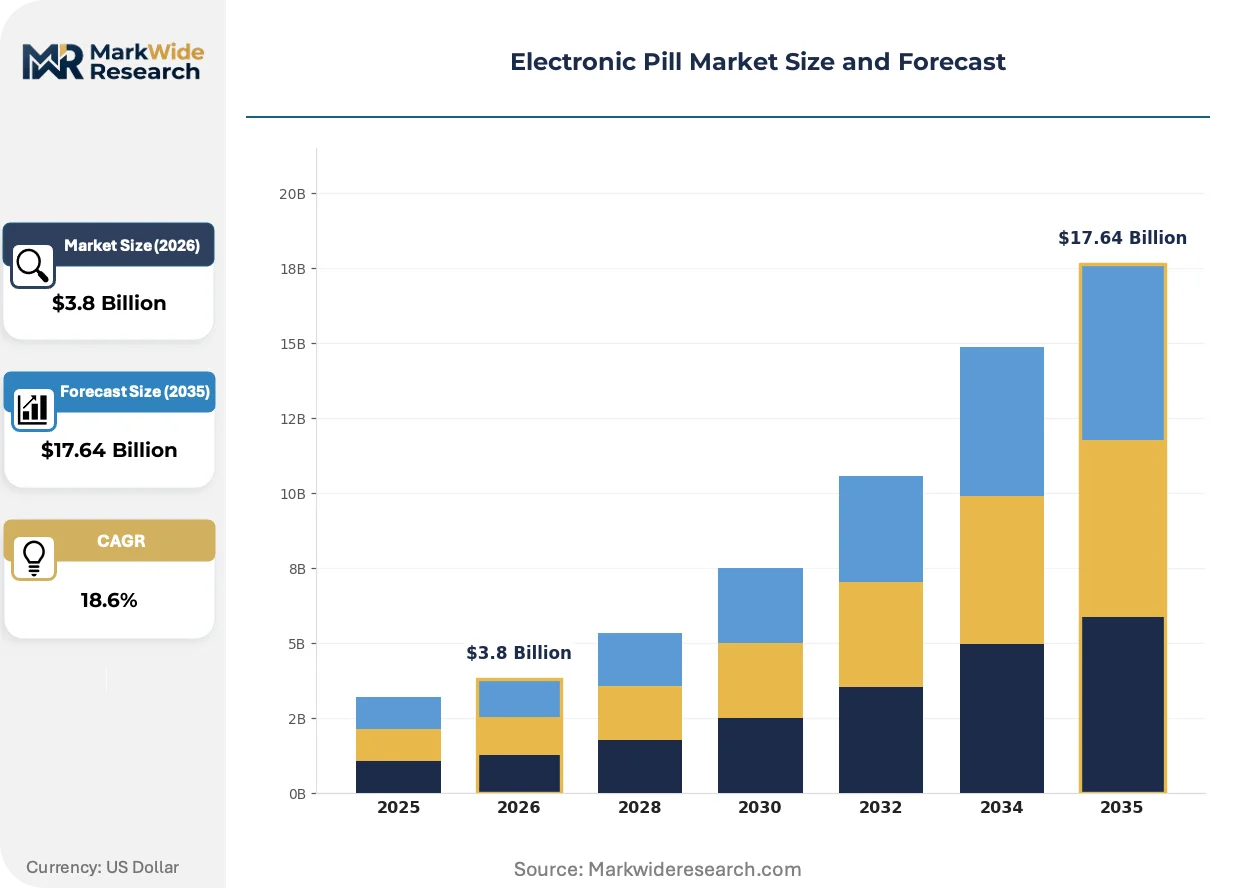
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Pills, Adherence Monitoring, Biosensors, Wearable Devices Technology: RFID, Bluetooth, NFC, Ultrasound End User: Hospitals, Outpatient Clinics, Home Care, Research Institutions Use Case: Chronic Disease Management, Clinical Trials, Medication Adherence, Remote Monitoring |
| Companies Covered | Medtronic, Olympus Corporation, CapsoVision, Inc., IntroMedic, Proteus Digital Health, JINSHAN Science & Technology, Check-Cap, BodyCap, Shenzhen Jifu Medical Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electronic Pill Market Emerging Trajectories
Wireless transmission protocols and regulatory data architectures are reshaping how electronic pill manufacturers structure product roadmaps and partnership strategies, with convergence between diagnostic imaging and therapeutic monitoring functions driving platform consolidation.
Multi-frequency transceiver modules capable of switching between 433 MHz RFID and 2.4 GHz Bluetooth protocols are collapsing the distinction between hospital-grade and consumer-accessible electronic pill categories. Cardiology departments at Cleveland Clinic and Charité Berlin are piloting dual-mode capsules that transmit high-resolution imaging data via hospital infrastructure while enabling home-based compliance verification through patient smartphones. This technical flexibility is collapsing the traditional segmentation between acute diagnostic and chronic disease management applications, forcing manufacturers to engineer for both regulated clinical and direct-to-patient use cases within single product families.
EMA's Medical Device Regulation implementation is compressing notified body capacity for Class III ingestible device reviews, extending technical documentation assessment timelines. Manufacturers are responding by front-loading clinical evidence generation through prospective registry studies, with Swissmedic and TGA parallel submission strategies becoming standard to circumvent single-jurisdiction bottlenecks. The biosensor segment faces the steepest compliance burden, as continuous biomarker monitoring claims trigger higher clinical evidence thresholds than discrete ingestion verification.
Hospital procurement committees are consolidating vendor relationships around platforms offering integrated data analytics rather than standalone device supply. Integrated delivery networks in Texas and California now require electronic pill suppliers to demonstrate bidirectional EHR integration and population health dashboard compatibility as table stakes for formulary inclusion. This specification elevation is displacing component-focused vendors who lack health informatics partnerships or captive cloud infrastructure, concentrating contract awards among firms with established clinical decision support software portfolios.
Electronic Pill Market Segmentation
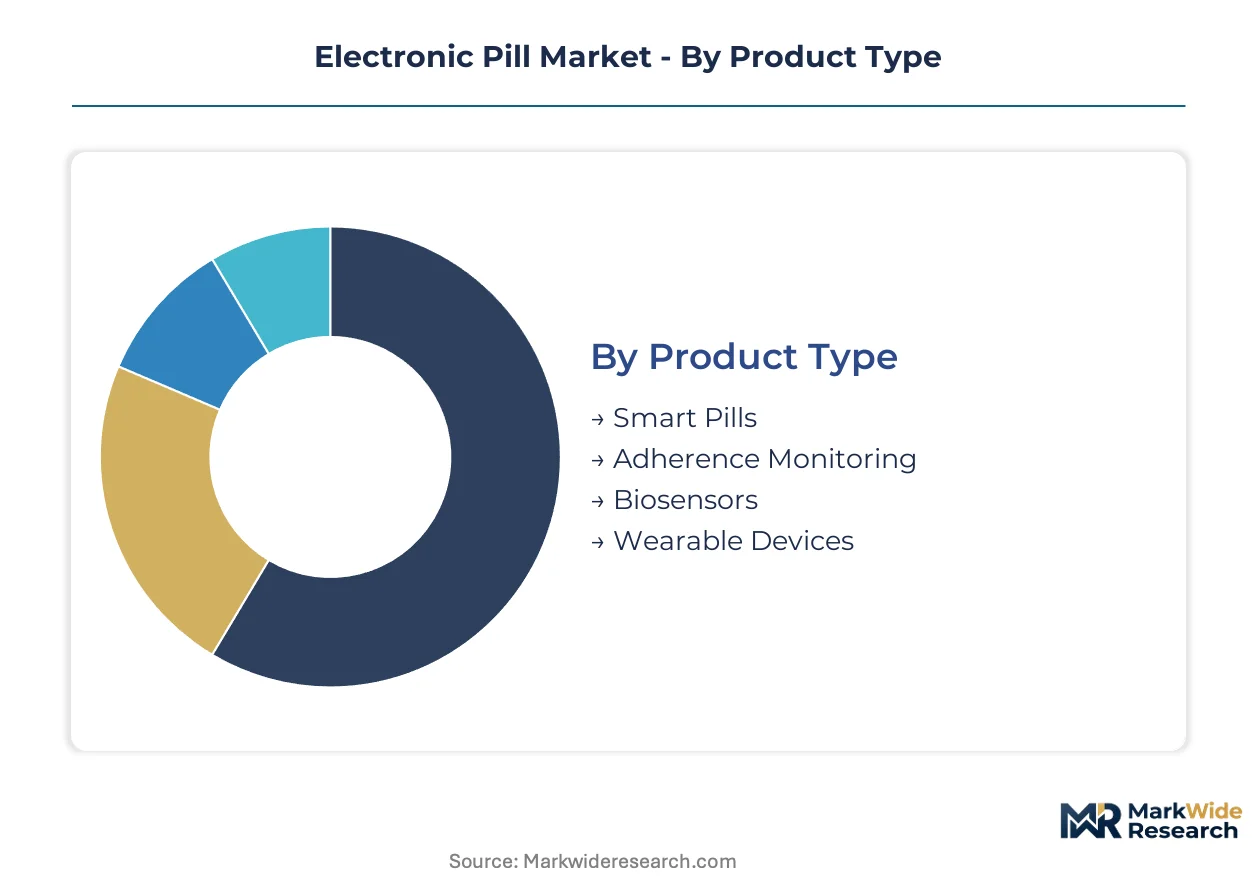
Electronic pill manufacturers engineer distinct product architectures to match transmission protocols, clinical settings, and reimbursement pathways. Segmentation strategy determines whether platforms target hospital infrastructure integration or direct-to-patient deployment models.
Product Type:
Product architectures span diagnostic imaging, compliance verification, and continuous biomarker tracking functions across acute and ambulatory care.
- Smart Pills:Capsule endoscopy platforms incorporate CMOS imagers, LED illumination arrays, and biocompatible optical windows for gastrointestinal visualization. Demand concentrates in German hospital systems expanding remote patient monitoring programs, driven by EHR interoperability requirements for integrated diagnostic workflows.
- Biosensors:Ingestible devices with enzymatic or electrochemical transducers enable continuous glucose and biomarker tracking through gastrointestinal fluid sampling. Home care settings in the United States prioritize these platforms as integrated health networks tie value-based care contracts to real-time metabolic data.
- Adherence Monitoring:Ingestion verification systems using pressure or pH sensors confirm medication delivery with timestamped transmission.
- Wearable Devices:External receiver patches and body-area network hubs capture and relay data from ingestible sensors to clinical dashboards.
The dominant share belongs to Smart Pills, while Biosensors is closing the gap fastest.
Technology:
Transmission frequency selection shapes power budgets, reader infrastructure requirements, and regulatory classification pathways.
- RFID:Passive and semi-passive 433 MHz transponders leverage existing hospital asset-tracking infrastructure with microampere-level power draw. United States health networks favor these platforms for inventory integration and reduced dedicated hardware deployment costs.
- Bluetooth:2.4 GHz protocols enable direct smartphone pairing, eliminating proprietary reader hardware for post-acute and ambulatory applications. German outpatient clinics are expanding procurement of these systems for home-based chronic disease protocols.
- NFC:Near-field communication at 13.56 MHz supports short-range authentication and localized data retrieval.
- Ultrasound:Acoustic transmission through tissue enables battery-free operation with external transducer activation.
RFID maintains installed base leadership, though Bluetooth is expanding most quickly into consumer-accessible segments.
End User:
Site-of-care selection determines regulatory scrutiny intensity, reimbursement coding, and data governance architecture requirements.
- Hospitals:Inpatient departments require Class III device compliance, sterilization protocols, and bidirectional EHR integration for diagnostic imaging applications.
- Outpatient Clinics:Ambulatory surgical centers and specialty practices prioritize adherence verification for high-cost biologic therapies.
- Home Care:Post-acute and aging-in-place settings demand smartphone-integrated platforms with simplified user interfaces for patient self-management.
- Research Institutions:Academic medical centers and CROs utilize electronic pills for pharmacokinetic studies and decentralized clinical trial execution.
Hospitals command the largest procurement volume, while Home Care is gaining share fastest as remote monitoring reimbursement codes mature.
Use Case:
Clinical application selection determines sensor payload, transmission frequency, and evidence generation requirements for payer acceptance.
- Chronic Disease Management:Diabetes, cardiovascular, and autoimmune protocols utilize continuous biomarker tracking to adjust therapy dosing between clinic visits.
- Clinical Trials:Electronic pill platforms enable decentralized verification of investigational drug ingestion, reducing site visit burdens and improving protocol compliance data quality.
- Medication Adherence:Directly observed therapy replacement through ingestible sensors addresses tuberculosis, HIV, and transplant immunosuppression protocols.
- Remote Monitoring:Post-discharge surveillance of high-risk patients bridges acute and ambulatory care transitions.
Medication Adherence anchors current revenue, while Remote Monitoring is climbing the fastest as hospital-at-home programs expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows of electronic pill components concentrate in Germany and the United States, while import demand is climbing across East Asian hospital networks seeking remote monitoring infrastructure. Trade imbalances favor established manufacturing clusters with ISO 13485 certification and FDA-registered facilities.
United States
Integrated health networks in Texas and California drive procurement of Bluetooth-enabled adherence platforms for value-based care contracts. FDA breakthrough device designation accelerates commercialization timelines for connected drug delivery systems. The Minneapolis-St. Paul corridor anchors cardiovascular device financing partnerships that extend into electronic pill ecosystems.
Germany
Bundesland hospital systems expand remote patient monitoring programs using ingestible sensor platforms with EHR interoperability. EMA Medical Device Regulation imposes clinical evidence thresholds that favor established players with post-market surveillance capabilities. The Berlin-Brandenburg cluster concentrates notified body relationships and regulatory affairs scale for Class III device submissions.
China
Domestic manufacturers scale production of biosensor capsules for metabolic monitoring applications under NMPA innovation pathway programs. The country's national pharmaceutical regulator harmonizes technical documentation with international standards to accelerate market access. Shenzhen and Shanghai anchor manufacturing clusters for medical-grade polymer encapsulation and wireless transmitter modules.
Japan
PMDA consultation programs guide electronic pill developers through quality management system requirements for gastrointestinal diagnostic platforms. METI funding supports dual-mode capsule development bridging hospital infrastructure and smartphone integration. The Kansai region, centered on Osaka, concentrates endoscopy equipment supply chains and precision manufacturing capabilities.
Switzerland
Swissmedic parallel submission strategies circumvent single-jurisdiction regulatory bottlenecks for continuous glucose monitoring claims. The country's medical device sector leverages bilateral recognition agreements with EU and TGA frameworks. Basel and Zurich clusters specialize in biocompatible housing materials and cloud infrastructure for biomarker data governance.
Electronic Pill Market Vendor Landscape
On the supply side, the industry is consolidating around entities with demonstrated capital access and institutional backing, compressing the vendor landscape as procurement shifts from component supply to turnkey remote monitoring deployments. Strategic archetypes include diversified cardiovascular device conglomerates extending financing partnerships, dedicated capsule endoscopy specialists anchoring through manufacturing scale, and Asia-Pacific distributors controlling hospital network channels. Dominant competitive moves encompass strategic partnerships with health information exchanges and portfolio diversification into dual-frequency transceiver modules.
Within the diversified device tier, Medtronic exemplifies capital-access positioning through established cardiovascular financing infrastructure. CapsoVision, Inc. and Olympus Corporation occupy specialist and distribution-control archetypes respectively, with the former representing dedicated manufacturing scale in capsule platforms and the latter anchoring Asia-Pacific channel relationships. These three entities illustrate the tripartite competitive structure: financing-backed conglomerates, focused technology specialists, and geography-anchored distributors.
| Leading Market Players |
|---|
| Medtronic |
| Olympus Corporation |
| CapsoVision, Inc. |
| IntroMedic |
| Proteus Digital Health |
| JINSHAN Science & Technology |
| Check-Cap |
| BodyCap |
| Shenzhen Jifu Medical Technology |
| Others |
Supply Flow & Price Mechanics
The Shanghai-Rotterdam maritime corridor carries medical-grade polymer and ceramic encapsulation materials whose freight cost volatility feeds directly into unit economics for biocompatible housings, compressing margins for manufacturers lacking captive supply arrangements while enabling price differentiation between ISO 13485-certified tiers and uncertified alternatives.
Pricing Analysis
Hospital procurement committees anchor pricing structures around subscription-based remote monitoring platforms bundled with device supply, with FDA breakthrough designation and EMA MDR compliance status driving premium-mid-economy pricing differentiation across vendor tiers. Cost compression in standard-grade RFID-enabled systems is intensifying because German Bundesland health networks consolidate formulary approvals around integrated EHR-compatible platforms. Research institutions and outpatient clinics exhibit highest price sensitivity due to capital budget constraints, while integrated US health networks demonstrate lowest sensitivity where value-based care contracts tie reimbursement to verified compliance metrics.
Supply Chain Analysis
Extended payment terms from supply-chain finance facilities anchor working capital structures for medical-grade polymer suppliers serving encapsulation foundries in Germany, Switzerland, and the United States. Raw material dependencies center on biocompatible ceramics, CMOS imagers, and enzymatic transducers sourced from specialized chemical and semiconductor suppliers. Single-source vulnerability concentrates in notified body capacity for Class III device reviews under EMA MDR implementation. Distribution runs through hospital procurement committees and group purchasing organizations with integrated delivery networks in Texas and California commanding preferential allocation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward integrated delivery networks consolidating vendor relationships around turnkey remote monitoring platforms rather than component procurement, compressing the competitive field to entities with demonstrated capital access and health informatics partnerships.
For Market Incumbents: Harden cybersecurity architecture capabilities against emerging Bluetooth-enabled home care entrants by recruiting firmware engineers with body-area network encryption expertise currently concentrated in cardiovascular device firms. Deepen backward integration into biocompatible housing materials through partnerships with Basel and Zurich polymer specialists to defend margin position against raw material premium escalation. For New Entrants and Emerging Players: Build out smartphone-integrated adherence verification platforms targeting post-acute home care settings previously cost-prohibitive for RFID-dependent systems, exploiting reimbursement code maturation for remote patient monitoring. Prioritize direct-to-patient deployment models with simplified user interfaces, leveraging the fastest-expanding biosensor segment for continuous glucose validation to accelerate payer acceptance. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified cardiovascular device conglomerates seeking to monetize non-core electronic pill divisions lacking health informatics partnerships or captive cloud infrastructure. Long-term viability favors platforms with dual-frequency transceiver capabilities bridging hospital-grade and consumer-accessible categories. Monitor FDA breakthrough device designation velocity and EMA notified body capacity expansion as inflection indicators for commercialization timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Submission | Prioritized review queues compress commercialization timelines for connected drug delivery systems seeking US market access. |
| Hospital System Partnership | Integrated delivery networks in Texas and California mandate bidirectional EHR integration as formulary inclusion threshold. |
| Dual-Frequency Transceiver Development | Multi-protocol capsules collapse segmentation between acute diagnostic and chronic disease management applications. |
| Health Information Exchange Integration | Biomarker data governance partnerships reduce vendor lock-in risk from HIPAA-compliant cloud infrastructure concentration. |
| Reimbursement Strategy Alignment | Value-based care contracts tie procurement pull to verified medication compliance metrics in US integrated networks. |
Methodological Framework
A spread of perspectives from hospital procurement managers, biomedical engineers, regulatory affairs leads, and GPO contracts managers converged on the working assumptions underlying demand projections, validated against FDA filings, EMA submission databases, hospital procurement records, and CMS Medicare reimbursement data. Bottom-up estimates of electronic pill deployment volumes triangulated with top-down analysis of health network capital expenditure patterns across the analysis window.
Demand-supply balance framing anchored the analytical approach, with segmentation dimensions spanning product type, transmission technology, end-user site-of-care, and clinical application use case modeled throughout the forecast period. CAGRs derived from regression analysis of historical adoption curves adjusted for regulatory pathway acceleration effects and payer reimbursement code expansion timelines, incorporating continuous glucose monitoring validation progress and smartphone integration penetration rates as industry-specific inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by diversified cardiovascular device conglomerates into electronic pill ecosystems would shift outcomes through financing partnership extension. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Autosamplers Market
Medical Devices
US Intrauterine Devices Market
Medical Devices
Functional Electrical Stimulation Market
Medical Devices
Soft Tissue Market
Medical Devices
Global Prosthetic Heart Valve Market
Medical Devices
Disposable Contact Lenses Market
Medical Devices
South Korea Minimally Invasive Surgery Devices Market
Medical Devices
Global Breast Surgery Retractors Market
Medical Devices
Veterinary Arthroscopy Device Market
Medical Devices
Canada Insulin Delivery Devices Market
Medical Devices
Global Bowel Management System Market
Medical Devices
North America Organ-On-Chip Market
Medical Devices
Biological Microscope Market
Medical Devices
Global IVF Devices Market
Medical Devices
Direct-Skin Wearable Medical Devices Market
Medical Devices
Medical Devices Vigilance Market