
 Medical Penlights Market | 2026-2036
Medical Penlights Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Penlights Market Outlook
IEC 60601-1 medical electrical equipment certification is reorganizing competitive access for manufacturers serving clinical environments. HEINE Optotechnik GmbH And Co. KG leverages its German engineering heritage to sustain premium positioning in diagnostic illumination. Rudolf Riester GmbH anchors European hospital supply chains through specialized ophthalmic and general examination tools. American Diagnostic Corporation competes on value-engineered designs that navigate price-sensitive clinic procurement in North America.
Medical penlights are handheld, battery-powered diagnostic instruments engineered to produce controlled white light typically between 3,000 and 6,500 Kelvin color temperature for pupillary response assessment and oropharyngeal examination. LED penlights now dominate hospital purchasing due to superior lumen-per-watt efficiency and extended operational lifespan exceeding 10,000 hours. Home Care represents the fastest-growing end user segment as post-acute monitoring expands beyond institutional settings. Rechargeable penlights capture widening margin pools as lithium-ion cell costs decline and USB-C standardization reduces accessory complexity.
FDA device classification rules and EU MDR conformity requirements shape product labeling, biocompatibility testing, and post-market surveillance obligations for manufacturers distributing in the United States and European Economic Area. Japan's PMDA enforces additional electromagnetic compatibility standards that filter non-compliant imports from regional tender participation. Stakeholders must monitor evolving battery transport regulations and state-level e-waste directives that will determine future power source configurations and service model economics.
Market Dynamics
LED photonic efficiency gains and IEC 60601-1 electrical safety recertification mandates are forcing wholesale replacement cycles across hospital procurement departments, compressing supplier margins while elevating technical compliance barriers.
Growth Catalysts
- EU Battery Regulation:Restrictions on mercury and cadmium cell chemistries are accelerating lithium-ion rechargeable adoption, opening margin expansion for manufacturers with USB-C integration capabilities.
- Home Care:Post-acute monitoring expansion beyond institutional walls is creating pull-through demand for consumer-durable penlight designs with simplified operation protocols.
- LED lumen-per-watt efficiency:Solid-state illumination now exceeds 100 lumens per watt at medical-grade color temperatures, reducing thermal management costs and extending operational lifespan beyond legacy halogen alternatives.
Market Restraints
- Lithium cell cost volatility:Cathode material price swings and supply concentration in Chinese processing facilities compress rechargeable penlight margins unpredictably.
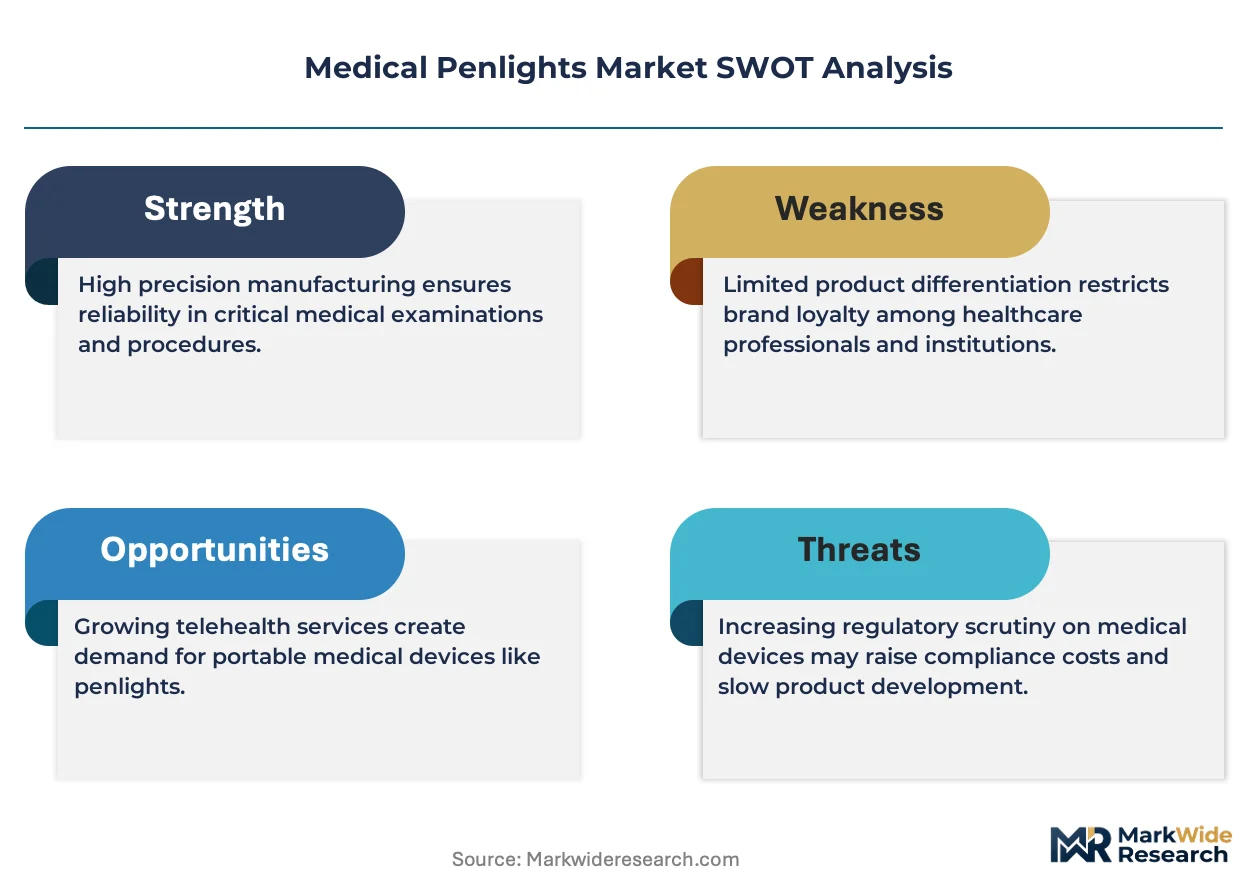
- Biocompatibility testing burden:EU MDR and FDA device classification rules impose extended validation timelines and documentation costs that filter smaller manufacturers from tender participation.
- Single-use disposables:Infection control protocols in acute care settings favor disposable illumination alternatives for high-risk examination scenarios, capping reusable penlight addressable volume.
Strategic Opportunities
- Germany:Hospital procurement rules mandating documented lumen output and color temperature specifications favor suppliers with metrology-certified production lines and quality management systems.
- Telehealth integration:Remote diagnostic platforms are creating demand for penlights with standardized illumination fields that enable consistent digital image capture for asynchronous clinical review.
- USB-C standardization:Universal charging infrastructure convergence allows manufacturers to eliminate proprietary dock ecosystems and reduce accessory SKU complexity.
Industry Challenges
- IEC 60601-1 third-edition compliance:Electrical safety testing for creepage distances and patient leakage currents extends product development cycles and requires capital investment in certified test facilities.
- Electromagnetic compatibility validation:Japan's PMDA enforces additional EMC standards that demand dedicated regional product variants, fragmenting production economics and inventory management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Penlights Market |
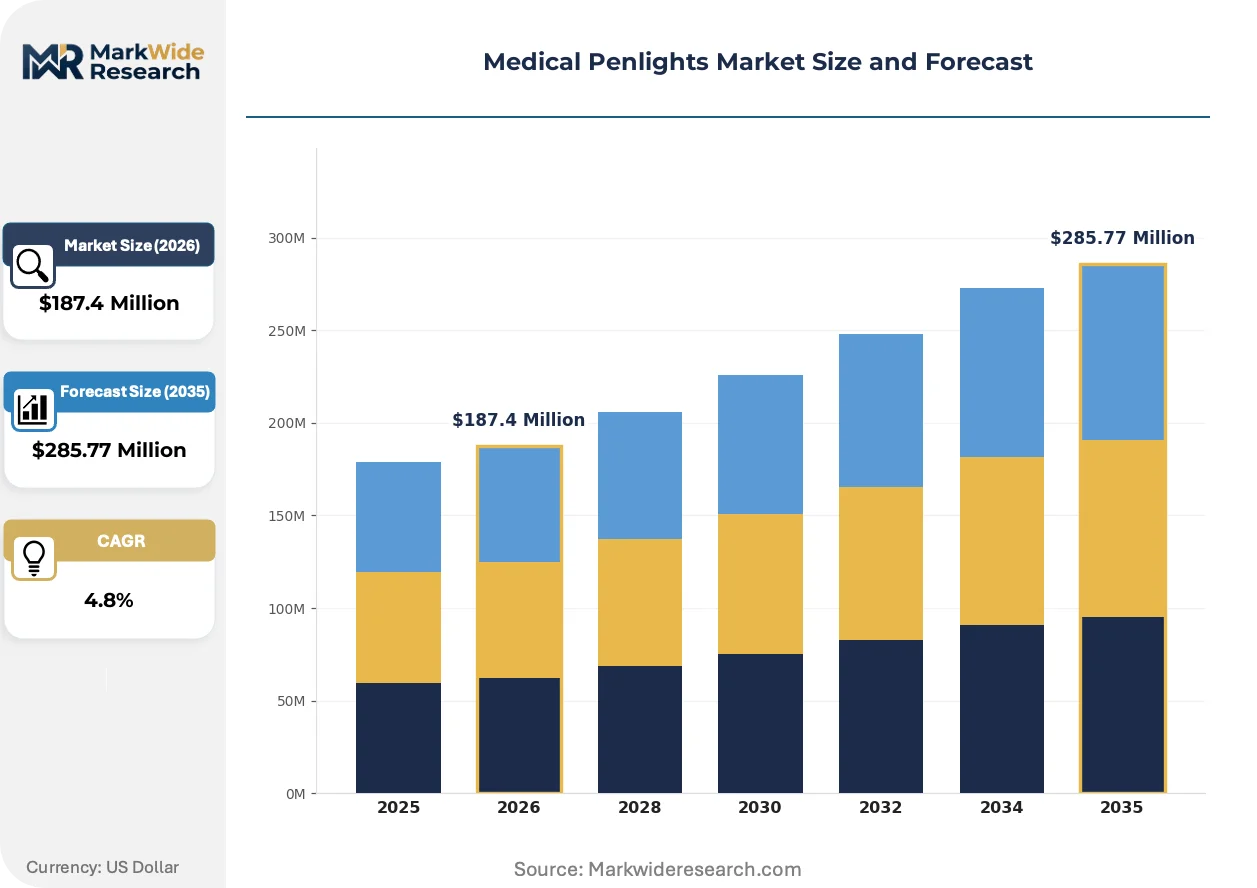
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED Penlights, Halogen Penlights, Disposable Penlights, Rechargeable Penlights End User: Hospitals, Clinics, Emergency Medical Services, Home Care Light Intensity: Standard Brightness, High Intensity, Adjustable Brightness, Dual Function Power Source: Battery Operated, Solar Powered, USB Rechargeable, Plug-in |
| Companies Covered | Rudolf Riester GmbH, GF Health Products, Inc., BV Medical, HEINE Optotechnik GmbH And Co. KG, Prestige Medical, Aspen Surgical Products, Inc., American Diagnostic Corporation, Welch Allyn Inc., Streamlight Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Penlights Market Strategic Shifts
Diagnostic illumination is converging with digital health infrastructure, forcing hardware manufacturers to embed connectivity and data capture capabilities into previously analog instruments.
Rechargeable lithium-ion penlight architectures are fragmenting the installed base between legacy disposable-battery designs and USB-C powered units. Hospital procurement departments in the United States are specifying rechargeable fleets for new equipment standards compliance. This bifurcation is compressing margins for manufacturers lacking both product variants while rewarding dual-capability suppliers with expanded tender eligibility.
EU MDR conformity requirements are reshaping product labeling obligations and post-market surveillance documentation for manufacturers distributing in the European Economic Area. Biocompatibility testing for patient-contact surfaces now extends to housing materials and switch mechanisms. German hospital supply chains are prioritizing suppliers with notified body certifications already in place, accelerating consolidation among prepared manufacturers.
Acute care buyers are unbundling after-sales service from hardware procurement, demanding discrete pricing for calibration, battery replacement, and warranty extension. Clinic networks in Japan are negotiating multi-year service contracts separate from capital equipment purchases. This disaggregation is forcing manufacturers to build service revenue capabilities or cede margin to third-party maintenance providers.
Medical Penlights Market Segmentation
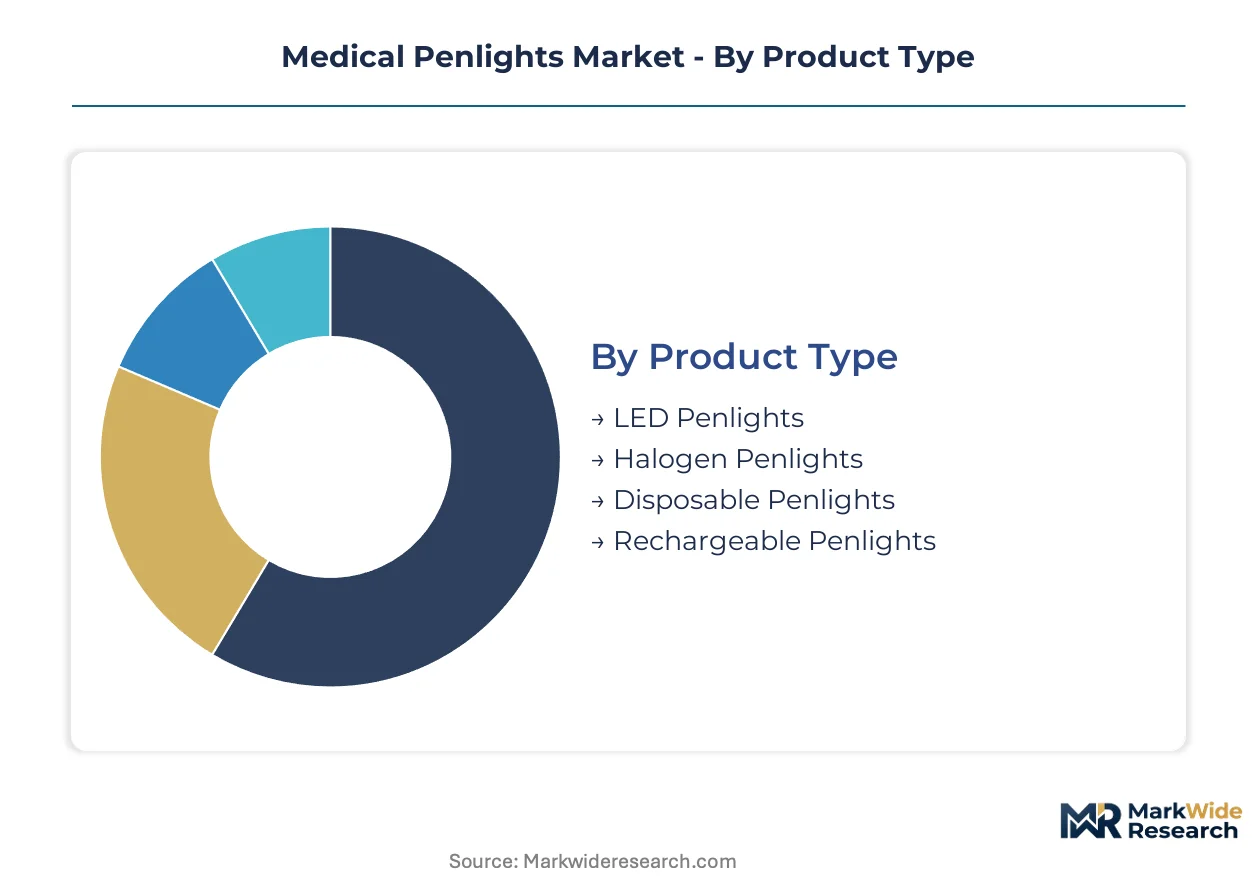
Segmentation in medical penlights reveals how procurement rules, clinical settings, and power infrastructure shape product configurations. Hospital buyers prioritize IEC 60601-1 certified units with documented photometric specifications, while home care channels favor simplified operation protocols. Understanding these divides clarifies where manufacturers must maintain dual capability versus single-segment specialization.
Product Type:
LED penlights dominate export flows to Germany and Japan where electrical safety certifications filter supplier bases, while halogen and disposable variants retain pockets of domestic demand in price-sensitive procurement environments.
- LED Penlights:Solid-state illumination delivering 3,000-6,500 Kelvin color temperature with lumen-per-watt efficiency exceeding 100. Demand concentrates in German hospital systems mandating documented photometric specifications under procurement rules favoring metrology-certified production lines.
- Rechargeable Penlights:Lithium-ion architectures with USB-C standardization reducing accessory SKU complexity. The steepest expansion runs through North American emergency medical services fleets replacing halogen inventories to meet updated equipment standards.
- Halogen Penlights:Legacy tungsten-filament designs with inferior thermal management and shorter operational lifespan. Retains residual demand in clinic networks with extended depreciation cycles and limited capital replacement budgets.
- Disposable Penlights:Single-use polymer housings with integrated alkaline cells. Addresses infection control protocols in acute care high-risk examination scenarios where reusable instrument sterilization protocols impose operational friction.
LED penlights command the established base. The steepest expansion runs through rechargeable architectures as lithium-ion cell costs decline and USB-C infrastructure converges.
End User:
Cost tier stratification separates capital-equipment procurement in institutional settings from consumer-durable specifications in post-acute monitoring channels.
- Hospitals:Centralized procurement departments specifying IEC 60601-1 certified fleets with documented lumen output and color temperature. German hospital supply chains prioritize suppliers with notified body certifications already in place under EU MDR conformity requirements.
- Home Care:Post-acute monitoring expansion beyond institutional walls creating pull-through demand for simplified operation protocols. Gaining share fastest as aging demographics and remote diagnostic platforms extend diagnostic illumination into residential settings.
- Clinics:Price-sensitive independent practices navigating value-engineered designs. American Diagnostic Corporation and similar suppliers compete on procurement cost minimization for outpatient examination workflows.
- Emergency Medical Services:Fleet replacement cycles driven by equipment standard updates across North American and European ambulance services. LED conversion mandates compressing legacy halogen inventory turnover.
Hospitals anchor volume concentration. Home Care climbs the fastest as telehealth integration and post-discharge monitoring protocols proliferate.
Light Intensity:
Application-specific requirements differentiate pupillary response assessment from oropharyngeal examination use cases, with adjustable architectures capturing margin expansion across mixed clinical workflows.
- Adjustable Brightness:Variable output control enabling transition between low-lumen pupillary assessment and high-lumen oropharyngeal visualization. Commanding premium positioning in ophthalmic and general examination tool portfolios from specialized European manufacturers.
- High Intensity:Fixed elevated output exceeding standard diagnostic thresholds for detailed tissue examination. Concentrating demand in surgical preparation and wound assessment protocols requiring shadow elimination.
- Standard Brightness:Fixed moderate output sufficient for routine pupillary response evaluation. Dominating high-volume clinic procurement where cost minimization supersedes feature differentiation.
- Dual Function:Integrated secondary capabilities such as tongue depressor attachment or pupil gauge markings. Addressing compact equipment requirements in field emergency medical services with limited storage capacity.
Standard Brightness retains volume leadership. Adjustable Brightness gains share fastest as multi-specialty clinics consolidate instrument procurement across divergent examination protocols.
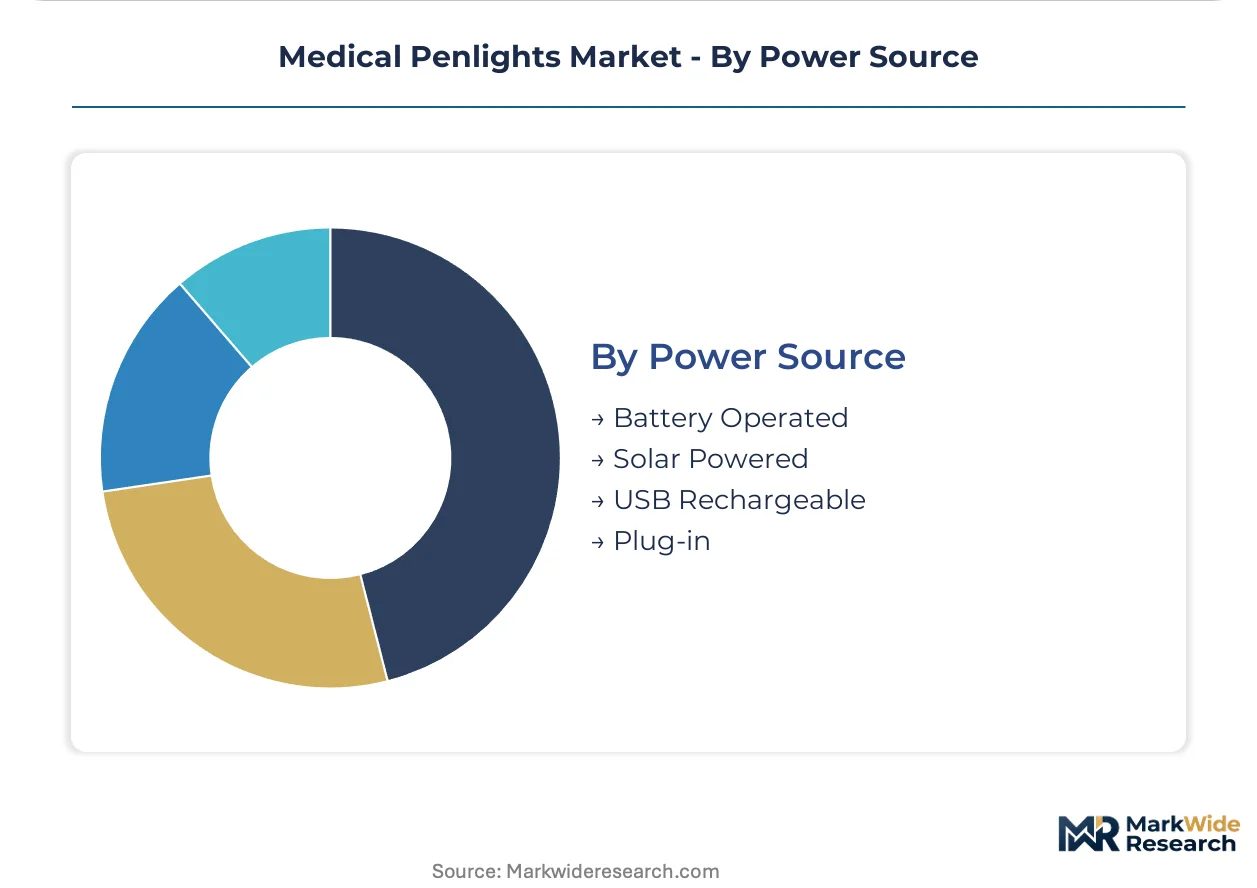
Power Source:
Supply concentration in Chinese lithium processing facilities and EU Battery Regulation chemistry restrictions are reorganizing power source economics across manufacturing footprints.
- USB Rechargeable:Lithium-ion cells with USB-C standardization eliminating proprietary dock ecosystems. Margin expansion opportunity as hospital procurement departments in the United States specify rechargeable fleets for new equipment standards compliance.
- Battery Operated:Disposable alkaline or lithium primary cells with universal availability. Retaining installed base in rural clinic networks and emergency medical services with unreliable electrical infrastructure.
- Solar Powered:Photovoltaic-integrated housings with limited commercial penetration. Addressing niche humanitarian and remote deployment scenarios where battery resupply logistics impose operational constraints.
- Plug-in:Tethered AC power eliminating battery dependency. Concentrating in fixed examination room installations with permanent diagnostic workstation configurations.
Battery Operated maintains the installed base. USB Rechargeable shows the steepest expansion trajectory as procurement standards shift toward sustainability metrics and total cost-of-ownership optimization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Battery Regulation chemistry restrictions and IEC 60601-1 electrical safety mandates are reorganizing procurement standards across hospital systems. Germany, the United States, and Japan concentrate demand where documented lumen output and color temperature specifications filter supplier bases.
United States
Emergency Medical Services fleets are replacing halogen inventories with LED units to meet updated equipment standards. FDA device classification rules shape product labeling and biocompatibility testing obligations. Hospital procurement departments in the Northeast and California are specifying rechargeable fleets for new equipment standards compliance.
Germany
Hospital procurement rules mandate documented lumen output and color temperature specifications favoring metrology-certified production lines. EU MDR conformity requirements reshape post-market surveillance documentation for manufacturers distributing in the European Economic Area. Bavaria and Baden-Württemberg anchor European hospital supply chains through specialized diagnostic instrument manufacturing.
Japan
PMDA enforces additional electromagnetic compatibility standards that filter non-compliant imports from regional tender participation. Aging demographics extend diagnostic illumination into residential settings. The Kanto region around Tokyo concentrates clinic networks negotiating multi-year service contracts separate from capital equipment purchases.
United Kingdom
Post-acute monitoring expansion beyond institutional walls creates pull-through demand for simplified operation protocols. NHS procurement frameworks prioritize suppliers with notified body certifications already in place. London and the Southeast concentrate telehealth integration platforms demanding penlights with standardized illumination fields for digital image capture.
India
Price-sensitive clinic procurement navigates value-engineered designs for outpatient examination workflows. CDSCO medical device regulations impose extended validation timelines filtering smaller manufacturers from tender participation. Maharashtra and Karnataka concentrate manufacturing operations serving domestic and export markets with cost-optimized product configurations.
Medical Penlights Market Competitive Environment
Listed leaders compete with private specialists across certification tiers and geographic footprints. The vendor base organizes around electrical safety compliance capabilities and notified body certification status. Three archetypes dominate: German engineering specialists with premium positioning, American value-engineered suppliers serving price-sensitive procurement, and diversified medical device conglomerates with integrated diagnostic portfolios. Competitive moves concentrate on M&A for certification acquisition and USB-C rechargeable portfolio diversification.
Among German-based precision manufacturers, HEINE Optotechnik GmbH And Co. KG and Rudolf Riester GmbH exemplify the engineering-specialist archetype anchored in metrology-certified production. American Diagnostic Corporation occupies a position within the value-engineered tier serving North American clinic procurement. These three represent the spectrum from premium diagnostic illumination to cost-optimized examination tools.
| Leading Market Players |
|---|
| Rudolf Riester GmbH |
| GF Health Products, Inc. |
| BV Medical |
| HEINE Optotechnik GmbH And Co. KG |
| Prestige Medical |
| Aspen Surgical Products, Inc. |
| American Diagnostic Corporation |
| Welch Allyn Inc. |
| Streamlight Inc. |
| Others |
Value Chain & Pricing Dynamics
IEC 60601-1 electrical safety certification gates both supplier qualification and price differentiation simultaneously, compressing margins for uncertified manufacturers while rewarding notified body-certified producers with premium positioning in German and Japanese hospital procurement channels.
Pricing Analysis
Certification level (IEC 60601-1/FDA/PMDA-grade) creates the primary spread between premium German-engineered units and value-engineered alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects after-sales service bundling and USB-C rechargeable capability. Pricing pressure stems from lithium cell cost volatility and biocompatibility testing documentation burdens. Clinic networks in North America exhibit highest price sensitivity, while Japanese hospital systems prioritize electromagnetic compatibility compliance over procurement cost minimization.
Supply Chain Analysis
Inbound logistics costs through Rotterdam and Hamburg port corridors influence landed cost structures for Asian-manufactured lithium-ion cells and LED emitter components. Manufacturing concentration in China, South Korea, and Germany feeds finished assembly operations. Raw material dependencies center on lithium carbonate cathodes, aluminum housings, and optical-grade polymers. Single-source vulnerability in Chinese lithium processing facilities poses structural risk. Distribution runs through specialized medical device distributors and hospital GPO contracts rather than direct OEM sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
USB-C charging infrastructure standardization is transforming medical penlights from isolated instruments into platform-compatible peripherals, creating ecosystem lock-in opportunities for manufacturers with interoperability-forward design strategies.
For Market Incumbents: Shield installed base revenue by accelerating IEC 60601-1 third-edition recertification across legacy product lines before EU MDR transition deadlines. Deepen backward integration into lithium cell supply through South Korean cathode partnerships to offset Chinese processing concentration. Prioritize notified body certification maintenance as the defensive moat against value-engineered entrants.
For New Entrants and Emerging Players: FDA 510(k) fast-track pathways for USB-rechargeable penlights with documented photometric specifications unlock white-space access in American clinic networks. Home Care post-acute monitoring channels offer lowest competitive density. Target telehealth platform partnerships as the primary go-to-market angle, embedding standardized illumination fields for asynchronous diagnostic image capture.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across rechargeable lithium-ion architectures as USB-C standardization eliminates proprietary dock ecosystem investments. Long-term viability favors manufacturers with dual disposable-rechargeable capability across the 5-10 year procurement standards transition. Acquisition target archetype: mid-tier European specialists with existing EU MDR notified body certifications. Signal to watch: Japanese PMDA electromagnetic compatibility waiver approvals for consolidated product variants.
| Strategic Initiative | Industry Significance |
|---|---|
| USB-C Rechargeable Portfolio Expansion | Eliminates proprietary dock SKUs and aligns with hospital sustainability procurement mandates. |
| IEC 60601-1 Third-Edition Recertification | Maintains tender eligibility in German hospital systems under updated electrical safety standards. |
| Telehealth Platform Integration Partnership | Captures Home Care growth through standardized illumination fields for remote diagnostic workflows. |
| EU MDR Notified Body Certification Acquisition | Accelerates market access consolidation via M&A for prepared manufacturers with existing documentation. |
| After-Sales Service Revenue Unbundling | Addresses Japanese clinic network demand for discrete calibration and warranty extension contracts. |
Study Parameters
A spread of perspectives from hospital purchasing committee members, biomedical engineering directors, emergency medical services fleet managers, and GPO contract specialists converged on the working assumptions. Primary interview intelligence combined with secondary validation from FDA 510(k) filings, EU MDR notified body certification databases, Japanese PMDA electromagnetic compatibility registrations, and hospital procurement contract repositories. Bottom-up unit demand modeling triangulated against top-down market size estimates across the analysis window.
Segmentation dimensions modeled include product type architecture, end user setting, power source configuration, and regional regulatory cluster. Analytical framework approach applied across the projection horizon without year-specific anchoring. CAGRs derived from weighted average of historical replacement cycle analysis and forward procurement standards adoption curves. Industry-specific forecast inputs incorporated lithium cell cost trajectories and USB-C infrastructure penetration rates.
The analysis sits within stated boundaries; outcomes outside sustained lithium-ion cost decline trajectories and stable IEC 60601-1 certification timelines would require recalibration. Forecasts reflect documented assumptions regarding EU Battery Regulation enforcement stringency and Japanese PMDA electromagnetic compatibility waiver availability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Homecare Surgical Drains Market
Surgical Instruments
Europe Minimally Invasive Surgery Market
Surgical Instruments
Germany General Surgical Devices Market
Surgical Instruments
Huber Needles Market
Surgical Instruments
Electrosurgery Market
Surgical Instruments
Disposable Laparoscopic Instruments Market
Surgical Instruments
Global Bipolar Electrosurgical Devices Market
Surgical Instruments
Handheld Arthroscopic Instruments Market
Surgical Instruments
Dental Surgical Microscopes Market
Surgical Instruments
Tonsil and Adenoid Removal Products Market
Surgical Instruments
Pneumoperitoneum Market
Surgical Instruments
Surgical Tubing Market
Surgical Instruments
Dermal Curettes Market
Surgical Instruments
Laparotomy Sponges Market
Surgical Instruments
Surgical Sutures Market
Surgical Instruments
Argentina General Surgical Devices Market