
 US Hemodialysis and Peritoneal Dialysis Market | 2026-2036
US Hemodialysis and Peritoneal Dialysis Market Size, Share, and Industry Trends Forecast 2026-2036
US Hemodialysis and Peritoneal Dialysis Market Intelligence
A nephrology nursing shortage is unwinding capacity expansion at freestanding dialysis centers nationwide. DaVita Inc. dominates clinic operations across Sun Belt states with captive patient intake networks. Fresenius Medical Care AG anchors vertical integration from dialyzer manufacturing to service delivery. Baxter specializes in peritoneal dialysis solutions for home settings.
Hemodialysis and peritoneal dialysis encompass extracorporeal and intracorporeal blood purification methods using semipermeable membranes, dialysate solutions, and controlled ultrafiltration to remove uremic toxins and excess fluid from patients with compromised renal function. Conventional dialysis equipment retains the largest installed base but automated peritoneal dialysis systems represent the fastest-growing technology segment as home therapy gains reimbursement traction. End-stage renal disease applications command the deepest margin pools due to recurring treatment frequency and Medicare entitlement coverage, while acute kidney injury applications serve as the entry point for hospital system vendor selection.
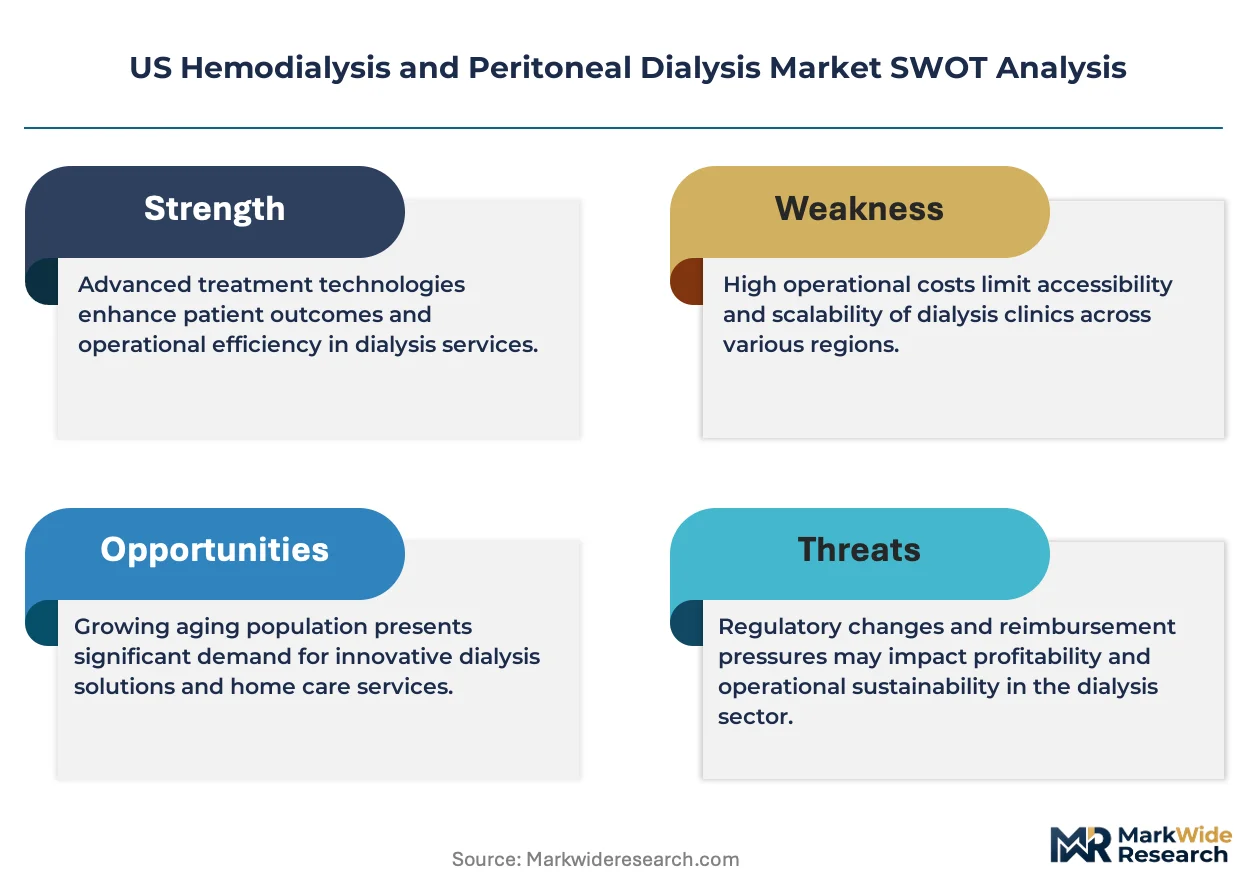
FDA device clearance requirements and CMS reimbursement coding under the ESRD Prospective Payment System shape product commercialization timelines and site-of-care economics for manufacturers and providers. State-level certificate-of-need regulations in New York and Illinois constrain new dialysis facility development, tightening incumbent positioning. Stakeholders must weigh home therapy infrastructure investments against in-center capacity constraints as workforce availability and site expansion rules diverge across state lines.
Market Dynamics
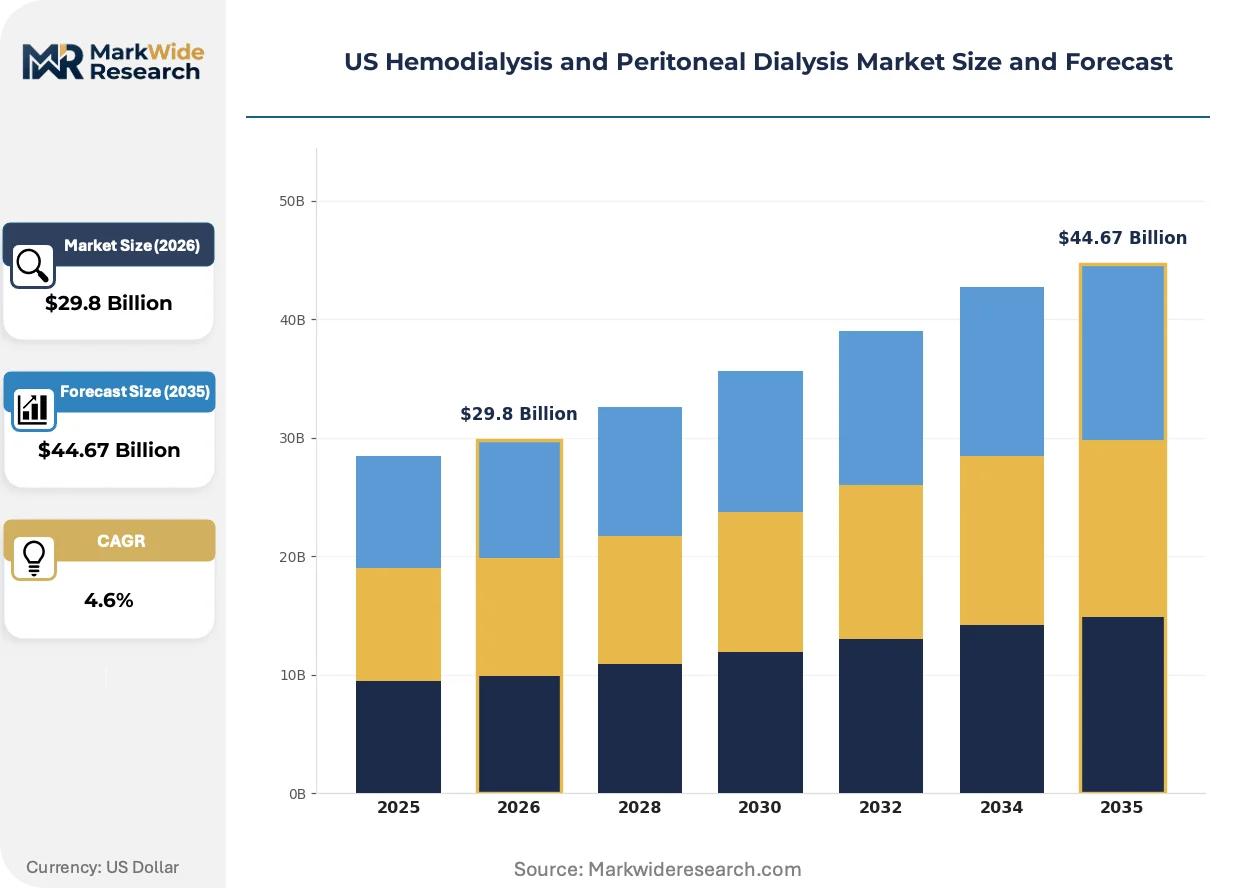
Medicare reimbursement incentives under the ESRD Prospective Payment System are accelerating site-of-care migration from freestanding clinics toward home-based modalities, forcing capital reallocation across provider networks and device manufacturers alike.
Growth Catalysts
- ESRD Prospective Payment System:CMS reimbursement bundles favor home dialysis modalities through payment differentials that reduce total cost of care. Medicare Advantage plans amplify this pull through supplemental benefit structures.
- Wearable artificial kidney platforms:FDA breakthrough device designation pathways compress premarket review timelines for portable hemodialysis systems. Renal replacement therapy candidates in rural geographies gain access flexibility.
- Automated peritoneal dialysis:Cloud-connected cycler systems enable remote monitoring by nephrology nurses. Texas and Florida Medicare beneficiaries show fastest uptake curves for nocturnal home therapy.
Market Restraints
- Certificate-of-need regimes:New York and Illinois CON regulations block de novo clinic development, entrenching DaVita and Fresenius positions in high-barrier markets. Competitors face multi-year approval horizons.
- Polysulfone membrane supply concentration:Three European chemical producers control dialyzer membrane substrate supply. Freight cost volatility and euro-denominated input pricing squeeze US converter margins.
- Biocompatibility limitations:Current synthetic membranes trigger complement activation in 15-20% of patients. Blood-membrane interaction research lags clinical demand for inflammation-neutral surfaces.
Strategic Opportunities
- Texas Rio Grande Valley:Underserved Hispanic ESRD populations along the border corridor lack bilingual dialysis infrastructure. Tele-nephrology paired with home PD deployment addresses access gaps.
- Acute kidney injury-to-chronic transition:Hospital-based continuous renal replacement therapy platforms create patient capture pipelines. Post-discharge home hemodialysis conversion rates remain suboptimal industry-wide.
- IRA Medicare drug pricing provisions:Oral phosphate binder cost controls free beneficiary disposable income for device upgrades. Supplemental home therapy equipment purchases accelerate among dual-eligible populations.
Industry Challenges
- Nephrology nursing scarcity:American Nephrology Nurses Association workforce surveys document 12% vacancy rates at freestanding centers. Training program throughput constrains home therapy training capacity expansion.
- Water treatment infrastructure:Home hemodialysis requires reverse osmosis installation and electrical upgrades. Medicare durable medical equipment contractors struggle with timely home modification coordination.
- FDA 510(k) predicate drift:Wearable kidney submissions lack established substantial equivalence pathways. Novel device categories trigger de novo classification reviews extending clearance timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Hemodialysis and Peritoneal Dialysis Market |
| Market Size in 2026 | $29.8 Billion |
| Market Size in 2035 | $44.67 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dialyzers, Dialysis Machines, Peritoneal Dialysis Solutions, Bloodlines End User: Hospitals, Freestanding Dialysis Centers, Home Patients, Clinics Technology: Conventional Dialysis, High-Flux Dialysis, Online Hemodiafiltration, Automated Peritoneal Dialysis Application: Chronic Kidney Disease, Acute Kidney Injury, End-Stage Renal Disease, Kidney Transplantation |
| Companies Covered | Fresenius Medical Care AG, Baxter, DaVita Inc., B. Braun Melsungen AG, Medtronic, Asahi Kasei Medical Co., Ltd., Nipro Corp., BD, Nikkiso Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Hemodialysis and Peritoneal Dialysis Market Strategic Shifts & Innovations
Device miniaturization and remote monitoring architectures are dismantling the historical link between dialysis delivery and fixed clinical infrastructure, enabling patient-managed therapy models that bypass traditional site-based care hierarchies.
Portable hemodialysis systems utilizing sorbent-based dialysate regeneration are fragmenting the conventional three-times-weekly in-center treatment paradigm. Medicare beneficiaries with transportation barriers adopt these platforms at rates exceeding younger commercial populations. The technology is fragmenting patient volume across home, travel, and intermittent clinic touchpoints rather than consolidating it.
FDA breakthrough device designation for wearable artificial kidneys is compressing premarket development timelines for novel renal replacement platforms. The agency's streamlined data requirements reduce pivotal trial burden for innovations addressing unmet home therapy needs. Fresenius and Baxter R&D pipelines prioritize sorbent cartridge and miniaturized pumping architectures to align with this regulatory pathway.
Home therapy training reimbursement unbundling is altering nephrology practice economics. CMS now separately pays for home hemodialysis and peritoneal dialysis patient education, shifting provider investment toward training infrastructure. California nephrology groups build dedicated home training suites to capture these incremental fee schedules.
US Hemodialysis and Peritoneal Dialysis Market Segmentation
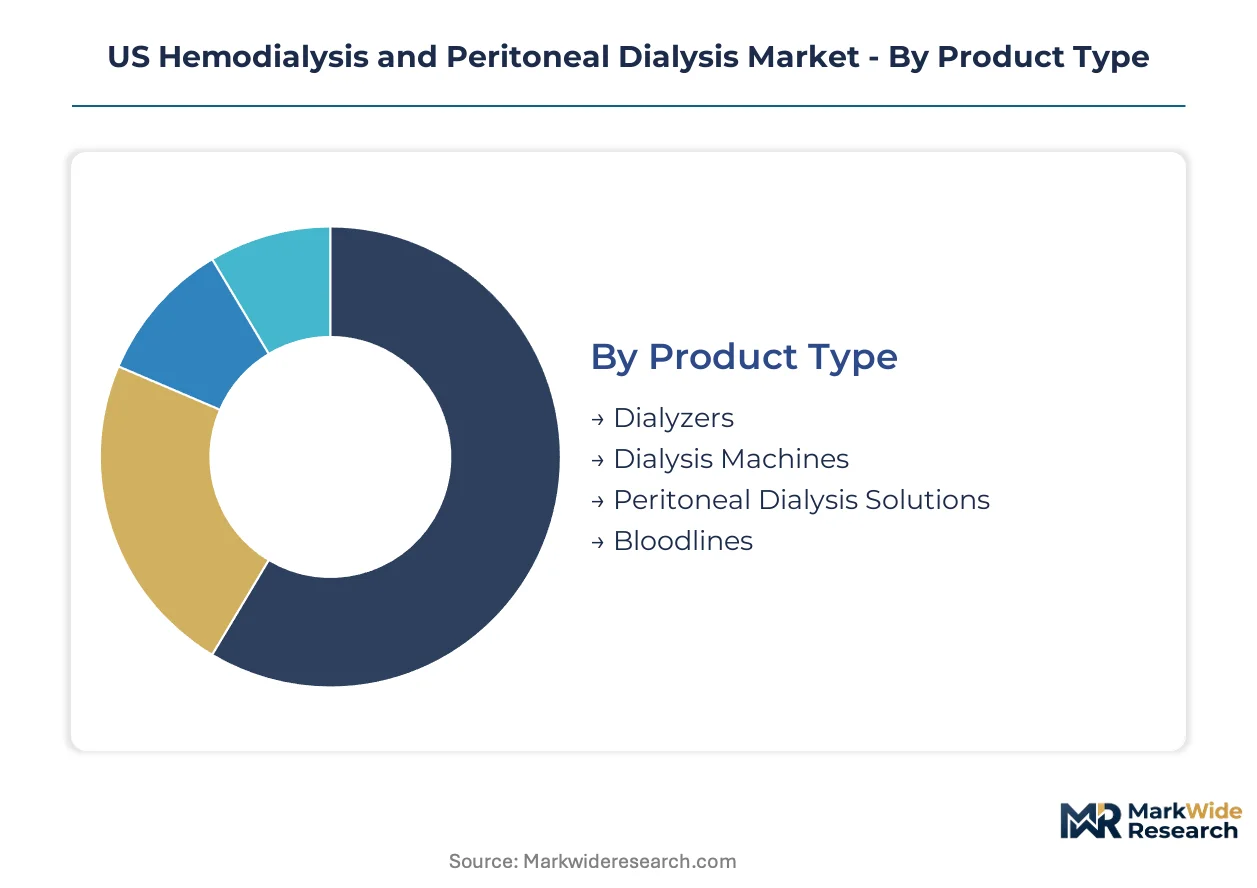
Segmentation reveals how reimbursement patterns and site-of-care economics split demand across modalities. Product and technology choices cascade through end-user settings and application types, determining margin structures and regulatory exposure for manufacturers.
Product Type:
Dialyzers and machines flow predominantly through domestic channels, while peritoneal solutions and bloodlines serve export-adjacent supply chains to Mexico and Canada.
- Dialyzers:Hollow-fiber polysulfone or polyethersulfone membranes filter uremic toxins during hemodialysis. Texas and California dialysis centers consume the highest unit volumes due to ESRD prevalence clustering along border corridors and urban corridors. FDA 510(k) clearance requirements govern membrane biocompatibility testing.
- Dialysis Machines:Console-based systems integrate blood pumps, heparin delivery, and ultrafiltration control for in-center use. Fresenius and DaVita procurement teams dominate capital equipment purchasing through multi-year service bundling. Medicare durable medical equipment contractors handle home unit distribution logistics.
- Peritoneal Dialysis Solutions:Sterile dextrose-based or icodextrin-based fluids enable intracorporeal toxin removal via peritoneal membrane exchange.
- Bloodlines:PVC tubing sets connect arterial and venous access to dialyzer circuits during treatment sessions.
Dialyzers command the established base. The steepest expansion runs through peritoneal dialysis solutions.
End User:
Cost tier differentiation separates high-acuity hospital settings from scaled freestanding operations and emerging home environments.
- Hospitals:Inpatient dialysis units manage acute kidney injury and ESRD complications requiring intensive monitoring. Urban medical centers in Florida and Illinois anchor demand for continuous renal replacement therapy platforms. CMS inpatient prospective payment system bundles constrain per-treatment reimbursement rates.
- Freestanding Dialysis Centers:Dedicated outpatient facilities deliver thrice-weekly hemodialysis under ESRD Prospective Payment System bundles. DaVita and Fresenius operate captive networks across Sun Belt states with concentrated Hispanic and elderly populations. Certificate-of-need regulations in New York limit new center development.
- Home Patients:Medicare beneficiaries perform self-administered peritoneal dialysis or home hemodialysis with remote nursing support.
- Clinics:Hospital-affiliated outpatient units serve as referral intermediaries between acute episodes and chronic management.
Freestanding dialysis centers command the established base. Home patients are expanding most quickly.
Technology:
Volume concentration favors legacy platforms, while application-specific demand pulls toward advanced filtration modalities.
- Conventional Dialysis:Standard low-flux membrane treatment removes small-molecular-weight uremic toxins through diffusive clearance. Rural dialysis centers in Texas and the Mountain West retain conventional systems due to capital replacement constraints. Equipment depreciation schedules stretch past typical technology obsolescence cycles.
- High-Flux Dialysis:Enhanced permeability membranes remove middle-molecular-weight toxins and beta-2 microglobulin more efficiently. California nephrology practices favor high-flux protocols for long-surviving ESRD populations with cardiovascular comorbidities. CMS reimbursement parity with conventional dialysis limits explicit premium capture.
- Online Hemodiafiltration:Combined diffusive and convective clearance uses sterile substitution fluid infusion during treatment.
- Automated Peritoneal Dialysis:Cloud-connected cycler systems deliver nocturnal therapy with remote monitoring capabilities.
Conventional dialysis commands the established base. Automated peritoneal dialysis shows the steepest expansion trajectory.
Application:
Customer type stratification separates recurring chronic populations from episodic acute cases and transitional transplant pathways.
- Chronic Kidney Disease:Pre-dialysis management encompasses anemia correction, phosphate binder therapy, and vascular access planning. Medicare Advantage plans in Florida invest in CKD stage 4-5 care coordination to delay ESRD transition. IRA drug pricing provisions reduce oral medication cost burdens for dual-eligible beneficiaries.
- Acute Kidney Injury:Hospital-acquired renal failure requiring temporary renal replacement therapy creates vendor selection entry points. Academic medical centers in California and New York pilot continuous renal replacement therapy platforms for ICU populations. Post-discharge conversion to home modalities remains suboptimal industry-wide.
- End-Stage Renal Disease:Irreversible kidney failure mandates permanent dialysis or transplantation.
- Kidney Transplantation:Pre- and post-transplant dialysis bridges patients through organ availability and graft recovery periods.
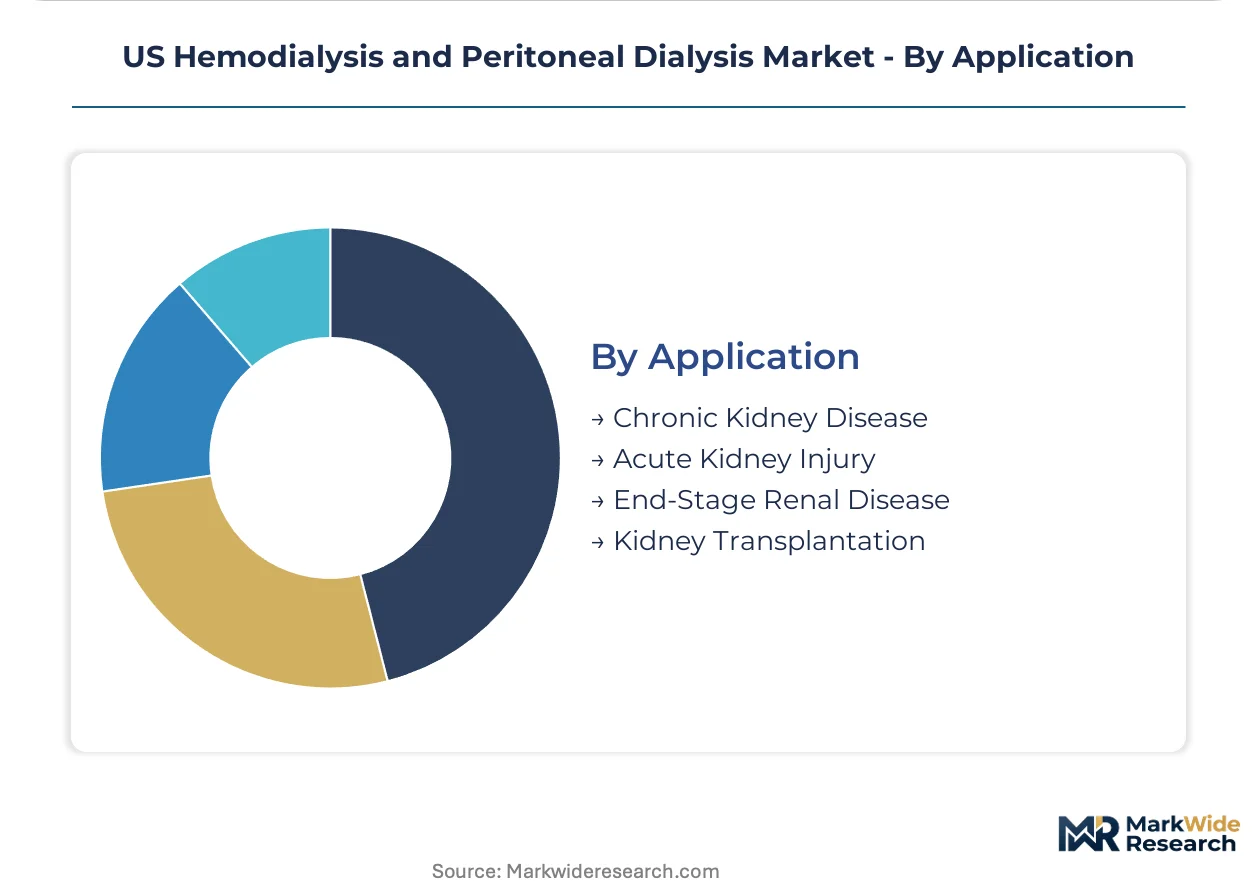
End-stage renal disease commands the established base. Acute kidney injury is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas and California consume dialysis services differently than Florida or Illinois, with border-state Hispanic populations driving peritoneal dialysis preference while certificate-of-need states constrain freestanding center expansion. Medicare Advantage penetration and home therapy reimbursement unbundling create divergent site-of-care economics across state lines.
Texas
The Rio Grande Valley anchors the nation's fastest home peritoneal dialysis adoption curve among Medicare beneficiaries. Texas lacks certificate-of-need restrictions, enabling rapid freestanding center development by integrated providers. DaVita operates dense clinic networks across Houston and Dallas-Fort Worth corridors with captive patient intake systems.
California
Nephrology groups in Los Angeles and San Francisco Bay Area build dedicated home training suites to capture CMS unbundled education payments. The state's Medicaid expansion and dual-eligible population concentration drive demand for bilingual dialysis infrastructure. High-flux dialysis protocols dominate long-surviving ESRD populations with cardiovascular comorbidities.
Florida
Medicare Advantage plans invest heavily in CKD stage 4-5 care coordination to delay ESRD transition among elderly retirees. Tampa and Miami medical centers pilot continuous renal replacement therapy platforms for ICU populations. The state's certificate-of-need regime blocks de novo clinic development, entrenching incumbent positioning.
Illinois
Chicago anchors hospital-affiliated outpatient units serving as referral intermediaries between acute episodes and chronic management. Illinois CON regulations limit new center development, tightening DaVita and Fresenius market positions. Academic medical centers in the metro area drive adoption of advanced filtration modalities.
New York
The state's stringent certificate-of-need regime creates multi-year approval horizons for competitors seeking market entry. New York City dialysis centers concentrate in hospital-affiliated settings rather than freestanding operations. Downstate Medicaid managed care plans experiment with home therapy incentive structures.
US Hemodialysis and Peritoneal Dialysis Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with vertical integration from membrane manufacturing to service delivery defining competitive positioning. The structure concentrates procurement power among three dominant provider networks while device manufacturers compete on FDA clearance timelines and sorbent technology portfolios. Strategic archetypes include integrated care delivery organizations, specialty device manufacturers, and home therapy solution providers. Competitive moves center on home therapy infrastructure investments and multi-year service bundling contracts with Medicare contractors.
Within the integrated care delivery tier, Fresenius Medical Care AG and DaVita Inc. exemplify vertical control from dialyzer production to clinic operations. Baxter occupies a specialist position in peritoneal dialysis solutions for home settings. These three anchors represent distinct strategic postures: German-based manufacturing integration, US-based clinic network density, and home therapy platform specialization respectively.
| Leading Market Players |
|---|
| Fresenius Medical Care AG |
| Baxter |
| DaVita Inc. |
| B. Braun Melsungen AG |
| Medtronic |
| Asahi Kasei Medical Co., Ltd. |
| Nipro Corp. |
| BD |
| Nikkiso Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Scale economies in dialyzer membrane manufacturing concentrate production among three European chemical producers, compressing margin capture for US converters while establishing price floors tied to euro-denominated substrate costs and freight volatility. This supply concentration cascades through procurement contracts for Fresenius and DaVita, locking in long-term offtake structures that resist spot-market disruption.
Pricing Analysis
Long-term offtake agreements dominate dialyzer and membrane procurement, with Fresenius leveraging captive manufacturing to insulate against spot-market volatility while DaVita negotiates multi-year service bundling for equipment leases. Price differentiation rests on FDA clearance tier and volume scale, with breakthrough-designation wearable devices commanding premium positioning against conventional 510(k) predicates. Cost compression in standard dialyzer lines intensifies as Medicare bundled payments tighten, while hospital systems show greatest price sensitivity compared to integrated provider networks with captive patient flows.
Supply Chain Analysis
Port congestion on trans-Atlantic lanes and container availability constraints elevate inbound logistics costs for polysulfone and polyethersulfone membrane substrates sourced from Germany, France, and Italy. Raw material dependencies center on specialty polymer resins, sterilization-grade packaging, and sorbent cartridge media, with single-source vulnerability concentrated in European chemical synthesis capacity. Distribution runs through Medicare durable medical equipment contractors for home units and direct hospital system procurement for acute platforms, creating divergent fulfillment economics across site-of-care tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US dialysis market rewards players who control scarce nephrology nursing capacity and FDA clearance velocity, with home therapy training infrastructure emerging as the critical bottleneck constraining modality expansion. Asset-light entrants face structural disadvantages against integrated operators with captive membrane supply and clinic networks.
For Market Incumbents: Consolidate home therapy training capacity through dedicated suite investments in Texas and California to capture unbundled CMS education payments. Deepen backward integration into sorbent cartridge production to align with wearable artificial kidney pipelines, defending against specialty device manufacturers exploiting FDA breakthrough pathways. For New Entrants and Emerging Players: Lead with tele-nephrology-enabled peritoneal dialysis deployment in the Rio Grande Valley, where bilingual infrastructure gaps and transportation barriers create accessible white space. Target acute kidney injury-to-chronic transition pipelines in Florida Medicare Advantage networks, converting hospital-based continuous renal replacement therapy exposures into home hemodialysis relationships through post-discharge training protocols. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among automated peritoneal dialysis platform providers with cloud-connected remote monitoring capabilities, offering visibility into patient adherence and reagent replenishment cycles. Long-term viability favors targets with FDA breakthrough device designations in portable hemodialysis, with sorbent technology advancement serving as the key inflection signal for platform scalability.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Submission | Compresses premarket review timelines for wearable kidney platforms addressing home therapy gaps. |
| Home Training Suite Expansion | Captures unbundled CMS reimbursement for patient education in high-adoption states. |
| Sorbent Cartridge Backward Integration | Secures supply control for portable hemodialysis systems amid European substrate concentration. |
| Medicare Advantage Partnership | Locks in CKD stage 4-5 care coordination contracts delaying ESRD transition costs. |
| Tele-Nephrology Platform Launch | Enables remote patient monitoring for nocturnal home therapy in underserved border corridors. |
Research Approach
Initial hypotheses were tested against primary input from nephrology nursing directors, biomedical equipment procurement managers, CMS reimbursement policy specialists, and dialysis clinic operations executives, then refined through secondary validation against FDA 510(k) and breakthrough device filing databases, CMS Medicare cost report extracts, and ESRD Prospective Payment System rulemaking records. Bottom-up patient volume modeling and top-down expenditure flow analysis were triangulated to reconcile modality-specific adoption curves with aggregate market sizing.
Variance decomposition across the projection horizon isolates drivers by product type, end-user setting, technology tier, and application severity, with segment-level CAGRs derived from elasticity-adjusted reimbursement scenario modeling. Forecast inputs incorporate Medicare Advantage penetration trajectories, CON regulation enforcement intensity by state, and wearable artificial kidney commercialization timelines under FDA streamlined review pathways.
Forecasts assume regulatory continuity in FDA device clearance frameworks and CMS ESRD Prospective Payment System structures; material policy shifts in home therapy reimbursement unbundling or breakthrough designation criteria would require re-modeling. Practitioners should keep alternative scenarios live as nursing workforce availability and state-level certificate-of-need enforcement evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nephrology
Global Nephroblastoma Treatment Market
Nephrology
Dialysis Centers Market
Nephrology
Renal Cell Carcinoma Market
Nephrology
Chronic Kidney Disease Market
Nephrology
Radiation Nephropathy Treatment and Management Market
Nephrology
Global Hepatorenal Syndrome Treatment Market
Nephrology
Aldosterone-Renin Screening Market
Nephrology
Hemodialyzer Market
Nephrology
US Dialysis Services Market
Nephrology
Global Renal Medical Devices and Services Market
Nephrology
Kidney Transplant Market
Nephrology
Glomerulonephritis Treatment Market
Nephrology
Late Stage Chronic Kidney Disease Therapeutics Market
Nephrology
End Stage Renal Disease Market
Nephrology
Hemodialysis and Peritoneal Dialysis Market
Nephrology
Hollow Fiber Dialyzers Market