
 Global Nephroblastoma Treatment Market | 2026-2036
Global Nephroblastoma Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Nephroblastoma Treatment Market Foresight
The gap between premium biologic regimens and commodity chemotherapy is expanding in nephroblastoma care. Merck & Co. Inc. leverages its immuno-oncology platform to differentiate in high-risk segments. Bristol Myers Squibb Company anchors its position through sustained R&D investment in pediatric indications. Bayer HealthCare LLC competes via geographic dominance in European reference centers.
Nephroblastoma treatment encompasses multimodal management of Wilms tumor, the most common renal malignancy in children, combining nephrectomy with adjuvant vincristine-dactinomycin chemotherapy and selective radiotherapy for favorable-histology cases. Surgery and chemotherapy occupy the core revenue pool due to their universal application across disease stages, while immunotherapy represents the fastest-growing segment as checkpoint inhibitors enter relapsed and refractory protocols. The age group segmentation tilts toward toddlers and children, who bear the highest incidence burden and require the most intensive surveillance protocols.
The FDA's pediatric investigational plan requirements and the EMA's Paediatric Regulation shape clinical trial design and market access timelines for new nephroblastoma therapies. The WHO's Essential Medicines List inclusion of vincristine and doxorubicin standardizes procurement in low-resource settings. Stakeholders must monitor biomarker-driven stratification trials that could redraw the boundary between standard-risk and high-risk treatment intensities.
Market Dynamics
The FDA's pediatric cancer drug priority review voucher program is compressing development timelines and redirecting R&D investment toward high-risk Wilms tumor subtypes, altering competitive positioning across the nephroblastoma treatment landscape.
Growth Catalysts
- Pediatric priority review vouchers:The FDA's incentive program accelerates regulatory approval for novel nephroblastoma therapies, attracting biopharma investment into previously deprioritized pediatric indications.
- Wilms tumor center concentration:Tertiary hospitals in the United States, Germany, and Japan consolidate expertise and drive adoption of multimodal treatment protocols.
- Biomarker stratification:Molecular profiling technologies enable refined risk classification, expanding addressable populations for targeted adjuvant therapies.
Market Restraints
- Vincristine supply volatility:Manufacturing concentration among limited sterile injectable suppliers creates vulnerability in first-line chemotherapy availability.
- Pediatric trial complexity:The FDA's pediatric investigational plan requirements impose extended timelines and higher capital requirements for protocol design.
- Radiotherapy capacity limits:Specialized pediatric radiation oncology infrastructure concentrates in urban academic centers, restricting geographic access.
Strategic Opportunities
- Relapsed-refractory protocols:Checkpoint inhibitor combinations represent underpenetrated therapeutic territory with limited established standards of care.
- EMA Paediatric Regulation alignment:Early integration of European development requirements enables streamlined dual-market authorization pathways.
- Low-resource procurement standardization:WHO Essential Medicines List inclusion of vincristine and doxorubicin creates institutional procurement frameworks in emerging markets.
Industry Challenges
- Pediatric oncology trial enrollment:Small incident populations across dispersed centers complicate patient accrual for randomized studies.
- Long-term survivorship infrastructure:Late-effect monitoring protocols require sustained coordination between primary oncology teams and adult transition services.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Nephroblastoma Treatment Market |
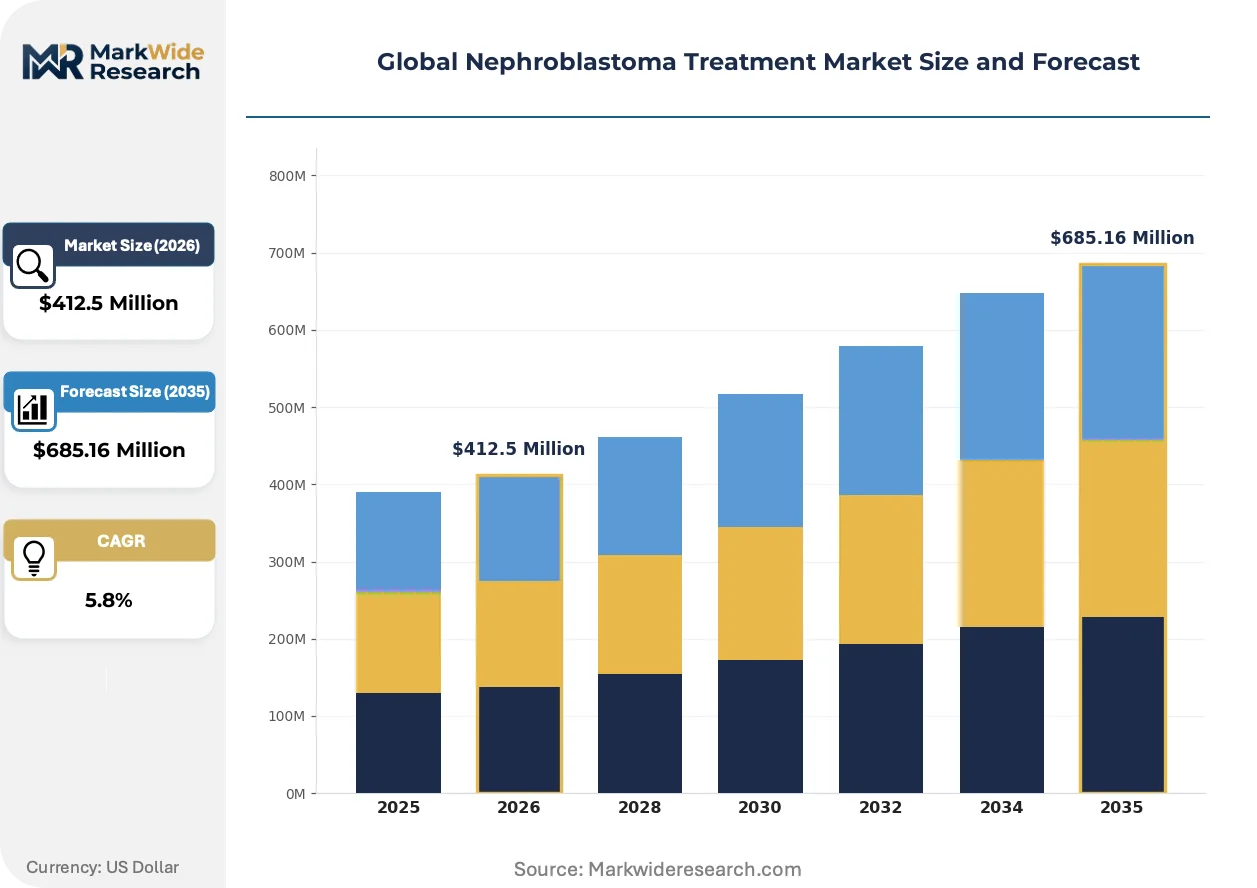
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $685.16 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: Surgery, Chemotherapy, Radiotherapy, Immunotherapy Age Group: Infants, Toddlers, Children, Adolescents Stage: Localized, Regional, Metastatic, Relapsed Care Setting: Hospitals, Specialized Clinics, Outpatient Facilities, Home Care |
| Companies Covered | Merck & Co. Inc., Bristol Myers Squibb Company, Bayer HealthCare LLC, Sun Pharmaceutical Industries Ltd., Teva Pharmaceutical Industries Ltd., F. Hoffmann-La Roche Ltd, Sanofi Pasteur Inc., Cipla Inc., Pfizer Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Nephroblastoma Treatment Market Shifts & Advancements
Biomarker-driven treatment stratification is fragmenting the historical risk-group boundaries that governed nephroblastoma protocol selection, while immunotherapy pipelines reshape competitive investment priorities.
Checkpoint inhibitors targeting PD-1 and CTLA-4 pathways are overtaking conventional cytotoxic salvage regimens in relapsed Wilms tumor management. Pediatric oncology consortia in North America and Europe are accelerating phase I/II enrollment for combination protocols. This displacement is compressing the revenue window for generic chemotherapy in high-risk segments.
The EMA's Paediatric Regulation mandates integrated development plans for all novel oncology assets, forcing sponsors to embed nephroblastoma cohorts earlier in clinical programs. This requirement has extended protocol design timelines but expanded the eligible therapeutic pipeline for pediatric renal malignancies. European reference centers are responding by consolidating multinational trial infrastructure.
Centralized procurement through national pediatric oncology networks is displacing hospital-level purchasing autonomy for chemotherapy agents. Group purchasing organizations in France and the United Kingdom are consolidating vincristine and dactinomycin contracts. This concentration is most visible in Western European markets where single-payer systems enable volume-based tender mechanisms.
Global Nephroblastoma Treatment Market Segmentation
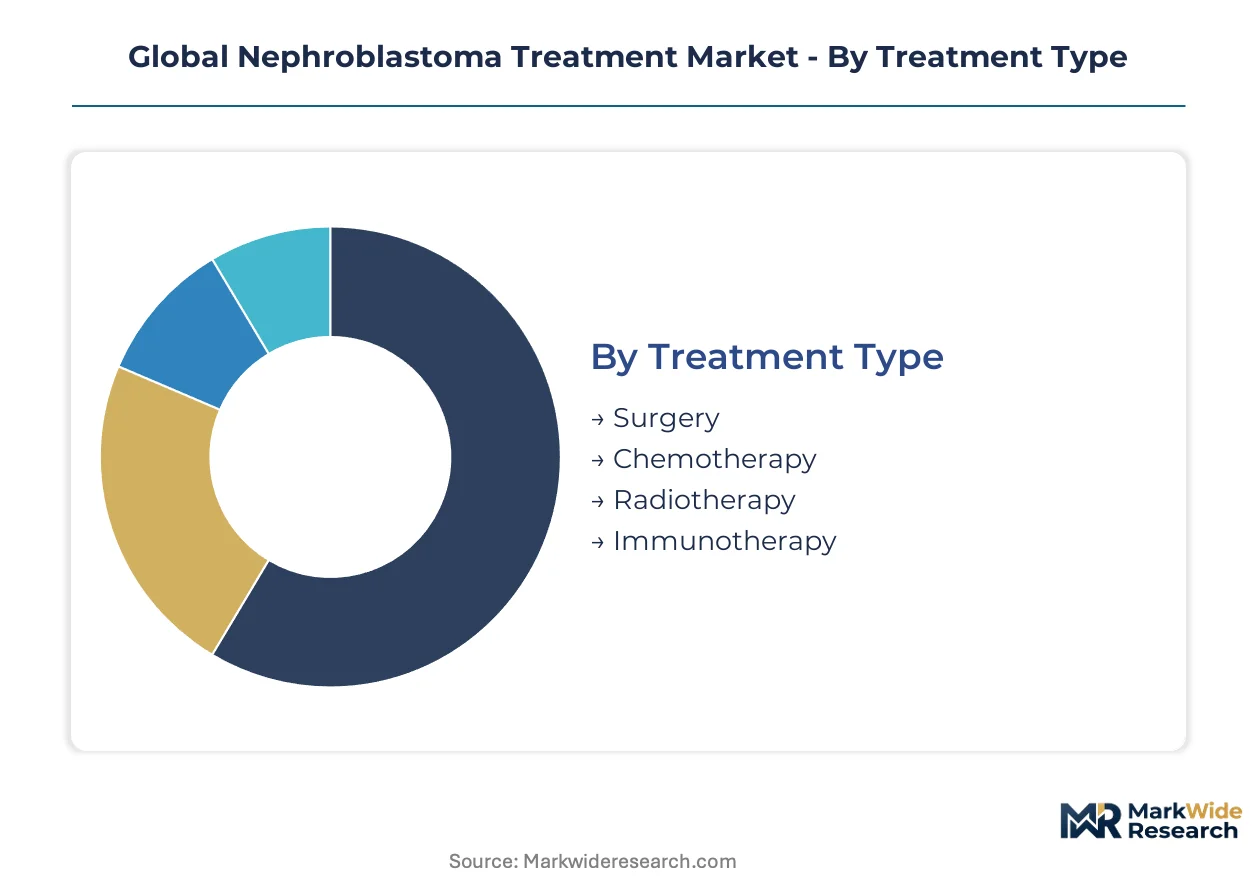
Segmentation in nephroblastoma treatment reveals how regulatory pathways and clinical infrastructure shape commercial opportunity across patient populations and care delivery models. Each dimension carries distinct certification requirements and reimbursement structures that determine market access feasibility.
Treatment Type:
Surgical resection and cytotoxic chemotherapy require FDA PMA or 510(k) clearance and EMA centralised procedure approval, while novel immunotherapies demand breakthrough therapy designation and paediatric investigation plans.
- Surgery:Nephrectomy procedures utilise open, laparoscopic, and robotic-assisted techniques with intraoperative staging requirements. Demand concentrates in tertiary pediatric surgical centers across the United States, Germany, and Japan where fellowship-trained urologic oncologists manage complex bilateral and recurrent cases. EMA's medical device regulation governs surgical instrumentation certification timelines.
- Chemotherapy:Vincristine-dactinomycin combinations form the backbone of favorable-histology protocols, with doxorubicin added for anaplastic variants. Procurement concentrates through national pediatric oncology networks in France and the United Kingdom, where group purchasing organisations consolidate volume-based contracts. FDA's sterile injectable manufacturing standards create supply vulnerability.
- Radiotherapy:External beam and proton therapy modalities target flank and whole-lung fields for high-risk and metastatic presentations. Specialized pediatric radiation oncology infrastructure limits geographic access to urban academic centers.
- Immunotherapy:Checkpoint inhibitors targeting PD-1 and CTLA-4 pathways enter relapsed-refractory protocols through priority review voucher acceleration.
Surgery sits at the top of the volume ranking, with immunotherapy climbing the fastest.
Age Group:
Developmental physiology and pharmacokinetic variability create distinct dosing and toxicity profiles across pediatric age strata, driving protocol-specific regulatory submissions.
- Infants:Patients under 12 months require modified chemotherapy dosing schedules and delayed radiotherapy protocols due to neurotoxicity sensitivity. Treatment concentrates in specialized congenital tumor programs at Children's Hospital of Philadelphia and Great Ormond Street Hospital, where neonatal anesthesia and nephron-sparing expertise coexist.
- Toddlers:The 1-3 year cohort bears peak incidence burden and drives surveillance protocol intensity. Wilms tumor centers in Tokyo and Munich prioritize this segment for biomarker stratification trials.
- Children:Standard-risk favorable-histology presentations dominate this 4-10 year category, with universal application of multimodal protocols.
- Adolescents:Older pediatric patients present with higher rates of anaplastic histology and require adult oncology transition coordination.
Toddlers command the largest addressable population, while infants show the steepest expansion trajectory for specialized protocol development.
Stage:
Risk stratification systems determine treatment intensity and directly influence the regulatory classification of adjuvant therapy trials.
- Localized:Stage I-II disease confined to the kidney permits nephrectomy with limited adjuvant chemotherapy. Enrollment concentrates in COG and SIOP consortium sites across North America and Western Europe, where upfront surgery versus preoperative chemotherapy debates continue.
- Regional:Stage III presentations with lymph node involvement or residual disease require intensified chemotherapy and flank radiotherapy. German reference centers excel in this segment through coordinated multidisciplinary tumor boards.
- Metastatic:Stage IV disease with pulmonary or hepatic spread demands whole-lung irradiation and platinum-based regimens. Japanese pediatric oncology networks report superior outcomes through proton therapy integration.
- Relapsed:Recurrent disease after initial therapy qualifies for salvage protocols and experimental immunotherapy access.
Localized disease generates the highest procedure volume, with relapsed cases gaining share fastest through checkpoint inhibitor pipeline expansion.
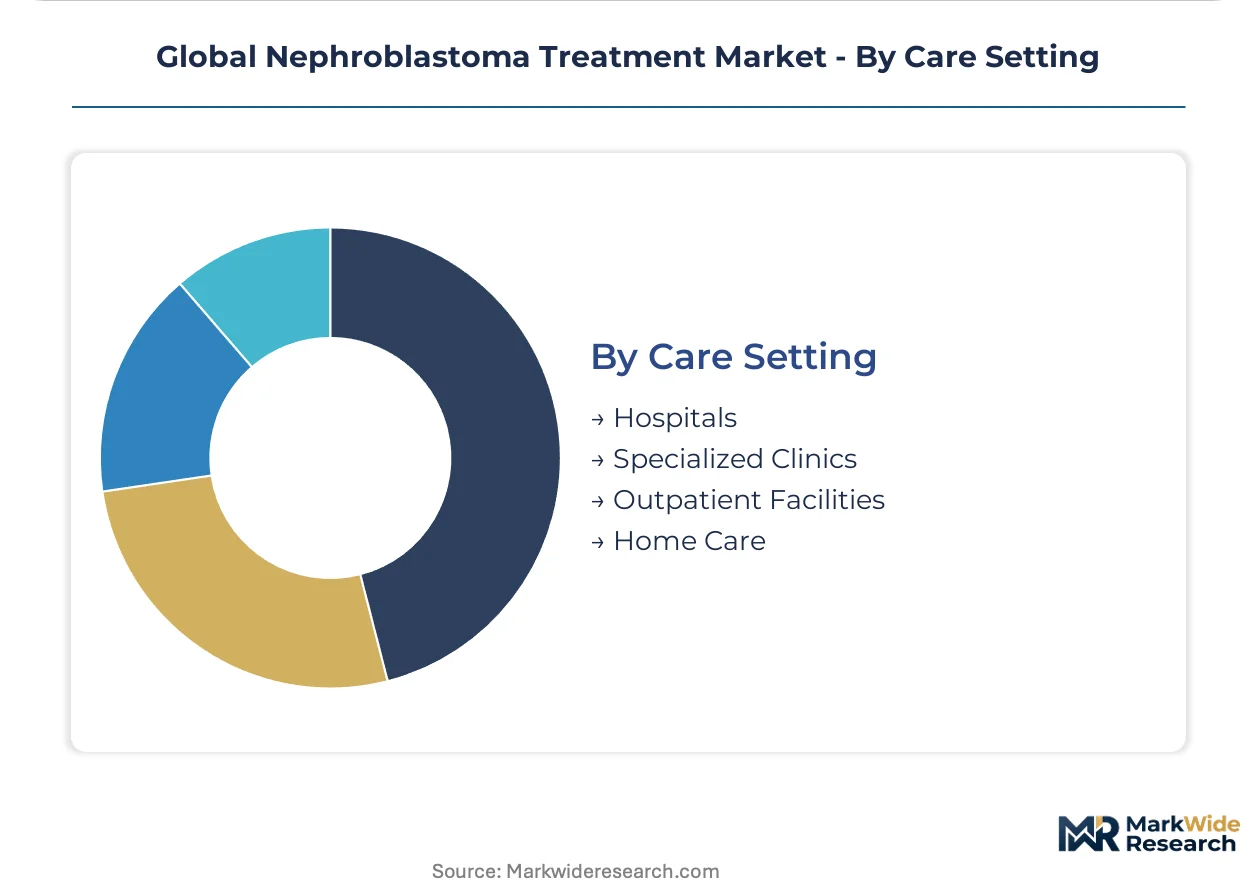
Care Setting:
Facility certification requirements vary by treatment modality, with radiation therapy mandating specialized pediatric accreditation unavailable in community settings.
- Hospitals:Tertiary pediatric oncology departments provide comprehensive multimodal care with embedded surgical, medical, and radiation oncology services. Concentration in academic medical centers across Boston, Heidelberg, and Osaka creates referral network dependencies.
- Specialized Clinics:Dedicated Wilms tumor centers offer consolidated expertise and trial access. French and Italian national health systems designate reference centers with exclusive pediatric radiation therapy authorization.
- Outpatient Facilities:Community infusion centers deliver maintenance chemotherapy cycles following hospital-based induction.
- Home Care:Oral supportive medications and central line maintenance shift to domestic settings for stable patients.
Hospitals retain the dominant share of acute interventions, though specialized clinics are expanding most quickly through European reference center consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates Wilms tumor expertise through reference center networks, while Japan advances proton therapy integration for metastatic cases. The United States anchors pediatric oncology consortium infrastructure. France and the United Kingdom consolidate procurement through national health systems.
United States
Pediatric oncology departments at Children's Hospital of Philadelphia and Boston Children's Hospital drive multimodal protocol adoption. The FDA's pediatric cancer drug priority review voucher program accelerates therapy development timelines. Tertiary centers across the Northeast and West Coast concentrate surgical and radiation oncology expertise.
Germany
Wilms tumor centers in Heidelberg and Munich coordinate multinational biomarker stratification trials. The EMA's Paediatric Regulation mandates integrated development plans for novel oncology assets. German reference centers excel in Stage III regional disease management through multidisciplinary tumor boards.
Japan
Pediatric oncology networks in Tokyo and Osaka report superior outcomes for metastatic presentations through proton therapy integration. The PMDA aligns with international pediatric trial standards while maintaining domestic regulatory requirements. Kanto and Kansai regions host specialized congenital tumor programs with neonatal anesthesia expertise.
France
National health system designation of reference centers with exclusive pediatric radiation therapy authorization consolidates care delivery. ANSM governs clinical trial authorization timelines for nephroblastoma protocols. Île-de-France and Provence-Alpes-Côte d'Azur regions concentrate specialized clinic infrastructure.
United Kingdom
Group purchasing organizations consolidate vincristine and dactinomycin contracts through volume-based tender mechanisms. The NHS England specialized commissioning framework governs access to proton therapy and experimental immunotherapy. London and Manchester pediatric oncology networks drive maintenance chemotherapy delivery through community infusion partnerships.
Global Nephroblastoma Treatment Market Competitive Landscape
Top-tier vendors anchor immuno-oncology development, while mid-tier generic manufacturers supply chemotherapy backbones. The market exhibits tiered concentration with premium biologic developers occupying high-risk segments and commodity sterile injectable producers serving first-line protocols. Strategic archetypes include checkpoint inhibitor specialists, cytotoxic chemotherapy suppliers, and pediatric-focused portfolio builders. Competitive moves center on priority review voucher acquisition and European reference center partnership formation.
Within the immuno-oncology tier, Merck & Co. Inc. and Bristol Myers Squibb Company exemplify platform-driven pediatric indication expansion. Among European-anchored diversified pharmas, Bayer HealthCare LLC occupies a position reflecting geographic concentration in reference center networks. These three entities represent distinct strategic postures: platform specialization, biologic premium positioning, and regional channel control.
| Leading Market Players |
|---|
| Merck & Co. Inc. |
| Bristol Myers Squibb Company |
| Bayer HealthCare LLC |
| Sun Pharmaceutical Industries Ltd. |
| Teva Pharmaceutical Industries Ltd. |
| F. Hoffmann-La Roche Ltd |
| Sanofi Pasteur Inc. |
| Cipla Inc. |
| Pfizer Inc. |
| Others |
Supply & Pricing Matrix
Sterile injectable manufacturing costs for vincristine and dactinomycin cascade through three pricing tiers, from commodity chemotherapy vials procured by national pediatric networks to premium checkpoint inhibitor regimens administered at tertiary centers in Boston, Heidelberg, and Tokyo.
Pricing Analysis
Capacity additions in India and China are reshaping price floors for generic chemotherapy backbones, intensifying cost compression in first-line protocols. Three-tier pricing structure across premium biologic, standard cytotoxic, and economy generic levels separates checkpoint inhibitor combinations from vincristine-dactinomycin regimens from volume-procured sterile injectables. Price differentiation hinges on FDA breakthrough therapy designation and EMA paediatric investigation plan certification. Pediatric oncology networks in France and the United Kingdom exhibit highest price sensitivity through centralized tender mechanisms, while Japanese proton therapy centers maintain lowest sensitivity due to outcome-based reimbursement.
Supply Chain Analysis
Returns and refurbishment flows for specialized pediatric radiation equipment create secondary market dynamics in European reference centers, extending asset lifecycles for linear accelerators and proton therapy systems. Manufacturing concentration rests on sterile injectable facilities in India, China, and the United States, with active pharmaceutical ingredient synthesis anchored in Italian and Swiss chemical parks. Supply chain vulnerability centers on single-source dependency for vincristine sterile fill-finish capacity. Distribution runs through national pediatric oncology group purchasing organizations in Western Europe and hospital-based procurement in Japanese metropolitan networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in nephroblastoma treatment derives from biomarker-driven stratification that shifts patient volumes toward premium immunotherapy tiers, while generic chemotherapy procurement standardization compresses input costs for first-line protocols.
For Market Incumbents: Hedge against checkpoint inhibitor pipeline saturation by securing priority review voucher positions for relapsed-refractory indications and deepening backward integration into sterile injectable manufacturing. Threats from biosimilar developers in European markets necessitate accelerated EMA paediatric investigation plan submissions. Channel control through exclusive partnerships with German and Japanese reference centers provides defensive moats. For New Entrants and Emerging Players: Begin with infant and adolescent age segments where modified dosing protocols and adult transition coordination create service differentiation opportunities. White-space exists in home care delivery models for maintenance chemotherapy in the United Kingdom and France. Go-to-market positioning through national health system procurement frameworks unlocks volume access faster than hospital-by-hospital contracting. For Investors and Strategic Acquirers: Consolidation pressure builds where pediatric oncology trial infrastructure concentrates in urban academic centers with embedded surgical, medical, and radiation oncology services. Long-term viability favors platform developers with cross-pediatric-indication immunotherapy assets over single-molecule chemotherapy suppliers. Signal to monitor: FDA pediatric cancer drug priority review voucher trading volume as indicator of strategic acquisition appetite.| Strategic Initiative | Industry Significance |
|---|---|
| Priority Review Voucher Acquisition | Accelerates regulatory timelines for relapsed-refractory checkpoint inhibitor protocols at FDA. |
| European Reference Center Partnership | Secures trial access and procurement preference through EMA Paediatric Regulation alignment. |
| Sterile Injectable Manufacturing Scale-Up | Reduces supply vulnerability for vincristine and dactinomycin in first-line chemotherapy. |
| Biomarker Stratification Trial Expansion | Captures patient volume shifts toward premium-tier targeted adjuvant therapies. |
| Proton Therapy Infrastructure Investment | Addresses radiotherapy capacity limits in Japanese and United States metropolitan markets. |
Research Methodology
Direct dialogue with pediatric oncologists, hospital procurement managers, regulatory affairs specialists at EMA and FDA, and formulary directors at national health systems combined with secondary validation against ClinicalTrials.gov records, FDA pediatric investigational plan filings, EMA submission databases, and WHO Essential Medicines List procurement reports. Bottom-up patient volume estimates by stage and age cohort triangulated against top-down therapy revenue projections across the analysis window.
Output metrics span treatment type, age group, disease stage, and care setting dimensions throughout the forecast period, with CAGRs derived from historical protocol adoption curves and pipeline progression timelines. Forecast inputs incorporate priority review voucher award velocity, biomarker stratification trial enrollment rates, and national pediatric oncology network procurement consolidation patterns.
Several conditions sit outside the modeled scope, including unforeseen manufacturing disruptions in sterile injectable supply, radical shifts in upfront surgery versus preoperative chemotherapy protocols, and novel immunotherapy safety signals that could halt checkpoint inhibitor expansion. Practitioners should monitor FDA pediatric cancer drug priority review voucher program modifications, EMA Paediatric Regulation enforcement patterns, and vincristine supply chain disruption indicators for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nephrology
ICU-Acquired Acute Kidney Treatment Market
Nephrology
Hemodialysis Services Market
Nephrology
US Dialysis Centers Market
Nephrology
Peritoneal Dialysis Market
Nephrology
Global Acute Kidney Injury Treatment Market
Nephrology
Global Diabetic Nephropathy Market
Nephrology
Membranous Nephropathy Treatment Market
Nephrology
US Dialysis Services Market
Nephrology
Kidney/Renal Function Test Market
Nephrology
Ketoanalogue for Kidney Disease Market
Nephrology
Late Stage Chronic Kidney Disease Therapeutics Market
Nephrology
Dialysis Centers Market
Nephrology
Kidney Fibrosis Treatment Market
Nephrology
Drug-Induced Nephrotoxicity Treatment Market
Nephrology
Blood Dialyzer Market
Nephrology
Kidney Transplant Market