
 US Dialysis Services Market | 2026-2036
US Dialysis Services Market Size, Share, and Industry Trends Forecast 2026-2036
US Dialysis Services Market Intelligence
Consolidation among Medicare Advantage plans is repositioning purchasing power toward value-based contracts. Fresenius Medical Care AG & Co. KGaA leverages its vertically integrated supply chain to control costs across clinic networks. DaVita Inc. anchors its position through chronic disease management partnerships with large payers. U.S. Renal Care Inc. competes on operational efficiency in secondary markets.
Dialysis services encompass extracorporeal blood purification and peritoneal fluid exchange procedures that substitute for failed renal function, typically requiring three weekly sessions lasting three to five hours each with prescribed ultrafiltration rates. In-center hemodialysis dominates service type revenue but carries higher fixed-cost burdens, while home hemodialysis and peritoneal dialysis segments attract margin expansion as remote patient monitoring reduces staffing intensity. Ambulatory surgical centers and home care providers represent the fastest-growing end-user channels as reimbursement shifts away from hospital-affiliated facilities toward independent and physician-owned operators.
FDA regulates dialysis device safety and efficacy under 510(k) and PMA pathways, while CMS payment rules through the ESRD Prospective Payment System directly shape clinic profitability and technology adoption timelines. State-level certificate-of-need laws in New York, Illinois, and Ohio restrict facility expansion, creating localized supply constraints that benefit incumbent operators. Stakeholders must monitor CMS innovation center demonstrations for home dialysis incentives that could redistribute volumes across facility ownership models.
Market Dynamics
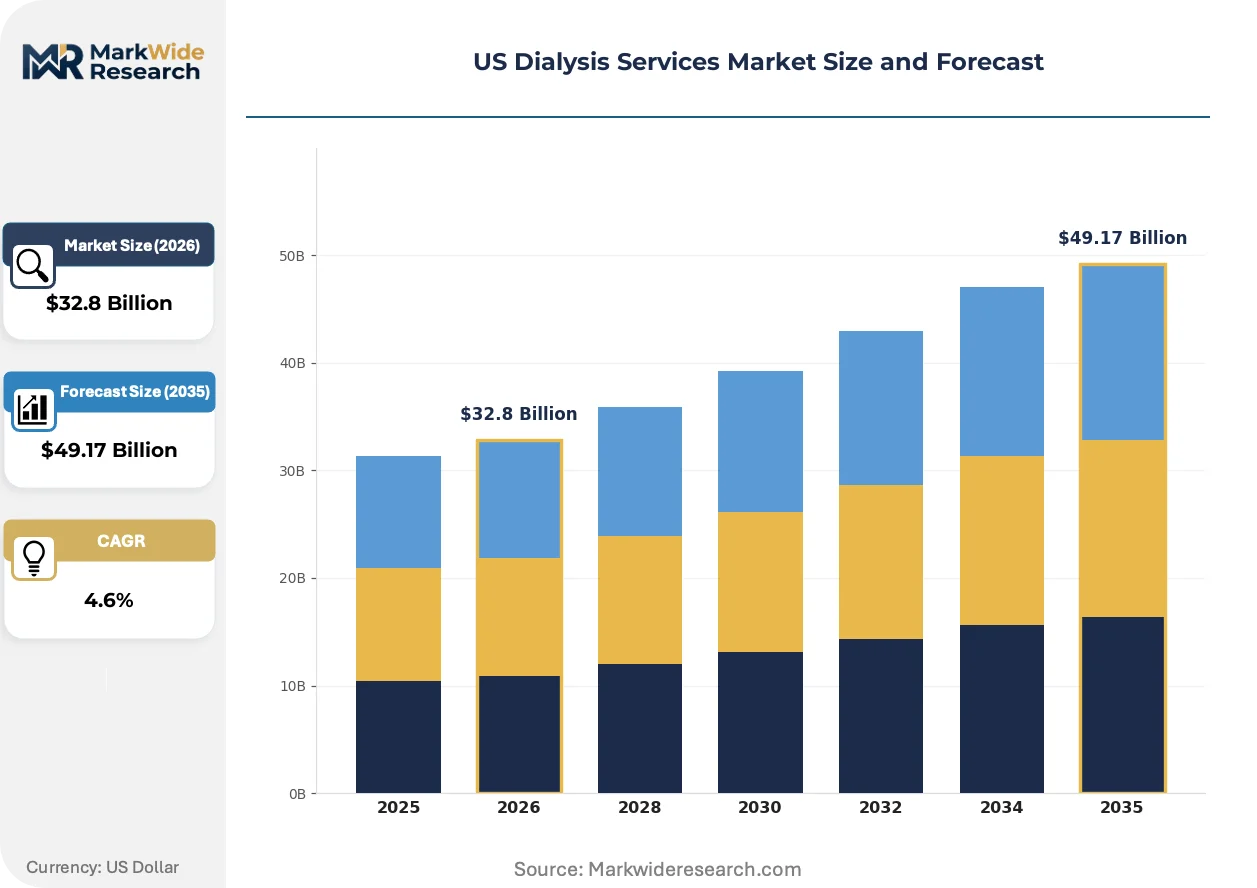
CMS reimbursement redesign through the ESRD Prospective Payment System is accelerating facility consolidation while remote patient monitoring technologies redraw staffing economics across clinic networks.
Growth Catalysts
- Medicare Advantage Penetration:Value-based contracting incentives from CMS are pulling dialysis providers toward risk-sharing arrangements with consolidated payers.
- Remote Monitoring Technology:Telehealth-enabled home dialysis platforms reduce per-patient labor hours while expanding treatable geography.
- Texas-Florida-California Cluster:Aging demographics and diabetes prevalence in these three states concentrate incident ESRD cases and justify facility expansion.
Market Restraints
- Certificate-of-Need Laws:New York, Illinois, and Ohio restrict new facility licensing, protecting incumbents but capping supply response.
- Single-Source Device Dependency:Concentrated supply of dialyzers and water purification systems exposes clinics to price volatility.
- Biocompatible Membrane Limitations:Current synthetic membranes trigger inflammatory responses that constrain treatment frequency and duration.
Strategic Opportunities
- Rural Underservice:Secondary markets in the Mountain West and Deep South lack adequate clinic density for growing ESRD populations.
- Peritoneal Dialysis Expansion:CMS innovation center demonstrations incentivize home-based modalities through bundled payment adjustments.
- AI-Enabled Predictive Analytics:Machine learning integration with remote monitoring platforms enables early intervention and hospitalization reduction.
Industry Challenges
- Nephrology Workforce Constraints:Fellowship-trained specialists cluster in urban academic centers, leaving community clinics understaffed.
- Interoperability Friction:EHR systems from hospital affiliates resist data exchange with independent dialysis operators, complicating care coordination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Dialysis Services Market |
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $49.17 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: In-Center Hemodialysis, Home Hemodialysis, Peritoneal Dialysis, Nocturnal Dialysis End User: Dialysis Centers, Ambulatory Surgical Centers, Home Care Providers, Rehabilitation Facilities Payment Model: Medicare Reimbursement, Private Insurance, Medicaid Financing, Self-Pay Facility Ownership: Hospital-Affiliated, Independent Providers, Physician-Owned, Nonprofit Organizations |
| Companies Covered | Fresenius Medical Care AG & Co. KGaA, DaVita Inc., U.S. Renal Care Inc., Dialysis Clinic, Inc., Satellite Healthcare, Northwest Kidney Centers, Centers for Dialysis Care, Innovative Renal Care, American Renal Associates, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Dialysis Services Market Strategic Shifts & Innovations
Digital health infrastructure and payment model experimentation are compressing the traditional boundary between institutional and home-based renal replacement therapy.
Portable hemodialysis systems with reduced water and power requirements are consolidating treatment location flexibility. Medicare beneficiaries in rural counties are adopting these devices faster than projected, compressing the historical dominance of fixed-site clinics and enabling same-day training discharge protocols.
FDA 510(k) clearance pathways for software-as-medical-device applications are accelerating algorithm-based dialysis prescription tools. CMS parallel coverage determinations for connected monitoring devices are reshaping capital allocation, with nephrology practices in the Southeast prioritizing remote infrastructure over physical expansion.
Patient self-management training protocols are displacing nurse-dependent education models. Home dialysis candidates in California and Florida now complete competency certification through virtual reality modules, reducing initial training from weeks to days while CMS tracks outcomes for payment adjustment eligibility.
US Dialysis Services Market Segmentation
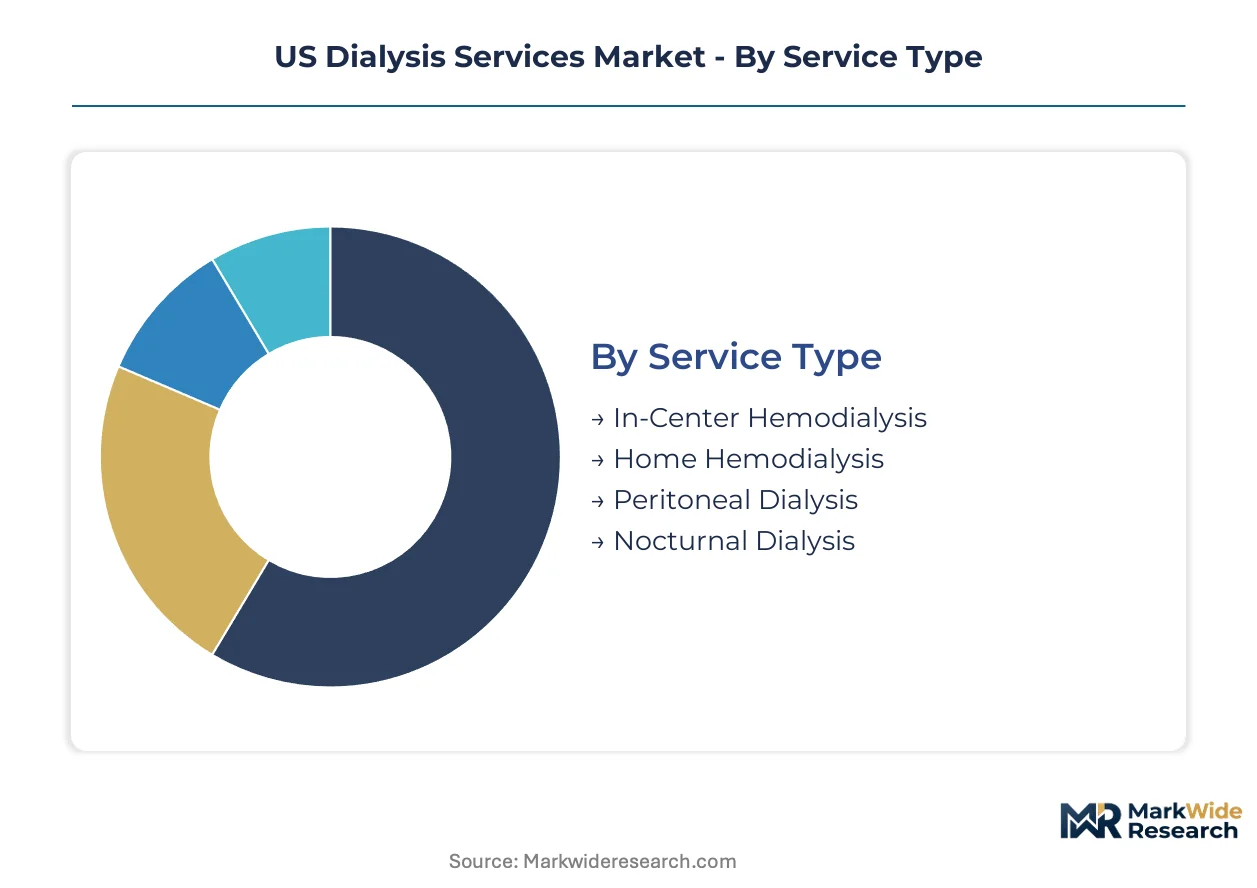
Service configuration and site-of-care decisions in US dialysis services are increasingly driven by reimbursement design and remote monitoring capabilities rather than clinical preference alone. Segment boundaries are blurring as CMS bundled payments incentivize modality shifts and ownership consolidation.
Service Type:
Technology refresh cycles and patient acuity thresholds determine where each modality captures volume across Medicare and commercial populations.
- In-Center Hemodialysis:Three-times-weekly sessions in fixed-site clinics with prescribed ultrafiltration rates and on-site nursing supervision. Texas, Florida, and California concentrate the highest patient volumes due to aging demographics and diabetes prevalence, though fixed-cost burdens compress margins relative to home alternatives.
- Home Hemodialysis:Portable systems with reduced water and power requirements enable patient-managed sessions with remote clinician oversight. Medicare beneficiaries in rural counties are adopting these devices faster than projected, compressing the historical dominance of fixed-site clinics and enabling same-day training discharge protocols.
- Peritoneal Dialysis:Peritoneal fluid exchange procedures performed daily by patients or caregivers without vascular access requirements. CMS innovation center demonstrations incentivize this modality through bundled payment adjustments.
- Nocturnal Dialysis:Extended-duration sessions administered overnight in-center or at home with slower ultrafiltration rates. Sleep-compatible protocols appeal to employed patients seeking daytime preservation.
In-Center Hemodialysis sits at the top of the volume ranking, with Home Hemodialysis climbing the fastest.
End User:
Capital intensity and staffing ratios separate channels with favorable reimbursement from those operating on thinner margin structures.
- Dialysis Centers:Dedicated renal replacement facilities with dialysis stations, water purification systems, and nephrology supervision. Hospital-affiliated centers in urban corridors retain referral leverage, though independent operators gain share through Medicare Advantage contracting.
- Ambulatory Surgical Centers:Same-day procedure sites with lower overhead than hospital outpatient departments. CMS site-neutral payment policies are redirecting vascular access procedures toward these lower-cost settings.
- Home Care Providers:Agencies delivering equipment, supplies, and nursing visits to residential settings. Remote patient monitoring partnerships with nephrology practices are reshaping capital allocation in the Southeast.
- Rehabilitation Facilities:Skilled nursing and inpatient rehab units managing dialysis for post-acute patients. Transitional care episodes concentrate in states with certificate-of-need restrictions on standalone clinic expansion.
Dialysis Centers capture the dominant revenue share, though Ambulatory Surgical Centers are expanding most quickly as site-neutral payments take hold.
Payment Model:
Payer mix directly dictates technology adoption timelines and site-of-care flexibility across provider networks.
- Medicare Reimbursement:ESRD Prospective Payment System bundles dialysis sessions, drugs, and laboratory services into fixed rates. CMS remote monitoring add-on codes are accelerating home modality uptake among beneficiaries.
- Private Insurance:Commercial plans with negotiated per-treatment rates and carve-outs for innovative therapies. Consolidated Medicare Advantage plans are repositioning purchasing power toward value-based contracts with risk-sharing provisions.
- Medicaid Financing:State-administered coverage for low-income and disabled populations with variable supplemental payments. Eligibility expansion in non-expansion states creates coverage gaps that strain safety-net providers.
- Self-Pay:Direct patient responsibility for uninsured or out-of-network services. High-deductible plan designs are pushing more commercially insured patients into this category for initial sessions.
Medicare Reimbursement anchors the payment landscape, with Private Insurance gaining share fastest as Medicare Advantage penetration deepens.
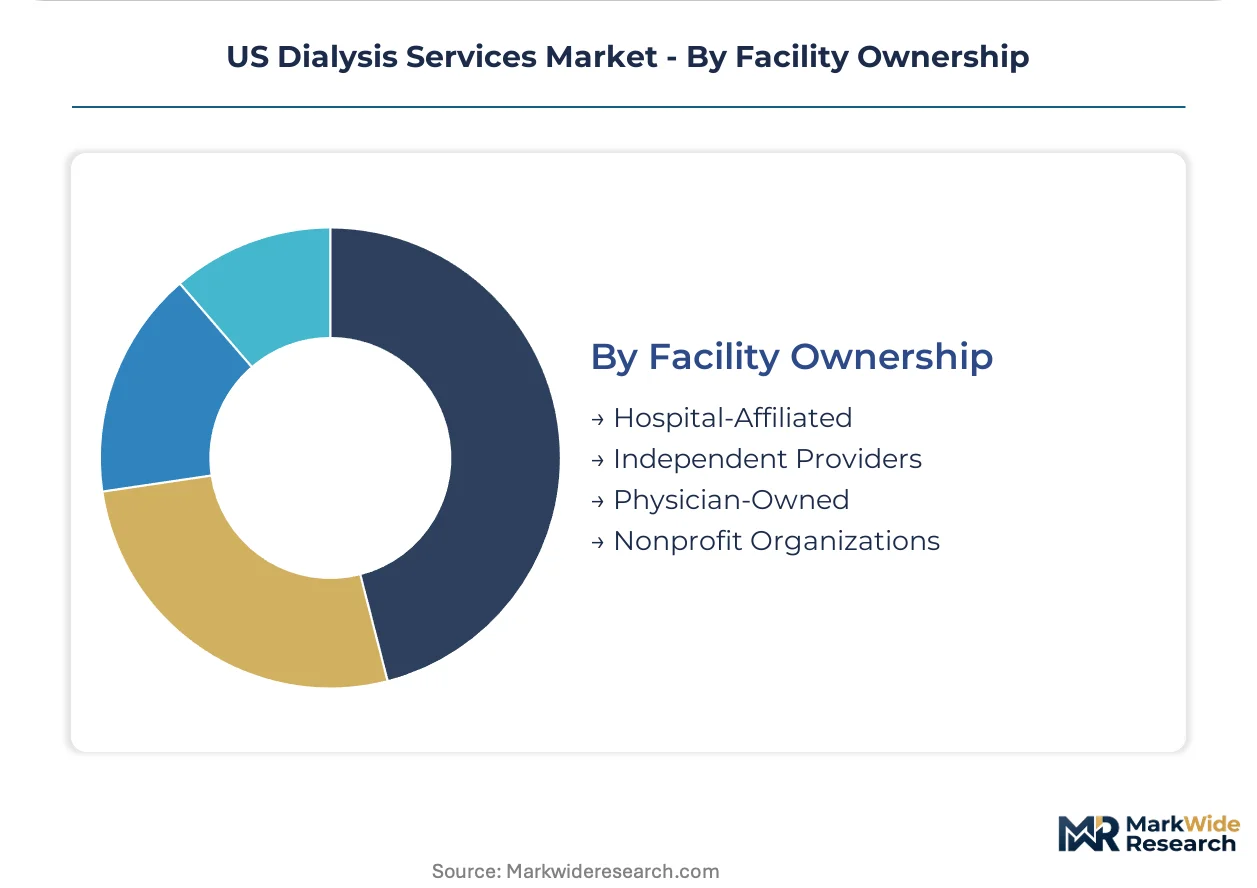
Facility Ownership:
Strategic control over supply chains and payer relationships separates ownership models with pricing power from those competing on operational efficiency.
- Hospital-Affiliated:Systems integrating dialysis within broader care continuums with EHR interoperability and emergency backup. Academic medical centers in New York, Illinois, and Ohio leverage certificate-of-need protections to limit independent entry.
- Independent Providers:Freestanding chains and regional operators optimizing throughput and labor scheduling. Secondary markets in the Mountain West and Deep South present expansion opportunities where clinic density lags ESRD incidence.
- Physician-Owned:Nephrology practice-affiliated facilities with Stark Law compliance requirements and referral self-direction. Joint ventures with dialysis chains are restructuring as CMS scrutinizes ownership transparency.
- Nonprofit Organizations:Mission-driven operators with community board governance and charity care obligations. Rural service areas depend on these entities where commercial returns would not sustain for-profit entry.
Hospital-Affiliated ownership retains structural advantages in restricted states, with Independent Providers climbing fastest through Medicare Advantage risk contracting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates more dialysis device manufacturing than any European peer, while the United States deploys more home-based treatment infrastructure per capita than Japan despite comparable ESRD prevalence rates.
California
Diabetes prevalence and aging demographics in Los Angeles and San Diego counties generate the nation's highest ESRD incidence density. CMS innovation center demonstrations for remote monitoring accelerate home modality adoption among Medicare Advantage enrollees. The Bay Area anchors telehealth-enabled dialysis platform development, with nephrology practices prioritizing virtual infrastructure over physical expansion.
Texas
Rapid population growth and uninsured rate volatility in Houston and Dallas-Fort Worth strain safety-net dialysis capacity. State Medicaid waiver programs supplement federal ESRD payments for low-income patients. The Rio Grande Valley exhibits acute clinic underservice relative to documented ESRD prevalence, attracting independent operator entry.
Florida
Snowbird migration patterns concentrate seasonal dialysis demand in Miami-Dade and Tampa Bay metropolitan areas. Medicare Advantage penetration exceeds national averages, pulling providers toward risk-sharing arrangements. The Orlando corridor hosts training centers for patient self-management protocols using virtual reality modules.
New York
Certificate-of-need laws restrict new facility licensing in New York City and upstate regions, protecting incumbent operators. Hospital-affiliated academic medical centers retain referral leverage through EHR interoperability. The Buffalo-Rochester corridor depends on nonprofit operators where commercial returns would not sustain for-profit entry.
Illinois
Urban-rural disparity in nephrology workforce distribution leaves Downstate community clinics understaffed relative to Chicago-area academic centers. State-level CON restrictions limit independent expansion in Peoria and Springfield markets. The Rockford cluster experiences capacity constraints as Wisconsin-based systems compete for cross-border patients.
US Dialysis Services Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across the US dialysis services landscape. The market structure concentrates around vertically integrated chains controlling supply chains and regional independents competing on operational efficiency. Three archetypes dominate: multinational device-and-service conglomerates, mid-scale regional chains, and physician-affiliated joint ventures. Consolidation through Medicare Advantage risk contracting and remote monitoring platform licensing constitute the primary competitive moves reshaping positioning.
Among German-diversified conglomerates, Fresenius Medical Care AG & Co. KGaA exemplifies the vertically integrated archetype through captive supply chain control. DaVita Inc. and U.S. Renal Care Inc. represent distinct scale tiers within US-focused service provision, with the former anchoring chronic disease management partnerships and the latter occupying operational efficiency positioning in secondary markets.
| Leading Market Players |
|---|
| Fresenius Medical Care AG & Co. KGaA |
| DaVita Inc. |
| U.S. Renal Care Inc. |
| Dialysis Clinic, Inc. |
| Satellite Healthcare |
| Northwest Kidney Centers |
| Centers for Dialysis Care |
| Innovative Renal Care |
| American Renal Associates |
| Others |
Cost & Logistics Intelligence
Medicare Advantage plan consolidation is compressing per-treatment reimbursement rates, forcing dialysis providers to renegotiate device procurement contracts and consolidate supplier relationships to protect margin structures.
Pricing Analysis
Capacity additions in Texas and Florida are reshaping price floors for in-center hemodialysis sessions as independent operators compete for Medicare Advantage risk contracts. Three-tier pricing structure across premium, standard, and economy levels separates hospital-affiliated academic centers from independent chains and rural nonprofit operators. Price differentiation hinges on CMS quality star ratings and geographic delivery cost to remote counties. Cost compression in the standard tier is intensifying because DaVita and Fresenius leverage captive supply chains. Safety-net providers in Medicaid-dependent markets exhibit highest price sensitivity while Medicare Advantage enrollees in California and Florida show lowest sensitivity due to bundled payment protections.
Supply Chain Analysis
FDA 510(k) and PMA certification requirements gate entry for dialyzer membrane manufacturers, concentrating upstream supply among German and Japanese producers with established quality systems. Germany, Japan, and the United States anchor dialyzer and water purification system manufacturing. Raw material dependencies span medical-grade polymers, hollow-fiber membranes, and reverse osmosis filtration media. Single-source vulnerability for biocompatible synthetic membranes exposes clinics to price volatility when polymer feedstock costs fluctuate. Distribution runs through vertically integrated chains with captive logistics networks and independent distributors serving secondary markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Texas-Florida-California clinic density gaps against ESRD incidence rates create geographic-arbitrage opportunities, with Texas Medicaid waiver supplemental payments offering margin buffers unavailable in California's rate-compressed Medicare Advantage environment.
For Market Incumbents: Extend remote patient monitoring platform licensing to independent nephrology practices before CMS innovation center demonstrations redistribute home dialysis volumes. Consolidate vascular access procedure capacity in ambulatory surgical centers as site-neutral payment policies redirect hospital outpatient department volume. Backward integration into dialyzer reprocessing services mitigates single-source device dependency threats from German and Japanese membrane suppliers. For New Entrants and Emerging Players: CMS ESRD Prospective Payment System remote monitoring add-on codes in the United States open a window for home hemodialysis equipment leasing models targeting rural Mountain West counties with acute clinic underservice. Peritoneal dialysis expansion presents the most penetrable modality segment given CMS bundled payment adjustments and lower capital intensity versus in-center buildout. Go-to-market through Medicare Advantage risk-sharing partnerships with regional plans in Florida bypasses incumbent hospital-affiliated referral networks. For Investors and Strategic Acquirers: Asymmetric upside sits with independent providers holding Medicare Advantage contracts in Texas secondary markets where CON restrictions do not apply. Long-term viability over the projection horizon favors operators with telehealth-enabled home dialysis infrastructure and nephrology workforce recruitment capabilities in rural geographies. Watch CMS innovation center demonstration outcome data as the inflection indicator for home modality reimbursement parity.| Strategic Initiative | Industry Significance |
|---|---|
| Remote Monitoring Platform Licensing | CMS add-on codes accelerate home dialysis adoption among Medicare Advantage enrollees in California. |
| Ambulatory Surgical Center Partnership | Site-neutral payment policies redirect vascular access procedures from hospital outpatient departments. |
| Peritoneal Dialysis Expansion | Bundled payment adjustments from CMS innovation center demonstrations incentivize modality shift. |
| Nephrology Workforce Recruitment | Fellowship-trained specialist scarcity in Downstate Illinois and Rio Grande Valley constrains capacity growth. |
| Medicare Advantage Risk Contracting | Consolidated payer purchasing power pulls providers toward value-based arrangements with shared savings provisions. |
Research Approach
Coverage spans California, Texas, Florida, New York, and Illinois, with primary inputs from each state market combined with secondary validation across federal and state regulatory filings. Primary interviews engaged nephrology practice administrators, dialysis center operations directors, Medicare Advantage plan contracting officers, and CMS policy analysts. Secondary sources encompassed FDA 510(k) and PMA device databases, CMS ESRD program payment rulemaking documents, state certificate-of-need regulatory filings, and hospital procurement databases. Bottom-up clinic capacity modeling and top-down ESRD incidence projections were triangulated against Medicare claims data.
Service type, end-user channel, payment model, and facility ownership were modeled at the state level with metropolitan statistical area granularity for California, Texas, and Florida. Patient volume forecasts incorporated diabetes prevalence trends, aging demographic shifts, and Medicare Advantage penetration rates across the projection horizon. CAGRs were derived from weighted average growth across in-center hemodialysis, home hemodialysis, and peritoneal dialysis segments. Forecast inputs included CMS remote monitoring reimbursement trajectory, CON law expansion or repeal probability by state, and portable hemodialysis device FDA clearance timelines.
Revisions become necessary when CMS innovation center demonstration results trigger bundled payment adjustments, state CON laws are repealed or expanded, or FDA clears breakthrough dialysis device categories. Forecasts reflect documented assumptions about Medicare Advantage plan consolidation pace and nephrology fellowship graduation rates. A model refresh is warranted upon material change in CMS home dialysis incentive payment structures or Texas Medicaid waiver program modifications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nephrology
Proteinuria Treatment Market
Nephrology
Blood Dialyzer Market
Nephrology
Plasmapheresis Market
Nephrology
Renal Stent Market
Nephrology
Global Hemodialysis Market
Nephrology
Late Stage Chronic Kidney Disease Therapeutics Market
Nephrology
Nephrosclerosis Treatment Market
Nephrology
Peritoneal Dialysis Market
Nephrology
Nephrology Stents and Catheters Market
Nephrology
Hemodialyzer Market
Nephrology
Nephrotic Syndrome Market
Nephrology
Radiation Nephropathy Treatment and Management Market
Nephrology
Kidney Stone Extraction Balloon Market
Nephrology
Hemodialysis and Peritoneal Dialysis Market
Nephrology
Chronic Kidney Disease Market
Nephrology
Global Acute Kidney Injury Treatment Market