
 Kidney Transplant Market | 2026-2036
Kidney Transplant Market Size, Share, and Industry Trends Forecast 2026-2036
Kidney Transplant Market Outlook
Transplant centers are rotating toward living donor programs as waitlist volumes strain deceased donor availability. XVIVO Perfusion AB dominates normothermic machine perfusion technology for marginal organ assessment. Paragonix Technologies specializes in portable hypothermic preservation devices that extend cold ischemia windows. TransMedics Group, Inc. leads organ care systems with portable warm perfusion platforms that enable functional evaluation prior to implantation.
A kidney transplant replaces a failed kidney with a healthy donor organ through vascular anastomosis and ureteral implantation, requiring human leukocyte antigen matching and lifelong immunosuppression to prevent rejection. The procedure restores renal filtration, electrolyte balance, and erythropoietin production without dialysis dependency. Deceased donor kidneys currently anchor transplant volume but face structural constraints from brain death declaration protocols and preservation time limits. Living donor segments sustain faster growth due to paired exchange algorithms and laparoscopic donor nephrectomy advances that reduce recovery trauma. Immunosuppressant technology occupies the deepest margin pool as tacrolimus, belatacept, and emerging costimulation blockers command chronic therapy positioning.
The FDA regulates organ preservation solutions and transport devices as combination products, while CMS reimbursement frameworks determine transplant center financial viability through bundled payment structures. The OPTN/UNOS allocation policy revisions periodically redistribute geographic organ distribution equity, directly affecting center case volumes. Stakeholders must monitor xenotransplantation trial readouts and bioengineered kidney platform progress as these modalities could redefine donor source economics within the forecast window.
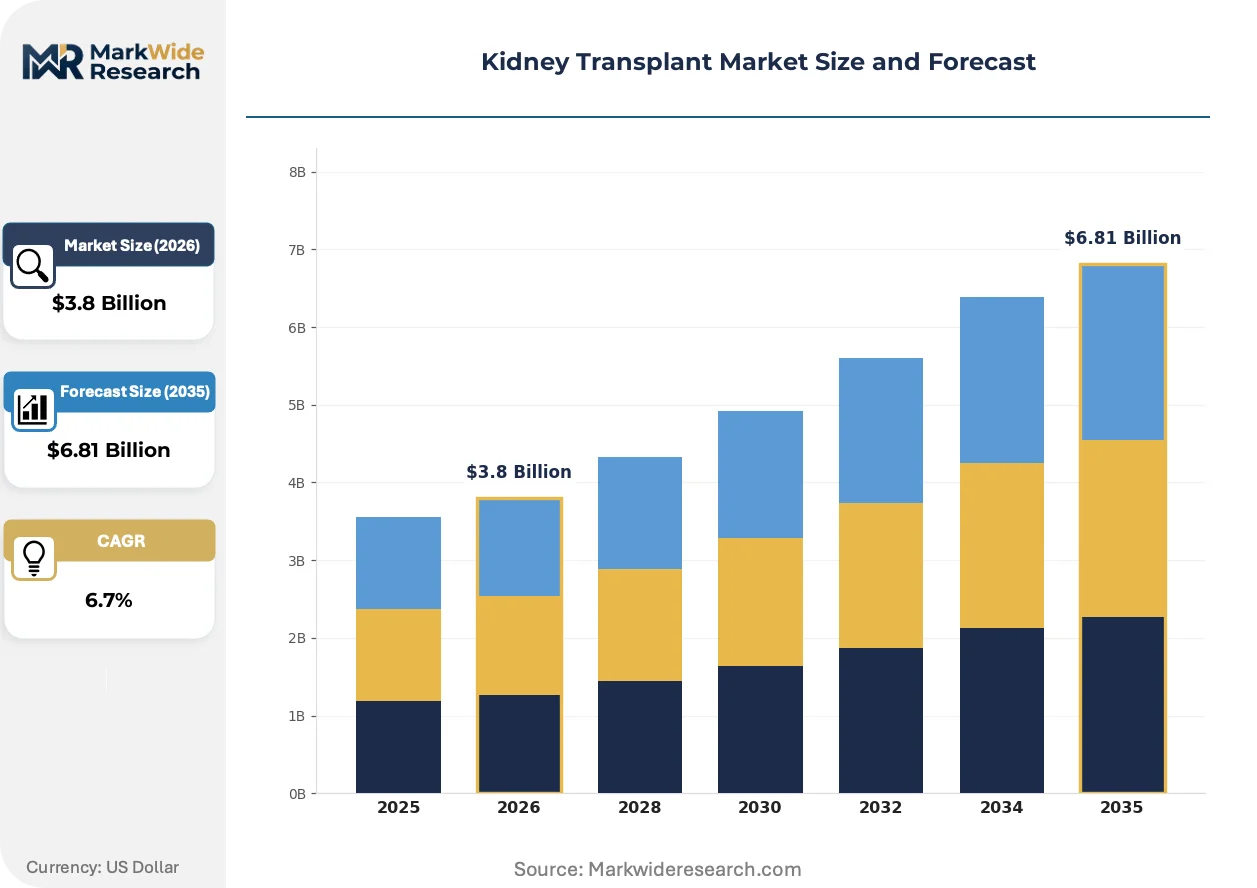
Market Dynamics
Living donor program expansion is fragmenting the traditional deceased-donor procurement model as transplant centers compete for surgical volume through paired exchange networks and laparoscopic nephrectomy protocols.
Growth Catalysts
- CMS Bundled Payment Frameworks:Reimbursement structures incentivize transplant center investment in living donor infrastructure across United States metropolitan clusters.
- Normothermic Machine Perfusion:Extended organ assessment windows enable marginal kidney utilization that deceased-donor constraints previously prohibited.
- Paired Exchange Algorithms:Software-driven donor-recipient matching expands incompatible-pair transplant feasibility in high-volume United States centers.
Market Restraints
- Organ Preservation Solution Concentration:Cold storage media supply depends on limited pharmaceutical-grade chemical manufacturers in Western Europe and North America.
- Brain Death Declaration Protocol Variability:Jurisdictional differences in neurological criteria reduce deceased-donor recovery rates in certain United States states.
- Immunosuppressant Cost Structure:Tacrolimus and belatacept pricing tiers strain Medicare Part B reimbursement ceilings for chronic therapy maintenance.
Strategic Opportunities
- Xenotransplantation Clinical Pathways:Genetically modified porcine kidney trials under FDA breakthrough designation could establish alternative donor economics.
- Telemedicine Donor Evaluation:Remote screening protocols expand living donor candidate pools in rural United States regions distant from transplant centers.
- Machine Perfusion as Service:Third-party organ assessment platforms create recurring revenue models independent of device ownership.
Industry Challenges
- Transplant Coordinator Workforce Scarcity:Specialized nursing and procurement coordination talent shortages delay living donor workup timelines.
- HLA Matching Algorithm Integration:Legacy electronic health record systems require costly API development to interface with OPTN/UNOS allocation software.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kidney Transplant Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Kidney, Living Donor Kidney, Deceased Donor Kidney, Bioengineered Kidney End User: Hospitals, Transplant Centers, Dialysis Clinics, Research Institutions Delivery Mode: In-Person Surgery, Telemedicine Consultation, Ambulatory Care, Home-Based Care Technology: Immunosuppressants, Surgical Techniques, Monitoring Devices, Gene Therapy |
| Companies Covered | TransMedics Group, Inc., XVIVO Perfusion AB, Paragonix Technologies, Organ Recovery Systems, OrganOx Limited, Bridge to Life Ltd., Waters Medical Systems, Organ Assist B.V., CareDx, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kidney Transplant Market Strategic Shifts
Organ care technology is displacing static cold storage as the default preservation modality, with functional assessment capabilities reshaping how marginal kidneys enter the allocation pool.
Normothermic machine perfusion is fragmenting the organ assessment landscape by enabling real-time metabolic monitoring during transport. High-volume United States transplant centers are adopting these platforms for extended-criteria donor kidneys previously discarded. The technology compresses cold ischemia time variability and creates discrete valuation tiers based on perfusion biomarker outputs.
FDA combination product guidance for organ preservation devices is tightening premarket submission requirements for solutions incorporating active transport mechanisms. Manufacturers must now demonstrate device-solution interaction stability across temperature protocols. United States-based transplant centers face procurement delays as legacy 510(k) clearances undergo supplemental clinical validation.
Living donor chains are compressing the traditional paired exchange timeline through non-directed donor initiation sequences. United States transplant centers with dedicated donor advocates and streamlined psychological evaluation protocols capture disproportionate chain volume. Geographic concentration of these programs in coastal metropolitan areas creates access inequities for interior region candidates.
Kidney Transplant Market Segmentation
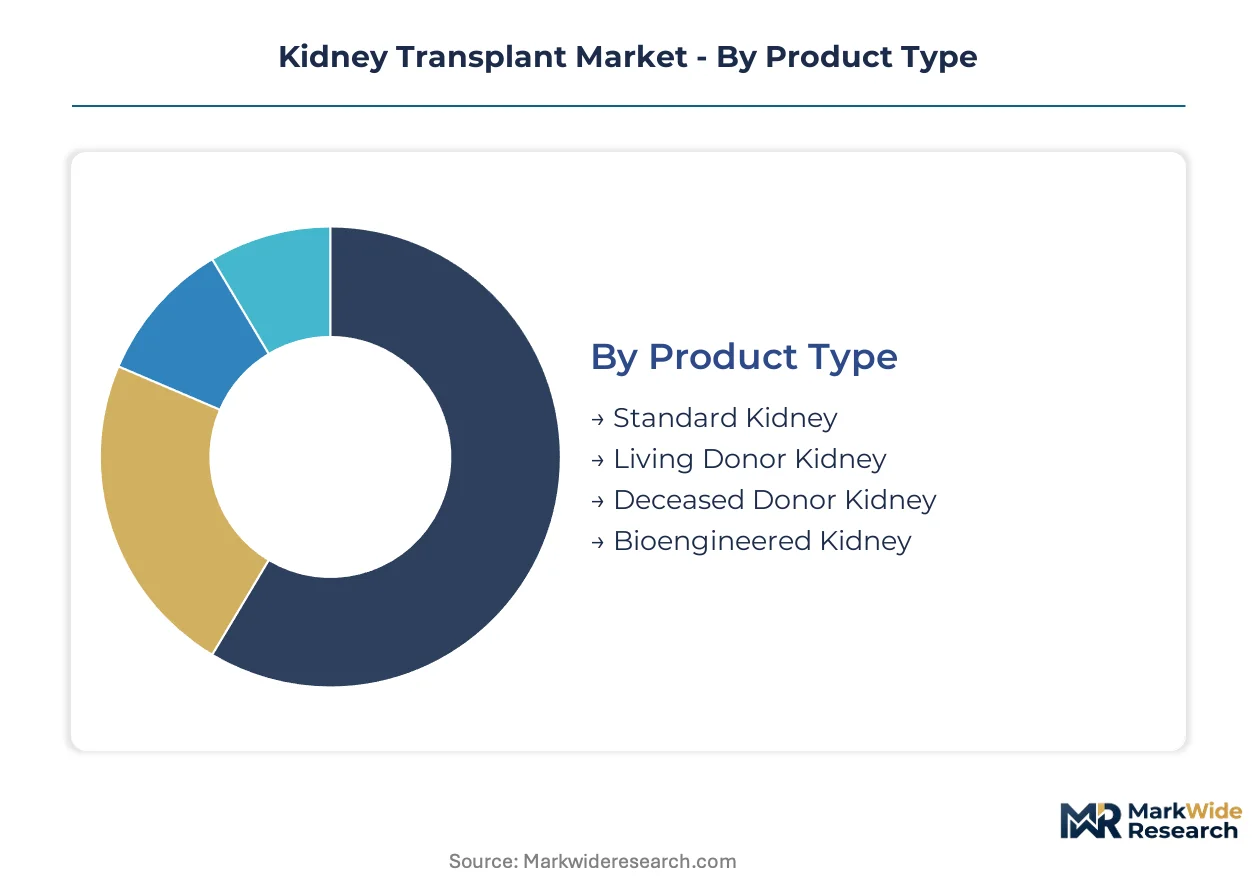
Kidney transplant segmentation reveals how procurement economics split across donor sources and institutional capabilities. Product type and end-user dynamics determine reimbursement pathways and technology adoption rates.
Product Type:
Donor source channels determine organ availability timelines, matching complexity, and long-term graft survival economics.
- Standard Kidney:Conventional deceased-donor organs procured through OPTN/UNOS allocation networks with established cold preservation protocols. United States transplant centers in metropolitan clusters absorb the majority of standard kidney volume due to proximity to organ procurement organizations and shorter ischemia windows.
- Living Donor Kidney:Surgically extracted from genetically related or emotionally connected donors through laparoscopic nephrectomy. Paired exchange networks in high-volume United States centers are expanding this segment through algorithmic matching of incompatible donor-recipient pairs.
- Deceased Donor Kidney:Organs recovered after brain death or cardiac death declaration, subject to geographic allocation policy and preservation time constraints. Brain death declaration protocol variability across United States states creates regional supply disparities.
- Bioengineered Kidney:Laboratory-cultured renal tissue and scaffold-based constructs under preclinical and early clinical investigation. Research institutions with NIH funding dominance hold current developmental capacity.
By volume, deceased donor kidney leads. By growth pace, living donor kidney is ahead.
End User:
Institutional capabilities stratify across surgical volume thresholds and reimbursement sophistication.
- Hospitals:General acute care facilities with transplant programs embedded within broader surgical service lines. CMS bundled payment frameworks incentivize hospital-based transplant center investment in living donor infrastructure.
- Transplant Centers:Specialized facilities with dedicated procurement coordinators, HLA laboratories, and immunosuppression management protocols. These centers concentrate paired exchange algorithm utilization and machine perfusion technology adoption.
- Dialysis Clinics:Outpatient renal replacement therapy facilities that identify transplant candidates and coordinate referrals. DaVita and Fresenius clinic networks in the United States function as primary patient funnel sources.
- Research Institutions:Academic medical centers conducting xenotransplantation trials and bioengineered kidney development. FDA breakthrough designation programs anchor their clinical translation pathways.
Transplant centers capture the highest procedure margins. Research institutions are expanding most quickly as xenotransplantation trials advance.
Delivery Mode:
Care setting configurations reflect reimbursement structure and patient acuity requirements.
- In-Person Surgery:Required for donor nephrectomy and recipient implantation procedures with no viable remote alternative. United States metropolitan transplant clusters maintain surgical volume concentration.
- Telemedicine Consultation:Remote donor evaluation and post-transplant monitoring protocols expanding through CMS telehealth reimbursement expansions. Rural United States regions distant from transplant centers drive adoption.
- Ambulatory Care:Outpatient immunosuppression management and routine graft function monitoring. Medicare Part B reimbursement ceilings constrain chronic therapy delivery economics.
- Home-Based Care:Emerging models for stable post-transplant patients with remote biometric monitoring. Home dialysis-to-transplant transition programs in United States value-based care contracts pilot this modality.
In-person surgery dominates procedure revenue. Telemedicine consultation is gaining share fastest.
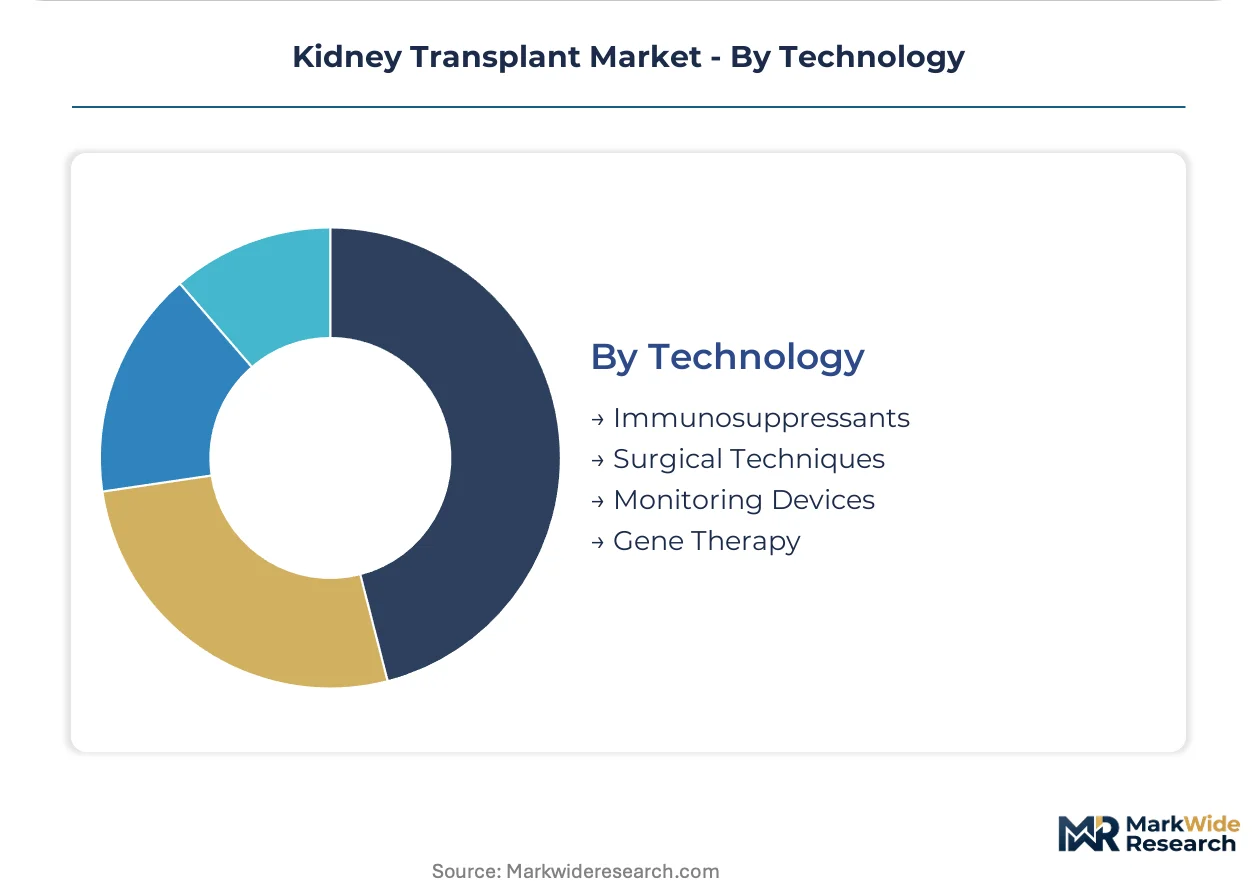
Technology:
Technology segments align with chronic therapy positioning versus acute intervention economics.
- Immunosuppressants:Tacrolimus, belatacept, and costimulation blockers commanding chronic therapy maintenance revenue. Medicare Part B reimbursement structures determine patient access tiers.
- Surgical Techniques:Laparoscopic donor nephrectomy and robotic-assisted vascular anastomosis reducing recovery trauma. High-volume United States centers differentiate through minimally invasive protocol refinement.
- Monitoring Devices:Graft function biomarker assays and wearable renal output sensors for early rejection detection. FDA combination product guidance tightens premarket submission requirements for active transport mechanisms.
- Gene Therapy:Preclinical approaches to induce immune tolerance and reduce lifelong immunosuppression burden. NIH-funded academic consortia hold current research concentration.
Immunosuppressants generate the deepest recurring revenue. Gene therapy shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States Interstate Highway System and dedicated organ transport aviation networks underpin North American transplant logistics, while Germany's dense autobahn grid and centralized procurement zones anchor European organ mobility.
United States
Metropolitan transplant clusters in Houston, Los Angeles, and New York drive living donor volume through paired exchange networks. CMS bundled payment frameworks incentivize hospital investment in laparoscopic nephrectomy infrastructure. The OPTN/UNOS allocation policy revisions redistribute geographic organ distribution equity, directly affecting center case volumes across state lines.
Germany
Deutsche Stiftung Organtransplantation coordinates deceased donor recovery through regional organ procurement organizations. The country's national pharmaceutical regulator, the Federal Institute for Drugs and Medical Devices, enforces strict organ preservation device standards. Berlin and Munich transplant centers concentrate machine perfusion adoption for marginal kidney assessment.
Japan
Cultural hesitancy around brain death declaration constrains deceased donor availability, intensifying living relative donor reliance. The Pharmaceuticals and Medical Devices Agency oversees immunosuppressant approval pathways with extended clinical trial requirements. Tokyo and Osaka academic medical centers lead paired exchange algorithm implementation.
United Kingdom
NHS Blood and Transplant operates the national organ allocation framework with geographic equity mandates. The Medicines and Healthcare products Regulatory Agency regulates normothermic perfusion devices under combination product guidance. London and Manchester transplant hubs drive living donor chain initiation through non-directed donor programs.
India
Expanding dialysis clinic networks in Delhi, Mumbai, and Chennai generate transplant candidate pools. The Central Drugs Standard Control Organization oversees organ preservation solution import licensing. Tamil Nadu and Maharashtra state governments operate deceased donor registries with varying brain death declaration protocol adoption.
Kidney Transplant Market Competitive Environment
Listed leaders compete with private specialists across device categories and preservation modalities. The vendor base stratifies into three tiers: large-cap diversified medical technology conglomerates, mid-cap organ-specific platform developers, and venture-backed perfusion technology startups. Strategic archetypes include integrated organ care system providers, standalone preservation device manufacturers, and immunosuppression monitoring specialists. Competitive moves concentrate on technology licensing partnerships and geographic expansion through distributor networks.
Within the organ care system tier, TransMedics Group, Inc. and OrganOx Limited represent integrated platform approaches combining perfusion hardware with transport logistics. XVIVO Perfusion AB and Paragonix Technologies occupy specialized device positions, with the former exemplifying normothermic assessment technology and the latter anchoring portable hypothermic preservation. These four entities collectively illustrate the competitive tension between comprehensive system integration and focused single-modality excellence.
| Leading Market Players |
|---|
| TransMedics Group, Inc. |
| XVIVO Perfusion AB |
| Paragonix Technologies |
| Organ Recovery Systems |
| OrganOx Limited |
| Bridge to Life Ltd. |
| Waters Medical Systems |
| Organ Assist B.V. |
| CareDx |
| Others |
Value Chain & Pricing Dynamics
CMS bundled payment frameworks lock in transplant center revenue visibility while simultaneously constraining supplier pricing power through Medicare Part B reimbursement ceilings. These contract structures tether device manufacturers to chronic therapy maintenance economics and limit premium capture for organ preservation technologies.
Pricing Analysis
Volume-discount tiering structures separate academic medical centers with high transplant volumes from community hospitals with sporadic case loads. Immunosuppressant pricing stratifies across premium, standard, and economy tiers based on patent exclusivity and biosimilar penetration. Cost compression in generic tacrolimus is intensifying because Medicare Part B reimbursement ceilings constrain chronic therapy margins. Dialysis clinic networks demonstrate highest price sensitivity due to thin referral economics, while research institutions show lowest sensitivity given NIH funding insulation.
Supply Chain Analysis
Inventory lead times for pharmaceutical-grade preservation solutions extend 8-14 weeks due to limited Western European and North American chemical manufacturers. Cold storage media production draws from specialty chemical suppliers in Germany, Switzerland, and the United States. Single-source vulnerability concentrates in organ transport device electronics sourced from East Asian semiconductor fabricators. Distribution runs through transplant center procurement coordinators who negotiate directly with device manufacturers and pharmaceutical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized transplant coordinator talent scarcity constrains living donor program expansion velocity, creating bottlenecks that favor institutions with established training pipelines and retention protocols.
For Market Incumbents: Secure paired exchange algorithm capabilities through exclusive licensing arrangements with software developers. Expand laparoscopic nephrectomy training infrastructure to capture living donor volume from competitors constrained by surgical workforce gaps. Xenotransplantation trial readouts represent the primary substitution threat requiring monitoring. For New Entrants and Emerging Players: FDA breakthrough designation fast-tracks offer regulatory acceleration for bioengineered kidney platforms and genetically modified porcine organ programs. Rural telemedicine donor evaluation presents the most penetrable white-space target given CMS telehealth reimbursement expansions. Partner with established dialysis clinic networks for patient funnel access rather than building de novo referral channels. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors platform-integrated device manufacturers over standalone preservation specialists. Long-term viability hinges on recurring revenue models from machine perfusion as service offerings rather than capital equipment sales. Watch xenotransplantation trial enrollment velocity as the primary inflection indicator for donor source economics disruption.| Strategic Initiative | Industry Significance |
|---|---|
| Machine Perfusion as Service Launch | Third-party organ assessment platforms create recurring revenue independent of device ownership cycles. |
| Paired Exchange Network Expansion | Algorithmic matching infrastructure captures incompatible-pair volume from competing transplant centers. |
| Xenotransplantation Clinical Pathway | FDA breakthrough designation programs anchor alternative donor economics development timelines. |
| Telemedicine Donor Evaluation Protocol | Remote screening expands candidate pools in rural regions distant from metropolitan transplant hubs. |
| Immunosuppressant Biosimilar Manufacturing | Generic tacrolimus production addresses Medicare Part B reimbursement ceiling constraints. |
Study Parameters
Cross-validation between transplant center financial disclosures and CMS reimbursement data anchors the qualitative findings. Primary interviews with transplant surgeons, organ procurement coordinators, biomedical engineers, and GPO contracts managers combined with secondary validation from FDA filings, CMS Medicare cost reports, OPTN/UNOS allocation databases, and hospital procurement systems. Bottom-up procedure volume estimates and top-down pharmaceutical revenue triangulation constrain forecast variance.
Sensitivity analysis tested forecast robustness across alternative immunosuppressant pricing scenarios and xenotransplantation trial acceleration assumptions. The analytical framework models donor source segmentation, end-user institutional tier, delivery mode configuration, and technology platform adoption across the projection horizon. CAGRs derive from logistic diffusion curves fitted to historical procedure volumes and pharmaceutical shipment data. Forecast inputs incorporate paired exchange network penetration rates and machine perfusion technology adoption thresholds.
Decision-makers should treat outputs as directional under stable CMS reimbursement and OPTN allocation policy assumptions; material deviation would warrant model refresh. Xenotransplantation clinical success, immunosuppressant patent cliffs, and transplant coordinator workforce expansion represent specific risk factors that could revise forecasts. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nephrology
Kidney Transplant Medicine Market
Nephrology
Global Continuous Renal Replacement Therapy (CRRT) Market
Nephrology
Global Hemodialysis Market
Nephrology
End Stage Renal Disease Market
Nephrology
Global Dialyzer Market
Nephrology
US Hemodialysis and Peritoneal Dialysis Market
Nephrology
Hemodialysis Services Market
Nephrology
Kidney Fibrosis Treatment Market
Nephrology
Renal Artery Stenosis Treatment Market
Nephrology
Renal Cell Carcinoma Market
Nephrology
Aldosterone-Renin Screening Market
Nephrology
Hemodialysis Vascular Graft Market
Nephrology
Nephrotic Syndrome Market
Nephrology
Kidney Dialysis Equipment Market
Nephrology
Global Dialysis Market
Nephrology
Renal Stent Market