
 Hollow Fiber Dialyzers Market | 2026-2036
Hollow Fiber Dialyzers Market Size, Share, and Industry Trends Forecast 2026-2036
Hollow Fiber Dialyzers Market Foresight
Modular dialyzer-to-circuit bundling is pivoting procurement decisions across hospital systems and dialysis chains. Fresenius Medical Care leverages captive manufacturing of polysulfone membranes to anchor its integrated supply position. Baxter International competes through geographic diversification across North American and European dialysis service networks. NIPRO Corporation differentiates via specialized hollow fiber spinning capabilities that sustain premium positioning in Asian markets.
A hollow fiber dialyzer is a cylindrical blood purification device containing thousands of semipermeable capillary membranes, typically manufactured from polysulfone or polyethersulfone through melt-spinning or solution-spinning processes, designed to remove uremic toxins and excess fluid during hemodialysis. High-flux configurations now lead volume share due to superior middle-molecule clearance, while single-use dialyzers dominate revenue as infection control protocols harden against reusable alternatives. Polysulfone material grades command margin concentration owing to their biocompatibility profile and established clinical validation.
The FDA's 510(k) clearance framework and the EU Medical Device Regulation shape product entry requirements, with MDR's enhanced clinical evidence demands extending certification timelines for new membrane technologies. The EPA oversees waste disposal standards for dialyzer effluent, influencing end-of-life cost structures for dialysis providers. Stakeholders must monitor evolving reimbursement parity between in-center and home dialysis modalities as regulatory bodies recalibrate payment models.
Market Dynamics
Membrane material consolidation around polysulfone and polyethersulfone grades is compressing supplier diversity while elevating biocompatibility standards as the defining procurement criterion across dialysis service networks.
Growth Catalysts
- High-flux membrane adoption:Dialysis chains in the United States are standardizing high-flux configurations for superior middle-molecule clearance, pulling volume share from low-flux alternatives.
- FDA 510(k) pathway modernization:Accelerated clearance timelines for next-generation membrane technologies are compressing product development cycles and reducing time-to-revenue for device manufacturers.
- Home-based hemodialysis expansion:Patient demand for treatment flexibility outside clinic settings is creating new addressable volume in residential care environments.
Market Restraints
- Polysulfone resin supply concentration:Three chemical producers control the majority of medical-grade polysulfone supply, exposing dialyzer manufacturers to input cost volatility and allocation risk.
- EU MDR clinical evidence demands:Enhanced documentation requirements for new membrane technologies are extending certification timelines and elevating regulatory compliance costs.
- Reusable dialyzer displacement:Single-use protocols are structurally eliminating reusable alternatives, compressing addressable market scope for refurbishment service providers.
Strategic Opportunities
- Home dialysis reimbursement parity:CMS payment model recalibration is narrowing the reimbursement gap between in-center and residential treatment modalities.
- Polyethersulfone-polymer blending:Hybrid membrane formulations combining polyethersulfone with surface-modifying additives are opening premium positioning for enhanced biocompatibility profiles.
- Dialysis chain direct procurement:Large service networks are consolidating supplier relationships and negotiating membrane-to-device bundled contracts, bypassing traditional distribution tiers.
Industry Challenges
- Hollow fiber spinning technician scarcity:Specialized melt-spinning and solution-spinning expertise is concentrated among aging workforce cohorts, constraining capacity expansion for precision membrane manufacturing.
- Legacy device integration complexity:Next-generation high-flux dialyzers require circuit compatibility verification with existing hemodialysis machines, complicating fleet upgrade decisions for dialysis providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hollow Fiber Dialyzers Market |
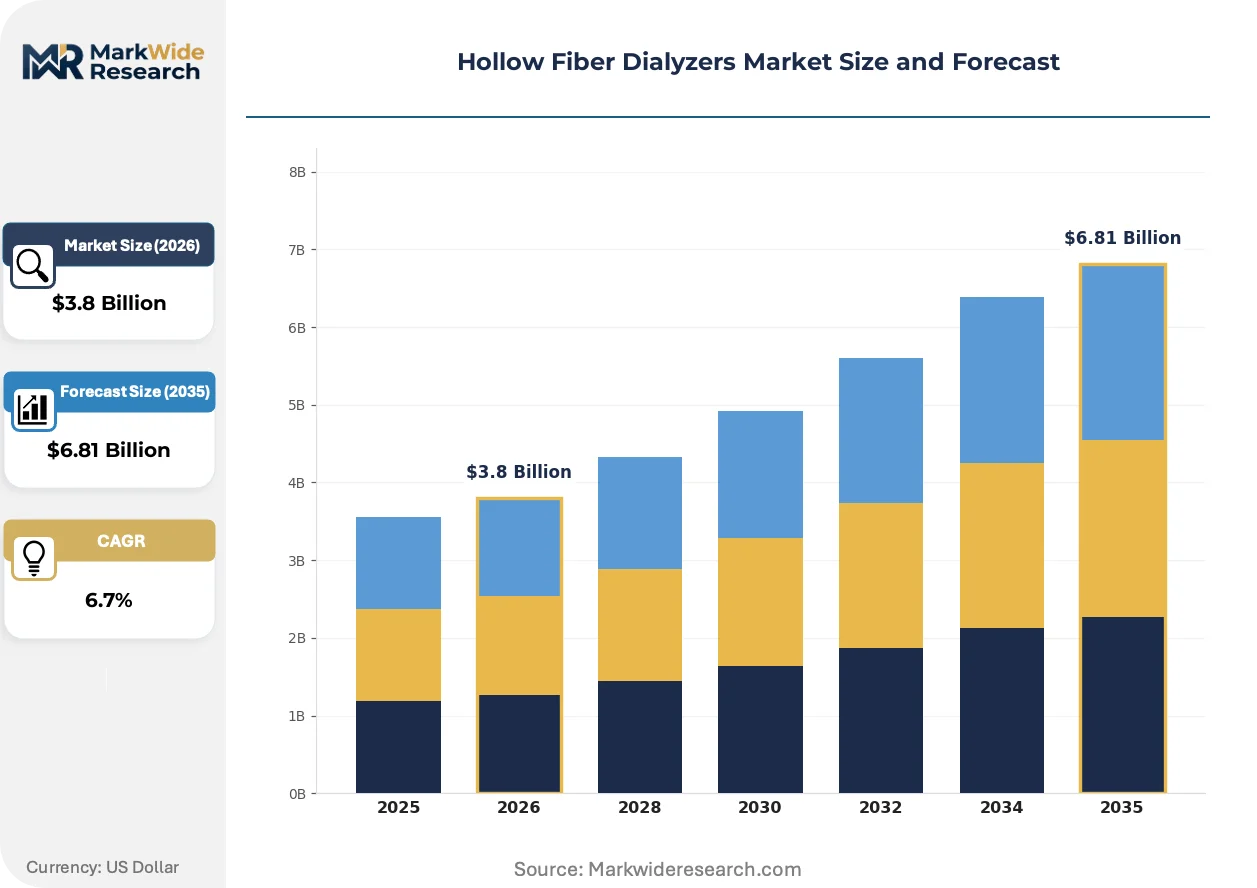
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reusable, Single-use, High-flux, Low-flux Material: Polyethersulfone, Polypropylene, Cellulose, Polysulfone End User: Dialysis Centers, Hospitals, Home Care, Long-term Care Facilities Distribution Channel: Direct Sales, Online Stores, Medical Distributors, Wholesalers |
| Companies Covered | Fresenius Medical Care, Baxter International, B. Braun, Toray Medical, Asahi Kasei Medical, NIPRO Corporation, Weigao Group, Haidylena, Allmed Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hollow Fiber Dialyzers Market Shifts & Advancements
Membrane surface chemistry modifications and manufacturing process automation are converging to redefine performance benchmarks and cost structures across the dialyzer value chain.
Polysulfone membrane technology is consolidating market position through established clinical validation and captive supply chain integration by major device manufacturers. Dialysis service networks in the United States and Western Europe are standardizing procurement around polysulfone-based high-flux configurations, displacing alternative polymer candidates. This consolidation is compressing R&D investment in competing membrane materials and elevating biocompatibility certification as the primary competitive differentiator.
The EU Medical Device Regulation's enhanced clinical evidence requirements are extending certification timelines for novel membrane technologies entering European markets. Manufacturers must now generate extended performance documentation and post-market surveillance data, elevating capital requirements for product launch. Asian manufacturers targeting European market entry are responding by pre-building clinical trial cohorts and partnering with EU-based notified bodies.
Direct contracting between dialysis chains and membrane suppliers is displacing traditional medical device distribution channels in high-volume procurement scenarios. Large service networks are negotiating multi-year supply agreements that bundle hollow fiber dialyzers with bloodline sets and concentrate sets, extracting volume discounts unavailable through distributor intermediaries. This pattern is most visible in the United States, where Fresenius Medical Care and DaVita's purchasing scale enables supplier bypass strategies.
Hollow Fiber Dialyzers Market Segmentation
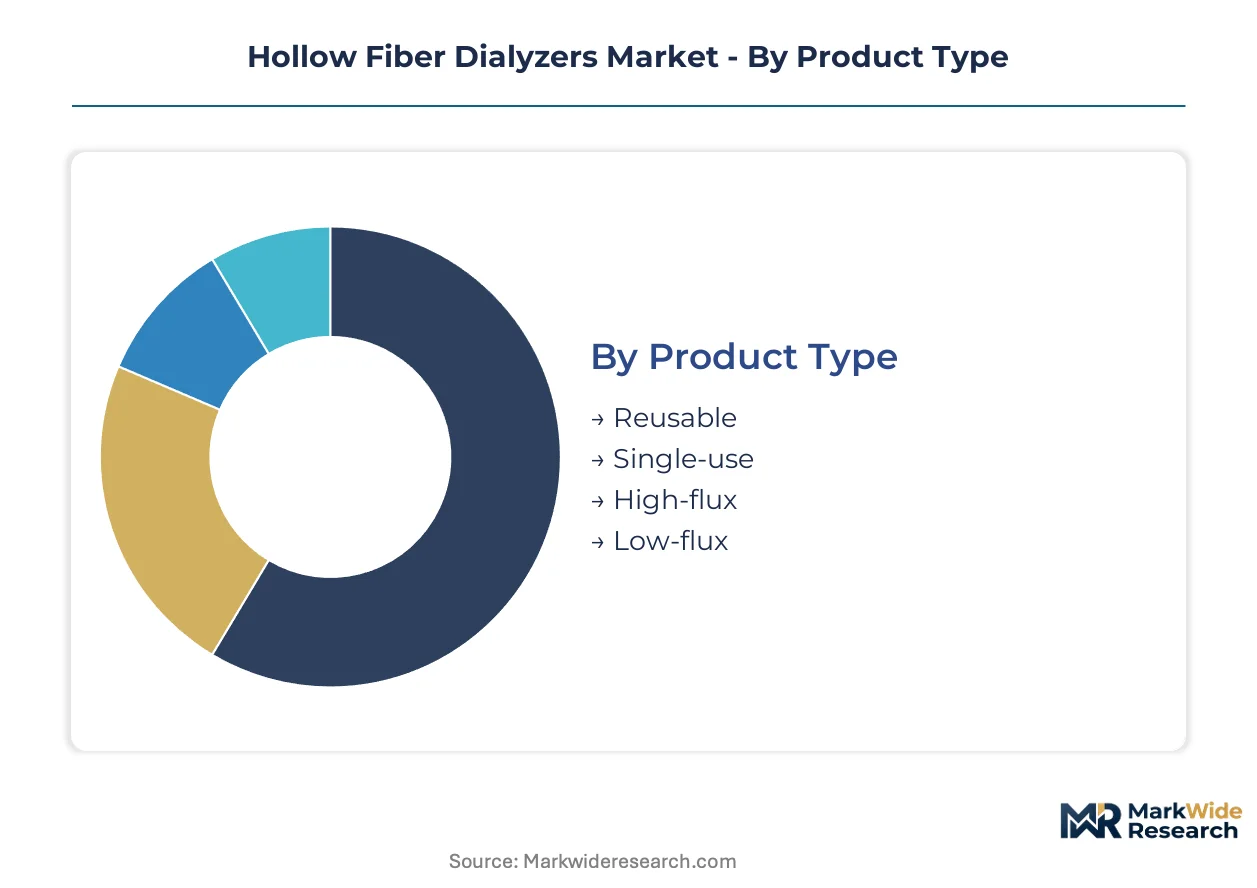
Segmentation in hollow fiber dialyzers reveals how procurement power concentrates around membrane material grades and sterilization protocols. Hospital systems and dialysis chains now segment their supplier bases by biocompatibility certification tiers rather than brand loyalty alone.
Product Type:
Supply concentration around single-use sterilization protocols has eliminated reusable manufacturing capacity across most OECD markets.
- Single-use:Gamma-sterilized polysulfone membranes dominate procurement specifications across United States dialysis chains. Infection control protocols in Medicare-certified facilities structurally mandate disposable configurations, compressing addressable scope for alternatives.
- High-flux:Enhanced middle-molecule clearance specifications now anchor purchasing criteria for hemodialysis providers upgrading from low-flux legacy fleets. United States reimbursement structures favor these configurations in both in-center and home-based settings.
- Low-flux:Remaining volume concentrates in cost-sensitive emerging markets with limited payer coverage for premium membrane technologies.
- Reusable:Chemical sterilization protocols persist only in isolated national health systems with explicit environmental waste mandates, facing accelerating regulatory displacement.
Today's leader: Single-use. Tomorrow's challenger: High-flux.
Material:
Cost tier stratification separates medical-grade polysulfone from commodity polymer alternatives in procurement negotiations.
- Polysulfone:Captive supply chain integration by major device manufacturers anchors premium positioning. Fresenius Medical Care's backward integration into membrane spinning sustains margin concentration unavailable to non-integrated competitors.
- Polyethersulfone:Hybrid formulations with surface-modifying additives command price premiums in Japanese and South Korean markets where biocompatibility certification requirements exceed baseline FDA 510(k) standards.
- Cellulose:Legacy cuprophane membranes retain residual volume in price-constrained national procurement tenders.
- Polypropylene:Bloodline component applications rather than primary membrane material, constrained by protein adsorption limitations in extended dialysis sessions.
Polysulfone anchors current procurement volumes. Polyethersulfone formulations are climbing the fastest in premium segment expansion.
End User:
Volume concentration among large dialysis service networks is compressing distributor margins and elevating direct contracting prevalence.
- Dialysis Centers:Outpatient facilities operated by Fresenius Medical Care and DaVita in the United States standardize high-flux configurations across fleet procurement, negotiating multi-year membrane supply agreements that bypass traditional distribution tiers.
- Home Care:Patient-managed hemodialysis is expanding fastest among end users seeking schedule flexibility outside clinic environments. CMS reimbursement parity initiatives are narrowing payment gaps versus in-center treatment.
- Hospitals:Acute dialysis requirements in emergency departments and ICUs concentrate demand for single-use protocols with rapid circuit priming specifications.
- Long-term Care Facilities:Skilled nursing facilities with on-site dialysis capabilities represent emerging volume in Medicare Advantage network expansions.
Dialysis centers command current procurement scale. Home care represents the steepest expansion trajectory in addressable volume.
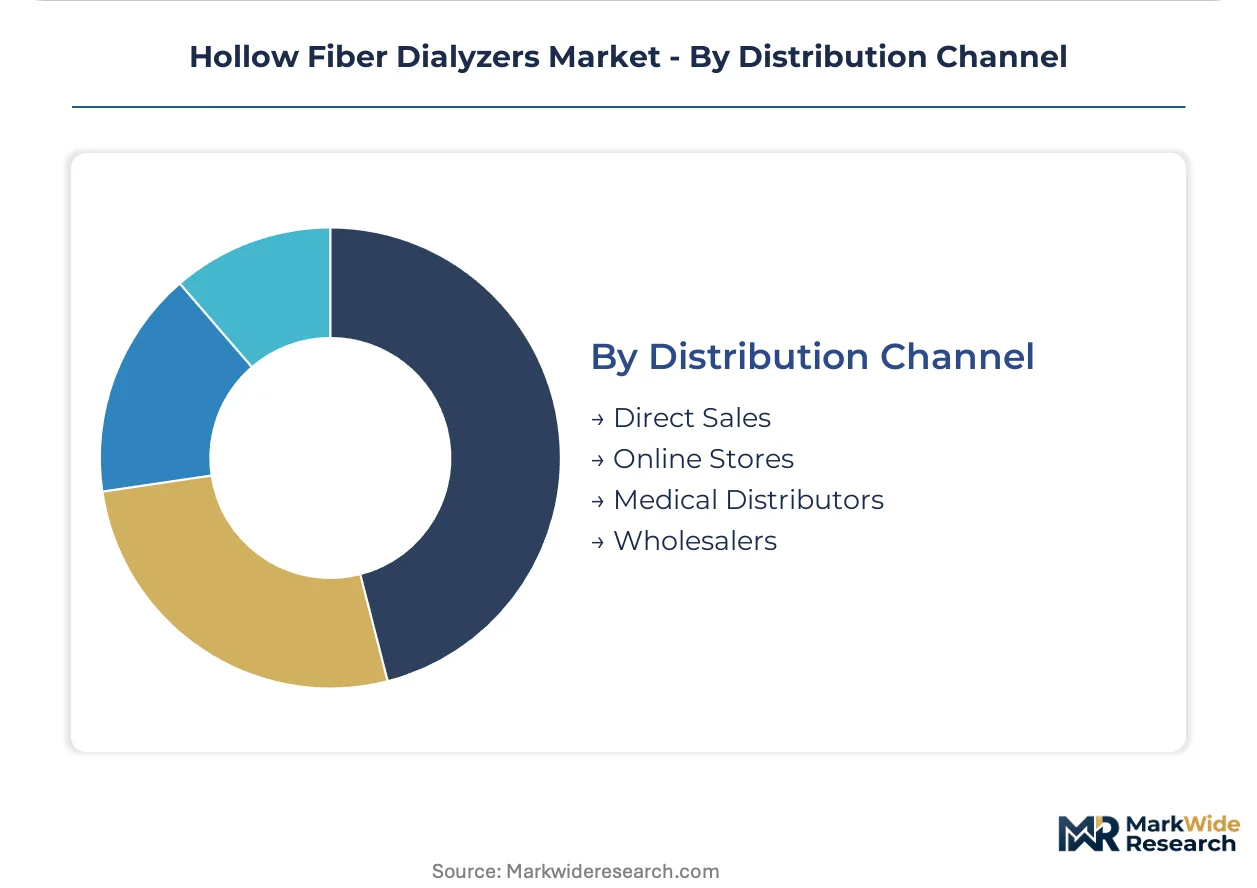
Distribution Channel:
Customer type fragmentation between institutional purchasers and individual patients is forcing channel specialization.
- Direct Sales:Large dialysis chains in the United States negotiate hollow fiber dialyzer-to-circuit bundled contracts directly with membrane manufacturers, extracting volume discounts unavailable through distributor intermediaries.
- Medical Distributors:Regional distributors retain relevance in hospital system procurement where SKU breadth across multiple device categories justifies consolidated purchasing relationships.
- Online Stores:Home dialysis patients in Germany and the United Kingdom access replacement dialyzer supplies through specialty medical e-commerce platforms with prescription verification protocols.
- Wholesalers:Pharmaceutical wholesalers with existing cold chain infrastructure leverage logistics networks for dialyzer distribution in markets with limited specialized medical device distribution capacity.
Direct sales channels capture institutional procurement concentration. Online stores are gaining share fastest in patient-direct home care segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered hollow fiber dialyzer manufacturing during the 1970s with Fresenius Medical Care's development of polysulfone membrane spinning technology. This engineering heritage established Central Europe as the foundational cluster for precision membrane production.
United States
Medicare's bundled payment system for dialysis services drives procurement standardization toward high-flux configurations across Fresenius and DaVita clinic networks. The FDA's 510(k) pathway modernization compresses clearance timelines for next-generation membrane technologies. Manufacturing concentration clusters in Massachusetts and California, where specialized medical device ecosystems support precision fiber spinning operations.
Germany
The EU Medical Device Regulation's enhanced clinical evidence requirements extend certification timelines for novel membrane technologies entering European markets. Germany's national reimbursement framework favors premium biocompatibility profiles in outpatient dialysis settings. Industrial capacity concentrates in Baden-Württemberg and Bavaria, where captive polysulfone resin supply chains integrate with dialyzer assembly operations.
Japan
Japan's aging demographic profile sustains demand for home-based hemodialysis systems with compact dialyzer footprints. The PMDA maintains stringent biocompatibility certification standards exceeding baseline FDA requirements. Manufacturing expertise clusters in Osaka and Tokyo metropolitan areas, where Toray Medical and Asahi Kasei Medical anchor specialized hollow fiber spinning capabilities.
China
Domestic dialysis patient volumes expand rapidly as NMPA accelerates local manufacturing approvals for membrane technologies. The country's dual carbon goals pressure dialyzer manufacturers toward reduced sterilization energy footprints. Production capacity concentrates in Shandong and Jiangsu provinces, where Weigao Group and emerging domestic players scale polysulfone membrane fabrication.
Hollow Fiber Dialyzers Market Competitive Landscape
The competitive structure tilts toward vertically integrated membrane manufacturers with captive resin supply arrangements. Three strategic archetypes dominate: integrated healthcare conglomerates controlling dialyzer-to-clinic value chains, specialized medical device manufacturers with precision spinning expertise, and regional champions serving price-sensitive emerging markets. Dominant competitive moves include backward integration into polysulfone resin production and multi-year direct contracting with large dialysis service networks.
Among integrated healthcare conglomerates, Fresenius Medical Care anchors the premium tier through its German engineering heritage and captive membrane manufacturing. Baxter International occupies a position exemplifying geographic diversification strategies across North American and European service networks. NIPRO Corporation represents the specialized precision manufacturing archetype, with its Japanese hollow fiber spinning capabilities sustaining premium positioning in Asian markets.
| Leading Market Players |
|---|
| Fresenius Medical Care |
| Baxter International |
| B. Braun |
| Toray Medical |
| Asahi Kasei Medical |
| NIPRO Corporation |
| Weigao Group |
| Haidylena |
| Allmed Medical |
| Others |
Supply & Pricing Matrix
Hollow fiber spinning technician scarcity in Germany and Japan compresses capacity expansion and widens labor-cost differentials between premium polysulfone membrane tiers and standard-grade alternatives. These workforce constraints feed directly into pricing spreads, with medical-grade certification requirements amplifying cost premiums for specialized manufacturing labor.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared high-flux configurations from CE-marked alternatives and uncertified commodity grades. Price differentiation rests on biocompatibility certification tier and captive resin supply integration, with Fresenius Medical Care's backward integration sustaining margin premiums unavailable to non-integrated competitors. Cost compression in the economy tier is intensifying because Chinese domestic manufacturers scale polysulfone membrane fabrication for emerging market tenders. Dialysis chains in the United States exhibit lowest price sensitivity due to Medicare bundled payment structures, while hospital systems in emerging markets face acute budget constraints.
Supply Chain Analysis
Regional distribution centers in Ohio and Baden-Württemberg anchor hub-and-spoke patterns serving Fresenius and DaVita clinic networks with 48-hour replenishment cycles. Geographic supply concentration clusters in Germany, Japan, and China, with medical-grade polysulfone resin production captive to three chemical producers. Raw material dependencies center on bisphenol-A derivatives, medical-grade solvents, and gamma-sterilization isotope supply. Single-source vulnerability in medical-grade polysulfone resin exposes dialyzer manufacturers to allocation risk during chemical plant turnarounds. Distribution runs through direct manufacturer-to-chain contracts for institutional purchasers, with regional medical distributors retaining relevance in fragmented hospital procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hollow fiber dialyzers market functions as a regulatory compounder, with FDA's 510(k) pathway modernization and EU MDR clinical evidence demands structurally elevating capital barriers for new membrane technologies. These regulatory milestones pull demand toward pre-cleared, clinically validated configurations.
For Market Incumbents: Deepen captive polysulfone resin supply arrangements to defend margin concentration against emerging Chinese membrane manufacturers scaling cost-competitive production. Prioritize certification investment in polyethersulfone-polymer blending capabilities to anchor premium positioning as biocompatibility standards tighten beyond baseline FDA requirements. For New Entrants and Emerging Players: Capture home dialysis reimbursement parity momentum in the United States by developing compact dialyzer footprints compatible with patient-managed residential treatment protocols. Target German and United Kingdom online specialty medical platforms as the most penetrable channel for patient-direct supply, leveraging prescription verification infrastructure already established for home care segments. For Investors and Strategic Acquirers: Dialysis service networks are the most active acquirer in this space, consolidating membrane-to-device bundled supply relationships to bypass distribution intermediaries. Long-term viability hinges on positioning within vertically integrated value chains spanning resin production through clinic operations. Watch CMS payment model recalibration between in-center and home modalities as the inflection indicator for volume shift timing.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerated clearance timelines compress time-to-revenue for next-generation membrane technologies entering United States markets. |
| Backward Integration into Resin | Captive polysulfone supply insulates margin structure from chemical producer allocation risk and input cost volatility. |
| Hospital System Partnership | Direct contracting with Fresenius and DaVita clinic networks displaces traditional medical device distribution channel margins. |
| CE Marking Pathway | EU MDR enhanced clinical evidence demands extend certification timelines and elevate capital requirements for European market entry. |
| Reimbursement Strategy | CMS payment model parity between in-center and home dialysis modalities reshapes addressable volume toward residential care environments. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with dialysis chain procurement directors, biomedical engineers at hospital systems, hollow fiber spinning technicians, and GPO contracts managers with secondary validation against FDA 510(k) filings, CMS Medicare reimbursement databases, EU MDR notified body documentation, and customs trade records for medical-grade polysulfone resin. Bottom-up dialyzer shipment estimates and top-down dialysis patient population models were triangulated to anchor volume assumptions.
Comparable historical periods anchored the forecast window, with growth rates derived from segment-level elasticity modeling across membrane material grade, sterilization protocol, and end-user configuration dimensions. The analytical framework incorporated hollow fiber spinning capacity utilization, dialysis clinic fleet upgrade cycles, and home dialysis reimbursement policy trajectories as industry-specific forecast inputs throughout the projection horizon.
Underlying measurement precision varies by segment; single-use high-flux configurations in United States dialysis chains carry tighter precision than emerging market low-flux tenders with fragmented procurement data. Forecasts reflect documented assumptions regarding FDA clearance timelines, EU MDR certification pacing, and CMS payment model stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nephrology
Global Hemodialysis Market
Nephrology
Hemodialysis and Peritoneal Dialysis Market
Nephrology
South Africa Hemodialysis and Peritoneal Dialysis Market
Nephrology
Global Nephroblastoma Treatment Market
Nephrology
Nephrology Stents and Catheters Market
Nephrology
Nephrosclerosis Treatment Market
Nephrology
ICU-Acquired Acute Kidney Treatment Market
Nephrology
Dialysis Service Market
Nephrology
Radiation Nephropathy Treatment and Management Market
Nephrology
Arteriovenous Fistula Treatment Market
Nephrology
Dialysis Centers Market
Nephrology
Global Continuous Renal Replacement Therapy (CRRT) Market
Nephrology
Hemodialyzer Market
Nephrology
Peritoneal Dialysis Market
Nephrology
Global Dialyzer Market
Nephrology
Renal Insufficiency Treatment Market