
 Bunion Correction Systems Market | 2026-2036
Bunion Correction Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Bunion Correction Systems Market Intelligence
Aftermarket service revenue for revision hardware and implant maintenance is narrowing as manufacturers shift toward bundled procedural solutions. Stryker Corporation leverages its integrated surgical technologies platform to capture value across the operative episode. Zimmer Biomet Holdings, Inc. anchors its position through scale in orthopedic reconstruction, while Treace Medical Concepts, Inc. specializes in minimally invasive bunion-specific systems that differentiate on patient recovery metrics.
Bunion correction systems encompass implants, fixation devices, and orthotic appliances engineered to realign the first metatarsophalangeal joint, typically utilizing titanium or stainless steel alloys with porosity gradients to promote osseointegration. Their primary purpose is restoring biomechanical function while reducing postoperative recurrence rates in hallux valgus deformities. Surgical implants command the dominant margin pool due to premium pricing on locking plate and screw constructs, while minimally invasive surgery technology represents the fastest-expanding segment as surgeons seek reduced soft-tissue disruption and earlier weight-bearing protocols. Orthotic devices retain steady demand for non-operative management, though reimbursement compression limits margin expansion in that category.
FDA 510(k) premarket notification requirements govern implant safety and efficacy claims in the United States, while the EU Medical Device Regulation (MDR) imposes stricter clinical evidence standards for CE marking access across European markets. Japan's PMDA oversees pharmaceutical and medical device approvals through structured review pathways that prioritize local clinical data submission. Stakeholders must monitor evolving MDR transition timelines and payer coverage decisions for outpatient bunion procedures to align portfolio investments with regulatory and reimbursement trajectories.
Market Dynamics
Outpatient migration from hospitals to ambulatory surgical centers is compressing procedure economics and forcing manufacturers to bundle hardware with procedural support services. This structural shift rewards integrated platform vendors while squeezing standalone implant suppliers.
Growth Catalysts
- Aging Demographics:Germany, Japan, and the United States exhibit expanding patient pools eligible for hallux valgus intervention as life expectancy extends active lifestyle demands into later decades.
- FDA 510(k) Pathway:Streamlined premarket notification for orthopedic implants accelerates product iteration cycles and reduces regulatory capital requirements relative to PMA processes.
- Titanium Porous Constructs:Osseointegration-enhancing surface architectures improve fixation stability and enable earlier weight-bearing protocols that differentiate premium implant portfolios.
Market Restraints
- Reimbursement Compression:CMS and private payers in the United States are narrowing coverage differentials between open and minimally invasive techniques, constraining price premiums for novel approaches.
- Supply Concentration:High-grade titanium sponge production concentrates in China and Russia, exposing manufacturers to raw material availability volatility and geopolitical sourcing risk.
- Technical Limitation:Severe deformity classifications (hallux valgus angle exceeding 40 degrees) remain outside the indication range for percutaneous systems, capping addressable procedure volume.
Strategic Opportunities
- Underpenetrated Markets:India's urban centers show rising bunion procedure volumes as private hospital chains expand orthopedic service lines and middle-class insurance penetration deepens.
- EU MDR Transition:Stricter clinical evidence requirements for CE marking create competitive moats for manufacturers with established notified body relationships and robust post-market surveillance infrastructure.
- Digital Surgical Planning:Convergence of preoperative CT-based modeling with patient-specific instrumentation enables precision osteotomy execution that reduces operative time and hardware waste.
Industry Challenges
- Surgeon Training Bottleneck:Minimally invasive techniques require distinct tactile skill sets and fluoroscopy interpretation competence that extend proctoring timelines and slow adoption curves.
- MDR Compliance Timeline:Legacy implant portfolios face recertification deadlines under EU Medical Device Regulation that strain clinical affairs resources and threaten market continuity for smaller manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bunion Correction Systems Market |
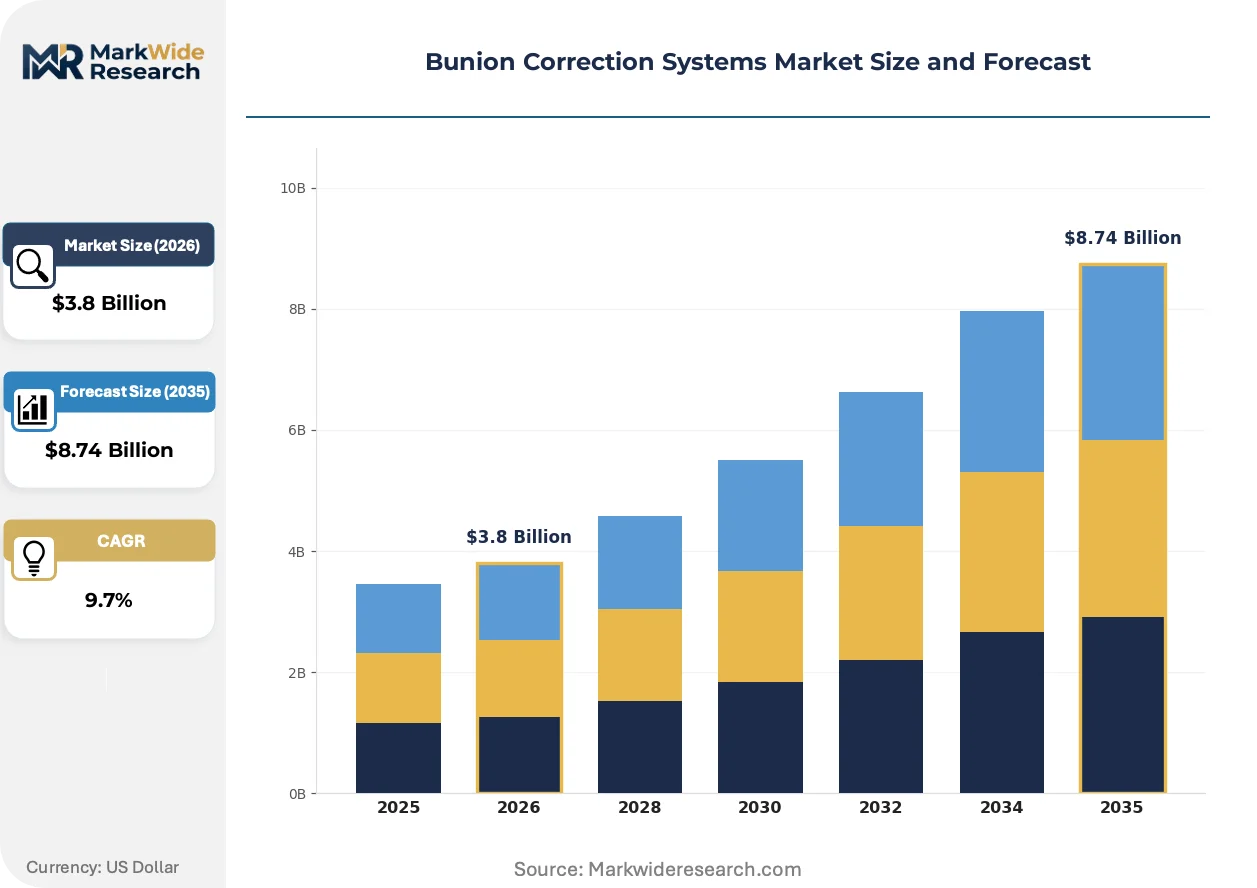
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Implants, Orthotic Devices, Braces, Compression Sleeves Application: Podiatry Clinics, Hospitals, Ambulatory Surgical Centers, Rehabilitation Centers End User: Patients, Healthcare Professionals, Orthopedic Surgeons, Physical Therapists Technology: Minimally Invasive Surgery, Traditional Surgery, Laser Therapy, Robotic Surgery |
| Companies Covered | Johnson & Johnson Services, Inc., Smith+Nephew plc, Zimmer Biomet Holdings, Inc., CONMED Corporation, Paragon 28, Inc., Stryker Corporation, Treace Medical Concepts, Inc., Enovis Corporation, Arthrex, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bunion Correction Systems Market Strategic Shifts & Innovations
Hardware commoditization is pushing competitive differentiation toward intraoperative technology and postoperative monitoring capabilities. Vendors now compete on episode-of-care outcomes rather than implant metallurgy alone.
Patient-specific instrumentation is migrating from experimental niches toward standard-of-care positioning in high-volume orthopedic centers. Academic medical centers in the United States and Germany are adopting 3D-printed surgical guides for complex revision cases. This migration from conventional instrumentation is compressing operative variability and reducing fluoroscopy exposure for surgical teams.
EU Medical Device Regulation is imposing stricter clinical evidence thresholds for CE marking renewal that favor manufacturers with deep post-market surveillance capabilities. Mid-tier suppliers without dedicated clinical affairs infrastructure face portfolio rationalization or partnership dependency. Implant categories with limited historical registry data are experiencing the steepest compliance cost escalation.
Hospital procurement committees are consolidating vendor relationships to reduce supply chain complexity and capture volume-based pricing concessions. Integrated delivery networks in the United States are replacing fragmented supplier rosters with single-source contracts for bunion procedure kits. This concentration dynamic is most visible in the southeastern United States where health system mergers have compressed eligible vendor pools by half within three years.
Bunion Correction Systems Market Segmentation
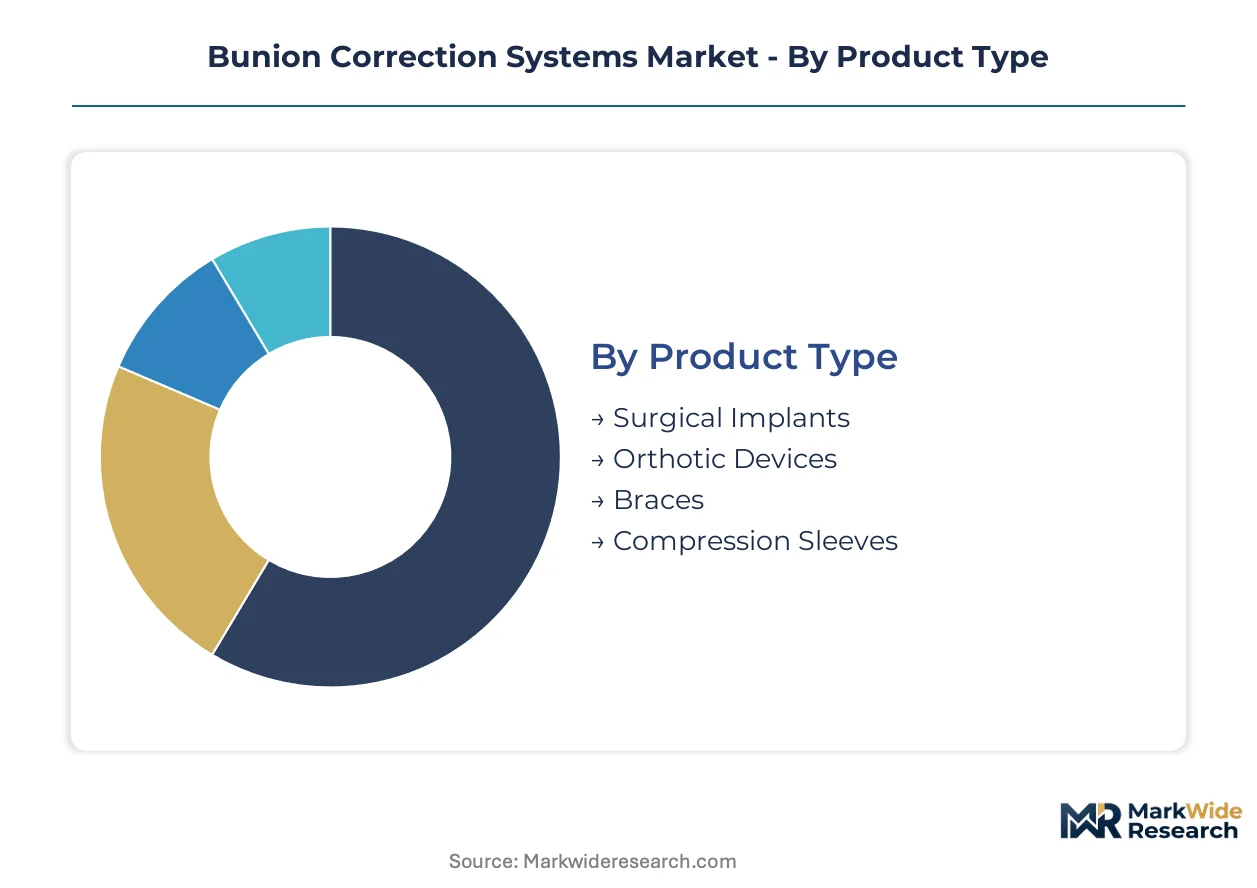
Segmentation reveals how bunion correction systems fragment across intervention intensity, care setting economics, and user sophistication. Each dimension carries distinct margin profiles and regulatory exposure that shape portfolio prioritization for manufacturers.
Product Type:
The use-case spectrum spans acute surgical intervention through chronic symptom management, with reimbursement intensity inversely correlated to invasiveness.
- Surgical Implants:Titanium and stainless steel locking plates, screws, and intramedullary devices with porous surface architectures engineered for osseointegration. Demand concentrates in ambulatory surgical centers across the United States and Germany, where bundled payment models reward durable fixation that reduces revision rates.
- Orthotic Devices:Custom-molded and prefabricated shoe inserts, toe spacers, and night splints designed for non-operative deformity management. Adoption clusters in Japan's aging urban populations where conservative first-line protocols dominate reimbursement pathways.
- Braces:Rigid and semi-rigid external stabilization systems for postoperative immobilization or progressive correction.
- Compression Sleeves:Elastic textile garments providing edema control and proprioceptive feedback during recovery.
The dominant share belongs to Surgical Implants, while Minimally Invasive Surgery technology is gaining share fastest through outpatient migration.
Application:
Care setting economics create tiered pricing structures where facility reimbursement rates dictate hardware procurement budgets.
- Ambulatory Surgical Centers:Freestanding facilities optimized for same-day discharge and episode-of-care cost containment. Volume is climbing fastest in the southeastern United States as integrated delivery networks consolidate orthopedic procedures away from hospital campuses.
- Hospitals:Inpatient and outpatient departments with comprehensive surgical infrastructure for complex deformity classifications. Demand persists in Germany where statutory health insurance maintains favorable reimbursement for hospital-based procedures.
- Podiatry Clinics:Office-based practices focusing on conservative management and minor surgical interventions.
- Rehabilitation Centers:Postoperative physical therapy facilities emphasizing gait retraining and functional restoration.
Ambulatory Surgical Centers now capture the dominant procedure volume, though Hospitals retain the highest-complexity cases.
End User:
Decision-making authority fragments across clinical prescribers, institutional procurement committees, and direct-to-consumer channels.
- Orthopedic Surgeons:Fellowship-trained specialists with authority over implant selection and operative technique. Preference formation in the United States increasingly flows through value analysis committees at integrated delivery networks.
- Healthcare Professionals:Podiatrists, nurse practitioners, and physician assistants managing conservative care pathways. Concentration is highest in Japan's primary care gatekeeper system where referral patterns shape specialist access.
- Patients:End beneficiaries whose out-of-pocket exposure varies by insurance design and procedure setting.
- Physical Therapists:Rehabilitation specialists influencing postoperative protocol adherence and device utilization.
Orthopedic Surgeons command the dominant purchasing influence, while direct patient decision-making is expanding through cash-pay cosmetic bunion procedures.
Technology:
Technical sophistication stratifies across tissue disruption levels, visualization requirements, and capital equipment intensity.
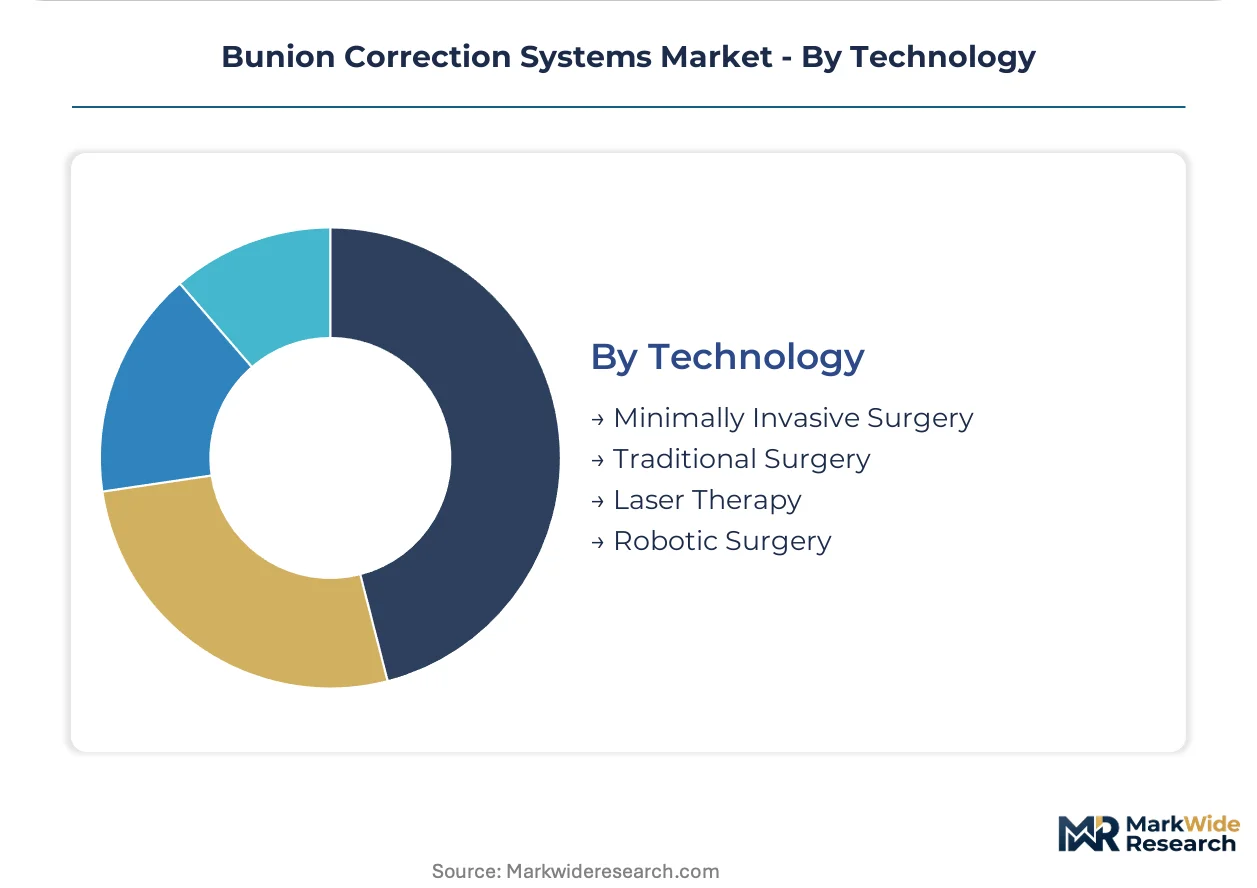
- Minimally Invasive Surgery:Percutaneous techniques utilizing fluoroscopic guidance and specialized burr systems for osteotomy execution. Adoption concentrates in academic medical centers in Germany and the United States where proctoring infrastructure supports skill acquisition.
- Traditional Surgery:Open chevron and scarf osteotomies with direct visualization and rigid internal fixation. Volume persists where severe deformity classifications exceed percutaneous indication thresholds.
- Laser Therapy:Low-level and ablative laser applications for soft tissue management and pain modulation.
- Robotic Surgery:Computer-navigated and autonomous systems for precision osteotomy planning and execution.
Traditional Surgery retains the dominant procedure base, though Minimally Invasive Surgery represents the steepest expansion trajectory as training pipelines mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies. United States buyers absorb premium minimally invasive systems, while India's cost-conscious market favors standard fixation hardware. Germany and Japan occupy intermediate positions where reimbursement quality determines procurement budgets.
United States
Ambulatory surgical centers in Texas and Florida drive fastest procedure volume growth as integrated delivery networks consolidate orthopedic services away from hospital campuses. FDA 510(k) premarket notification pathways accelerate product iteration cycles for domestic manufacturers. Nashville and Phoenix surgical clusters now perform majority of bunion procedures in freestanding facilities.
Germany
Statutory health insurance maintains favorable reimbursement for hospital-based procedures, preserving inpatient volume despite outpatient migration elsewhere. EU Medical Device Regulation imposes stricter clinical evidence thresholds for CE marking renewal that favor established manufacturers. Bavarian medical device clusters around Munich and Erlangen concentrate notified body relationships and post-market surveillance infrastructure.
Japan
Aging urban populations in Tokyo and Osaka sustain conservative first-line protocols that privilege orthotic devices over surgical intervention. PMDA structured review pathways prioritize local clinical data submission, extending approval timelines for foreign manufacturers. Nagoya orthopedic centers pioneer hybrid approaches combining traditional osteotomy with percutaneous techniques.
India
Private hospital chains in Mumbai and Delhi expand orthopedic service lines as middle-class insurance penetration deepens. Central Drugs Standard Control Organization regulates medical device imports through escalating quality certification requirements. Chennai and Hyderabad manufacturing zones attract contract production of standard-grade titanium fixation hardware for domestic and export markets.
United Kingdom
National Health Service procurement frameworks compress hardware margins while prioritizing episode-of-care cost containment over implant premiumization. Medicines and Healthcare products Regulatory Agency aligns with EU MDR standards post-Brexit, maintaining stringent clinical evidence requirements. London and Manchester academic medical centers concentrate revision case complexity and patient-specific instrumentation adoption.
Bunion Correction Systems Market Key Industry Players
Integrated platform vendors and standalone implant specialists split the market into distinct competitive spheres. Hospital procurement consolidation rewards vendors offering bundled procedural solutions spanning hardware, instrumentation, and training infrastructure. Three archetypes dominate: diversified orthopedic conglomerates with scale advantages, minimally invasive technology specialists with differentiated recovery protocols, and regional contract manufacturers serving price-sensitive segments. Competitive dynamics center on M&A activity absorbing niche technology assets and strategic partnerships securing ambulatory surgical center distribution.
Within the diversified orthopedic tier, Stryker Corporation and Zimmer Biomet Holdings occupy positions exemplifying scale-driven platform strategies. Treace Medical Concepts represents the minimally invasive specialist archetype with bunion-specific system focus. Among these, Stryker leverages integrated surgical technologies across the operative episode, Zimmer Biomet anchors through reconstruction scale, and Treace differentiates on patient recovery metrics.
| Leading Market Players |
|---|
| Johnson & Johnson Services, Inc. |
| Smith+Nephew plc |
| Zimmer Biomet Holdings, Inc. |
| CONMED Corporation |
| Paragon 28, Inc. |
| Stryker Corporation |
| Treace Medical Concepts, Inc. |
| Enovis Corporation |
| Arthrex, Inc. |
| Others |
Cost & Logistics Intelligence
Geopolitical sourcing risk in high-grade titanium sponge production determines both margin tier stratification and inventory positioning across implant manufacturers. China and Russia concentrate sponge supply, forcing buyers to absorb volatility premiums or pursue backward integration into alternative feedstock channels.
Pricing Analysis
Aftermarket service revenue for revision hardware and implant maintenance now drives lifetime value capture as manufacturers bundle procedural support with hardware sales. Three-tier pricing structure across premium porous titanium constructs, standard stainless steel fixation, and economy orthotic appliances reflects certification grade and osseointegration performance. Cost compression in standard fixation tiers intensifies as ambulatory surgical centers consolidate vendor relationships and demand volume concessions. Hospital procurement committees exhibit lowest price sensitivity for patient-specific instrumentation, while cash-pay cosmetic bunion patients drive economy tier demand.
Supply Chain Analysis
Extended payment terms from Chinese titanium sponge producers strain working capital for mid-tier implant manufacturers without supply-chain finance facilities. Manufacturing concentration in China, Russia, and Japan feeds raw material dependencies for aerospace-grade titanium sponge, precision-machined instrumentation, and 3D-printed surgical guides. Single-source vulnerability in sponge supply exposes producers to export restriction risk and commodity price volatility. Distribution runs through integrated delivery networks in the United States, statutory health insurance channels in Germany, and private hospital chains in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Orthobiologic injectables and regenerative soft-tissue approaches threaten to displace mechanical fixation for mild-to-moderate deformities, compelling incumbent implant manufacturers to defend procedural indications through outcome differentiation.
For Market Incumbents: Insulate core revenue streams by deepening surgeon training infrastructure to extend proctoring relationships and slow orthobiologic substitution. Pursue backward integration into titanium sponge processing to reduce China-Russia sourcing exposure. Anchor hospital system partnerships through bundled episode-of-care contracts that embed implants within comprehensive service agreements. For New Entrants and Emerging Players: India's urban private hospital chains represent the most penetrable entry point for standard-grade fixation hardware as orthopedic service lines expand and insurance penetration deepens. Target podiatry clinic networks in Japan's aging metropolitan corridors where conservative-first protocols create orthotic device demand. Differentiate through digital surgical planning companions that reduce operative time and fluoroscopy exposure. For Investors and Strategic Acquirers: EU MDR recertification deadlines reshape the acquisition landscape by straining clinical affairs resources at mid-tier manufacturers and forcing portfolio rationalization. Target notified body-certified specialists with established post-market surveillance infrastructure and CE-marked porous titanium portfolios. Monitor MDR transition compliance cost escalation as the inflection signal for distressed asset availability.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Streamlined premarket notification reduces regulatory capital requirements for porous titanium construct iterations. |
| CE Marking Pathway Investment | Robust clinical evidence packages satisfy EU MDR stricter thresholds and extend market continuity. |
| Hospital System Partnership | Integrated delivery network contracts embed implants within bundled payment models across southeastern United States clusters. |
| Software Companion Development | CT-based preoperative modeling platforms differentiate precision osteotomy execution and reduce hardware waste. |
| Reimbursement Strategy | CMS coverage pathway optimization for minimally invasive techniques preserves price premiums against open procedure compression. |
Research Approach
A spread of perspectives from orthopedic surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers converged on the working assumptions underlying demand projections. Primary interviews with ambulatory surgical center administrators and regulatory affairs specialists at notified bodies combined with secondary validation against FDA 510(k) filings, EU MDR transition guidance documents, CMS Medicare reimbursement databases, and hospital procurement contract registries. Bottom-up procedure volume estimates triangulated with top-down implant shipment data across the analysis window.
Demand-supply balance modeling anchored forecasts to aging demographic trajectories in the United States, Germany, and Japan against titanium sponge production capacity and machining throughput constraints. Segmentation dimensions spanned intervention intensity, care setting economics, technology sophistication, and regional reimbursement quality. CAGRs derived from historical procedure growth rates adjusted for outpatient migration acceleration and training pipeline maturation. Forecast inputs incorporated PMDA approval timeline assumptions for foreign manufacturers and private insurance penetration curves in India.
Practitioners should monitor MDR recertification compliance rates, CMS minimally invasive coverage decisions, and orthobiologic clinical trial readouts for early signals of structural shift. Forecasts reflect documented assumptions regarding surgeon adoption curves and reimbursement stability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Digital Respiratory Devices Market
Medical Devices
North America Electric Wheelchair Market
Medical Devices
Electronic Pediatric Nebulizer Market
Medical Devices
Transcatheter Aortic Valve Implantation (TAVI) Market
Medical Devices
Global Pressure Relief Devices Market
Medical Devices
Global Cochlear Implant Market
Medical Devices
Transcranial Doppler Devices Market
Medical Devices
Asia-Pacific Micro Invasive Glaucoma Surgery (MIGS) Devices Market
Medical Devices
Asthma Device Market
Medical Devices
Wearable Blood Pressure Monitor Market
Medical Devices
Nerve Stimulators Market
Medical Devices
Spinal Traction Market
Medical Devices
Medical Coatings for Implants Market
Medical Devices
Nano Healthcare Technology for Medical Equipment Market
Medical Devices
Veterinary Stereotactic Radiosurgery System Market
Medical Devices
Infertility Treatment Devices Market