
 Global Hepatorenal Syndrome Treatment Market | 2026-2036
Global Hepatorenal Syndrome Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hepatorenal Syndrome Treatment Market Intelligence
Expanded clinical trial infrastructure across Western Europe, particularly in Germany and France, is tilting the therapeutic development landscape toward novel vasoconstrictor agents. Ferring Pharmaceuticals leverages its expertise in peptide-based therapeutics for this segment. BioVie specializes in developing treatments targeting chronic liver diseases linked to HRS. Grifols sustains its market position through its extensive portfolio of plasma-derived albumin products, essential for combination therapy.
Hepatorenal syndrome treatment involves managing acute kidney failure in patients with advanced liver disease, primarily through therapies that reverse renal vasoconstriction. The standard of care often combines a vasoconstrictor agent, such as terlipressin, with intravenous albumin to restore circulatory function. Vasoconstrictors and Albumin Therapy form the core of the treatment type segment. The therapy area is dominated by interventions for Type 1 HRS, which requires immediate hospitalization and intensive care, making hospitals the principal end-user setting.
Regulatory pathways from the Food and Drug Administration (FDA) in the United States and the European Medicines Agency (EMA) in Europe define market entry strategies. These frameworks, particularly through orphan drug designations, incentivize development by offering market exclusivity and streamlined review processes. Consequently, navigating evolving clinical trial endpoint requirements for demonstrating efficacy in HRS treatment remains a critical focus for all therapy developers.
Market Dynamics
The central force shaping the hepatorenal syndrome treatment market is the regulatory incentive structure for rare diseases. Orphan drug designations from the FDA and EMA are de-risking investment and accelerating the clinical development of novel vasoconstrictor agents and combination therapies.
Growth Catalysts
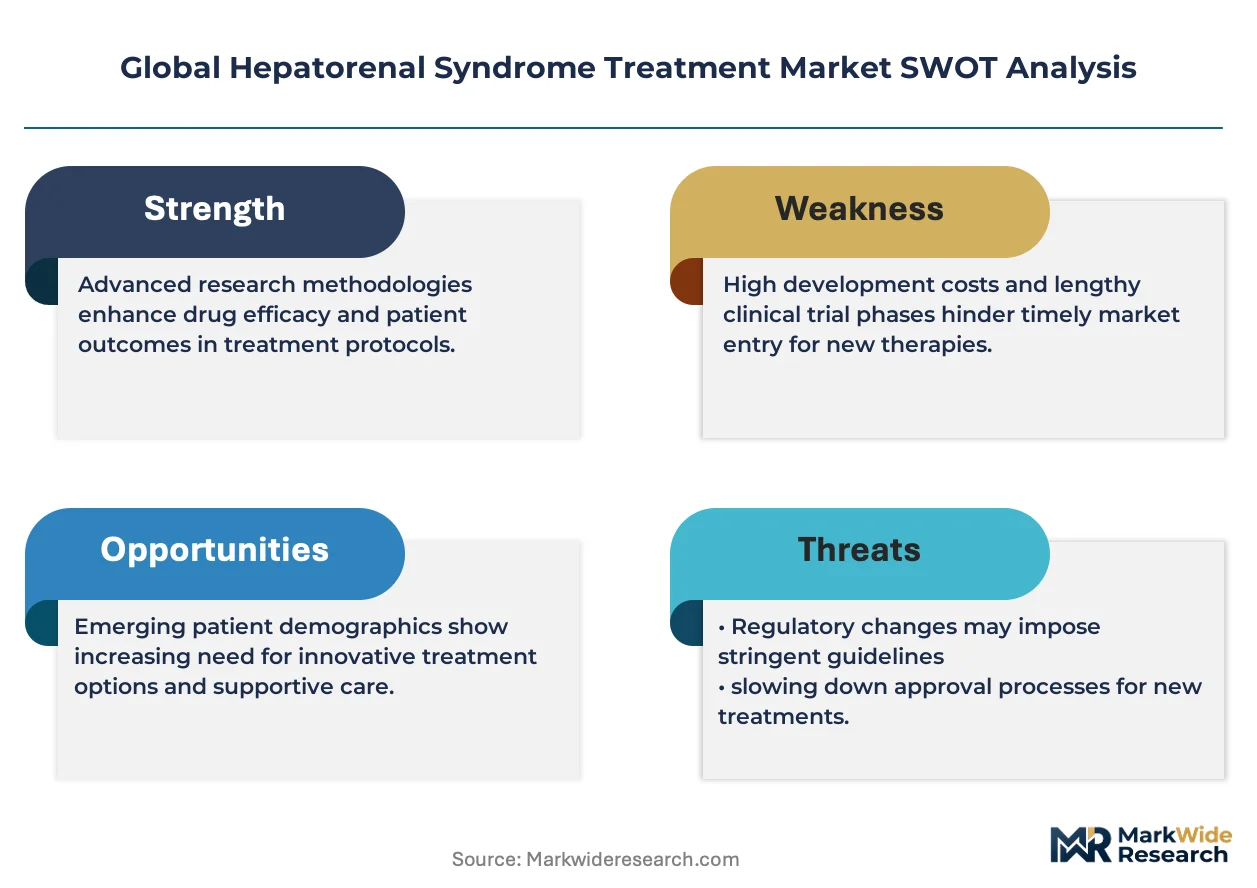
- Orphan Drug Legislation:Frameworks like the FDA's Orphan Drug Act provide market exclusivity and streamlined review processes, encouraging developers to invest in therapies for the relatively small HRS patient population.
- Therapeutic Pipeline Expansion:A growing pipeline of novel peptide-based vasoconstrictors and alternative agents targeting different pathophysiological pathways promises improved efficacy and safety profiles over existing options.
- Specialized Care Infrastructure:The proliferation of specialized liver centers and transplant units improves early diagnosis and protocol-driven management of HRS, increasing the addressable patient pool for approved therapies.
Market Restraints
- High Treatment Costs:The combined expense of branded pharmaceuticals, intensive care unit stays, and requisite human albumin infusions creates significant cost barriers, limiting accessibility in healthcare systems with stringent budget controls.
- Diagnostic Complexity:Differentiating HRS from other forms of acute kidney injury in cirrhotic patients remains a clinical challenge, often leading to delayed or inappropriate treatment and compromising patient outcomes.
- Albumin Supply Volatility:As a plasma-derived product, the supply and cost of human albumin are subject to fluctuations in plasma donations, posing a potential constraint for its use in essential combination therapy.
Strategic Opportunities
- Non-Invasive Diagnostics:Developing and validating novel urinary or plasma biomarkers for early HRS detection represents a significant opportunity to improve patient stratification and enable earlier therapeutic intervention.
- Geographic Expansion:Untapped markets in Asia-Pacific, where the prevalence of chronic liver disease is high, offer substantial growth potential for companies able to navigate local regulatory and reimbursement landscapes.
- Type 2 HRS Therapies:The development of treatments specifically for Type 2 HRS, a more chronic and indolent form, addresses a clinical need that is secondary to the acute focus on Type 1 HRS.
Industry Challenges
- Clinical Trial Endpoint Definition:Reaching a consensus between developers and regulators, including the FDA and EMA, on clinically meaningful endpoints for HRS trials beyond serum creatinine levels remains a persistent hurdle.
- Specialist Scarcity:A shortage of trained hepatologists and critical care nephrologists with expertise in managing HRS limits the optimal delivery of care, especially outside of major academic medical centers.
- Reimbursement Hurdles:Securing favorable reimbursement status for new, high-cost HRS therapies from public and private payers requires extensive health economic data, often delaying patient access after regulatory approval.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hepatorenal Syndrome Treatment Market |
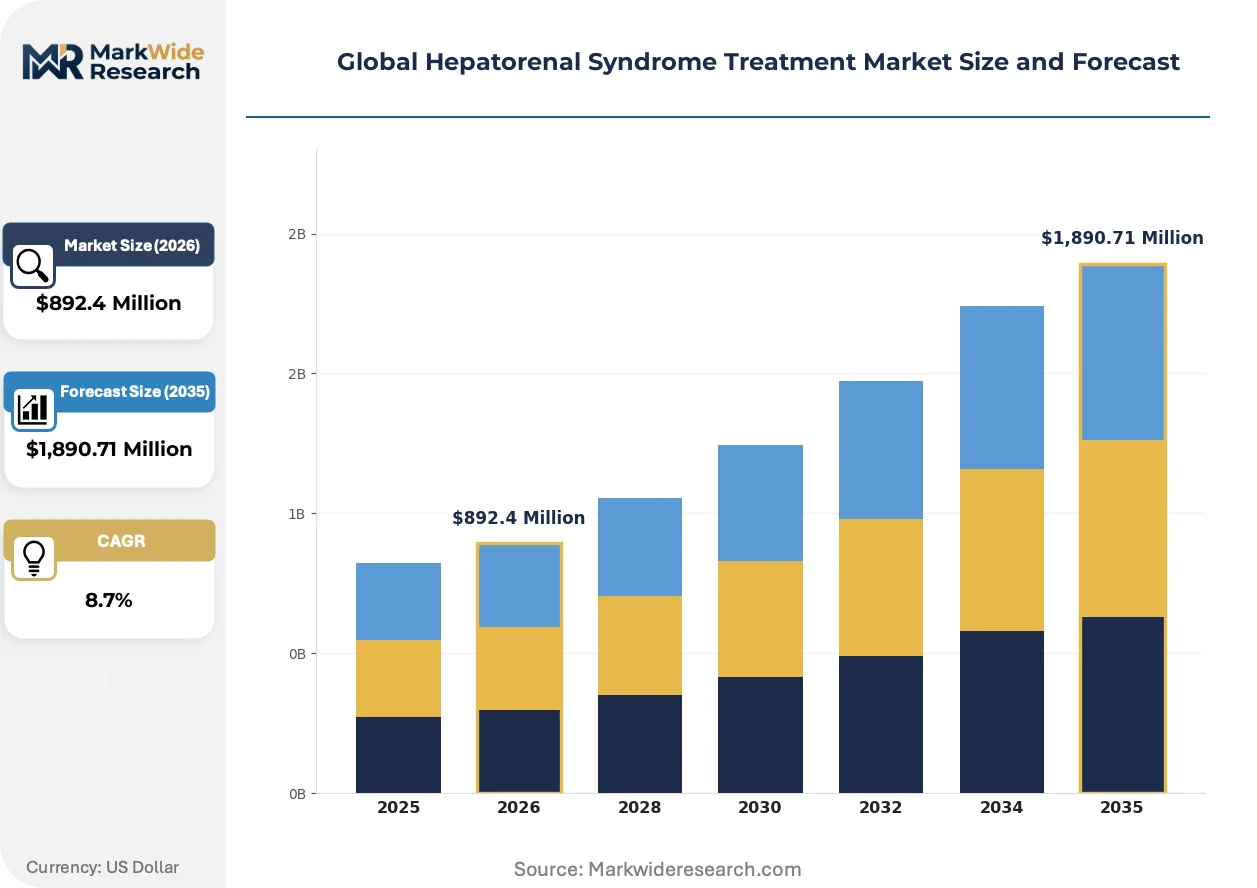
| Market Size in 2026 | $892.4 Million |
| Market Size in 2035 | $1,890.71 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: Vasoconstrictors, Albumin Therapy, Liver Transplant, Renal Replacement, Supportive Care Therapy Area: Type 1 HRS, Type 2 HRS, Acute Kidney Injury, Chronic Kidney Disease, Cirrhosis Management End User: Hospitals, Specialized Clinics, Diagnostic Centers, Home Healthcare, Rehabilitation Centers Delivery Mode: Intravenous, Oral, Subcutaneous, Intramuscular, Transplantation Procedures |
| Companies Covered | Baxter International, Cumberland Pharmaceuticals, Mallinckrodt Pharmaceuticals, Orphan Therapeutics, BioVie, Grifols, Fresenius Medical Care, Ferring Pharmaceuticals, CSL Behring, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hepatorenal Syndrome Treatment Market Strategic Shifts & Innovations
The market is advancing from supportive care towards targeted pharmacological interventions that address the specific pathophysiological mechanisms of hepatorenal syndrome. This evolution is driven by a deeper biological understanding and a clearer regulatory path to market, fostering innovation in both therapeutics and diagnostics.
Novel therapeutic agents targeting systemic inflammation and oxidative stress are being explored as adjuncts or alternatives to pure vasoconstrictors. Academic research centers and specialized biopharmaceutical firms are actively advancing these compounds through early and mid-stage clinical trials. This focus on multiple disease pathways is hybridizing the treatment model from simple hemodynamic correction toward a more complex, multi-modal intervention strategy.
Regulatory precedents, such as the FDA's first drug approval for HRS, have fundamentally clarified development pathways in the United States. This action establishes a benchmark for demonstrating efficacy, particularly concerning the reversal of kidney dysfunction. Consequently, therapy developers worldwide are now aligning their clinical trial designs with these established endpoints to improve their probability of success in the pivotal U.S. market.
A notable behavioral shift is underway in how hospital systems assess new HRS therapies, moving beyond acquisition cost to a total cost-of-care framework. This value-based evaluation incorporates a drug's ability to reduce ICU days, avoid dialysis, and successfully bridge patients to liver transplantation. This holistic procurement model is most apparent within large, integrated health networks in North America and Western Europe.
Global Hepatorenal Syndrome Treatment Market Segmentation
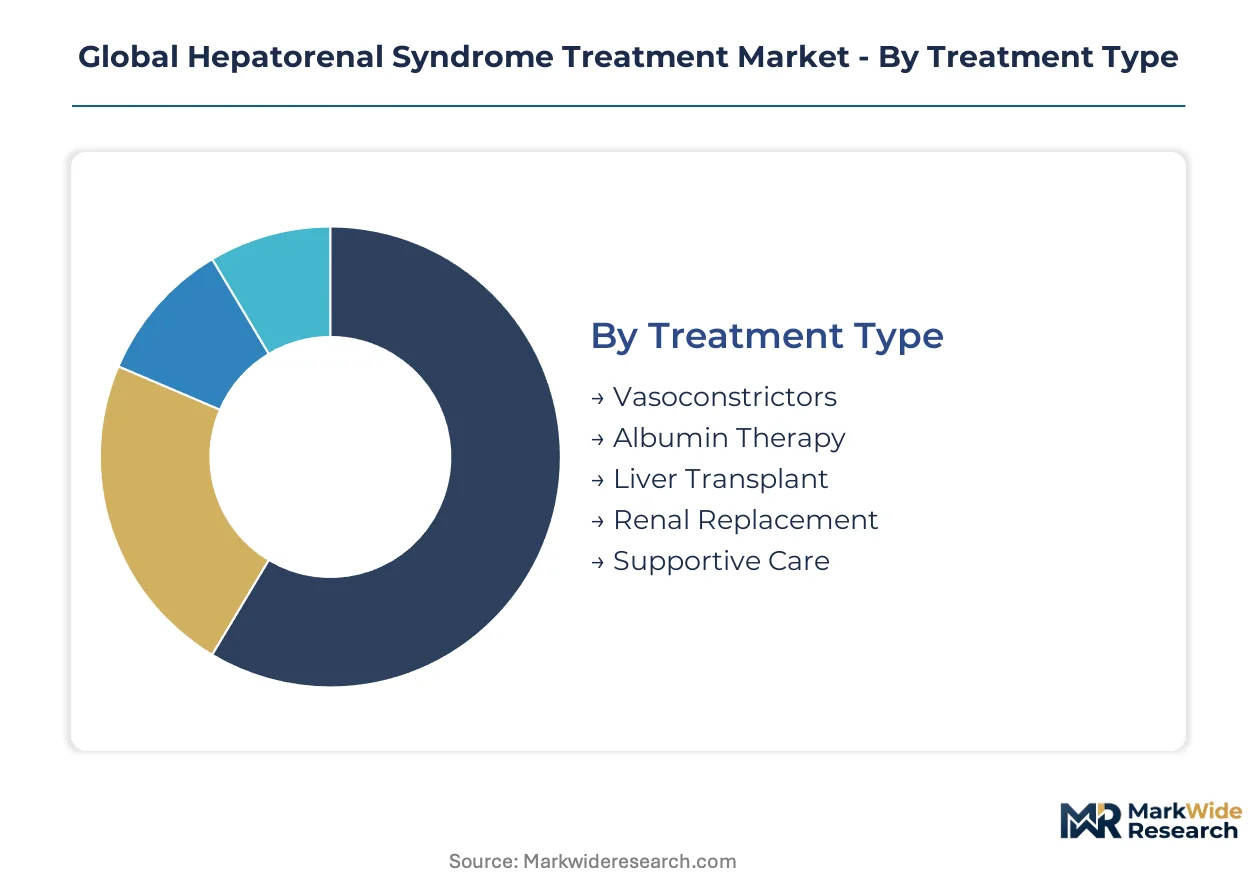
The global hepatorenal syndrome treatment market is segmented to reflect the diverse approaches required for patient care, from acute interventions to long-term management. Understanding these segments helps stakeholders identify specific patient needs, refine product development, and optimize market entry strategies across different therapeutic modalities and end-user settings.
Treatment Type:
After-sales service intensity varies significantly across different hepatorenal syndrome treatment modalities, impacting patient management and long-term care.
- Vasoconstrictors:These peptide-based agents or synthetic analogs induce systemic vasoconstriction, primarily targeting renal blood flow restoration. Demand concentrates in hospital settings, driven by the need for rapid hemodynamic stabilization in acute HRS.
- Albumin Therapy:This involves the intravenous administration of human plasma-derived albumin proteins, crucial for maintaining oncotic pressure and circulatory volume. Demand is high in critical care units, linked to its role in essential combination therapy.
- Liver Transplant:This represents the definitive cure for end-stage liver disease, effectively reversing HRS by replacing the diseased organ.
- Renal Replacement:Dialysis or continuous renal replacement therapy supports kidney function in severe renal failure when other interventions are insufficient.
- Supportive Care:Symptomatic management and general medical interventions improve patient comfort and mitigate complications while addressing underlying conditions.
Vasoconstrictors holds the largest share; momentum sits with Albumin Therapy.
Therapy Area:
Cost tiering influences the selection of therapeutic interventions based on the specific manifestation of hepatorenal syndrome.
- Type 1 HRS:This rapidly progressive acute kidney injury in patients with cirrhosis requires urgent, intensive intervention due to its severity. Demand for intensive care and specific vasoconstrictors concentrates in specialized liver centers.
- Type 2 HRS:This moderately progressive kidney dysfunction in cirrhosis is characterized by a more chronic, indolent course requiring sustained management. Demand for long-term management strategies and less aggressive interventions is gaining traction.
- Acute Kidney Injury:Sudden and severe deterioration of kidney function often requires immediate medical attention and close monitoring.
- Chronic Kidney Disease:Progressive loss of kidney function over time necessitates ongoing management to prevent end-stage renal disease.
- Cirrhosis Management:Comprehensive care strategies address the underlying liver disease that predisposes patients to HRS.
Interventions for Type 1 HRS dominate the market, while Type 2 HRS therapies are expanding most quickly.
End User:
The application of hepatorenal syndrome treatments is primarily concentrated within institutional settings due to the complexity of patient care.
- Hospitals:These acute care facilities provide comprehensive medical and surgical services, including intensive care units crucial for HRS patients. Demand is highest here for all HRS therapies, driven by the need for continuous monitoring and specialized procedures.
- Specialized Clinics:These outpatient or inpatient facilities focus on specific medical conditions like liver disease or nephrology, offering targeted expertise. Demand for early diagnosis and follow-up care for HRS patients is increasing in these dedicated centers.
- Diagnostic Centers:Facilities offering advanced imaging and laboratory testing are crucial for HRS diagnosis and differential assessment.
- Home Healthcare:Limited but emerging services provide supportive care and monitoring for stable HRS patients post-discharge.
- Rehabilitation Centers:Post-acute care facilities assist patients in recovery from severe illness or transplantation, focusing on functional improvement.
Hospitals represent the predominant end-user segment, with specialized clinics demonstrating significant growth.
Delivery Mode:
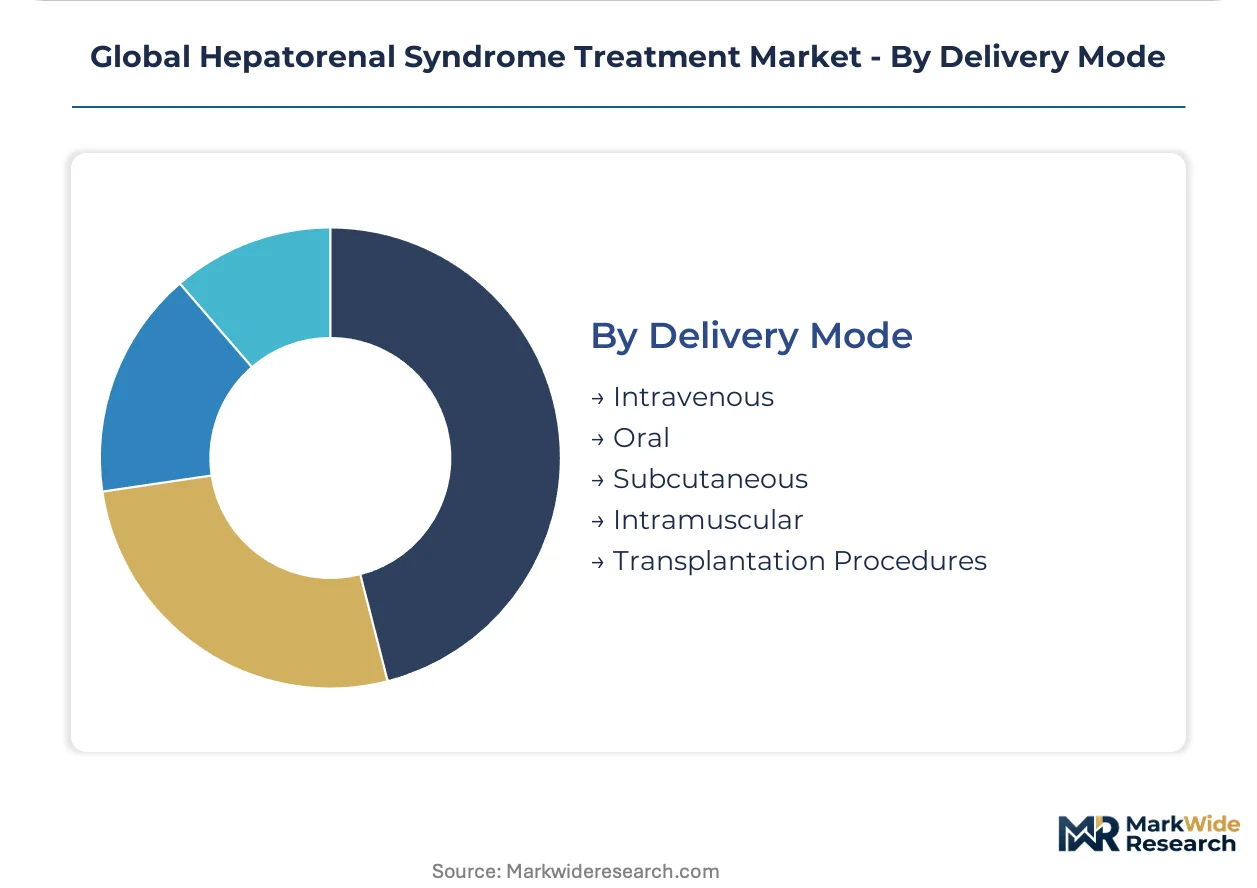
Volume of administration dictates the preferred delivery mode for hepatorenal syndrome treatments, optimizing for efficacy and patient comfort.
- Intravenous:This mode administers medications directly into a vein, ensuring rapid systemic distribution and immediate therapeutic effect. This mode is critical for vasoconstrictors and albumin therapy in acute HRS, requiring hospital-level care.
- Oral:Medications taken by mouth offer convenience for long-term or less acute management scenarios. Research into oral agents for Type 2 HRS or maintenance therapy could shift demand patterns.
- Subcutaneous:Injection of medication into the tissue layer just under the skin is suitable for certain peptide-based therapies.
- Intramuscular:Administration of drugs deep into muscle tissue is a less common but viable route for specific formulations.
- Transplantation Procedures:Surgical methods for organ replacement, including liver or kidney transplantation, represent a distinct delivery pathway.
Intravenous delivery remains the primary route, while oral administration methods are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supply-side concentration for hepatorenal syndrome treatments primarily centers on regions with advanced pharmaceutical research and development capabilities. These areas also possess sophisticated healthcare infrastructures capable of implementing complex treatment protocols. Key markets demonstrate robust regulatory support and a high prevalence of chronic liver diseases.
United States
Demand for advanced HRS therapies is particularly high in the United States due to significant chronic liver disease prevalence and a robust healthcare system. The FDA's orphan drug designation accelerates product development and market entry for novel agents. Biotech clusters in Boston and San Francisco drive innovation in peptide-based therapeutics.
Germany
Germany demonstrates substantial demand for hepatorenal syndrome treatments, supported by its expanded clinical trial infrastructure. The European Medicines Agency (EMA) framework facilitates the approval of new therapeutic agents across the region. Major pharmaceutical centers like Munich and Berlin are active in drug discovery and development.
Japan
Japan's demand for HRS treatments stems from its aging population and high standards of medical technology. The Pharmaceuticals and Medical Devices Agency (PMDA) streamlines approvals for critical care medications. Research institutions in Tokyo and Osaka contribute significantly to clinical studies and treatment advancements.
India
India exhibits a rising demand for hepatorenal syndrome management, driven by increasing chronic liver disease incidence. The Production Linked Incentive (PLI) scheme encourages domestic pharmaceutical manufacturing. Hyderabad and Mumbai are emerging as key hubs for generic and biosimilar drug production.
France
France prioritizes the development of novel vasoconstrictor agents, leveraging its strong research and development ecosystem. The Agence Nationale de Sécurité du Médicament et des produits de santé (ANSM) guides regulatory pathways for new therapies. Specialized liver centers in Paris and Lyon are critical for advanced HRS patient care.
Global Hepatorenal Syndrome Treatment Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, focusing on specific therapeutic agents and raw materials. The market exhibits a tiered structure, with established pharmaceutical giants and specialized biopharmaceutical firms operating across different segments. Strategic archetypes include companies leveraging extensive R&D capabilities for novel drug discovery and those focusing on plasma-derived products for essential combination therapies. Capacity expansion and strategic partnerships are dominant competitive moves among these diverse players.
Within the innovative biopharmaceutical segment, BioVie exemplifies firms specializing in developing treatments for chronic liver diseases linked to HRS. Ferring Pharmaceuticals represents a key player in peptide-based vasoconstrictor agents, leveraging its expertise in this therapeutic area. Grifols anchors the market for plasma-derived albumin products, which are critical for combination therapy and circulatory volume restoration. These companies collectively illustrate the varied approaches to addressing the complex needs of hepatorenal syndrome patients across different treatment modalities.
| Leading Market Players |
|---|
| Baxter International |
| Cumberland Pharmaceuticals |
| Mallinckrodt Pharmaceuticals |
| Orphan Therapeutics |
| BioVie |
| Grifols |
| Fresenius Medical Care |
| Ferring Pharmaceuticals |
| CSL Behring |
| Others |
Cost & Logistics Intelligence
Albumin supply volatility, stemming from plasma donations, directly influences treatment costs and patient accessibility within the hepatorenal syndrome market. This upstream constraint affects downstream margin distribution for combination therapies.
Pricing Analysis
FDA's orphan drug designation dictates the pricing tier structure for novel hepatorenal syndrome therapies, incentivizing high initial costs. The dominant pricing model is value-based, reflecting a drug's ability to reduce ICU days and avoid dialysis. Price differentiation stems from regulatory approval and brand premium for specialized vasoconstrictors. Pricing pressure is generally upward due to extensive R&D investments, while healthcare systems with stringent budget controls remain highly price-sensitive.
Supply Chain Analysis
Pharmaceutical manufacturers like Ferring Pharmaceuticals and Grifols hold significant capacity for hepatorenal syndrome treatments. Geographic supply concentration for advanced therapies centers on the United States and Western Europe, with India emerging for biosimilars. Raw material dependencies include human plasma for albumin and specialized peptides for vasoconstrictors. Albumin supply volatility represents a structural risk. Distribution runs through direct channels to hospitals and specialized clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hepatorenal syndrome treatment market faces significant challenges due to a scarcity of trained hepatologists and critical care nephrologists. This capability gap limits optimal care delivery and wider market penetration for advanced therapies.
For Market Incumbents: Pre-empt reimbursement hurdles by investing in robust health economic data demonstrating total cost-of-care benefits. Incumbents should also expand clinical trial infrastructure in Western Europe to accelerate novel agent development. This defends against emerging therapeutic pipeline expansion and diagnostic complexity, reinforcing market leadership in critical care.
For New Entrants and Emerging Players: Novel urinary or plasma biomarkers for early HRS detection represent a significant entry point for new players. Untapped markets in Asia-Pacific, with high chronic liver disease prevalence, offer substantial growth potential. A go-to-market angle focusing on Type 2 HRS therapies and local regulatory navigation will allow differentiation.
For Investors and Strategic Acquirers: Capital is best deployed toward specialized biopharmaceutical firms with robust pipelines in novel vasoconstrictor agents or non-invasive diagnostics. The long-term viability of this market is strong, driven by unmet medical needs and orphan drug incentives. Investors should watch for successful phase 3 clinical trial readouts for Type 2 HRS therapies as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Accelerate development of novel vasoconstrictors through expanded infrastructure in Germany. |
| Regulatory Approval Pathway | Align clinical trial designs with FDA established endpoints for improved U.S. market success. |
| Pipeline Diversification | Explore agents targeting systemic inflammation and oxidative stress as adjuncts to existing therapies. |
| Geographic Expansion | Target high-prevalence Asia-Pacific markets by navigating local regulatory and reimbursement landscapes. |
| Manufacturing Scale-Up | Secure stable supply chains for plasma-derived albumin products to support combination therapy. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FDA filings, EMA submissions, and medical journals. This approach involved extensive interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and specialized clinic directors. Data triangulation was performed using both bottom-up and top-down validation techniques.
Forecast inputs being considered include the incidence of chronic liver disease and the impact of orphan drug designations. The analytical framework incorporates quantitative modeling and scenario analysis across the projection horizon. Segmentation dimensions modeled include treatment type, therapy area, end-user, delivery mode, and regional regulatory clusters. Compound Annual Growth Rates were derived from historical market trends, therapeutic pipeline analysis, and expert projections.
Stress conditions across regulatory changes, albumin supply fluctuations, and clinical trial failures were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions documented regarding market dynamics and therapeutic advancements. Quarterly review of regulatory approvals and plasma supply data is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nephrology
Kidney Stone Extraction Balloon Market
Nephrology
Kidney Fibrosis Treatment Market
Nephrology
Aldosterone-Renin Screening Market
Nephrology
Nephrosclerosis Treatment Market
Nephrology
Hemodialysis Services Market
Nephrology
Chronic Kidney Disease Market
Nephrology
Global Renal Medical Devices and Services Market
Nephrology
US Continuous Renal Replacement Therapy Market
Nephrology
Membranous Nephropathy Treatment Market
Nephrology
Renal Insufficiency Treatment Market
Nephrology
Proteinuria Treatment Market
Nephrology
Nephrotic Syndrome Market
Nephrology
Ketoanalogue for Kidney Disease Market
Nephrology
Renal Denervation Market
Nephrology
End Stage Renal Disease Market
Nephrology
Hemodialysis and Peritoneal Dialysis Market