
 Aldosterone-Renin Screening Market | 2026-2036
Aldosterone-Renin Screening Market Size, Share, and Industry Trends Forecast 2026-2036
Aldosterone-Renin Screening Market Insights
High-sensitivity chemiluminescence immunoassay standards is reorganizing competitive expectations across the aldosterone-renin screening landscape. Siemens Healthineers leverages its automated analyzer installed base to sustain recurring reagent revenue in European hospital networks. Roche anchors its position through integrated cobas platform workflows that reduce manual sample handling. Beckman Coulter competes on throughput density, targeting high-volume reference laboratories with batch-processing configurations.
Aldosterone-renin screening encompasses quantitative biochemical assays that measure plasma aldosterone concentration, plasma renin activity, or direct renin concentration to calculate aldosterone-to-renin ratios, typically employing chemiluminescence detection limits below one picogram per milliliter for clinical diagnostic utility in endocrine hypertension evaluation. Chemiluminescence immunoassays command the dominant product position due to superior precision and throughput, while point-of-care devices represent the fastest-expanding segment as decentralized cardiovascular risk assessment gains traction in specialty clinics. Diagnostic laboratories absorb the majority of end-user demand, though nephrology departments are emerging as concentrated margin pools where bundled electrolyte-renal testing protocols justify premium platform placements.
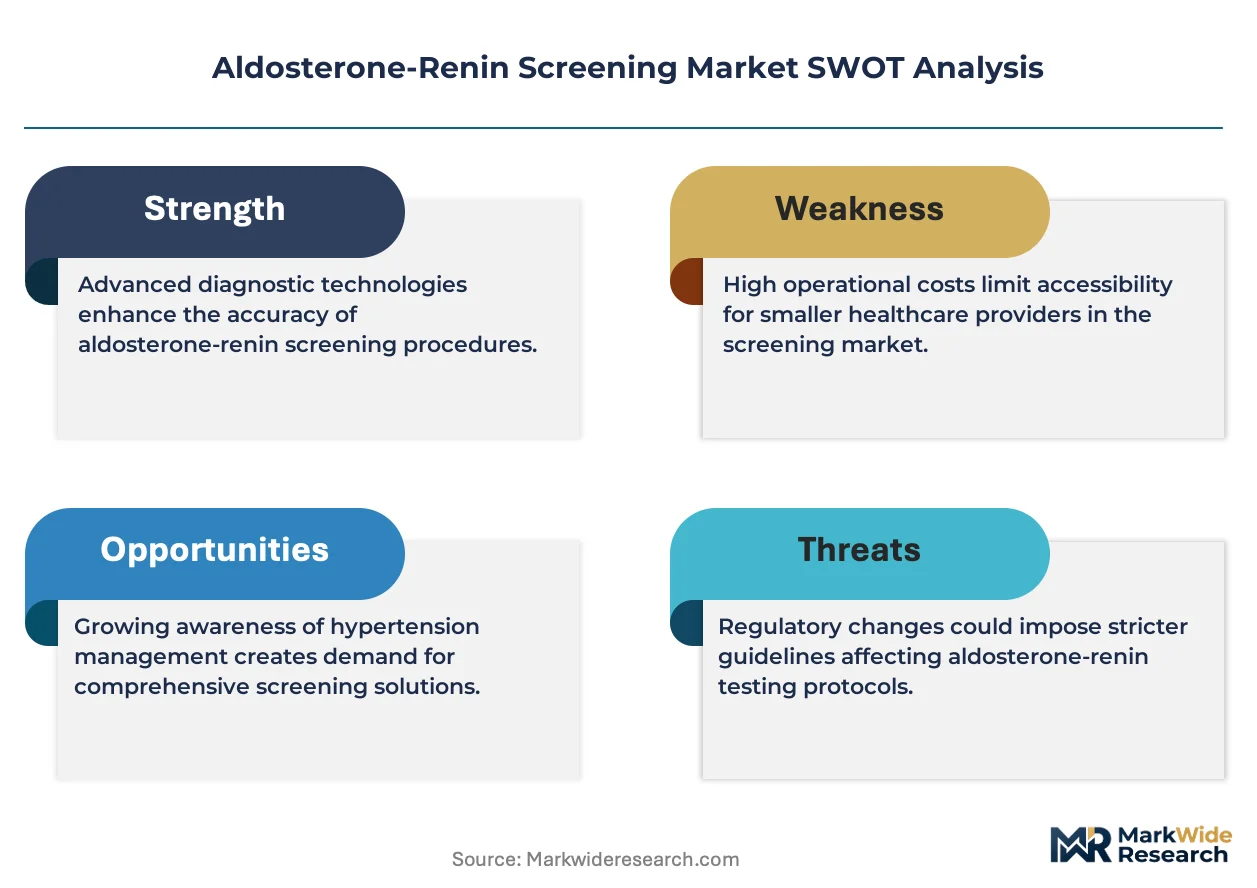
The FDA's Clinical Laboratory Improvement Amendments and the EU's In Vitro Diagnostic Regulation impose escalating analytical validation burdens that filter out smaller assay developers. ISO 15189 accreditation requirements in diagnostic laboratories further concentrate procurement authority toward vendors with documented quality management systems. Stakeholders must monitor evolving reimbursement thresholds for primary aldosteronism confirmatory testing as payer scrutiny intensifies.
Market Dynamics
Automated chemiluminescence platforms are consolidating diagnostic workflows, compressing turnaround times from batch processing to random-access testing while forcing mid-tier laboratories into equipment upgrade cycles.
Growth Catalysts
- IVDR compliance deadlines:The EU's In Vitro Diagnostic Regulation mandates stricter analytical validation, filtering out non-compliant assay developers and concentrating procurement toward accredited vendors with documented quality systems.
- Specialized cardiovascular centers:Hypertension referral networks in Germany, Japan, and the United States are bundling aldosterone-renin ratios with electrolyte panels, driving platform placements.
- High-sensitivity detection thresholds:Chemiluminescence immunoassays achieving sub-picogram-per-milliliter precision are replacing radioimmunoassay methods in confirmatory testing protocols.
Market Restraints
- Reagent cost concentration:Proprietary chemiluminescence reagent contracts lock laboratories into multi-year consumable commitments with limited vendor switching flexibility.
- Analytical validation burden:FDA Clinical Laboratory Improvement Amendments and ISO 15189 accreditation requirements extend product development timelines by 18-24 months for novel assay developers.
- Radioimmunoassay substitution inertia:Reference laboratories with sunk capital in legacy gamma counters delay platform transitions despite superior chemiluminescence throughput.
Strategic Opportunities
- Point-of-care decentralization:Cardiology specialty clinics in the United States are adopting compact aldosterone-renin analyzers for same-visit hypertension workups, bypassing centralized laboratory routing.
- Nephrology department bundling:Electrolyte-renal testing protocols in German hospital networks justify premium platform placements with dedicated aldosterone-renin modules.
- Japanese metabolic screening expansion:METI-supported preventive cardiovascular programs are incorporating aldosterone-renin ratios into national health checkup guidelines.
Industry Challenges
- Cross-trained technologist scarcity:Laboratories struggle to staff personnel proficient in both chemiluminescence platform maintenance and endocrine assay interpretation.
- Legacy analyzer integration friction:Hospital information system connectivity gaps between new chemiluminescence platforms and existing laboratory middleware create workflow disruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aldosterone-Renin Screening Market |
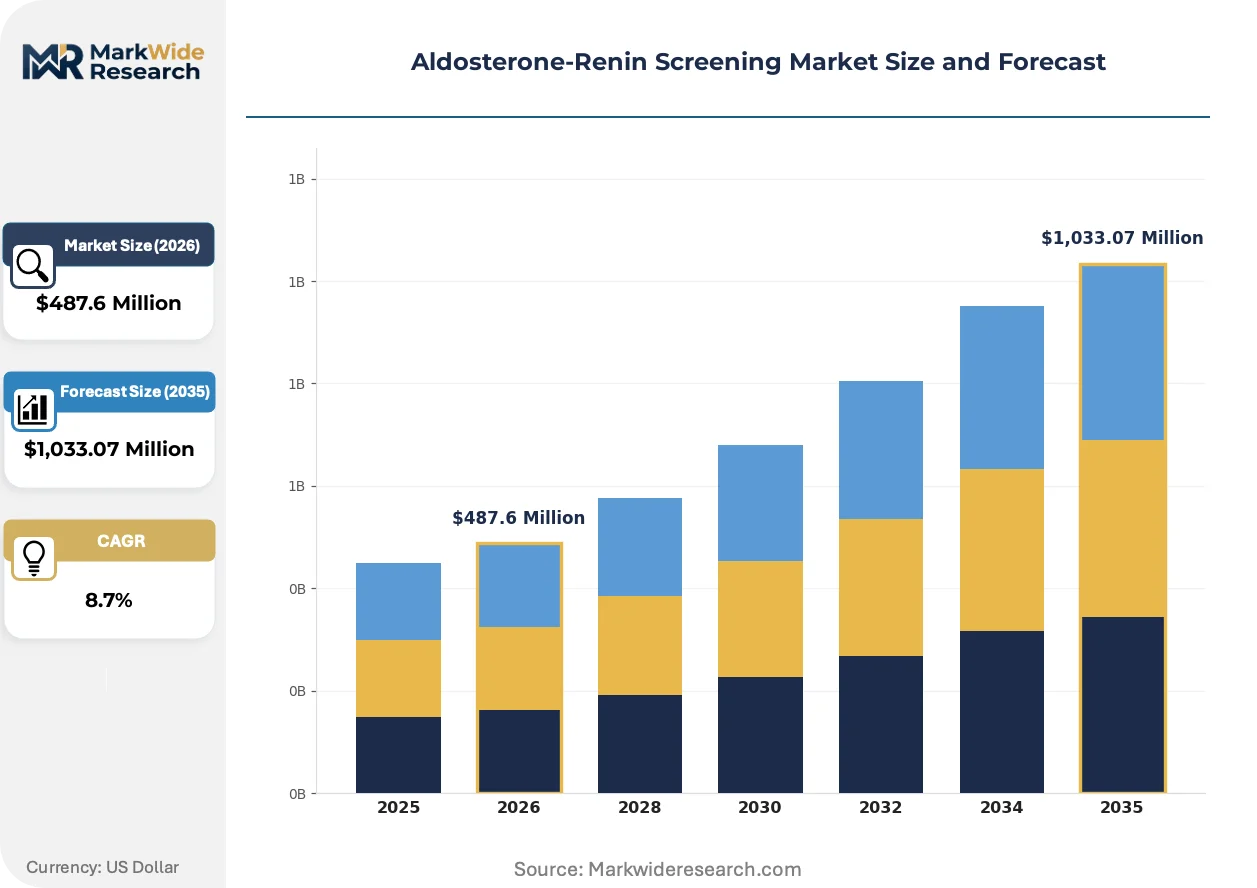
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Analyzers, Elisa Kits, Chemiluminescence Immunoassays, Radioimmunoassays, Point-of-Care Devices Application: Primary Aldosteronism, Hypertension Diagnosis, Cardiovascular Risk Assessment, Kidney Disorder Detection, Electrolyte Imbalance Analysis End User: Diagnostic Laboratories, Specialty Clinics, Cardiovascular Centers, Nephrology Departments, Research Institutions Deployment Model: Laboratory-Based Testing, Hospital-Based Testing, Home Testing Kits, Mobile Testing Units, Outpatient Facilities |
| Companies Covered | Siemens Healthineers, Abbott, Roche, Beckman Coulter, DiaSorin, Thermo Fisher Scientific, bioMérieux, Sysmex, PerkinElmer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aldosterone-Renin Screening Market Trends and Innovations
Random-access automation is fragmenting the traditional batch-processing model, enabling stat testing capabilities that reshape competitive differentiation around turnaround speed rather than throughput volume alone.
Multiplexed chemiluminescence immunoassays are decomposing the sequential aldosterone-then-renin testing paradigm into single-reaction panels. Nephrology departments in the United States are adopting these platforms within 12-18 month procurement cycles. The technology is decomposing capital allocation patterns as laboratories redirect funds from discrete analyzers toward integrated renal-endocrine workstations.
REACH chemical registration requirements are constraining reagent formulation flexibility for European manufacturers. Substances used in chemiluminescence substrates face heightened disclosure and substitution mandates. Assay developers are reformulating detection chemistry to maintain supply continuity under ECHA scrutiny.
Buyer concentration among integrated delivery networks is compressing vendor negotiation cycles. Group purchasing organizations in the United States are unbundling equipment and reagent contracts, forcing suppliers into transparent cost-per-test pricing. This restructuring is most visible in cardiovascular service line consolidations across Midwestern health systems.
Aldosterone-Renin Screening Market Segmentation
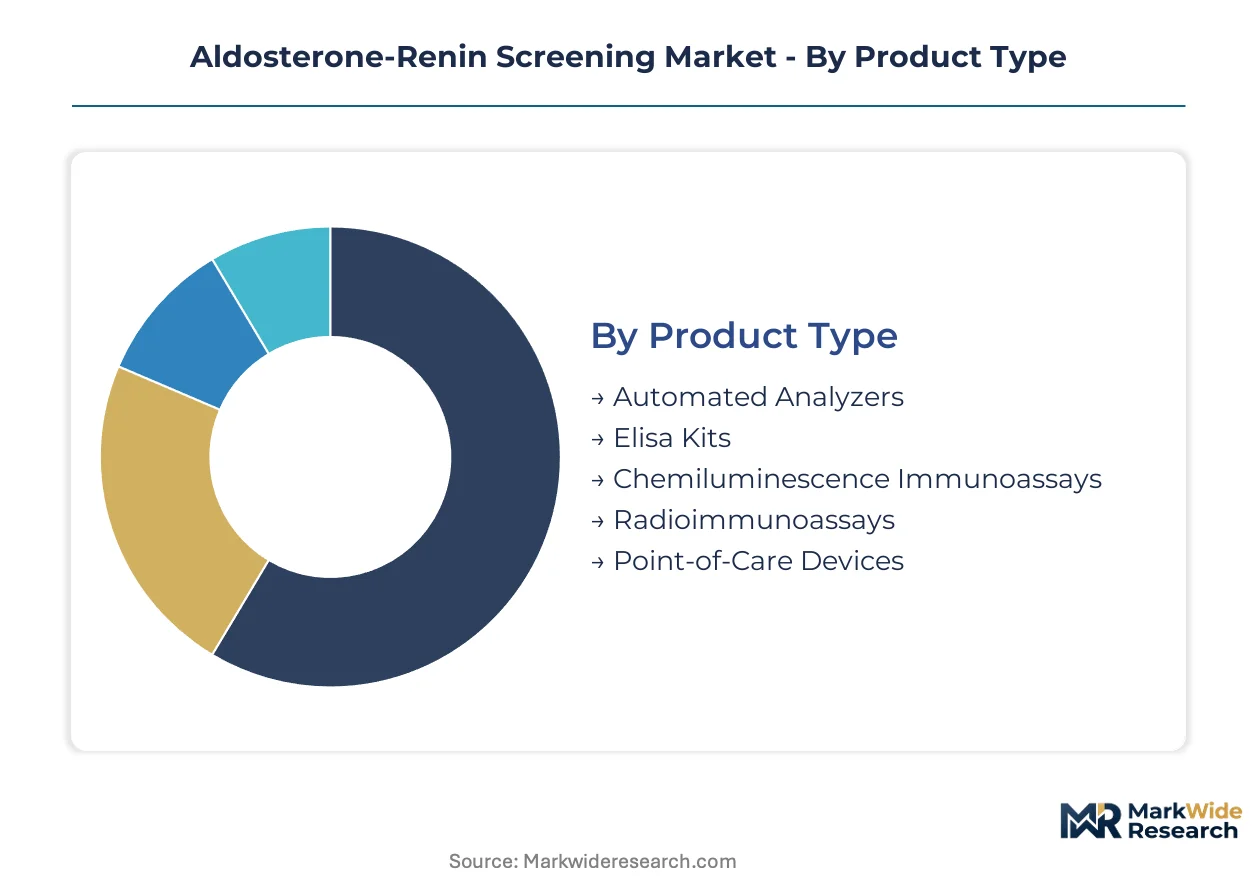
Segmentation in aldosterone-renin screening reveals distinct competitive dynamics across product platforms, clinical applications, and care settings. Each dimension carries unique substitution pressures that reshape procurement patterns and vendor positioning strategies.
Product Type:
Chemiluminescence immunoassays face the most acute substitution pressure from point-of-care alternatives, while legacy radioimmunoassays confront method obsolescence from automated platforms.
- Automated Analyzers:High-throughput random-access systems process 200-400 samples hourly with integrated sample handling. Siemens Healthineers and Roche dominate placements in German hospital networks where bundled electrolyte-renal workflows justify capital investment.
- Chemiluminescence Immunoassays:Sub-picogram-per-milliliter detection limits enable confirmatory primary aldosteronism testing with superior precision over radioimmunoassay methods. FDA CLIA and EU IVDR compliance requirements filter procurement toward accredited vendors with documented quality systems.
- Point-of-Care Devices:Compact analyzers deliver same-visit results in cardiology specialty clinics.
- Elisa Kits:Manual batch-processing formats persist in research settings with lower throughput requirements.
- Radioimmunoassays:Gamma-counter-dependent methods face declining adoption despite established clinical validation.
Automated analyzers anchor the volume base while point-of-care devices gain share at the steepest rate.
Application:
Cost tier differentiation separates high-complexity confirmatory testing from routine screening volumes.
- Primary Aldosteronism:Confirmatory saline suppression and captopril challenge testing require high-sensitivity aldosterone-renin ratio quantification. Nephrology departments in the United States bundle these assays with comprehensive metabolic panels.
- Hypertension Diagnosis:Resistant hypertension workups drive the largest absolute test volume across diagnostic laboratory networks. Japanese METI-supported preventive cardiovascular programs incorporate screening ratios into national health checkup guidelines.
- Cardiovascular Risk Assessment:Integrated screening protocols in German specialized cardiovascular centers combine aldosterone-renin ratios with cardiac biomarker panels.
- Kidney Disorder Detection:Renal function correlation with aldosterone dysregulation supports nephrology department adoption.
- Electrolyte Imbalance Analysis:Sodium-potassium disturbance investigation represents an emerging application segment.
Hypertension diagnosis generates the highest absolute test volume while primary aldosteronism commands premium pricing per assay.
End User:
Customer type concentration creates divergent procurement authority patterns across centralized laboratories and distributed care settings.
- Diagnostic Laboratories:High-volume reference laboratories in the United States absorb the majority of test demand through automated chemiluminescence platforms. Beckman Coulter targets this segment with batch-processing configurations optimized for throughput density.
- Nephrology Departments:German hospital networks justify premium integrated platform placements through bundled electrolyte-renal testing protocols.
- Cardiovascular Centers:Specialized hypertension referral networks in Japan drive confirmatory testing volume.
- Specialty Clinics:Decentralized cardiology practices adopt point-of-care devices for same-visit workups.
- Research Institutions:Academic medical centers support assay development and clinical validation studies.
Diagnostic laboratories capture the highest test throughput while nephrology departments deliver the strongest margin contribution per platform placement.
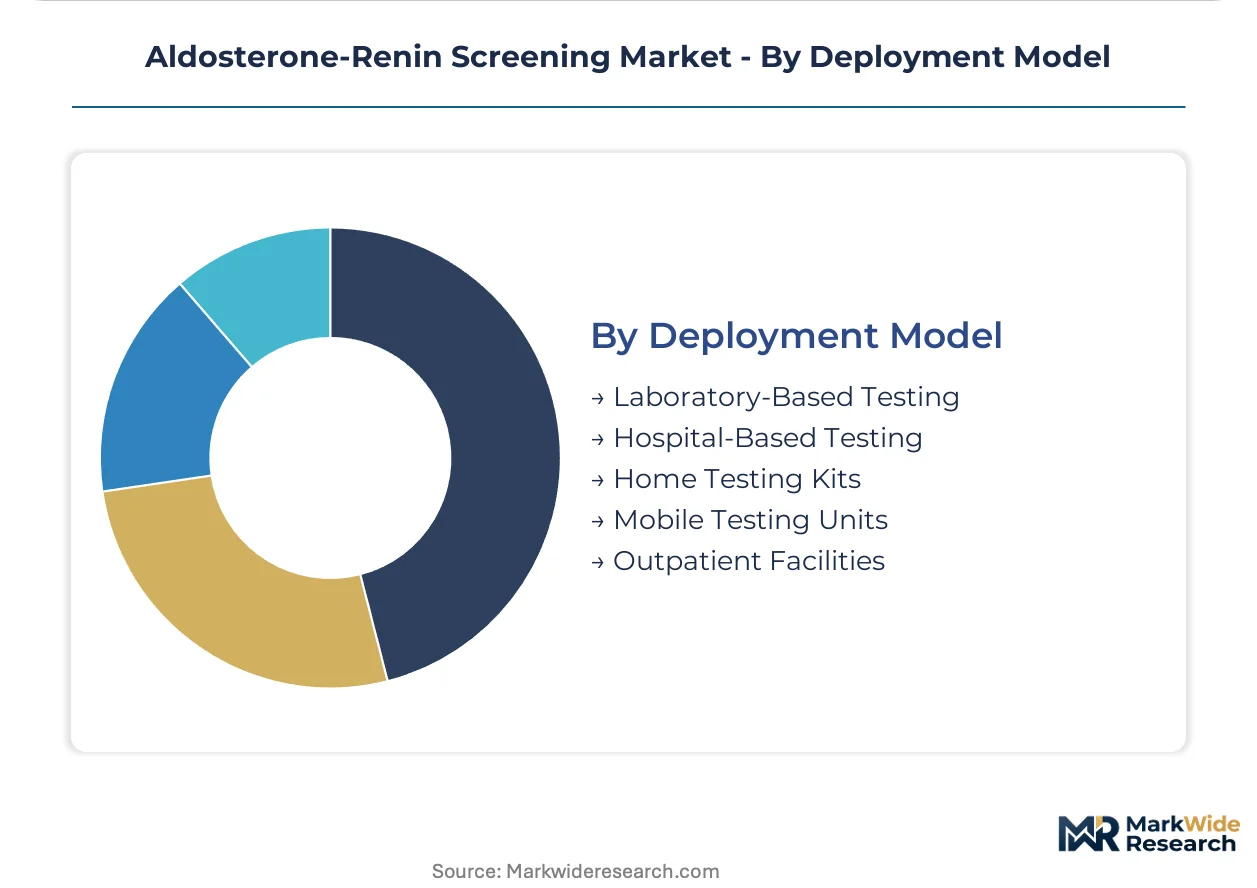
Deployment Model:
Supply concentration in centralized laboratory infrastructure is fragmenting toward distributed testing modalities.
- Laboratory-Based Testing:Centralized reference laboratories maintain dominant volume share through automated high-throughput platforms. ISO 15189 accreditation requirements concentrate procurement toward vendors with documented quality management systems.
- Hospital-Based Testing:Integrated delivery networks in the United States consolidate cardiovascular service line testing within hospital laboratory infrastructure.
- Outpatient Facilities:Ambulatory care settings adopt compact analyzers for rapid turnaround requirements.
- Mobile Testing Units:Deployable screening platforms support population health initiatives in underserved regions.
- Home Testing Kits:Patient-collected specimens for mail-in laboratory analysis represent an nascent deployment modality.
Laboratory-based testing retains the installed base majority while outpatient facilities expand capacity most aggressively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German diagnostics manufacturers export automated chemiluminescence platforms to cardiovascular centers in the United States and Japan, establishing the primary trade-flow corridor for aldosterone-renin screening technology.
United States
Specialized cardiovascular centers in Cleveland Clinic and Mayo Clinic networks drive confirmatory testing volume for primary aldosteronism. FDA Clinical Laboratory Improvement Amendments impose analytical validation requirements that filter procurement toward accredited vendors. Midwestern integrated delivery networks consolidate hypertension service line testing within hospital laboratory infrastructure.
Germany
Bundled electrolyte-renal testing protocols in university hospital networks justify premium platform placements with dedicated aldosterone-renin modules. EU In Vitro Diagnostic Regulation compliance deadlines concentrate procurement authority toward manufacturers with documented quality management systems. The Rhine-Ruhr metropolitan region hosts dense clusters of reference laboratories adopting automated high-throughput systems.
Japan
METI-supported preventive cardiovascular programs incorporate aldosterone-renin ratios into national health checkup guidelines, expanding screening eligibility. PMDA regulatory frameworks govern in vitro diagnostic quality controls for domestic assay deployment. Tokyo and Osaka metropolitan areas concentrate specialized hypertension referral networks driving confirmatory testing demand.
Switzerland
Swissmedic oversight of in vitro diagnostics shapes product registration timelines for chemiluminescence immunoassays entering the Alpine market. Basel and Zurich host research-intensive medical centers supporting clinical validation studies for novel detection platforms. Private laboratory networks adopt premium automated analyzers to maintain ISO 15189 accreditation standards.
Aldosterone-Renin Screening Market Competitive Landscape
Listed leaders compete with private specialists across platform automation and reagent supply dimensions. The vendor base clusters around three tiers: diversified diagnostics conglomerates with installed analyzer bases, mid-scale immunoassay specialists, and emerging point-of-care device developers. Strategic archetypes include platform-anchored revenue models, throughput-optimized batch processors, and decentralized rapid-testing innovators. Competitive moves concentrate on M&A for assay portfolio expansion and strategic partnerships for hospital information system integration.
Among diversified diagnostics conglomerates, Siemens Healthineers and Roche occupy positions exemplifying platform-anchored revenue strategies, leveraging automated analyzer installed bases to sustain recurring reagent contracts. Beckman Coulter represents the throughput-optimized archetype, targeting high-volume reference laboratories with batch-processing configurations. These three companies anchor the competitive structure while mid-scale specialists and point-of-care developers fragment the remaining addressable market.
| Leading Market Players |
|---|
| Siemens Healthineers |
| Abbott |
| Roche |
| Beckman Coulter |
| DiaSorin |
| Thermo Fisher Scientific |
| bioMérieux |
| Sysmex |
| PerkinElmer |
| Others |
Pricing and Supply Chain Analysis
Multi-year reagent supply contracts with take-or-pay clauses lock diagnostic laboratories into predictable consumable commitments while constraining vendor-switching flexibility across United States, German, and Japanese procurement networks. These arrangements tether price visibility to analyzer platform loyalty, compressing negotiation leverage for mid-tier laboratories seeking alternative chemiluminescence suppliers.
Pricing Analysis
Next-generation random-access chemiluminescence platforms command substantial premiums over legacy batch-processing systems and aging radioimmunoassay configurations. Three-tier pricing structure across premium, standard, and economy levels stratifies by detection sensitivity, throughput capacity, and ISO 15189 accreditation bundling. Cost compression in economy-tier ELISA formats intensifies as manual methods lose volume to automation. Reference laboratories with sunk capital in gamma counters exhibit lowest price sensitivity, while ambulatory cardiology clinics drive hardest bargain for point-of-care devices.
Supply Chain Analysis
Strategic stockpiling of chemiluminescence substrates and detection antibodies dominates inventory strategy among European manufacturers confronting REACH chemical registration uncertainties. Manufacturing concentration clusters in Germany, Switzerland, and Japan for precision optical components and assay reagents. Supply chains draw from specialized chemical suppliers for acridinium ester substrates and monoclonal antibody production. Single-source vulnerability pervades proprietary reagent formulations locked to specific analyzer platforms. Distribution runs through authorized distributor networks serving hospital laboratory consortia and GPO-negotiated contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Proficiency in dual chemiluminescence platform maintenance and endocrine assay interpretation remains scarce across diagnostic labor markets, constraining operational scaling for laboratories expanding aldosterone-renin testing volumes. This capability gap elevates human capital investment as a structural priority for market participants.
For Market Incumbents: Shield installed analyzer bases through exclusive reagent contracts and embedded service engineering teams that elevate switching costs for diagnostic laboratories. Accelerate hospital information system integration capabilities to reduce connectivity friction during platform upgrades. Prioritize ISO 15189 accreditation support services as a retention lever against emerging point-of-care substitutes. For New Entrants and Emerging Players: Same-visit hypertension workup capabilities in United States cardiology specialty clinics represent an underserved service layer where compact analyzer portability trumps throughput specifications. Target Midwestern integrated delivery networks consolidating cardiovascular service lines with transparent cost-per-test pricing unbundled from equipment finance. Pursue direct clinical workflow integration rather than laboratory-centric distribution. For Investors and Strategic Acquirers: Point-of-care device developers with FDA-cleared compact analyzers and established reimbursement pathways present attractive acquisition archetypes for platform diversification. Long-term viability hinges on decentralization trends in cardiovascular risk assessment outpacing centralized laboratory consolidation. Watch PMDA regulatory timelines for aldosterone-renin ratio inclusion in Japanese national health checkup guidelines as demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| IVDR Compliance Certification | EU regulatory accreditation filters procurement toward quality-system-documented vendors under ECHA scrutiny. |
| Multiplexed Panel Development | Single-reaction aldosterone-renin quantification decomposes sequential testing paradigms in nephrology departments. |
| Point-of-Care Miniaturization | Compact analyzer form factors enable same-visit hypertension workups bypassing centralized laboratory routing. |
| Hospital Information System Integration | Middleware connectivity reduces workflow disruption during chemiluminescence platform transitions. |
| Reimbursement Strategy Formulation | Primary aldosteronism confirmatory testing coverage expansion shapes United States volume accessibility. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with diagnostic laboratory directors, biomedical engineers, GPO contracts managers, and nephrology department heads; and secondary validation against FDA 510(k) filings, EU IVDR technical documentation, hospital procurement databases, and CMS Medicare reimbursement schedules. Bottom-up test volume modeling triangulated with top-down market sizing across product platforms and geographic clusters.
Across the analysis window, the forecasting framework segmented by product type, clinical application, end-user category, and deployment modality while incorporating technology substitution curves and regulatory compliance timelines. CAGRs were derived from installed base expansion rates, reagent consumption patterns, and platform replacement cycles. Model inputs included chemiluminescence analyzer placement data and point-of-care device adoption trajectories in cardiology specialty settings.
Forecasts assume regulatory continuity in FDA CLIA, EU IVDR, and PMDA frameworks; material policy shifts would require re-modeling. Specific risks encompass reimbursement threshold revisions for primary aldosteronism testing and REACH chemical substitution mandates affecting reagent formulation continuity. Revision becomes warranted when point-of-care device accuracy specifications cross thresholds sufficient to displace laboratory-based confirmatory protocols.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nephrology
US Hemodialysis and Peritoneal Dialysis Market
Nephrology
Radiation Nephropathy Treatment and Management Market
Nephrology
Global Acute Kidney Injury Treatment Market
Nephrology
Renal Artery Stenosis Treatment Market
Nephrology
Late Stage Chronic Kidney Disease Therapeutics Market
Nephrology
Peritoneal Dialysis Market
Nephrology
Ketoanalogue for Kidney Disease Market
Nephrology
Complement 3 Glomerulopathy (C3G) Treatment Market
Nephrology
Global Continuous Renal Replacement Therapy (CRRT) Market
Nephrology
Kidney Transplant Medicine Market
Nephrology
Blood Dialyzer Market
Nephrology
US Dialysis Market
Nephrology
Hemodialysis and Peritoneal Dialysis Market
Nephrology
Chronic Kidney Disease Market
Nephrology
Renal Cell Carcinoma Market
Nephrology
Kidney Stone Extraction Balloon Market