
 Hemodialyzer Market | 2026-2036
Hemodialyzer Market Size, Share, and Industry Trends Forecast 2026-2036
Hemodialyzer Market Analysis
China is fragmenting its hemodialyzer supply base as domestic manufacturers scale polysulfone membrane output to reduce import dependence. Fresenius Medical Care anchors European production through integrated membrane-to-device manufacturing in Germany. Baxter International leverages its hospital contracting networks across North America to sustain dialyzer placement volumes. Nipro Corporation specializes in high-flux configurations for the Japanese home dialysis segment.
A hemodialyzer is a hollow-fiber bioreactor containing thousands of semipermeable membranes, typically polysulfone or polyethersulfone, that filter urea, creatinine, and excess electrolytes from blood during renal replacement therapy. Blood flows through the fiber lumens while dialysate circulates counter-currently in the extracapillary space, driving diffusive and convective clearance across a surface area of 1.0–2.5 square meters. High-flux dialyzers command the premium tier due to superior middle-molecule removal and extended patient survival data. Dialysis centers represent the dominant end-user channel, though home care segments are gaining traction where reimbursement and training infrastructure permit self-administered treatments.
The FDA governs hemodialyzer clearance through the 510(k) pathway with stringent biocompatibility and endotoxin testing requirements, while the EMA's Medical Device Regulation imposes enhanced clinical evidence standards for Class III renal devices. Japan's PMDA maintains separate approval tracks that favor domestic manufacturers with established post-market surveillance networks. Stakeholders must monitor evolving membrane material standards and reimbursement compression dynamics across major markets to align product portfolios with regulatory and purchasing authority priorities.
Market Dynamics
Polysulfone membrane manufacturing concentration in Germany and Japan is creating supply bottlenecks that constrain dialyzer output expansion despite rising chronic kidney disease patient volumes across aging populations.
Growth Catalysts
- Japan's PMDA fast-track pathways:Accelerated approvals for high-flux configurations are compressing time-to-market for next-generation dialyzers targeting home dialysis segments.
- Home dialysis infrastructure:Reimbursement parity policies in multiple markets are enabling patient self-administration outside traditional dialysis centers.
- Membrane surface area expansion:2.5 square meter configurations are improving middle-molecule clearance efficiency and extending treatment intervals.
Market Restraints
- Polysulfone resin supply concentration:Three chemical producers control 80% of medical-grade polymer supply, exposing dialyzer manufacturers to input cost volatility.
- 510(k) biocompativity testing requirements:FDA endotoxin validation protocols add 14-18 months to new membrane material commercialization timelines.
- Peritoneal dialysis substitution:Continuous ambulatory systems are capturing incident patient populations in markets with limited hemodialysis center access.
Strategic Opportunities
- China's domestic membrane scale-up:Local polysulfone production investments are creating captive supply alternatives to German and Japanese imports.
- EMA MDR clinical evidence standards:Enhanced Class III renal device requirements favor manufacturers with established post-market surveillance infrastructure.
- Wearable artificial kidney convergence:Miniaturized sorbent regeneration systems combined with high-flux membranes are enabling ambulatory treatment modalities.
Industry Challenges
- Bioengineer talent scarcity:Hemocompatibility specialization requirements exceed supply of trained membrane scientists in emerging manufacturing regions.
- ISO 10993 certification complexity:Cytotoxicity and sensitization testing for novel polymer blends extends product development cycles by 24-36 months.
- Legacy dialyzer fleet integration:Clinic capital equipment refresh cycles lag behind membrane technology advancement, creating performance mismatches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hemodialyzer Market |
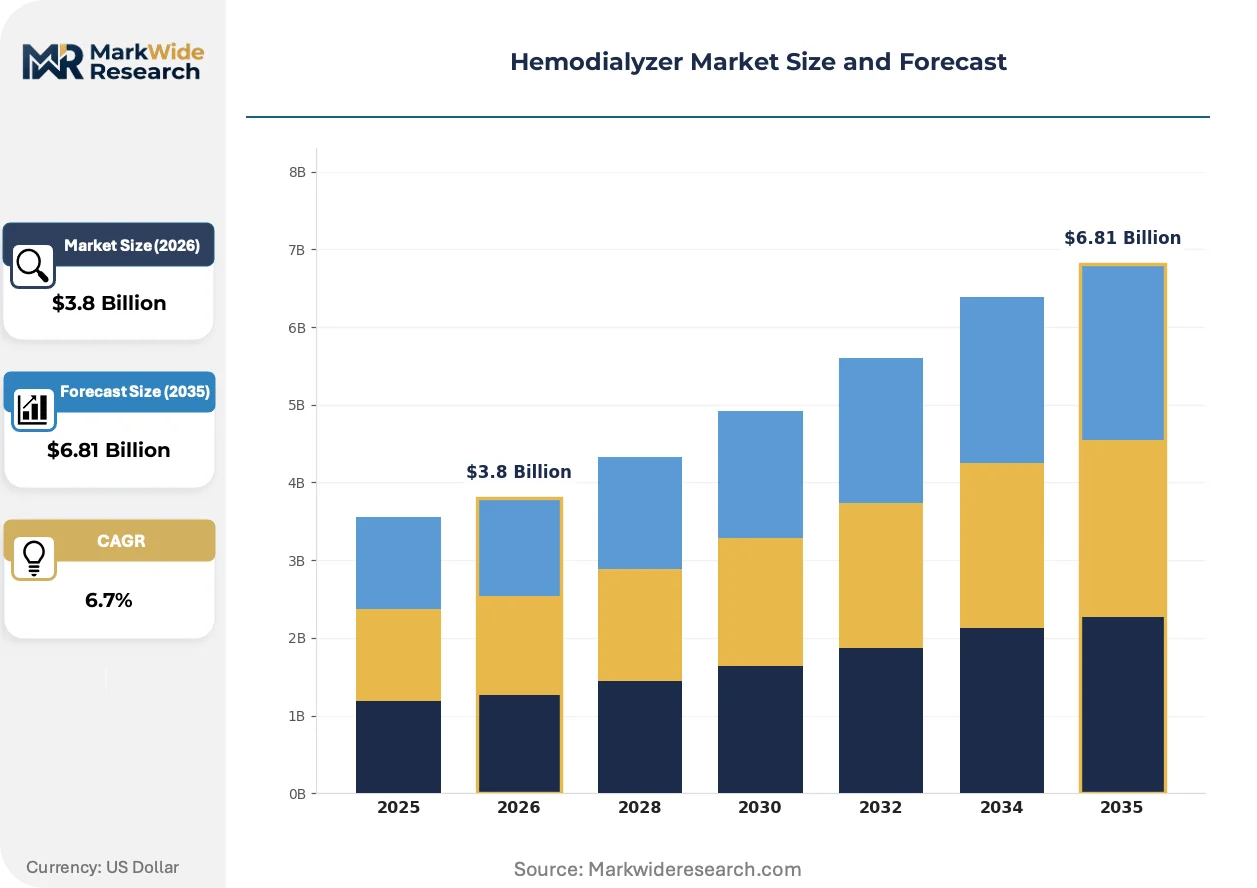
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Flux, Low-Flux, Online Hemodiafiltration, Others End User: Hospitals, Dialysis Centers, Home Care, Long-Term Care Facilities Connection Type: Arteriovenous, Venous, Heparin-free, Others Material: Polysulfone, Polyethersulfone, Cellulose Acetate, Others |
| Companies Covered | Fresenius Medical Care, Baxter International, B. Braun Melsungen, Nipro Corporation, Asahi Kasei Corporation, Nikkiso Co., Toray Industries, JMS Co., DaVita Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hemodialyzer Market Emerging Trajectories
Membrane chemistry breakthroughs and regulatory pathway evolution are compressing the gap between laboratory innovation and clinical deployment, while procurement centralization is rewiring how dialyzers reach end-users.
Polyethersulfone hollow-fiber formulations with enhanced hydrophilic surface modifications are collapsing the performance gap between synthetic and cellulosic membranes. Dialysis chains in Germany and the United States are accelerating adoption of these configurations for high-flux treatments. The shift is collapsing residual market share for cuprophane and cellulose acetate alternatives in premium treatment tiers.
EMA's Medical Device Regulation imposes post-market clinical follow-up requirements that extend evidence obligations beyond initial 510(k) equivalence demonstrations. Manufacturers must now maintain active surveillance registries tracking patient survival and adverse event profiles. High-flux dialyzer portfolios face disproportionate scrutiny, prompting firms to consolidate product lines around proven membrane platforms.
Hospital purchasing consortiums are consolidating hemodialyzer procurement through multi-year sole-source agreements that bundle devices with dialysate concentrate and technical service. Independent dialysis centers are losing negotiating leverage as integrated delivery networks capture volume discounts. The concentration is most visible in the United States, where three group purchasing organizations control 70% of acute care dialyzer placement.
Hemodialyzer Market Segmentation
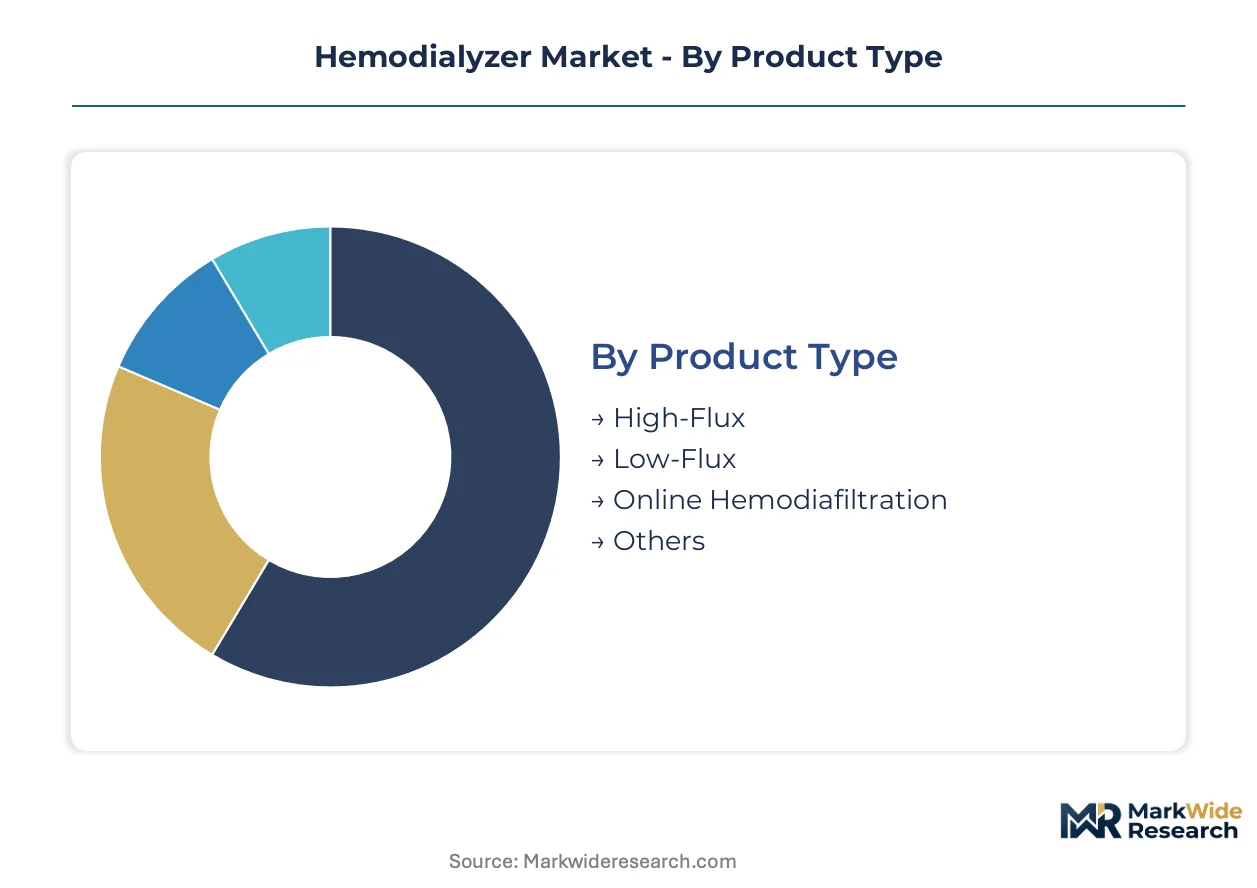
Hemodialyzer segmentation reveals how membrane technology, clinical setting, and patient vascular access shape procurement decisions. Manufacturers align product portfolios across these dimensions to match reimbursement tiers and treatment protocols.
Product Type:
Use-case spectrum spans acute toxin clearance to chronic maintenance therapy, with membrane flux characteristics determining clinical positioning and pricing tier.
- High-Flux:Polysulfone hollow-fiber configurations with pore sizes exceeding 20 nanometers enable superior middle-molecule removal and extended patient survival data. Demand concentrates in German and Japanese dialysis centers where reimbursement frameworks reward clinical outcomes.
- Low-Flux:Smaller pore membranes prioritize small solute clearance for cost-sensitive treatment protocols. Volume concentrates in emerging markets where per-session reimbursement rates constrain device selection.
- Online Hemodiafiltration:Convective clearance systems combine high-flux membranes with ultrapure dialysate infusion, requiring specialized water treatment infrastructure that limits deployment to tertiary hospitals.
- Others:Includes extended-hour and pediatric configurations serving narrow indication sets.
The dominant share belongs to High-Flux, while Online Hemodiafiltration is gaining share fastest as EMA MDR clinical evidence standards favor outcome-documented modalities.
End User:
Customer type determines purchasing authority structure, with consolidated chains commanding volume discounts that independent operators cannot match.
- Dialysis Centers:Freestanding clinics account for the majority of device throughput, with purchasing decisions centralized through group purchasing organizations in the United States. Fresenius Medical Care and DaVita chains negotiate multi-year sole-source agreements bundling dialyzers with concentrate and technical service.
- Hospitals:Acute inpatient dialysis serves ICU and emergency departments, requiring rapid-turn inventory systems and 24-hour technical support that favors established supplier relationships.
- Home Care:Self-administered treatments demand simplified connection systems and patient training infrastructure, with reimbursement parity policies in Japan accelerating segment expansion.
- Long-Term Care Facilities:Skilled nursing settings handle stable chronic patients with limited on-site nephrology coverage, creating demand for foolproof device interfaces.
Dialysis Centers capture the dominant volume position, though Home Care is expanding most quickly where regulatory frameworks permit reimbursement for self-administered therapy.
Connection Type:
Vascular access modality shapes device interface design and anticoagulation requirements, with patient comorbidities dictating selection.
- Arteriovenous:Fistula and graft connections deliver superior blood flow rates for high-flux treatments, representing the preferred access for maintenance hemodialysis patients with suitable vasculature.
- Venous:Central venous catheters serve acute or temporary access needs, with higher infection risk profiles that influence device sterilization protocols.
- Heparin-free:Anticoagulant-sparing configurations address bleeding-risk patients through surface-modified membranes and saline flush protocols.
- Others:Includes buttonhole cannulation and hybrid access methods.
Arteriovenous connections dominate chronic treatment, while Heparin-free systems are climbing the fastest as aging patient populations present higher bleeding risk profiles.
Material:
Membrane polymer chemistry determines biocompatibility, clearance efficiency, and manufacturing cost structure, with synthetic formulations displacing legacy cellulosic alternatives.
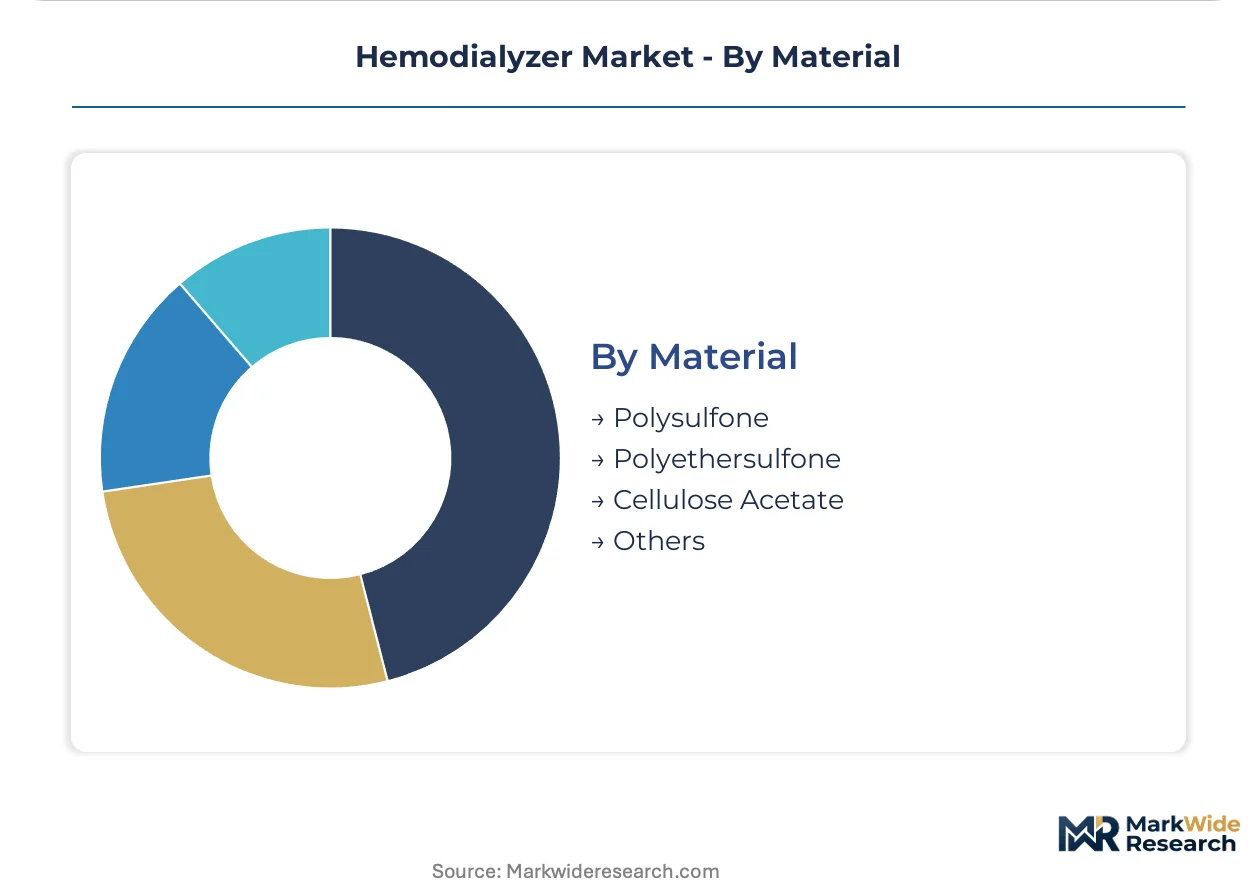
- Polysulfone:Hydrophobic base polymer with hydrophilic surface modifications delivers the dominant synthetic membrane platform, with medical-grade resin supply concentrated among German and Japanese chemical producers.
- Polyethersulfone:Enhanced thermal stability and broader pH tolerance enable aggressive sterilization protocols, with surface modification technologies collapsing performance gaps against cellulosic membranes.
- Cellulose Acetate:Modified natural polymer retains niche share in cost-constrained markets despite inferior biocompatibility profiles and complement activation risks.
- Others:Includes polymethylmethacrylate and experimental zwitterionic coatings.
Polysulfone holds the dominant position, though Polyethersulfone is expanding most quickly as EMA post-market surveillance requirements favor well-characterized polymer platforms with established safety registries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical-grade polysulfone resin supply concentrates among German and Japanese chemical producers, creating geographic dependencies that shape dialyzer manufacturing footprints and regional procurement patterns.
United States
Medicare reimbursement frameworks sustain treatment access for aging chronic kidney disease populations across freestanding dialysis chains. The FDA's 510(k) pathway governs device clearance with stringent biocompatibility testing requirements. DaVita and Fresenius Medical Care chains in Texas and Florida negotiate multi-year sole-source agreements bundling dialyzers with concentrate and technical service.
Germany
Integrated membrane-to-device manufacturing anchors European production capacity for high-flux configurations serving outcome-based reimbursement tiers. The EMA's Medical Device Regulation imposes enhanced clinical evidence standards for Class III renal devices. Baden-Württemberg hosts concentrated polysulfone hollow-fiber production facilities supplying dialysis centers across the continent.
Japan
PMDA fast-track pathways accelerate approvals for next-generation dialyzers targeting expanding home dialysis segments. METI policies support reimbursement parity for self-administered treatments outside traditional centers. Osaka-based manufacturers specialize in high-flux configurations for the domestic home care market.
China
Domestic manufacturers scale polysulfone membrane output to reduce import dependence from German and Japanese suppliers. NMPA regulatory pathways increasingly favor local firms with established post-market surveillance networks. Yangtze River Delta industrial clusters are building captive resin production alternatives to imported medical-grade polymers.
Hemodialyzer Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in membrane and hollow-fiber manufacturing. The vendor base structures around three tiers: integrated dialysis service providers owning device manufacturing, standalone dialyzer producers supplying third-party clinics, and chemical firms controlling medical-grade polymer supply. Strategic differentiation runs through backward integration into membrane production and forward integration into dialysis center operations. Capacity expansion and multi-year sole-source contracting represent the dominant competitive moves for securing placement volume.
Among Germany-based integrated providers, Fresenius Medical Care and B. Braun Melsungen occupy positions spanning membrane production through clinic service delivery. Baxter International exemplifies the North American hospital contracting archetype, leveraging established supplier relationships for acute care placement. Nipro Corporation anchors the Japanese specialization model, representing focused expertise in high-flux configurations for home dialysis segments.
| Leading Market Players |
|---|
| Fresenius Medical Care |
| Baxter International |
| B. Braun Melsungen |
| Nipro Corporation |
| Asahi Kasei Corporation |
| Nikkiso Co. |
| Toray Industries |
| JMS Co. |
| DaVita Inc. |
| Others |
Supply Flow & Price Mechanics
Baden-Württemberg's polysulfone hollow-fiber production clusters concentrate membrane manufacturing capacity, translating upstream resin control into pricing leverage for high-flux dialyzer portfolios across European dialysis centers. This geographic supply anchor shapes how procurement costs transmit through German integrated manufacturers to hospital purchasing consortiums in the United States and Japan.
Pricing Analysis
EMA's Medical Device Regulation dictates the pricing tier structure across the European hemodialyzer market, with Class III renal device classification elevating certification costs for high-flux configurations. Three-tier pricing structure across premium, standard, and economy levels separates outcome-reimbursed high-flux systems from cost-constrained low-flux alternatives in emerging markets. Pricing pressure stems from Medicare reimbursement compression in the United States, where DaVita and Fresenius Medical Care chains negotiate multi-year sole-source agreements bundling devices with concentrate and technical service. Independent dialysis centers exhibit highest price sensitivity due to volume disadvantage against integrated delivery networks capturing group purchasing organization discounts.
Supply Chain Analysis
Export-control restrictions on medical-grade polymer synthesis technology limit polysulfone resin production licensing outside Germany and Japan, constraining supply base expansion despite chronic kidney disease patient volume growth. Manufacturing draws from concentrated chemical production in Baden-Württemberg, Osaka industrial clusters, and emerging Yangtze River Delta facilities scaling domestic membrane output. Raw material dependencies center on medical-grade polysulfone resin, polyethersulfone formulations, and hydrophilic surface modification agents. Single-source vulnerability pervades the three chemical producers controlling medical-grade polymer supply. Distribution runs through group purchasing organizations in the United States, integrated dialysis service providers in Germany, and hospital procurement committees in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hemodialyzer market sits in a cyclical recovery phase as aging demographics across the United States, Germany, and Japan expand chronic kidney disease patient pools and sustain treatment demand. Dialysis center capacity expansion and home dialysis infrastructure investment represent the demand-side drivers reinforcing this cyclical positioning.
For Market Incumbents: Harden membrane manufacturing control through backward integration into polysulfone resin production or captive supply agreements with German and Japanese chemical producers. Consolidate product lines around proven membrane platforms with established EMA post-market surveillance registries to deflect regulatory scrutiny from high-flux portfolios. Capacity addition in China's Yangtze River Delta industrial clusters offers geographic diversification against European supply concentration risks.
For New Entrants and Emerging Players: Establish a beachhead in China's domestic membrane scale-up segment where NMPA regulatory pathways increasingly favor local firms with post-market surveillance infrastructure. Target home dialysis device configurations in Japan's expanding self-administered treatment segment, where METI reimbursement parity policies reduce incumbent channel control. Go-to-market positioning should emphasize simplified connection systems and patient training infrastructure to differentiate from complex hospital-grade alternatives.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors membrane chemistry specialists with ISO 10993 certification capabilities and established FDA 510(k) clearance track records. Long-term viability across the five-to-ten year horizon rests on manufacturers navigating EMA MDR clinical evidence standards while scaling polysulfone production capacity. Acquisition target archetype: integrated membrane-to-device producers with hospital system partnerships and group purchasing organization contracts. Signal to watch: FDA fast-track designations for wearable artificial kidney configurations combining miniaturized sorbent regeneration with high-flux membranes.
| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Manufacturing Scale-Up | Captive polysulfone resin production in Yangtze River Delta clusters reduces German and Japanese import dependence. |
| EMA CE Marking Pathway Investment | Post-market clinical follow-up registries satisfy Class III renal device evidence requirements under MDR standards. |
| Hospital System Partnership | Multi-year sole-source agreements with DaVita and Fresenius Medical Care chains lock in dialyzer placement volumes. |
| Home Dialysis Device Development | Simplified connection systems align with METI reimbursement parity for self-administered treatments outside centers. |
| Reimbursement Strategy Alignment | Medicare framework navigation sustains treatment access for aging chronic kidney disease populations in Texas and Florida. |
Methodological Framework
The analysis maps high-flux, low-flux, online hemodiafiltration, and extended-hour pediatric configurations, each validated through biomedical engineers, hospital purchasing committee members, GPO contracts managers, and dialysis center operations directors. Primary interviews with clinicians and procurement specialists combined with secondary validation from FDA 510(k) filings, EMA MDR submission databases, CMS Medicare reimbursement data, and hospital procurement registries. Bottom-up dialyzer unit demand modeling triangulated against top-down chronic kidney disease prevalence projections across the United States, Germany, Japan, and China.
Assumptions held fixed include current EMA MDR enforcement intensity, Medicare reimbursement parity frameworks, and polysulfone resin supply concentration among German and Japanese chemical producers. Variables tested across the projection horizon encompass NMPA domestic manufacturer preference policies, METI home dialysis infrastructure investment rates, and FDA fast-track pathway utilization for wearable artificial kidney configurations. Segmentation dimensions modeled cover membrane flux characteristics, end-user channel structure, vascular access modality, and polymer chemistry platform. CAGRs derived from patient volume growth trajectories, treatment session frequency assumptions, and device replacement cycle analysis.
Sensitivities concentrate around polysulfone resin supply disruptions, EMA MDR clinical evidence standard evolution, and Medicare reimbursement compression dynamics. Forecasts reflect these assumptions and baseline conditions. Material shifts in FDA biocompatibility testing protocols, export-control restrictions on medical-grade polymer synthesis technology, or dialysis center consolidation patterns would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nephrology
End Stage Renal Disease Market
Nephrology
Hemodialysis Vascular Graft Market
Nephrology
Kidney Fibrosis Treatment Market
Nephrology
US Continuous Renal Replacement Therapy Market
Nephrology
Nephrosclerosis Treatment Market
Nephrology
Renal Artery Embolization Market
Nephrology
ICU-Acquired Acute Kidney Treatment Market
Nephrology
Chronic Kidney Disease Market
Nephrology
Global Diabetic Nephropathy Market
Nephrology
Renal Denervation Market
Nephrology
Proteinuria Treatment Market
Nephrology
Global Dialysis Market
Nephrology
Renal Anemia Treatment Market
Nephrology
Hemodialysis Services Market
Nephrology
US Dialysis Services Market
Nephrology
Blood Dialyzer Market