
 End Stage Renal Disease Market | 2026-2036
End Stage Renal Disease Market Size, Share, and Industry Trends Forecast 2026-2036
End Stage Renal Disease Market Intelligence
The capital-intensity divergence between players is rotating competitive advantage toward vertically integrated manufacturers with captive dialyzer production. Fresenius Medical Care AG & Co. KGaA leverages its in-house supply of dialyzers and concentrates to protect margin pools across the treatment chain. Baxter International, Inc. sustains differentiation through peritoneal dialysis platform breadth and home-care channel control. DaVita Inc. anchors its position via clinic network density and direct patient relationship management in key metropolitan markets.
End stage renal disease denotes the terminal phase of chronic kidney disease where renal function declines below fifteen percent of normal capacity, requiring external filtration through hemodialysis, peritoneal dialysis, or transplantation to sustain life. Hemodialysis dominates treatment type volumes due to established clinical infrastructure and reimbursement alignment, though peritoneal dialysis gains traction as home-based modalities reduce facility overhead. Dialysis centers capture the largest end-user value pool given their capital equipment intensity and recurring consumable demand, while home care segments expand fastest as portable monitoring systems enable remote treatment supervision.
FDA premarket notification requirements and CMS bundled payment frameworks govern device approval and service reimbursement in the United States, directly influencing manufacturer pricing architecture and provider adoption thresholds. EMA medical device regulations and national health technology assessment bodies across Germany, France, and Italy shape market access timelines for renal replacement technologies in Europe. Stakeholders must monitor evolving value-based care contracts and biosensor integration standards that will determine which technology platforms secure preferential placement in procurement frameworks.
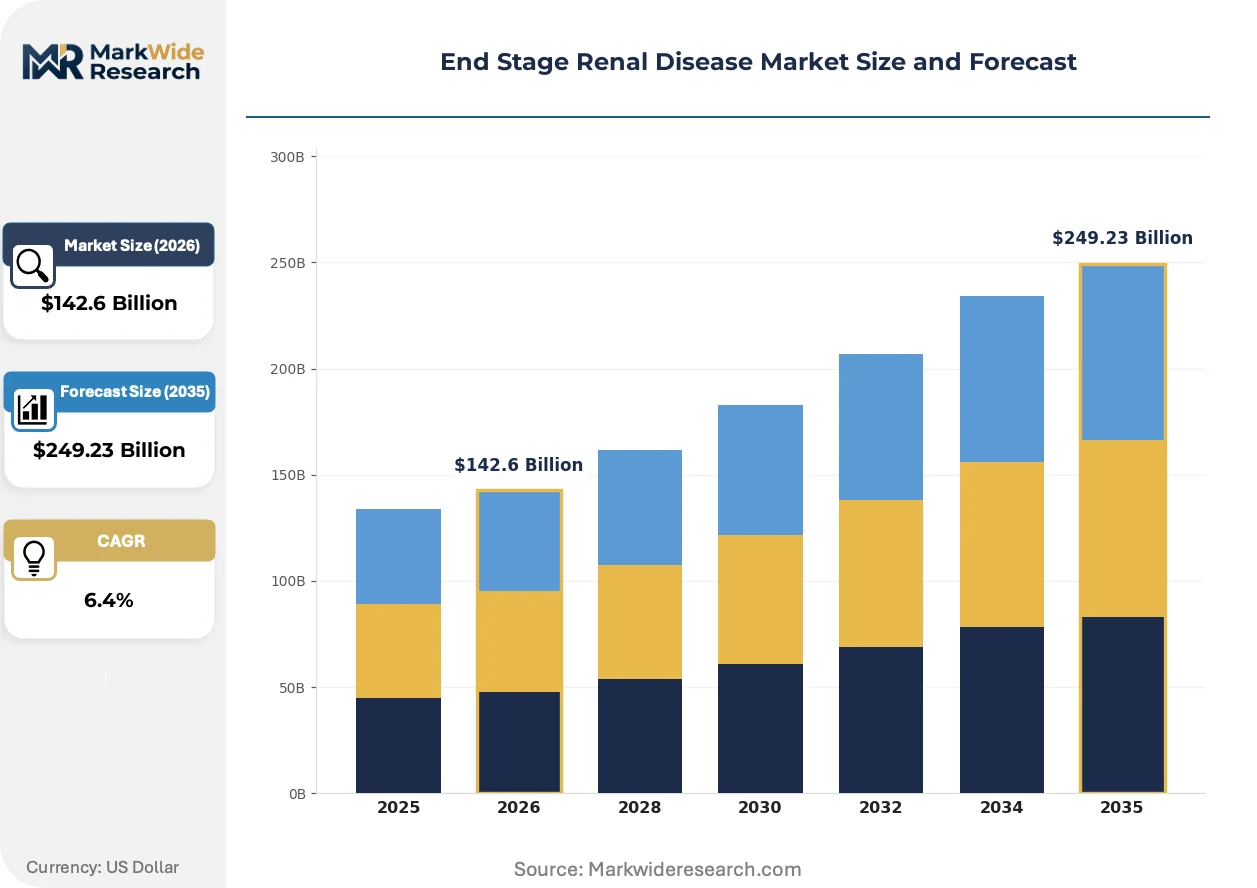
Market Dynamics
The dialysis supply chain is compressing as captive dialyzer production becomes the decisive margin-control mechanism, forcing independent providers to secure long-term concentrate contracts or face cost disadvantages against vertically integrated competitors.
Growth Catalysts
- CMS Bundled Payment Expansion:The United States reimbursement framework incentivizes home-based peritoneal dialysis modalities, accelerating patient migration from facility-based hemodialysis.
- Japan's Super-Aged Society:Metropolitan Tokyo and Osaka dialysis centers report capacity constraints as diabetes prevalence among patients over 75 sustains treatment volume expansion.
- Wearable Artificial Kidney Development:Portable filtration systems are advancing through FDA breakthrough device designation pathways, enabling ambulatory treatment outside clinical settings.
Market Restraints
- Polysulfone Membrane Supply Concentration:Three German and Japanese chemical suppliers control high-flux dialyzer membrane substrate production, creating input vulnerability for independent device manufacturers.
- EMA MDR Transition Friction:Stricter clinical evidence requirements for Class III renal replacement devices extend European market access timelines by 18-24 months versus previous directives.
- Transplant Substitution Ceiling:Organ donation rates in France, Spain, and the United States plateau below waiting-list growth, capping the patient pool diversion potential from dialysis dependency.
Strategic Opportunities
- India Tier-2 City Penetration:Dialysis center networks in Lucknow, Jaipur, and Kochi remain underserved relative to Mumbai and Delhi, offering first-mover density advantages.
- AI-Enabled Dose Optimization:Machine learning integration with dialysis prescription software is reducing intradialytic hypotension episodes, creating differentiation for technology-integrated providers.
- IRA Medicare Price Negotiation Exemption:Dialysis services fall outside the Inflation Reduction Act's drug pricing provisions, preserving reimbursement stability for US operators versus other therapeutic areas.
Industry Challenges
- Nephrology Workforce Density:The American Society of Nephrology documents persistent fellowship vacancy gaps in rural Texas, Alabama, and Mississippi, constraining clinic expansion velocity.
- Water Purification Infrastructure:Hemodialysis facilities require reverse osmosis systems meeting AAMI/ISO 13959 standards, with capital costs per treatment station exceeding $50,000 in aged US hospital buildings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | End Stage Renal Disease Market |
| Market Size in 2026 | $142.6 Billion |
| Market Size in 2035 | $249.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: Hemodialysis, Peritoneal Dialysis, Kidney Transplantation, Conservative Management End User: Hospitals, Dialysis Centers, Home Care, Specialty Clinics Technology: Dialysis Machines, Catheters, Renal Replacement Therapy Devices, Monitoring Systems Product Component: Dialyzers, Tubing, Concentrates, Catheterization Kits |
| Companies Covered | Fresenius Medical Care AG & Co. KGaA, Baxter International, Inc., Nipro Corporation, Medtronic Plc, B. Braun Melsungen AG, Asahi Kasei Medical Co., Ltd., Nikkiso Co., Ltd., Becton Dickinson, DaVita Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
End Stage Renal Disease Market Strategic Shifts & Innovations
Renal replacement therapy is fragmenting across treatment settings as technology miniaturization and remote monitoring capabilities dissolve the traditional facility-centric model.
Bioartificial kidneys incorporating living renal cells alongside synthetic filtration membranes are supplanting purely mechanical dialyzers in preclinical development programs. Academic medical centers in California and Massachusetts are prioritizing these hybrid devices for their potential to restore endocrine functions beyond toxin clearance. This convergence is compressing the addressable market for conventional hemodialysis equipment manufacturers while opening regenerative medicine partnerships.
The European Union Medical Device Regulation (MDR) is reclassifying hemodialysis machines and dialyzers under stricter conformity assessment procedures. Notified bodies in Germany and the Netherlands are demanding extended clinical follow-up data for high-flux membrane biocompatibility claims. French and Italian manufacturers are responding by consolidating regulatory affairs functions and accelerating post-market surveillance system investments to maintain CE marking validity.
Home dialysis training programs are displacing facility-based initiation as the default patient onboarding pathway in US Medicare Advantage networks. Large dialysis organizations are unbundling education services from treatment delivery, contracting with specialized home therapy nursing agencies. This restructuring is most visible in Florida and Arizona retirement corridors where snowbird populations demand geographic flexibility in care access.
End Stage Renal Disease Market Segmentation
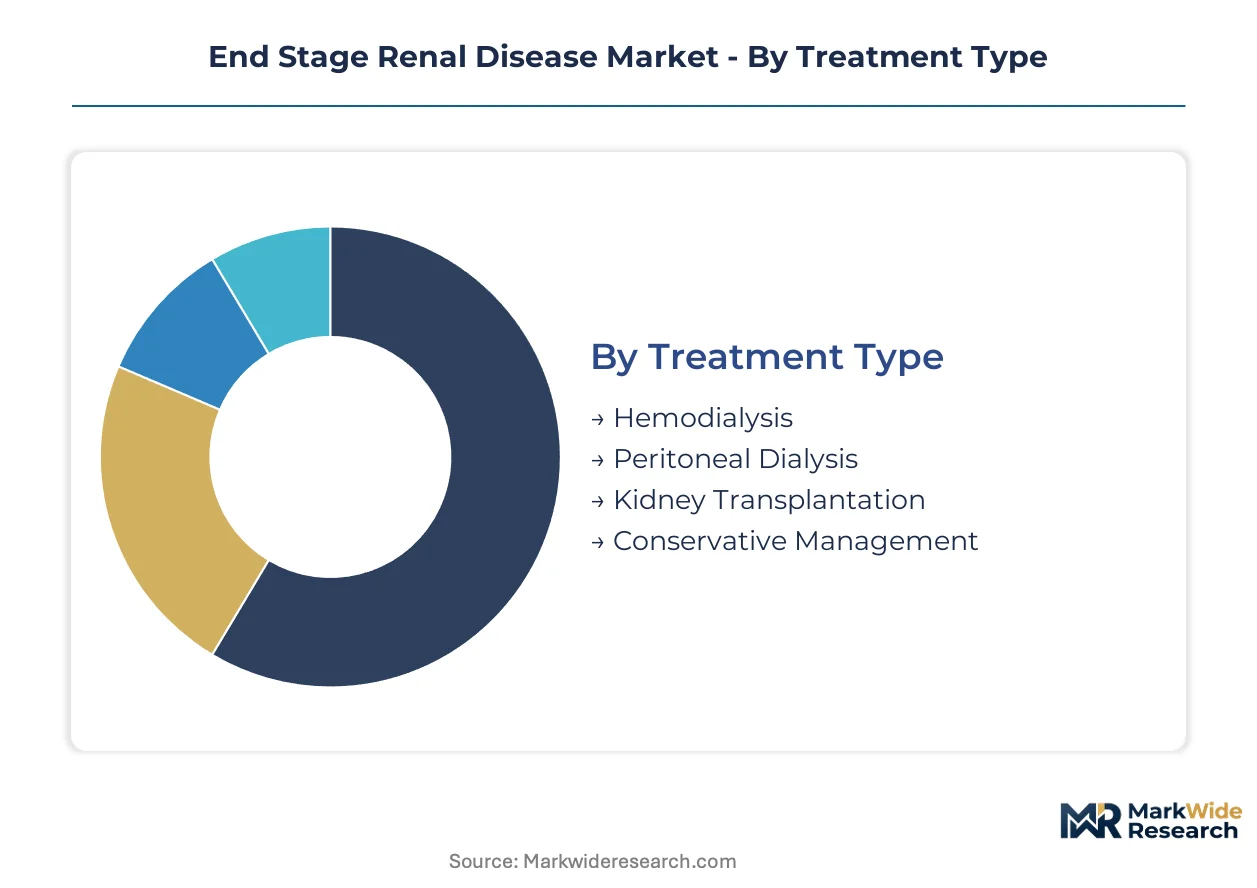
Renal replacement therapy segments fragment across treatment settings and reimbursement models, with regulatory pathways and capital intensity determining where manufacturers concentrate development resources. Understanding these divisions reveals which technology platforms capture recurring revenue versus one-time equipment sales.
Treatment Type:
FDA and EMA approval requirements diverge sharply across modalities, with device-based therapies facing stricter premarket scrutiny than pharmaceutical conservative management.
- Hemodialysis:Blood filtration through external dialyzer membranes requires thrice-weekly facility visits. Demand concentrates in United States metropolitan corridors where CMS bundled payments sustain clinic infrastructure investments.
- Peritoneal Dialysis:Intraperitoneal fluid exchange enables home-based treatment with portable cycler units. United States Medicare Advantage networks in Florida and Arizona are accelerating patient migration toward this modality for geographic flexibility.
- Kidney Transplantation:Surgical organ replacement offers definitive therapy but remains supply-constrained by donor availability.
- Conservative Management:Palliative symptom control without renal replacement serves patients with limited life expectancy or contraindications to invasive therapy.
Hemodialysis handles the majority of throughput; peritoneal dialysis is expanding most quickly as home-care infrastructure matures.
End User:
Capital deployment requirements and patient volume economics create distinct competitive dynamics across care settings.
- Dialysis Centers:Freestanding facilities with 15-30 stations per location generate recurring consumable demand through high patient throughput. Germany's outpatient clinic networks in Berlin and Munich operate at capacity constraints due to aging diabetes prevalence.
- Hospitals:Acute care settings manage inpatient dialysis for hemodynamically unstable patients requiring continuous monitoring.
- Home Care:Residential treatment delivery demands portable equipment and remote monitoring infrastructure. Japanese super-aged households in Tokyo prefecture are adopting peritoneal dialysis cycler systems faster than facility alternatives.
- Specialty Clinics:Nephrology-focused practices concentrate complex case management and transplant evaluation services.
Dialysis centers absorb the largest capital equipment investment; home care is climbing the fastest on patient preference shifts.
Technology:
Software integration and biosensor miniaturization are redrawing competitive boundaries between device categories.
- Dialysis Machines:Automated blood pumps and ultrafiltration controllers form the core capital equipment base. United States providers in Texas and California prioritize units with embedded AI dose optimization to reduce intradialytic complications.
- Monitoring Systems:Remote patient surveillance platforms enable home therapy supervision through cloud-connected vital sign transmission.
- Catheters:Vascular and peritoneal access devices bridge patient anatomy to external filtration circuits.
- Renal Replacement Therapy Devices:Wearable artificial kidneys and bioartificial hybrid systems represent next-generation platforms advancing through FDA breakthrough pathways.
Dialysis machines anchor installed base value; monitoring systems are gaining share fastest through telehealth reimbursement expansion.
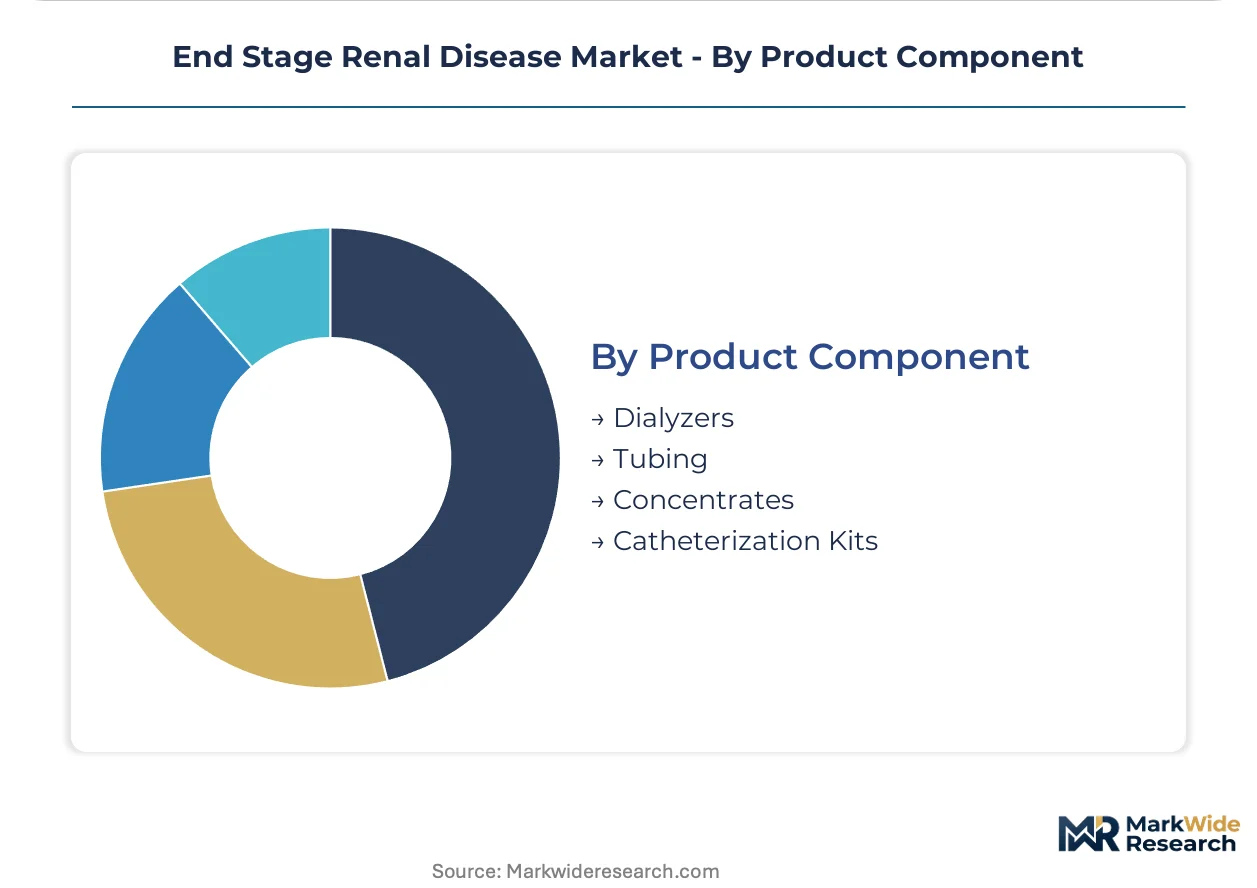
Product Component:
Supply chain control over membrane substrates and concentrate chemistry determines margin capture for integrated manufacturers.
- Dialyzers:Hollow-fiber membrane cartridges execute toxin clearance through polysulfone or polyethersulfone substrates. German and Japanese chemical suppliers dominate high-flux membrane production, creating input bottlenecks for independent device makers.
- Concentrates:Acid and bicarbonate solutions constitute recurring consumables with formulation-specific chemistry requirements.
- Tubing:Bloodline sets and fluid circuits represent standardized disposables with volume-scale economics.
- Catheterization Kits:Sterile procedure packs bundle access devices with antiseptic preparation materials.
Dialyzers command the highest unit economics; concentrates follow the steepest expansion trajectory through recurring treatment volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in renal replacement devices and dialyzer membranes concentrate manufacturing value in Germany and Japan while the United States absorbs the largest import volume for finished dialysis equipment. Service delivery economics favor domestic clinic operators over cross-border treatment models.
United States
Diabetes prevalence among Medicare beneficiaries drives treatment volume expansion across Florida, Texas, and Arizona retirement corridors. CMS bundled payment frameworks incentivize home-based peritoneal dialysis migration over facility hemodialysis. DaVita and Fresenius clinic networks dominate metropolitan density in Houston, Phoenix, and Miami-Dade markets.
Germany
Polysulfone membrane substrate production concentrates in Baden-Württemberg and North Rhine-Westphalia chemical corridors, supplying dialyzer manufacturers worldwide. EMA MDR transition extends conformity assessment timelines for Class III renal devices by 18-24 months. Berlin and Munich outpatient dialysis centers operate at capacity constraints due to super-aged demographic demand.
Japan
Metropolitan Tokyo and Osaka dialysis facilities report station saturation as patients over 75 constitute the fastest-expanding treatment cohort. PMDA breakthrough device pathways accelerate wearable artificial kidney prototypes toward clinical validation. Government reimbursement maintains per-session rates that sustain clinic profitability despite labor cost pressures.
India
Tier-2 cities including Lucknow, Jaipur, and Kochi remain underserved relative to Mumbai and Delhi dialysis infrastructure. CDSCO medical device registration requirements create compliance hurdles for imported hemodialysis machines. Karnataka and Tamil Nadu hospital networks are expanding captive dialysis center partnerships to capture chronic kidney disease patient flows.
China
Domestic dialyzer production scales in Jiangsu and Zhejiang manufacturing zones to reduce import dependency on German and Japanese membrane suppliers. NMPA innovation approval pathways prioritize bioartificial kidney development through designated fast-track channels. Shanghai and Beijing tertiary hospitals anchor peritoneal dialysis training programs for rural patient migration.
End Stage Renal Disease Market Key Industry Players
Concentration sits with vertically integrated manufacturers possessing captive dialyzer production and clinic network operators controlling patient access points. The market structure bifurcates between equipment manufacturers competing on membrane technology and service providers competing on metropolitan density. Two strategic archetypes dominate: integrated manufacturers with in-house concentrate and dialyzer supply, and clinic operators with direct patient relationship management. Competitive moves center on backward integration into membrane substrate production and geographic densification in underserved metropolitan corridors.
Among integrated manufacturers, Fresenius Medical Care AG & Co. KGaA and Baxter International, Inc. exemplify divergent strategic positioning. Fresenius represents the captive supply archetype through in-house dialyzer and concentrate production protecting margin pools across the treatment chain. Baxter occupies a position emphasizing peritoneal dialysis platform breadth and home-care channel development. DaVita Inc. anchors the service-provider tier through clinic network density and metropolitan market concentration. Nipro Corporation and Asahi Kasei Medical Co., Ltd. sit within the membrane technology specialist segment, supplying high-flux substrates to independent device manufacturers. B. Braun Melsungen AG and Nikkiso Co., Ltd. represent European and Japanese equipment fabrication archetypes respectively, competing on regional regulatory familiarity and installed base maintenance.
| Leading Market Players |
|---|
| Fresenius Medical Care AG & Co. KGaA |
| Baxter International, Inc. |
| Nipro Corporation |
| Medtronic Plc |
| B. Braun Melsungen AG |
| Asahi Kasei Medical Co., Ltd. |
| Nikkiso Co., Ltd. |
| Becton Dickinson |
| DaVita Inc. |
| Others |
Cost & Logistics Intelligence
Ninety-day polysulfone membrane inventory buffers at German chemical suppliers concentrate pricing power with dialyzer substrate manufacturers, forcing independent device makers into long-term offtake contracts or margin compression. This lead-time asymmetry between captive producers and external buyers anchors the cost architecture across hemodialysis consumables.
Pricing Analysis
Configured-to-order dialyzer specifications command 15-25% premiums over standard high-flux configurations in United States procurement frameworks. The market operates on contract-based long-term offtake structures with three-tier pricing stratification across premium membrane biocompatibility grades, standard clinical efficacy tiers, and economy concentrates for high-volume clinic chains. Cost compression in economy-grade dialyzers is intensifying because Indian and Chinese domestic manufacturers are scaling polysulfone membrane production. Independent dialysis providers exhibit highest price sensitivity due to absence of captive concentrate supply, while vertically integrated clinic networks absorb pricing volatility through in-house dialyzer production.
Supply Chain Analysis
Port congestion at Hamburg and Rotterdam container terminals elevates inbound logistics costs for dialyzer membrane substrates shipped from Baden-Württemberg chemical corridors to Asian device assembly plants. Supply concentrates in Germany, Japan, and emerging Chinese manufacturing zones for polysulfone and polyethersulfone membrane substrates. Raw material dependencies span medical-grade polymers, acid concentrate chemistry, and sterilization packaging. Single-source vulnerability sits with three German and Japanese chemical suppliers controlling high-flux membrane substrate production. Distribution runs through direct manufacturer-to-clinic contracts for large dialysis organizations, with regional distributors serving independent facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The End Stage Renal Disease Market sits in early-cycle expansion as home-based peritoneal dialysis penetration accelerates through Medicare Advantage network incentives and portable cycler technology maturation.
For Market Incumbents: Fortify membrane substrate supply security through backward integration into polysulfone production or exclusive long-term contracts with Baden-Württemberg chemical suppliers. Expand AI-enabled dose optimization software development to differentiate against emerging wearable artificial kidney platforms. Prioritize certification investment for EMA MDR Class III device conformity to defend European market access timelines against regulatory friction.
For New Entrants and Emerging Players: Anchor in India's tier-2 city dialysis infrastructure gap, specifically Lucknow and Jaipur metropolitan corridors where clinic density trails Mumbai and Delhi by 60-70%. Target home care monitoring systems as the most penetrable technology segment, leveraging telehealth reimbursement expansion in United States Medicare frameworks. Pursue hospital system partnership go-to-market angles with Karnataka and Tamil Nadu hospital networks expanding captive dialysis center partnerships.
For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue infrastructure play because dialysis treatment dependency creates predictable consumable demand with limited transplant substitution ceiling. Acquisition target archetype: membrane technology specialists with FDA breakthrough device pathway progress and established concentrate chemistry IP. Watch PMDA and FDA wearable artificial kidney approval timelines as inflection indicators for next-generation platform displacement risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Membrane Production | Captive polysulfone supply protects margin pools against German and Japanese chemical supplier concentration. |
| AI-Enabled Dose Optimization Development | FDA-cleared algorithms reduce intradialytic hypotension episodes, creating differentiation in Texas and California clinic procurement. |
| Home Care Monitoring Platform Launch | Cloud-connected vital sign transmission enables remote peritoneal dialysis supervision through Medicare Advantage reimbursement. |
| EMA MDR Class III Certification Investment | Extended clinical follow-up data satisfies notified body demands in Germany and Netherlands for CE marking validity. |
| India Tier-2 City Clinic Network Expansion | First-mover density in Lucknow and Jaipur captures chronic kidney disease patient flows before infrastructure saturation. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, CMS Medicare reimbursement databases, EMA medical device registration records, and hospital procurement contract disclosures. Interviews with dialysis center operations directors, nephrology clinic medical directors, biomedical equipment procurement managers, and GPO contracts specialists informed demand-side assumptions. Bottom-up patient volume modeling triangulated against top-down manufacturer revenue aggregation across treatment modalities.
Segmentation dimensions modeled span treatment type, end-user setting, technology platform, and product component chemistry across the projection horizon. CAGRs derive from patient population epidemiology, reimbursement rate trajectories, and technology adoption S-curves. Forecast inputs incorporate diabetes prevalence projections, transplant waiting-list dynamics, and home therapy training program expansion rates.
Material uncertainties — regulatory pathway delays, membrane substrate supply disruptions, and nephrology workforce vacancy persistence — sit outside the modeled envelope. Forecasts reflect documented assumptions about CMS bundled payment stability and EMA MDR transition timelines. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nephrology
Complement 3 Glomerulopathy (C3G) Treatment Market
Nephrology
Kidney Transplant Medicine Market
Nephrology
Proteinuria Treatment Market
Nephrology
Late Stage Chronic Kidney Disease Therapeutics Market
Nephrology
Drug-Induced Nephrotoxicity Treatment Market
Nephrology
Kidney Transplant Market
Nephrology
Global Diabetic Nephropathy Market
Nephrology
Chronic Kidney Disease Market
Nephrology
US Continuous Renal Replacement Therapy Market
Nephrology
Renal Anemia Treatment Market
Nephrology
Renal Stent Market
Nephrology
Global Acute Kidney Injury Treatment Market
Nephrology
Hemodialysis and Peritoneal Dialysis Market
Nephrology
Dialysis Centers Market
Nephrology
South Africa Hemodialysis and Peritoneal Dialysis Market
Nephrology
Renal Artery Embolization Market