
 Platysmaplasty Treatment Market | 2026-2036
Platysmaplasty Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Platysmaplasty Treatment Market Analytics
The platysmaplasty treatment landscape is pivoting between premium surgical outcomes and commoditized non-invasive alternatives. Allergan Aesthetics leverages its injectables portfolio to anchor the minimally invasive tier, while Galderma SA competes through neuromodulator and filler combinations that address platysmal banding without surgery. Merz Pharma specializes in ultrasound-assisted delivery systems that occupy a middle position between injectables and open surgical intervention.
Platysmaplasty denotes the surgical correction of platysmal banding and cervical laxity through anterior neck access, typically involving partial muscle transection, imbrication, or suspension with absorbable suture fixation to restore cervicomental angle definition. Its primary commercial purpose centers on aesthetic neck rejuvenation for patients with visible platysmal separation unresponsive to non-invasive modalities. Injectables and energy devices currently lead volume throughput in dermatology clinics, while surgical implants and combined therapy approaches capture concentrated margin pools in cosmetic surgery centers. The homecare and telemedicine delivery modes remain nascent but attract venture funding for remote consultation-to-procedure platforms.
The FDA regulates surgical implants and energy devices under distinct premarket pathways, with 510(k) clearance timelines directly influencing product launch sequencing for manufacturers. State medical boards in California, Texas, and Florida impose facility accreditation requirements that filter clinic-level market access and shape regional supply distribution. Stakeholders must monitor evolving scope-of-practice debates between plastic surgeons and dermatologists, as these jurisdictional decisions will determine which provider categories control procedural volume and device purchasing authority.
Market Dynamics
The platysmaplasty treatment market pivots on the tension between surgical precision and energy-based device commoditization, with FDA 510(k) clearance timelines for neck-tightening technologies compressing product development cycles and reshaping competitive entry barriers.
Growth Catalysts
- Medical tourism infrastructure:Brazil's established cosmetic surgery corridors channel international patients toward bundled neck rejuvenation packages, sustaining procedural volume despite domestic economic pressures.
- Energy device proliferation:Radiofrequency and ultrasound platforms cleared under streamlined FDA pathways expand clinic-level access to platysmal banding treatments previously reserved for surgical suites.
- Aging demographic weight:Cervical laxity concerns among patients aged 55-70 drive consult-to-procedure conversion in dermatology practices across California, Texas, and Florida.
Market Restraints
- Input cost volatility:Absorbable suture materials and biocompatible mesh implants face polymer supply chain disruptions, squeezing margins for surgical kit manufacturers.
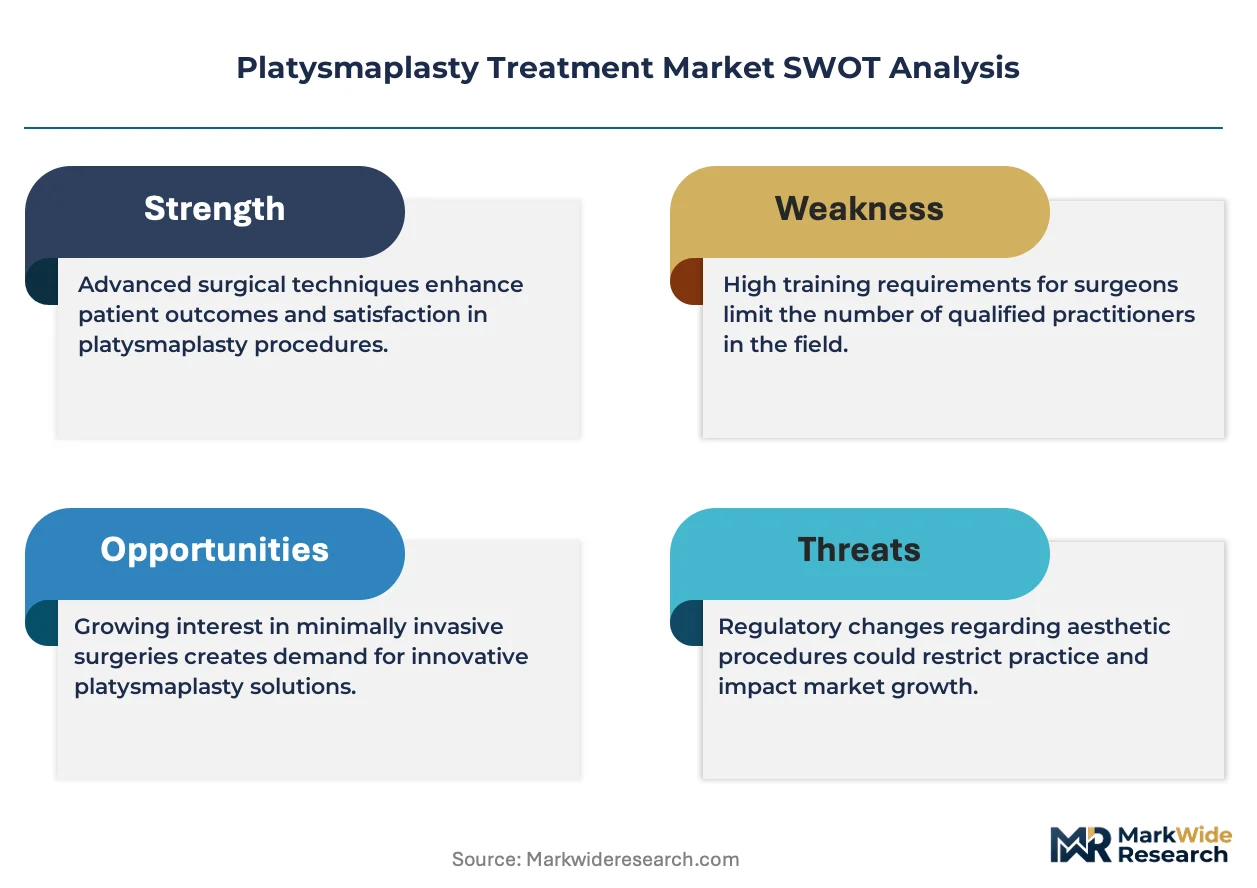
- Technical ceiling:Non-invasive modalities demonstrate limited efficacy for advanced platysmal separation, creating a treatment gap that surgical providers alone cannot scale to meet volume demand.
- Substitution acceleration:Neuromodulator and hyaluronic acid combinations for horizontal neck lines capture patients who might otherwise pursue platysmaplasty, diverting revenue from surgical practices.
Strategic Opportunities
- Telemedicine-to-procedure platforms:Remote consultation workflows that streamline surgical candidacy assessment reduce geographic friction for patients in secondary US markets lacking specialized providers.
- Combined therapy protocols:Integration of preoperative energy-based skin tightening with surgical platysmaplasty creates premium service tiers that capture margin from patients seeking comprehensive outcomes.
- State scope-of-practice expansion:Legislative proposals in Florida and Texas that broaden dermatologist authority to perform limited neck procedures would unlock new provider categories for device manufacturers.
Industry Challenges
- Cross-specialty credentialing complexity:Plastic surgeons and facial plastic surgeons maintain divergent training pathways for cervical procedures, complicating standardized competency verification across clinic networks.
- Facility accreditation bottlenecks:State medical board requirements for office-based surgical suites in California impose capital-intensive compliance burdens that filter independent practice participation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Platysmaplasty Treatment Market |
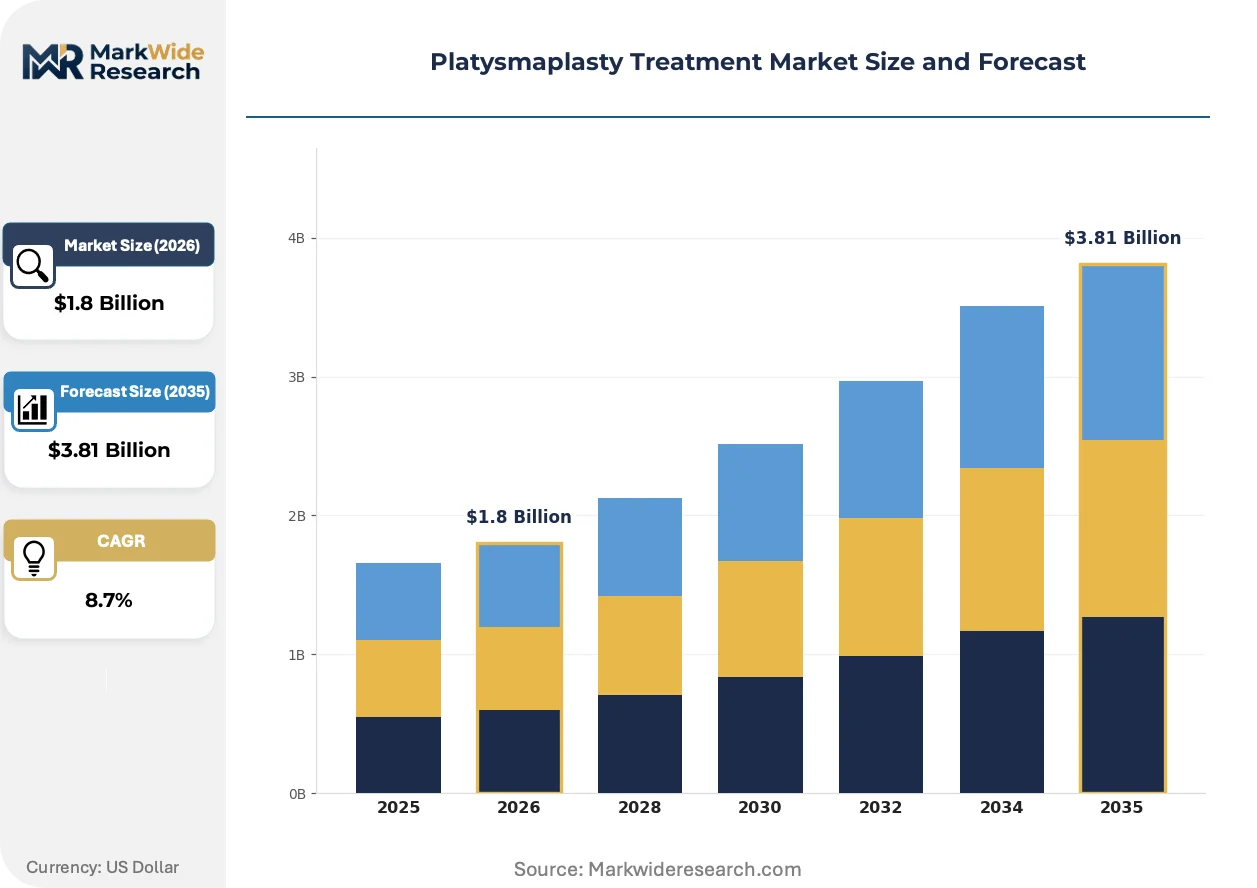
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectables, Surgical Implants, Energy Devices, Topical Treatments Application: Neck Rejuvenation, Skin Tightening, Facial Contouring, Aesthetic Surgery End User: Dermatology Clinics, Cosmetic Surgery Centers, Hospitals, Homecare Delivery Mode: In-Person Consultation, Telemedicine, Outpatient Procedure, Combined Therapy |
| Companies Covered | Allergan Aesthetics, Galderma SA, Merz Pharma, Cynosure LLC, InMode Ltd., Long Island Plastic Surgical Group, Westlake Dermatology & Cosmetic Surgery, Cadogan Clinic, Nazarian Plastic Surgery, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Platysmaplasty Treatment Market Evolving Landscape
Neck rejuvenation modalities are fragmenting across a spectrum from injectable neurotoxins to minimally invasive thread lifts, with device manufacturers racing to occupy the middle ground where downtime reduction meets durable structural correction.
Microfocused ultrasound with visualization (MFU-V) is electrifying the minimally invasive tier by delivering thermal coagulation points to the platysma without surface incision. Dermatology clinics in Miami and Los Angeles are adopting MFU-V as a bridge treatment for patients with early banding who resist surgical commitment. The technology is electrifying price compression in the non-surgical segment, forcing radiofrequency platform holders to differentiate through combination protocols or retreat toward lower-cost market positions.
The FDA's evolving guidance on energy-based aesthetic devices is tightening clinical evidence requirements for indications involving deeper tissue planes. Manufacturers now face expanded pivotal trial obligations for platysmal-targeting systems, extending time-to-market by 12-18 months relative to prior clearance pathways. Surgical implant suppliers with established 510(k) histories are accelerating PMA-submission strategies to secure durable competitive moats against emerging energy device competitors.
Patients are compressing their decision cycles through social media-facilitated before-and-after validation, reducing the traditional consultation-to-procedure interval from multiple visits to single-session commitment. Cosmetic surgery centers in São Paulo and Rio de Janeiro have adapted by offering real-time imaging simulations and same-day scheduling for surgical platysmaplasty. This behavioral shift pressures providers to maintain transparent pricing architectures and outcome documentation accessible through digital channels.
Platysmaplasty Treatment Market Segmentation
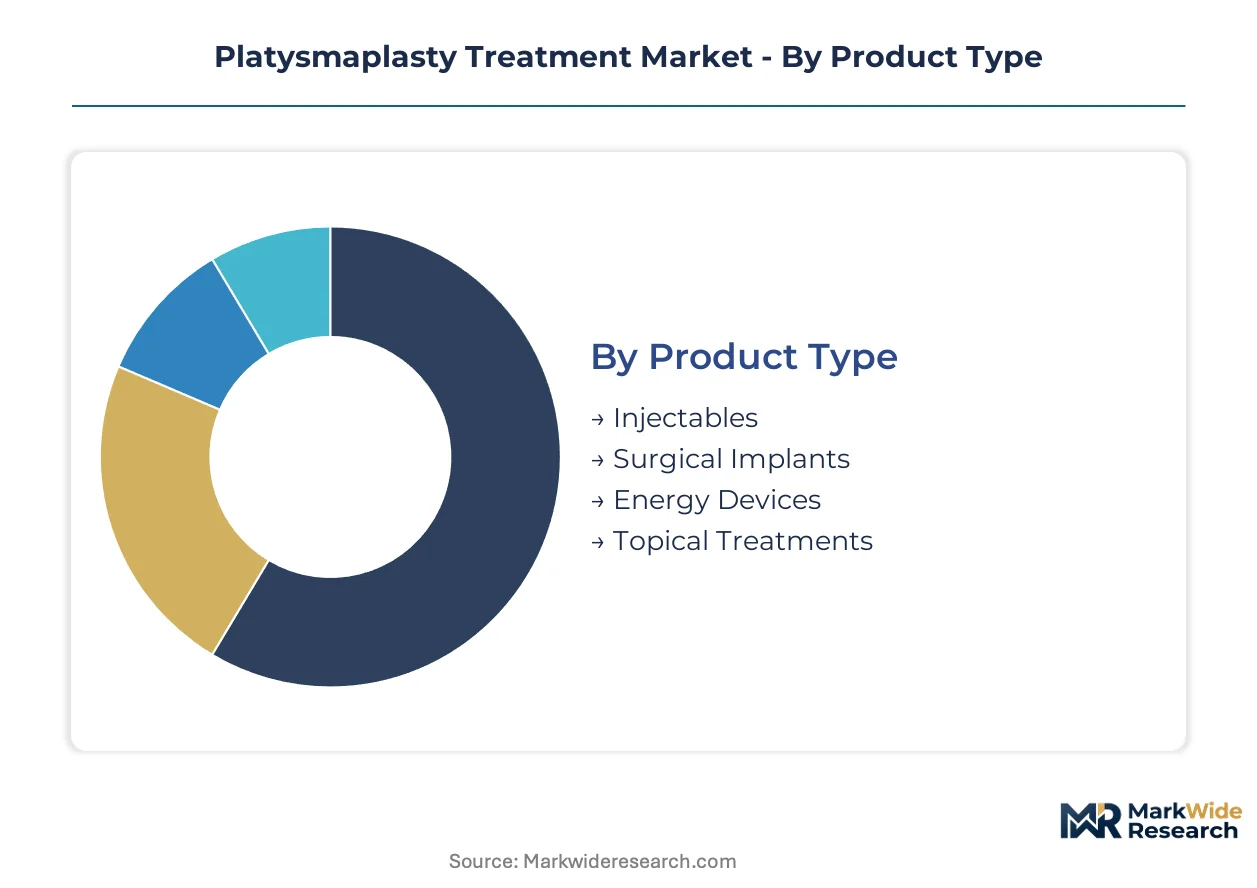
Platysmaplasty treatment segmentation reveals how patient risk tolerance and recovery constraints shape procurement patterns across provider networks. Product type and delivery mode decisions increasingly determine margin capture rather than pure volume throughput.
Product Type:
Cost tier stratification dominates buyer selection, with reimbursement status and capital expenditure requirements filtering clinic-level access.
- Injectables:Neuromodulator and hyaluronic acid formulations target horizontal neck lines through superficial dermal placement. Demand concentrates in Miami and Los Angeles dermatology practices where patients prioritize zero-downtime solutions over structural correction.
- Surgical Implants:Absorbable suture systems and biocompatible mesh constructs enable platysmal imbrication with durable fixation. Brazilian cosmetic surgery centers sustain highest procedural volumes through bundled neck rejuvenation packages attracting medical tourism flows.
- Energy Devices:Radiofrequency and microfocused ultrasound platforms deliver thermal coagulation to platysmal bands without incision. FDA 510(k) clearance pathways compress development cycles for manufacturers targeting clinic-based deployment.
- Topical Treatments:Retinoid and peptide formulations provide adjunctive skin quality maintenance post-procedure. Homecare adoption remains limited by efficacy ceiling for established platysmal banding.
Injectables lead on scale; energy devices lead on momentum.
Application:
Volume distribution tracks the severity spectrum of cervical aging, from early intervention to advanced structural correction.
- Neck Rejuvenation:Comprehensive correction of platysmal banding, submental fat, and skin laxity through surgical or combined approaches. California and Texas practices report strongest consult-to-procedure conversion among patients aged 55-70.
- Skin Tightening:Non-invasive collagen induction through energy-based dermal heating. Dermatology clinics in São Paulo deploy these modalities as bridge treatments delaying surgical commitment.
- Facial Contouring:Jawline definition enhancement through submental fat reduction and platysmal suspension. Brazilian surgeons integrate this with rhytidectomy for comprehensive facial rejuvenation.
- Aesthetic Surgery:Open surgical platysmaplasty with anterior neck access and muscle transection. Florida cosmetic surgery centers capture premium pricing through same-day scheduling and real-time imaging simulations.
Neck rejuvenation commands the largest addressable base; skin tightening is climbing the fastest.
End User:
Customer type determines purchasing authority and device specification requirements across the care continuum.
- Dermatology Clinics:Non-surgical volume leaders deploying injectables and energy devices under physician supervision. State scope-of-practice debates in Florida and Texas threaten to expand their procedural authority.
- Cosmetic Surgery Centers:Surgical margin concentration with facility accreditation requirements filtering market participation. California imposes capital-intensive compliance burdens for office-based surgical suites.
- Hospitals:Reconstructive and post-traumatic neck revision procedures utilizing operating room infrastructure. Academic medical centers in Brazil train international surgeons sustaining procedural knowledge transfer.
- Homecare:Nascent segment attracting venture funding for remote consultation-to-procedure platforms. Telemedicine workflows remain experimental for surgical candidacy assessment.
Dermatology clinics lead on scale; homecare leads on momentum.
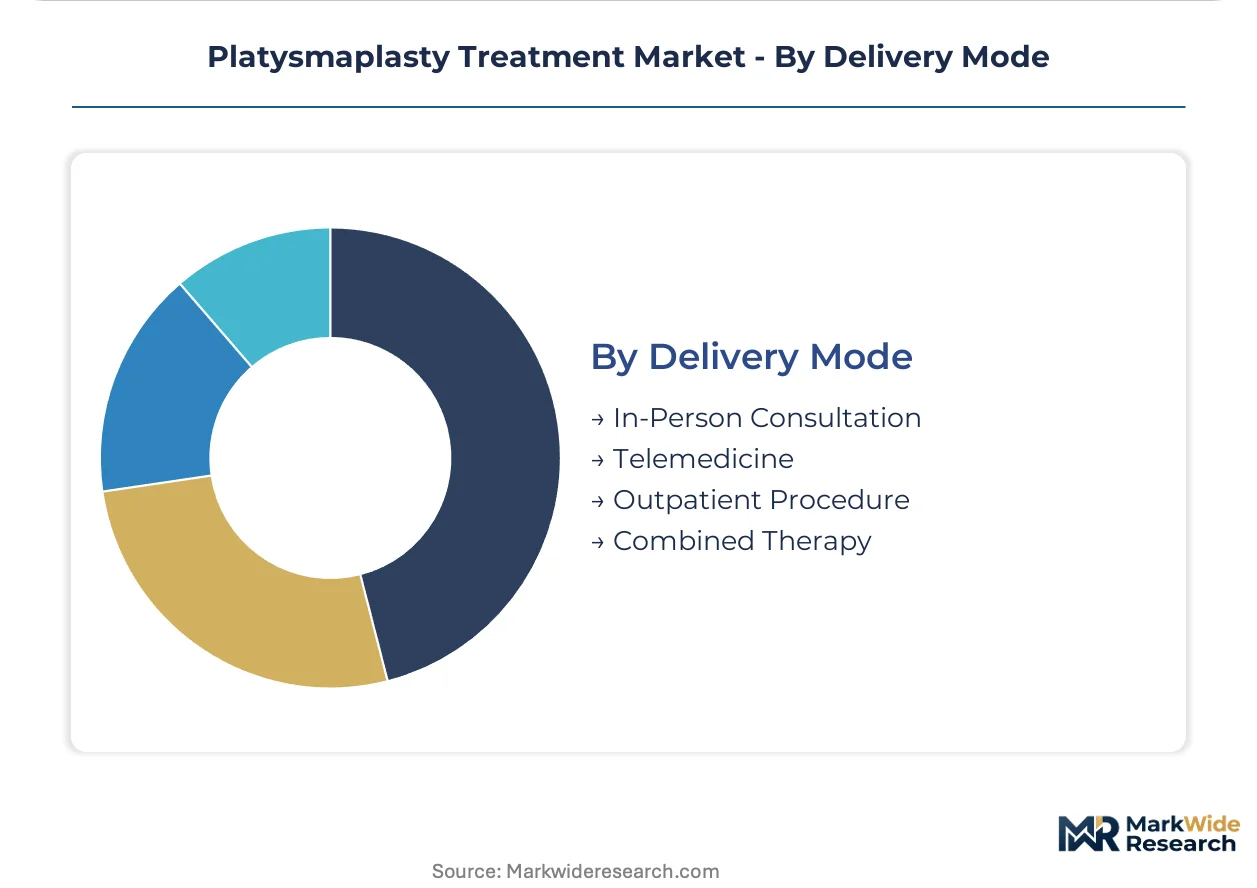
Delivery Mode:
Supply concentration shapes how providers configure patient touchpoints from initial inquiry through postoperative follow-up.
- In-Person Consultation:Traditional multi-visit pathway with physical examination and manual platysmal assessment. Rio de Janeiro centers have compressed this to single-session commitment through digital pre-qualification.
- Telemedicine:Remote screening and surgical candidacy triage reducing geographic friction for patients in secondary US markets. Regulatory uncertainty surrounds informed consent for procedural recommendations.
- Outpatient Procedure:Ambulatory surgical center or office-based suite deployment with local anesthesia and same-day discharge. Brazilian infrastructure supports this model through established cosmetic surgery corridors.
- Combined Therapy:Integration of preoperative energy-based tightening with surgical platysmaplasty for premium outcomes. Los Angeles and Miami practices capture margin from patients seeking comprehensive rejuvenation.
Outpatient procedure leads on scale; combined therapy leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Board-certified plastic surgeons and facial plastic surgeons cluster in metropolitan corridors with established medical tourism infrastructure and high disposable income density.
United States
Dermatology practices in Miami and Los Angeles drive non-surgical volume through injectable and energy-device protocols. FDA 510(k) clearance pathways for radiofrequency and ultrasound platforms compress development cycles for manufacturers targeting clinic deployment. California state medical board facility accreditation requirements impose capital-intensive compliance burdens that filter independent practice participation.
Brazil
Cosmetic surgery centers in São Paulo and Rio de Janeiro sustain the highest procedural volumes globally through bundled neck rejuvenation packages attracting international patients. ANVISA regulates surgical implants and energy devices under distinct premarket pathways that influence product launch sequencing. Brazilian surgeons integrate platysmaplasty with rhytidectomy for comprehensive facial rejuvenation, anchoring medical tourism flows.
Germany
Academic medical centers in Munich and Hamburg train international surgeons in cervical procedure techniques, sustaining knowledge transfer networks. MDR compliance requirements for surgical implants and energy-based devices extend time-to-market for manufacturers targeting the European Economic Area. German aesthetic medicine practices emphasize combination protocols integrating preoperative energy-based tightening with surgical intervention.
United Kingdom
Private cosmetic surgery groups in London's Harley Street district concentrate premium surgical volume for platysmal banding correction. CQC registration requirements for independent healthcare providers shape clinic-level market access and facility investment decisions. Cadogan Clinic anchors the premium-tier surgical segment through specialized neck rejuvenation service lines.
South Korea
Seoul-based dermatology clinics deploy microfocused ultrasound platforms as bridge treatments for patients with early platysmal banding. MFDS regulates energy-based aesthetic devices with clinical evidence requirements that influence manufacturer trial design. Gangnam district practices capture regional medical tourism flows through same-day scheduling and digital outcome documentation.
Platysmaplasty Treatment Market Competitive Landscape
Capital-heavy surgical implant manufacturers compete with asset-light energy device designers and injectable formulators for provider mindshare. The vendor base stratifies across three tiers: multinational pharmaceutical conglomerates with aesthetics divisions, specialized medical device manufacturers, and regional cosmetic surgery center networks. Surgical kit suppliers pursue PMA-submission strategies to secure durable competitive moats, while energy device manufacturers exploit streamlined 510(k) pathways for rapid clinic penetration. Portfolio diversification into combination therapy protocols and geographic expansion through distributor partnerships represent the dominant competitive vectors.
Within the pharmaceutical conglomerate tier, Allergan Aesthetics and Galderma SA exemplify archetypes leveraging injectables portfolios to anchor minimally invasive market positions. Merz Pharma occupies a middle position between injectables and surgical intervention through ultrasound-assisted delivery systems. Among specialized device manufacturers, Cynosure LLC and InMode Ltd. represent energy-based platform developers competing for dermatology clinic placement.
| Leading Market Players |
|---|
| Allergan Aesthetics |
| Galderma SA |
| Merz Pharma |
| Cynosure LLC |
| InMode Ltd. |
| Long Island Plastic Surgical Group |
| Westlake Dermatology & Cosmetic Surgery |
| Cadogan Clinic |
| Nazarian Plastic Surgery |
| Others |
Value Network & Pricing Analysis
Board-certified plastic surgeons concentrated in São Paulo and Los Angeles command labor-cost premiums that widen pricing-tier spreads between surgical suites and clinic-based alternatives. Their specialized cervical anatomy training sustains margin capture in premium bundled packages while dermatology practices in secondary US markets compete on unbundled, per-procedure rates.
Pricing Analysis
The bundled-vs-unbundled service split defines pricing architecture across provider tiers. Surgical implant kits with absorbable suture systems and biocompatible mesh constructs anchor premium-mid-economy pricing differentiation based on FDA clearance tier and facility accreditation status. Cost compression in energy-device segments intensifies as radiofrequency platform holders compete for dermatology clinic placement against streamlined 510(k) entrants. Price sensitivity concentrates among patients aged 55-70 seeking bridge treatments, while medical tourism packages in Brazil capture least-sensitive buyers demanding comprehensive outcomes.
Supply Chain Analysis
Freight cost volatility for temperature-sensitive biopolymer shipments from Germany and Japan elevates landed costs for absorbable suture materials. Raw material procurement draws from medical-grade polymer suppliers in the United States, precision-mesh weavers in Switzerland, and ultrasound transducer component manufacturers in South Korea. Single-source vulnerability concentrates in FDA-certified polymer grades, where regulatory requalification timelines deter supplier switching. Distribution runs through GPO-affiliated medical device distributors for hospital systems and direct manufacturer-to-clinic relationships for cosmetic surgery centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The platysmaplasty treatment market functions as a stable compounder, with aging demographic weight across California, Texas, and Florida sustaining consult-to-procedure conversion regardless of macroeconomic cycles.
For Market Incumbents: Extend proprietary energy-device platforms into combination therapy protocols that integrate preoperative skin tightening with surgical referral pathways. Secure PMA-submission moats for surgical implants before FDA tightens clinical evidence requirements for deeper-tissue indications. Backward integration into absorbable suture polymer sourcing mitigates margin pressure from supply chain disruptions. For New Entrants and Emerging Players: Enter via telemedicine-to-procedure platforms targeting secondary US markets lacking specialized cervical procedure providers. White-space availability concentrates in remote surgical candidacy assessment workflows and same-day scheduling infrastructure. A direct-to-patient digital marketing angle with transparent outcome documentation bypasses established referral networks. For Investors and Strategic Acquirers: Dermatology clinic networks with scope-of-practice expansion exposure in Florida and Texas are the most active acquirer in this space, consolidating regional purchasing authority ahead of legislative shifts. Long-term viability hinges on combined therapy protocol adoption rates rather than single-modality volume. The signal to monitor is FDA guidance publication timing for energy-based aesthetic device indications involving platysmal tissue planes.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Streamlined clearance pathways compress time-to-market for radiofrequency platform developers targeting clinic deployment. |
| Combination Therapy Protocol Development | Preoperative MFU-V integration with surgical platysmaplasty creates premium service tiers capturing margin from outcome-focused patients. |
| Telemedicine Platform Launch | Remote consultation workflows reduce geographic friction for patients in secondary US markets lacking specialized providers. |
| Scope-of-Practice Legislative Engagement | Florida and Texas proposals broadening dermatologist procedural authority unlock new provider categories for device manufacturers. |
| Medical Tourism Infrastructure Partnership | Brazilian cosmetic surgery corridor bundling sustains procedural volume through international patient flow capture. |
Research Methodology
Coverage spans the United States, Brazil, Germany, the United Kingdom, and South Korea, with primary inputs from each market informing demand-side calibration. The research combined structured interviews with plastic surgeons, dermatology practice administrators, biomedical engineers at device manufacturers, and hospital purchasing committee members with secondary validation from FDA 510(k) filings, ANVISA premarket submissions, MFDS device registrations, and clinical trial protocol disclosures. Bottom-up procedural volume estimates triangulated against top-down market sizing from manufacturer revenue disclosures and distributor shipment data.
Rate-of-change decomposition across the analysis window separated volume effects from price-mix shifts in energy-device versus surgical implant segments. The forecast framework modeled product type, application severity tier, end-user facility accreditation level, and delivery mode configuration as primary segmentation dimensions. CAGRs derived from procedure growth assumptions weighted by reimbursement status and capital expenditure requirements, with aging demographic projections and medical tourism flow estimates as key demand-side inputs.
Inputs from regulatory filing databases and manufacturer revenue disclosures were available through the study window; gaps in real-time procedural volume reporting from independent cosmetic surgery centers introduce uncertainty bands around short-term estimates. Forecasts reflect assumptions regarding FDA clearance pathway stability and scope-of-practice legislative timelines. Stakeholders should weight assumptions against their own operating context and regional regulatory exposure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aesthetic Medicine
Middle East and Africa Aesthetic Dermatology Market
Aesthetic Medicine
Asia-Pacific Dermal Fillers Market
Aesthetic Medicine
Spa Market
Aesthetic Medicine
Global Aesthetic Fillers Market
Aesthetic Medicine
North America Medical Aesthetic Devices Market
Aesthetic Medicine
Customized China Aesthetics Equipment Market
Aesthetic Medicine
Medical Aesthetic Dermal Filler Market
Aesthetic Medicine
Body Contouring Market
Aesthetic Medicine
UAE Laser Hair Removal Market
Aesthetic Medicine
Australia Facial Injectable Market
Aesthetic Medicine
Phototherapy Lamps and Units for Aesthetic Medicine Market
Aesthetic Medicine
Aesthetic Surgery Procedures Market
Aesthetic Medicine
Energy-Based Aesthetic Devices Market
Aesthetic Medicine
Spain Facial Aesthetics Market
Aesthetic Medicine
Asia-Pacific Aesthetic Dermatology Market
Aesthetic Medicine
Radio Frequency Beauty Equipment Market