
 Hemodialysis Vascular Graft Market | 2026-2036
Hemodialysis Vascular Graft Market Size, Share, and Industry Trends Forecast 2026-2036
Hemodialysis Vascular Graft Market Foresight
Polymer manufacturing clusters in the eastern United States is broadening substrate availability for graft producers. W.L. Gore & Associates leverages its fluoropolymer expertise to sustain premium positioning in expanded PTFE architectures. CryoLife anchors biological tissue processing capabilities that differentiate its portfolio from synthetic competitors. Merit Medical Systems competes through vertical control over catheter and access device portfolios.
A hemodialysis vascular graft is a synthetic or biological conduit surgically implanted to create arteriovenous access for repeated cannulation during renal replacement therapy, typically manufactured from expanded polytetrafluoroethylene (ePTFE) with wall thicknesses of 0.4–0.6 mm and porosities calibrated to balance tissue ingrowth against hemorrhage risk. ePTFE Grafts dominate current revenue pools due to decades of clinical validation and surgeon familiarity, while Collagen-Enhanced Grafts represent the fastest-growing category as manufacturers integrate extracellular matrix components to improve endothelialization and reduce thrombogenicity. Dialysis Centers constitute the most concentrated end-user segment by procedure volume, though Hospitals capture disproportionate margin pools through complex surgical placements and complication revisions.
The FDA enforces 510(k) clearance pathways with escalating biocompatibility and fatigue-testing standards for permanent implantable vascular devices, while ISO 7198 specifies dimensional and mechanical performance benchmarks that shape global product specifications. The EU Medical Device Regulation (MDR) imposes stricter clinical-evidence requirements and post-market surveillance obligations on graft manufacturers seeking CE marking. Stakeholders must monitor how evolving FDA guidance on physiologic flow modeling and updated ISO standards for vascular prostheses will reshape R&D prioritization and regulatory submission timelines.
Market Dynamics
The FDA's escalating biocompatibility testing mandates for vascular access products are forcing graft manufacturers to restructure R&D timelines and validation protocols, compressing competitive windows for new market entrants.
Growth Catalysts
- Biological tissue processing:CryoLife's differentiated portfolio demonstrates clinical validation for collagen-enhanced architectures, accelerating surgeon acceptance of hybrid graft categories.
- ISO 7198 dimensional benchmarks:Standardized mechanical performance specifications reduce regulatory friction for multi-market submissions, streamlining commercial expansion.
- Dialysis center consolidation:Procedure volume concentration in United States outpatient facilities creates predictable demand patterns for synthetic polymer suppliers.
Market Restraints
- Fluoropolymer supply concentration:ePTFE substrate production clusters in eastern United States create geographic vulnerability for graft manufacturers dependent on regional polymer processing.
- EU MDR clinical-evidence thresholds:Stricter post-market surveillance obligations for CE marking extend certification timelines and inflate regulatory compliance costs.
- Catheter-based dialysis access:Tunneled central venous catheters retain indication share for acute renal failure, limiting addressable market expansion for permanent grafts.
Strategic Opportunities
- Endothelialization acceleration:Extracellular matrix component integration represents unmet clinical need, with collagen-enhanced grafts capturing fastest-growing category positioning.
- Complex surgical placement services:Hospital-based complication revision procedures command disproportionate margin pools compared to routine dialysis center placements.
- Physiologic flow modeling guidance:Updated FDA guidance on hemodynamic simulation creates first-mover advantage for manufacturers with computational fluid dynamics capabilities.
Industry Challenges
- Biocompatibility validation timelines:FDA 510(k) fatigue-testing standards for permanent implantable devices extend pre-market submission preparation by 12-18 months.
- Surgeon training standardization:Heterogeneous cannulation technique across dialysis centers produces variable graft survival outcomes, complicating clinical evidence generation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hemodialysis Vascular Graft Market |
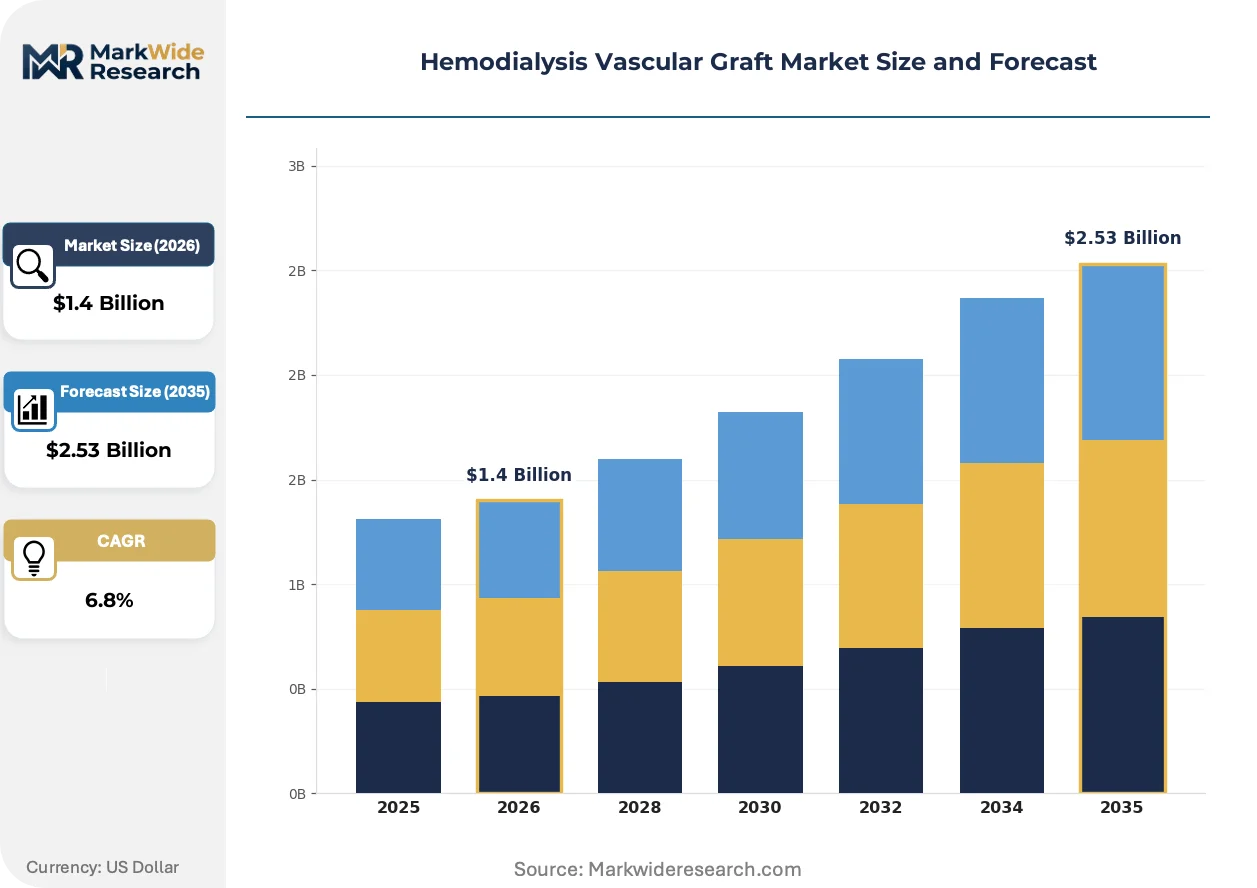
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PTFE Grafts, ePTFE Grafts, Collagen-Enhanced Grafts, Non-Biodegradable Grafts End User: Hospitals, Dialysis Centers, Clinics, Home Care Providers Material: Biomaterials, Synthetic Polymers, Composite Materials, Metal Alloys Application: Hemodialysis Access, Vascular Surgery, Transplantation, Research |
| Companies Covered | Getinge AB, CryoLife, W.L. Gore & Associates, Vascudyne, Merit Medical Systems, Terumo Corporation, C. R. Bard, B. Braun Melsungen, LeMaitre Vascular, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hemodialysis Vascular Graft Market Shifts & Advancements
Manufacturing technology and regulatory science are reshaping graft development priorities, with biocompatibility engineering and flow dynamics simulation displacing traditional material-centric R&D approaches.
Collagen-enhanced graft architectures are converging with synthetic polymer substrates to accelerate endothelialization and reduce thrombogenicity. Dialysis centers in the United States are piloting these hybrid constructions for routine arteriovenous access, though surgeon familiarity with legacy ePTFE remains a adoption constraint. This convergence is compressing development cycles for biological-synthetic composite products.
EU Medical Device Regulation post-market surveillance obligations are intensifying clinical evidence requirements for CE-marked vascular prostheses. Manufacturers must now maintain active implant registries and periodic safety update reports, inflating compliance infrastructure costs. Small and mid-cap graft producers without established European notified body relationships face disproportionate certification barriers.
Hospital procurement committees are consolidating supplier relationships for vascular access portfolios, bundling graft procurement with catheter and access device contracts. Merit Medical Systems leverages vertical control across these categories to defend account relationships, while standalone graft specialists face margin compression. This concentration is most visible in United States integrated delivery networks managing high-volume dialysis populations.
Hemodialysis Vascular Graft Market Segmentation
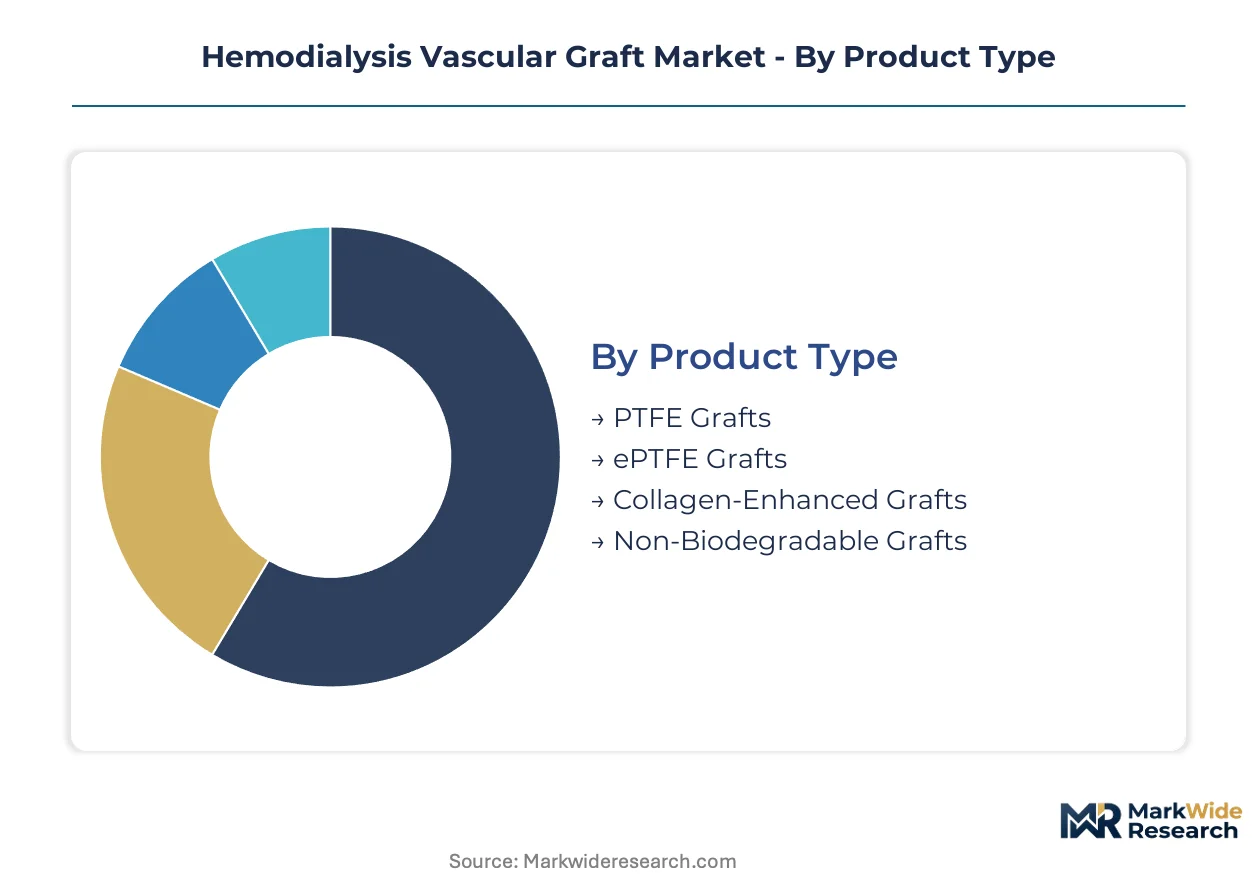
Graft segmentation reveals how material science, clinical setting, and procedural complexity fragment procurement decisions. Manufacturers must align product architectures with distinct validation requirements and reimbursement pathways across each dimension.
Product Type:
Standardization dominates PTFE and ePTFE platforms, while collagen integration demands bespoke manufacturing protocols and extended biocompatibility validation.
- ePTFE Grafts:Expanded polytetrafluoroethylene substrates with calibrated 0.4–0.6 mm wall thickness and engineered porosity balance tissue ingrowth against hemorrhage risk. Dialysis centers in the United States concentrate procurement here due to decades of surgeon familiarity and established reimbursement codes.
- Collagen-Enhanced Grafts:Hybrid architectures integrating extracellular matrix components with synthetic polymer scaffolds to accelerate endothelialization and reduce thrombogenicity. Hospital-based surgical services drive adoption as these command premium pricing for complex arteriovenous access procedures.
- PTFE Grafts:Non-expanded fluoropolymer conduits with denser wall structures suitable for specific anatomical constraints.
- Non-Biodegradable Grafts:Permanent implantable constructs designed for multi-year cannulation cycles without structural degradation.
Most installed capacity flows through ePTFE Grafts. Expansion is steepest in Collagen-Enhanced Grafts.
End User:
Volume concentration diverges from margin capture, with outpatient facilities driving procedure counts while acute care settings extract premium economics from complication management.
- Dialysis Centers:Outpatient facilities performing routine arteriovenous access cannulation on chronic renal replacement populations. United States dialysis center consolidation creates predictable demand patterns for synthetic polymer suppliers with national distribution networks.
- Hospitals:Acute care institutions managing complex surgical placements, revision procedures, and graft complications. These capture disproportionate margin pools through bundled vascular access contracts and catheter portfolio integration.
- Clinics:Ambulatory surgical centers handling intermediate-complexity graft placements with shorter procedure timelines.
- Home Care Providers:Emerging segment coordinating patient monitoring and cannulation training for remote dialysis populations.
Procedure volume concentrates in Dialysis Centers. Value capture concentrates in Hospitals.
Material:
Supply chain geography and regulatory validation burden separate commodity polymer feedstocks from engineered biological-synthetic composites.
- Synthetic Polymers:ePTFE and fluoropolymer substrates manufactured in eastern United States polymer processing clusters. FDA 510(k) clearance pathways with escalating fatigue-testing standards shape commercial timelines for permanent implantable devices.
- Biomaterials:Processed biological tissues and collagen matrices requiring CryoLife-style cold-chain infrastructure and donor screening protocols. EU MDR post-market surveillance obligations intensify clinical evidence requirements for CE-marked biological vascular prostheses.
- Composite Materials:Engineered combinations of synthetic polymers with biological coatings or reinforcement layers.
- Metal Alloys:Nitinol and stainless steel components for structural support elements in hybrid graft designs.
Revenue concentration favors Synthetic Polymers. R&D investment flows toward Biomaterials.
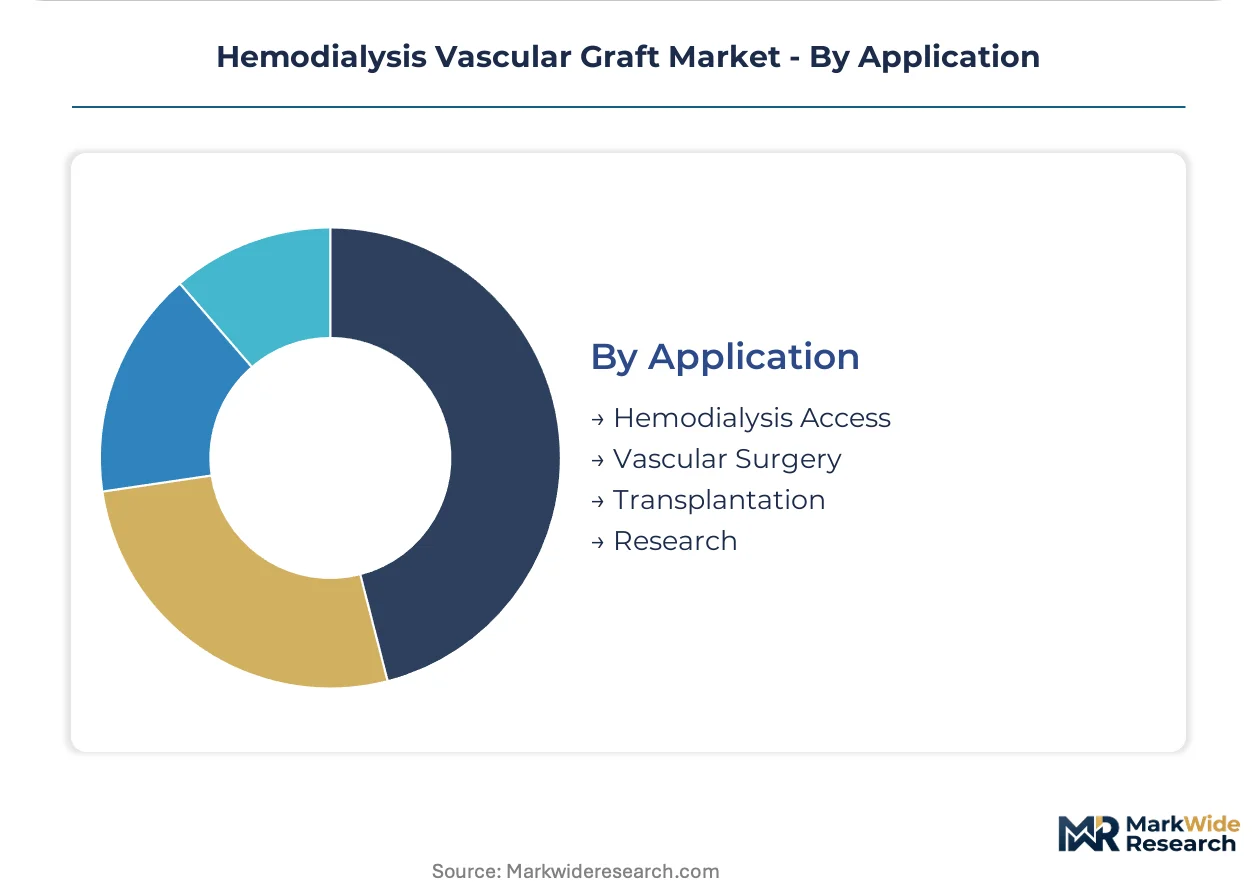
Application:
Clinical indication breadth determines regulatory pathway complexity and post-market surveillance intensity.
- Hemodialysis Access:Primary indication for arteriovenous graft creation in end-stage renal disease populations. ISO 7198 dimensional and mechanical performance benchmarks standardize specifications across United States and European submissions.
- Vascular Surgery:Peripheral bypass and trauma reconstruction applications with distinct hemodynamic performance requirements. Hospital procurement committees bundle these with dialysis access portfolios, favoring suppliers with vertical control across catheter and graft categories.
- Transplantation:Vascular anastomosis support in solid organ transplant procedures.
- Research:Preclinical and clinical trial applications driving next-generation graft architecture validation.
Commercial scale centers on Hemodialysis Access. Technology migration originates in Vascular Surgery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States sustains higher procedure volumes per capita than Germany, though both markets face tightening biocompatibility validation requirements that compress commercial timelines for new graft architectures.
United States
Dialysis center consolidation in Florida and Texas generates predictable demand patterns for synthetic polymer suppliers. FDA 510(k) clearance pathways enforce escalating fatigue-testing standards for permanent implantable vascular devices. Polymer processing clusters in North Carolina and Ohio broaden substrate availability for ePTFE graft manufacturers serving national distribution networks.
Germany
Hospital procurement committees in Bavaria and Baden-Württemberg bundle vascular access contracts with catheter portfolios. EU Medical Device Regulation post-market surveillance obligations extend certification timelines for CE-marked biological prostheses. Medical technology manufacturers in the Stuttgart and Munich metropolitan regions maintain cold-chain infrastructure for processed tissue grafts.
Japan
Aging demographics in the Kanto and Kansai regions expand the chronic renal replacement population base. PMDA marketing approval pathways align with ISO 7198 dimensional benchmarks for multi-regional submissions. Tokyo-based medical device distributors coordinate graft procurement for hospital-based surgical services managing complex arteriovenous access procedures.
China
End-stage renal disease prevalence in the Yangtze River Delta and Pearl River Delta drives hemodialysis infrastructure expansion. NMPA medical device registration requirements incorporate biocompatibility testing protocols adapted from international standards. Domestic polymer processors in Jiangsu and Guangdong provinces develop fluoropolymer substrate capabilities for synthetic graft production.
France
Hospital networks in Île-de-France and Auvergne-Rhône-Alpes manage complex graft placement and complication revision procedures. ANSM post-market vigilance obligations intensify clinical evidence requirements for vascular prostheses seeking market authorization. Medical device clusters in the Lyon and Paris regions coordinate with notified bodies for CE marking under EU MDR frameworks.
Hemodialysis Vascular Graft Market Competitive Landscape
United States producers anchor one tier; European specialists hold differentiated positions through tissue processing capabilities. The vendor base separates into consolidated synthetic polymer suppliers, biological graft processors, and vertically integrated access device portfolios. Three archetypes dominate: fluoropolymer substrate experts, collagen-enhanced architecture developers, and catheter-graft bundling strategists. Competitive moves concentrate on regulatory pre-validation partnerships and backward integration into polymer feedstock processing.
Within the biological processing tier, CryoLife exemplifies cold-chain infrastructure deployment for collagen-enhanced graft categories. Among fluoropolymer substrate specialists, W.L. Gore & Associates occupies a position representing premium-tier ePTFE architecture supply. At the integrated portfolio end, Merit Medical Systems anchors the bundling archetype spanning catheter and graft procurement relationships. These three entities represent distinct competitive vectors without implying specific market share positions or strategic actions.
| Leading Market Players |
|---|
| Getinge AB |
| CryoLife |
| W.L. Gore & Associates |
| Vascudyne |
| Merit Medical Systems |
| Terumo Corporation |
| C. R. Bard |
| B. Braun Melsungen |
| LeMaitre Vascular |
| Others |
Supply & Pricing Matrix
Biocompatibility certification tiers separate premium collagen-enhanced grafts from commodity ePTFE platforms, with this divergence amplifying both pricing power for validated architectures and geographic concentration in fluoropolymer feedstock sourcing. FDA fatigue-testing mandates and ISO 7198 compliance layers create cost ladders that concentrate margin capture among manufacturers with captive polymer processing capabilities.
Pricing Analysis
Capacity additions in China and domestic United States polymer processing are reshaping price floors for synthetic graft substrates while collagen-enhanced categories sustain premium positioning through extended validation timelines. Three-tier pricing structure across premium biologic-synthetic composites, standard ePTFE platforms, and economy PTFE alternatives reflects certification burden and endothelialization performance. Pricing pressure stems from dialysis center procurement consolidation demanding volume discounts on routine synthetic placements. Hospital-based surgical services exhibit lowest price sensitivity due to bundled vascular access contracts prioritizing complication avoidance over unit cost.
Supply Chain Analysis
Direct-to-dialysis-center distribution handles high-volume synthetic graft demand while hospital procurement committees manage complex placement bundles through integrated delivery networks. Geographic supply concentration centers on United States eastern seaboard fluoropolymer clusters, Chinese Jiangsu and Guangdong substrate development zones, and German Stuttgart-region cold-chain tissue processing infrastructure. Raw material dependencies span ePTFE resin, processed collagen matrices, and nitinol structural components. Single-source vulnerability in fluoropolymer precursor supply creates exposure to regional production disruptions. Distribution runs through national GPO contracts for dialysis chains and direct manufacturer relationships for hospital-based surgical services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
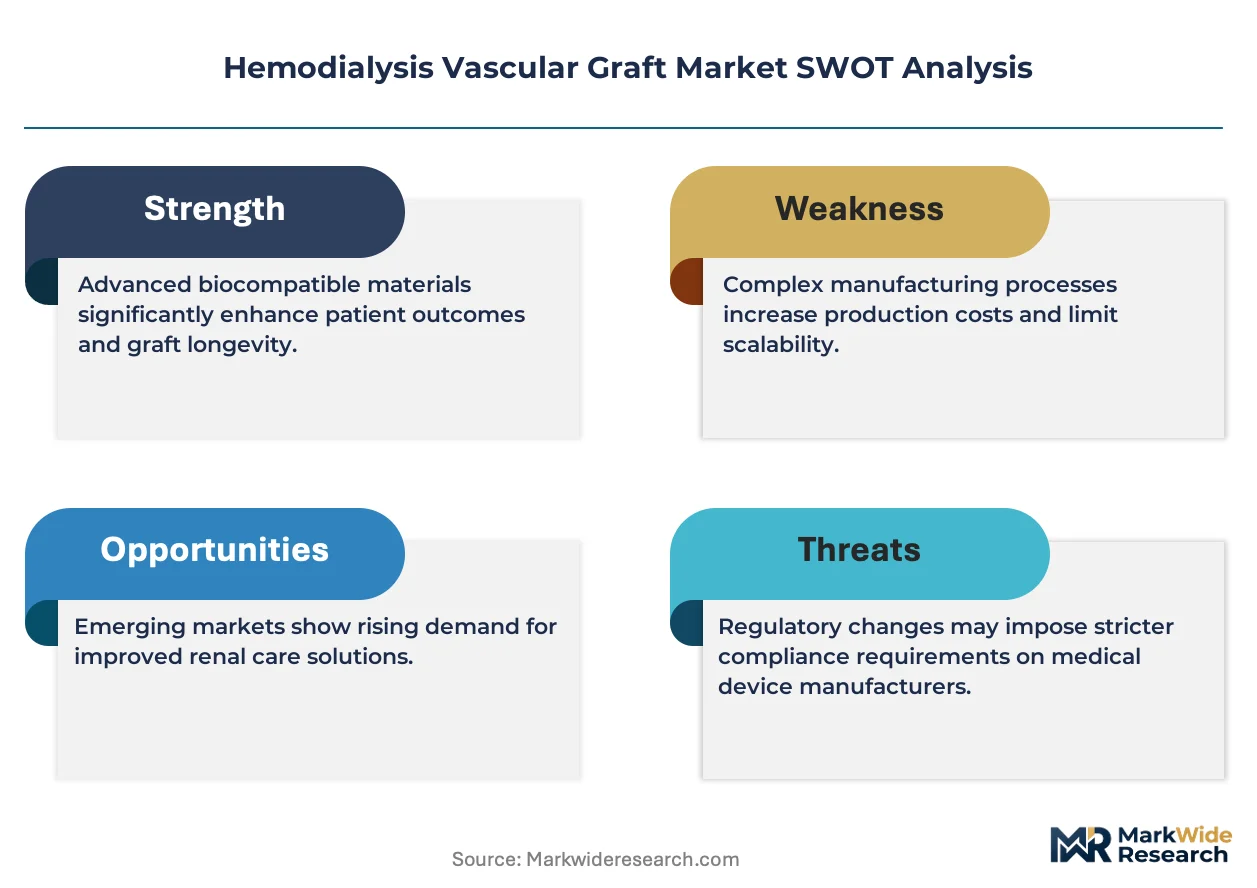
This market reads as a late-cycle quality story where surgeon demand shifts toward collagen-enhanced architectures with demonstrated endothelialization acceleration justify sustained R&D investment in biocompatibility engineering.
For Market Incumbents: To counter catheter-based dialysis access substitution and emerging biological graft competitors, incumbents should deepen backward integration into fluoropolymer precursor production in North Carolina and Ohio processing clusters while accelerating FDA pre-submission partnerships for physiologic flow modeling capabilities that compress 510(k) validation timelines.
For New Entrants and Emerging Players: The premium-to-economy price-point gap in collagen-enhanced categories creates entry opportunity through focused positioning on hospital-based complication revision procedures where bundled vascular access contracts reward endothelialization performance. Most penetrable white-space sits in United States integrated delivery networks managing high-volume dialysis populations with unmet hybrid graft demand. Go-to-market execution should prioritize direct surgeon education partnerships over GPO channel competition.
For Investors and Strategic Acquirers: Consolidation pressure builds where EU MDR post-market surveillance obligations and FDA escalating biocompatibility standards create disproportionate compliance burdens for mid-cap graft producers lacking established notified body relationships. Long-term viability favors manufacturers with dual synthetic polymer and biological tissue processing capabilities spanning the full graft architecture spectrum. Signal to monitor: hospital procurement committee consolidation velocity toward bundled catheter-graft contracts.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Pre-Submission Partnership | Accelerates biocompatibility validation timelines for permanent implantable vascular devices. |
| CE Marking Pathway Under EU MDR | Secures European market access through intensified clinical-evidence and surveillance obligations. |
| Hospital System Partnership | Defends account relationships through bundled vascular access portfolio procurement contracts. |
| Backward Integration into Polymer Feedstock | Captures margin compression risk from eastern United States fluoropolymer supply concentration. |
| Reimbursement Strategy | Aligns collagen-enhanced graft coding with premium pricing for complex surgical placement services. |
Research Methodology
Coverage spans United States, Germany, Japan, China, and France, with primary inputs from each market informing demand modeling and regulatory pathway analysis. The approach combines structured interviews with vascular surgeons, dialysis center medical directors, hospital purchasing committee members, and GPO contracts managers with secondary validation through FDA 510(k) filings, EU MDR notified body documentation, hospital procurement databases, and ISO standard revision records. Bottom-up procedure volume estimates and top-down manufacturer capacity assessments undergo triangulation for convergence.
Rate-of-change decomposition separates volume expansion from value migration across material type, end-user setting, and application complexity dimensions over the projection horizon. The analytical framework models hemodialysis access procedure growth, collagen-enhanced graft penetration curves, and synthetic polymer placement stability throughout the forecast period. CAGRs derive from regression-adjusted historical trend extrapolation modified by regulatory timeline impacts and surgeon adoption elasticity for hybrid architectures.
Caveats apply where FDA guidance revisions on physiologic flow modeling or updated ISO 7198 vascular prosthesis standards could materially shift the outlook for new entrant commercialization timelines. Forecasts reflect assumptions regarding dialysis center consolidation velocity, EU MDR enforcement consistency, and fluoropolymer substrate supply stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nephrology
Renal Cell Carcinoma Market
Nephrology
Kidney/Renal Function Test Market
Nephrology
US Dialysis Market
Nephrology
Drug-Induced Nephrotoxicity Treatment Market
Nephrology
Renal Stent Market
Nephrology
Renal Artery Stenosis Treatment Market
Nephrology
Global Hepatorenal Syndrome Treatment Market
Nephrology
Renal Insufficiency Treatment Market
Nephrology
Dialysis Service Market
Nephrology
Global Nephroblastoma Treatment Market
Nephrology
Kidney Dialysis Equipment Market
Nephrology
Kidney Transplant Medicine Market
Nephrology
Global Acute Kidney Injury Treatment Market
Nephrology
Lupus Nephritis Treatment Market
Nephrology
Renal Artery Embolization Market
Nephrology
Global Dialysis Market