
 US Hearing Aids Market | 2026-2036
US Hearing Aids Market Size, Share, and Industry Trends Forecast 2026-2036
US Hearing Aids Market Intelligence
The integration of direct-to-consumer sales platforms with telehealth support is fragmenting the traditional audiologist-centric distribution model in the US. Sonova leverages its diverse product portfolio to compete across both traditional clinics and emerging online channels. Starkey Hearing Technologies differentiates through advanced sensor integration and custom-fit solutions distributed via professional networks. Eargo Inc. specializes in the direct-to-consumer, self-fitting device category, targeting a different consumer base.
A hearing aid is a small electronic device designed to amplify sound for individuals with hearing loss. It uses a microphone, a digital signal processor (DSP), and a receiver to capture, process, and deliver sound into the ear canal. While Behind-The-Ear models remain prevalent for their power, demand for discreet In-The-Ear and Completely-In-Canal styles is significant. Technology is shifting towards Rechargeable power sources and Bluetooth Enabled connectivity for seamless integration with other personal electronics.
The US Food and Drug Administration (FDA) has fundamentally altered the competitive landscape by establishing a regulatory pathway for over-the-counter (OTC) hearing aids. This ruling expands consumer access outside of traditional audiology clinics, while HIPAA regulations continue to govern patient data privacy for connected devices. Success for manufacturers now depends on navigating this dual market structure and clearly differentiating between medical-grade and consumer-oriented products.
Market Dynamics
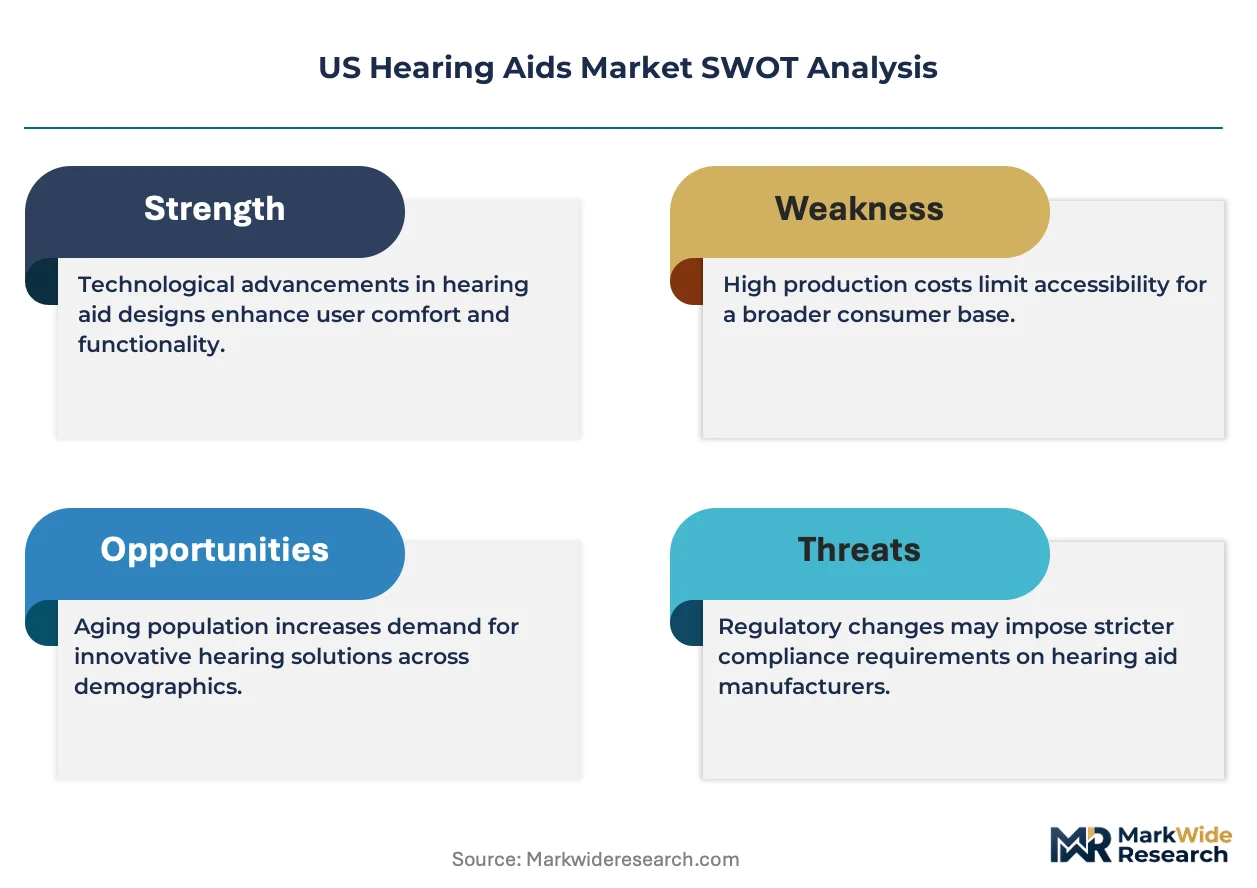
The central structural force in the US hearing aid market is the creation of a dual-channel system by the FDA. This regulatory action establishes a clear divide between traditional medical devices and a new category of consumer-accessible OTC products.
Growth Catalysts
- FDA OTC Regulation:This ruling creates a new over-the-counter sales channel, expanding consumer access and stimulating demand for self-fitting devices designed for mild to moderate hearing loss.
- Aging Demographics:The growing elderly population in the US, particularly in states with high senior concentrations like Florida and Arizona, provides a sustained source of new users for hearing aids.
- Technology Integration:Adoption of rechargeable batteries and Bluetooth connectivity enhances user convenience, integrating aids with personal electronics like smartphones and improving the overall user experience.
Market Restraints
- High Traditional Cost:The high price of professionally fitted hearing aids remains a significant barrier, pushing some consumers toward unregulated personal sound amplification products (PSAPs) as perceived substitutes.
- Data Privacy Compliance:HIPAA regulations for connected devices introduce complexity and cost, particularly for new entrants in the OTC space who must securely manage protected health information.
- Technical Limitations:Limited battery longevity in miniaturized In-The-Canal devices presents a functional trade-off against strong user demand for discreet, less visible form factors.
Strategic Opportunities
- Telehealth Integration:Developing direct-to-consumer platforms that incorporate remote telehealth support and virtual consultations offers a way to serve the emerging OTC market effectively and build consumer trust.
- Health Monitoring Functions:Integrating biometric sensors for functions like fall detection or activity tracking can reposition hearing aids as multifunctional health wearables, creating new value propositions beyond sound amplification.
- Targeting Underserved Segments:Marketing discreet, aesthetically-focused products to younger adults with mild hearing loss can help overcome historical stigma and capture a historically underpenetrated demographic.
Industry Challenges
- Dual-Market Navigation:Manufacturers face the challenge of managing distinct quality systems, regulatory submissions, and marketing strategies for medical-grade versus OTC product lines under FDA guidelines.
- Channel Conflict:Balancing the growth of direct online sales with the business models of established audiologist distribution networks creates friction and requires careful channel management.
- Consumer Education Gap:A significant challenge is educating the public on the functional differences between OTC aids, professionally fitted devices, and PSAPs to ensure appropriate selection and manage performance expectations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Hearing Aids Market |
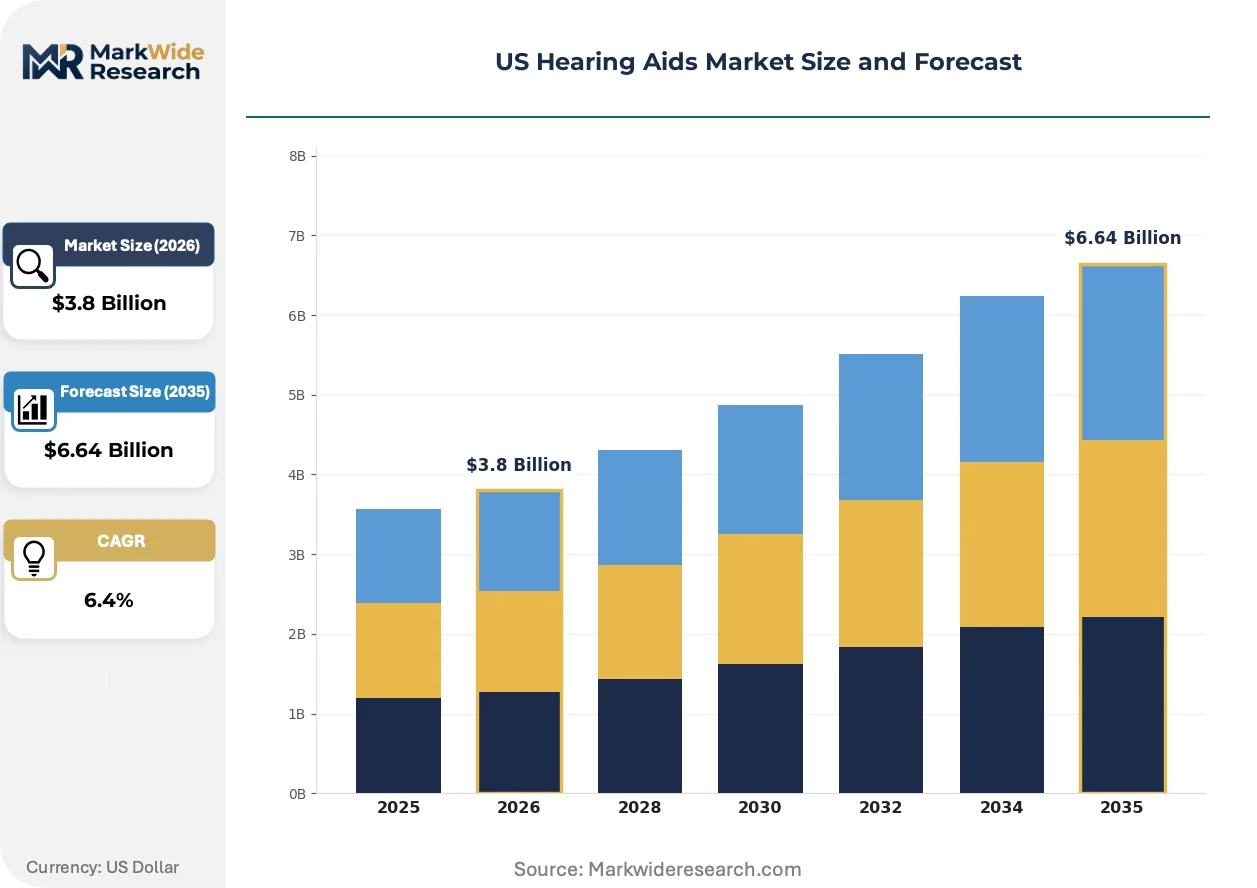
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Behind-The-Ear, In-The-Ear, Receiver-In-Canal, Completely-In-Canal, Eyeglass Hearing Aids Technology: Digital, Analog, Bluetooth Enabled, Rechargeable, Wireless End User: Elderly Adults, Seniors, Individuals with Sensorineural Hearing Loss, Veterans Distribution Channel: Specialty Stores, Audiologists, Online Platforms, Hearing Clinics, Retail Pharmacies |
| Companies Covered | Sonova, Demant A/S, GN Store Nord A/S, WS Audiology, Starkey Hearing Technologies, Eargo Inc., Cochlear Limited, MDHearing, Audicus, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Hearing Aids Market Strategic Shifts & Innovations
Convergence between medical device engineering and consumer electronics design is reshaping the US hearing aid market. This shift is driven by new regulations and evolving user expectations for connectivity and personalization.
Digital signal processors (DSPs) provide the foundation for advanced audio features like noise reduction and speech clarity. Consumers across all hearing loss severities are adopting devices with sophisticated DSP capabilities. The integration of AI with this hardware is digitizing the user experience, enabling real-time environmental sound classification and automatic adjustments.
The FDA's final rule established an over-the-counter category for hearing aids treating perceived mild to moderate hearing loss. This policy removes the requirement for a medical exam or professional fitting for this product class. The direct-to-consumer segment is most affected, spurring innovation in self-fitting applications and new retail strategies.
Consumer purchasing behavior is evolving from a medical transaction to a consumer electronics model. This change disrupts the traditional audiologist-centric channel, as online platforms and direct sales gain significant traction. The trend is most visible among younger, tech-savvy adults in major US metropolitan areas.
US Hearing Aids Market Segmentation
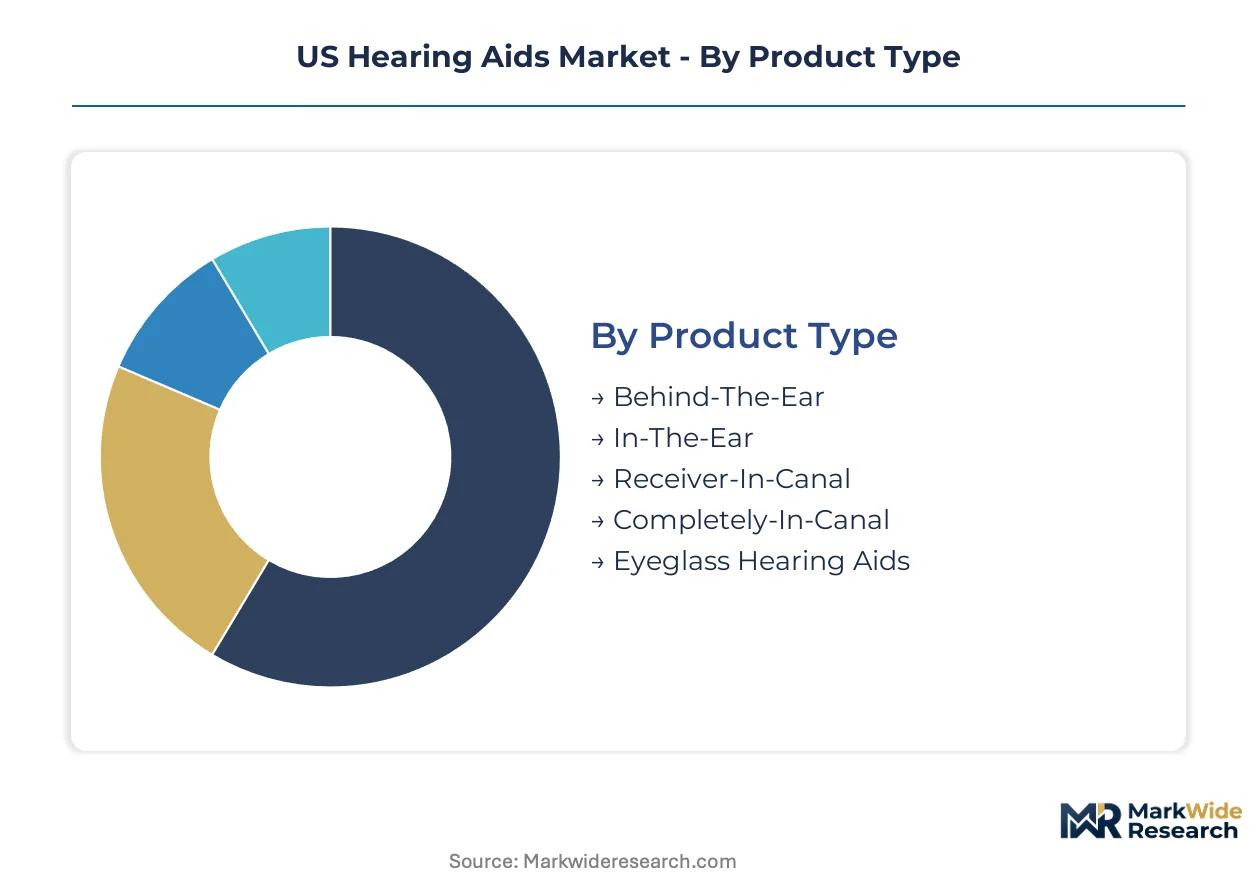
The US hearing aids market segments across product types, technological integrations, end-user demographics, and distribution channels. Understanding these divisions highlights where demand concentrates and how new regulatory frameworks are redefining access points for consumers.
Product Type:
The product type segmentation reveals a blend of mature, established form factors and emerging, discreet designs.
- Behind-The-Ear:This form factor houses components behind the ear, connecting to an earmold or thin tube. Demand for these devices remains strong among users requiring higher power output for significant hearing loss across US states.
- In-The-Ear:These custom-molded devices fit directly inside the outer ear bowl, offering a balance of discretion and power. Younger adults in metropolitan areas frequently seek these less visible solutions, driving segment expansion.
- Receiver-In-Canal:A small case behind the ear connects to a thin wire with a receiver placed in the ear canal.
- Completely-In-Canal:These are the smallest hearing aids, custom-molded to fit entirely within the ear canal, offering maximum discretion.
- Eyeglass Hearing Aids:Components are integrated into the temple of eyeglasses, often used when other styles are not suitable.
Behind-The-Ear models retain volume leadership; In-The-Ear styles hold the steepest expansion curve.
Technology:
Technology adoption patterns differentiate user experiences across various functional enhancements.
- Bluetooth Enabled:These devices integrate wirelessly with smartphones and other personal electronics, enabling direct audio streaming and remote control. Consumers prioritize seamless connectivity, especially in tech-savvy US demographics.
- Rechargeable:Hearing aids with built-in rechargeable batteries eliminate the need for frequent battery changes, enhancing user convenience. This feature is particularly popular among elderly adults seeking ease of use and reduced maintenance.
- Digital:Digital signal processing forms the core of modern hearing aids, allowing for advanced sound customization and noise reduction.
- Analog:Older analog technology amplifies all sounds equally, offering a simpler, less expensive option for some users.
- Wireless:This technology allows hearing aids to communicate with each other and with external accessories, improving spatial awareness.
Digital processing forms the foundational technology; Bluetooth Enabled connectivity is gaining market share most quickly.
End User:
End-user groups exhibit distinct purchasing behaviors and specific audiological requirements.
- Elderly Adults:This demographic represents the largest user base, driven by age-related hearing loss and the overall aging population in states like Florida and Arizona. Demand here is a sustained source for the market.
- Individuals with Sensorineural Hearing Loss:This specific medical condition, characterized by damage to the inner ear or auditory nerve, necessitates specialized amplification and processing. These users often require professionally fitted devices.
- Seniors:This segment overlaps with elderly adults but specifically highlights the demographic aged 65 and above, a significant portion of the US hearing aid market.
- Veterans:The US Department of Veterans Affairs provides hearing care services, making veterans a distinct and substantial end-user group within the country.
Elderly Adults represent the largest user base; Veterans show consistent demand driven by specific support programs.
Distribution Channel:
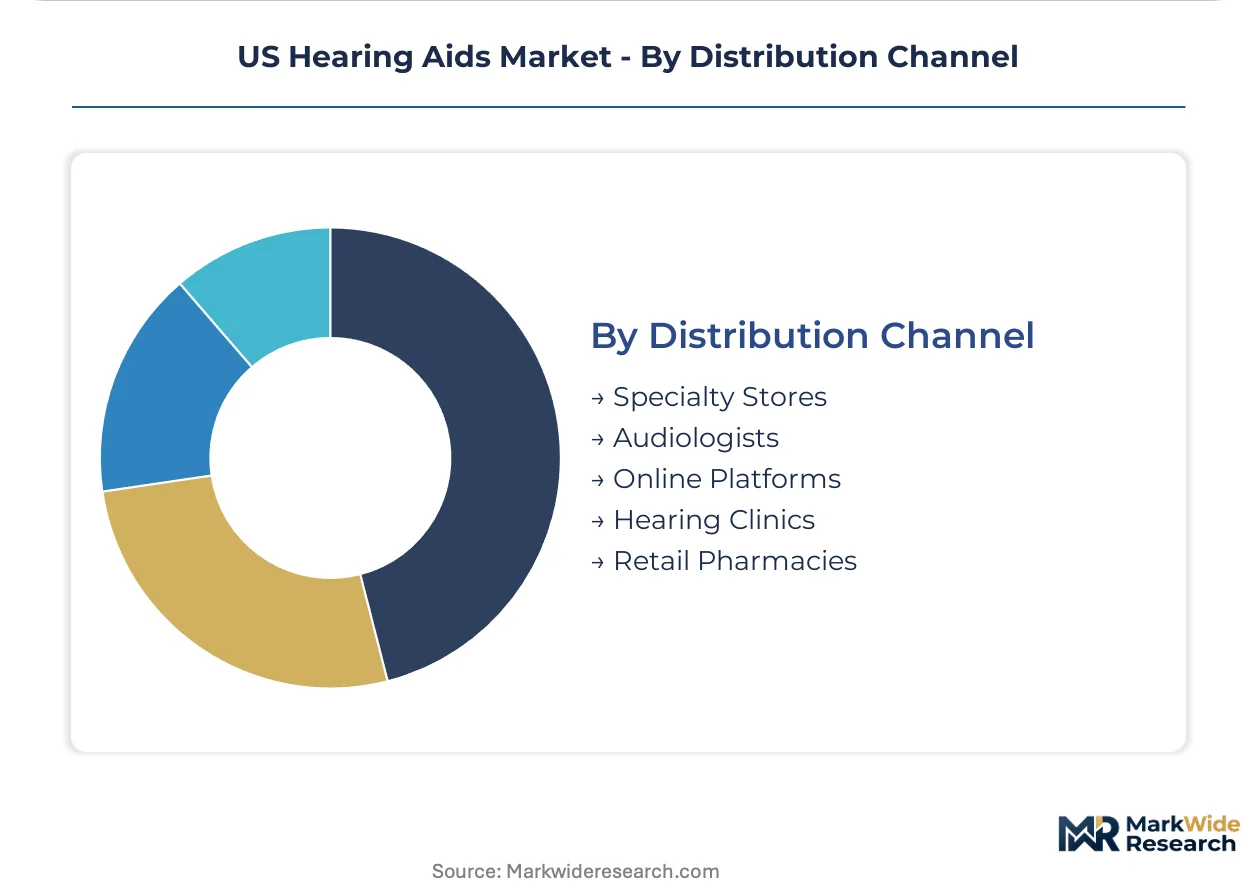
Distribution channels reflect the market's dual structure, balancing traditional clinical models with direct-to-consumer pathways.
- Audiologists:These licensed professionals provide comprehensive hearing evaluations, custom fittings, and ongoing support for medical-grade devices. This channel remains central for complex hearing loss cases across the US.
- Online Platforms:The emergence of over-the-counter (OTC) regulations has significantly boosted direct-to-consumer online sales for self-fitting devices. This channel targets consumers with mild to moderate hearing loss.
- Specialty Stores:These dedicated retail outlets offer a curated selection of hearing aids and related accessories, often providing fitting services.
- Hearing Clinics:These facilities provide a range of audiological services, including testing, fitting, and maintenance of hearing aids.
- Retail Pharmacies:Select pharmacies are beginning to stock OTC hearing aids, offering convenient access for consumers in local communities.
Audiologist networks remain central for professional fittings; Online Platforms are rapidly expanding their reach for OTC devices.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US hearing aids market facilitates a new trade-flow corridor from manufacturers directly to consumers, particularly in states with high elderly populations. This expansion is driven by the FDA's OTC ruling, which broadens accessibility and shifts purchasing behavior. Demand concentrates in key demographic centers, reflecting both an aging populace and evolving technological preferences.
Florida
Florida's substantial elderly population drives significant demand for hearing aids, particularly rechargeable and Bluetooth-enabled models. The FDA's OTC regulation makes devices more accessible for residents managing age-related hearing loss. Major metropolitan areas like Miami and Orlando see increased interest in discreet, self-fitting solutions.
Arizona
Arizona’s growing senior demographic fuels consistent demand for both traditional and over-the-counter hearing aids. HIPAA regulations ensure patient data privacy for connected devices, influencing manufacturer compliance strategies. Retirement communities in Phoenix and Tucson represent concentrated user bases seeking convenient and effective hearing solutions.
California
California, with its tech-savvy population, shows strong demand for advanced, Bluetooth-enabled hearing aids and direct-to-consumer platforms. The FDA's framework supports innovation in self-fitting devices, appealing to younger adults with mild hearing loss. Major tech hubs like Silicon Valley are centers for digital health integration and telehealth support for hearing care.
New York Metro
The New York metropolitan area exhibits demand for discreet In-The-Ear and Completely-In-Canal hearing aid styles, alongside a rising interest in OTC options. State-level initiatives complement federal HIPAA guidelines in protecting consumer health information. Urban clinics and retail pharmacies in New York City are adapting to the dual-channel distribution model.
US Hearing Aids Market Key Industry Players
Channel-controlling players compete with product-specialist players across the US hearing aid market. The market structure exhibits a blend of established medical device manufacturers and agile direct-to-consumer entrants. Strategic archetypes include integrated solution providers, technology innovators, and accessibility-focused disruptors. Companies pursue portfolio diversification and strategic partnerships to navigate the evolving regulatory and distribution landscape.
Within the integrated solution provider tier, Sonova and Starkey Hearing Technologies exemplify traditional manufacturers with broad product portfolios. These companies anchor professional networks, offering advanced medical-grade devices. Eargo Inc. represents the direct-to-consumer archetype, specializing in self-fitting devices for mild to moderate hearing loss. These firms compete by leveraging distinct distribution channels and targeting different consumer segments.
| Leading Market Players |
|---|
| Sonova |
| Demant A/S |
| GN Store Nord A/S |
| WS Audiology |
| Starkey Hearing Technologies |
| Eargo Inc. |
| Cochlear Limited |
| MDHearing |
| Audicus |
Cost & Logistics Intelligence
California's innovation clusters drive rapid product development for hearing aids, influencing premium pricing for advanced features in the US market. This concentration of R&D directly impacts the cost structure and competitive positioning of high-end devices.
Pricing Analysis
Cost-plus contracts, often indexed to component costs for digital signal processors, govern pricing for medical-grade hearing aids. A hybrid pricing model prevails, with professionally fitted devices often following value-based pricing based on audiological outcomes. Price differentiation stems from FDA certification levels and comprehensive after-sales service bundles. Pricing softness reflects increased competition from OTC devices. Elderly adults seeking convenience are less price-sensitive for rechargeable models, while younger adults for OTC products exhibit higher sensitivity.
Supply Chain Analysis
Extended payment terms are common for specialized component suppliers, reflecting the capital-intensive nature of hearing aid manufacturing. Manufacturing largely centers in Europe (e.g., Denmark, Switzerland) and Asia (e.g., China, Malaysia) for core components. Key dependencies include digital signal processors, micro-batteries, and custom-molding polymers. Single-source vulnerability for specialized DSPs poses a structural risk. Distribution runs through a dual model, combining audiologist networks and direct-to-consumer online platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US hearing aids market exhibits a cyclical recovery, propelled by the FDA's OTC ruling expanding access and destigmatizing usage.
For Market Incumbents: Entrench core audiologist relationships through enhanced training and integrated software platforms. Deepen product portfolios with medical-grade devices featuring advanced DSP capabilities and biometric sensors. This counters the channel conflict posed by online-only entrants. Leverage existing professional networks for robust service delivery.
For New Entrants and Emerging Players: The direct-to-consumer segment for mild to moderate hearing loss in tech-savvy metropolitan areas represents a significant white space. Target younger adults with discreet, aesthetically focused devices and robust smartphone integration. Focus on telehealth-supported self-fitting solutions to reduce friction. A digital-first marketing strategy emphasizing lifestyle benefits over medical necessity will capture this user base.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors agile digital health platforms integrating AI for personalized sound processing. The market offers strong long-term viability over a 5-10 year window due to persistent demographic trends and ongoing innovation. Acquisition targets should include innovators in self-fitting algorithms and biometric health monitoring. The signal to watch is the rate of adoption of multi-functional hearing wearables beyond pure amplification.
| Strategic Initiative | Industry Significance |
|---|---|
| Telehealth Platform Development | Expands access for OTC consumers and supports remote audiological care in rural US areas. |
| Biometric Sensor Integration | Repositions devices as health wearables, attracting younger users seeking multi-functional personal electronics. |
| OTC Product Line Expansion | Captures the growing mild-to-moderate hearing loss segment, distinct from traditional medical devices. |
| Advanced DSP Algorithm R&D | Enhances noise reduction and speech clarity, maintaining a competitive edge in high-end medical devices. |
| Strategic Partnerships with Retail Pharmacies | Broadens physical distribution points for OTC products, reaching local US communities effectively. |
Research Approach
A spread of perspectives from audiology clinic owners, hearing aid manufacturers, regulatory affairs specialists, and consumer electronics retailers converged on the working assumptions for this US market analysis. This involved primary interviews complemented by extensive secondary validation. FDA rulings, company annual reports, industry association publications, and US demographic data provided key insights. Bottom-up and top-down triangulation ensured robust data consistency.
The demand-supply balance for hearing aids was modeled across the analysis window, considering both consumer needs and manufacturing capabilities. An integrated analytical framework assessed market dynamics. Segmentation dimensions included product type, technology, end-user demographics, distribution channels, and regional adoption patterns within the US. Compound annual growth rates were derived from historical trends and projected market shifts. Key forecast inputs included US elderly population growth and FDA regulatory impacts.
Practitioners should monitor shifts in US healthcare policy and consumer technology preferences for early signals of market redirection. This forecast reflects current market assumptions. Unforeseen changes in FDA regulations or major technological breakthroughs could alter market trajectories. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
ENT
Nasal Polyps Treatment Market
ENT
North America Hearing Aid Market
ENT
Hearing Implants Market
ENT
Audiology Devices Market
ENT
ENT Disorder Treatment Market
ENT
Surgical ENT Devices Market
ENT
ENT Devices Market
ENT
Europe Speech Therapy Market
ENT
Europe Hearing Aids Market
ENT
Custom Hearing Aids Market
ENT
Over-The-Counter (OTC) Hearing Aids Market
ENT
Head and Neck Squamous Cell Carcinoma Market
ENT
Acute Sinusitis Market
ENT
Electrolarynx Market
ENT
Ear Health Market
ENT
Global Acute Otitis Media Treatment Market