
 Surgical ENT Devices Market | 2026-2036
Surgical ENT Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Surgical ENT Devices Market Intelligence
German precision instrument manufacturing is restructuring supply chains for rigid endoscope production. Karl Storz SE & Co. KG leverages its Tuttlingen production cluster to dominate high-definition visualization systems. Medtronic plc anchors North American distribution through its integrated surgical navigation platforms. Olympus Corporation competes in the flexible endoscope segment with proprietary image-processing architectures.
Surgical ENT devices encompass instruments, endoscopes, implants, and navigation systems designed for operative intervention in the ear, nose, throat, and adjacent skull-base structures, typically manufactured from surgical-grade stainless steel, titanium alloys, or polymer composites with working channel diameters ranging from 1.9 mm to 4.0 mm depending on anatomical access requirements. These devices enable minimally invasive tissue resection, reconstruction, and implantation while preserving critical neurovascular structures. Endoscopes command premium pricing due to optical stack complexity and sterilization durability requirements. Navigation systems represent the fastest-expanding product category as image-guided surgery displaces conventional landmark-based approaches in sinus and skull-base procedures. Robotics remains nascent in ENT relative to orthopedic or abdominal surgery, constraining near-term margin pool migration.
FDA 510(k) pathways and EMA MDR compliance timelines shape product launch sequencing and clinical trial investment for manufacturers targeting dual-market access. ISO 13485 quality management certification functions as a baseline procurement filter for hospital systems conducting vendor qualification. Stakeholders must monitor reimbursement coding decisions by CMS and analogous national health technology assessment bodies, as procedure classification directly determines addressable patient volumes and capital equipment purchasing cycles.
Market Dynamics
Navigation system adoption is compressing procedural variance in sinus and skull-base surgery, forcing capital equipment purchasing cycles toward integrated platforms that bundle visualization, tracking, and instrument control.
Growth Catalysts
- EMA MDR compliance compression:Streamlined technical documentation requirements for Class IIa ENT devices are accelerating CE mark acquisition timelines for navigation platform entrants targeting European hospital systems.
- Ambulatory surgical center expansion:United States outpatient facilities are scaling procedure volumes for balloon sinuplasty and laryngeal interventions, driving disposable instrument consumption.
- Optical stack miniaturization:Advances in CMOS sensor fabrication are enabling 4K resolution within 2.7 mm working channel diameters for pediatric otology applications.
Market Restraints
- Titanium alloy supply concentration:German and Japanese specialty metallurgy suppliers control premium-grade bar stock for micro-instrument forging, creating input cost volatility during aerospace demand spikes.
- Navigation system technical limitation:Electromagnetic tracking suffers line-of-sight interference from ferromagnetic operating room equipment, constraining adoption in legacy surgical suites without structural retrofit.
- FDA 510(k) predicate device saturation:Substantial equivalence pathways for incremental rigid endoscope iterations face heightened scrutiny, extending review timelines for optical stack modifications.
Strategic Opportunities
- Underpenetrated Indian metropolitan markets:Tier-1 cities including Mumbai and Delhi are constructing dedicated ENT surgical towers with government-backed infrastructure financing.
- AI-assisted image guidance convergence:Machine learning segmentation of intraoperative endoscopic video streams is enabling real-time anatomical landmark recognition for trainee surgeons.
- Reimbursement coding tailwind:CMS valuation of image-guided sinus surgery procedures is expanding addressable volumes for navigation system capital justification in United States hospital systems.
Industry Challenges
- Skull-base surgical skill scarcity:Fellowship-trained rhinologists with navigation proficiency remain concentrated in academic medical centers, limiting platform utilization in community hospitals.
- ISO 13485 certification timeline compression:Notified body backlogs for quality management system audits are delaying product launch sequencing for mid-cap manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surgical ENT Devices Market |
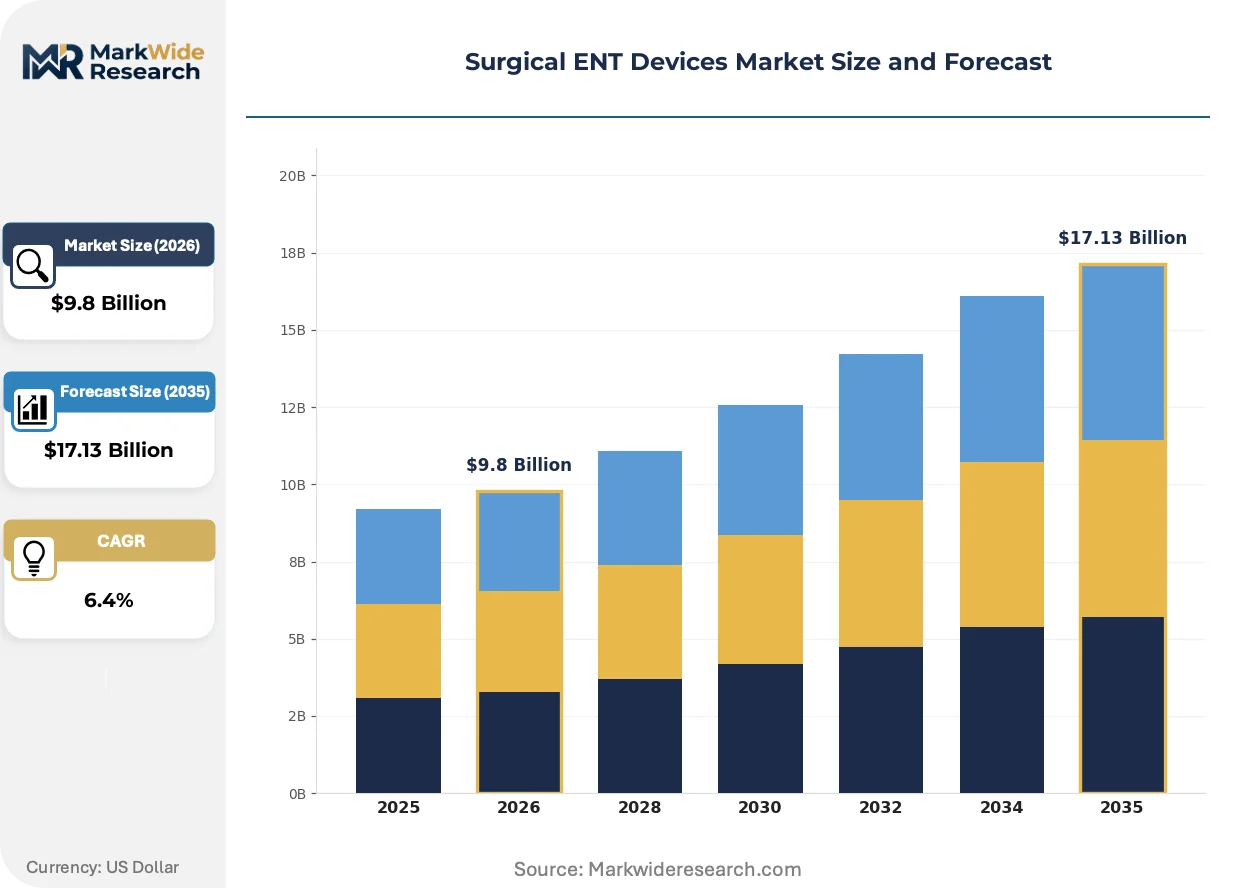
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $17.13 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Endoscopes, Surgical Instruments, Diagnostic Devices, Implantable Devices Application: Sinus Surgery, Ear Surgery, Throat Surgery, Cochlear Implants End User: Hospitals, ENT Clinics, Surgical Centers, Research Institutes Technology: Laser Technology, Navigation Systems, Robotics, Imaging Systems |
| Companies Covered | Karl Storz SE & Co. KG, Richard Wolf GmbH, Medtronic plc, Integra LifeSciences, Johnson & Johnson, Olympus Corporation, Smith & Nephew plc, ZEISS Group, Stryker Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surgical ENT Devices Market Strategic Shifts & Innovations
Device architecture is fragmenting from monolithic platforms toward interoperable subsystems, enabling hospital systems to upgrade visualization, tracking, or instrument components without full capital replacement.
Disposable sheaths for rigid endoscopes are modularizing sterilization workflows in high-throughput ambulatory settings. United States surgical centers are adopting single-use optical protection barriers to eliminate reprocessing bottlenecks. This shift is compressing capital allocation toward consumable revenue models and away from durable equipment financing.
EU MDR technical documentation requirements are restructuring clinical evidence portfolios for ENT navigation systems. Manufacturers must now submit post-market surveillance data with annual periodic safety update reports. Sinus surgery platforms face the steepest compliance burden due to their Class IIa risk classification and software-driven functionality.
Hospital procurement committees are unbundling service contracts from capital equipment purchases. United States health systems now negotiate preventive maintenance, software updates, and training separately from device acquisition. This disintermediation is visible most acutely in integrated platform sales, where original equipment manufacturers previously captured lifetime value through bundled arrangements.
Surgical ENT Devices Market Segmentation
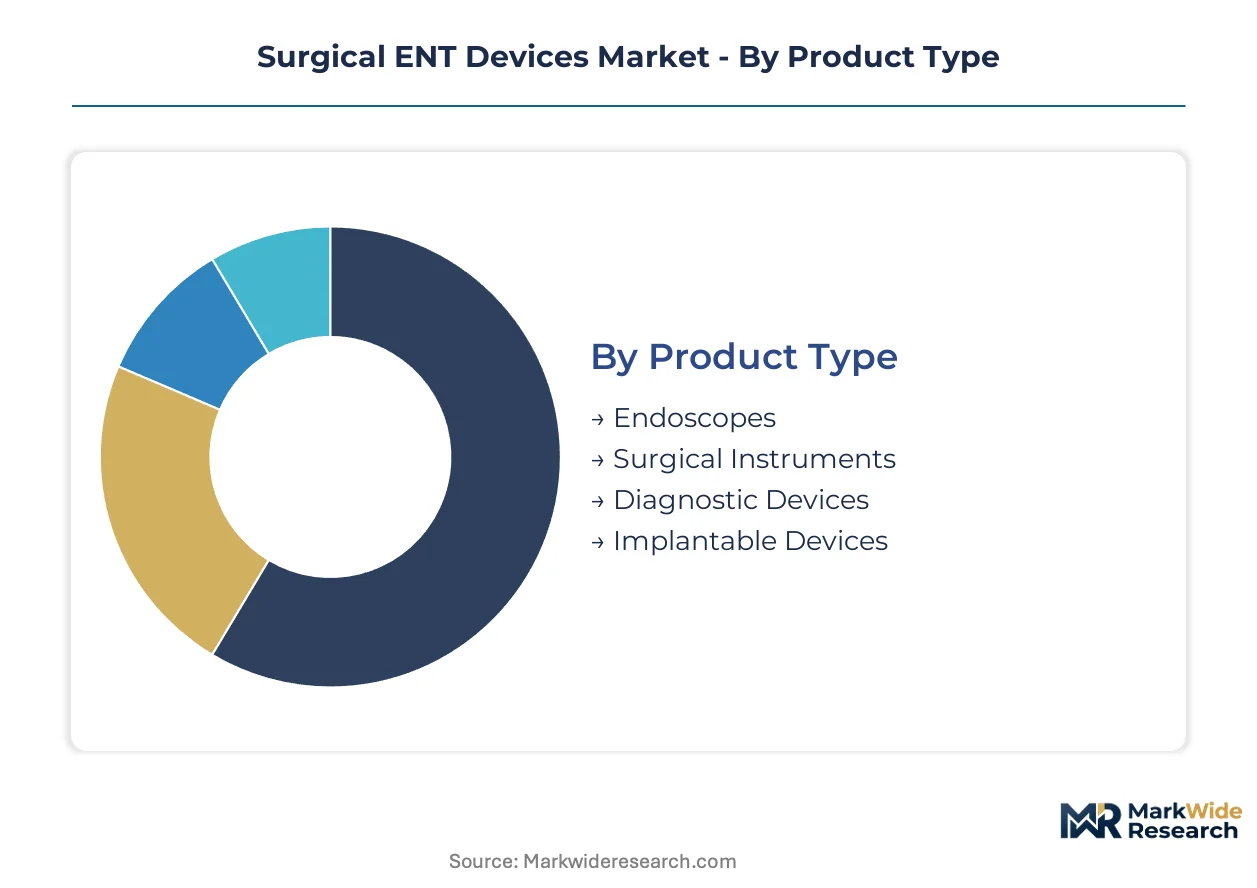
Surgical ENT devices fragment across four intersecting dimensions that determine procurement workflows and capital allocation priorities. Product architecture and application specificity drive premium pricing tiers, while end-user scale and technology integration depth shape vendor selection criteria.
Product Type:
Customization intensity varies sharply across this category, with visualization platforms demanding bespoke optical configurations while instruments standardize toward interchangeable specifications.
- Endoscopes:Rigid and flexible variants incorporate CMOS sensors, fiber-optic bundles, or rod-lens systems with working channels calibrated to anatomical access requirements. German and Japanese production clusters dominate high-definition visualization supply. FDA 510(k) predicate saturation is extending review timelines for optical stack modifications.
- Surgical Instruments:Micro-forceps, suction devices, and cutting tools are forged from surgical-grade stainless steel or titanium alloys with tip geometries optimized for specific tissue resection. United States hospital consolidation is driving bulk procurement of instrument sets bundled with capital platforms. Most installed capacity flows through Endoscopes. Expansion is steepest in Implantable Devices.
- Diagnostic Devices:Audiometry equipment and tympanometry systems enable preoperative assessment and postoperative monitoring protocols.
- Implantable Devices:Cochlear implants, bone-anchored hearing systems, and sinus stents incorporate biocompatible polymers and electrode arrays for long-term physiological integration.
Most installed capacity flows through Endoscopes. Expansion is steepest in Implantable Devices.
Application:
Procedure complexity and reimbursement valuation create divergent margin profiles across anatomical targets.
- Sinus Surgery:Functional endoscopic sinus surgery and balloon sinuplasty address chronic rhinosinusitis through minimally invasive tissue preservation. United States ambulatory surgical centers are scaling outpatient procedure volumes for balloon sinuplasty interventions.
- Ear Surgery:Stapedectomy, tympanoplasty, and mastoidectomy require microscopic visualization and micro-instrument precision for ossicular chain reconstruction. Academic medical centers concentrate fellowship-trained otologists capable of complex revision procedures.
- Throat Surgery:Laryngeal microsurgery and tonsillectomy procedures utilize rigid laryngoscopes with suspension fixation systems.
- Cochlear Implants:Multichannel electrode array insertion demands specialized surgical navigation to preserve residual hearing and facial nerve integrity.
Revenue concentration aligns with Sinus Surgery. Volume acceleration is most pronounced in Cochlear Implants.
End User:
Purchasing authority and capital budget scale determine platform configuration complexity across facility types.
- Hospitals:Integrated surgical suites with navigation capability and 4K visualization towers anchor high-academic referral networks. United States health systems are unbundling service contracts from capital equipment purchases.
- ENT Clinics:Office-based settings prioritize flexible endoscopy and diagnostic audiometry for initial patient evaluation workflows.
- Surgical Centers:Ambulatory facilities in Germany and the United States are expanding procedure volumes for disposable instrument consumption models.
- Research Institutes:Preclinical testing and training simulation centers drive demand for cadaveric specimen-compatible instrumentation.
Capital deployment concentrates in Hospitals. Patient volume growth is climbing the fastest in Surgical Centers.
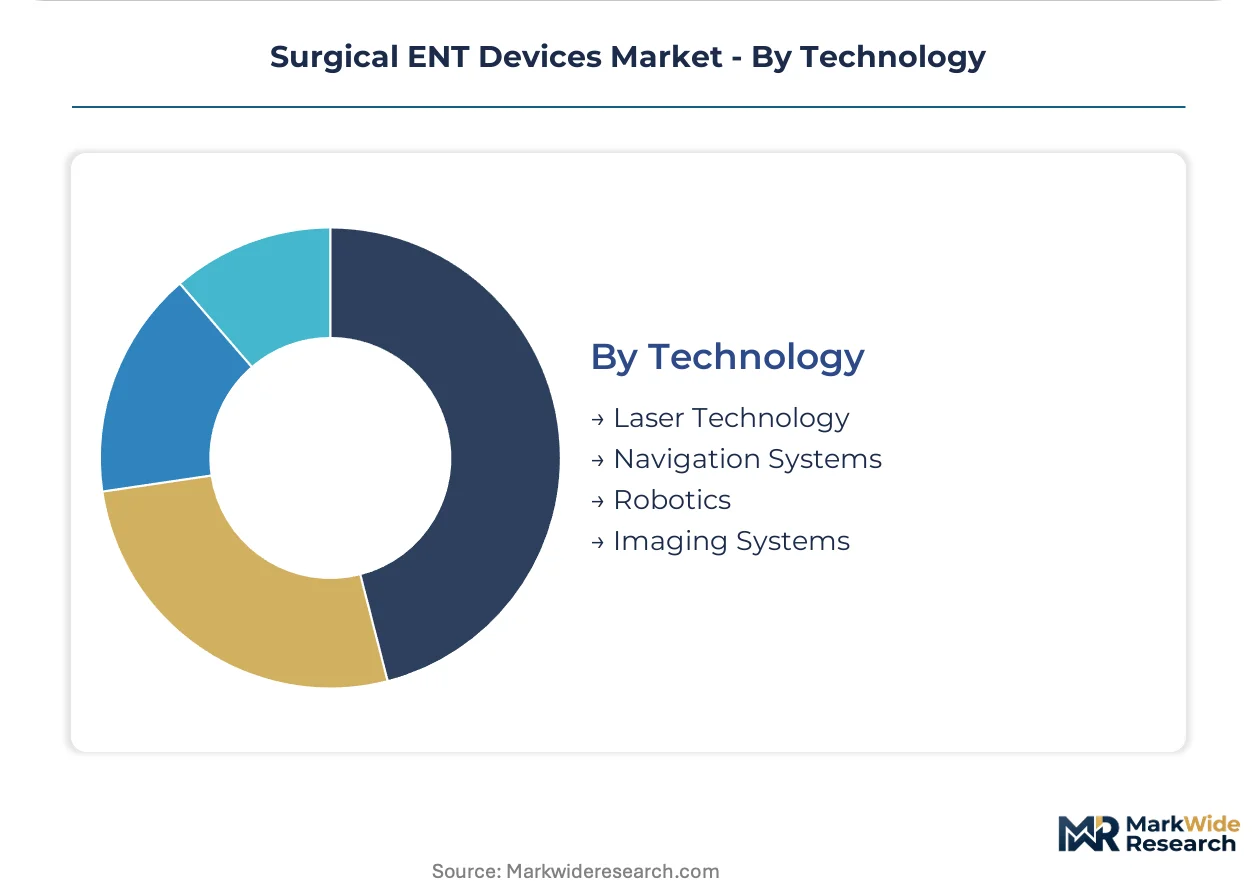
Technology:
Integration maturity separates established modalities from emerging platforms requiring infrastructure retrofit.
- Laser Technology:CO2 and KTP laser systems enable precise soft-tissue ablation with minimal thermal spread for laryngeal and sinonasal applications.
- Navigation Systems:Electromagnetic and optical tracking platforms register preoperative imaging to intraoperative anatomy for skull-base and sinus procedures. EMA MDR compliance compression is accelerating CE mark acquisition timelines for European entrants.
- Robotics:Telemanipulator platforms remain nascent in ENT relative to orthopedic or abdominal surgery, constraining near-term adoption curves.
- Imaging Systems:Intraoperative CT and cone-beam CT enable real-time anatomical verification during implant placement.
Platform penetration is deepest in Navigation Systems. Development investment is expanding most quickly in Robotics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EMA MDR compliance compression is diverting navigation platform investment toward European manufacturing clusters, while FDA 510(k) pathway congestion pushes incremental optical innovations toward Asian assembly hubs seeking faster regulatory turnaround.
United States
Hospital consolidation is driving bulk procurement of integrated ENT surgical platforms across health systems. CMS reimbursement coding for image-guided sinus procedures is expanding addressable volumes for navigation system capital justification. The Greater Boston corridor anchors academic medical centers where fellowship-trained rhinologists concentrate skull-base surgical expertise.
Germany
Ambulatory surgical centers are scaling procedure volumes for balloon sinuplasty and laryngeal interventions. EMA MDR streamlined technical documentation for Class IIa devices is accelerating CE mark acquisition timelines for Tuttlingen-based visualization system manufacturers. The Baden-Württemberg production cluster dominates high-definition rigid endoscope supply through precision instrument manufacturing restructuring.
India
Tier-1 metropolitan markets including Mumbai and Delhi are constructing dedicated ENT surgical towers with government-backed infrastructure financing. CDSCO regulatory harmonization with IMDRF guidelines is compressing import clearance timelines for navigation platform entrants. The Maharashtra-Gujarat industrial corridor is attracting contract manufacturing for disposable instrument consumption models.
Japan
PMDA priority review pathways for minimally invasive surgical devices are shortening time-to-market for optical stack miniaturization technologies. METI funding for medical device innovation clusters is concentrating CMOS sensor fabrication capabilities in the Kansai region. Osaka-based precision optics suppliers are scaling 4K resolution capabilities within pediatric otology working channel specifications.
United Kingdom
NHS England procurement frameworks are unbundling service contracts from capital equipment purchases for integrated surgical platforms. MHRA post-Brexit regulatory autonomy is enabling faster conformity assessment timelines for navigation system software updates. The Cambridge-Oxford-London triangle anchors research institutes driving cadaveric specimen-compatible instrumentation development.
Surgical ENT Devices Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue navigation software and disposable sheath specialization. The vendor base stratifies across three tiers: integrated platform manufacturers capturing hospital system contracts, precision instrument specialists dominating rigid endoscope supply, and regional assemblers serving price-sensitive ambulatory markets. Dominant competitive moves include M&A for optical stack capabilities and strategic partnerships for electromagnetic tracking licensing.
Among German precision instrument fabricators, Karl Storz SE & Co. KG and Richard Wolf GmbH exemplify the visualization-dominant archetype through their Tuttlingen production heritage. Medtronic plc occupies a position representing the integrated surgical navigation platform category. These three entities anchor the competitive structure without exhausting its diversity.
| Leading Market Players |
|---|
| Karl Storz SE & Co. KG |
| Richard Wolf GmbH |
| Medtronic plc |
| Integra LifeSciences |
| Johnson & Johnson |
| Olympus Corporation |
| Smith & Nephew plc |
| ZEISS Group |
| Stryker Corporation |
| Others |
Cost & Logistics Intelligence
Titanium alloy bar stock indices from German and Japanese specialty metallurgy suppliers cascade directly into surgical instrument pricing tiers, with aerospace demand spikes transmitting volatility through ENT micro-forging supply chains into hospital procurement cycles.
Pricing Analysis
Distributor margins for rigid endoscopes compress pricing stratification across premium, standard, and economy tiers, with OEM direct-to-hospital contracts bypassing traditional channels for integrated navigation platforms. FDA 510(k) predicate saturation extends review timelines for optical stack modifications, elevating certification-grade premiums for entrants with cleared predicates. Cost compression in disposable instrument categories intensifies as ambulatory surgical centers scale volume procurement. Community hospitals exhibit highest price sensitivity due to capital budget constraints, while academic medical centers prioritize performance tier over unit economics.
Supply Chain Analysis
CMOS sensor fabrication rests on Japanese precision optics suppliers and Taiwanese semiconductor foundries, with rod-lens systems drawing from German glass-ceramic producers in the Tuttlingen cluster. Titanium alloy bar stock feeds from Japanese and German specialty metallurgy suppliers into micro-instrument forging operations. Single-source vulnerability concentrates in pediatric otology working channel specifications where 4K resolution miniaturization depends on Kansai-region sensor packaging capabilities. Distribution runs through regional medical device distributors with GPO contract access in United States health systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Surgical ENT device margins expand through optical stack miniaturization cost curves and navigation system software premium tiers displacing conventional visualization hardware.
For Market Incumbents: Acquire electromagnetic tracking algorithm portfolios to defend navigation platform positioning against optical tracking entrants. Consolidate rigid endoscope service contract bundling to counter hospital procurement committee unbundling trends. Capacity addition in Maharashtra-Gujarat industrial corridor captures disposable instrument consumption model growth. For New Entrants and Emerging Players: Enter via AI-assisted image guidance software modules targeting trainee surgeon segmentation tools in academic medical centers. Underpenetrated Indian metropolitan surgical towers offer white-space infrastructure with government-backed financing. Reimbursement coding tailwinds for image-guided sinus procedures provide go-to-market leverage with United States hospital systems. For Investors and Strategic Acquirers: Asymmetric upside sits with navigation software specialists possessing CE-marked platforms and FDA-cleared predicates. Long-term viability frames around MDR compliance compression enabling European market access velocity. Acquisition target archetype: mid-cap manufacturers with ISO 13485 certification and notified body relationships navigating audit backlogs. Watch EMA MDR Class IIa technical documentation streamlining as inflection indicator for platform entrant timing.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EMA MDR streamlined documentation accelerates navigation platform European hospital system access. |
| Hospital System Partnership | United States health system consolidation creates bulk procurement leverage for integrated platform vendors. |
| Software Companion Development | AI-assisted anatomical landmark recognition modules differentiate visualization platforms for trainee surgeons. |
| Reimbursement Strategy | CMS valuation expansion for image-guided sinus surgery procedures drives navigation system capital justification. |
| FDA Submission | 510(k) predicate device saturation demands novel optical stack configurations to avoid review timeline extension. |
Research Approach
Coverage spans United States, Germany, India, Japan, and United Kingdom markets, with primary inputs from each region's hospital procurement committees, biomedical engineers, GPO contracts managers, and ENT surgeons. Secondary validation drew from FDA 510(k) filings, EMA MDR submission databases, CMS Medicare reimbursement schedules, and hospital procurement contract repositories. Bottom-up triangulation across product type, application, end user, and technology dimensions converged with top-down macroeconomic anchoring.
Granularity-level modeling treated endoscope, instrument, diagnostic device, and implantable device categories separately, with navigation system and robotics technology segments receiving discrete growth trajectory assumptions. CAGRs derived from procedure volume elasticity to reimbursement coding changes, capital equipment replacement cycles, and ambulatory surgical center expansion rates. Optical stack miniaturization cost curves and titanium alloy input price volatility informed margin compression assumptions across the projection horizon.
Inputs from FDA 510(k) clearance databases and EMA MDR notified body audit schedules were available through the study window; gaps in private hospital system contract terms introduce uncertainty bands around pricing tier assumptions. Forecasts reflect documented elasticity assumptions between reimbursement valuation and capital equipment procurement cycles. Regulatory timeline compression, fellowship-trained surgeon supply constraints, and aerospace demand spillover into titanium alloy markets warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
ENT
Nasal Sampling Lines Market
ENT
Denmark Hearing Aids Market
ENT
Global Acute Otitis Media Treatment Market
ENT
Europe Hearing Aids Market
ENT
ENT Devices Market
ENT
Head and Neck Squamous Cell Carcinoma Market
ENT
Global Pediatric Hearing Aids Market
ENT
Hearing Implants Market
ENT
Europe Speech Therapy Market
ENT
Audiology Devices Market
ENT
ENT Examination Chair Market
ENT
Ear Health Market
ENT
Global Audiological Devices Market
ENT
Laryngeal Papillomatosis Treatment Market
ENT
Custom Hearing Aids Market
ENT
Global Sinusitis Treatment Market