
 ENT Devices Market | 2026-2036
ENT Devices Market Size, Share, and Industry Trends Forecast 2026-2036
ENT Devices Market Analysis
Asian contract manufacturers of transducer assemblies is rebalancing toward higher-margin digital signal processing modules. Medtronic leverages its integrated neuro-otology portfolio to sustain premium positioning across cochlear implant categories. Stryker anchors its ENT surgical franchise through rigid endoscope supply chains that dominate North American hospital purchasing. Olympus Corporation differentiates via optical imaging architectures that compete directly with chip-on-tip video systems from Karl Storz GmbH & Co. KG.
ENT devices comprise diagnostic, surgical, and prosthetic instruments engineered for the ear, nose, and throat anatomies, with hearing aids typically integrating digital signal processors, microphones, and receivers within housings weighing under three grams. These instruments restore sensory function, enable minimally invasive tissue resection, or maintain airway patency across clinical and home environments. Hearing aids command the largest revenue pool among product types due to recurring replacement cycles and rechargeable battery transitions, while electrode systems within the technology dimension capture disproportionate margins from cochlear implant upgrades. Endoscopes face pricing pressure from single-use alternatives, though ENT specialists continue driving demand for reusable flexible rhinolaryngoscopes with 720p resolution thresholds.
FDA 510(k) clearance pathways govern market access for powered surgical instruments and implantable hearing devices in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence requirements for Class III ENT implants across European member states. Japan's PMDA maintains distinct pharmaceutical and medical device agency review timelines that shape launch sequencing for bone conduction systems. Stakeholders must monitor reimbursement code revisions for osseointegrated implants and home-based diagnostic sleep apnea devices as payors recalibrate coverage criteria.
Market Dynamics
Hearing aid manufacturers face margin compression from rechargeable battery transitions while cochlear implant suppliers capture value through electrode array upgrades that extend replacement cycles.
Growth Catalysts
- EU Medical Device Regulation:Class III implant clinical evidence requirements are consolidating supplier bases and rewarding firms with pre-existing trial infrastructure across Germany and France.
- Geriatric ambulatory migration:Hearing aid dispensing is relocating from hospital audiology departments to retail hearing centers, expanding touchpoints for device fitting.
- Digital signal processing:AI-powered noise cancellation algorithms are differentiating premium hearing aid tiers and justifying reimbursement premiums in Japanese long-term care insurance.
Market Restraints
- Lithium-ion supply concentration:Rechargeable hearing aid battery cell production clusters in East Asian contract manufacturers, exposing OEMs to input cost volatility and logistics bottlenecks.
- FDA 510(k) pathway friction:Premarket notification volume for powered surgical instruments is extending review timelines, delaying US commercialization for novel microdebrider designs.
- Single-use endoscope substitution:Disposable rhinolaryngoscopes are capturing outpatient clinic volume, eroding reusable instrument aftermarket service revenue.
Strategic Opportunities
- Home-based diagnostic sleep apnea:Wearable acoustic monitoring devices for obstructive sleep apnea screening are opening direct-to-consumer channels outside traditional sleep lab referrals.
- India PLI scheme:Production-linked incentives for medical device manufacturing are attracting hearing aid assembly investments to offset tariff exposure in South Asian markets.
- Bone conduction-implant convergence:Osseointegrated sound processors are merging with active middle ear implants, creating hybrid categories for mixed hearing loss.
Industry Challenges
- Cochlear implant mapping specialization:Audiologist training programs for electrode programming are not scaling with implantable device volumes, creating post-surgical fitting backlogs.
- Interoperability with legacy systems:New wireless hearing aid protocols are failing to pair with existing assistive listening infrastructure in US public venues, forcing dual-device carriage.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ENT Devices Market |
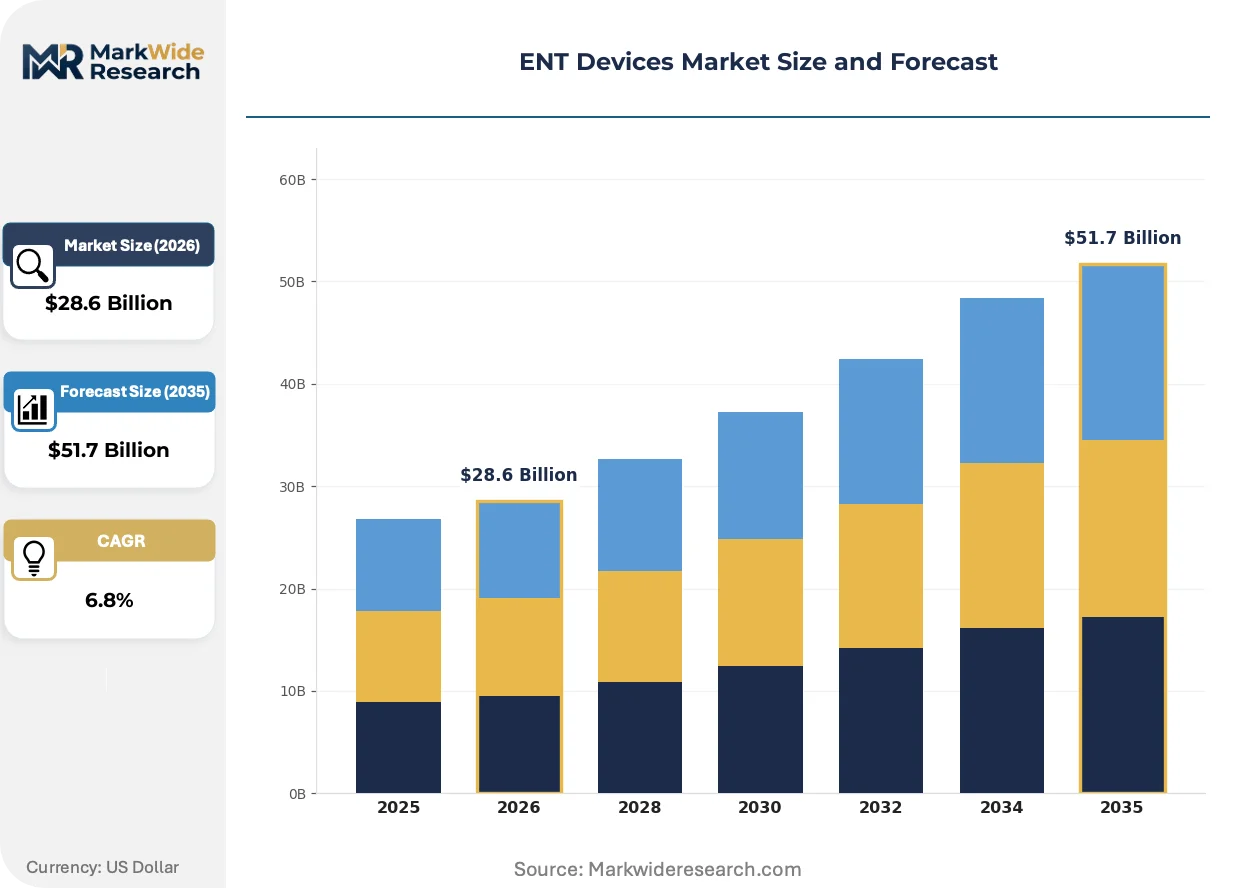
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hearing Aids, Nasal Devices, Otological Devices, Endoscopes Technology: Digital, Analog, Bone Conduction, Electrode Systems End User: Hospitals, Audiology Clinics, ENT Specialists, Home Care Application: Hearing Loss, Sinus Treatment, Sleep Apnea, Surgery |
| Companies Covered | Medtronic, Stryker, Smith & Nephew, Olympus Corporation, Cochlear Ltd., Johnson & Johnson Services, Inc., Sonova Holding AG, Karl Storz GmbH & Co. KG, Boston Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ENT Devices Market Emerging Trajectories
Signal processing architectures and regulatory evidence frameworks are redrawing competitive boundaries between hearing aid and implantable device categories.
Machine learning-based acoustic scene classification is automating hearing aid program switching without user manual input. Geriatric users in Japanese long-term care facilities are adopting these hands-free systems faster than middle-aged first-time wearers. The technology is automating the traditional audiologist fitting workflow and compressing the initial adjustment period from weeks to days.
Japan's PMDA has introduced parallel review tracks for bone conduction systems that synchronize pharmaceutical and medical device approval timelines. This regulatory convergence is accelerating launch sequencing for combined drug-device therapies targeting Ménière's disease. Cochlear implant manufacturers with Tokyo-based clinical trial operations are capturing first-mover positioning in hybrid therapeutics.
Hospital purchasing cooperatives are consolidating ENT surgical instrument procurement across multi-hospital systems in the United States. Independent ambulatory surgery centers are losing direct vendor relationships as these buying groups centralize contract negotiation for rigid endoscope suites. German university hospitals remain exceptions, maintaining separate procurement for research-compatible optical systems.
ENT Devices Market Segmentation
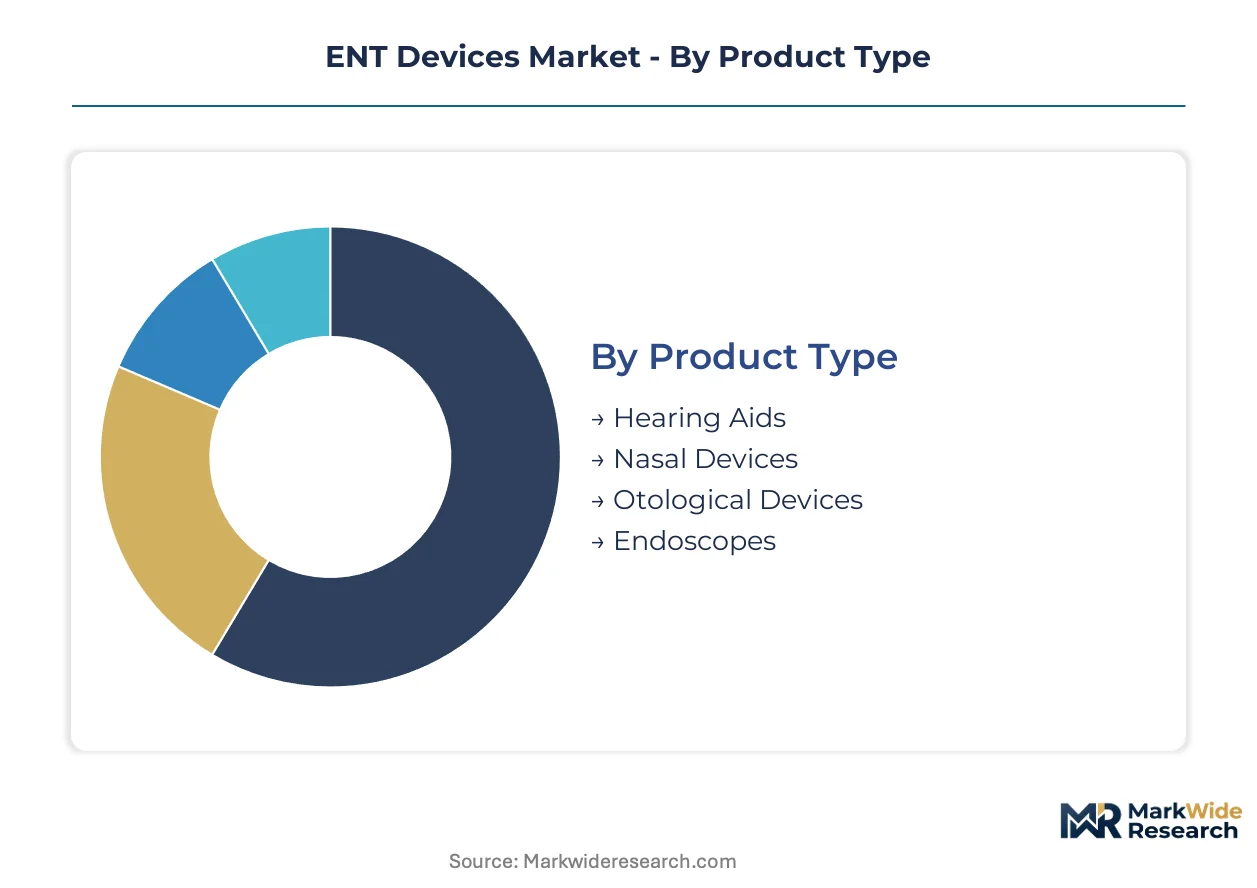
ENT device segmentation reveals divergent margin structures across prosthetic, diagnostic, and surgical categories. Procurement patterns vary sharply between institutional buyers negotiating bulk endoscope contracts and retail channels dispensing hearing aids to individual patients.
Product Type:
Buyers in this category separate into high-frequency replacement purchasers seeking rechargeable convenience versus capital equipment acquirers prioritizing optical precision and service longevity.
- Hearing Aids:These microelectronic prosthetics integrate digital signal processors, microphones, and receivers within sub-three-gram housings. Demand concentrates among geriatric users in ambulatory retail settings across the United States, Germany, and Japan as reimbursement frameworks expand for implantable hearing solutions.
- Nasal Devices:This category spans stents, dilators, and drug-eluting implants engineered for airway patency maintenance. ENT specialists in hospital outpatient departments drive procurement, with preference shifting toward bioresorbable materials that reduce revision surgery rates.
- Otological Devices:Bone-anchored sound processors and tympanostomy tubes comprise this surgical segment. The FDA 510(k) pathway governs US market access, while Japan's PMDA maintains distinct review timelines shaping regional launch sequencing.
- Endoscopes:Rigid and flexible optical systems enable minimally invasive visualization of sinus and laryngeal anatomy. Reusable rhinolaryngoscopes with 720p resolution thresholds face pricing pressure from single-use alternatives capturing outpatient clinic volume.
Hearing Aids leads volumes today; Endoscopes is gaining share fastest through single-use substitution in ambulatory settings.
Technology:
Technology selection in this market tracks directly to patient severity and reimbursement tier, with premium digital systems commanding distinct clinical workflows from basic amplification.
- Digital:AI-powered noise cancellation algorithms automate acoustic scene classification without manual user input. Japanese long-term care insurance justifies reimbursement premiums for these hands-free systems, compressing fitting periods from weeks to days.
- Analog:Conventional amplification circuits persist in economy-tier dispensing for price-sensitive first-time wearers. Emerging market audiology clinics in India leverage these devices to offset tariff exposure under the PLI scheme for medical device manufacturing.
- Bone Conduction:Osseointegrated sound processors bypass damaged middle ear structures through direct skull vibration. Japan's PMDA parallel review tracks for combined drug-device therapies are accelerating launch sequencing for hybrid systems targeting Ménière's disease.
- Electrode Systems:Cochlear implant electrode arrays capture disproportionate margins through upgrade cycles extending replacement timelines. Audiologist training programs for post-surgical mapping are not scaling with implant volumes, creating fitting backlogs.
Digital technology dominates current installed base; Electrode Systems is climbing the fastest as cochlear implant surgical volumes expand.
End User:
End user segmentation reflects institutional purchasing power concentration versus fragmented retail dispensing, with distinct regulatory and reimbursement interfaces at each node.
- Hospitals:Integrated delivery networks centralize procurement for surgical instrument suites and implantable devices. US hospital purchasing cooperatives are consolidating multi-hospital system contracts, marginalizing independent ambulatory surgery center vendor relationships.
- Audiology Clinics:Retail hearing centers now outpace hospital audiology departments in device fitting volume. These clinics face margin compression from rechargeable battery transitions while capturing geriatric ambulatory migration.
- ENT Specialists:Otolaryngology practices drive demand for reusable flexible rhinolaryngoscopes and powered surgical instruments. EU Medical Device Regulation Class III implant clinical evidence requirements are consolidating supplier bases accessible to these practitioners.
- Home Care:Direct-to-consumer channels are emerging for wearable acoustic monitoring devices screening obstructive sleep apnea outside traditional sleep lab referrals.
Hospitals anchor procurement value today; Home Care is expanding most quickly through diagnostic device consumerization.
Application:
Application demand correlates to population aging intensity and chronic disease prevalence, with surgical intervention rates varying by healthcare system reimbursement design.
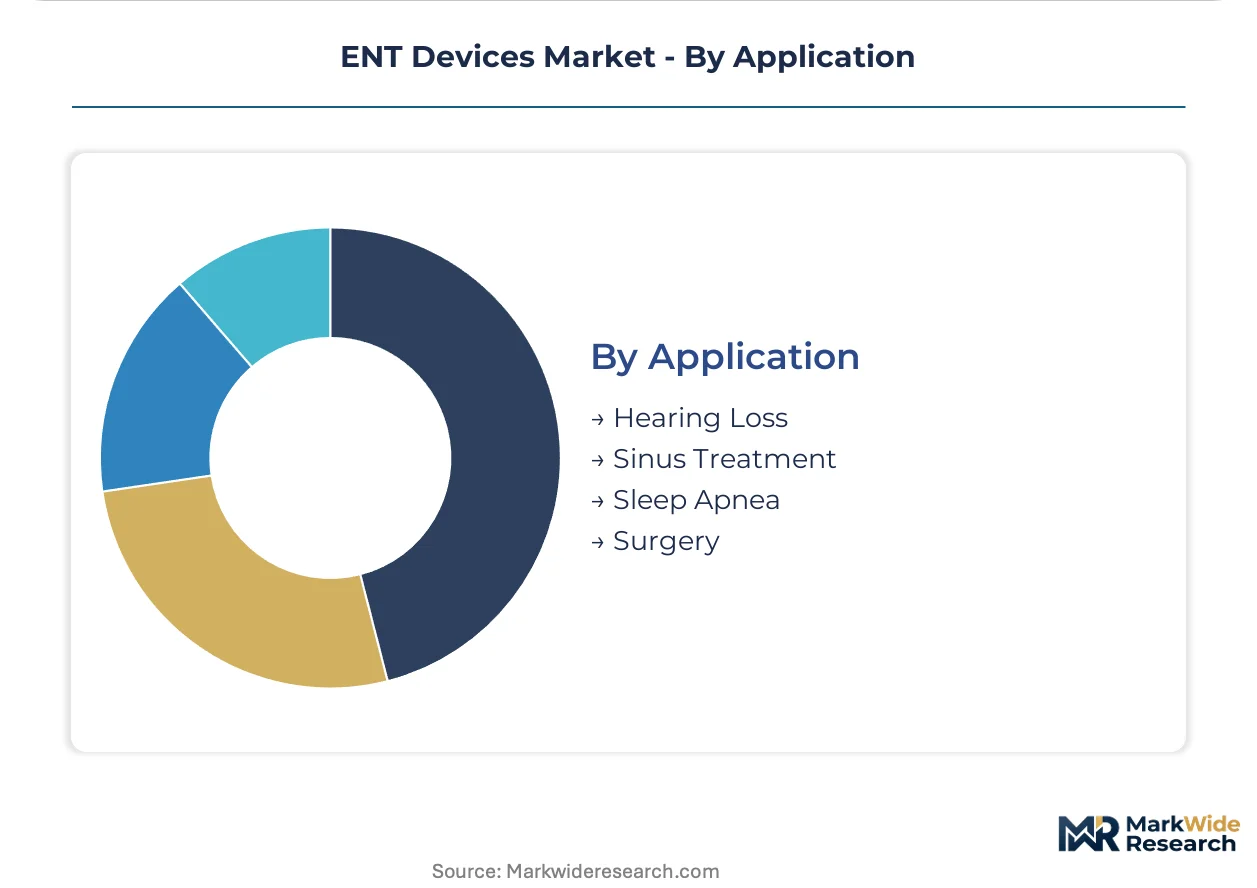
- Hearing Loss:Sensorineural and conductive impairment treatment spans hearing aids through cochlear implants. FDA premarket notification requirements for Class II devices continue tightening quality benchmarks for manufacturers serving this indication.
- Sinus Treatment:Chronic rhinosinusitis interventions include balloon dilation and functional endoscopic sinus surgery. German university hospitals maintain separate procurement for research-compatible optical systems in this application.
- Sleep Apnea:Obstructive sleep apnea management is shifting from polysomnography labs to home-based diagnostic monitoring. Payor recalibration of reimbursement codes for these devices is reshaping competitive entry points.
- Surgery:Tonsillectomy, adenoidectomy, and laryngeal microsurgery procedures drive demand for powered microdebriders and rigid endoscopes. FDA 510(k) review timeline extensions are delaying US commercialization for novel instrument designs.
Hearing Loss commands the largest patient population today; Sleep Apnea shows the steepest expansion trajectory through diagnostic decentralization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing ENT device manufacturing toward jurisdictions with calibrated compliance costs, while demand concentrates in aging economies with expanded reimbursement for implantable hearing solutions.
United States
Geriatric ambulatory migration drives hearing aid dispensing toward retail channels outside hospital audiology departments. FDA 510(k) premarket notification pathways for powered surgical instruments are extending review timelines and tightening quality benchmarks. Minneapolis and Boston anchor cochlear implant clinical trial infrastructure that shapes global launch sequencing.
Germany
EU Medical Device Regulation Class III implant requirements are consolidating supplier bases and rewarding firms with pre-existing trial infrastructure across university hospital networks. EMA-aligned clinical evidence frameworks govern market access for bone-anchored sound processors. Stuttgart and Tübingen clusters concentrate rigid endoscope optical engineering expertise serving hospital purchasing cooperatives.
Japan
PMDA parallel review tracks for combined drug-device therapies are accelerating launch sequencing for bone conduction systems targeting Ménière's disease. Long-term care insurance justifies reimbursement premiums for AI-powered hearing aid noise cancellation. Tokyo-based clinical trial operations capture first-mover positioning in hybrid therapeutics.
India
Production-linked incentive schemes for medical device manufacturing are attracting hearing aid assembly investments to offset tariff exposure in South Asian markets. CDSCO regulatory pathways shape import substitution strategies for economy-tier analog amplification devices. Gujarat and Karnataka clusters host contract manufacturing for transducer assemblies rebalancing toward digital signal processing modules.
China
NMPA review timelines for Class II implantable hearing devices are extending domestic commercialization schedules for foreign OEMs. Dual carbon goals are pressuring lithium-ion battery supply chains for rechargeable hearing aid production. Shenzhen and Suzhou industrial zones concentrate acoustic component fabrication serving regional hearing instrument demand.
ENT Devices Market Vendor Landscape
United States producers anchor the premium implantable tier; German and Japanese specialists hold differentiated positions in optical systems and signal processing. The vendor base separates into three strategic archetypes: integrated neuro-otology portfolios, rigid endoscope supply chain dominators, and digital hearing instrument specialists. Dominant competitive moves include backward integration into electrode array manufacturing and strategic partnerships for AI-powered acoustic scene classification algorithms.
Within the integrated portfolio tier, Medtronic represents consolidated neuro-otology capabilities spanning cochlear implant categories. Stryker occupies a position in rigid endoscope supply chains that dominate North American hospital purchasing. Olympus Corporation exemplifies optical imaging architectures competing directly with chip-on-tip video systems from Karl Storz GmbH & Co. KG.
| Leading Market Players |
|---|
| Medtronic |
| Stryker |
| Smith & Nephew |
| Olympus Corporation |
| Cochlear Ltd. |
| Johnson & Johnson Services, Inc. |
| Sonova Holding AG |
| Karl Storz GmbH & Co. KG |
| Boston Scientific |
| Others |
Supply Flow & Price Mechanics
Premium-digital versus economy-analog hearing aid divergence manifests in starkly different margin structures and supply chain footprints. AI-powered noise cancellation modules command three-tier pricing stratification across premium, standard, and economy levels, while rechargeable battery transitions force cost compression through East Asian contract manufacturer concentration.
Pricing Analysis
Distributor markups in retail audiology channels absorb the steepest margin compression from rechargeable battery transitions. Three-tier pricing structure across premium, standard, and economy levels differentiates by digital signal processing capability and FDA 510(k) clearance tier. Price erosion runs through economy-analog devices as India's PLI scheme attracts assembly investments, while premium tiers maintain pricing power through AI-powered acoustic scene classification. Retail hearing centers show highest price sensitivity; hospital purchasing cooperatives demonstrate lowest sensitivity due to bundled service contracts.
Supply Chain Analysis
Regional distribution centers in Shenzhen, Stuttgart, and Minneapolis anchor hub-and-spoke patterns for finished device logistics. Component supply concentrates in China, South Korea, and Japan for lithium-ion battery cells, digital signal processors, and transducer assemblies. Raw material dependencies span rare earth magnets, medical-grade silicones, and optical glass substrates. Single-source vulnerability in East Asian battery cell production exposes OEMs to logistics bottlenecks. Distribution runs through audiology retail chains for hearing aids and GPO-negotiated hospital contracts for surgical instruments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in ENT devices hinges on electrode array upgrade cycles and AI-powered premium tier differentiation offsetting rechargeable battery cost compression.
For Market Incumbents: Deploy backward integration into electrode array manufacturing to capture cochlear implant upgrade margins. Consolidate rigid endoscope service contracts before single-use alternatives erode aftermarket revenue. Counter single-use rhinolaryngoscope substitution by bundling preventive maintenance with capital equipment leases. For New Entrants and Emerging Players: Direct-to-consumer acoustic monitoring channels unlock home-based sleep apnea screening outside polysomnography lab gatekeepers. Target India's PLI scheme for hearing aid assembly to offset tariff exposure in South Asian markets. Pursue white-label partnerships with audiology retail chains for economy-tier analog devices. For Investors and Strategic Acquirers: Consolidation pressure builds where EU Medical Device Regulation Class III clinical evidence requirements exceed mid-tier trial infrastructure capacity. Five-to-ten-year viability favors electrode system specialists with Tokyo-based PMDA parallel review track access. Signal to monitor: audiologist training program scaling rates against cochlear implant surgical volume growth.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Pathway Optimization | Accelerated clearance timelines for powered microdebriders capture US hospital purchasing cooperative contracts. |
| CE Marking Pathway Investment | EMA-aligned clinical evidence frameworks secure German university hospital procurement for bone-anchored systems. |
| Hospital System Partnership | Integrated delivery network contracts marginalize independent ambulatory surgery center vendor relationships. |
| Software Companion Development | AI-powered acoustic scene classification automates hearing aid fitting workflows in Japanese long-term care facilities. |
| Reimbursement Strategy | CMS code revisions for osseointegrated implants reshape competitive entry points for hybrid hearing loss categories. |
Methodological Framework
Bottom-up audiology clinic and hospital purchasing modeling reconciled against top-down OEM shipment tracking forms the analytical core of this study. Primary interviews with ENT specialists, biomedical engineers, GPO contracts managers, and audiology retail chain procurement heads combine with secondary validation from FDA 510(k) filings, PMDA approval databases, CMS reimbursement code revisions, and hospital procurement contract repositories. Triangulation across these sources anchors volume and value estimates.
Input-output matrices map hearing aid, endoscope, and implantable device flows across product type, technology tier, end user channel, and application indication dimensions over the projection horizon. CAGRs derive from segment-level growth rate reconciliation against macro healthcare expenditure trends. Forecast inputs incorporate geriatric ambulatory migration rates, rechargeable battery adoption curves, and single-use endoscope substitution trajectories.
Regulatory timeline delays, lithium-ion supply disruptions, and audiologist training bottlenecks are the dominant revision risks for forecast outputs. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
ENT
Global Audiological Devices Market
ENT
Hearing Amplifiers Market
ENT
Hearing Loss Disease Treatment Market
ENT
Global Pediatric Hearing Aids Market
ENT
Global Sinusitis Treatment Market
ENT
ENT Disorder Treatment Market
ENT
Europe Hearing Aids Market
ENT
Global ENT Workstations Market
ENT
Surgical ENT Devices Market
ENT
Audiology Devices Market
ENT
ENT Examination Chair Market
ENT
Interventional ENT Devices Market
ENT
Laryngeal Papillomatosis Treatment Market
ENT
ENT Laser Devices Market
ENT
Acute Sinusitis Market
ENT
Custom Hearing Aids Market