
 Audiology Devices Market | 2026-2036
Audiology Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Audiology Devices Market Analysis
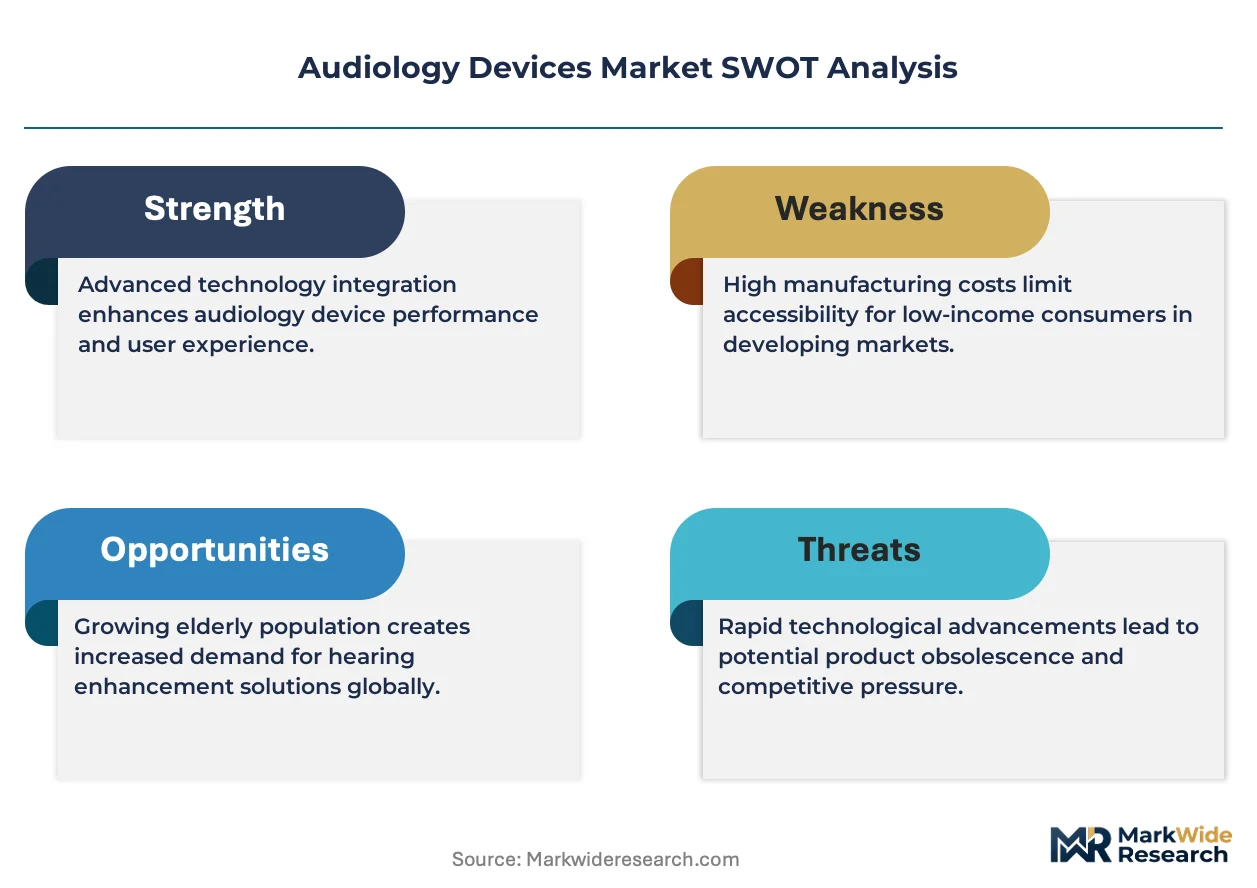
The FDA's over-the-counter hearing aid rule is pivoting the cost-of-entry calculus for new competitors and established manufacturers alike. Sonova Holding AG leverages its vertical integration across transducer manufacturing to sustain margin control amid pricing pressure. Demant A/S anchors its position through R&D intensity in digital signal processing architectures. Starkey Hearing Technologies differentiates via in-house production of custom earmold fabrication systems.
Audiology devices encompass electroacoustic instruments designed to amplify, process, or directly stimulate auditory pathways, typically operating across frequencies from 250 Hz to 8 kHz with programmable gain exceeding 40 dB for moderate-to-profound hearing loss. These systems serve the primary commercial purpose of restoring functional communication capacity in individuals with sensorineural, conductive, or mixed hearing impairments. Hearing aids occupy the largest revenue pool within product type segmentation, while cochlear implants represent the fastest-growing category as surgical candidacy broadens and electrode array designs advance. Bluetooth-enabled wireless technology commands premium positioning as direct streaming from consumer electronics becomes standard functionality across hospital and homecare end-user channels.
The FDA oversees device clearance through 510(k) and De Novo pathways for hearing aids and implantable systems, while the EU Medical Device Regulation mandates notified body conformity assessment for CE-marked audiology products entering European markets. ISO 10993 biocompatibility standards and IEC 60601-1 electrical safety requirements shape material selection and design validation protocols for manufacturers targeting multi-jurisdictional approval. Stakeholders must monitor how reimbursement code revisions in Medicare and parallel national health systems interact with direct-to-consumer channel expansion to determine optimal portfolio allocation between prescription and self-fit product architectures.
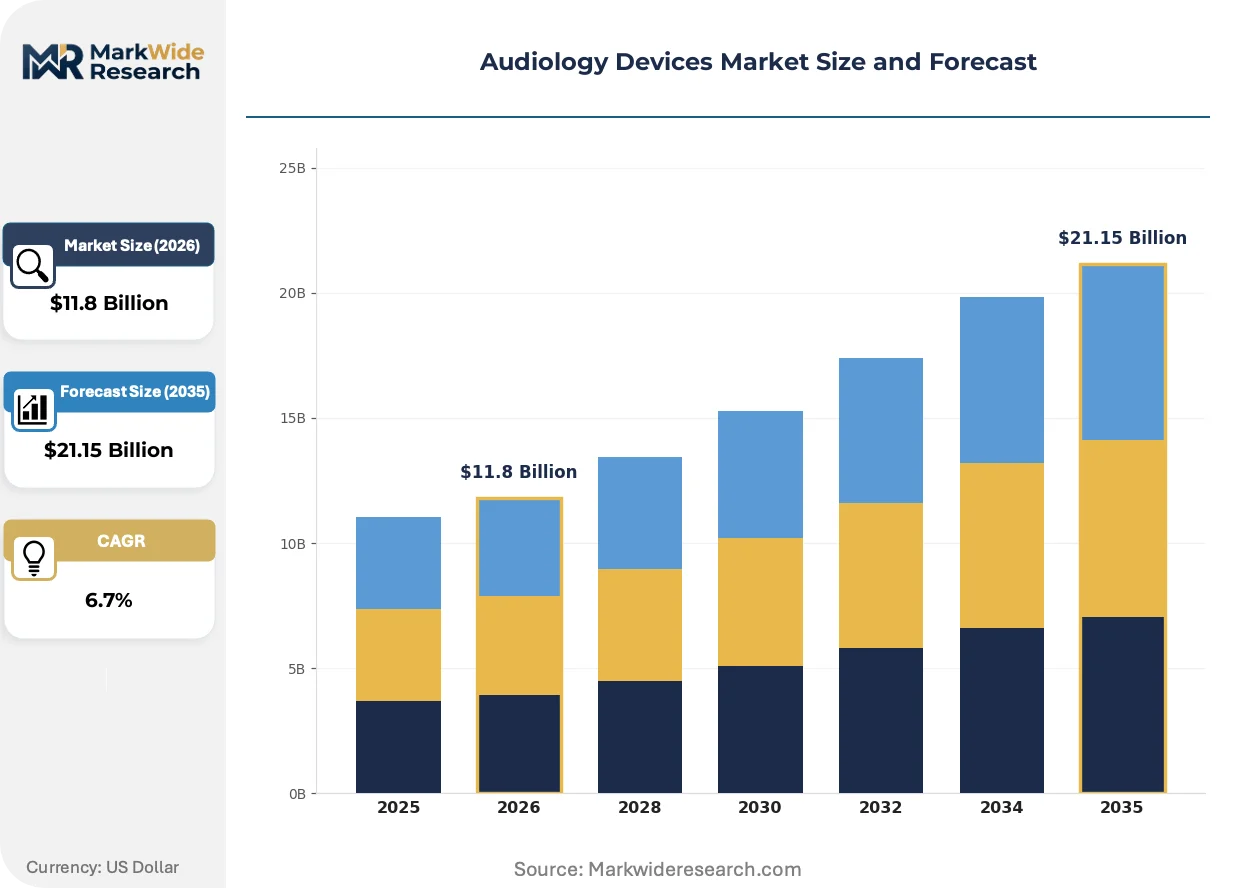
Market Dynamics
The FDA's over-the-counter hearing aid rule is compressing traditional prescription channels while opening self-fit pathways, forcing manufacturers to reconfigure distribution architectures and pricing tiers simultaneously.
Growth Catalysts
- Bluetooth Low Energy streaming protocols:Direct audio transmission from smartphones and televisions eliminates intermediary accessories, reducing device complexity for homecare users.
- Germany's statutory health insurance reimbursement frameworks:Digital signal processing platforms receive preferential coverage codes, accelerating provider upgrades to programmable gain systems.
- Japan's super-aging demographic profile:The world's highest 65-plus population ratio sustains concentrated demand for remote fitting solutions and tele-audiology services.
Market Restraints
- Semiconductor foundry concentration in Taiwan:Discrete audio DSP chip supply faces single-source vulnerability for programmable hearing instrument manufacturers.
- Zinc-air battery chemistry cost volatility:Silver oxide price swings directly impact disposable power cell economics for behind-the-ear device segments.
- Cochlear implant surgical candidacy thresholds:Strict audiological and radiological screening protocols limit addressable patient pools despite expanding electrode array capabilities.
Strategic Opportunities
- India's underserved rural audiology infrastructure:Community health worker screening programs create entry points for low-cost amplification devices outside formal clinic networks.
- Artificial intelligence-driven real-time noise classification:Machine learning inference at the edge converges with traditional DSP architectures to enable adaptive scene recognition.
- Direct-to-consumer subscription models:Monthly hardware-plus-service bundles bypass traditional audiologist gatekeepers while capturing recurring revenue streams.
Industry Challenges
- Audiologist workforce density gaps:Rural and exurban regions in the United States face practitioner shortages that constrain fitting capacity for prescription device channels.
- Multi-jurisdictional certification timelines:Simultaneous FDA 510(k), EU MDR notified body review, and Japan PMDA shonin processes extend product launch windows by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Audiology Devices Market |
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $21.15 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hearing Aids, Cochlear Implants, Bone Anchored Hearing Systems, Assistive Listening Devices Technology: Digital, Analog, Wireless, Bluetooth End User: Hospitals, Clinics, Homecare, Rehabilitation Centers Application: Hearing Loss, Tinnitus, Speech Therapy, Audiometric Testing |
| Companies Covered | Sonova Holding AG, Demant A/S, Starkey Hearing Technologies, Cochlear Ltd., MED-EL Medical Electronics, WS Audiology A/S, GN Store Nord A/S, Amplifon, Audina Hearing Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Audiology Devices Market Emerging Trajectories
Signal processing architectures and distribution channels are undergoing parallel transformation as self-fit devices gain legitimacy and artificial intelligence migrates to edge hardware.
Deep neural network-based noise suppression is electrifying real-time audio processing capabilities in premium hearing instruments. Homecare users with moderate-to-severe sensorineural loss are adopting these systems faster than clinic-based fitting cycles permit. The technology is compressing differentiation timelines between flagship and mid-tier product lines.
REACH restrictions on persistent organic pollutants are reshaping material selection for earmold fabrication and transducer housings. Manufacturers must validate alternative polymer formulations without compromising biocompatibility under ISO 10993 protocols. European notified bodies are enforcing stricter documentation requirements for CE-marked audiology products entering German and French distribution channels.
Consumers are bypassing traditional audiologist intermediaries through online hearing assessments and remote programming applications. Retail pharmacy chains and consumer electronics retailers are capturing device transactions previously controlled by independent hearing aid dispensers. This channel rotation is most visible in United States metropolitan markets following the FDA's 2022 over-the-counter classification.
Audiology Devices Market Segmentation
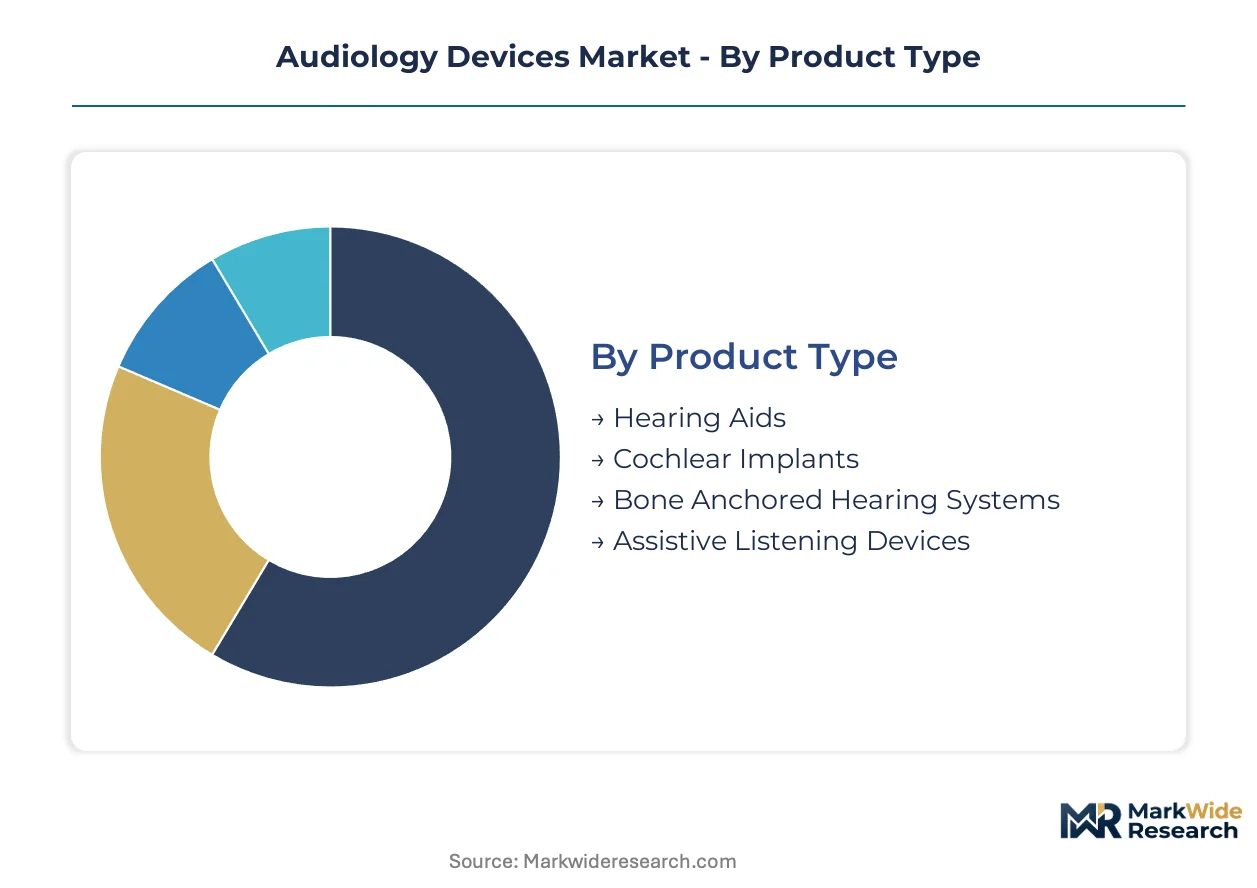
Audiology device manufacturers configure product portfolios across four intersecting dimensions. Supply chain positioning and reimbursement pathways vary substantially by segment, demanding differentiated go-to-market architectures.
Product Type:
Manufacturing scale concentrates disproportionately in electroacoustic amplification systems, while implantable neurostimulation platforms require specialized surgical channel partnerships.
- Hearing Aids:Miniaturized programmable amplifiers with multi-channel digital signal processing and directional microphone arrays. Demand clusters in Germany and Japan where statutory reimbursement frameworks favor programmable gain systems over basic analog alternatives.
- Cochlear Implants:Surgically implanted electrode arrays that bypass damaged cochlear hair cells to directly stimulate the auditory nerve. Surgical candidacy expansion in tertiary hospital networks drives volume, though strict audiological screening protocols constrain addressable pools relative to amplification devices.
- Bone Anchored Hearing Systems:Osseointegrated titanium implants transmitting sound via bone conduction for conductive or mixed hearing loss. ENT surgical suites in academic medical centers anchor distribution.
- Assistive Listening Devices:Personal amplifiers, FM systems, and infrared receivers supplementing primary hearing instruments. Educational institutions and theater venues sustain niche procurement.
Today's leader: Hearing Aids. Tomorrow's challenger: Cochlear Implants.
Technology:
Component sourcing strategies diverge sharply between legacy analog architectures and software-defined digital platforms requiring semiconductor partnerships.
- Digital:DSP-enabled adaptive compression and noise reduction algorithms. Premium tier positioning in Bluetooth-enabled instruments commands reimbursement code advantages across Japanese and German statutory systems.
- Bluetooth:Direct audio streaming protocols eliminating intermediary accessories. Homecare adoption accelerates as smartphone integration becomes standard functionality.
- Wireless:Proprietary radio frequency links between bilateral devices and remote microphones. Clinic-fitted premium systems retain this connectivity layer.
- Analog:Basic linear amplification circuits with manual volume controls. Price-sensitive procurement in emerging markets and institutional bulk purchasing.
Digital architectures dominate revenue contribution. Bluetooth integration represents the steepest expansion trajectory as direct-to-consumer channels mature.
End User:
Channel economics bifurcate between prescriptive clinical fitting workflows and emerging self-directed procurement pathways.
- Homecare:Direct-to-consumer and remote tele-audiology fitting models. FDA over-the-counter classification in the United States accelerates channel rotation away from traditional dispensers.
- Hospitals:Cochlear implant surgical programs and acute diagnostic audiology suites. Tertiary academic centers concentrate implantable device volume.
- Clinics:Independent audiology practices and hearing aid dispensers. Workforce density gaps in rural United States regions constrain fitting capacity.
- Rehabilitation Centers:Post-implantation auditory training and pediatric habilitation services. Government-contracted service providers dominate procurement.
Homecare channels are capturing transaction volume fastest. Hospital-based surgical programs retain premium pricing power.
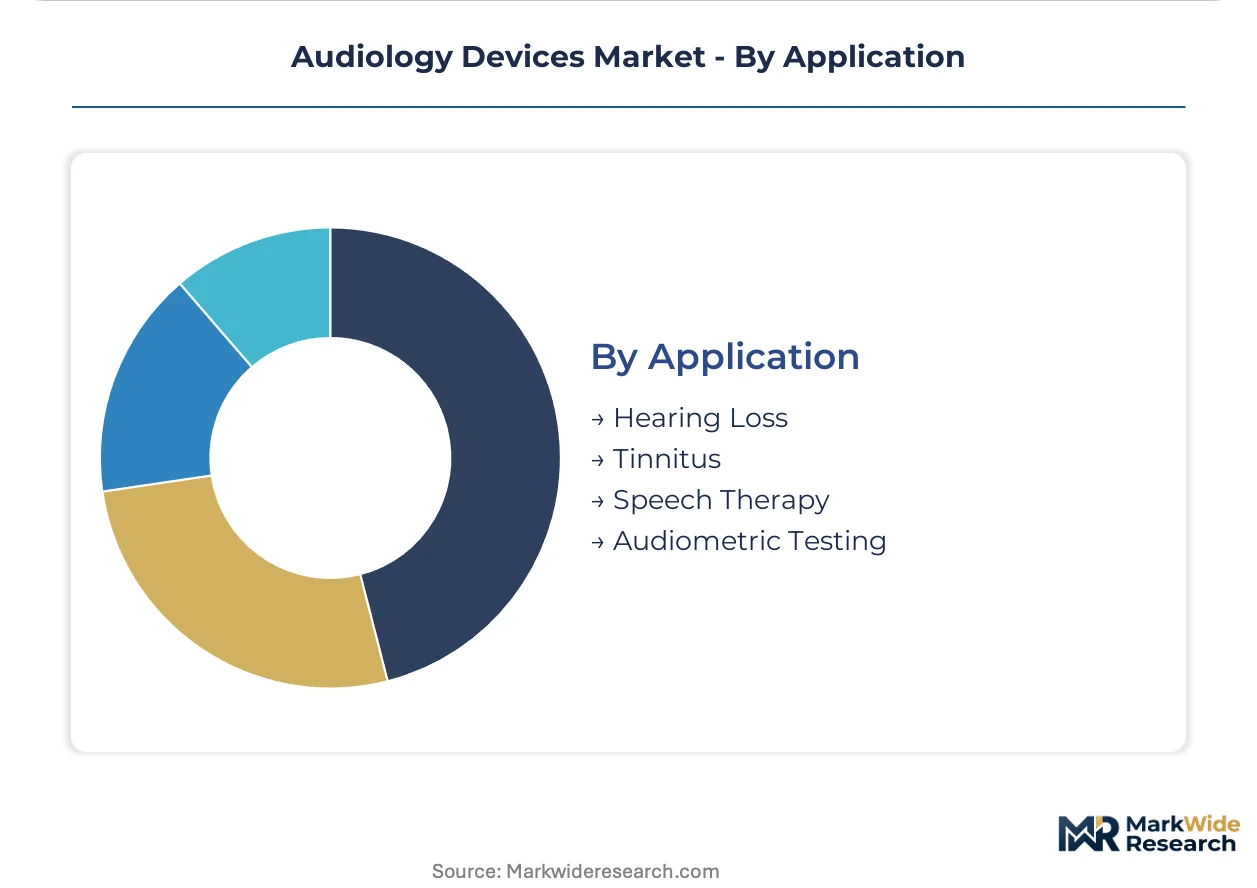
Application:
Clinical indication severity determines reimbursement tiering and device sophistication requirements across national health systems.
- Hearing Loss:Sensorineural, conductive, and mixed impairment categories spanning mild to profound severity. Medicare code revisions in the United States interact with direct-to-consumer expansion to reshape portfolio allocation.
- Tinnitus:Sound therapy masking and notched amplification approaches. Wellness-oriented positioning outside traditional medical device channels.
- Speech Therapy:Pediatric habilitation and adult aural rehabilitation tools. Educational and clinical speech-language pathology procurement.
- Audiometric Testing:Diagnostic equipment for pure-tone and speech audiometry. Hospital and clinic capital expenditure cycles drive replacement demand.
Sensorineural hearing loss indications anchor commercial volume. Tinnitus management applications are climbing fastest as consumer wellness positioning expands addressable demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Audiologist workforce density and reimbursement frameworks cluster demand in specific metropolitan corridors across five major economies. Germany's statutory health insurance system and Japan's super-aging demographic profile anchor premium device adoption. The FDA's over-the-counter rule is redistributing transaction volume toward direct-to-consumer channels in the United States.
United States
The FDA's 2022 over-the-counter hearing aid classification compresses traditional prescription channels while opening self-fit pathways for homecare users. Medicare reimbursement code revisions interact with direct-to-consumer expansion to reshape portfolio allocation between prescription and self-fit architectures. Minneapolis-St. Paul anchors a concentration of hearing instrument manufacturers and tele-audiology service providers.
Germany
Statutory health insurance reimbursement frameworks favor digital signal processing platforms with programmable gain systems over basic analog alternatives. The EU Medical Device Regulation mandates notified body conformity assessment for CE-marked audiology products entering German distribution channels. Berlin and Munich host clusters of hearing aid dispensers and digital health startups developing remote fitting solutions.
Japan
The world's highest 65-plus population ratio sustains concentrated demand for remote fitting solutions and tele-audiology services. Japan's PMDA shonin processes extend product launch timelines alongside FDA and EU MDR reviews. Tokyo and Osaka metropolitan areas concentrate audiology clinic networks and cochlear implant surgical programs.
India
Community health worker screening programs create entry points for low-cost amplification devices outside formal clinic networks. India's CDSCO regulates medical device imports while domestic manufacturing expands under production-linked incentive schemes. Bangalore and Hyderabad host emerging clusters of hearing instrument assemblers targeting rural audiology infrastructure gaps.
United Kingdom
The National Health Service procurement frameworks influence hearing aid dispensing patterns through contracted service providers. Post-Brexit regulatory divergence from EU MDR creates parallel conformity assessment requirements for manufacturers. London and Manchester concentrate private audiology chains and hospital-based cochlear implant centers.
Audiology Devices Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across the audiology devices landscape. The vendor base stratifies into three tiers: vertically integrated hearing instrument manufacturers, implantable neurostimulation platform developers, and retail service network operators. Strategic archetypes include R&D-intensive DSP architecture innovators, custom earmold fabrication system producers, and direct-to-consumer channel disruptors. M&A activity concentrates on tele-audiology capabilities and AI-driven noise classification technologies.
Among Swiss and Danish hearing instrument manufacturers, Sonova Holding AG and Demant A/S exemplify vertically integrated archetypes with captive transducer manufacturing. Starkey Hearing Technologies represents the American specialist model with in-house production capabilities. These three entities anchor competitive positioning across prescription and emerging self-fit market segments.
| Leading Market Players |
|---|
| Sonova Holding AG |
| Demant A/S |
| Starkey Hearing Technologies |
| Cochlear Ltd. |
| MED-EL Medical Electronics |
| WS Audiology A/S |
| GN Store Nord A/S |
| Amplifon |
| Audina Hearing Instruments |
| Others |
Supply Flow & Price Mechanics
Audiologist workforce concentration in Germany and Japan compresses labor-cost differentials between premium prescription channels and emerging self-fit tiers. This geographic clustering of fitting expertise widens pricing spreads as manufacturers offset higher service-bundled costs in statutory reimbursement markets against leaner direct-to-consumer architectures elsewhere.
Pricing Analysis
The bundled-versus-unbundled service split defines pricing architecture across the audiology devices landscape. Three-tier pricing structure across premium, standard, and economy levels separates Bluetooth-enabled DSP platforms with remote fitting support from basic programmable amplifiers and analog alternatives. Cost compression in the self-fit tier is intensifying because FDA over-the-counter classification invites consumer electronics entrants with leaner cost structures. Price sensitivity concentrates among homecare users seeking direct-to-consumer pathways, while hospital-based cochlear implant programs retain the lowest sensitivity due to surgical bundling and statutory coverage floors.
Supply Chain Analysis
Regional distribution centers in the Netherlands and Singapore anchor hub-and-spoke patterns for European and Asia-Pacific device fulfillment. Manufacturing concentrates in Switzerland, Denmark, and China, with discrete audio DSP chip sourcing drawing from Taiwan and South Korea. Zinc-air battery chemistry and silver oxide supply feed from South Korean and Japanese chemical processors. Single-source vulnerability in Taiwan semiconductor foundries threatens programmable instrument production. Distribution runs through audiologist dispensers, hospital procurement committees, and emerging direct-to-consumer logistics platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The audiology devices market functions as a stable compounder anchored by irreversible demographic aging across developed economies. Hearing loss prevalence curves ensure replacement demand cycles that outpace macroeconomic volatility.
For Market Incumbents: Hedge against channel compression by diversifying revenue mix between prescription and self-fit architectures. Deepen backward integration into transducer manufacturing to defend margin control as consumer electronics entrants drive pricing pressure in over-the-counter segments. Prioritize certification investment for EU MDR and Japan PMDA shonin pathways to maintain premium positioning in statutory reimbursement markets.
For New Entrants and Emerging Players: Retail pharmacy chains represent the most penetrable channel partner type for bypassing audiologist gatekeepers. Target India's rural audiology infrastructure gaps through community health worker screening programs paired with low-cost amplification devices. Pursue direct-to-consumer subscription models capturing recurring hardware-plus-service revenue outside traditional fitting workflows.
For Investors and Strategic Acquirers: Consumer electronics conglomerates are the most active acquirer in this space as they seek hearing health entry points. The five-to-ten-year viability window favors platform plays combining edge AI noise classification with tele-audiology service layers. Acquisition target archetypes include tele-audiology software specialists and AI-driven audio processing chip designers. Monitor FDA enforcement discretion on over-the-counter quality standards as the critical inflection signal for competitive intensity.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Clears prescription hearing aid pathways while over-the-counter alternatives pressure timing. |
| CE Marking Pathway | EU MDR notified body review gates access to German statutory reimbursement frameworks. |
| Hospital System Partnership | Tertiary academic centers concentrate cochlear implant surgical volume and premium pricing. |
| Software Companion Development | Remote fitting applications enable tele-audiology service differentiation beyond hardware. |
| Reimbursement Strategy | Medicare code revisions interact with direct-to-consumer expansion to reshape portfolio allocation. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged hearing instrument manufacturers, audiology clinic operators, hospital purchasing committees, biomedical engineers, and GPO contracts managers. Secondary validation drew from FDA 510(k) filings, EU MDR notified body databases, Japan PMDA shonin registers, CMS Medicare reimbursement codes, and customs trade records. Bottom-up segment sizing and top-down macroeconomic cross-checks ensured analytical consistency.
Segment-weighting approaches distributed value and volume across product type, technology architecture, end-user channel, and application indication dimensions. Hearing aid, cochlear implant, and bone anchored system categories each carried distinct growth trajectories over the projection horizon. CAGRs emerged from fitted curve analysis against demographic prevalence data and reimbursement policy evolution. Semiconductor supply constraints and zinc-air battery chemistry volatility fed as scenario variables.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA enforcement patterns, EU MDR implementation delays, and Taiwan foundry capacity allocation. Outputs reflect documented assumptions around aging demographics, reimbursement code stability, and Bluetooth protocol adoption curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
ENT
Europe Speech Therapy Market
ENT
US Hearing Aids Market
ENT
North America Hearing Aid Market
ENT
Global ENT Workstations Market
ENT
Hearing Implants Market
ENT
Europe Hearing Aids Market
ENT
ENT Devices Market
ENT
Global Pediatric Hearing Aids Market
ENT
Nasal Sampling Lines Market
ENT
Electrolarynx Market
ENT
Over-The-Counter (OTC) Hearing Aids Market
ENT
Head and Neck Squamous Cell Carcinoma Market
ENT
Denmark Hearing Aids Market
ENT
Custom Hearing Aids Market
ENT
ENT Examination Chair Market
ENT
Ear Health Market