
 Medical X-Ray Films Market | 2026-2036
Medical X-Ray Films Market Size, Share, and Industry Trends Forecast 2026-2036
Medical X-Ray Films Market Foresight
Aftermarket service revenue for legacy film processors is fragmenting across regional service networks and third-party refurbishment specialists. Fujifilm Holdings Corporation leverages its vertical integration into silver halide chemistry and coating infrastructure to sustain margins on specialty film lines. Carestream Health Inc. competes through channel control over hospital group purchasing contracts in North American diagnostic networks. Agfa-Gevaert NV anchors its position in European diagnostic centers with extended service agreements for analog-to-digital hybrid workflows.
Medical X-Ray Films comprise silver halide emulsion layers coated onto polyester bases, typically measuring 35 × 43 cm for chest radiography and 24 × 30 cm for extremity imaging, designed to convert ionizing radiation into visible grayscale images for diagnostic interpretation. These films serve commercial purposes in healthcare settings where immediate hard-copy records, legal documentation requirements, or infrastructure constraints preserve analog workflows. Film Type segments dominate volume in emerging markets where digital radiography capital investment remains constrained, while Specialty Film lines carry premium positioning in mammography and dental applications. Digital X-Ray segments capture growth in hospital systems pursuing enterprise imaging consolidation, though Analog X-Ray retains defensive demand from clinics with depreciated equipment bases.
FDA 21 CFR Part 820 quality system regulations govern film manufacturing for US market access, while EU MDR and CE marking requirements impose clinical evaluation obligations on imaging consumables distributed in European member states. Japan's PMDA maintains distinct pharmacovigilance reporting standards for radiographic materials classified as medical devices. Stakeholders must monitor reimbursement parity shifts between digital and analog modalities as health technology assessment bodies recalibrate cost-effectiveness thresholds for diagnostic imaging pathways.
Market Dynamics
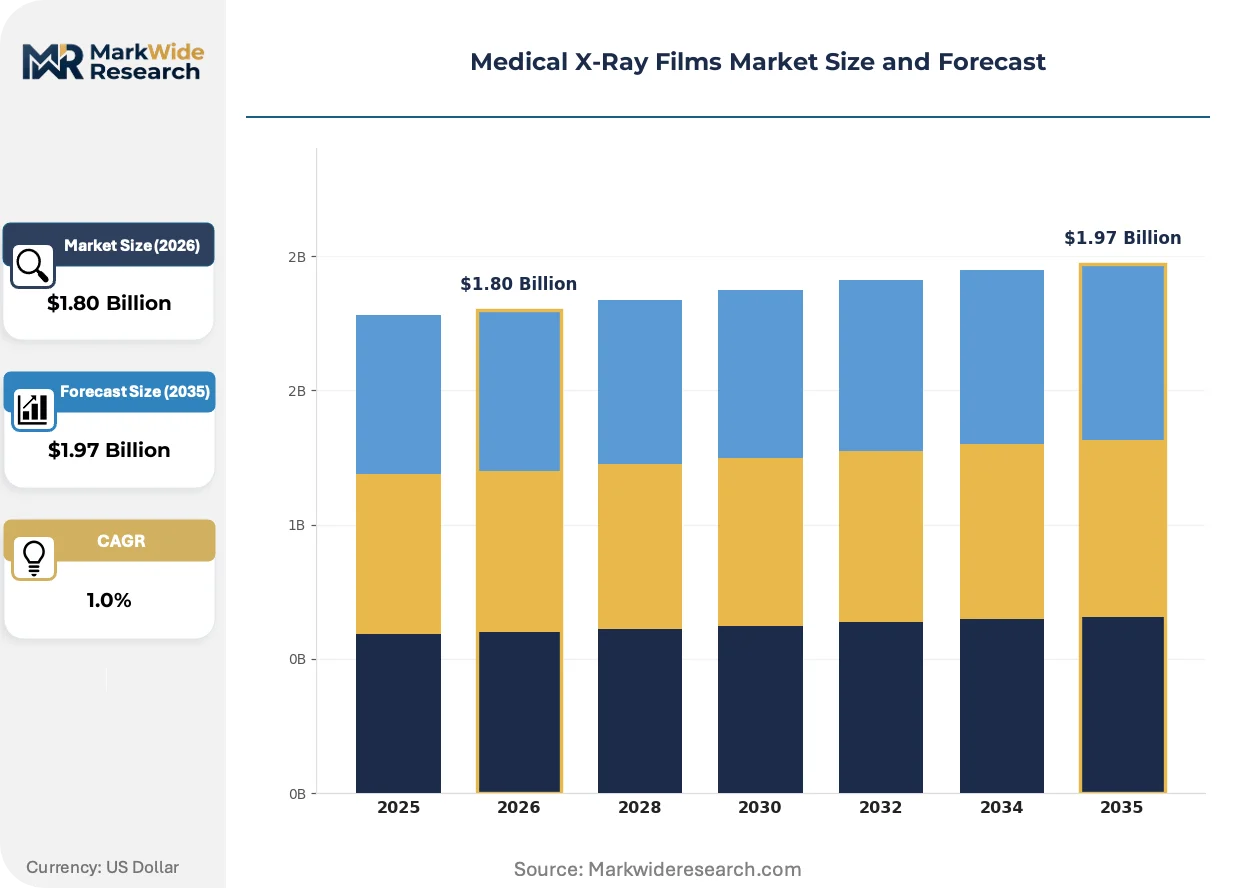
The medical X-ray films market faces sustained pressure from digital radiography adoption while residual analog demand persists in infrastructure-constrained settings. Hospital capital budgets and regulatory reimbursement parity between modalities determine procurement velocity across healthcare networks.
Growth Catalysts
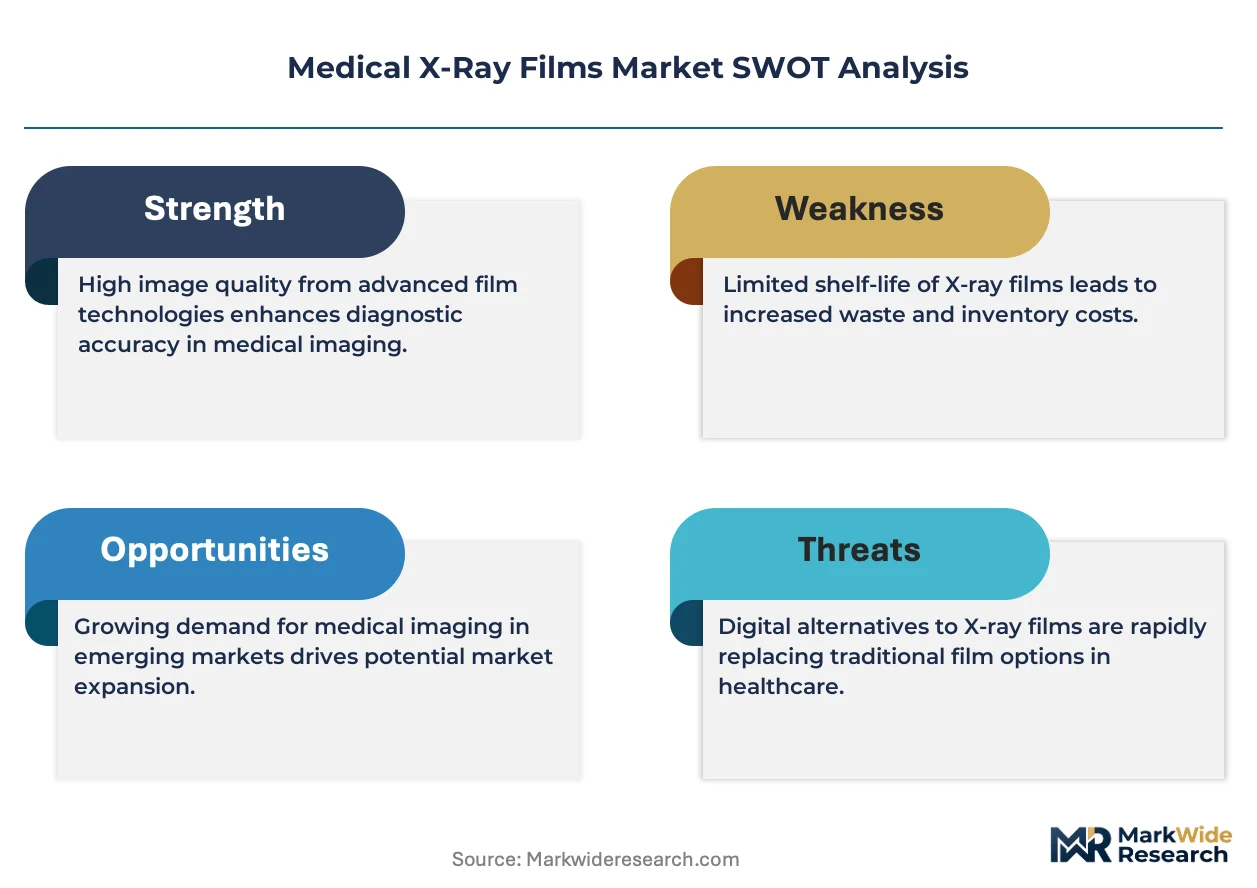
- Hybrid workflow persistence:Diagnostic centers in Germany and Japan maintain dual analog-digital systems to serve legacy equipment bases and legal documentation requirements. EU MDR imaging specifications preserve film-based pathways for specific clinical indications.
- Silver halide chemistry refinement:Specialty film lines for mammography and dental applications leverage advanced emulsion technologies to sustain diagnostic accuracy where digital sensors underperform. These premium segments resist full digitization.
- FDA 21 CFR Part 820 compliance infrastructure:Established quality systems for US market access create barriers to entry that protect incumbent manufacturers serving hospital radiology departments with validated supply chains.
Market Restraints
- Silver price volatility:Raw material input costs for silver halide emulsion layers fluctuate with precious metals markets, compressing margins on standard film grades without corresponding pricing power.
- Digital radiography substitution:Computed radiography and direct digital radiography systems displace film-based workflows in hospital systems pursuing enterprise imaging consolidation and PACS integration.
- Capital intensity of coating infrastructure:Polyester base manufacturing and emulsion coating facilities require specialized environmental controls and scale economics that deter new market entry.
Strategic Opportunities
- Service contract bundling:Extended maintenance agreements for legacy film processors in European diagnostic centers create recurring revenue streams and customer lock-in alongside consumable sales.
- Veterinary and industrial NDT applications:Non-destructive testing workflows and animal health imaging sustain demand for analog films outside hospital radiology, with less price pressure from digital alternatives.
- Developing market infrastructure gaps:Clinics in regions with unreliable electricity supply and limited technical service networks preserve film-based workflows as the default diagnostic standard.
Industry Challenges
- Technical workforce attrition:Darkroom technicians and film processor maintenance specialists retire without replacement training pipelines, straining service delivery for analog equipment bases.
- Dual registration burden:Manufacturers must maintain parallel FDA 510(k) and EU MDR technical documentation for film products classified as medical devices, diverting regulatory affairs resources.
- Legacy system integration friction:Hybrid workflows combining analog capture with digital archiving require specialized digitizer hardware and workflow software that complicates IT procurement decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical X-Ray Films Market |
| Market Size in 2026 | $1.80 Billion |
| Market Size in 2035 | $1.97 Billion |
| CAGR (2026 – 2036) | 1.0% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Film Type, Digital X-Ray, Analog X-Ray, Specialty Film End User: Hospitals, Diagnostic Centers, Clinics, Research Labs Application: Pediatrics, Oncology, Orthopedics, Cardiology Delivery Mode: Direct Distribution, Retail Sale, Online Sales, Distributor Networks |
| Companies Covered | Fujifilm Holdings Corporation, Konica Minolta Inc., Agfa-Gevaert NV, Carestream Health Inc., Sony Corporation, Codonics Inc., Foma Bohemia Ltd, Flow Dental, Colenta, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical X-Ray Films Market Shifts & Advancements
Technological substitution and regulatory recalibration are compressing traditional film demand while opening defensive niches for specialized applications. Market participants must navigate divergent digitization timelines across geographies and clinical settings.
Dry laser imaging films are collapsing the wet processing infrastructure requirement that previously anchored hospital darkroom operations. Outpatient imaging centers and smaller diagnostic networks adopt these films to eliminate chemical handling, environmental compliance, and water usage while preserving hard-copy output for legal records. The technology compresses facility overhead and accelerates clinic deployment in space-constrained settings.
EU MDR clinical evaluation obligations for imaging consumables are extending product registration timelines and documentation requirements for film manufacturers. The regulation demands post-market surveillance and performance validation that increases compliance costs disproportionately for lower-volume specialty lines. European diagnostic centers respond by consolidating supplier relationships toward established registrants with dedicated regulatory affairs capabilities.
Aftermarket service unbundling is fragmenting the legacy processor maintenance ecosystem. Third-party refurbishment specialists and regional service networks displace manufacturer-direct service contracts, particularly for equipment beyond original warranty periods. This pattern concentrates in the United States where independent service organizations exploit gaps in OEM coverage for depreciated installed bases.
Medical X-Ray Films Market Segmentation
Segmentation in medical X-ray films reveals divergent profit pools across analog persistence and digital transition zones. After-sales service intensity varies dramatically by product maturity and end-user technical sophistication, reshaping vendor resource allocation and partnership priorities.
Product Type:
After-sales service intensity peaks with legacy analog equipment requiring darkroom chemistry management and processor maintenance contracts.
- Analog X-Ray:Silver halide emulsion films coated on polyester bases require wet chemical processing in hospital darkrooms. Demand concentrates in German diagnostic centers maintaining dual workflows for legal documentation compliance, sustained by EU MDR imaging specifications that preserve film-based pathways.
- Specialty Film:Advanced emulsion formulations for mammography and dental applications deliver superior spatial resolution where digital sensors underperform. Japanese diagnostic networks drive procurement for these premium lines, leveraging PMDA pharmacovigilance standards that validate specialized clinical performance.
- Film Type:Standard-grade diagnostic films serving volume markets in infrastructure-constrained regions.
- Digital X-Ray:Direct and computed radiography systems displacing film in enterprise imaging consolidation.
Analog X-Ray holds the largest share; momentum sits with Specialty Film.
End User:
Cost tier stratification separates capital-rich hospital systems from price-sensitive outpatient facilities.
- Hospitals:Radiology departments sustain hybrid procurement of analog films alongside digital transition, driven by depreciated equipment bases and PACS integration timelines. United States hospital networks anchor volume through group purchasing contracts, though capital budgets increasingly favor enterprise imaging consolidation.
- Diagnostic Centers:Specialized imaging facilities balance throughput economics against space constraints. German and Japanese centers maintain the strongest analog film demand, supported by extended service agreements for hybrid analog-digital workflows and regulatory documentation requirements.
- Clinics:Smaller facilities with limited technical service access.
- Research Labs:Academic and institutional users with specialized imaging protocols.
Hospitals command the revenue base; Diagnostic Centers are expanding most quickly.
Application:
Volume concentration follows procedure reimbursement rates and imaging modality standardization.
- Orthopedics:Extremity and skeletal imaging generates consistent film demand for trauma and post-operative assessment. United States orthopedic clinics preserve analog workflows where immediate hard-copy documentation supports malpractice risk management.
- Oncology:Tumor imaging and treatment monitoring requires high-resolution capture for subtle tissue differentiation. Japanese oncology centers sustain specialty film procurement where PMDA standards emphasize diagnostic accuracy in radiation therapy planning.
- Pediatrics:Reduced-dose imaging protocols with specific film sensitivity requirements.
- Cardiology:Cardiac catheterization and vascular imaging with distinct technical specifications.
Orthopedics dominates procedure volume; Oncology shows the steepest expansion trajectory.
Delivery Mode:
Margin structure varies by channel control intensity and inventory carrying requirements.
- Distributor Networks:Regional medical supply distributors aggregate fragmented clinic demand and manage silver price volatility through inventory buffers. German and Japanese diagnostic networks rely heavily on these channels for just-in-time film delivery alongside chemistry reagents.
- Direct Distribution:Manufacturer-direct sales to hospital systems with validated supply chains and FDA 21 CFR Part 820 compliance documentation. United States hospital group purchasing organizations concentrate procurement through these channels for contract pricing enforcement.
- Retail Sale:Limited direct-to-facility transactions for emergency replenishment.
- Online Sales:Emerging channel for standardized film grades with predictable specifications.
Distributor Networks capture the broadest reach; Direct Distribution is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Japan and Germany show the least price sensitivity, prioritizing diagnostic accuracy and regulatory compliance over procurement costs. United States hospital networks exhibit moderate elasticity, balancing film quality against group purchasing contract leverage. Clinics across developing markets demonstrate the highest sensitivity, where infrastructure constraints preserve analog workflows as the default standard.
United States
FDA 21 CFR Part 820 quality system regulations govern hospital radiology department procurement, with group purchasing organizations concentrating volume through validated supply chains. Orthopedic clinics in the Southeast sustain analog film demand for immediate hard-copy documentation supporting malpractice risk management. The Pacific Northwest accelerates digital transition faster than national averages.
Germany
EU MDR imaging specifications preserve film-based pathways for specific clinical indications, sustaining dual analog-digital workflows in diagnostic centers. Extended service agreements for hybrid equipment anchor customer relationships in Bavaria and North Rhine-Westphalia. The country's national pharmaceutical regulator enforces post-market surveillance obligations that favor established registrants.
Japan
PMDA pharmacovigilance reporting standards for radiographic materials validate specialized clinical performance in oncology and mammography applications. Diagnostic networks in Kanto and Kansai regions drive premium specialty film procurement. METI industrial policy supports domestic coating infrastructure for silver halide chemistry refinement.
India
CDSCO medical device regulations impose registration requirements on imaging consumables, though enforcement capacity varies across states. Clinics in Maharashtra and Gujarat preserve film-based workflows where electricity reliability and technical service access remain constrained. BIS standards provide nominal quality benchmarks for imported and domestic film grades.
Brazil
ANVISA medical device oversight governs film product registration, with compliance costs limiting supplier diversity in diagnostic networks. São Paulo and Rio de Janeiro concentrate hospital radiology demand, while interior states rely on distributor networks for just-in-time replenishment. Regional service fragmentation complicates legacy processor maintenance outside major metros.
Medical X-Ray Films Market Competitive Landscape
Capability concentration sits with chemistry and coating specialists; scale advantage sits with diversified imaging conglomerates. The market structure reflects a consolidated tier of integrated manufacturers defending position through regulatory compliance infrastructure and quality system validation, alongside regional specialists serving price-sensitive developing markets. Three archetypes dominate: silver halide chemistry specialists with backward integration into emulsion technology, diversified healthcare conglomerates leveraging cross-modal distribution networks, and regional coating facilities serving localized demand pools. Competitive moves center on service contract bundling for legacy equipment bases and geographic expansion through distributor network partnerships.
Among Japanese diversified imaging conglomerates, Fujifilm Holdings Corporation and Sony Corporation exemplify the chemistry-coating integration archetype, with Konica Minolta Inc. occupying a parallel position in the same national cluster. Agfa-Gevaert NV represents the European specialist model, while Carestream Health Inc. anchors North American channel control through hospital group purchasing relationships. These named entities illustrate how geographic origin and corporate structure correlate with strategic positioning: Tokyo-based conglomerates leverage upstream control over silver halide supply chains, Belgian and US incumbents emphasize regulatory affairs capabilities and contract enforcement respectively.
| Leading Market Players |
|---|
| Fujifilm Holdings Corporation |
| Konica Minolta Inc. |
| Agfa-Gevaert NV |
| Carestream Health Inc. |
| Sony Corporation |
| Codonics Inc. |
| Foma Bohemia Ltd |
| Flow Dental |
| Colenta |
| Others |
Supply & Pricing Matrix
Silver price volatility determines both margin compression in standard-grade film tiers and the geographic concentration of coating infrastructure. Raw material input costs fluctuate with precious metals markets, forcing manufacturers to stratify pricing across premium specialty lines and volume economy grades while anchoring production in Japan and Belgium where environmental compliance infrastructure justifies capital intensity.
Pricing Analysis
Aftermarket service revenue from legacy processor maintenance contracts drives lifetime value for established manufacturers. Three-tier pricing structure across premium mammography films, standard diagnostic grades, and economy lines for developing markets separates Fujifilm's specialty positioning from regional competitors. Cost compression in standard grades is intensifying because digital radiography substitution erodes volume leverage. Clinics across India and Brazil demonstrate the highest price sensitivity, while Japanese diagnostic networks prioritize diagnostic accuracy over procurement costs.
Supply Chain Analysis
Export-control restrictions on silver halide emulsion technology limit coating equipment flows to unlicensed facilities, concentrating advanced manufacturing in Japan, Belgium, and the United States. Silver bullion supply draws from Mexican and Peruvian mining operations, while polyester base manufacturing rests on petrochemical feedstocks anchored in Gulf Coast and Northeast Asian refining clusters. Single-source vulnerability concentrates in specialty chemical additives for mammography emulsion formulations. Distribution runs through hospital group purchasing organizations in North America and regional medical supply distributors in European diagnostic networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across hybrid analog-digital workflows creates defensive niches for specialists serving infrastructure-constrained settings and regulatory documentation requirements.
For Market Incumbents: Insulate core revenue by extending service agreements for depreciated film processors in German and Japanese diagnostic centers, locking in consumable pull-through. Deepen backward integration into silver halide chemistry to offset raw material volatility. Prioritize FDA 21 CFR Part 820 compliance infrastructure as a barrier against emerging coating specialists from developing markets. For New Entrants and Emerging Players: Build out veterinary imaging and industrial non-destructive testing applications where digital substitution pressure remains muted. Target Brazilian interior states and Indian state-level clinic networks where electricity reliability constraints preserve film workflows. Lead with dry laser imaging films to eliminate wet processing infrastructure requirements and accelerate clinic deployment. For Investors and Strategic Acquirers: The market sits at a late-digitization phase that favors service-intensive incumbents with regulatory affairs capabilities over capital-light entrants. Acquisition candidates should demonstrate validated EU MDR technical documentation and established hospital GPO relationships. Watch reimbursement parity shifts between analog and digital modalities as the inflection signal for residual demand durability.| Strategic Initiative | Industry Significance |
|---|---|
| Extended Service Agreement Expansion | Locks in recurring revenue alongside consumable sales in European diagnostic networks. |
| Specialty Film Line Investment | Captures premium positioning in mammography where PMDA standards validate clinical performance. |
| Dry Laser Imaging Transition | Eliminates chemical handling overhead for outpatient imaging centers in space-constrained settings. |
| Regulatory Affairs Capability Buildout | Accelerates EU MDR registration timelines for imaging consumables in consolidated supplier relationships. |
| Veterinary Application Diversification | Opens defensive demand pools outside hospital radiology with reduced digital price pressure. |
Research Methodology
A standing panel of hospital purchasing committee members, biomedical engineers, GPO contracts managers, and darkroom technicians provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with these stakeholders and secondary validation against FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement records, and silver market commodity reports. Bottom-up volume estimates from end-user segments triangulated against top-down manufacturer capacity assessments.
Scenario bracketing anchored the analytical framework across the projection horizon, with CAGRs derived from segment-level adoption curves and replacement cycle modeling. Segmentation dimensions included product type, end-user facility tier, application specialty, and regional regulatory cluster. Forecast inputs incorporated silver price trajectory assumptions and digital radiography capital expenditure patterns from hospital system disclosures.
The forecast holds incumbent behavior within observed patterns; aggressive consolidation moves by diversified imaging conglomerates or abrupt reimbursement parity shifts would shift outcomes. Material shifts in FDA quality system enforcement or EU MDR clinical evaluation obligations would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Ultrasound Systems Market
Medical Imaging
South America Digital X-Ray Devices Market
Medical Imaging
Japan Nuclear Imaging Market
Medical Imaging
Canada Computed Tomography Market
Medical Imaging
Saudi Arabia Diagnostic Imaging Market
Medical Imaging
France Nuclear Imaging Market
Medical Imaging
Medical X-Ray Equipment and Imaging Software Market
Medical Imaging
Japan Digital Radiology Market
Medical Imaging
South Korea Mammography Market
Medical Imaging
Imaging Agents Market
Medical Imaging
Magnetic Resonance Imaging Market
Medical Imaging
Advanced Computed Tomography (CT) Scanner Market
Medical Imaging
Asia Pacific Nuclear Imaging Market
Medical Imaging
China Digital Radiology Market
Medical Imaging
Asia Pacific Open System MRI Market
Medical Imaging
Japan Magnetic Resonance Imaging Market