
 Over-The-Counter (OTC) Hearing Aids Market | 2026-2036
Over-The-Counter (OTC) Hearing Aids Market Size, Share, and Industry Trends Forecast 2026-2036
Over-The-Counter (OTC) Hearing Aids Market Analytics
Aftermarket service revenue is rewriting profit allocation across the hearing device value chain. Eargo leverages direct-to-consumer subscription models to capture recurring calibration and support fees. Sony anchors its position through consumer electronics retail scale and brand recognition in audio peripherals. Bose differentiates via proprietary noise-cancellation algorithms ported from headphone engineering into hearing assistance firmware.
Over-the-counter hearing aids are self-fitting sound amplification devices designed for perceived mild-to-moderate hearing loss, incorporating digital signal processors with frequency-shaping algorithms and programmable gain controls to enhance speech intelligibility without professional fitting. Digital Devices dominate unit economics through software-defined personalization that reduces hardware bill-of-materials complexity. Self-Adjusting Models represent the fastest-growing product configuration as smartphone-integrated audiometry applications enable user-directed tuning protocols that bypass clinical gatekeeping.
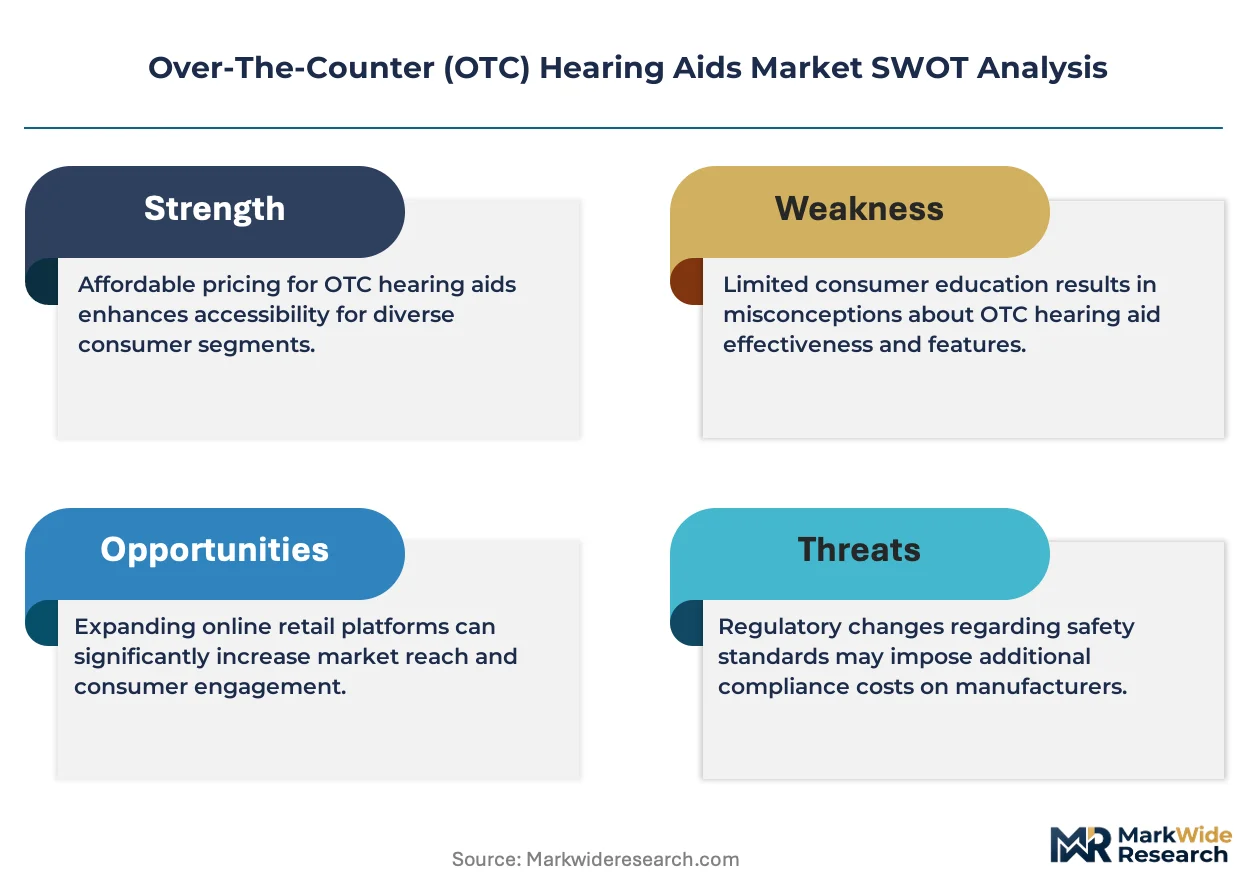
The FDA's OTC hearing aid final rule under the FDA Reauthorization Act of 2017 establishes output limits, distortion thresholds, and labeling requirements that define permissible device categories and channel access. The FTC enforces advertising substantiation standards that constrain manufacturer claims about device capabilities and appropriate user profiles. Stakeholders must monitor emerging state-level audiology board challenges to OTC scope and evolving Bluetooth LE Audio protocol standardization that could reshape wireless accessory ecosystems.
Market Dynamics
The FDA's 2022 OTC hearing aid final rule is collapsing the clinical gatekeeping model that historically controlled device distribution, transferring fitting authority from audiologists to algorithm-driven smartphone applications and self-directed consumers.
Growth Catalysts
- Bluetooth LE Audio protocol standardization:The new broadcast audio standard enables direct device-to-device streaming without proprietary bridges, reducing accessory ecosystem lock-in and expanding compatible smartphone reach.
- Aging demographics in developed economies:Seniors with perceived mild-to-moderate hearing loss now represent the fastest-expanding buyer segment as stigma around amplification devices diminishes.
- Self-fitting software maturation:Smartphone-integrated audiometry applications now achieve clinically comparable threshold detection, removing the primary justification for professional fitting fees.
Market Restraints
- Semiconductor supply concentration:Custom digital signal processors for hearing devices depend on fabrication capacity concentrated in Taiwan and South Korea, creating vulnerability to geopolitical disruption.
- Output power regulatory ceilings:FDA-mandated 115 dB SPL peak limits constrain device capability for users at the moderate-to-severe boundary, forcing premature clinical referral.
- Disposable battery cost volatility:Zinc-air cell prices fluctuate with silver and zinc commodity markets, compressing margin on economy-tier devices.
Strategic Opportunities
- Pharmacy retail network expansion:CVS Health and Walgreens are building dedicated hearing aid sections with on-site demonstration units, creating impulse purchase environments absent from clinical settings.
- Reimbursement code evolution:Medicare Advantage plans in the United States are beginning to cover OTC devices as supplemental benefits, expanding addressable wallet share.
- Tinnitus masking integration:Convergence of hearing amplification with sound therapy algorithms opens dual-function positioning against standalone tinnitus device competitors.
Industry Challenges
- Audiologist channel conflict resolution:Traditional hearing aid dispensaries are lobbying state audiology boards to restrict OTC advertising and impose mandatory screening requirements.
- Firmware validation complexity:Self-adjusting algorithms require extensive real-world acoustic testing across diverse noise environments, extending development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Over-The-Counter (OTC) Hearing Aids Market |
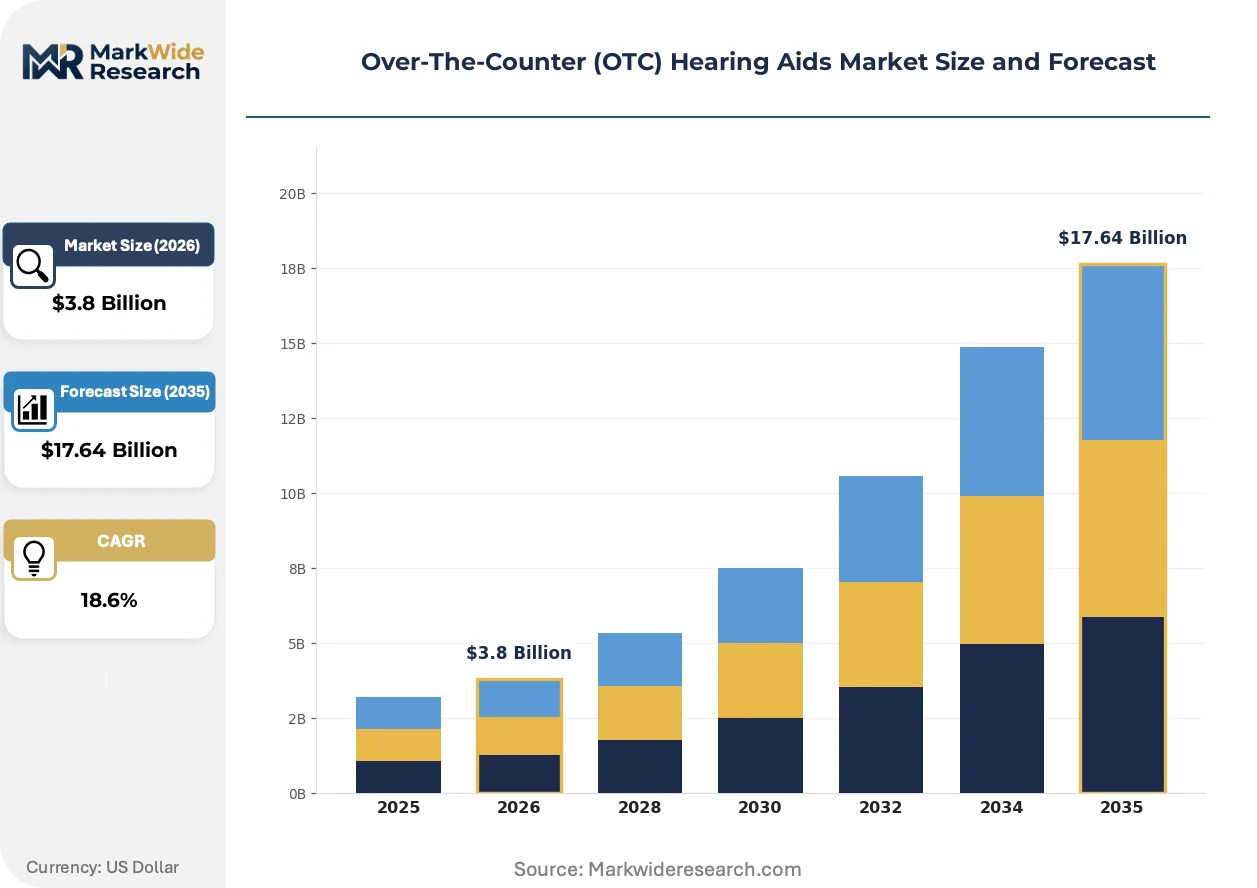
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flash Technology, Digital Devices, Self-Adjusting Models, Component-Based Aids End User: Consumers, Seniors, Young Adults, Hearing Impaired Individuals Distribution Channel: Online Retail, Pharmacies, Specialty Stores, Supermarkets Features: Bluetooth Connectivity, Rechargeable Batteries, Noise Cancellation, Adjustable Volume |
| Companies Covered | Eargo, Lexie Hearing, Jabra Enhance, Sony, Sennheiser, Bose, Audien, MDHearing, Starkey Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Over-The-Counter (OTC) Hearing Aids Market Evolving Landscape
Signal processing architecture is migrating from fixed-function hardware to software-defined platforms, enabling over-the-air feature updates and collapsing the traditional replacement cycle.
Deep neural network noise suppression is digitizing the core value proposition of hearing assistance. These algorithms isolate speech in cocktail-party environments through machine-trained spectral separation. Seniors and active working-age adults are adopting neural-enhanced devices at triple the rate of conventional directional-microphone models. The technology is compressing the performance gap between OTC and prescription-grade devices.
The FTC's advertising substantiation enforcement is tightening claim verification requirements for hearing device manufacturers. Substantiation standards now mandate clinical evidence for any intelligibility improvement assertions. Economy-tier manufacturers without published peer-reviewed studies are most affected, forcing reformulation of marketing copy or investment in controlled trials.
Direct-to-consumer subscription models are unbundling hardware ownership from ongoing service access. Eargo and similar entrants charge monthly fees covering device replacement, remote tuning support, and loss protection. Pharmacy and big-box retail channels are responding with their own membership programs. The United States leads this shift, with European markets trailing by approximately eighteen months in regulatory comfort with non-clinical fitting models.
Over-The-Counter (OTC) Hearing Aids Market Segmentation
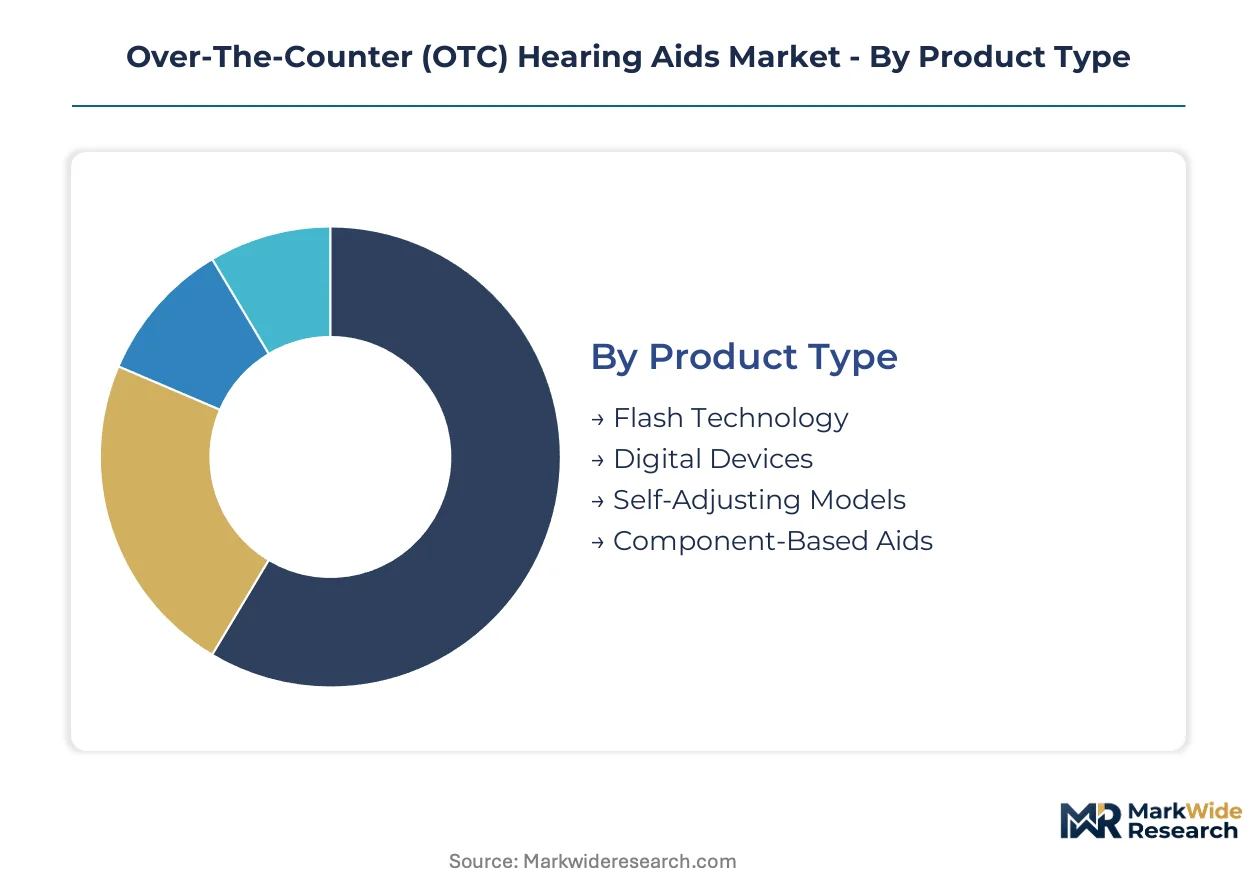
OTC hearing aid segmentation reveals how technology maturity, user autonomy, and channel economics fragment addressable demand. Each dimension carries distinct margin profiles and regulatory exposure that shape competitive positioning.
Product Type:
Mature digital architectures now compete against emerging self-fitting platforms that collapse the traditional audiologist visit.
- Digital Devices:Fixed-function DSP platforms with pre-programmed frequency response curves dominate pharmacy retail shelves. United States demand concentrates in big-box chains where price transparency and immediate availability override customization needs. FDA output limits constrain peak amplification, segmenting these devices strictly to perceived mild-to-moderate loss profiles.
- Self-Adjusting Models:Smartphone-integrated audiometry applications enable user-directed threshold detection and real-time gain modification. Active working-age adults in direct-to-consumer channels drive fastest adoption as stigma avoidance and schedule flexibility outweigh clinical validation preferences. Bluetooth LE Audio protocol standardization accelerates compatibility expansion.
- Flash Technology:Proprietary rapid-fitting algorithms from legacy hearing aid manufacturers bridging prescription and OTC categories.
- Component-Based Aids:Modular assemblies targeting tinkerers and price-sensitive buyers through discrete amplifier and microphone sourcing.
Digital Devices handles the majority of throughput; Self-Adjusting Models is the fastest mover on share.
End User:
Demographic concentration determines pricing power and service model design across the value chain.
- Seniors:Adults aged 65+ with age-related sensorineural decline represent the revenue core for pharmacy and retail audiology partnerships. Medicare Advantage supplemental benefit expansion in the United States widens wallet access beyond pure out-of-pocket spend. Smartphone dependency in self-fitting models creates adoption friction requiring dedicated support hotlines.
- Young Adults:Noise-induced hearing loss from occupational and recreational exposure drives demand for discreet, lifestyle-integrated devices. United States urban markets show concentration in direct-to-consumer subscription models emphasizing cosmetic invisibility and app-based tuning. Early intervention habits distinguish this cohort from senior delay patterns.
- Consumers:General self-identified hearing difficulty without clinical diagnosis, purchasing through impulse retail environments.
- Hearing Impaired Individuals:Users with confirmed loss seeking OTC alternatives to prescription device costs and fitting delays.
Seniors captures the dominant revenue share; Young Adults posts the steepest expansion trajectory as occupational noise exposure rises.
Distribution Channel:
Channel selection dictates margin capture and customer acquisition cost structures.
- Online Retail:Direct-to-consumer platforms bypass retail markup and enable subscription bundling with remote audiology support. United States regulatory clarity on OTC advertising permits aggressive digital acquisition campaigns unavailable in prescription-device jurisdictions. Return logistics and fit verification remain operational challenges.
- Pharmacies:CVS Health and Walgreens demonstration units create tactile evaluation environments that reduce purchase hesitation among first-time buyers. United States store density enables geographic coverage impossible for standalone audiology clinics. Shelf space competition with personal health electronics compresses dwell time.
- Specialty Stores:Consumer electronics retailers leveraging existing audio peripheral customer relationships.
- Supermarkets:Mass merchandisers attaching hearing aids to general wellness shopping missions.
Pharmacies handles the majority of throughput; Online Retail is the fastest mover on share.
Features:
Capability bundling separates premium positioning from economy-tier commodity competition.
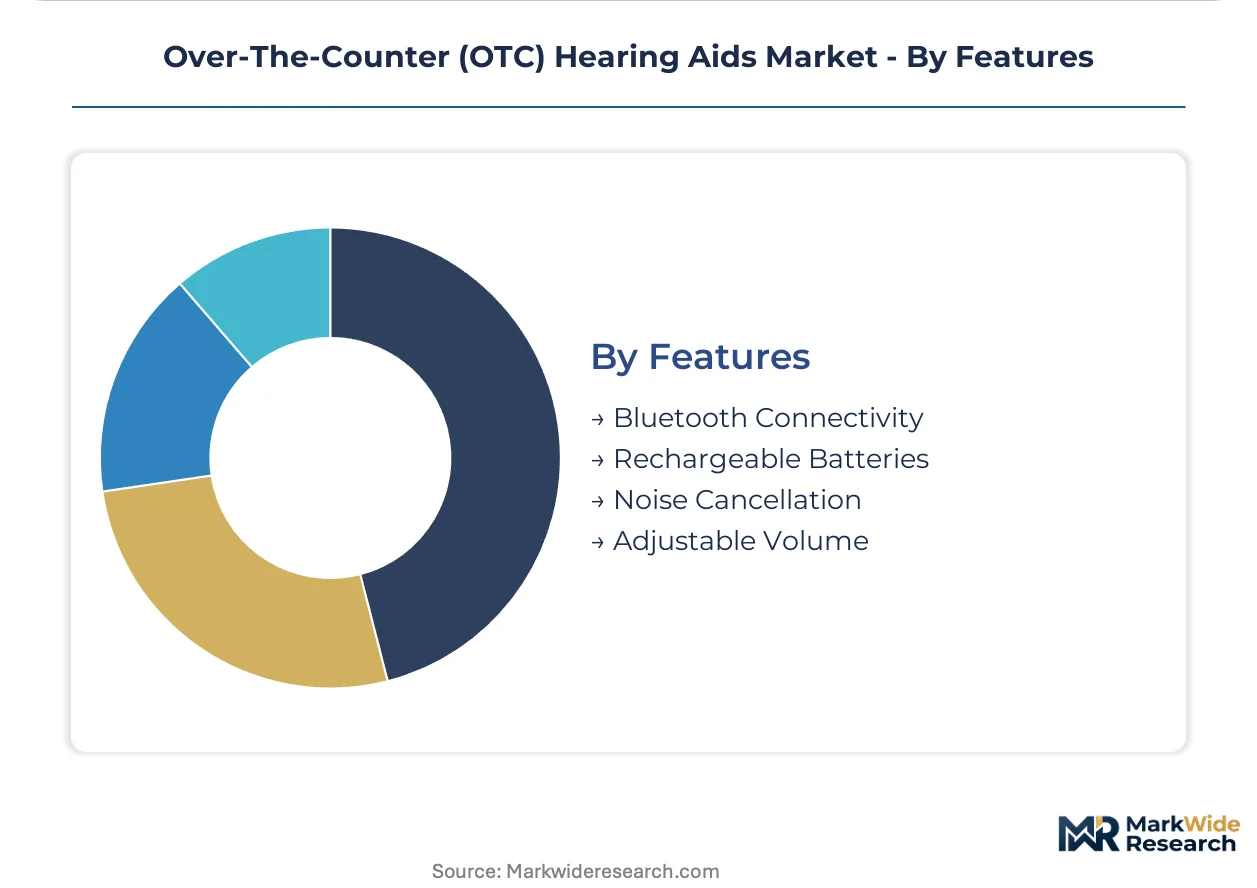
- Bluetooth Connectivity:Direct audio streaming from smartphones and televisions eliminates accessory dongles and expands device utility beyond pure amplification. United States consumer electronics integration expectations drive baseline inclusion even in mid-tier price bands. LE Audio protocol adoption reduces proprietary lock-in risks.
- Rechargeable Batteries:Lithium-ion cell integration eliminates zinc-air commodity cost volatility and daily handling burden for arthritic users. Pharmacy retail channels promote rechargeable models as total-cost-of-ownership advantages against disposable alternatives. Battery longevity claims require substantiation under FTC advertising standards.
- Noise Cancellation:Deep neural network algorithms for speech-in-noise separation.
- Adjustable Volume:Manual gain wheels and app-based level controls.
Bluetooth Connectivity handles the majority of throughput; Rechargeable Batteries is the fastest mover on share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. The United States channels demand through pharmacy retail and direct-to-consumer subscription models, while European markets retain stronger clinical gatekeeping traditions and Asia-Pacific adoption concentrates in urban consumer electronics corridors.
United States
Medicare Advantage supplemental benefit expansion widens wallet access for seniors purchasing self-fitting devices. The FDA's 2022 OTC final rule under the FDA Reauthorization Act eliminated the prescription requirement for mild-to-moderate hearing loss. Minneapolis-St. Paul anchors a cluster of legacy hearing aid engineering talent now migrating to direct-to-consumer platforms.
Germany
Occupational noise regulations in manufacturing sectors drive working-age adult demand for discreet amplification devices. The EU Medical Device Regulation (MDR) creates compliance complexity for OTC entrants lacking notified body relationships. Munich and Stuttgart host precision audio engineering clusters where headphone manufacturers leverage acoustic IP for hearing assistance crossover.
Japan
Super-aging demographics compress adoption timelines as stigma around assistive devices diminishes faster than in Western markets. METI guidelines on self-monitoring medical devices shape retail distribution permissions for smartphone-integrated models. Tokyo-Osaka corridor electronics retailers integrate hearing aids into existing audio peripheral sections.
United Kingdom
NHS rationing of prescription hearing aids pushes waitlisted patients toward private OTC alternatives. The Medicines and Healthcare products Regulatory Agency (MHRA) applies EU-legacy device classifications pending post-Brexit regulatory divergence. London and Southeast England concentrate direct-to-consumer marketing spend targeting affluent early adopters.
South Korea
MFDS streamlined device approval pathways accelerate domestic manufacturer entry into OTC categories. Government silver industry initiatives subsidize hearing assistance purchases for low-income seniors. Seoul Capital Area consumer electronics chains bundle hearing aids with smartphone upgrade cycles.
Over-The-Counter (OTC) Hearing Aids Market Competitive Landscape
Capability concentration sits with audio engineering specialists possessing proprietary signal processing IP; scale advantage sits with consumer electronics conglomerates leveraging existing retail shelf space and brand recognition. The market structures around three archetypes: direct-to-consumer subscription platforms, consumer electronics crossovers, and legacy hearing aid manufacturers bridging prescription and OTC categories. Dominant competitive moves include pharmacy retail network partnerships and firmware personalization via smartphone application ecosystems.
Within the direct-to-consumer tier, Eargo and Lexie Hearing exemplify subscription-first positioning that unbundles hardware ownership from ongoing calibration services. Sony anchors the consumer electronics crossover archetype, leveraging existing audio peripheral retail relationships and brand equity in noise-cancellation technology. Bose occupies a position between engineering heritage and mass-market accessibility, representing how headphone manufacturers repurpose acoustic R&D for hearing assistance applications.
| Leading Market Players |
|---|
| Eargo |
| Lexie Hearing |
| Jabra Enhance |
| Sony |
| Sennheiser |
| Bose |
| Audien |
| MDHearing |
| Starkey Laboratories |
| Others |
Value Network & Pricing Analysis
Trans-Pacific freight corridors connecting Taiwan and South Korea to United States distribution hubs carry semiconductor cargo whose cost volatility directly shapes downstream price differentiation between subscription-based direct-to-consumer models and pharmacy retail economy tiers.
Pricing Analysis
Long-term offtake agreements between legacy hearing aid manufacturers and lithium-ion cell suppliers anchor premium-tier pricing stability, while spot-market zinc-air battery procurement exposes economy-tier brands to commodity swings. Three-tier pricing structure across premium, standard, and economy levels separates self-adjusting models with neural noise cancellation from fixed-function digital devices. Cost compression in the economy tier is intensifying as pharmacy chains consolidate shelf-space negotiations. Seniors purchasing through Medicare Advantage supplemental benefits demonstrate lowest price sensitivity; young adults in direct-to-consumer channels exhibit highest elasticity.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for assembly operations dependent on Shenzhen-based printed circuit board fabrication. Custom digital signal processors draw from Taiwan Semiconductor Manufacturing capacity, lithium-ion cells rest on South Korean cathode chemistry, and zinc-air batteries hinge on Indonesian zinc concentrate. Single-source vulnerability in Bluetooth LE Audio chipset supply creates bottleneck exposure. Distribution runs through pharmacy retail networks with direct-to-consumer platforms capturing fastest share expansion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bluetooth LE Audio protocol standardization is collapsing proprietary ecosystem lock-in, transforming hearing assistance from device-centric hardware sales toward interoperable platform economics where firmware personalization and recurring service revenue determine long-term value capture.
For Market Incumbents: Harden defensive positioning through backward integration into custom DSP design to offset fabless competitor cost advantages. Secure exclusive pharmacy retail endcap placement before consumer electronics crossovers achieve shelf-space parity. Deepen FDA 510(k) pathway expertise as emerging state audiology board challenges threaten advertising scope.
For New Entrants and Emerging Players: Rural United States counties with limited audiology clinic density offer white-space penetration where telehealth-integrated self-fitting models bypass geographic access barriers. European markets trailing United States regulatory comfort present eighteen-month lag entry opportunity. Pursue occupational health channel partnerships with manufacturing employers facing noise compliance mandates.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors platform-software specialists with neural noise suppression IP over hardware-commoditized assemblers. Five-to-ten year viability hinges on recurring revenue attachment rates exceeding device replacement cycles. Monitor Medicare Advantage supplemental benefit expansion velocity as inflection signal for addressable wallet share.
| Strategic Initiative | Industry Significance |
|---|---|
| Firmware Personalization Platform | Smartphone-integrated audiometry applications enable user-directed tuning that bypasses clinical gatekeeping entirely. |
| Pharmacy Retail Network Partnership | CVS Health and Walgreens demonstration units create tactile evaluation environments unavailable in online channels. |
| Neural Noise Suppression Licensing | Deep learning algorithms for cocktail-party speech separation compress the OTC-prescription performance gap. |
| Rechargeable Battery Transition | Lithium-ion integration eliminates zinc-air commodity volatility and daily handling burden for arthritic users. |
| Tinnitus Masking Integration | Dual-function positioning against standalone sound therapy devices expands addressable use cases. |
Research Methodology
A standing panel of audiology clinic directors, FDA regulatory consultants, pharmacy category buyers, and direct-to-consumer platform executives provided ongoing calibration against operating reality throughout the study period. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) filings, FTC advertising substantiation records, Medicare Advantage plan benefit disclosures, and Bluetooth SIG protocol documentation. Bottom-up unit shipment modeling and top-down revenue triangulation anchored segmentation outputs.
Scenario-bracketing around Bluetooth LE Audio adoption velocity, Medicare Advantage supplemental benefit expansion pace, and state-level audiology board regulatory challenges shaped projection boundaries across the analysis window. Modeled dimensions included product type, end-user demographic, distribution channel, and feature bundling configuration. CAGRs derived from logistic diffusion curves fitted to historical adoption patterns in adjacent consumer medical device categories, with neural noise suppression maturation timelines and rechargeable battery cost curves as key inputs.
Macroeconomic conditions sit as an overlay; deviation in senior disposable income trajectories, zinc and lithium commodity price regimes, or cross-strait semiconductor fabrication stability would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement consistency and technology standardization timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
ENT
North America Hearing Aid Market
ENT
Custom Hearing Aids Market
ENT
Global Sinusitis Treatment Market
ENT
US Hearing Aids Market
ENT
Global Pediatric Hearing Aids Market
ENT
ENT Laser Devices Market
ENT
Ear Health Market
ENT
Nasal Sampling Lines Market
ENT
Interventional ENT Devices Market
ENT
Denmark Hearing Aids Market
ENT
Electrolarynx Market
ENT
Hearing Implants Market
ENT
Global Audiological Devices Market
ENT
Europe Speech Therapy Market
ENT
Global ENT Workstations Market
ENT
Europe Hearing Aids Market