
 Global Virtual Clinical Trials Market | 2026-2036
Global Virtual Clinical Trials Market Size, Share, and Industry Trends Forecast 2026-2036
Global Virtual Clinical Trials Market Foresight
FDA guidance on digital health endpoints is pivoting sponsor investment toward platform-based trial infrastructure. IQVIA leverages its integrated data science network to anchor large-scale decentralized studies across multiple therapeutic areas. ICON plc sustains competitive positioning through specialized siteless trial capabilities that reduce patient dropout rates. Medable, Inc. differentiates via direct-to-patient technology stacks that bypass traditional clinical site dependencies.
Virtual clinical trials execute investigational protocols through remote data collection, digital biomarker capture, and telemedicine oversight rather than physical site visits, typically employing wearable sensors, electronic patient-reported outcomes, and cloud-based electronic data capture systems to monitor safety and efficacy endpoints in real time. Phase II and Phase III segments generate the dominant revenue share as sponsors seek to preserve statistical power while expanding geographic recruitment pools. Remote monitoring and wearable devices within the technology used dimension represent the fastest-expanding capability clusters, driven by continuous glucose monitors, activity trackers, and cardiac event recorders that feed algorithmic safety surveillance. Oncology commands the largest therapy area allocation, reflecting the urgency of tumor-specific trials and the compatibility of liquid biopsy logistics with direct-to-patient shipping models.
EMA's Clinical Trials Regulation and FDA's decentralized trial guidance collectively reshape protocol design requirements, while WHO's digital health standards influence validation frameworks in lower-resource settings. Japan's PMDA has issued specific recommendations on telemedicine-informed consent that affect multinational trial harmonization. Stakeholders must monitor evolving data localization requirements across jurisdictions as cloud-based patient data flows encounter divergent privacy enforcement regimes.
Market Dynamics
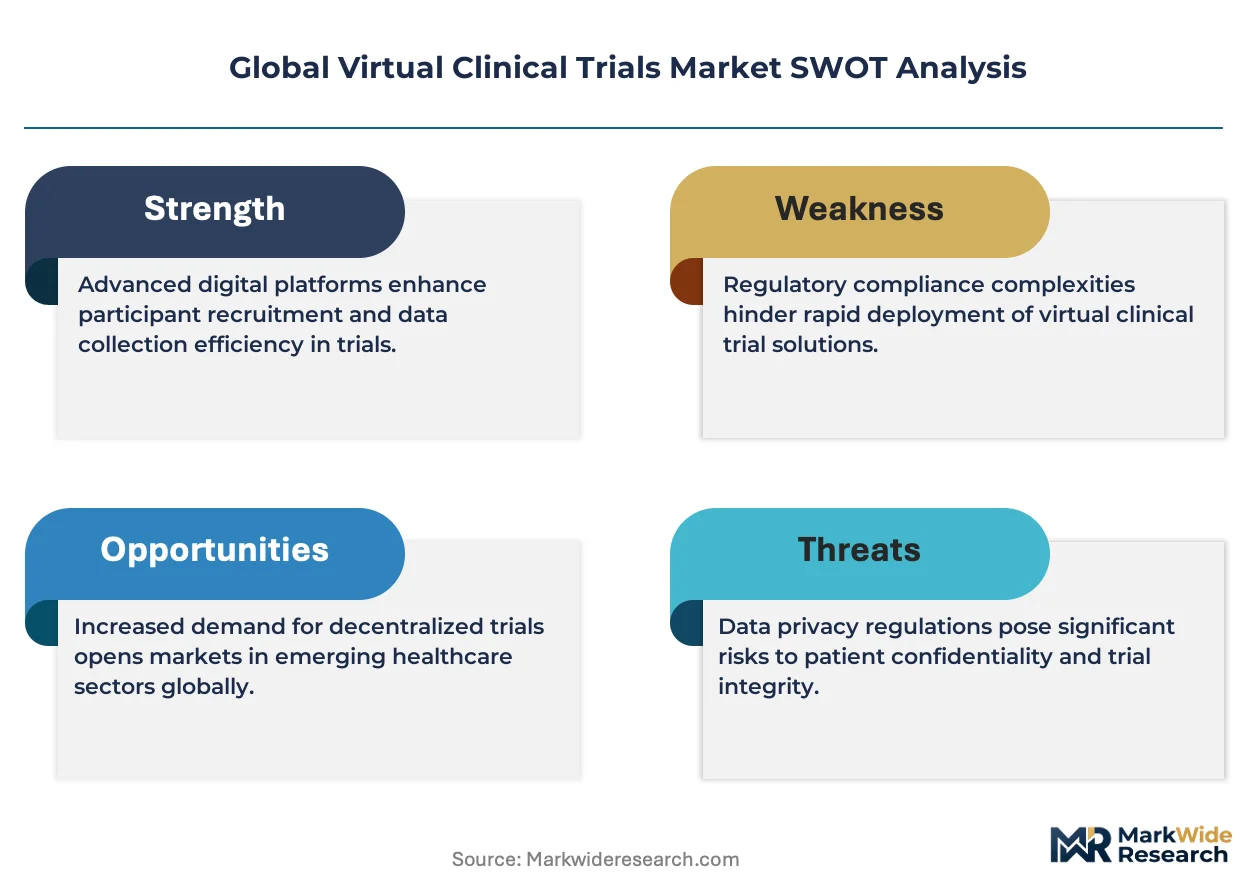
FDA's 2023 decentralized trial guidance and EMA's Clinical Trials Regulation are compressing protocol design cycles, forcing sponsors to rebuild infrastructure around remote data capture rather than retrofit legacy site networks.
Growth Catalysts
- Continuous glucose monitors and cardiac wearables:These devices generate real-time safety signals that reduce protocol amendment rates. Oncology sponsors deploy them for remote patient monitoring.
- Japan's PMDA telemedicine-informed consent framework:This regulation enables multinational trial harmonization across Asia-Pacific sites, reducing startup timelines for Japanese enrollment.
- Liquid biopsy logistics:Direct-to-patient specimen shipping models eliminate site-dependent collection bottlenecks, accelerating biomarker-driven trial recruitment.
Market Restraints
- Cloud data localization mandates:Divergent privacy enforcement regimes in Germany, Japan, and multiple US states fragment platform architecture, raising compliance engineering costs.
- Wearable sensor calibration variance:Algorithmic safety surveillance depends on device-standardized outputs, yet manufacturer-specific signal processing creates endpoint validation friction.
- Site network dependency displacement:Traditional investigative sites resist revenue loss from decentralized protocols, slowing sponsor adoption in investigator-initiated study segments.
Strategic Opportunities
- India's CDSCO digital health pathway:Underpenetrated patient pools and emerging regulatory clarity position the country for Phase II expansion with lower per-patient costs.
- AI-enabled adverse event prediction:Machine learning convergence with continuous biomarker streams enables proactive safety interventions, differentiating platform value.
- Pharmacy channel integration:Community pharmacy networks represent untapped last-mile infrastructure for device distribution and patient education in decentralized trials.
Industry Challenges
- Digital biomarker qualification timelines:FDA's evidentiary standards for novel endpoints extend validation cycles, compressing patent-protected commercialization windows.
- Telemedicine investigator licensing:Cross-border practitioner credentialing creates operational complexity for multinational protocols spanning multiple jurisdictions.
- Legacy EDC integration:Cloud-native platforms must reconcile with sponsor-installed data systems, raising implementation costs and timeline risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Virtual Clinical Trials Market |
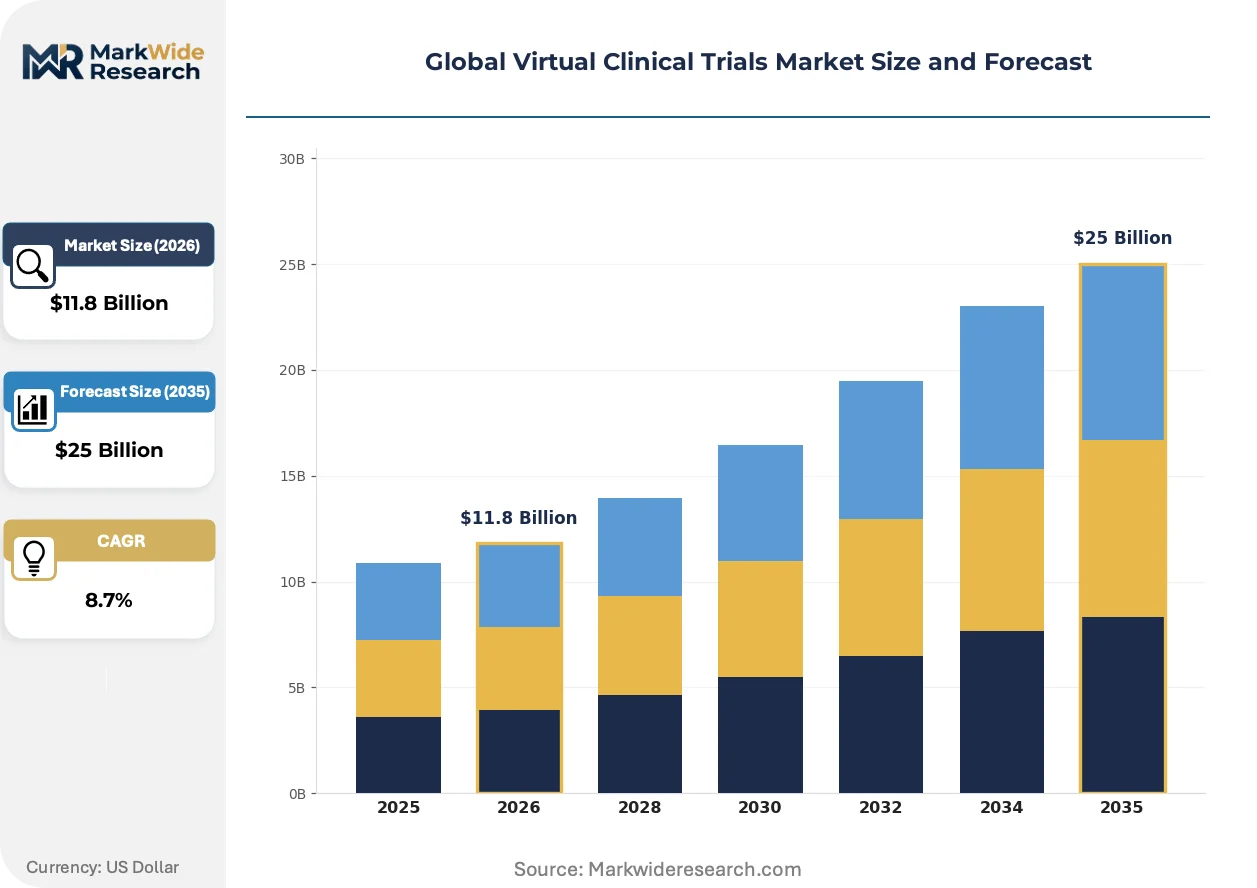
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $25 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Trial Phase: Phase I, Phase II, Phase III, Phase IV, Post-Marketing Surveillance Technology Used: Remote Monitoring, Wearable Devices, Electronic Data Capture, Mobile Apps, Telemedicine Therapy Area: Oncology, Neurology, Cardiology, Endocrinology, Infectious Diseases Stakeholder Type: Pharmaceutical Companies, Contract Research Organizations, Healthcare Providers, Regulatory Authorities, Technology Vendors |
| Companies Covered | IQVIA, ICON plc, Parexel International, Medable, Inc., Medidata Solutions, Oracle Corporation, Clinical Ink, Signant Health, Science 37, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Virtual Clinical Trials Market Shifts & Advancements
Virtual trial platforms are shifting from point solutions toward integrated ecosystems that bundle patient recruitment, remote monitoring, and regulatory submission support into unified workflows.
Artificial intelligence-driven patient matching is expanding into protocol feasibility assessment, reducing screen-failure rates. Mid-sized biotech sponsors adopt these tools fastest, compressing traditional 12-month site activation cycles. This capability is expanding into adaptive trial design, enabling real-time sample-size recalculation without protocol amendment.
EMA's Clinical Trials Information System (CTIS) portal mandates standardized electronic submission formats across all EU member states. This harmonization reduces multinational protocol variance but forces sponsors to rebuild document management infrastructure. German and French regulators are enforcing CTIS compliance most strictly, accelerating vendor consolidation for EU-focused CROs.
Patient advocacy groups now demand trial accessibility as a condition of partnership, shifting sponsor priorities toward home-based participation models. This pressure is restructuring site selection criteria, with geographic reach replacing investigator reputation as the primary filter. The United States and Germany show the strongest advocacy influence on protocol design decisions.
Global Virtual Clinical Trials Market Segmentation
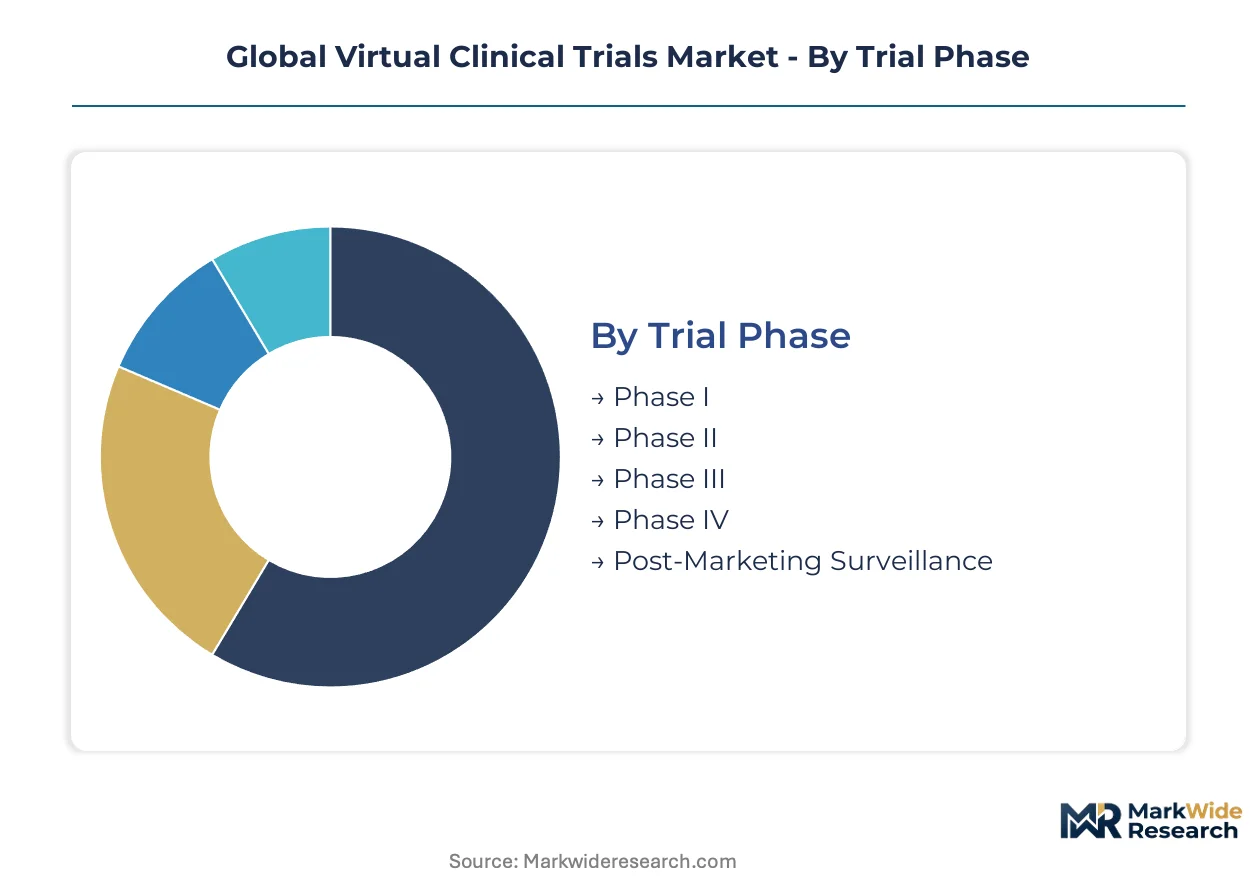
Segmentation in virtual clinical trials reveals how capital allocation, regulatory complexity, and patient access requirements reshape platform architecture across therapeutic development. Sponsors deploy distinct technology stacks and operational models depending on trial phase, disease indication, and stakeholder configuration.
Trial Phase:
Capital intensity peaks in Phase III, where statistical power requirements and geographic expansion drive infrastructure investment.
- Phase I:First-in-human safety assessments demand intensive biomarker monitoring but limited patient counts. Sponsors concentrate these studies in specialized academic medical centers in the United States and Germany.
- Phase II:Efficacy signal detection with expanded cohorts requires flexible recruitment platforms. Oncology sponsors in Japan leverage PMDA's telemedicine-informed consent framework to accelerate enrollment timelines.
- Phase III:Large-scale confirmatory trials generate the dominant revenue share as sponsors preserve statistical power while expanding geographic recruitment pools across multiple jurisdictions.
- Phase IV:Post-approval safety surveillance employs real-world data capture with lower per-patient infrastructure costs.
- Post-Marketing Surveillance:Long-term outcome tracking integrates with existing healthcare delivery systems rather than standalone trial infrastructure.
Most installed capacity flows through Phase III. Expansion is steepest in Phase II.
Technology Used:
Platform architecture investment stratifies by data capture modality and integration complexity.
- Remote Monitoring:Centralized oversight of distributed sites requires cloud-native infrastructure with real-time data streaming capabilities. FDA's decentralized trial guidance accelerates sponsor migration toward these platforms.
- Wearable Devices:Continuous glucose monitors, activity trackers, and cardiac event recorders feed algorithmic safety surveillance. Calibration variance across manufacturers creates endpoint validation friction that extends qualification timelines.
- Electronic Data Capture:Cloud-based systems must reconcile with sponsor-installed legacy systems, raising implementation costs.
- Mobile Apps:Patient-facing interfaces for electronic patient-reported outcomes reduce site dependency.
- Telemedicine:Virtual investigator visits enable home-based participation models demanded by patient advocacy groups in Germany and the United States.
Remote monitoring commands the largest installed base. Wearable devices are gaining share fastest.
Therapy Area:
Disease-specific endpoint requirements determine sensor configuration and logistics infrastructure.
- Oncology:Tumor-specific trials command the largest allocation, with liquid biopsy logistics compatible with direct-to-patient shipping models.
- Neurology:Cognitive endpoint capture requires specialized digital biomarker validation under FDA's evidentiary standards.
- Cardiology:Cardiac wearables generate continuous safety signals that reduce protocol amendment rates.
- Endocrinology:Continuous glucose monitors enable real-time metabolic monitoring with established regulatory pathways.
- Infectious Diseases:Rapid enrollment demands and public health urgency accelerate decentralized protocol adoption.
Oncology dominates current deployment. Neurology shows the steepest capability investment trajectory.
Stakeholder Type:
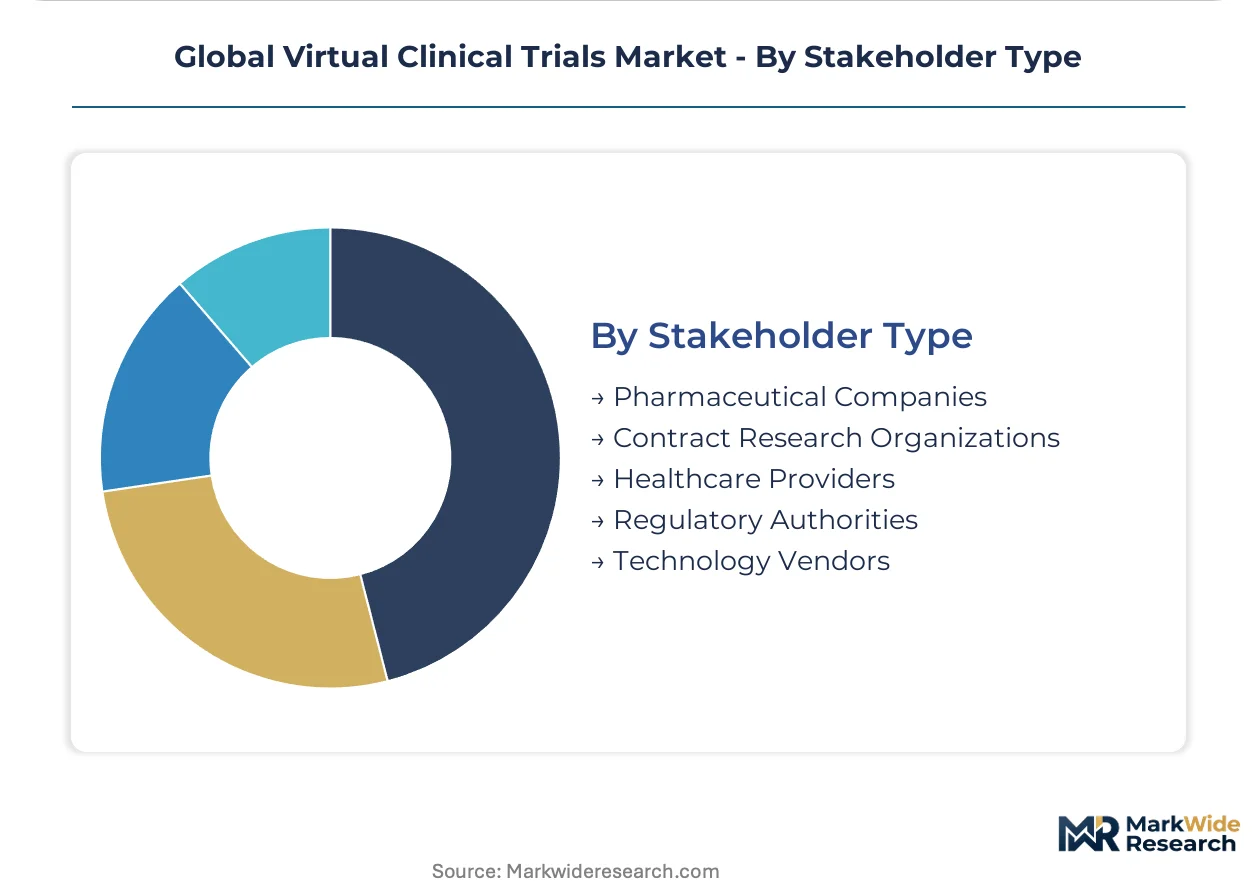
Customer procurement patterns segment by integration depth and regulatory risk tolerance.
- Pharmaceutical Companies:Large sponsors rebuild infrastructure around remote data capture rather than retrofit legacy site networks.
- Contract Research Organizations:Vendor consolidation accelerates as EU-focused CROs rebuild document management infrastructure for CTIS compliance.
- Healthcare Providers:Traditional investigative sites resist revenue displacement from decentralized protocols.
- Regulatory Authorities:EMA, FDA, and PMDA reshape protocol design requirements through converging guidance frameworks.
- Technology Vendors:Platform providers bundle patient recruitment, remote monitoring, and regulatory submission support into unified workflows.
Pharmaceutical companies anchor procurement volume. Technology vendors are expanding their share of total platform spend fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Talent concentration in clinical informatics and regulatory science anchors geographic deployment patterns. Principal investigators with decentralized trial experience cluster in established pharmaceutical hubs. Platform vendors locate engineering centers near these concentrations to accelerate protocol iteration cycles.
United States
FDA's 2023 decentralized trial guidance compresses protocol design cycles for oncology sponsors. The agency's digital health endpoint framework accelerates wearable sensor qualification timelines. Greater Boston and the San Francisco Bay Area host the densest concentrations of virtual trial platform engineering talent.
Germany
EMA's Clinical Trials Information System mandates standardized electronic submission formats across EU member states. German regulators enforce CTIS compliance most strictly, forcing sponsor infrastructure rebuilds. Munich and Frankfurt anchor continental Europe's largest contract research organization clusters for decentralized protocol execution.
Japan
PMDA's telemedicine-informed consent framework enables multinational trial harmonization across Asia-Pacific sites. Pharmaceutical sponsors leverage this regulation to accelerate Japanese enrollment timelines. Tokyo and Osaka concentrate the region's principal investigators with siteless trial experience.
India
CDSCO's emerging digital health pathway positions the country for Phase II expansion with lower per-patient costs. Regulatory clarity around remote monitoring devices attracts mid-sized biotech sponsors. Hyderabad and Bangalore host the fastest-growing clinical data science workforces outside North America.
United Kingdom
MHRA alignment with EMA frameworks preserves post-Brexit trial continuity for multinational sponsors. London's regulatory consulting density supports protocol design for concurrent EU-UK submissions. The Cambridge life sciences cluster generates specialized talent in digital biomarker validation.
Global Virtual Clinical Trials Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the platform infrastructure layer. Market structure tilts toward consolidation as EU regulatory harmonization raises compliance engineering barriers. Three archetypes dominate: integrated data science networks, specialized siteless trial providers, and direct-to-patient technology stacks. Dominant competitive moves include vendor consolidation for CTIS compliance and strategic partnerships for wearable sensor calibration standardization.
Within the integrated data science tier, IQVIA anchors large-scale decentralized studies across multiple therapeutic areas. ICON plc occupies a position among specialized siteless trial providers that reduce patient dropout rates. Medable, Inc. exemplifies the direct-to-patient technology stack archetype, bypassing traditional clinical site dependencies through cloud-native infrastructure.
| Leading Market Players |
|---|
| IQVIA |
| ICON plc |
| Parexel International |
| Medable, Inc. |
| Medidata Solutions |
| Oracle Corporation |
| Clinical Ink |
| Signant Health |
| Science 37 |
| Others |
Supply & Pricing Matrix
Captive cloud infrastructure investment by platform vendors anchors both supply security and pricing power in the virtual clinical trials market. Sponsors purchasing bundled ecosystem services from vertically integrated providers face higher contract minimums but gain guaranteed capacity during protocol surge periods.
Pricing Analysis
Platform vendors split between bundled full-service contracts and modular component pricing. Three-tier pricing structure across enterprise, mid-market, and emerging biotech levels reflects integration depth and regulatory support scope. Cost compression in the mid-market tier is intensifying because CROs compete for sponsor migration from legacy site networks. Emerging biotech sponsors show highest price sensitivity, while large pharmaceutical companies prioritize compliance guarantees over per-patient cost.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea for advanced wearable sensor fabrication, creating concentration risk for cardiac and glucose monitoring devices. Cloud infrastructure draws from hyperscaler regions in the United States, Germany, and Japan, with data localization mandates fragmenting architecture. Tariff exposure on semiconductor components threatens device cost stability. Distribution runs through direct-to-patient logistics partnerships with specialized cold-chain carriers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in virtual clinical trials rests on automation of patient recruitment workflows and premium-tier pricing for AI-enabled safety surveillance capabilities.
For Market Incumbents: Lock in sponsor relationships through CTIS-compliant document management infrastructure ahead of EU enforcement deadlines. Deepen backward integration into wearable sensor calibration standardization to reduce endpoint validation friction. Defend against pure-play technology vendors by embedding regulatory submission support into core platform contracts. For New Entrants and Emerging Players: Launch via pharmacy channel partnerships for device distribution and patient education in underserved geographies. Target India's Phase II expansion opportunity where CDSCO regulatory clarity meets lower per-patient infrastructure costs. Penetrate through specialized neurology digital biomarker validation services where FDA evidentiary standards extend qualification timelines for established competitors. For Investors and Strategic Acquirers: Roll-up economics work for mid-sized CROs with CTIS-ready infrastructure because EU regulatory harmonization raises compliance engineering barriers beyond standalone reach. Five-to-ten year viability hinges on platform consolidation into unified workflow ecosystems. Watch for inflection in AI-enabled adverse event prediction capability deployment as differentiation signal.| Strategic Initiative | Industry Significance |
|---|---|
| CTIS Compliance Infrastructure Buildout | EMA's standardized submission formats force document management rebuilds for EU-focused sponsors. |
| AI-Enabled Safety Surveillance Integration | Machine learning convergence with continuous biomarker streams enables proactive intervention differentiation. |
| Pharmacy Channel Partnership Development | Community pharmacy networks represent untapped last-mile infrastructure for decentralized device distribution. |
| Wearable Sensor Calibration Standardization | Manufacturer-specific signal processing creates endpoint validation friction extending qualification timelines. |
| Direct-to-Patient Logistics Capability | Liquid biopsy shipping models eliminate site-dependent collection bottlenecks accelerating biomarker-driven recruitment. |
Research Methodology
Coverage spans the United States, Germany, Japan, India, and the United Kingdom, with primary inputs from each market informing cross-regional pattern detection. The analysis combines interviews with clinical operations executives, regulatory affairs leads, principal investigators, and platform engineering directors with secondary validation from FDA filings, EMA CTIS submissions, ClinicalTrials.gov records, and PMDA guidance documents. Bottom-up patient enrollment modeling and top-down platform revenue triangulation anchor market size estimation.
Granularity-level modeling captures trial phase, technology modality, therapy area, and stakeholder type dimensions at the country level across the projection horizon. CAGRs derive from protocol volume growth rates, per-patient technology spend trajectories, and sponsor budget allocation surveys. Forecast inputs include regulatory guidance implementation timelines, wearable device qualification pipeline status, and cloud infrastructure capacity expansion announcements.
Several conditions sit outside the modeled scope, including specific protocol amendment frequencies, individual sponsor bankruptcy events, and geopolitical disruptions to semiconductor supply chains. Forecasts reflect assumptions about regulatory harmonization progress and technology vendor consolidation pace. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Research
Global in Vivo Toxicology Market
Clinical Research
Real World Evidence Linkage Services Market
Clinical Research
AI-Assisted Clinical Trial Protocol Design Market
Clinical Research
Preclinical CRO Market
Clinical Research
Clinical Trial Logistics and Direct-to-Patient Delivery Platforms Market
Clinical Research
Clinical Trial Management Services Market
Clinical Research
Global Clinical Trial Supply Market
Clinical Research
Clinical Trials Market
Clinical Research
Generative AI in Clinical Trials Market
Clinical Research
Pharmacovigilance Outsourcing Market
Clinical Research
Omics-Based Clinical Trials Market
Clinical Research
Real-World Evidence Analytics Market
Clinical Research
US Virtual Clinical Trials Market
Clinical Research
Asia-Pacific Contract Research Organization Market
Clinical Research
HIV Clinical Trials Market
Clinical Research
Global Healthcare Contract Research Outsourcing Market