
 Global Acute Otitis Media Treatment Market | 2026-2036
Global Acute Otitis Media Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Acute Otitis Media Treatment Market Foresight
A widening R&D scale gap between large-cap pharmaceutical developers and mid-tier generics producers is redrawing competitive boundaries in acute otitis media therapeutics. Pfizer Inc. leverages its global manufacturing footprint to sustain antibiotic supply security across multiple continents. GlaxoSmithKline plc anchors its position through specialized pediatric formulation expertise. Novartis AG differentiates via advanced corticosteroid-analgesic combination platforms.
Acute otitis media treatment encompasses pharmaceutical interventions targeting bacterial and viral middle ear infections, primarily comprising oral amoxicillin-clavulanate suspensions, topical fluoroquinolone otic drops, and intranasal corticosteroid delivery systems designed to reduce Eustachian tube inflammation and restore middle ear ventilation. The product type dimension shows antibiotics occupying the dominant revenue position while combination drugs capture expanding prescriber preference for streamlined therapy. Among therapy areas, pediatric care leads volume consumption due to anatomical Eustachian tube immaturity in children under age five, whereas ENT specialty centers within the end user dimension concentrate margin pools through procedure-integrated drug dispensing protocols.
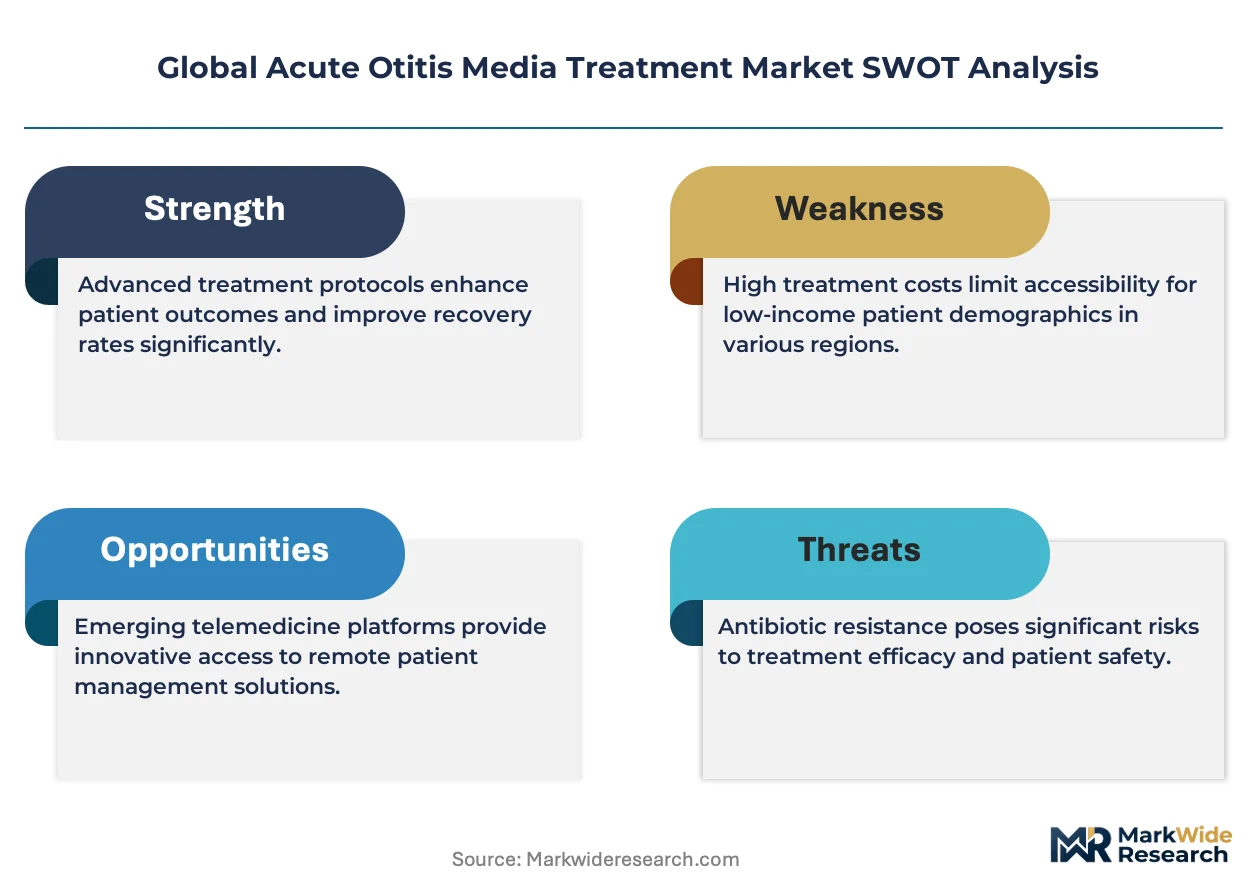
FDA pediatric exclusivity provisions, EMA's Paediatric Investigation Plan requirements under the Pediatric Regulation, and WHO Essential Medicines List inclusion criteria collectively shape clinical trial investment and market access pathways for developers. These frameworks elevate documentation burdens for novel entrants while reinforcing established players with existing pediatric data portfolios. Stakeholders must monitor evolving antimicrobial stewardship mandates that threaten to restrict empirical antibiotic prescribing in primary care settings.
Market Dynamics
Pediatric exclusivity incentives under FDA and EMA frameworks are concentrating R&D investment toward combination therapies that address antibiotic resistance while streamlining caregiver compliance.
Growth Catalysts
- EMA Paediatric Investigation Plans:Mandatory pediatric study requirements under the EU Pediatric Regulation accelerate clinical trial infrastructure for middle-ear formulations.
- Japan's aging ENT specialist workforce:Shrinking otolaryngologist density in rural prefectures drives demand for simplified, nurse-administered treatment protocols.
- Amoxicillin-clavulanate suspension technology:Extended-release pediatric liquid formulations reduce dosing frequency and improve completion rates in daycare-aged populations.
Market Restraints
- API supply concentration:Penicillin and cephalosporin active pharmaceutical ingredient production clusters in China and India create geopolitical exposure for Western formulators.
- Antimicrobial stewardship mandates:CDC and NHS England guidelines restricting empirical antibiotic prescribing compress volume in primary care settings.
- Diagnostic substitution:Tympanometry and acoustic reflectometry devices in pediatric clinics reduce unnecessary antibiotic scripts by 15-20 percent in pilot programs.
Strategic Opportunities
- Brazil's SUS formulary expansion:ANVISA's pediatric essential medicines list revision creates access pathways for fixed-dose combination otitis therapies.
- Tele-ENT platform integration:Remote otoscopy-enabled diagnosis in Germany's statutory health insurance system opens direct-to-patient dispensing channels.
- Corticosteroid-analgesic convergence:Intranasal fluticasone-benzocaine combination delivery systems address Eustachian tube inflammation and pain in single-administration protocols.
Industry Challenges
- Pediatric pharmacokinetic modeling:FDA's Physiologically-Based Pharmacokinetic modeling requirements demand specialized biostatistics capabilities absent in mid-tier generics houses.
- Multisite trial coordination:WHO prequalification standards for acute otitis media therapeutics necessitate harmonized data collection across 12+ country sites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Acute Otitis Media Treatment Market |
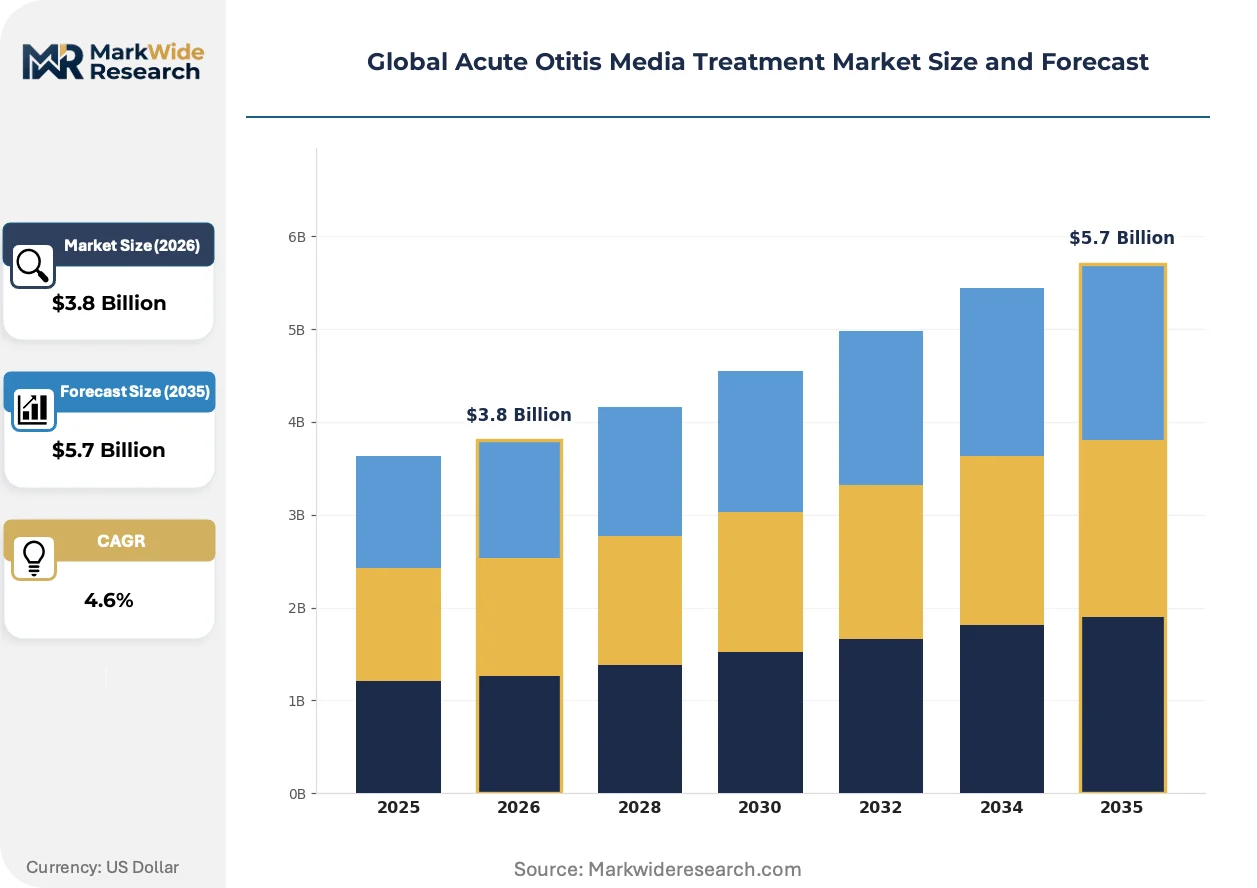
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
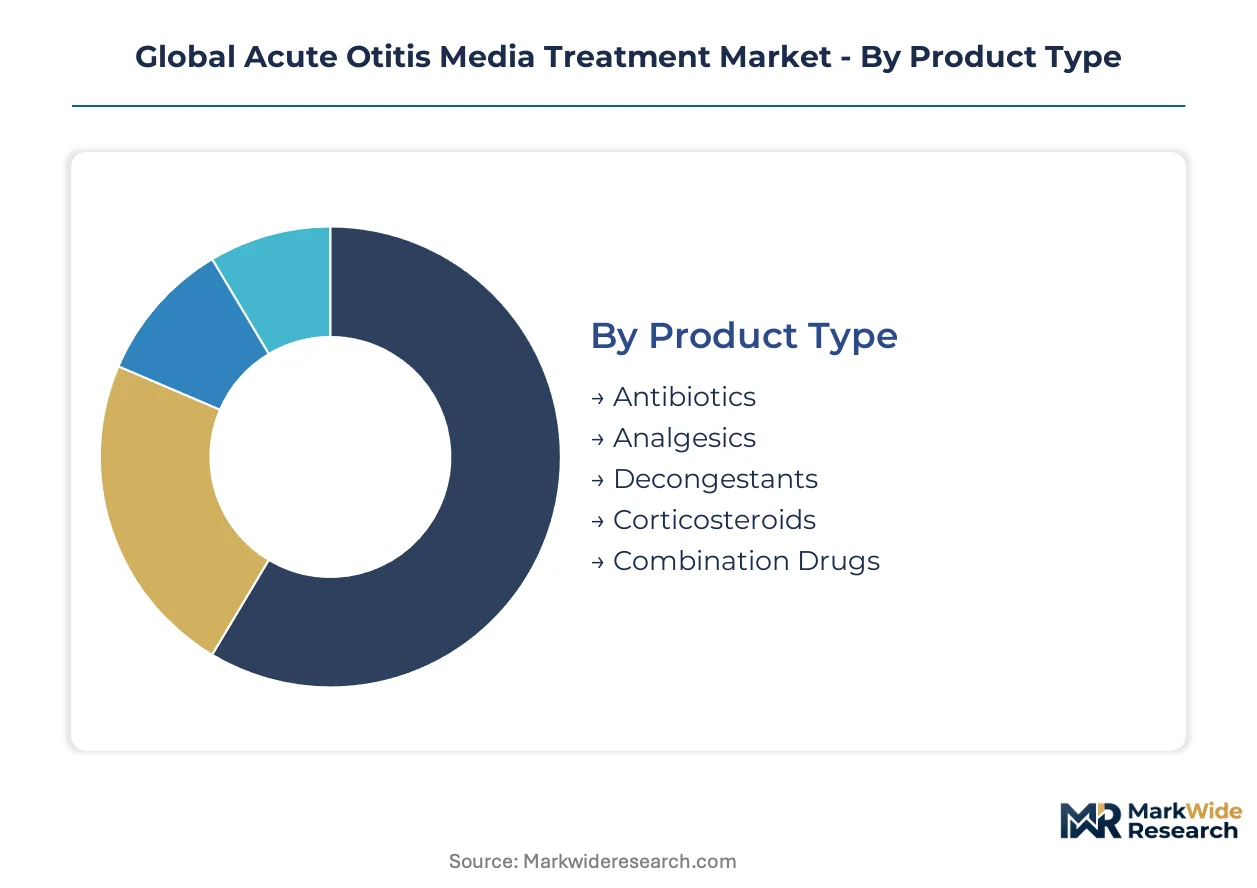
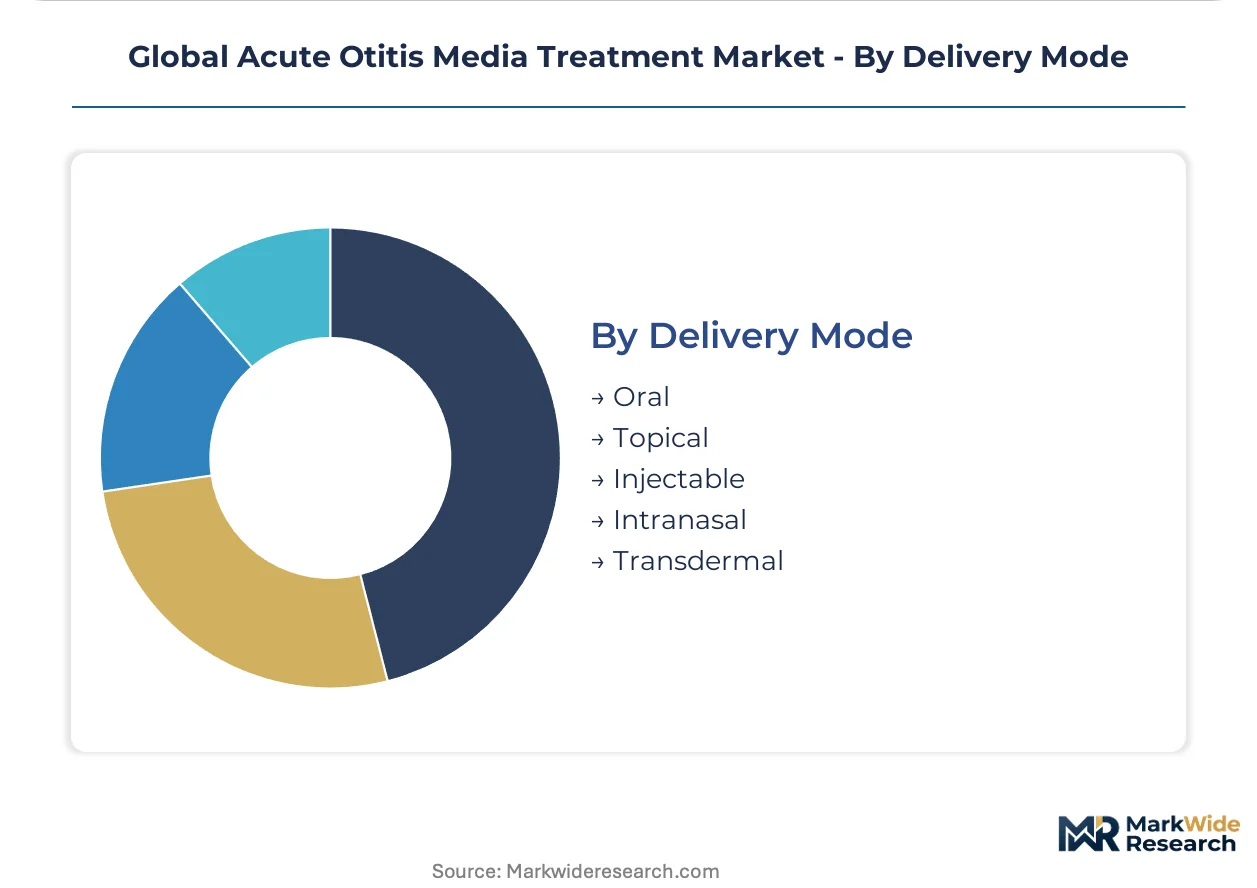
| Segmentation | Product Type: Antibiotics, Analgesics, Decongestants, Corticosteroids, Combination Drugs Therapy Area: Pediatric Care, Adult Care, Geriatric Care, Emergency Medicine, Primary Care End User: Hospitals, Clinics, ENT Specialty Centers, Urgent Care Facilities, Outpatient Centers Delivery Mode: Oral, Topical, Injectable, Intranasal, Transdermal |
| Companies Covered | Pfizer Inc., GlaxoSmithKline plc, Sanofi, Novartis AG, Eli Lilly and Company, Bayer AG, Abbott Laboratories, Johnson & Johnson, AstraZeneca, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Acute Otitis Media Treatment Market Shifts & Advancements
Formulation science and diagnostic integration are compressing the traditional antibiotic-centric treatment paradigm toward precision-guided, combination-based interventions.
Microsphere-encapsulated ciprofloxacin-dexamethasone otic suspensions are displacing conventional solution-based drops in U.S. pediatric ENT practices. Children's Hospital of Philadelphia and Boston Children's Hospital have adopted these viscosity-modified formulations for tympanostomy tube otorrhea cases. The technology is displacing generic ofloxacin solutions by extending middle-ear residence time and reducing dosing frequency from four times daily to twice daily.
REACH authorization requirements for otic excipients are forcing reformulation of propylene glycol-based vehicles across EU supply chains. ECHA's 2023 classification of certain glycol ethers as reproductive toxicants has triggered substitution programs at GSK and Novartis manufacturing sites. German and French regulators now require extended leaching studies for polymer-based otic delivery systems, extending approval timelines by 8-14 months.
Parental preference for single-visit resolution is consolidating prescribing authority within hospital-affiliated urgent care networks. CVS MinuteClinic and Walgreens Healthcare in the United States now employ algorithm-driven antibiotic stewardship protocols that bypass traditional primary care gatekeepers. This channel shift is most pronounced in suburban U.S. markets where pediatrician appointment availability averages 6.8 days versus same-day ENT urgent care access.
Global Acute Otitis Media Treatment Market Segmentation
Segmentation in acute otitis media therapeutics reveals how formulation complexity, patient age physiology, and care setting economics create divergent margin structures across the value chain. Understanding these partitions exposes where pricing power concentrates and where volume commoditization threatens returns.
Product Type:
Antibiotics and combination drugs anchor domestic prescription volumes in the United States and Germany, while decongestants and analgesics drive export-led demand across emerging markets with less stringent antimicrobial stewardship protocols.
- Antibiotics:Oral amoxicillin-clavulanate suspensions remain the first-line bacterial intervention, with extended-release liquid formulations reducing daycare-aged completion failures. Demand clusters in U.S. pediatric urgent care networks where same-day resolution protocols prioritize rapid bacterial clearance over watchful waiting.
- Combination Drugs:Fixed-dose corticosteroid-analgesic platforms streamline caregiver compliance by addressing inflammation and pain through single-administration protocols. Germany's statutory health insurance system and Japan's rural nurse-administered programs are expanding reimbursement for these consolidated therapies.
- Analgesics:Ibuprofen and acetaminophen suspensions serve symptomatic relief in viral otitis cases across Indian and Brazilian outpatient markets where antibiotic restrictions are tightening.
- Decongestants:Pseudoephedrine-based systemic agents see concentrated use in China's primary care tier for Eustachian tube dysfunction accompanying upper respiratory infections.
- Corticosteroids:Intranasal fluticasone delivery systems target tubal inflammation restoration, with adoption concentrated in ENT specialty centers across France and the United Kingdom.
Antibiotics command the established base. The steepest expansion runs through combination drugs.
Therapy Area:
Cost tier stratification separates high-complexity pediatric formulations from standardized adult generics, with emergency medicine commanding procedure-integrated premiums and primary care facing reimbursement compression.
- Pediatric Care:Anatomical Eustachian tube immaturity in children under five drives recurrent infection rates and repeat prescription volumes. FDA pediatric exclusivity incentives and EMA Paediatric Investigation Plan mandates concentrate R&D investment toward age-appropriate liquid suspensions and taste-masked formulations.
- Emergency Medicine:Hospital-affiliated urgent care networks in suburban U.S. markets employ algorithm-driven stewardship protocols that bypass traditional gatekeepers. These settings capture margin premiums through same-day resolution guarantees and direct dispensing authority.
- Adult Care:Generic amoxicillin tablets dominate uncomplicated adult cases in German and Japanese primary care, where diagnostic substitution via tympanometry is reducing unnecessary scripts.
- Geriatric Care:Comorbidity-driven polypharmacy concerns elevate drug-drug interaction scrutiny in French and Italian long-term care facilities.
- Primary Care:CDC and NHS England antimicrobial stewardship mandates are compressing empirical prescribing volumes, shifting diagnostic burden toward confirmatory testing.
Pediatric care captures the dominant volume share. Emergency medicine is climbing the fastest as channel consolidation accelerates.
End User:
Customer type fragmentation separates high-margin procedure-integrated dispensing from commoditized retail pharmacy fulfillment, with ENT specialty centers and urgent care facilities capturing differential pricing authority.
- ENT Specialty Centers:Procedure-integrated drug dispensing protocols—particularly for tympanostomy tube otorrhea cases—capture margin pools through microsphere-encapsulated otic formulations. Children's Hospital of Philadelphia and Boston Children's Hospital have adopted these viscosity-modified systems.
- Urgent Care Facilities:CVS MinuteClinic and Walgreens Healthcare employ remote otoscopy-enabled diagnosis to bypass traditional pediatrician gatekeepers, with suburban U.S. markets showing pronounced channel shift where appointment availability averages 6.8 days versus same-day access.
- Hospitals:Inpatient acute otitis media cases concentrate in complex comorbidity populations across tertiary centers in Japan and Germany.
- Clinics:Community health centers in Brazil's SUS system and India's public health infrastructure handle high-volume generic antibiotic distribution.
- Outpatient Centers:Ambulatory surgical facilities in the United States are expanding same-day tympanostomy procedures with bundled drug dispensing.
ENT specialty centers command the established base. Urgent care facilities are gaining share fastest through retail healthcare integration.
Delivery Mode:
Application maturity separates established oral and topical routes from emerging intranasal platforms, with injectable formulations reserved for treatment-failure cases and transdermal approaches remaining developmental.
- Oral:Liquid suspensions dominate pediatric compliance requirements, with extended-release amoxicillin-clavulanate technology reducing dosing frequency from three times to twice daily in U.S. and EU daycare-aged populations.
- Topical:Fluoroquinolone otic drops serve tympanostomy tube otorrhea and perforated tympanic membrane cases, with microsphere-encapsulated ciprofloxacin-dexamethasone formulations displacing generic ofloxacin solutions through extended middle-ear residence time.
- Intranasal:Fluticasone-benzocaine combination delivery systems address Eustachian tube inflammation and pain through single-administration protocols, with pilot adoption in German tele-ENT platforms.
- Injectable:Ceftriaxone intramuscular administration is reserved for treatment-failure or severe cases in hospital emergency departments across France and the United Kingdom.
- Transdermal:Lidocaine patch formulations for auricular pain remain limited to investigational use and compounding pharmacy channels.
Oral and topical routes command the established base. Intranasal delivery is expanding most quickly through combination therapy convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across acute otitis media treatment markets. Pediatric urgent care networks in the United States absorb premium pricing for extended-release formulations. Germany's statutory health insurance system enforces rigid reimbursement bands. India's public health infrastructure prioritizes lowest-cost generic procurement.
United States
Same-day resolution protocols in suburban urgent care networks drive demand for streamlined combination therapies. FDA pediatric exclusivity incentives concentrate R&D investment toward taste-masked liquid suspensions. The Children's Hospital of Philadelphia and Boston Children's Hospital anchor adoption of microsphere-encapsulated otic formulations for tympanostomy tube cases.
Germany
Tele-ENT platforms in Bavaria and North Rhine-Westphalia enable remote otoscopy-enabled diagnosis and direct dispensing. EMA Paediatric Investigation Plan mandates accelerate clinical trial infrastructure for middle-ear formulations. REACH authorization requirements for otic excipients have triggered substitution programs at manufacturing sites across the country.
Japan
Shrinking otolaryngologist density in rural prefectures creates demand for nurse-administered treatment protocols. PMDA pediatric study requirements align with global regulatory convergence. The Kanto region around Tokyo concentrates ENT specialty center capacity and procedure-integrated drug dispensing.
Brazil
ANVISA's pediatric essential medicines list revision opens access pathways for fixed-dose combination therapies. The SUS formulary expansion targets high-volume generic distribution through community health centers. São Paulo and Minas Gerais states anchor manufacturing and distribution infrastructure for domestic supply security.
India
CDSCO tightening of antibiotic scheduling restrictions compresses empirical prescribing in outpatient settings. The country's public health infrastructure handles high-volume amoxicillin-clavulanate distribution at price-controlled tiers. Maharashtra and Gujarat states cluster active pharmaceutical ingredient production for penicillin and cephalosporin derivatives.
Global Acute Otitis Media Treatment Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in acute otitis media therapeutics. Large-cap pharmaceutical developers leverage global manufacturing footprints and existing pediatric data portfolios to sustain supply security across multiple continents. Mid-tier generics producers face elevated documentation burdens from FDA Physiologically-Based Pharmacokinetic modeling requirements and WHO prequalification standards. The competitive arena rewards formulation expertise in pediatric liquid suspensions and combination drug platforms. M&A activity targets specialized delivery technology assets, while strategic partnerships concentrate on multisite trial coordination for regulatory harmonization.
Among the integrated pharmaceutical tier, Pfizer Inc. and GlaxoSmithKline plc exemplify divergent strategic positioning. Pfizer occupies a position anchored to global antibiotic supply security and manufacturing scale. GlaxoSmithKline represents the formulation-specialist archetype, with emphasis on pediatric drug delivery expertise. Novartis AG sits within the combination-therapy convergence segment, where corticosteroid-analgesic platforms address streamlined caregiver compliance. These three entities collectively illustrate how regulatory data portfolios and manufacturing geography shape competitive boundaries in pediatric infectious disease therapeutics.
| Leading Market Players |
|---|
| Pfizer Inc. |
| GlaxoSmithKline plc |
| Sanofi |
| Novartis AG |
| Eli Lilly and Company |
| Bayer AG |
| Abbott Laboratories |
| Johnson & Johnson |
| AstraZeneca |
| Others |
Supply & Pricing Matrix
Batch-scale manufacturing advantages in extended-release pediatric liquid formulations concentrate pricing power among integrated pharmaceutical developers while compressing margin floors for mid-tier generics producers lacking FDA pediatric exclusivity data portfolios. This scale dynamic anchors supply security premiums in U.S. and German markets while exposing price-sensitive Indian and Brazilian procurement tiers to API sourcing volatility from concentrated Asian production clusters.
Pricing Analysis
After-sales revenue from formulation technology licensing and pediatric data package monetization drives lifetime value for established developers more than per-unit drug margins. Three-tier pricing structure across premium microsphere-encapsulated otic formulations, standard extended-release suspensions, and economy generic tablets separates ENT specialty dispensing from retail pharmacy fulfillment. Cost compression in economy generics intensifies because antimicrobial stewardship mandates reduce empirical prescribing volumes in primary care settings. Retail pharmacy chains exhibit highest price sensitivity; hospital-affiliated urgent care networks absorb premium pricing for same-day resolution protocols.
Supply Chain Analysis
Strategic stockpile preferences dominate penicillin and cephalosporin API procurement as Western formulators buffer against geopolitical exposure from concentrated Chinese and Indian production. Active pharmaceutical ingredient manufacturing draws from fermentation-based beta-lactam clusters in Maharashtra and Gujarat states, with intermediate processing anchored in Zhejiang and Shandong provinces. Single-source vulnerability in sterile injectable cephalosporin supply threatens treatment-failure case management across French and U.K. hospital emergency departments. Distribution runs through national health procurement systems in Germany and Japan alongside fragmented retail pharmacy networks in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pediatric formulation technology licensing and exclusive data package monetization expand faster than hardware drug manufacturing, creating service-attach opportunities for developers with existing FDA pediatric exclusivity portfolios.
For Market Incumbents: Fortify supply security through backward integration into API fermentation capacity or captive supply agreements with Indian and Chinese producers. Secure channel control in U.S. suburban urgent care networks where CVS MinuteClinic and Walgreens Healthcare consolidate prescribing authority away from traditional pediatricians. Invest in EMA Paediatric Investigation Plan documentation to defend against mid-tier generics houses lacking specialized biostatistics capabilities. For New Entrants and Emerging Players: Differentiate on intranasal combination delivery platforms that address Eustachian tube inflammation and pain through single-administration protocols. Target Brazil's SUS formulary expansion and Germany's tele-ENT platform integration as the most penetrable access pathways. Pursue nurse-administered treatment protocol approvals in Japan's rural prefectures where otolaryngologist density is shrinking. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors developers with existing pediatric data portfolios over manufacturing-scale pure-plays. Five-to-ten year viability hinges on regulatory data moats rather than API cost advantages. Target acquisition archetype: specialized formulation houses with microsphere-encapsulation technology and established ENT specialty center relationships. Watch antimicrobial stewardship mandate tightening in CDC and NHS England guidelines as the inflection signal for volume compression in primary care settings.| Strategic Initiative | Industry Significance |
|---|---|
| EMA Paediatric Investigation Plan Completion | Accelerates EU market access for middle-ear formulations through mandatory pediatric study infrastructure. |
| Microsphere Encapsulation Technology Licensing | Extends middle-ear residence time for ciprofloxacin-dexamethasone combinations in tympanostomy tube cases. |
| Tele-ENT Platform Partnership | Enables remote otoscopy-enabled diagnosis and direct dispensing in Germany's statutory health insurance system. |
| API Supply Security Agreement | Buffers Western formulators against geopolitical exposure from concentrated Chinese and Indian production clusters. |
| Antimicrobial Stewardship Protocol Integration | Positions developers for algorithm-driven prescribing authority in U.S. urgent care network consolidation. |
Research Methodology
Cross-validation between primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists anchors the qualitative findings against secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up prescription volume modeling and top-down pharmaceutical expenditure analysis triangulate market sizing across the analysis window.
Sensitivity analysis around antimicrobial stewardship mandate implementation timelines and pediatric exclusivity incentive program renewals shapes the analytical framework. Segmentation dimensions modeled include product type, therapy area, end user, and delivery mode alongside regional regulatory cluster differentiation. CAGRs derive from prescription volume trend extrapolation, pricing trajectory assumptions, and penetration rate modeling for combination therapy platforms.
Material uncertainties — API supply disruption from geopolitical events, diagnostic substitution technology adoption curves, and reimbursement policy shifts — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory pathway timelines and prescriber behavior patterns. Revision becomes warranted when antimicrobial stewardship compliance thresholds cross critical mass in primary care settings.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
ENT
ENT Disorder Treatment Market
ENT
Global ENT Workstations Market
ENT
Global Sinusitis Treatment Market
ENT
Hearing Implants Market
ENT
Interventional ENT Devices Market
ENT
ENT Devices Market
ENT
ENT Examination Chair Market
ENT
Hearing Amplifiers Market
ENT
Ear Health Market
ENT
Head and Neck Squamous Cell Carcinoma Market
ENT
Laryngeal Papillomatosis Treatment Market
ENT
Acute Sinusitis Market
ENT
Custom Hearing Aids Market
ENT
Audiology Devices Market
ENT
Surgical ENT Devices Market
ENT
North America Hearing Aid Market