
 North America Hearing Aid Market | 2026-2036
North America Hearing Aid Market Size, Share, and Industry Trends Forecast 2026-2036
North America Hearing Aid Market Analytics
Premium-tier digital signal processing is unwinding legacy analog market positions across North America. Sonova Holding AG leverages its audiology clinic network to sustain premium channel control. WS Audiology anchors its position through R&D intensity in rechargeable lithium-ion architectures. Starkey Hearing Technologies differentiates via in-house production of custom shell manufacturing in its Minnesota facilities.
A hearing aid is an electroacoustic wearable device that amplifies, filters, and digitally processes sound for individuals with sensorineural or conductive hearing impairment, typically operating across frequencies from 250 Hz to 8 kHz with programmable compression ratios. Its primary commercial purpose is to restore speech intelligibility and environmental awareness for users with measured hearing thresholds exceeding 25 dB HL. Behind-the-Ear models dominate volume due to their adaptability for severe-to-profound loss and battery longevity, while Receiver-in-Canal configurations capture margin pools through cosmetic appeal and open-fit comfort. Digital technology leads value generation through directional microphone arrays and noise reduction algorithms, whereas analog remains confined to price-sensitive dispensing channels.
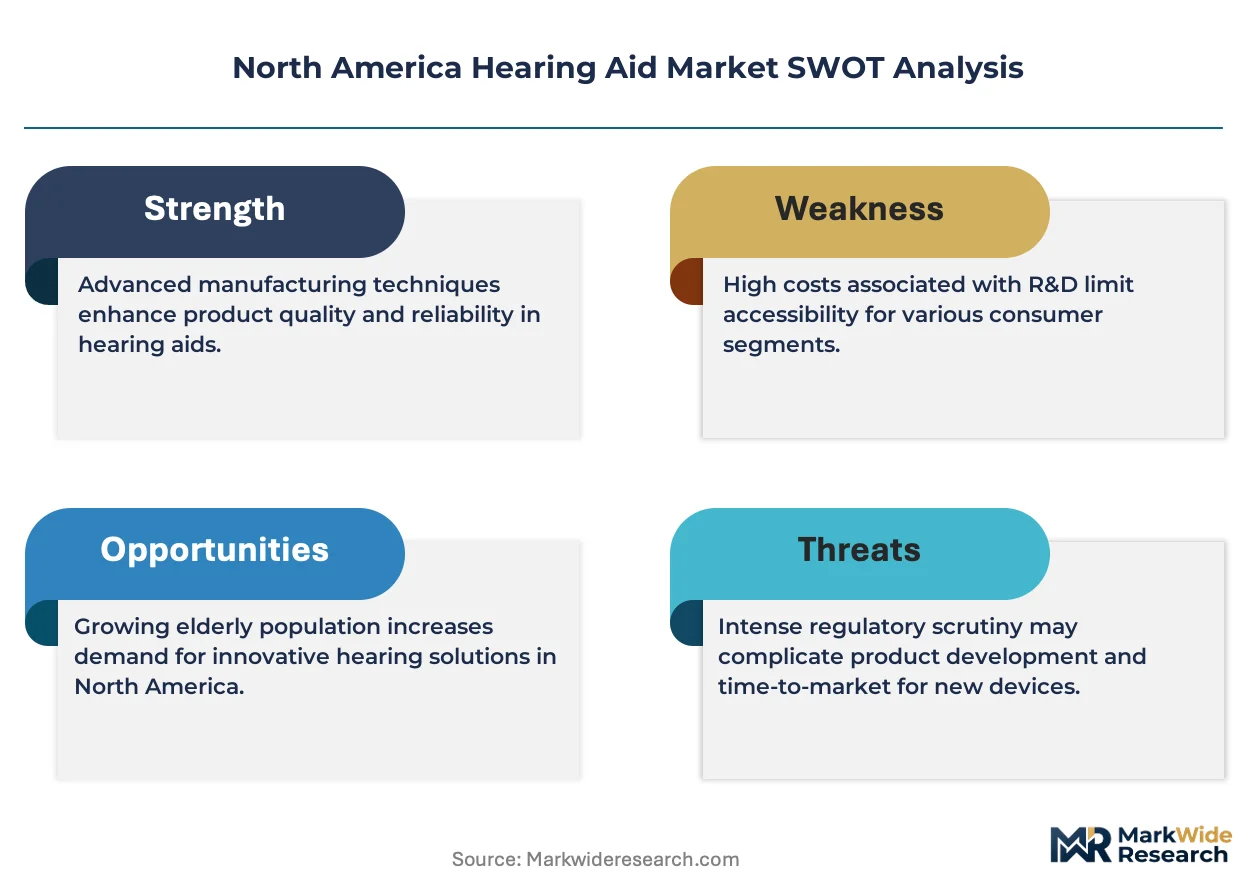
The FDA oversees device safety and efficacy through 21 CFR 874.3300 classification, while the FCC regulates wireless connectivity standards for Bluetooth-enabled instruments; state-level audiology licensing boards constrain direct-to-consumer dispensing pathways. These overlapping frameworks elevate compliance costs for new entrants but protect professional channel integrity for established manufacturers. Stakeholders must monitor how OTC channel expansion alters patient triage behavior and whether audiologist-led service bundling can retain margin against self-fitting alternatives.
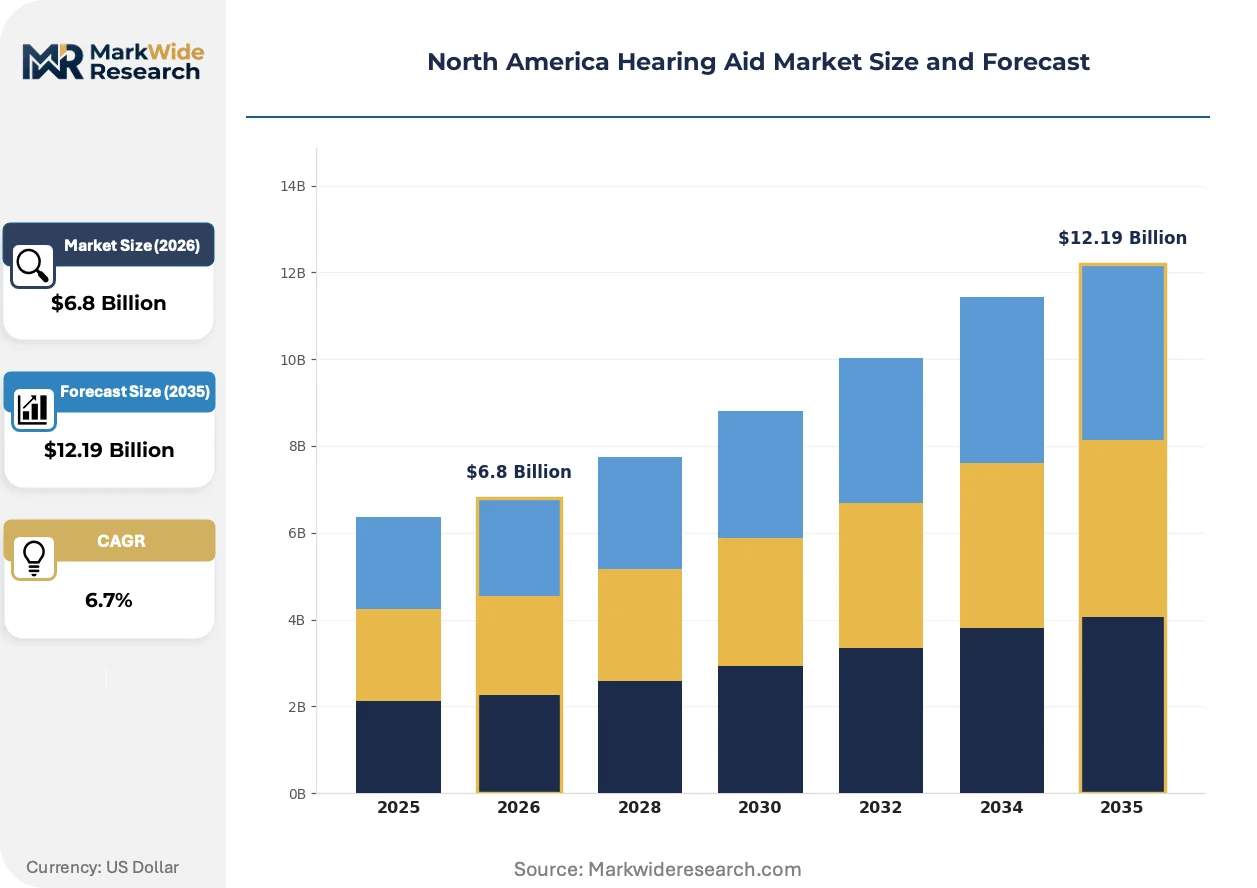
Market Dynamics
The FDA's 2022 over-the-counter hearing aid rule is fragmenting patient access pathways, splitting demand between audiologist-led professional channels and self-fitting direct-to-consumer alternatives while compressing legacy pricing structures.
Growth Catalysts
- Aging Demographics:California's metropolitan corridors and Florida's retiree-dense coastal counties concentrate demand for programmable digital devices, with independent audiology clinics serving as primary adoption engines.
- Rechargeable Lithium-Ion Architectures:Extended battery life and eliminated disposable cell costs are pulling users away from zinc-air powered legacy instruments toward sealed rechargeable systems.
- Bluetooth Wireless Connectivity:FCC-regulated spectrum access enables direct smartphone streaming, expanding device utility beyond amplification into communication and entertainment integration.
Market Restraints
- Professional Channel Concentration:State-level audiology licensing boards constrain direct dispensing pathways, elevating compliance costs for new entrants seeking to bypass established clinic networks.
- Custom Shell Manufacturing Bottlenecks:In-house production capacity for ear-mold fabrication limits rapid scaling of personalized device output, particularly for severe-to-profound loss configurations.
- Input Cost Volatility:Rare earth magnet supply for receiver assemblies faces pricing pressure from concentrated upstream mining geographies outside the region.
Strategic Opportunities
- OTC Channel White Space:Self-fitting alternatives for mild-to-moderate impairment remain underdeveloped in Canadian provinces, where Health Canada regulations lag FDA pathway liberalization.
- Remote Programming Services:Tele-audiology platforms enable post-purchase adjustment without clinic visits, unlocking rural and mobility-constrained user segments previously excluded from professional care.
- AI-Powered Noise Reduction Convergence:Machine learning algorithms trained on environmental sound libraries are merging with directional microphone arrays to deliver adaptive listening in dynamic acoustic environments.
Industry Challenges
- Audiologist Workforce Constraints:Specialized training pipelines for diagnostic audiology and device programming cannot match expansion velocity of patient eligibility pools.
- Firmware Validation Timelines:FDA 21 CFR 874.3300 software-as-medical-device requirements extend certification cycles for over-the-air feature updates, compressing competitive response windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Hearing Aid Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $12.19 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Behind-the-Ear, In-the-Ear, Receiver-in-Canal, Completely-in-Canal Technology: Analog, Digital, Feature-rich, Directional End User: Seniors, Adults, Pediatrics, Patients with Hearing Loss Distribution Channel: Retail, Online, Audiology Clinics, Hospitals |
| Companies Covered | Sonova Holding AG, WS Audiology, Starkey Hearing Technologies, GN Store Nord A/S, Demant A/S, Cochlear Limited, Eargo, Inc., Audina Hearing Instruments, SeboTek Hearing Systems, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Hearing Aid Market Evolving Landscape
Digital signal processing architectures are actively compressing analog market positions while regulatory pathway fragmentation and shifting patient triage behaviors reshape competitive dynamics across the region.
Deep neural network-based noise suppression is supplanting traditional multi-channel compression algorithms in premium-tier instruments. Audiologists in independent clinics are prescribing these systems for patients with complex listening demands in noisy environments. The technology is compressing margins for legacy analog manufacturers while enabling manufacturers to command service-bundled pricing for algorithm-optimized fitting protocols.
The FDA's over-the-counter hearing aid final rule is eliminating the medical evaluation requirement for mild-to-moderate impairment devices, enabling direct retail and e-commerce distribution. This regulatory shift is diverting patient volume from professional channels toward self-selection models. Established manufacturers with clinic network dependencies are responding by unbundling hardware from service contracts to compete on device-only price points.
Patient triage behavior is fragmenting across age and technology-comfort segments. Younger users with early-onset loss are bypassing audiologist consultations entirely, purchasing self-fitting instruments through online direct channels. This channel rotation is most visible in Texas and Arizona metropolitan markets, where tech-forward demographics overlap with regulatory clarity on OTC eligibility thresholds.
North America Hearing Aid Market Segmentation
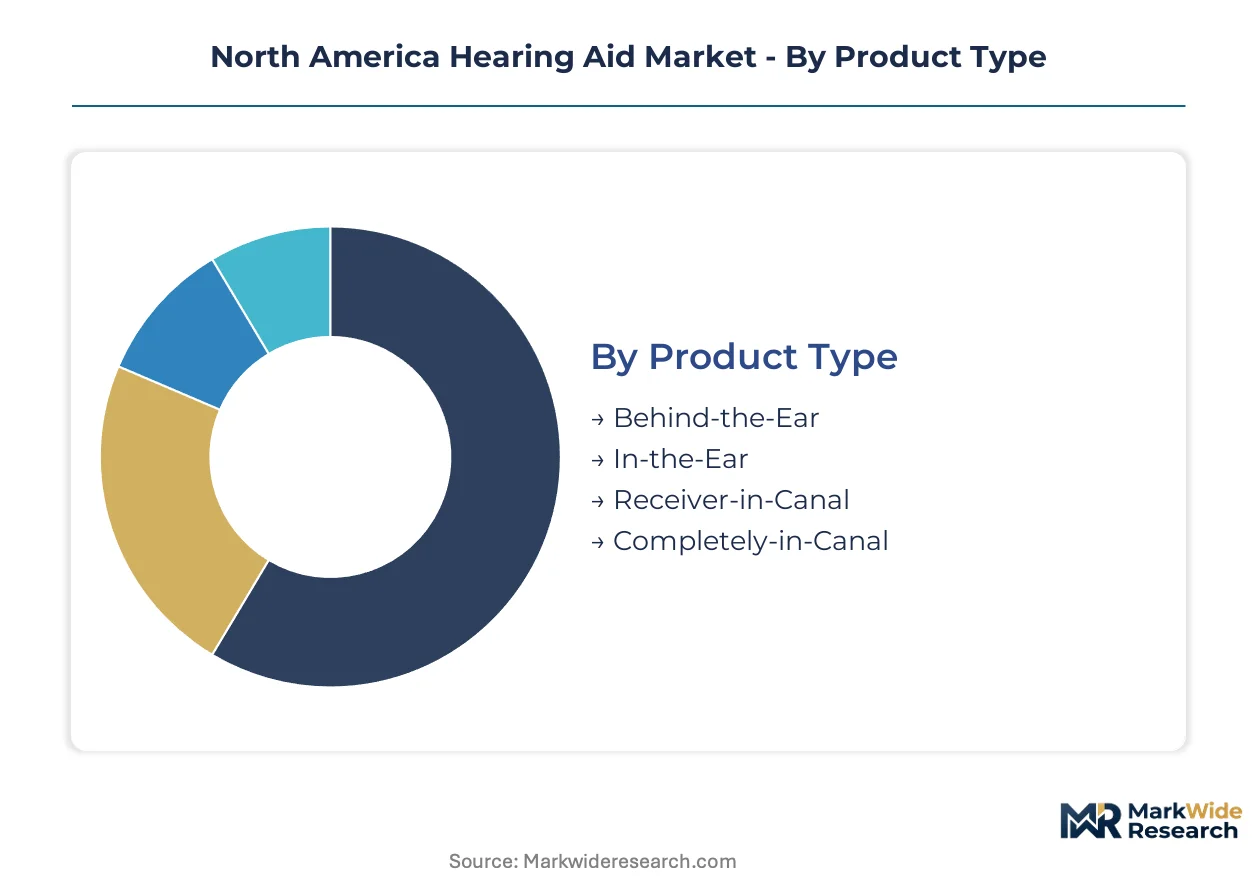
Hearing aid segmentation reveals how FDA pathway fragmentation and audiologist channel economics split revenue pools across form factors and dispensing models. Manufacturers calibrate R&D allocation and service bundling strategies against these fault lines.
Product Type:
Margin pools concentrate in discreet form factors that command premium pricing through cosmetic appeal and open-fit comfort.
- Behind-the-Ear:These devices house electronics in a casing resting behind the auricle, connecting via tubing to a custom ear-mold. Demand clusters in California's metropolitan corridors for severe-to-profound loss patients prioritizing battery longevity and amplification power. The configuration dominates volume through adaptability across impairment severity levels.
- Receiver-in-Canal:A miniature speaker sits directly in the ear canal with the processor behind the ear, enabling open-fit comfort and reduced occlusion. Florida's retiree-dense coastal counties drive adoption where cosmetic discretion meets mild-to-moderate loss profiles. Rechargeable lithium-ion architectures are accelerating migration from traditional Behind-the-Ear systems.
- In-the-Ear:Custom shells fill the concha and canal, offering compact integration for moderate loss.
- Completely-in-Canal:Deep canal placement renders these devices virtually invisible, serving cosmetic-sensitive users with mild impairment.
The dominant share belongs to Behind-the-Ear, while Receiver-in-Canal is closing the gap fastest.
Technology:
Cost tier stratification separates legacy amplification from algorithm-driven signal processing architectures.
- Digital:Programmable systems deploy directional microphone arrays and multi-channel compression across 250 Hz to 8 kHz frequency ranges. Independent audiology clinics in Texas and Arizona metropolitan markets prescribe these for patients demanding adaptive noise reduction. FDA 21 CFR 874.3300 software validation requirements extend certification timelines for firmware updates.
- Feature-rich:Bluetooth wireless connectivity and smartphone app integration expand utility into communication and entertainment domains. Younger adults with early-onset loss in tech-forward demographics bypass traditional channels for these self-adjustable systems. FCC spectrum regulation governs wireless interoperability standards.
- Analog:Basic amplification circuits serve price-sensitive dispensing channels with minimal processing capability.
- Directional:Focused microphone beamforming enhances speech intelligibility in noisy environments through fixed or adaptive polar patterns.
Digital commands the revenue base, though Feature-rich configurations are expanding most quickly among self-fitting user segments.
End User:
Customer type determines service bundling intensity and channel access requirements.
- Seniors:Adults aged 65+ with age-related sensorineural loss constitute the primary eligibility pool. Florida's coastal retirement communities and California's aging metropolitan corridors concentrate demand for audiologist-led fitting and ongoing adjustment services. Medicare coverage gaps sustain private-pay dynamics for premium-tier devices.
- Adults:Working-age users with occupational or early-onset impairment exhibit divergent channel preferences. Tech-forward demographics in Arizona and Texas metropolitan markets favor direct-to-consumer OTC pathways, while traditionalists retain professional clinic relationships. Bluetooth streaming compatibility drives specification priorities.
- Pediatrics:Congenital or early childhood hearing loss requires specialized fitting protocols and educational support coordination.
- Patients with Hearing Loss:This catch-all clinical designation spans all etiologies and severity grades in diagnostic and reimbursement documentation.
Seniors retain the largest patient volume, yet Adults are gaining share fastest through OTC channel migration.
Distribution Channel:
Supply concentration in professional networks constrains direct access while protecting service-embedded margins.
- Audiology Clinics:Licensed diagnostic and dispensing practices provide comprehensive hearing evaluation, custom fitting, and ongoing rehabilitation. State-level audiology licensing boards in California, Florida, and Texas enforce professional channel integrity against direct dispensing alternatives. Service bundling sustains premium pricing for programmable digital systems.
- Online:E-commerce platforms and manufacturer-direct websites enable self-selection for OTC-eligible mild-to-moderate impairment. The FDA's 2022 rule elimination of medical evaluation requirements unlocked this pathway for younger, tech-comfortable demographics. Remote programming services are extending post-purchase support without clinic visits.
- Retail:Big-box electronics and pharmacy chains capture walk-in demand for entry-level and self-fitting instruments.
- Hospitals:Acute care and outpatient ENT departments handle diagnostic referrals and complex medical-surgical cases.
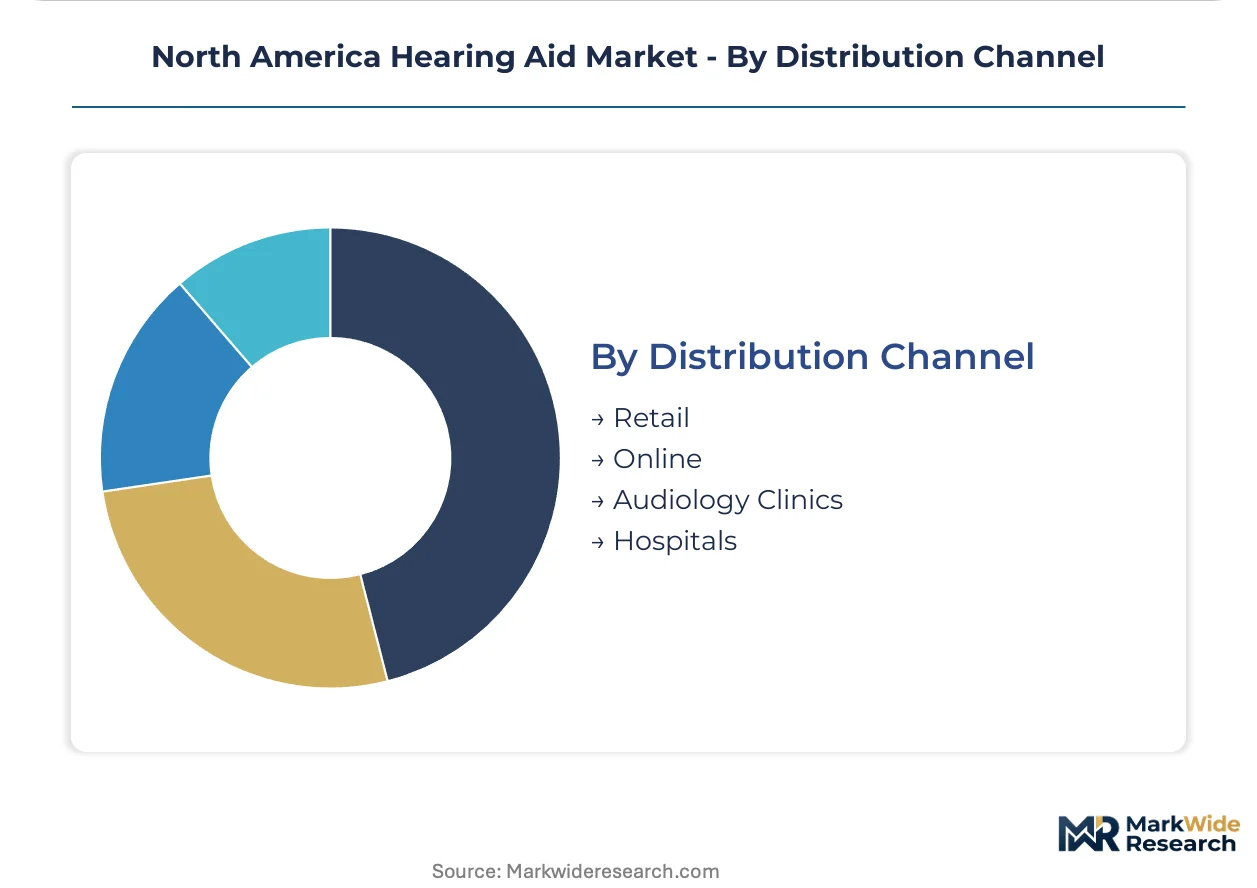
Audiology Clinics control the value pool, but Online is climbing the fastest following regulatory pathway liberalization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters in Minnesota and Denmark, with assembly operations concentrated near major audiology service networks. Distribution runs through licensed professional channels in metropolitan corridors and emerging direct-to-consumer pathways in tech-forward markets.
United States
FDA's 2022 over-the-counter rule unlocked self-fitting pathways for mild-to-moderate impairment, diverting patient volume from traditional audiology clinics toward direct retail and e-commerce channels. California's aging metropolitan corridors and Florida's retiree-dense coastal counties concentrate demand for programmable digital devices. Texas and Arizona metropolitan markets show fastest channel rotation toward tech-forward demographics bypassing professional consultations entirely.
Canada
Health Canada regulations lag FDA pathway liberalization, leaving self-fitting alternatives for mild-to-moderate impairment underdeveloped across provinces. Ontario and Quebec maintain professional channel dominance through provincial audiology licensing requirements. Vancouver and Toronto metropolitan areas show emerging demand for rechargeable lithium-ion architectures and Bluetooth-enabled streaming compatibility.
Mexico
COFEPRIS medical device registration requirements sustain professional dispensing dominance for imported digital instruments. Mexico City and Monterrey metropolitan corridors concentrate purchasing power for premium-tier programmable systems. Northern border states show cross-border procurement patterns toward US-based audiology clinics and OTC retail channels.
North America Hearing Aid Market Competitive Landscape
Concentration sits with vertically integrated manufacturers maintaining captive audiology clinic networks and in-house custom shell fabrication capacity. Three archetypes dominate: multinational hearing instrument conglomerates with professional channel control, rechargeable technology specialists, and direct-to-consumer disrupters leveraging OTC regulatory pathways. Competitive moves center on unbundling hardware from service contracts and tele-audiology platform deployment.
Among European-based hearing instrument conglomerates, Sonova Holding AG and Demant A/S occupy positions representing professional channel anchoring strategies. WS Audiology exemplifies the rechargeable technology specialist archetype. At the direct-to-consumer vector, Eargo, Inc. sits within the self-fitting disrupter tier. Starkey Hearing Technologies represents North American manufacturing concentration with in-house production capabilities.
| Leading Market Players |
|---|
| Sonova Holding AG |
| WS Audiology |
| Starkey Hearing Technologies |
| GN Store Nord A/S |
| Demant A/S |
| Cochlear Limited |
| Eargo, Inc. |
| Audina Hearing Instruments |
| SeboTek Hearing Systems |
| Others |
Value Network & Pricing Analysis
Ninety-day custom ear-mold fabrication cycles compress margin capture for personalized devices while concentrating pricing power with manufacturers maintaining captive shell production in Minnesota and Denmark. This lead-time asymmetry between standard and custom configurations splits the market into service-bundled premium tiers and transaction-priced commodity segments.
Pricing Analysis
FDA 21 CFR 874.3300 dictates the pricing tier structure through software validation burdens that extend certification timelines for firmware updates. Three-tier pricing stratifies across premium programmable digital systems, standard feature-rich Bluetooth-enabled instruments, and economy analog amplification devices. Cost compression in the OTC-eligible mild-to-moderate segment intensifies as self-fitting alternatives bypass audiologist service bundling. Younger adults purchasing through direct channels exhibit highest price sensitivity, while Florida's retiree-dense coastal counties retain lowest sensitivity due to Medicare-adjacent private-pay dynamics.
Supply Chain Analysis
Port congestion along trans-Pacific lanes elevates inbound logistics costs for rare earth magnet assemblies sourced from Chinese mining operations. Manufacturing draws from Denmark, Switzerland, and Minnesota for final instrument assembly, with receiver components resting on Malaysian and Indonesian semiconductor packaging facilities. Single-source vulnerability concentrates in Chinese rare earth processing for neodymium receiver magnets. Distribution runs through licensed audiology clinic networks for professional-channel devices and direct-to-consumer logistics for OTC-eligible instruments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense against OTC self-fitting devices that divert mild-to-moderate patients from professional channels, compressing service-embedded margin pools.
For Market Incumbents: Consolidate clinic network control through exclusive fitting partnerships in California and Florida metropolitan corridors. Acquire tele-audiology platforms to extend post-purchase adjustment services without physical infrastructure. Defend against Eargo-style disrupters by unbundling hardware from service contracts while retaining algorithm-optimized fitting protocols as proprietary lock-in. For New Entrants and Emerging Players: Anchor in Canadian provincial markets where Health Canada regulations lag FDA pathway liberalization, leaving self-fitting alternatives underdeveloped. Target Ontario and Quebec audiology clinics with rechargeable lithium-ion architectures that reduce total cost of ownership against zinc-air legacy systems. Pursue hospital system partnerships for diagnostic referral capture rather than direct-to-consumer marketing spend. For Investors and Strategic Acquirers: Long-term, this sits as a demographic-capture play because aging eligibility pools in California and Florida sustain volume expansion regardless of channel fragmentation. Acquisition targets should display captive custom shell fabrication capacity or established tele-audiology platforms. Watch FDA enforcement discretion on OTC marketing claims as the inflection signal for professional channel stability.| Strategic Initiative | Industry Significance |
|---|---|
| Tele-audiology Platform Deployment | Remote programming unlocks rural user segments previously excluded from clinic-based adjustment services. |
| Rechargeable Lithium-ion Architecture Migration | Sealed battery systems eliminate disposable cell costs and differentiate against zinc-air legacy instruments. |
| OTC Channel Regulatory Navigation | FDA 21 CFR 874.3300 compliance for self-fitting devices opens direct retail pathways bypassing audiology licensing. |
| Custom Shell Fabrication Capacity Expansion | In-house ear-mold production reduces ninety-day lead times and protects margin capture for severe-to-profound loss configurations. |
| AI-Powered Noise Reduction R&D Investment | Deep neural network algorithms trained on environmental sound libraries command premium pricing through adaptive listening performance. |
Research Methodology
A standing panel of audiology clinic directors, FDA regulatory affairs specialists, GPO contracts managers, and biomedical engineers provided ongoing calibration across the study period. Primary interviews combined with secondary validation against FDA 510(k) filings, CMS Medicare claims data, state audiology licensing board records, and hospital procurement databases. Bottom-up patient volume estimates triangulated against top-down manufacturer shipment data.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. Segmentation modeling captured product type, technology tier, end user demographics, and distribution channel dynamics. CAGRs derived from fitted growth curves applied to base-year observations, with inputs including rechargeable battery adoption curves and OTC channel penetration assumptions.
Decision-makers should treat outputs as directional under stable FDA enforcement posture and demographic eligibility expansion; material deviation in regulatory pathway liberalization would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
ENT
Hearing Loss Disease Treatment Market
ENT
Global Audiological Devices Market
ENT
Over-The-Counter (OTC) Hearing Aids Market
ENT
Hearing Implants Market
ENT
Europe Hearing Aids Market
ENT
Electrolarynx Market
ENT
Europe Speech Therapy Market
ENT
Global Pediatric Hearing Aids Market
ENT
Ear Health Market
ENT
ENT Examination Chair Market
ENT
Global Sinusitis Treatment Market
ENT
Hearing Amplifiers Market
ENT
Acute Sinusitis Market
ENT
Audiology Devices Market
ENT
Nasal Polyps Treatment Market
ENT
Denmark Hearing Aids Market