
 Hearing Implants Market | 2026-2036
Hearing Implants Market Size, Share, and Industry Trends Forecast 2026-2036
Hearing Implants Market Analysis
Multi-source component procurement is repositioning supply chain risk profiles across the hearing implants sector. Cochlear Limited leverages captive electrode array manufacturing to protect margin pools on premium systems. MED-EL Medical Electronics anchors European production with vertically integrated processor assembly in Austria. Advanced Bionics competes through specialized sound-processing algorithms that differentiate performance in noisy environments.
Hearing implants are surgically implanted neuroprosthetic devices that bypass damaged cochlear structures to directly stimulate auditory nerve fibers via electrode arrays, typically incorporating titanium housings, platinum-iridium electrodes, and hermetic ceramic feedthroughs to ensure decade-long biocompatibility in physiological saline environments. Their primary purpose is restoring functional hearing in individuals with severe-to-profound sensorineural loss where conventional acoustic amplification proves ineffective. Cochlear implants dominate value generation due to established reimbursement codes and expanding pediatric candidacy, while bone anchored hearing aids capture faster volume growth in conductive and mixed loss populations underserved by traditional air-conduction pathways. Electrode array technology concentrates R&D investment as manufacturers pursue perimodiolar positioning and increased channel counts to improve spectral resolution.
FDA premarket approval requirements and the EU Medical Device Regulation reshape competitive barriers by mandating clinical evidence thresholds that favor incumbents with established trial infrastructures. CE marking under MDR and adherence to ISO 5841 standards for active implantable medical devices govern transatlantic market access, while China's NMPA pathway increasingly influences commercial prioritization for second-tier manufacturers. Stakeholders must monitor evolving payer evidence requirements as health technology assessment bodies tighten cost-effectiveness criteria for expanded indication sets.
Market Dynamics
Electrode array miniaturization and perimodiolar positioning techniques are compressing development cycles while expanding addressable patient populations beyond traditional candidacy boundaries.
Growth Catalysts
- Expanded Pediatric Candidacy:Audiological screening mandates in neonatal programs across Germany, the United Kingdom, and Australia are identifying sensorineural loss cases earlier, compressing intervention timelines and extending device utilization periods.
- FDA De Novo Pathway:The streamlined approval mechanism for novel implantable hearing devices reduces commercialization timelines from traditional PMA routes, enabling faster market entry for electrode array innovations and sound-processing platforms.
- Medicare Coverage Determinations:National coverage decisions for cochlear implantation in the United States increasingly influence private payer reimbursement policies, expanding insured access to bilateral and upgraded systems.
Market Restraints
- Platinum-Iridium Electrode Costs:Precious metal price volatility in electrode array manufacturing compresses margin pools on mid-tier systems, particularly affecting manufacturers without captive refining arrangements.
- EU MDR Clinical Evidence Burden:The Medical Device Regulation mandates expanded clinical trial infrastructures for CE marking renewal, favoring incumbents with established European investigator networks and disadvantaging smaller entrants.
- Non-Surgical Alternatives:Over-the-counter hearing aids and bone conduction headphones capture mild-to-moderate loss segments, constraining implant candidacy to severe-to-profound thresholds.
Strategic Opportunities
- Single-Sided Deafness Indications:Regulatory filings for expanded labeling in unilateral loss populations open addressable markets in Japan and South Korea, where congenital single-sided cases remain underpenetrated.
- Teleaudiology Integration:Remote programming and mapping services reduce clinical visit burdens for rural and elderly recipients, creating channel differentiation opportunities against traditional hospital-based fitting models.
- Hybrid Electrode-Acoustic Systems:Convergence of cochlear implant electrodes with residual hearing preservation techniques enables electro-acoustic stimulation platforms that capture high-frequency loss segments previously excluded from full implantation.
Industry Challenges
- Surgeon Training Pipeline:The specialized otologic surgical skill set required for perimodiolar electrode insertion faces supply constraints, with fellowship programs in the United States and Germany producing limited annual graduates relative to expanding candidacy volumes.
- Biocompatibility Certification Timelines:ISO 5841 compliance testing for active implantable medical devices requires multi-year saline immersion and fatigue validation, compressing product refresh cycles against competitive pressure.
- Legacy Processor Interoperability:Backward compatibility requirements across generationally spaced external sound processors constrain architecture redesigns and fragment software development resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hearing Implants Market |
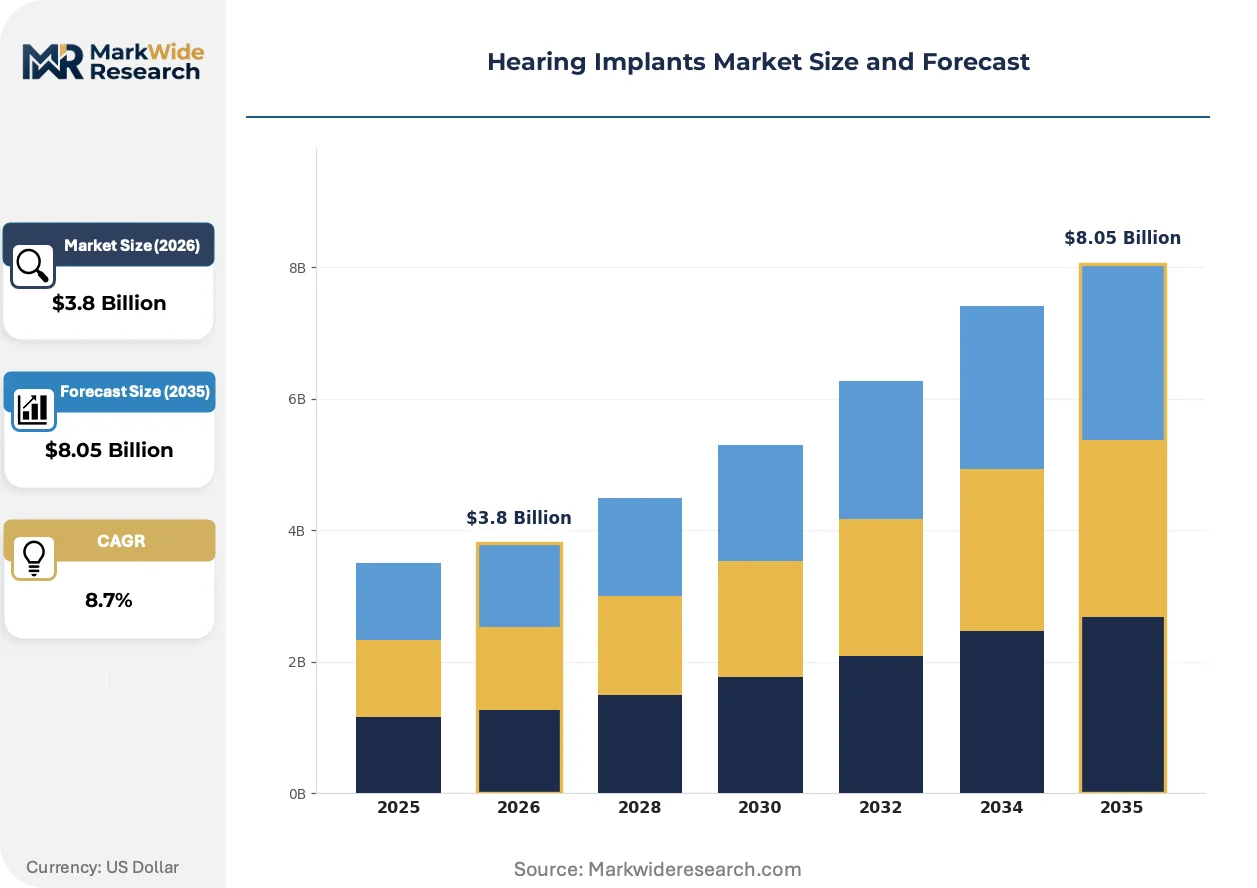
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cochlear Implants, Bone Anchored Hearing Aids, Auditory Brainstem Implants, Middle Ear Implants End User: Hospitals, Clinics, Home Healthcare, Rehabilitation Centers Technology: Digital Signal Processing, Wireless Connectivity, Miniaturized Systems, Electrode Array Application: Pediatric Hearing Loss, Adult Hearing Loss, Severe Hearing Loss, Conductive Hearing Loss |
| Companies Covered | Cochlear Limited, MED-EL Medical Electronics, Sonova, Advanced Bionics, Oticon Medical, Demant A/S, Zhejiang Nurotron Biotechnology, Envoy Medical, WS Audiology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hearing Implants Market Emerging Trajectories
Digital signal processing architectures and electrode-neural interface engineering are converging to expand spectral resolution capabilities while compressing power consumption profiles in next-generation implantable systems.
Thin-film electrode arrays with increased channel counts are absorbing R&D investment from major manufacturers seeking perimodiolar positioning precision. Pediatric and geriatric recipient populations are adopting these platforms at accelerated replacement cycles compared to legacy contour electrodes. The technology is absorbing margin pressure from premium-tier systems by enabling differentiated pricing for high-resolution configurations.
CE marking under the EU Medical Device Regulation now requires post-market clinical follow-up protocols that extend evidence generation obligations beyond initial approval. Manufacturers with established European quality management systems are consolidating notified body relationships to streamline conformity assessment. Active implantable devices face the steepest compliance cost escalation, prompting some second-tier competitors to deprioritize European market entry.
Hospital procurement committees are consolidating vendor relationships through multi-year single-source agreements that bundle devices, surgical support, and rehabilitation services. This concentration displaces fragmented purchasing across separate audiology and otology departments. The United States exhibits the most pronounced consolidation, with integrated delivery networks capturing implant volume in metropolitan markets.
Hearing Implants Market Segmentation
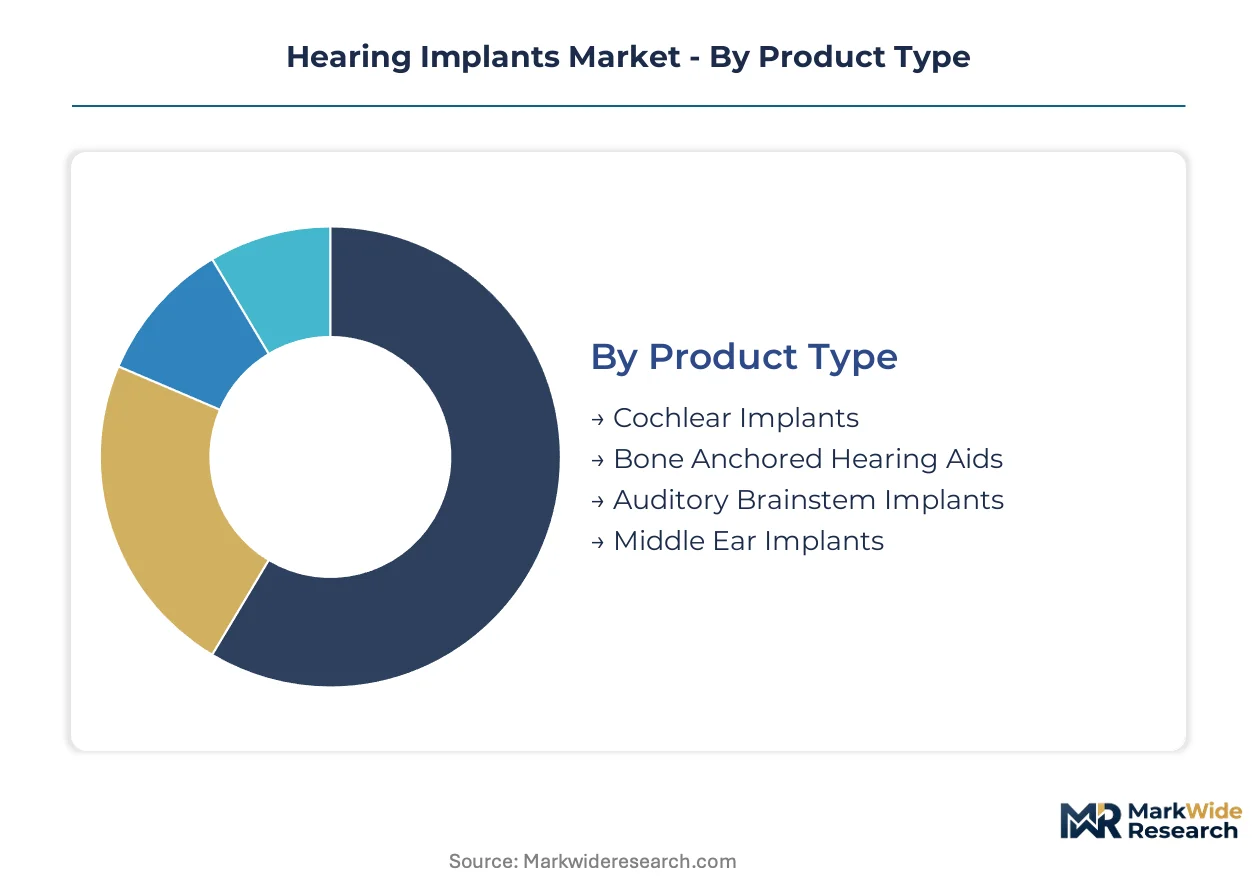
Hearing implants segment along technological sophistication, clinical setting, and patient physiology. Each dimension shapes procurement patterns, reimbursement pathways, and manufacturer R&D allocation differently.
Product Type:
Supply concentration in electrode array manufacturing favors systems with captive component production.
- Cochlear Implants:Titanium-encased devices with platinum-iridium electrode arrays that stimulate auditory nerve fibers directly. Demand clusters in the United States where Medicare coverage determinations for bilateral systems expand insured access. Incumbents protect margin pools through vertical integration into electrode manufacturing.
- Bone Anchored Hearing Aids:Percutaneous titanium abutment systems that transmit sound via bone conduction, bypassing damaged outer or middle ear structures. Volume growth accelerates in conductive and mixed loss populations in Germany and Australia where surgical candidacy criteria have broadened.
- Auditory Brainstem Implants:Surface electrode arrays positioned on the cochlear nucleus for neurofibromatosis type 2 patients lacking functional auditory nerves. Limited to specialized otologic centers in Japan and South Korea with established surgical protocols.
- Middle Ear Implants:Electromechanical transducers coupled directly to ossicular chain structures for moderate-to-severe sensorineural loss. Niche positioning in European markets where residual hearing preservation drives device selection.
Today's leader: Cochlear Implants. Tomorrow's challenger: Bone Anchored Hearing Aids.
End User:
Procurement authority is shifting toward consolidated hospital systems that bundle device, surgical, and rehabilitation contracts.
- Hospitals:Academic medical centers and community hospital systems performing the majority of implant surgeries. Volume concentrates in integrated delivery networks in the United States that negotiate multi-year single-source agreements.
- Clinics:Outpatient otology and audiology practices handling pre-operative assessment and post-activation mapping. Independent clinics in Germany face margin pressure from centralized hospital procurement.
- Home Healthcare:Remote programming services and device maintenance delivered through teleaudiology platforms. Regulatory clarity from the FDA on remote care reimbursement shapes expansion feasibility.
- Rehabilitation Centers:Dedicated facilities providing auditory training and speech therapy for pediatric implant recipients. Publicly funded programs in the United Kingdom and Australia extend intervention timelines through school-age support.
Procurement gravity centers on Hospitals. Channel differentiation opens through Home Healthcare.
Technology:
Cost tiers separate premium configurations with advanced signal processing from standard systems constrained by legacy processor interoperability.
- Digital Signal Processing:Multi-channel sound coding strategies that convert acoustic signals into electrical stimulation patterns. Algorithm differentiation in noisy environments drives competitive positioning for Advanced Bionics and MED-EL.
- Wireless Connectivity:Bluetooth Low Energy and proprietary radio frequency links enabling direct streaming from consumer electronics. Patient demand in Japan and South Korea accelerates replacement cycles for compatible external processors.
- Miniaturized Systems:Reduced-profile internal receivers and external speech processors improving cosmetic acceptability. Pediatric adoption in Australia favors smaller devices for active school-age recipients.
- Electrode Array:Thin-film and pre-curved configurations pursuing perimodiolar positioning for improved spectral resolution. R&D investment concentrates on channel count expansion and insertion trauma reduction.
Electrode Array commands current R&D spend. Wireless Connectivity is climbing the fastest.
Application:
Volume distribution reflects expanded pediatric candidacy and aging population hearing loss prevalence.
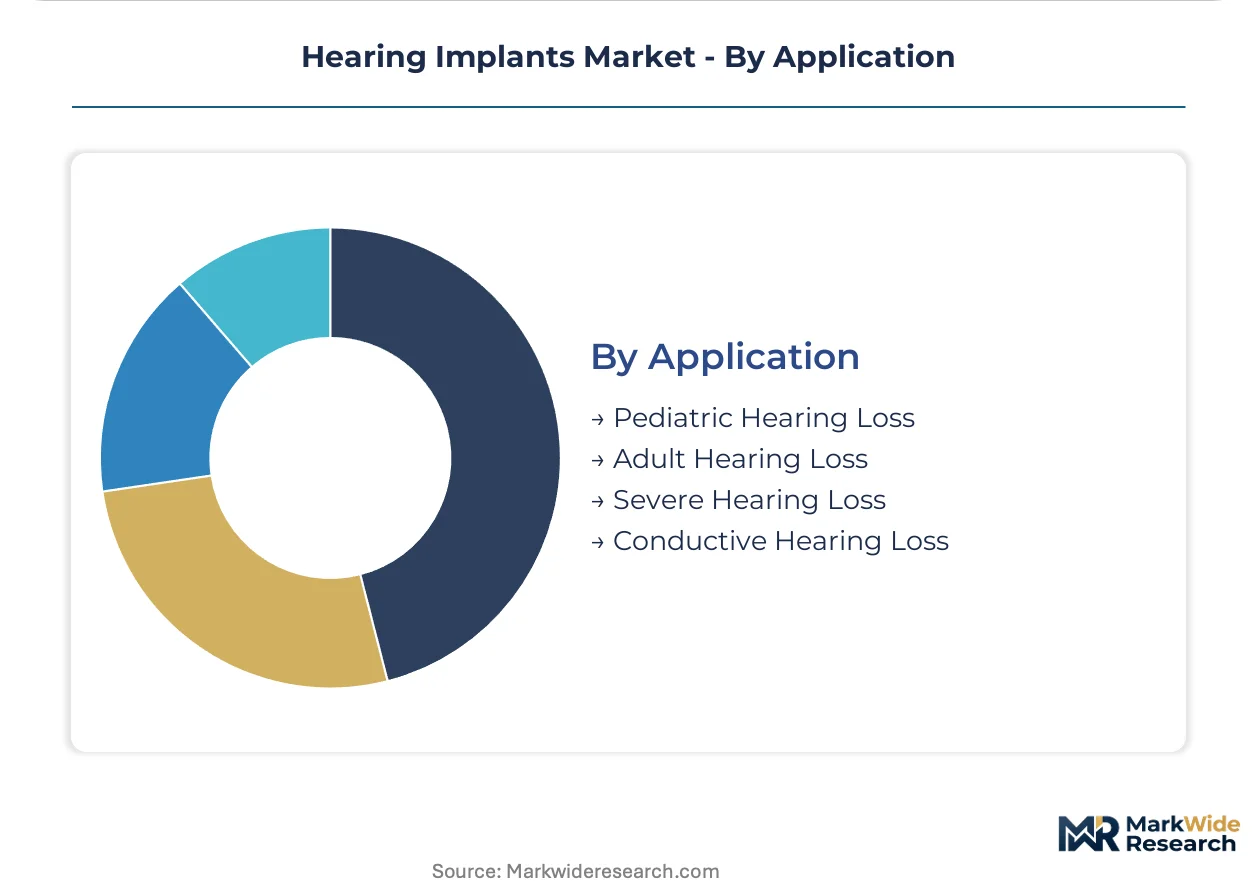
- Pediatric Hearing Loss:Congenital and early-acquired sensorineural loss cases identified through universal newborn screening. Neonatal programs in Germany, the United Kingdom, and Australia compress intervention timelines to under 12 months.
- Adult Hearing Loss:Progressive age-related and noise-induced degeneration in working-age and elderly populations. Medicare coverage in the United States increasingly includes bilateral implantation for seniors.
- Severe Hearing Loss:Profound sensorineural thresholds exceeding 70 dB HL where acoustic amplification provides limited benefit. Traditional core indication for cochlear implant systems across all regulatory jurisdictions.
- Conductive Hearing Loss:Mechanical disruption of sound conduction from outer to inner ear, often combined with chronic infection or atresia. Bone anchored systems capture this segment where surgical reconstruction fails.
Pediatric Hearing Loss anchors volume growth. Single-Sided Deafness within Adult Hearing Loss represents the expansion frontier.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Auditory Implant Center at Hannover Medical School anchors European clinical expertise, while manufacturing clusters in Austria and Australia concentrate electrode array production and processor assembly for global distribution networks.
United States
Medicare coverage determinations for bilateral cochlear implantation expand insured access beyond unilateral systems. The FDA's streamlined de novo pathway accelerates commercialization timelines for novel electrode array designs. Academic medical centers in Boston and Baltimore concentrate surgical volume through integrated delivery network contracts.
Germany
Universal newborn screening mandates compress intervention timelines to under 12 months for congenital sensorineural loss cases. The EU Medical Device Regulation mandates expanded clinical evidence thresholds for CE marking renewal under BfArM oversight. The Hannover-Berlin corridor anchors both pediatric audiology programs and electrode manufacturing facilities.
Australia
Publicly funded early intervention programs extend rehabilitation services through school-age support for pediatric recipients. The Therapeutic Goods Administration aligns post-market surveillance with ISO 5841 standards for active implantable devices. Sydney and Melbourne house regional headquarters for captive processor assembly operations serving Asia-Pacific markets.
Japan
Regulatory filings for single-sided deafness indications address underpenetrated unilateral loss populations. The Pharmaceuticals and Medical Devices Agency evaluates hybrid electro-acoustic stimulation platforms under accelerated review pathways. Tokyo and Osaka concentrate specialized otologic surgical expertise for auditory brainstem implant procedures.
South Korea
Congenital single-sided deafness cases drive demand for expanded labeling in unilateral loss segments. The Ministry of Food and Drug Safety streamlines approval pathways for wireless-enabled external processors. Seoul anchors both manufacturing partnerships for miniaturized components and clinical trial infrastructure for next-generation electrode arrays.
Hearing Implants Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue hybrid electro-acoustic convergence and teleaudiology service integration. The vendor base concentrates around three manufacturers with captive electrode array production, while second-tier competitors face margin pressure from precious metal volatility and regulatory compliance costs. Strategic archetypes include vertically integrated system suppliers, algorithm-specialized sound-processing developers, and regional challengers with NMPA pathway prioritization. Dominant competitive moves encompass backward integration into platinum-iridium refining and multi-year single-source procurement agreements bundling devices with surgical support.
Within the premium-system tier, Cochlear Limited and MED-EL Medical Electronics occupy positions defined by electrode manufacturing control and European production anchoring. Advanced Bionics exemplifies the algorithm-differentiation archetype through specialized sound-processing platforms. Zhejiang Nurotron Biotechnology represents the regional challenger model with China NMPA pathway prioritization. These three anchors illustrate how competitive positioning separates captive component producers from software-specialized and geography-focused alternatives.
| Leading Market Players |
|---|
| Cochlear Limited |
| MED-EL Medical Electronics |
| Sonova |
| Advanced Bionics |
| Oticon Medical |
| Demant A/S |
| Zhejiang Nurotron Biotechnology |
| Envoy Medical |
| WS Audiology |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap specialists anchor electrode array manufacturing in Austria and Australia, creating supply-side discipline that feeds into premium-tier pricing power. Their captive production of platinum-iridium electrodes insulates margin pools from precious metal volatility while constraining price competition in high-resolution configurations.
Pricing Analysis
Input-cost pass-through from platinum-iridium electrode manufacturing runs through premium system tiers, compressing margins on mid-tier offerings lacking captive refining arrangements. Pricing stratifies across premium, standard, and economy tiers based on channel count and perimodiolar positioning precision, with FDA certification tier and after-sales service bundling as secondary differentiation drivers. Cost compression in standard systems intensifies because precious metal volatility disproportionately affects manufacturers without backward integration into electrode production. Pediatric audiology programs exhibit least price sensitivity due to reimbursement coverage, while independent clinics in Germany face acute sensitivity from centralized hospital procurement consolidation.
Supply Chain Analysis
Domestic-content mandates under China's NMPA pathway are reshaping sourcing priorities for regional challengers targeting Asia-Pacific distribution. Manufacturing concentrates in Austria, Australia, and the United States, with electrode array fabrication and processor assembly drawing from titanium feedstock, platinum-iridium alloys, and hermetic ceramic feedthroughs. Single-source vulnerability in platinum-iridium refining creates exposure to commodity price swings. Distribution runs through integrated delivery networks in the United States and academic medical center procurement committees in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hearing implants market functions as a stable compounder anchored by expanding pediatric candidacy criteria that extend device utilization periods and replacement cycles.
For Market Incumbents: Extend control over electrode manufacturing through captive refining arrangements to defend margin pools against precious metal volatility. Deepen hospital system partnerships through multi-year single-source agreements bundling devices, surgical support, and rehabilitation services to lock out algorithm-specialized competitors lacking integrated service infrastructure. For New Entrants and Emerging Players: Begin with single-sided deafness indications in Japan and South Korea, where congenital unilateral loss populations remain underpenetrated by established manufacturers. Target teleaudiology integration as a channel differentiation play against traditional hospital-based fitting models, leveraging regulatory clarity from the FDA on remote care reimbursement to reduce clinical visit burdens for rural recipients. For Investors and Strategic Acquirers: Valuations sit cheapest among algorithm-specialized sound-processing developers lacking electrode manufacturing control but possessing differentiated noisy-environment performance platforms. Long-term viability centers on five-to-ten year replacement cycle capture across pediatric and geriatric populations. Watch FDA de novo pathway utilization rates as the signal indicating whether second-tier competitors can compress commercialization timelines against incumbent clinical evidence advantages.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR compliance under BfArM oversight secures European market access for active implantable devices. |
| Hospital System Partnership | Integrated delivery network contracts in the United States consolidate procurement volume and displace fragmented purchasing. |
| Electrode Array Innovation | Thin-film configurations with increased channel counts enable perimodiolar positioning and spectral resolution premiums. |
| Reimbursement Strategy | Medicare coverage determinations for bilateral systems influence private payer policy and expand insured access. |
| Teleaudiology Platform Development | Remote programming services reduce clinical visit burdens and create channel differentiation in rural segments. |
Methodological Framework
Bottom-up pediatric and adult hearing loss modeling reconciled against top-down electrode array production tracking forms the analytical core. Primary interviews with otologic surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers combine with secondary validation from FDA PMA filings, CE marking databases under MDR, CMS Medicare coverage determinations, and hospital procurement records. Triangulation between demand-side patient volume estimates and supply-side manufacturing capacity assessments ensures cross-verification.
Historical trendline analysis of implantation rates across congenital screening programs and age-related loss prevalence establishes baseline growth patterns. Segmentation dimensions span product type, end user, technology tier, and application severity, with regional regulatory cluster as an additional modeled variable. CAGRs derive from patient population growth, expanded candidacy criteria, and replacement cycle compression. Forecast inputs include platinum-iridium price trajectories and surgeon training pipeline constraints.
Caveats apply where FDA coverage determination reversals, EU MDR clinical evidence requirement escalations, or non-surgical alternative technology breakthroughs could materially shift the outlook. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
ENT
Nasal Sampling Lines Market
ENT
Global Sinusitis Treatment Market
ENT
Interventional ENT Devices Market
ENT
ENT Disorder Treatment Market
ENT
US Hearing Aids Market
ENT
Europe Speech Therapy Market
ENT
Hearing Loss Disease Treatment Market
ENT
North America Hearing Aid Market
ENT
Custom Hearing Aids Market
ENT
ENT Examination Chair Market
ENT
Global ENT Workstations Market
ENT
Global Pediatric Hearing Aids Market
ENT
Head and Neck Squamous Cell Carcinoma Market
ENT
Ear Health Market
ENT
Acute Sinusitis Market
ENT
Over-The-Counter (OTC) Hearing Aids Market